
 Cat Litter Market | 2026-2036
Cat Litter Market Size, Share, and Industry Trends Forecast 2026-2036
Cat Litter Market Analysis
EPA registration requirements for antimicrobial claims in pet care products is recalibrating the cost-of-entry calculus for new entrants. Nestlé Purina PetCare leverages extensive R&D infrastructure to navigate these compliance thresholds. Church & Dwight Co., Inc. anchors its position through specialized odor-control technology leadership. The Clorox Company competes via broad retail channel control and brand recognition in mass-market distribution.
Cat litter comprises absorbent granular material, typically sodium bentonite clay or silica gel, engineered to capture feline waste moisture and neutralize ammonia-based odors in domestic environments. Manufacturing involves mining and milling bentonite deposits, followed by particle size grading and additive blending to achieve clumping or non-clumping performance profiles. Clumping formulations dominate volume due to consumer preference for scoopable maintenance, while biodegradable segments attract margin pools from sustainability-oriented pet owners. Crystal variants sustain premium positioning through extended change intervals, though wood and corn materials extend appeal among chemical-averse buyers.
FDA oversight of pet product labeling intersects with EPA antimicrobial registration to shape formulation transparency and marketing claims in the United States. State-level regulations in California and New York impose additional Proposition 65 disclosure requirements and packaging waste directives that manufacturers must integrate. Stakeholders should monitor pending federal per- and polyfluoroalkyl substances restrictions that could force material substitutions across conventional clay supply chains.
Market Dynamics
Multi-cat household formation is compressing purchase cycles and elevating performance requirements for odor control and clumping efficiency, forcing manufacturers to reformulate around higher-grade sodium bentonite and activated carbon blends.
Growth Catalysts
- EU REACH chemical disclosure mandates:Importers must document additive compositions, advantaging compliant domestic producers with established testing protocols.
- Specialty retail channel expansion:Pet superstores and veterinary clinics are carving out dedicated premium shelf space for extended-change crystal formulations.
- Sodium bentonite mining consolidation in Wyoming:Captive deposit access secures input cost stability for integrated manufacturers serving clumping segment demand.
Market Restraints
- Wyoming bentonite supply concentration:Three mining districts control premium swelling clay deposits, exposing buyers to regional weather and labor disruption risks.
- Silica dust exposure litigation:Respiratory hazard claims in California and New York are elevating product liability insurance costs for conventional clay producers.
- Wood pellet fuel competition:Biomass heating demand in Nordic countries and Canada diverts pine and spruce fiber from biodegradable litter feedstock pools.
Strategic Opportunities
- India urban pet ownership acceleration:Apartment-dwelling cat adoption in Mumbai and Bangalore creates first-time buyer pools for compact, low-dust formulations.
- Subscription direct-to-home delivery:Auto-replenishment platforms bypass retail slotting fees and capture recurring revenue from convenience-seeking households.
- California SB 54 packaging waste mandates:Post-consumer recycled content requirements favor molded pulp and paper-based litter over plastic jugs.
Industry Challenges
- EPA antimicrobial registration timelines:FIFRA compliance for odor-control additives stretches 18-24 months, delaying formulation launches.
- Legacy equipment retooling for biodegradable lines:Corn and wheat starch processing requires humidity-controlled extrusion systems foreign to clay-centric plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cat Litter Market |
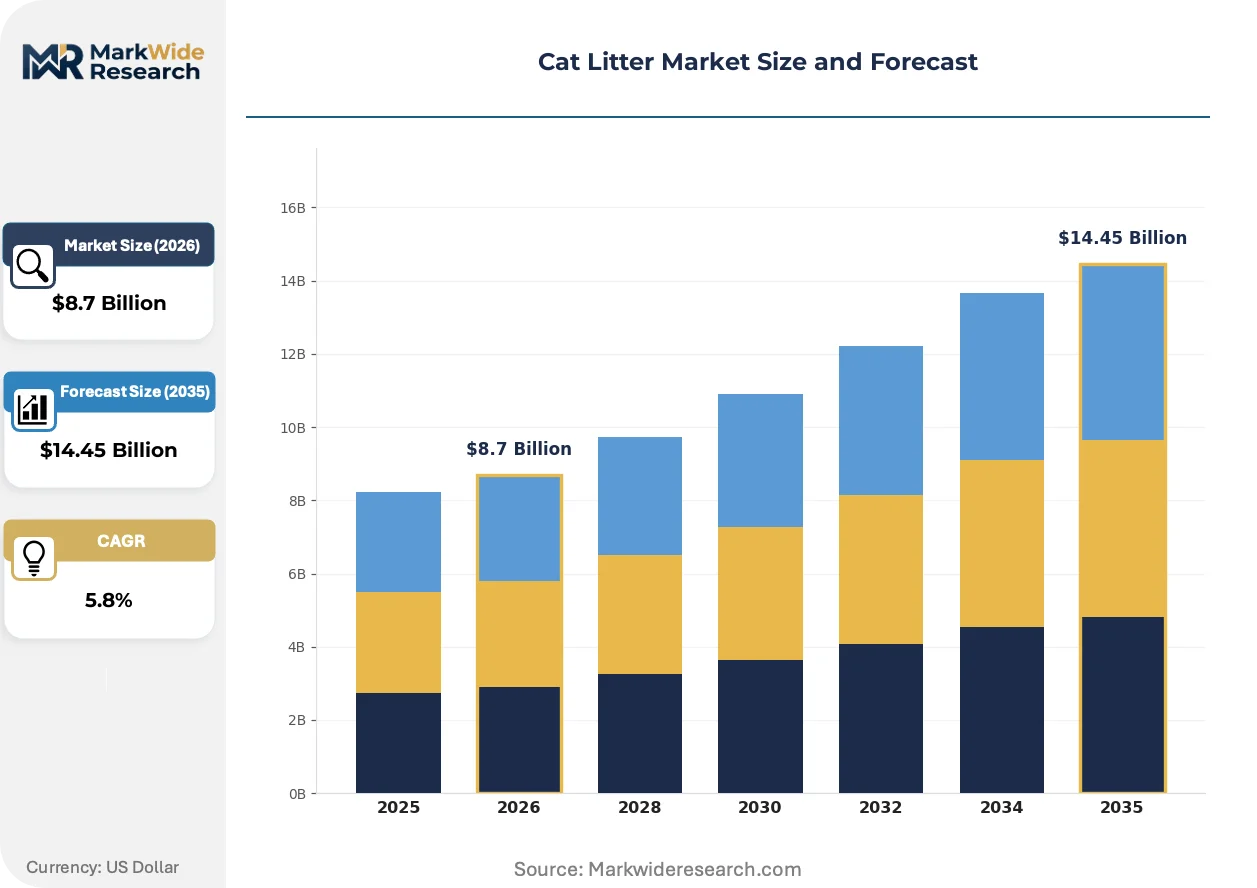
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clumping, Non-Clumping, Crystal, Biodegradable Material: Clay, Wood, Corn, Paper End User: Pet Owners, Veterinarians, Pet Care Facilities, Retailers Application: Home Use, Enclosed Litter Boxes, Commercial Use, Travel |
| Companies Covered | Oil-Dri Corporation of America, Dr. Elsey's, Nestlé Purina PetCare, Kent Corporation, Healthy Pet L.P., The Clorox Company, Church & Dwight Co., Inc., Intersand, Mars Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cat Litter Market Emerging Trajectories
Formulation chemistry and distribution logistics are converging to redefine how manufacturers capture margin, with sustainability credentials and last-mile efficiency emerging as the primary battlegrounds for differentiation.
Probiotic and enzyme-based odor neutralization is integrating into premium clumping formulas, replacing masking fragrances with bacterial cultures that metabolize ammonia compounds. Veterinary clinics and multi-cat shelters are piloting these biologically active products to reduce ventilation costs. This biotechnology infusion is compressing the performance gap between mid-tier clay and premium crystal segments.
REACH authorization requirements for biocidal products are forcing reformulation of antimicrobial litter additives across EU import channels. Manufacturers must submit full toxicological dossiers for zinc pyrithione and triclosan alternatives, extending product development cycles by 12-18 months. German and French distributors are prioritizing suppliers with pre-registered substance portfolios to avoid customs delays.
Pet specialty retailers are unbundling bulk refill programs from traditional packaged goods, installing in-store dispensing systems for unscented clay and silica gel. Warehouse club buyers in Texas and Florida are driving volume commitments for private-label tanker deliveries. This channel experimentation is most advanced in suburban markets where garage storage space accommodates 40-pound reusable containers.
Cat Litter Market Segmentation
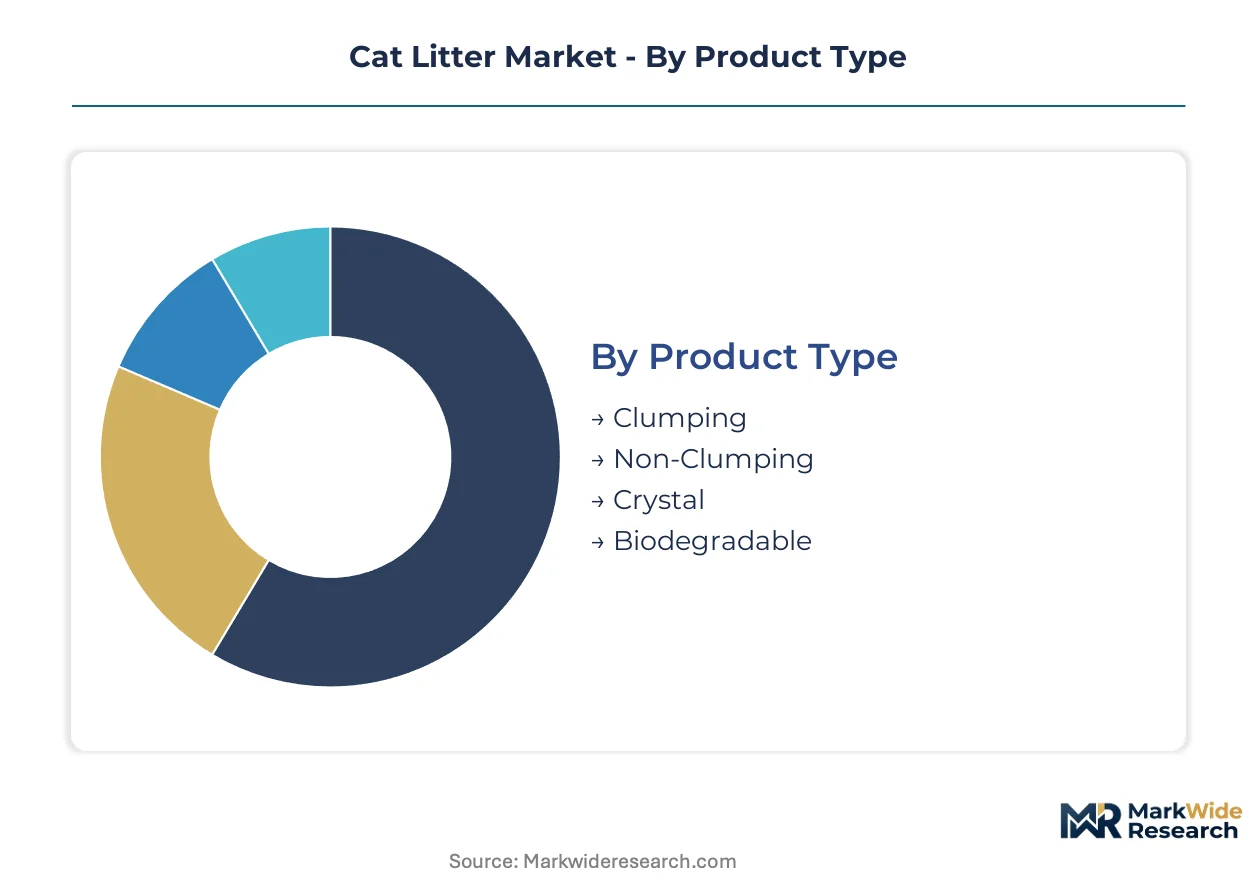
Cat litter manufacturers compete across distinct performance tiers and material platforms, each commanding different margin structures and regulatory exposure. Segmentation reveals where sodium bentonite mining integration, probiotic formulation R&D, and biodegradable feedstock sourcing create sustainable competitive moats.
Product Type:
Sodium bentonite chemistry and moisture-capture mechanics define the performance hierarchy across household and commercial deployment scenarios.
- Clumping:Sodium bentonite clay formulations form solid aggregates upon liquid contact, enabling selective waste removal without full tray replacement. Multi-cat households in the United States concentrate demand here, driven by EPA-registered odor-control additive compatibility and scoopable maintenance convenience.
- Crystal:Silica gel microstructure adsorbs moisture through capillary action, extending change intervals to 3-4 weeks. Apartment-dwelling pet owners in Mumbai and Bangalore favor this segment for compact storage and minimal dust generation in limited square footage.
- Non-Clumping:Absorbent clay or mineral substrates require complete tray replacement, sustaining price-sensitive volume through institutional procurement channels.
- Biodegradable:Corn, wheat, and pine fiber substrates decompose in municipal composting streams, attracting California and New York buyers facing SB 54 packaging waste mandates.
Clumping leads on scale; biodegradable leads on momentum.
Material:
Feedstock provenance determines supply security, dust exposure liability, and REACH compliance burden across manufacturing footprints.
- Clay:Wyoming-mined sodium bentonite supplies premium swelling capacity for clumping formulations. Three mining districts control deposit access, exposing integrated manufacturers to regional weather disruption and silica dust litigation risks in California courts.
- Wood:Pine and spruce fiber from Nordic and Canadian timber operations competes with biomass heating demand, constraining biodegradable litter feedstock availability.
- Corn:Midwest grain processing byproducts enter extruded pellet formulations, requiring humidity-controlled production lines foreign to clay-centric plants.
- Paper:Post-consumer recycled pulp aligns with California post-consumer content mandates, favoring molded pulp packaging over plastic jugs.
Clay dominates volume concentration; paper gains share fastest through regulatory tailwinds.
End User:
Procurement authority and performance specification intensity vary sharply across household, clinical, and institutional buyers.
- Pet Owners:Subscription auto-replenishment platforms capture recurring revenue from convenience-seeking households, bypassing retail slotting fees.
- Veterinarians:Clinical settings pilot probiotic and enzyme-based odor neutralization to reduce ventilation infrastructure costs.
- Pet Care Facilities:High-turnover shelters prioritize bulk unscented formulations through warehouse club tanker delivery programs in Texas and Florida.
- Retailers:Pet superstores and veterinary clinics carve dedicated premium shelf space for extended-change crystal variants.
Pet owners anchor demand volume; veterinarians drive formulation innovation premiums.
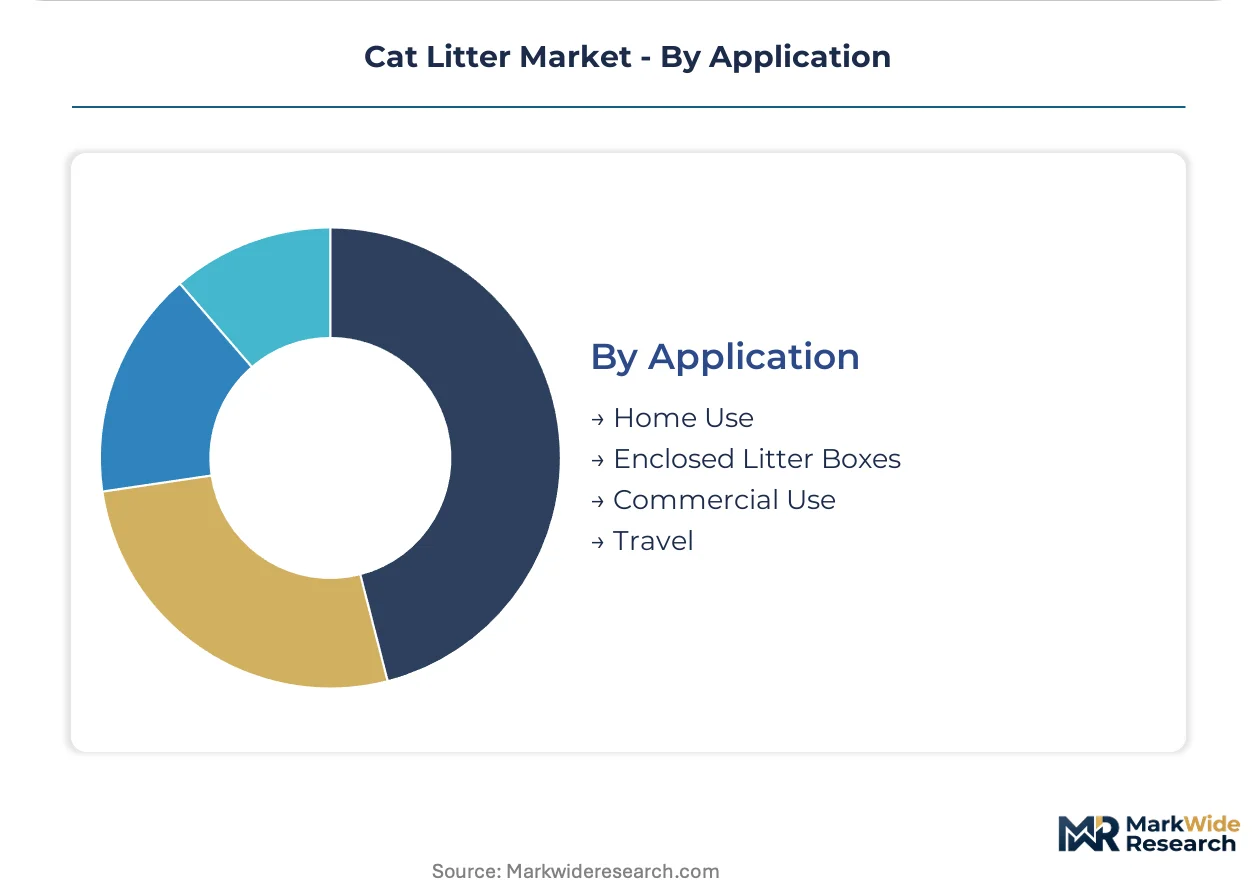
Application:
Deployment environment dictates dust tolerance, odor containment requirements, and portability specifications.
- Home Use:Standard tray configurations dominate, with scoopable clumping formulations preferred for daily maintenance routines.
- Enclosed Litter Boxes:Hooded and automated systems demand low-dust formulations to protect mechanical components and reduce respiratory exposure.
- Commercial Use:Boarding facilities and shelters prioritize bulk procurement of non-clumping substrates for cost-efficient full-tray replacement protocols.
- Travel:Disposable tray liners and lightweight crystal formulations address airline cargo constraints and temporary housing transitions.
Home use commands revenue scale; enclosed systems climb fastest through automation adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cat litter industry traces its industrial origins to Wyoming's sodium bentonite mining districts, where swelling clay deposits first enabled commercial clumping formulations during the mid-twentieth century.
United States
Multi-cat household formation in Texas and Florida compresses purchase cycles for high-performance clumping products. EPA registration requirements for antimicrobial odor-control additives extend new entrant lead times to 18-24 months under FIFRA. Wyoming's three mining districts supply premium sodium bentonite to integrated manufacturers, though silica dust litigation in California courts elevates product liability exposure.
Germany
REACH authorization mandates for biocidal additives force reformulation of zinc pyrithione and triclosan alternatives, stretching development cycles by 12-18 months. German distributors prioritize suppliers with pre-registered substance portfolios to avoid customs delays at Hamburg and Bremerhaven ports. The country's veterinary clinic networks pilot probiotic-based odor neutralization to reduce ventilation infrastructure costs.
China
Apartment-dwelling cat adoption in Shanghai and Shenzhen drives demand for compact, low-dust crystal formulations suited to limited square footage. The country's national chemical regulator enforces GB standards for silica gel manufacturing, tightening purity specifications for export-bound production. Yangtze River Delta manufacturers scale humidity-controlled extrusion systems for corn and wheat starch biodegradable lines.
India
First-time pet ownership in Mumbai and Bangalore creates buyer pools for scoopable maintenance products among urban apartment dwellers. The Bureau of Indian Standards (BIS) has yet to impose mandatory additive disclosure rules, preserving formulation flexibility for domestic producers. Maharashtra-based distributors experiment with subscription auto-replenishment platforms to bypass traditional retail slotting fees.
France
EU REACH chemical disclosure mandates advantage compliant domestic producers with established toxicological testing protocols. ANSM and CNIL oversight intersects with ECHA biocidal product regulations to shape marketing claims transparency. The Île-de-France region concentrates pet specialty retail expansion, with Parisian suburbs hosting in-store bulk refill dispensing systems for unscented clay variants.
Cat Litter Market Vendor Landscape
The competitive structure tilts toward integrated mining-and-manufacturing conglomerates with captive Wyoming bentonite access. Three strategic archetypes dominate: diversified consumer goods conglomerates leveraging broad retail channel control, specialty pet care pure-plays emphasizing veterinary clinic relationships, and mineral extraction specialists with upstream deposit ownership. Competitive moves concentrate on sodium bentonite mining consolidation and probiotic formulation R&D partnerships with biotechnology firms.
Among diversified consumer goods conglomerates, Nestlé Purina PetCare and Mars Incorporated occupy positions defined by extensive R&D infrastructure and mass-market distribution scale. Church & Dwight Co., Inc. exemplifies the specialty chemical archetype, while The Clorox Company anchors the retail channel control vector through brand recognition in mass-market distribution. Oil-Dri Corporation of America represents the upstream-integrated mining specialist, with Dr. Elsey's occupying the veterinary-endorsed premium tier.
| Leading Market Players |
|---|
| Oil-Dri Corporation of America |
| Dr. Elsey's |
| Nestlé Purina PetCare |
| Kent Corporation |
| Healthy Pet L.P. |
| The Clorox Company |
| Church & Dwight Co., Inc. |
| Intersand |
| Mars Incorporated |
| Others |
Supply Flow & Price Mechanics
Captive sodium bentonite mining in Wyoming's three districts anchors both supply security and pricing power for integrated clumping litter manufacturers. This upstream control insulates established producers from input cost volatility while compressing margins for non-integrated competitors forced into spot market purchases.
Pricing Analysis
Packaged retail goods and bulk refill dispensing split the pricing architecture between convenience premiums and volume discounts. Three-tier pricing structure across premium crystal, standard clumping, and economy non-clumping levels separates performance tiers by odor-control technology and change interval claims. Cost compression in the mid-tier clay segment intensifies because Wyoming mining consolidation limits second-source options. Multi-cat households show lowest price sensitivity, while first-time apartment adopters in emerging markets gravitate toward entry-level formulations.
Supply Chain Analysis
Reverse logistics for reusable bulk containers and in-store refill systems are reshaping last-mile distribution economics in suburban Texas and Florida markets. Primary bentonite extraction concentrates in Wyoming, with silica gel manufacturing anchored in China's Yangtze River Delta and pine fiber sourcing drawn from Nordic timber operations. Single-source vulnerability in Wyoming's weather-exposed mining districts elevates force majeure risk for clumping formulation supply. Distribution runs through pet specialty retailers, warehouse club tanker programs, and subscription direct-to-home platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in probiotic formulation premiums and captive bentonite integration, with cost-down drivers emerging from automated production lines and bulk refill channel economics.
For Market Incumbents: Hedge against silica dust litigation exposure in California and New York courts by accelerating low-dust crystal and biodegradable line capacity. Secure captive Wyoming deposit access through lease consolidation or joint venture structures before mining district consolidation completes. EPA registration timelines for antimicrobial additives remain the critical bottleneck; prioritize pre-submission toxicological dossiers to compress FIFRA compliance windows.
For New Entrants and Emerging Players: California SB 54 packaging waste mandates open a window for molded pulp and paper-based litter formulations that bypass plastic jug requirements. Target first-time pet owners in Mumbai and Bangalore through compact, low-dust crystal products suited to apartment constraints. Launch via subscription auto-replenishment platforms to circumvent retail slotting fee barriers and capture recurring revenue streams.
For Investors and Strategic Acquirers: Consolidation pressure builds where REACH-registered substance portfolios intersect with captive Wyoming bentonite access, creating scarcity value for compliant integrated assets. Veterinary-endorsed premium tiers and probiotic formulation capabilities represent the most defensible acquisition archetypes over extended holding periods. Monitor EPA per- and polyfluoroalkyl substances restriction proposals as inflection indicators for forced material substitutions across conventional clay supply chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Probiotic Formulation Development | Biotechnology partnerships with enzyme suppliers compress the performance gap between clay and crystal tiers. |
| Wyoming Mining Lease Consolidation | Captive bentonite access secures input cost stability against regional weather disruption risks. |
| Subscription Platform Launch | Auto-replenishment bypasses retail slotting fees and locks recurring revenue from convenience-seeking households. |
| REACH Pre-Registration Investment | Toxicological dossier preparation avoids customs delays at Hamburg and Bremerhaven ports. |
| Bulk Refill Dispensing Infrastructure | In-store tanker systems capture warehouse club volume commitments in Texas and Florida suburban markets. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at Wyoming mining operations, procurement leads at downstream pet care manufacturers, distribution channel partners in German and French import networks, and technical R&D directors overseeing probiotic formulation development. Secondary validation drew from EPA FIFRA registration databases, ECHA REACH substance portfolios, customs and trade flow records, and SEC 10-K filings of publicly traded pet care conglomerates. Bottom-up volume modeling across material platforms and end-user segments triangulated against top-down market sizing from production capacity assessments.
Historical reference periods anchored volume and value projections across the analysis window, with segmentation dimensions spanning product type, material chemistry, end-user procurement authority, and application environment. CAGRs derived from regression analysis of mining output trends, household formation patterns, and regulatory compliance cost trajectories. Forecast inputs incorporated Wyoming bentonite deposit depletion rates and REACH authorization timelines for biocidal additives.
Revisions become necessary when EPA per- and polyfluoroalkyl substances restrictions materialize, REACH substance authorization timelines extend, or Wyoming mining district labor disruptions emerge. Forecasts reflect assumptions about continued clumping formulation dominance and probiotic technology adoption curves. Practitioners should monitor ECHA biocidal product committee rulings and California appellate court silica dust litigation outcomes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
UAE Pet Boarding Market
Pet Care Products
Japan Organic and Natural Pet Food Market
Pet Care Products
North America Pet Treats Market
Pet Care Products
Saudi Arabia Pet Boarding Market
Pet Care Products
Fish Based Pet Food Market
Pet Care Products
Pet Grooming Services Market
Pet Care Products
US and Mexico Cat Litter Market
Pet Care Products
Bird Toy Market
Pet Care Products
Pet Furniture Market
Pet Care Products
Pet Apparel Market
Pet Care Products
UK Pet Treats Market
Pet Care Products
Dog Harness Market
Pet Care Products
Asia-Pacific Pet Clothing Market
Pet Care Products
US Pet Boarding Market
Pet Care Products
Smart Pet Kennel Market
Pet Care Products
Dog Litter Boxes Market