
 Dog Raincoats Market | 2026-2036
Dog Raincoats Market Size, Share, and Industry Trends Forecast 2026-2036
Dog Raincoats Market Analytics
Subscription-based replenishment for seasonal sizing is consolidating how pet apparel brands retain customers beyond single transactions. Kurgo leverages its direct-to-consumer platform to sustain recurring revenue through weather-alert triggered campaigns. HugeHounds anchors its position with breed-specific measurement tools that reduce return rates. Non-stop Dogwear competes through Nordic-tested durability standards that extend product lifecycles in harsh climates.
A dog raincoat constitutes a weather-resistant outer garment engineered with sealed seams, waterproof membranes measured in millimeters of hydrostatic head rating, and adjustable fastening systems to maintain thermoregulation during precipitation exposure. Its commercial purpose centers on protecting canine skin and coat integrity while enabling sustained outdoor exercise in wet conditions. Waterproof coats and reflective gear command premium positioning due to dual-function safety value, while fleece-lined variants capture margin pools in temperate climates where insulation drives replacement frequency. Nylon and polyester dominate material procurement for their strength-to-weight ratios and quick-dry properties, though PVC faces displacement from phthalate-conscious buyers.
The US Consumer Product Safety Commission monitors choking hazards in pet apparel hardware, while California's Proposition 65 imposes labeling burdens on coated textiles containing trace heavy metals. The OEKO-TEX Standard 100 certification shapes supplier selection for brands seeking European export access and domestic premium positioning. Stakeholders must monitor evolving state-level chemical disclosure laws and decide whether to front-run compliance costs or segment product lines by regulatory jurisdiction.
Market Dynamics
California's Proposition 65 enforcement on textile chemicals is compressing formulation choices across the Dog Raincoats Market, forcing manufacturers to abandon solvent-based coatings and accelerate migration toward OEKO-TEX certified supply chains.
Growth Catalysts
- Urban Pet Ownership Density:Pacific Northwest metropolitan clusters sustain year-round outdoor exercise routines with dogs, generating consistent replacement demand for weather-resistant apparel.
- REACH Chemical Restrictions:European regulatory pressure on phthalates and heavy metals in coated textiles is elevating certified fabric premiums and rewarding early compliance investments.
- Reflective Safety Integration:Dual-function garments combining waterproof membranes with high-visibility elements command pricing power from safety-conscious owners in low-light climates.
Market Restraints
- Petroleum-Derived Input Volatility:Nylon and polyester feedstock costs fluctuate with crude oil indices, compressing margins for mid-tier manufacturers without long-term polymer contracts.
- Asian Manufacturing Concentration:Fabric weaving and membrane lamination capacity clusters in Zhejiang and Guangdong provinces, exposing brands to shipping rate spikes and tariff uncertainty.
- Size Standardization Gaps:Absence of universal canine measurement protocols elevates return processing costs and inventory fragmentation for multi-breed product lines.
Strategic Opportunities
- Subscription Replenishment Models:Weather-alert triggered direct-to-consumer campaigns lock in recurring revenue beyond single-transaction seasonal purchases.
- Breed-Specific Customization:Deep-chested and long-backed breeds remain underserved by off-rack sizing, creating white space for made-to-measure digital tools.
- Nordic Climate Export:Harsh-weather durability testing protocols developed for Scandinavian markets differentiate products for premium positioning in coastal US and Canadian regions.
Industry Challenges
- Hardware Safety Certification:US Consumer Product Safety Commission choking hazard monitoring requires rigorous buckle and fastener testing, extending product development timelines.
- Multi-Jurisdictional Labeling:State-level chemical disclosure laws fragment packaging requirements, forcing brands to either front-run compliance costs or segment production runs by destination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dog Raincoats Market |
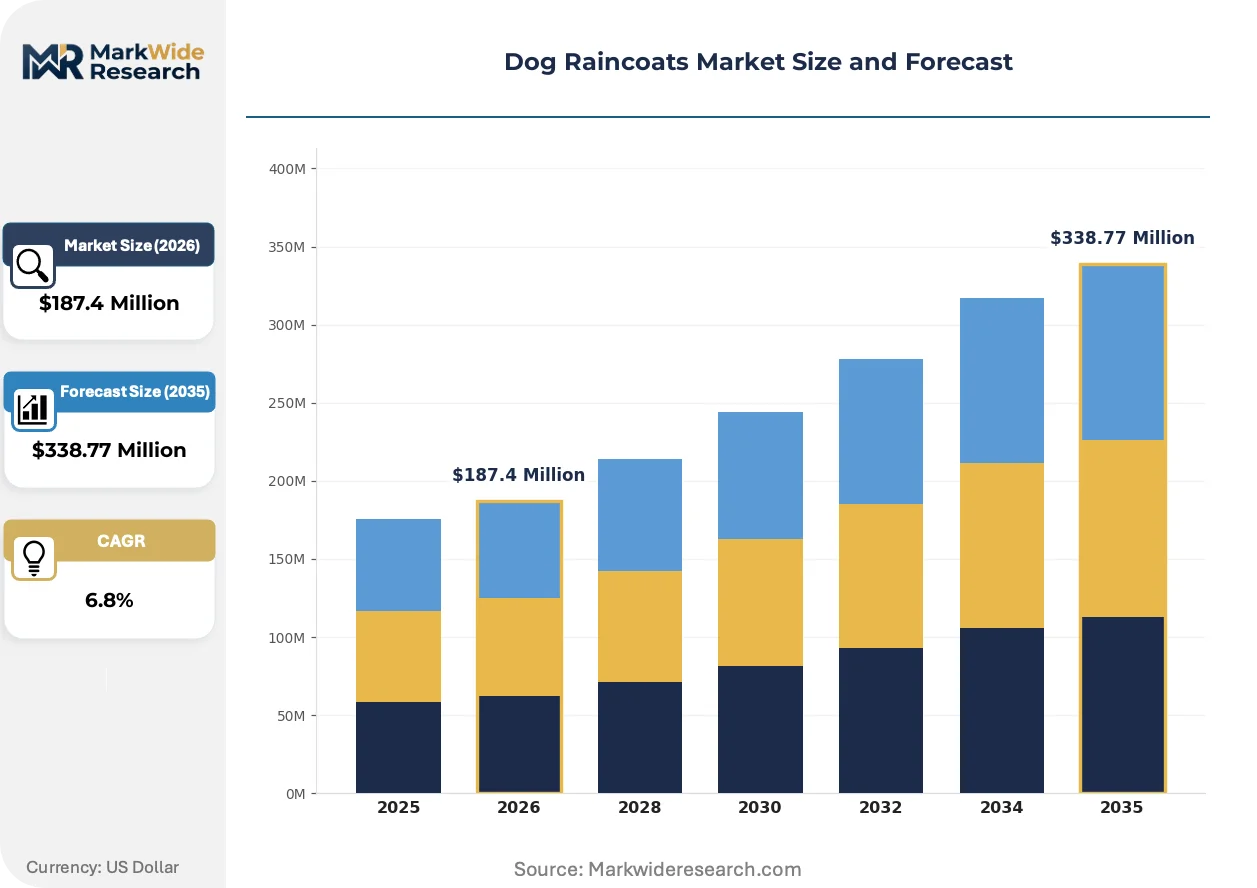
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Waterproof Coats, Lightweight Jackets, Reflective Gear, Fleece-lined Coats Material: Nylon, Polyester, PVC, Cotton Blend Size: X-Small, Small, Medium, Large End User: Pet Owners, Dog Shelters, Pet Retailers, Veterinary Clinics |
| Companies Covered | Kurgo, HugeHounds, Non-stop Dogwear, Ningbo V. K. Industry and Trading Co., Ltd., Jiangmen Muyjis Pet Products Co., Ltd., Ruffwear, Voyagers K9 Apparel, Hangzhou Tianyuan Pet Products Co., Ltd., Hurtta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dog Raincoats Market Evolving Landscape
Material science advances and regulatory chemistry restrictions are converging to reshape competitive positioning in canine weather apparel, with certification-driven procurement and digital fit technologies emerging as decisive differentiators.
Water-based polyurethane coatings are decentralizing manufacturing location decisions for waterproof membranes. Small-batch producers in Oregon and Vermont now source OEKO-TEX certified laminates from regional textile mills rather than importing pre-coated fabrics from Asia. This geographic redistribution shortens lead times for seasonal product drops and reduces exposure to trans-Pacific shipping volatility.
California's Proposition 65 warning label mandates for trace heavy metals in coated textiles are compressing supplier qualification timelines. Brands seeking domestic premium positioning must document supply chain chemistry at the fiber level, with non-compliant batches facing retailer rejection before reaching consumers. The burden falls heaviest on value-tier private labels lacking dedicated compliance infrastructure.
Breed-specific measurement algorithms are displacing generic size charts in direct-to-consumer channels. Owners of French Bulldogs, Dachshunds, and Greyhounds—breeds with proportions deviating from industry-standard sizing—drive adoption of smartphone-based fitting tools that reduce return rates. This behavioral shift concentrates in metropolitan markets with high purebred registration density and elevated digital commerce penetration.
Dog Raincoats Market Segmentation
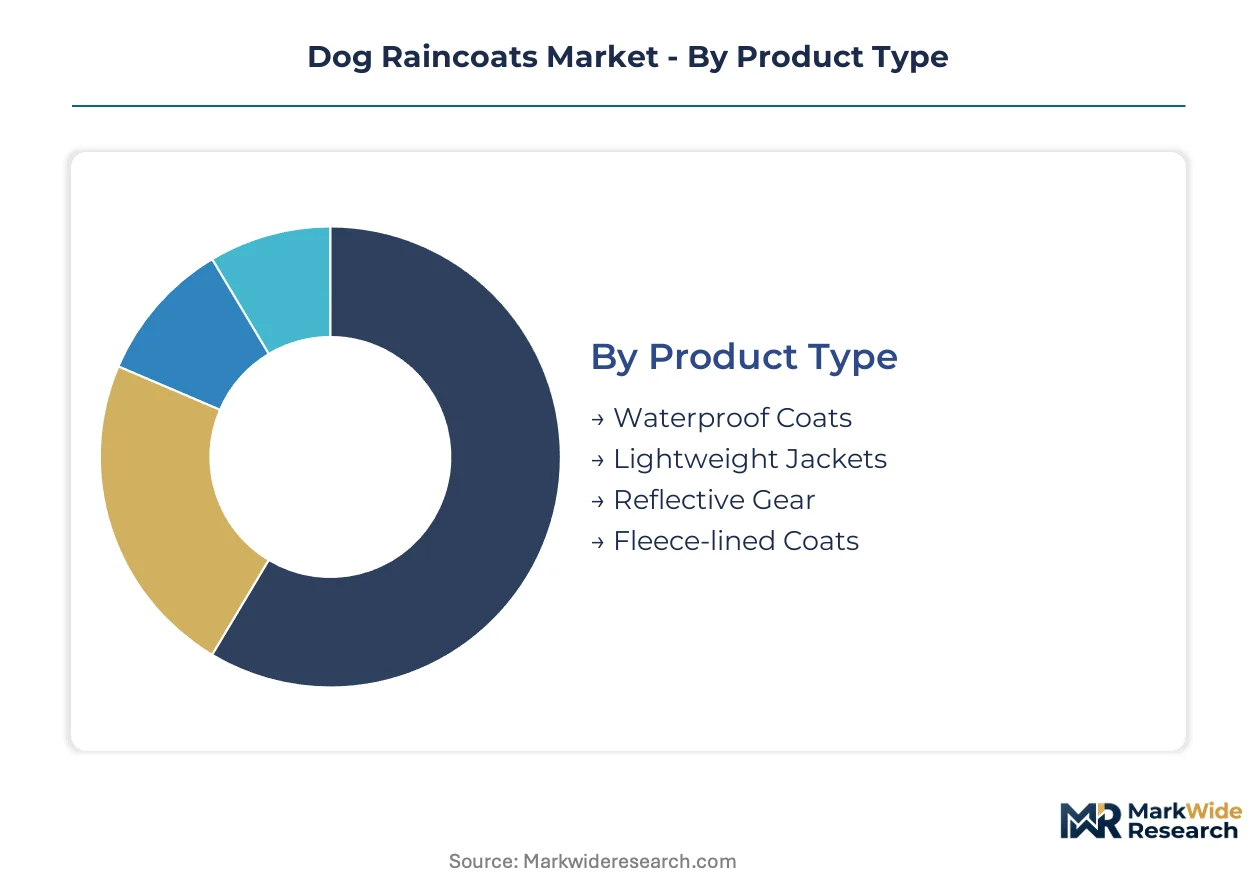
Product differentiation in canine weather apparel tracks directly to climate severity and owner activity patterns. Segmentation reveals how material certification, breed morphology, and channel economics partition margin pools across the value chain.
Product Type:
Buyer decisions pivot on dual-function requirements combining weather protection with visibility or thermal regulation in specific precipitation conditions.
- Waterproof Coats:Engineered with sealed seams and hydrostatic head ratings exceeding 10,000mm, these garments incorporate adjustable neck gussets and belly coverage for complete moisture exclusion. Demand concentrates in Seattle and Portland metropolitan clusters where year-round outdoor exercise routines sustain replacement cycles every 18-24 months.
- Reflective Gear:High-visibility strips bonded to waterproof membranes achieve ANSI/ISEA 107-equivalent luminance for dawn and dusk safety. The Pacific Northwest and Northeast corridor drive adoption where shortened winter daylight hours elevate safety-conscious purchasing.
- Lightweight Jackets:Unlined shells prioritize packability for intermittent drizzle in temperate zones.
- Fleece-lined Coats:Thermal retention layers target transitional seasons in coastal California and mid-Atlantic states.
Waterproof coats lead on scale; reflective gear leads on momentum.
Material:
Procurement economics and regulatory chemistry restrictions now dominate supplier qualification timelines.
- Nylon:Ripstop weaves with denier ratings of 210D-420D deliver optimal strength-to-weight ratios for active breeds. REACH chemical restrictions on heavy metal catalysts in polymer production elevate certified fiber premiums.
- Polyester:Recycled PET variants capture sustainability-positioned buyers in metropolitan markets with elevated environmental consciousness.
- PVC:Phthalate-conscious buyers in California and EU export markets accelerate displacement of conventional coated fabrics.
- Cotton Blend:Breathable natural fiber content appeals to owners of short-coated breeds prone to overheating.
Nylon dominates volume throughput; polyester climbs the fastest on sustainability credentials.
Size:
Inventory fragmentation and return processing costs escalate where breed morphology deviates from standardized measurement protocols.
- Large:Deep-chested breeds including German Shepherds and Golden Retrievers require extended belly panels and adjustable neck openings. Absence of universal canine measurement standards elevates fit-related returns to 15-20% for this tier.
- Medium:Labrador Retrievers and Border Collies constitute the densest population segment, supporting economy-of-scale production runs.
- Small:French Bulldogs and Dachshunds with disproportionate chest-to-length ratios drive adoption of smartphone-based fitting tools.
- X-Small:Toy breeds under 15 pounds represent a margin-compressed niche with limited SKU investment.
Medium sizes anchor production planning; large sizes gain share fastest on breed popularity trends.
End User:
Channel economics and purchase frequency diverge sharply between individual owners and institutional buyers.
- Pet Owners:Direct-to-consumer platforms capture recurring revenue through weather-alert triggered replenishment campaigns. Urban households in precipitation-heavy metros sustain 2-3x replacement frequency versus national averages.
- Pet Retailers:Multi-brand assortments require OEKO-TEX certification documentation for shelf placement in premium channels.
- Dog Shelters:Bulk procurement prioritizes durability over styling for outdoor kennel operations.
- Veterinary Clinics:Post-surgical recovery applications represent a clinically validated niche with prescription-level pricing tolerance.
Pet owners generate the steepest expansion trajectory; pet retailers concentrate margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pet owners spend three times more per capita on canine weather apparel than Italian households, yet both markets face identical REACH chemical compliance deadlines for coated textiles.
United States
Pacific Northwest metropolitan clusters sustain replacement cycles every 18-24 months through year-round outdoor exercise routines. California's Proposition 65 enforcement compels manufacturers to abandon solvent-based coatings for water-based alternatives. Seattle and Portland anchor domestic demand concentration, with urban pet owners driving premium positioning for dual-function reflective gear.
Germany
REACH chemical restrictions on phthalates and heavy metals elevate certified fabric premiums across the value chain. ECHA enforcement timelines compress supplier qualification windows for brands seeking EU market access. Bavaria's textile engineering heritage supports regional laminate production, reducing import dependency for membrane materials.
United Kingdom
Nordic-tested durability standards command premium positioning among safety-conscious owners in low-light winter conditions. The country's departure from EU regulatory frameworks introduces parallel compliance obligations for cross-border trade. Greater London's dense pet ownership sustains direct-to-consumer platform penetration for subscription replenishment models.
China
Zhejiang and Guangdong provinces concentrate fabric weaving and membrane lamination capacity, exposing brands to shipping rate volatility and tariff uncertainty. GB standards for textile safety create divergent testing protocols from Western certification schemes. Yangtze River Delta manufacturing clusters serve both domestic pet apparel growth and export contract production.
Japan
METI guidelines on product safety shape hardware testing requirements for buckles and fasteners in pet apparel. Kanto region metropolitan density supports premium positioning for breed-specific measurement tools. Tokyo's purebred registration concentration drives smartphone-based fitting technology adoption among owners of proportionally atypical breeds.
Dog Raincoats Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with direct-to-consumer platforms capturing recurring revenue while Asian fabricators dominate volume throughput. The vendor base organizes around three strategic archetypes: weather-alert triggered subscription operators, Nordic-tested durability specialists, and breed-specific measurement innovators. Capacity expansion and geographic redistribution of laminate sourcing constitute the dominant competitive moves, with regional textile mills in Oregon and Vermont displacing pre-coated Asian imports.
Within the branded specialist tier, Kurgo and HugeHounds exemplify divergent channel strategies, while Non-stop Dogwear anchors the Nordic-tested durability positioning. Among China-based fabricators, Ningbo V. K. Industry and Trading Co., Ltd. and Jiangmen Muyjis Pet Products Co., Ltd. occupy positions in contract manufacturing supply chains. Hangzhou Tianyuan Pet Products Co., Ltd. represents the scale-driven export archetype serving cross-border e-commerce demand.
| Leading Market Players |
|---|
| Kurgo |
| HugeHounds |
| Non-stop Dogwear |
| Ningbo V. K. Industry and Trading Co., Ltd. |
| Jiangmen Muyjis Pet Products Co., Ltd. |
| Ruffwear |
| Voyagers K9 Apparel |
| Hangzhou Tianyuan Pet Products Co., Ltd. |
| Hurtta |
| Others |
Value Network & Pricing Analysis
Urban pet owners in precipitation-heavy metropolitan clusters anchor demand concentration and sustain subscription-based pricing models that lock in recurring revenue through weather-alert triggered replenishment cycles.
Pricing Analysis
Capacity additions in regional textile mills across Oregon and Vermont are reshaping price floors for water-based polyurethane coatings. Three-tier pricing structure across premium, standard, and economy levels stratifies by OEKO-TEX certification grade and hydrostatic head performance ratings. Cost compression in mid-tier nylon variants is intensifying because petroleum-derived feedstock volatility feeds directly into polymer contract renegotiations. Value-tier private labels exhibit highest price sensitivity due to compliance infrastructure gaps, while Nordic-tested durability specialists command lowest sensitivity through proven harsh-climate performance.
Supply Chain Analysis
California's Proposition 65 enforcement and REACH chemical restrictions are reshaping sourcing decisions toward OEKO-TEX certified regional suppliers. Fabric weaving and membrane lamination capacity draws from Zhejiang and Guangdong provinces in China, with emerging backup capacity in Bavaria and the US Pacific Northwest. Raw material dependencies center on nylon and polyester polymers, water-based coating formulations, and reflective strip laminates. Single-source vulnerability concentrates in Asian membrane lamination clusters exposed to trans-Pacific shipping volatility. Distribution runs through direct-to-consumer platforms for branded specialists and cross-border e-commerce aggregators for contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where California Proposition 65 enforcement and REACH chemical deadlines continuously elevate compliance costs and reward early certification investments.
For Market Incumbents: To counter Asian manufacturing concentration risks, secure long-term polymer contracts with Zhejiang-based weavers while accelerating backward integration into regional OEKO-TEX certified laminate production in Oregon and Vermont. Certification investment serves as the primary defensive lever against value-tier private label displacement. For New Entrants and Emerging Players: Begin with breed-specific measurement algorithms targeting French Bulldogs, Dachshunds, and Greyhounds—segments underserved by generic sizing protocols. Smartphone-based fitting tools represent the most penetrable white space, with direct-to-consumer launch enabling bypass of retailer certification documentation barriers. For Investors and Strategic Acquirers: Pet apparel multinationals seeking geographic diversification are the most active acquirer in this space. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than brand equity alone. Acquisition targets should demonstrate documented fiber-level chemistry traceability. Watch for OEKO-TEX Standard 100 certification adoption velocity as the inflection indicator separating viable platforms from stranded assets.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Laminate Sourcing | Oregon and Vermont mills reduce trans-Pacific shipping exposure for seasonal product drops. |
| Breed-Specific Digital Fitting | Smartphone algorithms cut return rates for deep-chested and long-backed breeds. |
| Subscription Replenishment Launch | Weather-alert campaigns convert single-transaction buyers into recurring revenue streams. |
| Water-Based Coating Migration | Proposition 65 compliance eliminates solvent-based formulation regulatory rejection risk. |
| Nordic Durability Certification | Scandinavian testing protocols differentiate premium positioning in coastal US markets. |
Research Methodology
Multiple input streams — primary interviews with brand managers and supply chain directors, secondary validation through customs records and OEKO-TEX certification databases, and triangulation against SEC filings from disclosed pet apparel suppliers — were reconciled to construct market estimates. Conversations captured procurement lead perspectives at Pacific Northwest retailers, compliance officers at California-based manufacturers, and category buyers at direct-to-consumer platforms. Bottom-up unit economics and top-down retail audit data were cross-referenced to anchor volume assumptions.
Data-stream reconciliation across product type, material certification tier, breed size morphology, and channel economics enabled segmentation-level modeling across the analysis window. CAGRs were derived from replacement cycle frequency analysis tied to metropolitan precipitation patterns and pet ownership density. Forecast inputs incorporated hydrostatic head rating adoption curves and smartphone-based fitting tool penetration rates in purebred-dense markets.
Caveats apply where feedstock price volatility, shipping rate spikes, or accelerated state-level chemical disclosure laws could materially shift the outlook. Forecasts reflect documented assumptions about regulatory enforcement timelines and breed popularity trends. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Mink Oil Market
Pet Care Products
Europe Pet Smart Tracker Market
Pet Care Products
Pet Stairs Market
Pet Care Products
Dog Harness Market
Pet Care Products
Cat Nail Clippers Market
Pet Care Products
Pet Water Dispenser Market
Pet Care Products
Germany Pet Clothing Market
Pet Care Products
Frozen Pet Food Market
Pet Care Products
Pet Care E-Commerce Market
Pet Care Products
Parrot Cage Market
Pet Care Products
Japan Organic and Natural Pet Food Market
Pet Care Products
Australia Pet Boarding Market
Pet Care Products
US Pet Boarding Market
Pet Care Products
UK Pet Treats Market
Pet Care Products
Tofu Cat Litter Market
Pet Care Products
United States Pet Market