
 Pet Grooming Services Market | 2026-2036
Pet Grooming Services Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Grooming Services Market Intelligence
Mobile booking and AI-powered scheduling is fragmenting how pet grooming services reach customers, replacing traditional phone-based appointment systems with platform-driven logistics. PetSmart LLC leverages its nationwide store footprint to anchor in-store grooming volume across suburban markets. Wag Labs Inc. competes through app-based dispatch that connects pet owners with independent groomers for on-demand service. Petco Animal Supplies Inc. differentiates by integrating veterinary wellness checks into its grooming packages, creating stickier customer relationships.
Pet grooming services encompass hygienic maintenance procedures performed on companion animals, including coat cleaning with pH-balanced formulations, mechanical de-shedding using specialized undercoat rakes, and nail grinding with variable-speed rotary tools designed to avoid quick injury. These services prevent dermatological conditions, reduce household allergen loads, and support early detection of lumps or parasites during hands-on inspection. Bathing and brushing together occupy the core revenue pool due to their high frequency and lower capital requirements, while spa packages represent the fastest-growing margin tier as owners trade up to aromatherapy treatments and mud therapies. Mobile grooming is displacing self-service stations in dense metropolitan zones where time scarcity among dual-income households outweighs cost sensitivity.
The FDA regulates topical pet care products through its Center for Veterinary Medicine, requiring safety substantiation for medicated shampoos that influences formulation choices by service chains. OSHA guidelines on salon ventilation and ergonomic lifting shape staffing costs and facility design standards that operators must absorb. State-level cosmetology boards in California, Texas, and New York impose licensing thresholds that create barriers to entry for independent groomers. Stakeholders must monitor whether platform-based labor classification disputes trigger reclassification of gig groomers as employees, altering unit economics across mobile and on-demand models.
Market Dynamics
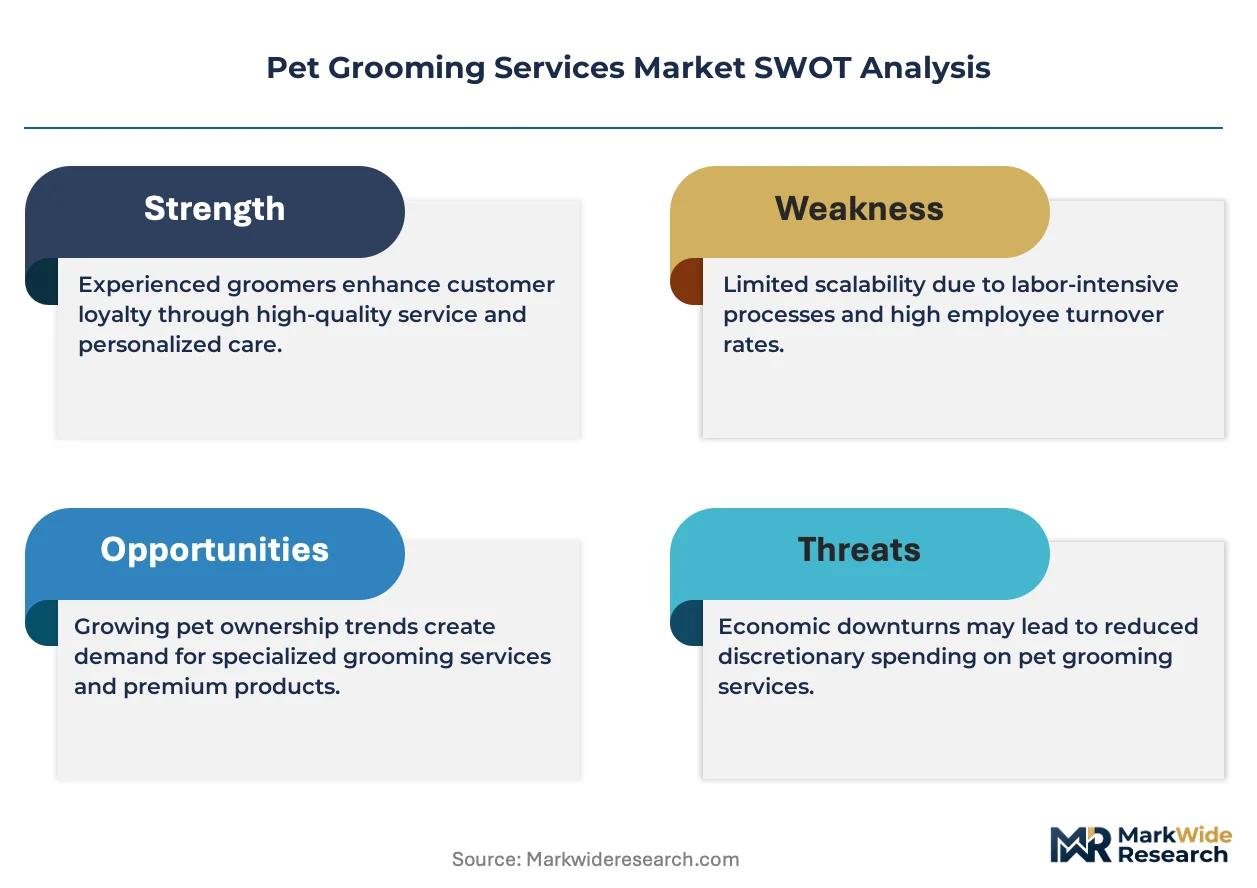
Mobile platform adoption is fragmenting service delivery across urban markets, replacing fixed-location salon dependency with algorithmic dispatch models that compress customer acquisition costs while expanding addressable households.
Growth Catalysts
- REACH Chemicals Framework:The EU's tightening ingredient disclosure requirements for topical pet products are accelerating formulation transparency investments by service chains, creating competitive differentiation through certified clean-label offerings.
- AI-Powered Scheduling:Predictive demand algorithms are optimizing groomer utilization rates, reducing idle time in mobile units and enabling same-day appointment fulfillment that captures time-scarce dual-income households.
- Urban Cluster Concentration:High-density metropolitan zones in the United States, China, and Germany are generating sufficient route density to support profitable mobile grooming unit economics.
Market Restraints
- Veterinary-Grade Input Costs:FDA-mandated safety substantiation for medicated shampoos elevates raw material sourcing expenses and extends product development timelines for service chains.
- State Licensing Fragmentation:California, Texas, and New York maintain divergent cosmetology board requirements that prevent standardized staffing models and increase compliance overhead for multi-state operators.
- Fixed Facility Capital Intensity:Salon ventilation and ergonomic lifting equipment mandated by OSHA guidelines require upfront capital outlays that disadvantage independent groomer entry.
Strategic Opportunities
- Veterinary Wellness Integration:Bundling grooming with preventive health checks creates stickier customer relationships and opens recurring revenue streams through subscription models.
- Spa Package Tier Expansion:Aromatherapy and mud therapy treatments represent underexploited margin pools as millennial pet owners trade up from basic bathing services.
- Gig Groomer Reclassification Risk:Platform operators who proactively structure employment relationships ahead of potential labor classification disputes will capture groomer supply that competitors lose to regulatory uncertainty.
Industry Challenges
- Certified Groomer Talent Scarcity:State-level licensing thresholds create bottlenecks in qualified labor supply, extending hiring timelines and elevating wage pressure in competitive metro markets.
- Legacy Phone-Based Booking Systems:Incumbent operators dependent on traditional appointment infrastructure face customer attrition to platform-native competitors with seamless mobile interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Grooming Services Market |
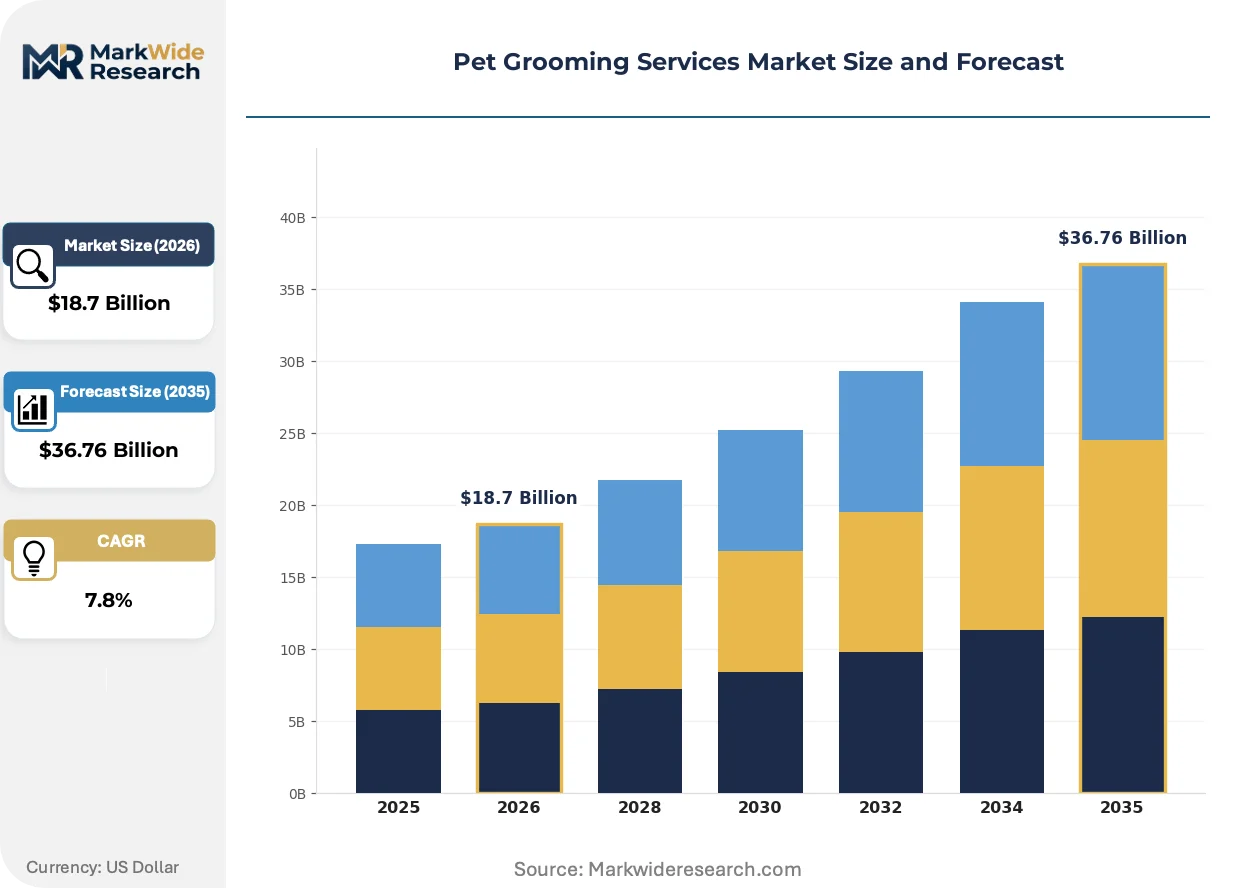
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $36.76 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Bathing, Brushing, Nail Trimming, De-shedding Animal Type: Dogs, Cats, Rabbits, Guinea Pigs Service Model: Mobile Grooming, In-store Grooming, Self-service, Spa Packages Customer Type: Pet Owners, Breeders, Shelters, Vet Clinics |
| Companies Covered | Independent Pet Partners, Wag Labs Inc., PetSmart LLC, Pet Palace Resort, PetPeople Enterprises LLC, Petco Animal Supplies Inc., Dogtopia Enterprises, Zoomin Groomin, Pets At Home Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Grooming Services Market Strategic Shifts & Innovations
Digital infrastructure investments are compressing the service delivery window while elevating quality transparency expectations. Three converging developments are restructuring competitive positioning across the value chain.
Variable-speed rotary nail grinding equipment is migrating from high-end specialty salons to mainstream service tiers. Independent mobile operators in dense urban corridors are adopting these tools to differentiate on safety metrics. The technology is migrating from premium positioning toward standard service inclusion, compressing price premiums that early adopters previously commanded.
OSHA ventilation guidelines are forcing facility redesign investments across fixed-location operators. The industrial consequence is accelerated consolidation as smaller salons absorb capital costs or exit. Suburban strip-mall locations in the United States are most affected, with chains leveraging scale to amortize HVAC upgrades across multiple sites.
Subscription-based grooming packages are displacing transactional appointment models among high-frequency users. Platform operators are capturing this shift through auto-renewal billing and priority scheduling guarantees. This pattern is most visible in German and Chinese urban markets where pet insurance penetration correlates with preventive service bundling acceptance.
Pet Grooming Services Market Segmentation
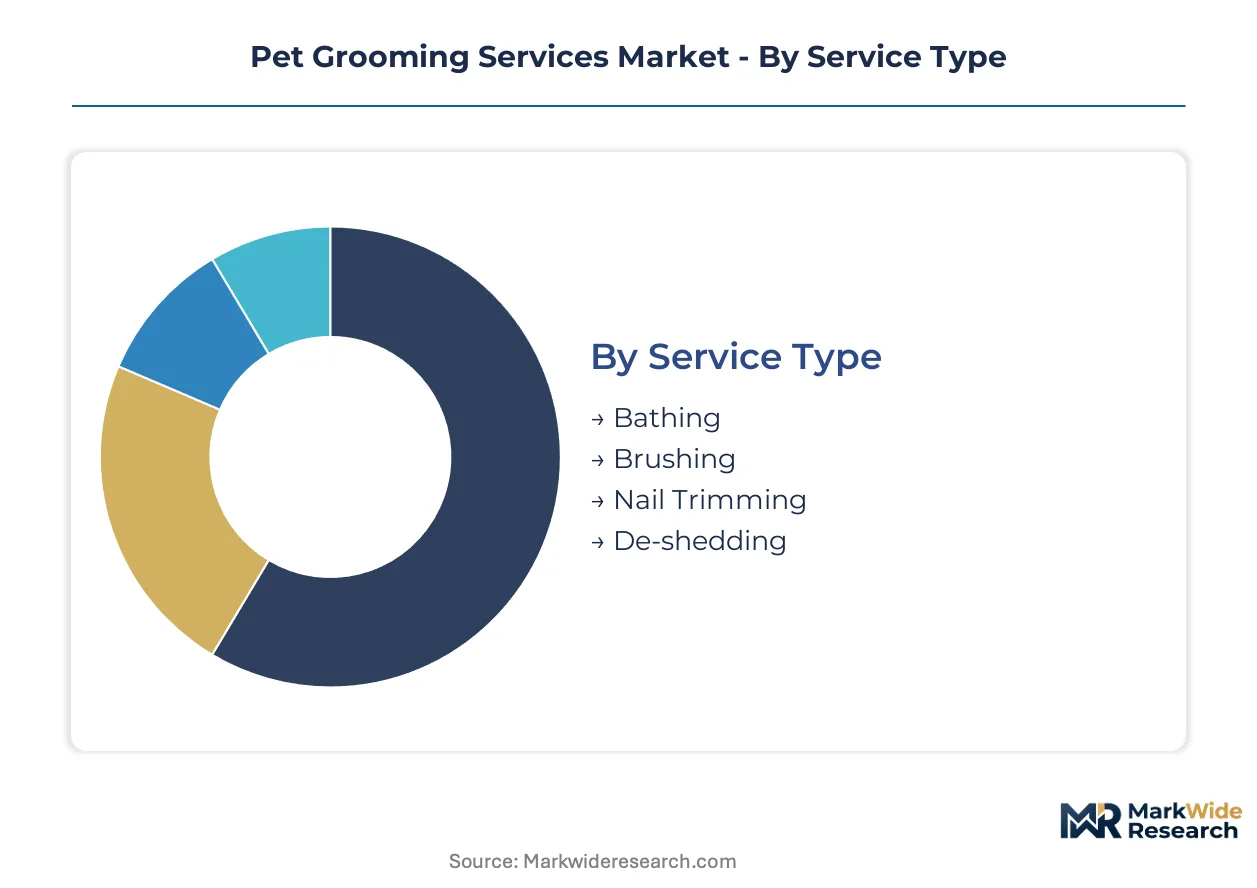
Segmentation in pet grooming services reveals how demand fragments across service intensity, species-specific needs, and delivery economics. Understanding these dimensions exposes where pricing power concentrates and which operational models capture disproportionate margin.
Service Type:
Cost tier determines frequency, capital requirements, and margin structure across the service spectrum.
- Bathing:pH-balanced formulation cleaning removes surface oils and environmental allergens while maintaining epidermal barrier integrity. Frequency concentrates among urban dog owners in the United States and Germany where apartment living elevates hygiene standards. Lower capital barriers sustain independent operator participation.
- Brushing:Mechanical coat maintenance using slicker brushes and undercoat rakes prevents matting and distributes natural sebum. Demand clusters with long-haired breed ownership in suburban United States markets where seasonal shedding drives appointment scheduling. This service anchors recurring revenue through subscription bundling.
- Nail Trimming:Quick-avoidance techniques using variable-speed rotary tools reduce injury risk.
- De-shedding:Specialized undercoat removal for double-coated breeds.
Bathing commands the established base. The steepest expansion runs through de-shedding as breed-specific ownership rises.
Animal Type:
Species physiology dictates equipment specifications, handling protocols, and regulatory considerations.
- Dogs:Diverse coat types from hairless breeds to heavy undercoats require specialized toolkits and breed-specific knowledge. Volume concentrates in the United States, China, and Germany where companion dog ownership rates exceed regional medians. Size variation creates service tier differentiation from toy breeds to giant breeds.
- Cats:Feline-specific restraint techniques and low-stress handling protocols reduce grooming-induced cortisol elevation. Demand is accelerating among indoor-only cat households in German urban clusters where allergen management priorities elevate professional service acceptance.
- Rabbits:Fragile skin and stress-sensitive physiology require specialized handling certification.
- Guinea Pigs:Small mammal grooming remains a niche service with limited dedicated infrastructure.
Dogs command the established base. The steepest expansion runs through cats as feline wellness spending converges with canine patterns.
Service Model:
Delivery format determines customer acquisition economics, geographic coverage, and labor classification exposure.
- Mobile Grooming:Self-contained van units with onboard water, power, and ventilation enable doorstep service delivery. Route density in high-income urban clusters across the United States and China supports profitable unit economics. Algorithmic dispatch platforms are compressing customer acquisition costs.
- Spa Packages:Premium tier incorporating aromatherapy, mud therapy, and specialized skin treatments. Urban millennial pet owners in the United States and Germany trade up from basic services, creating the highest margin tier across the value chain.
- In-store Grooming:Fixed-location salon operations anchored by retail foot traffic.
- Self-service:Equipment rental models for cost-conscious owners.
In-store grooming commands the established base. The steepest expansion runs through spa packages as premiumization accelerates.
Customer Type:
End-user category shapes service specifications, pricing tolerance, and relationship duration.
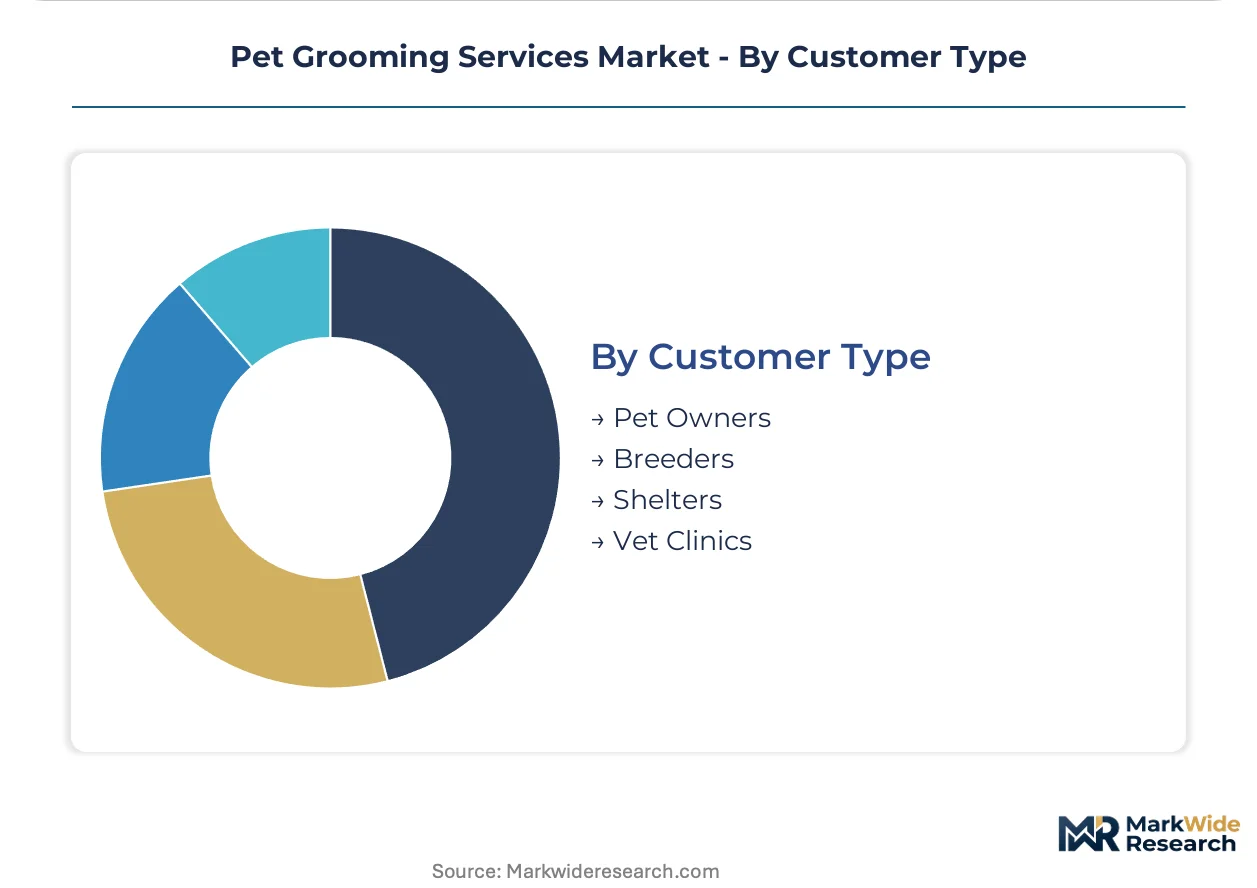
- Pet Owners:Individual household demand driven by humanization trends and time scarcity among dual-income families. Concentration in the United States, China, and Germany correlates with disposable income and pet insurance penetration. Subscription acceptance is highest in this segment.
- Vet Clinics:Referral partnerships and co-located service arrangements create B2B revenue streams. German and United States markets show strongest integration as preventive care bundling gains traction.
- Breeders:Pre-sale grooming for show and companion animal litters.
- Shelters:Non-profit and municipal contract grooming for intake hygiene.
Pet owners command the established base. The steepest expansion runs through vet clinics as wellness integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based service chains export operational blueprints and veterinary-integrated service models to German and Chinese markets through franchise licensing and platform technology licensing agreements.
United States
Millennial pet owners in dense urban clusters drive premium spa package adoption, with dual-income households prioritizing time-scarce convenience over cost sensitivity. OSHA ventilation guidelines and state cosmetology board licensing in California, Texas, and New York elevate compliance costs for independent operators. Greater Los Angeles and New York Metro anchor the highest mobile grooming route density, where algorithmic dispatch platforms compress customer acquisition economics.
Germany
Feline wellness spending convergence with canine patterns accelerates professional cat grooming demand among indoor-only households in Berlin and Munich. The EU REACH chemicals framework mandates ingredient disclosure for topical pet products, forcing formulation transparency investments by service chains. North Rhine-Westphalia concentrates veterinary clinic co-location partnerships, where preventive care bundling gains strongest traction.
China
Rapid companion dog ownership growth in tier-one cities generates sufficient route density for profitable mobile unit economics among high-income demographics. The national veterinary medicine regulator tightens safety substantiation requirements for medicated grooming products. Shanghai and Beijing urban clusters lead platform-based grooming adoption, where app-native dispatch models displace traditional phone booking infrastructure.
United Kingdom
Pet insurance penetration correlates with subscription-based grooming package acceptance among high-frequency users in London and Southeast England. The country's national veterinary regulator aligns topical pet product standards with EU REACH frameworks post-Brexit. Greater Manchester and Birmingham emerging clusters show accelerating mobile grooming penetration as platform operators expand beyond capital markets.
Japan
Small-living-space urbanization in Tokyo and Osaka elevates hygiene standards and professional service acceptance for companion animals. METI standards for service sector digitization encourage AI-powered scheduling adoption among grooming operators. Kanto region concentration supports premium spa tier expansion as aging pet owners trade up from basic bathing services.
Pet Grooming Services Market Key Industry Players
Channel-controlling players compete with product-specialist players across a fragmented service landscape where no single operator commands dominant national share. Fixed-location retail chains anchor suburban volume through veterinary-integrated packages, while mobile platform operators capture urban time-scarce demographics through algorithmic dispatch. Three archetypes define competitive positioning: retail-anchored chains with veterinary wellness integration, app-native mobile dispatch platforms, and independent boutique operators with breed-specialist certification. Consolidation pressure concentrates among suburban fixed-location operators absorbing OSHA-mandated ventilation capital costs, while platform operators pursue groomer supply lock-in ahead of potential labor reclassification disputes.
Among retail-anchored chains, PetSmart LLC and Petco Animal Supplies Inc. exemplify the veterinary-integrated archetype, with PetSmart leveraging nationwide store footprints and Petco differentiating through preventive health check bundling. Wag Labs Inc. occupies the platform-native position, representing app-based dispatch models that connect pet owners with independent groomers for on-demand service delivery. These three companies anchor the competitive structure without individually dominating segment share.
| Leading Market Players |
|---|
| Independent Pet Partners |
| Wag Labs Inc. |
| PetSmart LLC |
| Pet Palace Resort |
| PetPeople Enterprises LLC |
| Petco Animal Supplies Inc. |
| Dogtopia Enterprises |
| Zoomin Groomin |
| Pets At Home Inc. |
| Others |
Cost & Logistics Intelligence
Overcapacity in suburban United States fixed-location salons compresses utilization rates below breakeven thresholds for independent operators, forcing price concessions on basic bathing packages while mobile units in dense urban corridors capture premium positioning through scarcity.
Pricing Analysis
Cost-plus contracts with veterinary-grade shampoo suppliers index raw material costs to FDA-mandated safety substantiation requirements. Three-tier pricing structure across premium spa, standard grooming, and economy self-service levels separates subscription-based wellness bundles from transactional appointments. Pricing pressure stems from algorithmic dispatch platforms compressing customer acquisition costs in metropolitan United States and Chinese markets. Corporate account buyers at multi-site veterinary chains exhibit lowest price sensitivity, while cost-conscious suburban households drive economy tier volume.
Supply Chain Analysis
Extended payment terms from pH-balanced formulation manufacturers to mobile grooming fleet operators reflect working capital strain from van outfitting costs. Supply concentrates in United States, German, and Chinese manufacturing hubs for variable-speed rotary tools and specialized undercoat rakes. Raw material dependencies include pharmaceutical-grade surfactants, ergonomic lifting equipment, and HVAC ventilation systems. Single-source vulnerability runs through FDA-certified medicated shampoo suppliers facing extended approval timelines. Distribution runs through platform-native dispatch algorithms displacing traditional phone-based booking intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where algorithmic dispatch interoperability between grooming booking apps and veterinary practice management software reshapes customer acquisition economics.
For Market Incumbents: Build data-network moats through subscription auto-renewal systems that embed grooming schedules into pet insurance portals. Integrate preventive health check workflows ahead of EU REACH chemical disclosure mandates that elevate compliance costs for smaller competitors. Lock in certified groomer supply through employment classification structures that preempt labor reclassification disputes.
For New Entrants and Emerging Players: Pursue feline-specific grooming certification gaps in German urban clusters where indoor-only cat households drive underserved demand. Target mobile unit deployment in Greater Manchester and Birmingham corridors where platform penetration lags London saturation. Lead with low-stress handling protocols as a veterinary referral acquisition channel.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform operators with embedded subscription billing and veterinary clinic partnerships. Five-to-ten year viability favors mobile dispatch platforms with route density advantages in tier-one Chinese cities and United States coastal metros. Monitor groomer supply reclassification litigation as an inflection signal for unit economics compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Wellness Integration | Bundling grooming with preventive health checks creates stickier customer relationships through Petco-style service models. |
| AI-Powered Scheduling Deployment | Predictive demand algorithms optimize groomer utilization rates and enable same-day fulfillment in time-scarce households. |
| Mobile Fleet Expansion | Self-contained van units capture route density advantages in dense urban clusters across United States and Chinese markets. |
| Certified Clean-Label Formulation | EU REACH compliance investments differentiate service chains through ingredient transparency in German urban markets. |
| Groomer Supply Lock-In | Proactive employment classification structures capture qualified labor ahead of platform labor disputes. |
Research Approach
Desk research of veterinary medicine regulatory filings, OSHA salon safety guidelines, and EU REACH chemical disclosure databases preceded structured interviews with mobile grooming fleet operators, veterinary clinic practice managers, platform dispatch algorithm engineers, and state cosmetology board administrators. Primary fieldwork with PetSmart and Petco operations executives validated service tier economics, while customs data on grooming equipment imports and SEC filings from publicly traded pet retail chains anchored supply chain assumptions. Bottom-up mobile unit economics modeling triangulated against top-down market sizing from pet ownership demographic projections.
Assumptions held fixed include FDA enforcement intensity on medicated shampoo substantiation, EU REACH disclosure implementation timelines, and state-level cosmetology licensing fragmentation in California, Texas, and New York. Variable conditions encompass platform labor classification dispute outcomes and pet insurance penetration rates in German and United Kingdom markets. Segmentation dimensions modeled span service intensity tier, species-specific handling protocols, delivery format economics, and customer type relationship duration. CAGRs derived from historical grooming frequency elasticity against disposable income indices and urbanization density metrics.
Sensitivities concentrate around veterinary-grade input cost inflation, gig groomer reclassification rulings, and platform commission rate compression. Forecasts reflect documented assumptions on regulatory enforcement trajectories and technology adoption curves. Macroeconomic recession impacts on discretionary pet spending, abrupt regulatory shifts in topical product safety standards, or breakthroughs in at-home grooming automation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Small Dog Harness Market
Pet Care Products
Pet Clothing Market
Pet Care Products
China Cat Litter Market
Pet Care Products
Pet Selfie Tools Market
Pet Care Products
Bird Toy Market
Pet Care Products
Pet Treats Market
Pet Care Products
Frozen and Freeze-Dried Pet Food Market
Pet Care Products
Large Breed Dog Food Market
Pet Care Products
Europe Pet Treats Market
Pet Care Products
Canned Wet Cat Food Market
Pet Care Products
Pet Lodging Market
Pet Care Products
Pet Hotels Market
Pet Care Products
Pet Calming Products Market
Pet Care Products
Smart Pet Supply Market
Pet Care Products
Asia Pacific Dog Food Market
Pet Care Products
Cat Bed Market