
 Global Flea and Tick Product Market | 2026-2036
Global Flea and Tick Product Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flea and Tick Product Market Foresight
REACH is consolidating the cost-of-entry calculus for biocide-based flea and tick formulations entering the European market. Zoetis Inc. leverages its veterinary channel dominance across North America and Europe. Merck Animal Health anchors its position through sustained R&D intensity in oral parasiticide development. Boehringer Ingelheim differentiates via manufacturing scale and backward integration into active pharmaceutical ingredient supply.
Flea and tick products comprise topical, oral, and collar-based ectoparasiticides formulated with isoxazolines, pyrethroids, or insect growth regulators to disrupt arthropod nervous systems or reproductive cycles. These products prevent zoonotic pathogen transmission and maintain companion animal welfare standards. Oral tablets command premium positioning due to convenience and systemic efficacy, while topical treatments retain volume leadership in price-sensitive channels. Sprays and shampoos occupy niche grooming and shelter applications with thinner margin profiles.
The EPA regulates topical pesticide tolerances in the United States, while the EU Green Deal and REACH framework govern biocide authorization and environmental persistence thresholds across Europe. China's MEE enforces dual carbon goals that constrain solvent-intensive manufacturing processes for traditional spray formulations. Stakeholders must monitor regulatory divergence between jurisdictions to align product portfolios with divergent safety and sustainability standards.
Market Dynamics
REACH authorization timelines and EU Green Deal biocide restrictions are compressing formulation pipelines for legacy pyrethroid-based products while accelerating isoxazoline patent migrations toward generic manufacturing hubs.
Growth Catalysts
- Preventive veterinary protocols:Small-animal clinics in the United States and Germany now bundle monthly oral parasiticides with wellness exams, embedding ectoparasite control into routine care schedules.
- REACH consolidation effects:Stricter environmental persistence thresholds are filtering out marginal biocide suppliers, concentrating shelf access for compliant formulations across European retail channels.
- Zoonotic disease awareness:Tick-borne pathogen transmission risks to human households are elevating year-round prophylaxis adherence among suburban pet owners in Brazil and the United States.
Market Restraints
- Active pharmaceutical ingredient concentration:China and India supply over 80% of isoxazoline intermediates, creating single-source vulnerability for oral tablet manufacturers.
- Pyrethroid regulatory friction:EPA aquatic toxicity reviews and ECHA aquatic hazard classifications are narrowing label claims for topical spot-on formulations near watersheds.
- Biocide substitution pressure:Natural oil-based repellents and mechanical flea combs are capturing price-sensitive shelter and rescue channel volume.
Strategic Opportunities
- Underpenetrated companion animal markets:Brazil's emerging middle-class pet ownership is outpacing veterinary clinic density, creating direct-to-consumer subscription openings for oral parasiticide brands.
- Regulatory tailwind from IRA veterinary provisions:United States pet insurance reimbursement expansion is reducing out-of-pocket cost barriers for premium systemic treatments.
- Telehealth channel convergence:Remote veterinary prescribing platforms are automating prescription renewal workflows, embedding product loyalty into digital care continuity.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in transdermal penetration enhancement for topical applications is concentrating among legacy animal health R&D centers.
- Biocide authorization timelines:ECHA's 18-36 month active substance evaluation windows are delaying product line extensions and geographic expansion plans.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flea and Tick Product Market |
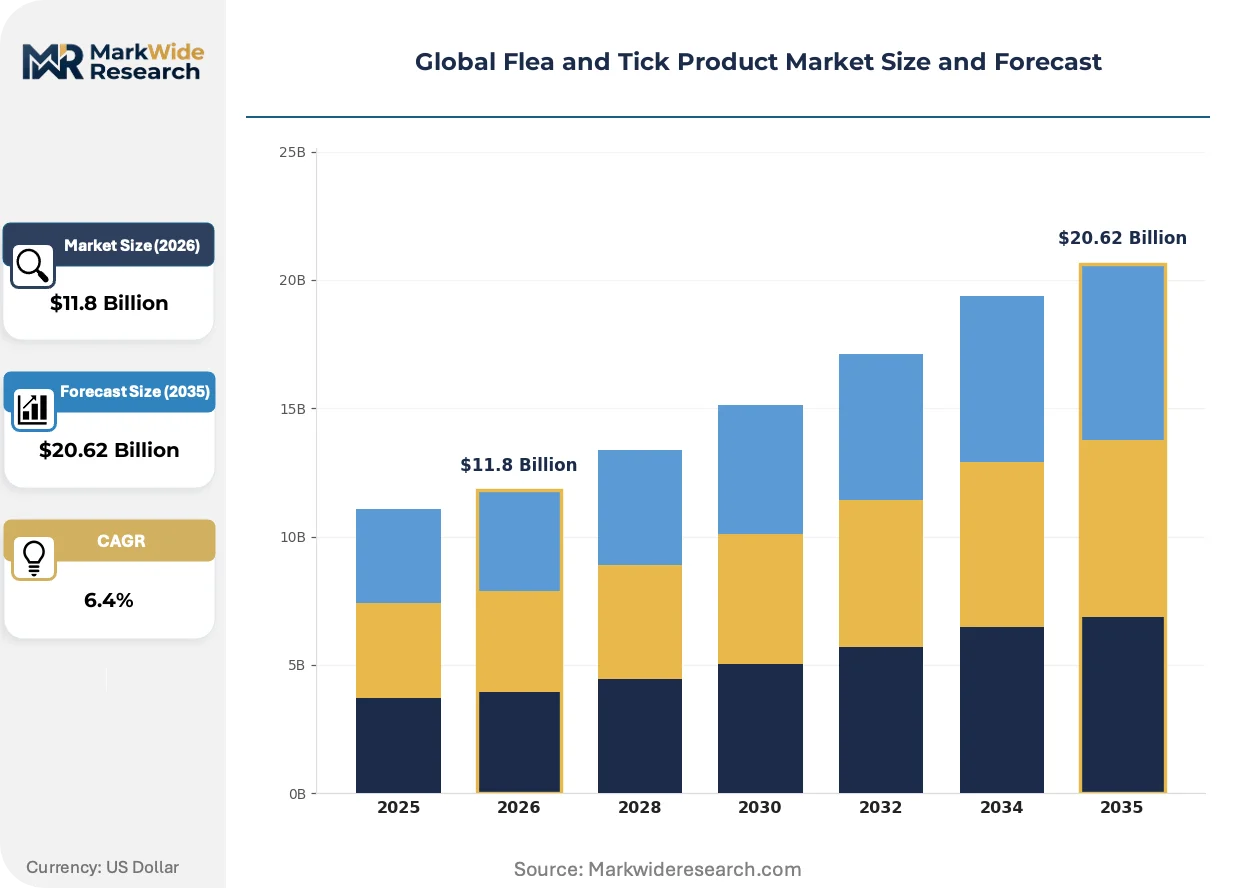
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Treatments, Oral Tablets, Collars, Sprays, Shampoos Application: Pet Dogs, Pet Cats, Livestock, Companion Animals, Exotic Pets End User: Veterinary Clinics, Animal Shelters, Pet Owners, Grooming Centers, Breeders Distribution Channel: Veterinary Hospitals, Online Retailers, Pet Specialty Stores, Pharmacies, Supermarkets |
| Companies Covered | Zoetis Inc., Merck Animal Health, Elanco Animal Health, Boehringer Ingelheim, Bayer AG, Ceva Sante Animale, Virbac Corporation, Central Garden & Pet Company, Sergeant’s Pet Care Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flea and Tick Product Market Shifts & Advancements
Isoxazoline chemistry maturation is intersecting with regulatory pressure on legacy actives, reshaping competitive differentiation around convenience delivery systems and environmental fate profiles.
Transdermal polymer matrix technology is automating sustained-release kinetics for topical spot-on formulations, enabling 12-week protection intervals. Specialty veterinary distributors in Germany and the United States are prioritizing these extended-duration SKUs. The technology is compressing purchase frequency and shifting margin capture toward upfront premium pricing.
EU Green Deal biocide sustainability criteria are mandating biodegradability thresholds for environmental risk assessments. Formulators are reformulating solvent systems and excipient packages to meet ECHA persistence cutoffs. Oral tablet categories face lighter environmental scrutiny, tilting R&D investment away from spray and shampoo formats.
Subscription-based auto-ship models are displacing episodic retail purchasing for chronic parasiticide needs. Direct-to-consumer platforms and veterinary practice management software integrations are capturing renewal volume. Brazil and United States urban markets show the highest subscription attach rates for oral isoxazoline products.
Global Flea and Tick Product Market Segmentation
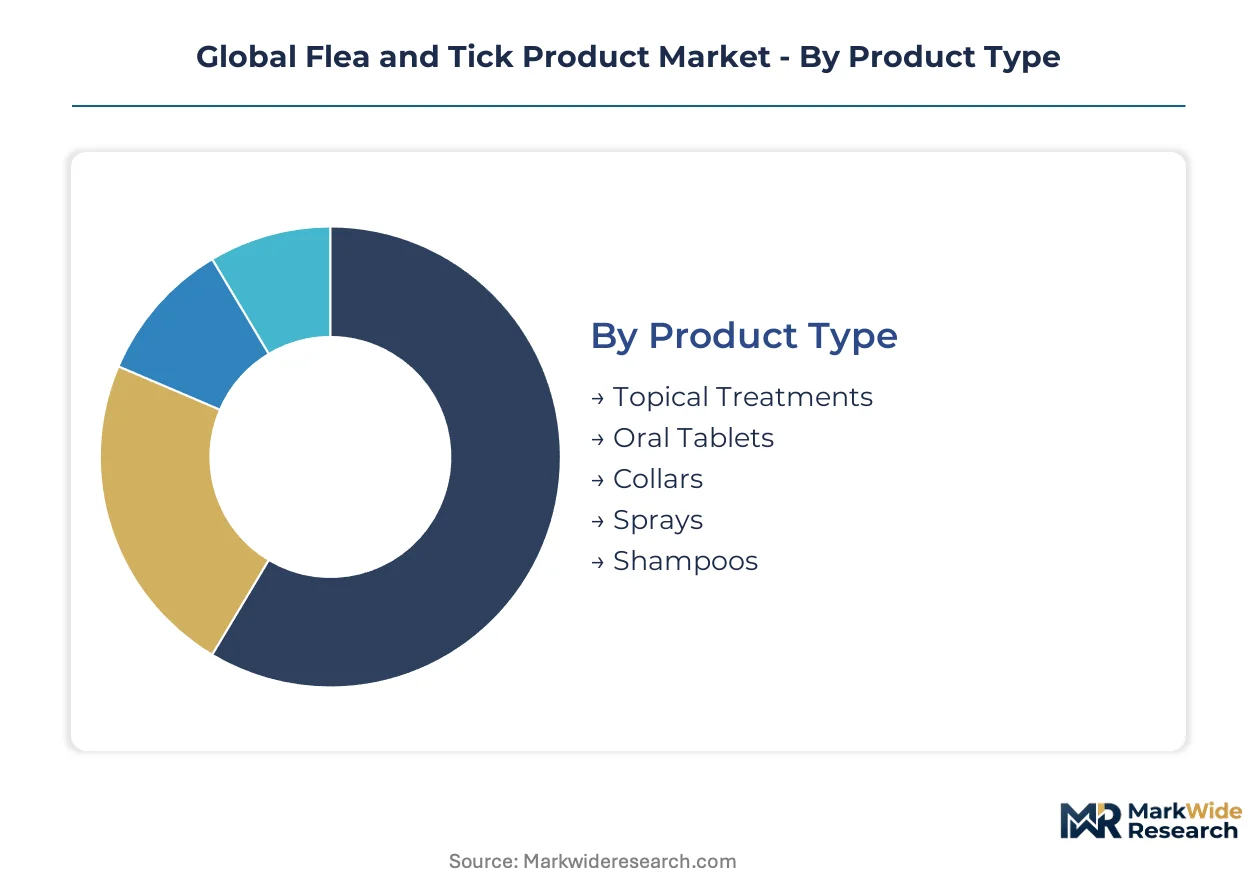
Flea and tick product segmentation reveals divergent capital requirements across formulation technologies. Each dimension shapes competitive positioning through distinct margin structures, regulatory exposure, and channel access patterns.
Product Type:
Oral tablet manufacturing demands the heaviest upfront investment in active pharmaceutical ingredient synthesis and bioavailability testing infrastructure.
- Topical Treatments:Transdermal spot-on formulations combine isoxazolines or pyrethroids with polymer penetration enhancers. Demand concentrates in Germany and the United States where pet owners prioritize monthly application convenience; EPA aquatic toxicity reviews are narrowing watershed-adjacent label claims.
- Oral Tablets:Systemic parasiticides using fluralaner, afoxolaner, or sarolaner require GMP-compliant synthesis suites and extended stability validation. Veterinary clinics in Brazil and the United States bundle these with wellness exams; supply chains concentrate on Chinese and Indian intermediate manufacturers.
- Collars:Polymer matrix diffusion technology delivers sustained-release protection through impregnated plastic or fabric collars.
- Sprays:Aqueous or solvent-based formulations target immediate knockdown in shelter and grooming environments.
- Shampoos:Surfactant-based rinse products occupy low-margin grooming channel volume with limited residual efficacy.
Topical treatments absorb the bulk of installed capacity; oral tablets are expanding most quickly.
Application:
Species-specific metabolism drives divergent active ingredient tolerances and dosing regimens across the application spectrum.
- Pet Dogs:Canine formulations dominate oral tablet development pipelines due to higher body mass enabling profitable dose scaling. United States suburban households drive year-round prophylaxis adherence; Lyme disease awareness elevates tick-borne pathogen concern.
- Pet Cats:Feline metabolism constraints limit pyrethroid use and favor isoxazoline oral or topical alternatives. European markets show stronger feline-specific product penetration; REACH biocide restrictions disproportionately affect collar and spray categories.
- Livestock:Cattle and sheep applications emphasize pour-on formulations and ear tags for herd-level parasite management.
- Companion Animals:Rabbits, ferrets, and small mammals require species-tailored dosing with limited commercial formulation availability.
- Exotic Pets:Reptile and avian applications represent niche veterinary compounding demand with minimal standardized product development.
Pet dogs capture the majority of R&D investment; pet cats show the steepest expansion trajectory in European compliance-driven markets.
End User:
Prescription authority and procurement scale separate institutional buyers from dispersed consumer channels.
- Veterinary Clinics:Licensed practitioners control oral parasiticide dispensing and bundle preventive care into subscription wellness plans. United States and German clinics embed product loyalty through practice management software integrations.
- Animal Shelters:High-volume, price-sensitive procurement favors generic topical treatments and bulk spray formulations.
- Pet Owners:Direct-to-consumer purchasing concentrates in online retail and pet specialty channels for collar and topical categories.
- Grooming Centers:Service-based application of shampoos and sprays generates thin-margin recurring revenue.
- Breeders:Litter-scale prophylaxis drives volume purchasing of puppy-safe formulations with specific weight-band dosing.
Veterinary clinics anchor premium pricing power; pet owners represent the most fragmented and price-elastic demand pool.
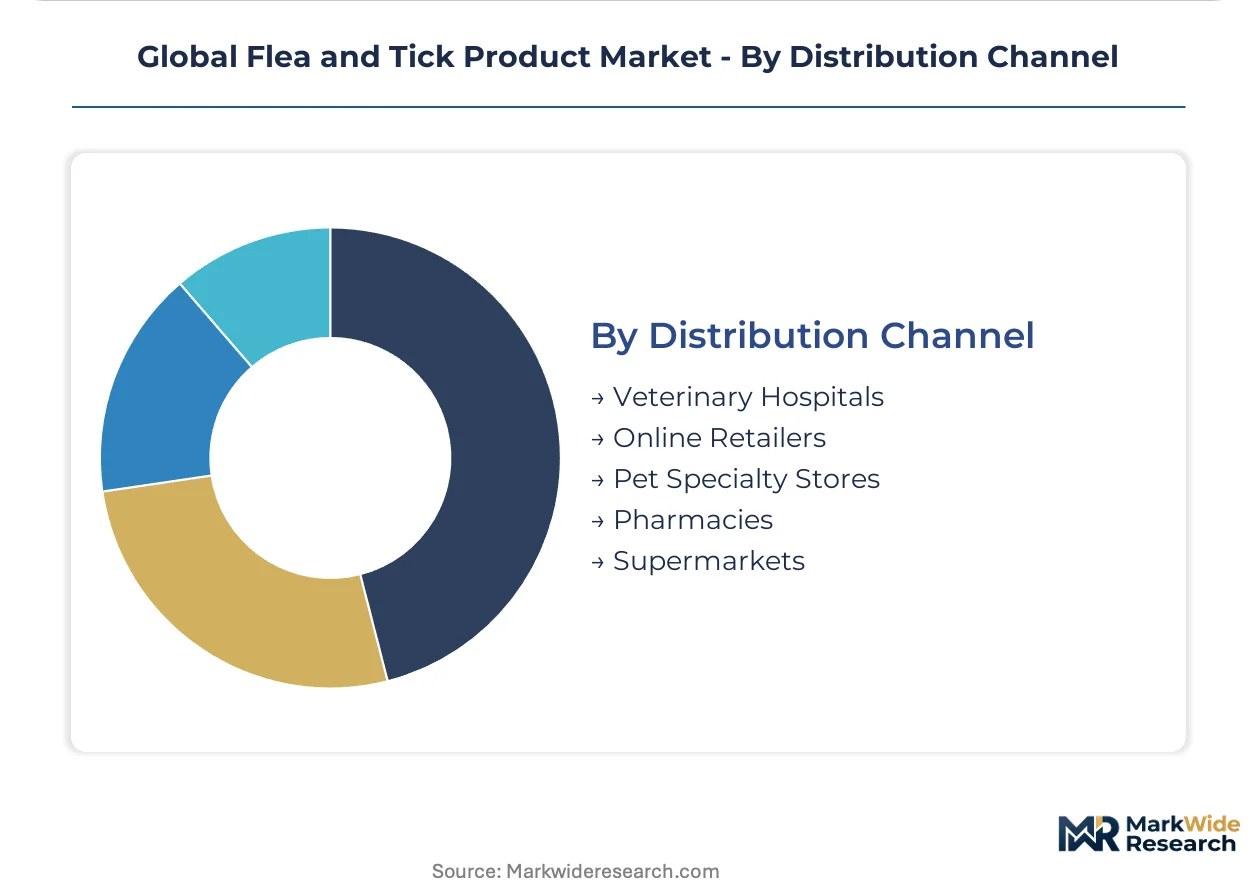
Distribution Channel:
Channel selection determines regulatory compliance burden and margin capture through prescription control or mass-market scale.
- Veterinary Hospitals:Institutional procurement consolidates oral tablet volume through direct manufacturer contracts. Brazil's emerging clinic density lags behind pet ownership growth, creating telehealth-enabled remote prescribing opportunities.
- Online Retailers:Subscription auto-ship models displace episodic purchasing for chronic parasiticide needs. United States urban markets show highest attach rates for isoxazoline oral products.
- Pet Specialty Stores:Staff-assisted selection supports collar and topical category sales with lower regulatory barriers than prescription channels.
- Pharmacies:Human health retail networks carry limited SKU ranges focused on crossover pet owner convenience purchasing.
- Supermarkets:Mass-market placement captures price-sensitive shampoo and collar volume with minimal staff intervention.
Veterinary hospitals retain margin leadership; online retailers are gaining share fastest through subscription automation and telehealth convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for pharmaceutical manufacturing in India and Brazil are concentrating active ingredient synthesis capacity for veterinary parasiticides. These zones attract investment through tax holidays and streamlined environmental permitting that accelerates product registration timelines.
United States
Suburban pet ownership density in Texas and Florida drives year-round preventive medication adherence among dog owners. EPA aquatic toxicity reviews are narrowing label claims for pyrethroid spot-ons near watersheds in the Pacific Northwest. Kansas City anchors veterinary distributor consolidation for oral parasiticide distribution to Midwestern clinics.
Germany
Feline-specific product penetration exceeds North American benchmarks due to higher multi-cat household prevalence. ECHA biocide authorization timelines extend 18-36 months for legacy pyrethroid formulations seeking renewal. Leipzig hosts formulation R&D clusters specializing in transdermal polymer matrices for extended-release topical applications.
Brazil
Emerging middle-class pet ownership in São Paulo and Rio de Janeiro outpaces veterinary clinic density growth. ANVISA streamlined registration pathways for isoxazoline generics are accelerating market entry. Campinas concentrates contract manufacturing for oral tablet packaging serving Latin American export markets.
China
Domestic pet ownership expansion in Shanghai and Beijing creates demand for imported premium oral parasiticides. MEE dual carbon goals constrain solvent-intensive spray formulation manufacturing in Jiangsu province. Zhejiang province hosts intermediate synthesis clusters supplying fluralaner and afoxolaner precursors to global tablet manufacturers.
India
Pharmaceutical export zones in Hyderabad and Ahmedabad attract contract manufacturing for generic isoxazoline intermediates. CDSCO veterinary product registration reforms are shortening import approval timelines for multinational brands. Pune clusters formulation development capabilities for tropical climate stability testing.
Global Flea and Tick Product Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation technology tiers. Market structure concentrates around three to five integrated players controlling oral tablet active ingredient supply and veterinary channel access. Strategic archetypes include backward-integrated pharmaceutical conglomerates, veterinary channel specialists, and generic intermediate suppliers. Competitive moves center on manufacturing scale expansion and regulatory compliance certification for EU Green Deal biocide sustainability thresholds.
Among diversified pharmaceutical conglomerates, Zoetis Inc. and Merck Animal Health occupy positions exemplifying veterinary channel dominance and sustained R&D intensity in systemic parasiticide development. Boehringer Ingelheim represents the manufacturing scale archetype through captive supply integration into active pharmaceutical ingredient production. These three anchors illustrate divergent pathways to margin capture: prescription control, innovation premium, and cost leadership through upstream integration.
| Leading Market Players |
|---|
| Zoetis Inc. |
| Merck Animal Health |
| Elanco Animal Health |
| Boehringer Ingelheim |
| Bayer AG |
| Ceva Sante Animale |
| Virbac Corporation |
| Central Garden & Pet Company |
| Sergeant's Pet Care Products |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between REACH-compliant biocide formulations and legacy pyrethroid alternatives manifests in both pricing premiums and supply chain reconfiguration toward audited manufacturing hubs. Oral tablet manufacturers capture upfront margin through GMP-certified synthesis infrastructure, while topical spot-on producers absorb reformulation costs to meet ECHA persistence thresholds.
Pricing Analysis
Short lead-time premiums for oral parasiticide inventory compress margins for veterinary distributors facing ANVISA registration delays in Brazil. Three-tier pricing structure across premium systemic tablets, standard topical spot-ons, and economy-grade collars reflects formulation complexity and regulatory compliance burden. Pricing pressure stems from isoxazoline patent cliff migration toward generic intermediate suppliers. Animal shelters and rescue channels exhibit highest price sensitivity; veterinary clinics with bundled wellness plans show lowest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Chinese and Indian intermediate manufacturers supplying over 80% of fluralaner and afoxolaner precursors. Formulation chemist expertise concentrates in legacy R&D clusters across Germany and the United States. Raw material dependencies include isoxazoline active pharmaceutical ingredients, polymer penetration enhancers, and biocide-grade solvents. Tariff exposure on intermediate imports threatens margin stability for oral tablet packagers. Distribution runs through veterinary hospital procurement contracts, specialty distributor networks, and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active pharmaceutical ingredient synthesis capacity constraints prop pricing power for backward-integrated incumbents, while ECHA authorization bottlenecks extend product line extension timelines.
For Market Incumbents: Anchor manufacturing scale through captive supply integration into isoxazoline intermediate production. Defend channel position by embedding prescription renewal workflows into veterinary practice management software. Counter natural oil-based repellent substitution pressure through extended-duration transdermal polymer matrix development. For New Entrants and Emerging Players: Telehealth-enabled remote prescribing platforms offer the most penetrable entry vector for oral parasiticide brands in Brazil's clinic-underserved urban markets. Target direct-to-consumer subscription auto-ship models to bypass veterinary channel gatekeeping. Pursue ANVISA streamlined registration pathways for generic isoxazoline formulations as fastest geographic expansion route. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified pharmaceutical conglomerates seeking veterinary channel density. Long-term viability hinges on regulatory compliance certification depth rather than formulation novelty alone. Watch ECHA active substance evaluation timeline compression as inflection signal for portfolio consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Synthesis | Captive supply of fluralaner intermediates insulates margin from Chinese export volatility. |
| REACH Compliance Certification | ECHA biocide authorization unlocks shelf access across European retail pharmacy channels. |
| Telehealth Platform Partnership | Remote prescribing automation embeds product loyalty into digital veterinary care continuity. |
| Extended-Release Formulation Development | Transdermal polymer matrices enable 12-week protection intervals commanding premium pricing. |
| Subscription Auto-Ship Infrastructure | Direct-to-consumer renewal capture displaces episodic retail purchasing in United States urban markets. |
Research Methodology
Independent corroboration across regulatory filing databases, customs trade records, and veterinary distributor procurement data underwrites the qualitative findings. Primary interviews with formulation R&D directors, regulatory affairs specialists at animal health conglomerates, veterinary clinic procurement managers, and specialty distributor category buyers combined with secondary validation from EPA tolerance databases, ECHA biocide authorization registers, and ANVISA registration disclosures. Bottom-up segmentation modeling triangulated against top-down market sizing from pharmaceutical export statistics.
Rate-of-change decomposition across product type, application species, end-user institution, and distribution channel dimensions structures the analytical framework. CAGRs derive from segment-level volume trajectories weighted by price realization trends. Forecast inputs incorporate REACH authorization timeline probability distributions and isoxazoline patent expiration schedules across the projection horizon.
Caveats apply where ECHA active substance evaluation delays or MEE dual carbon enforcement intensity could materially shift the outlook. Forecasts reflect assumptions around veterinary clinic density growth in Brazil and telehealth regulatory permissiveness in the United States. Deviation in Chinese intermediate export policy would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Corrector Spray Market
Pet Care Products
Europe Pet Treats Market
Pet Care Products
South America Pet Food Market
Pet Care Products
Gcc Pet Food Market
Pet Care Products
Pet Snacks and Treats Market
Pet Care Products
GCC Cat Food Market
Pet Care Products
Pet Toys Market
Pet Care Products
Smart Pet Leash Market
Pet Care Products
Hypoallergenic Dog Food Market
Pet Care Products
Vegan Dog Food Market
Pet Care Products
India Pet Food Market
Pet Care Products
Dog Clothes Market
Pet Care Products
Asia Pacific Pet Diet Market
Pet Care Products
Pet Care E-Commerce Market
Pet Care Products
Pet Hotels Market
Pet Care Products
Pet Treats and Chews Market