
 Global Cat Trees and Towers Market | 2026-2036
Global Cat Trees and Towers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cat Trees and Towers Market Analysis
The pet specialty retail channel is fragmenting as direct-to-consumer platforms and veterinary clinic partnerships erode traditional big-box dominance. Ware Pet Products leverages its long-standing distributor relationships to sustain shelf presence across North American chains. Armarkat competes through aggressive online pricing, while Vesper differentiates via design-forward positioning in European pet boutiques. AeroMark controls significant private-label manufacturing capacity, supplying multiple retail banners without consumer-facing branding.
Cat trees and towers are engineered vertical structures combining platforms, enclosures, and scratching surfaces to satisfy feline climbing, perching, and claw-sharpening instincts. Manufacturers typically construct frames from engineered wood or cardboard cores wrapped in sisal rope and carpet-grade fabric, with stability requirements dictating base dimensions proportional to total height. Wood-based products command premium positioning due to durability and aesthetic integration with residential interiors, while foldable designs represent the fastest-growing feature segment as urban consumers prioritize storage flexibility. The end-user base tilts heavily toward individual pet owners, though veterinarian clinics represent a concentrated procurement channel for behavioral enrichment programs.
The US Consumer Product Safety Commission monitors structural stability and small-part ingestion risks, while the EU REACH framework restricts certain chemical treatments in fabric coverings and adhesives. California's Proposition 65 labeling requirements create compliance complexity for imported products, pushing manufacturers toward certified material sourcing. Stakeholders must monitor evolving state-level flammability standards and the EU's expanding EPR packaging obligations, which will reshape cost structures for cross-border suppliers.
Market Dynamics
ISO pet product safety standards are tightening material certification requirements across North America and Europe, forcing manufacturers to rebuild supply chains around certified sisal rope and low-VOC adhesives while pet specialty retailers expand premium floor space.
Growth Catalysts
- REACH chemical restrictions:EU fabric treatment regulations are eliminating competitors using non-compliant dyes, opening shelf space for certified suppliers in German and French retail channels.
- Multi-cat household density:Urban clustering of companion animals in US apartments drives replacement demand for space-efficient vertical structures with modular platform configurations.
- Engineered wood substitution:Manufacturers adopting FSC-certified plywood cores command price premiums in Japanese and South Korean markets where interior aesthetics influence purchasing.
Market Restraints
- Sisal fiber price volatility:Brazilian and Tanzanian harvest fluctuations compress margins for rope-dependent producers unable to hedge agricultural commodity exposure.
- Guangdong manufacturing concentration:Private-label capacity clustering in Pearl River Delta creates single-point vulnerability for North American inventory replenishment cycles.
- Cardboard structural limits:Core material fatigue thresholds prevent tower heights exceeding 180 centimeters, capping premium positioning for foldable designs.
Strategic Opportunities
- Veterinary behavioral enrichment:Clinic procurement channels for anxiety-reduction programs remain underdeveloped in Australia and Canada relative to US penetration rates.
- Extended Producer Responsibility packaging:EU EPR obligations will advantage suppliers with recyclable corrugated designs over foam-dependent competitors in 2025 compliance windows.
- Walnut shell litter convergence:Scratching surface material innovation combining biodegradable substrates with odor control creates cross-category bundling potential with sustainable litter brands.
Industry Challenges
- Feline ergonomics expertise scarcity:Product development teams lack veterinary behavioral specialists capable of validating platform spacing and enclosure dimensions for stress reduction claims.
- California Proposition 65 labeling timelines:Six-month chemical disclosure compliance windows delay product launches for imported goods with adhesive-dependent assembly.
- Legacy carpet-grade inventory:Warehouse stockpiles of synthetic fiber coverings face stranded asset risk as natural material preferences accelerate among premium buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cat Trees and Towers Market |
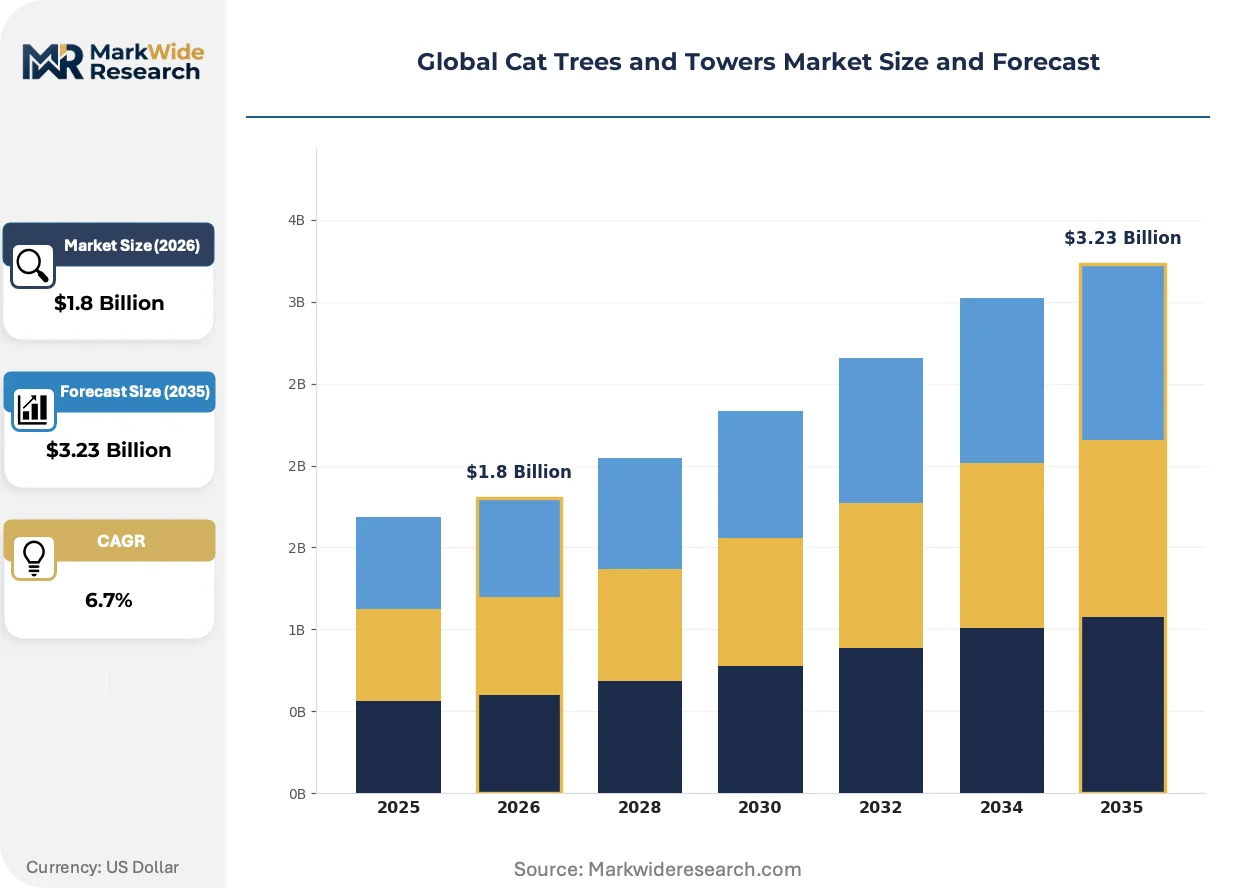
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wood, Cardboard, Fabric, Plastic End User: Pet Owners, Retailers, Veterinarians, Shelters Feature: Multi-Level, Interactive, Scratch-resistant, Foldable Size: Small, Medium, Large, Extra Large |
| Companies Covered | Ware Pet Products, PetPals, New Cat Condos, Frisco, Vesper, AeroMark, Armarkat, Kitty Mansions, Molly and Friends, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cat Trees and Towers Market Emerging Trajectories
Modular assembly systems and sustainable material substitutions are compressing traditional manufacturing lead times while reshaping how urban consumers evaluate storage flexibility against durability trade-offs.
Foldable steel-frame core technology is virtualizing the traditional solid-wood tower category by enabling flat-pack shipping densities that reduce freight costs by half. Japanese and South Korean direct-to-consumer platforms are adopting these structures fastest, compressing inventory holding requirements for last-mile fulfillment networks. The technology is virtualizing regional manufacturing advantage by decoupling final assembly from production geography.
EU REACH Annex XVII restrictions on formaldehyde-releasing adhesives in fabric-laminated components took full effect in 2023, eliminating solvent-based bonding for products entering German and French distribution. Manufacturers are responding by migrating to water-based PUR adhesives certified under updated ISO 16000 indoor air standards. Wood-based premium lines face the steepest reformulation costs, accelerating consolidation among suppliers with in-house adhesive blending capabilities.
Subscription-based replacement cycles for scratching surfaces are displacing single-transaction tower purchases in US urban markets. Chewy and Amazon's recurring delivery programs now capture platform and sisal post sales that previously flowed through pet specialty retail. This pattern concentrates most visibly in Manhattan and San Francisco zip codes where storage constraints limit spare component stockpiling.
Global Cat Trees and Towers Market Segmentation
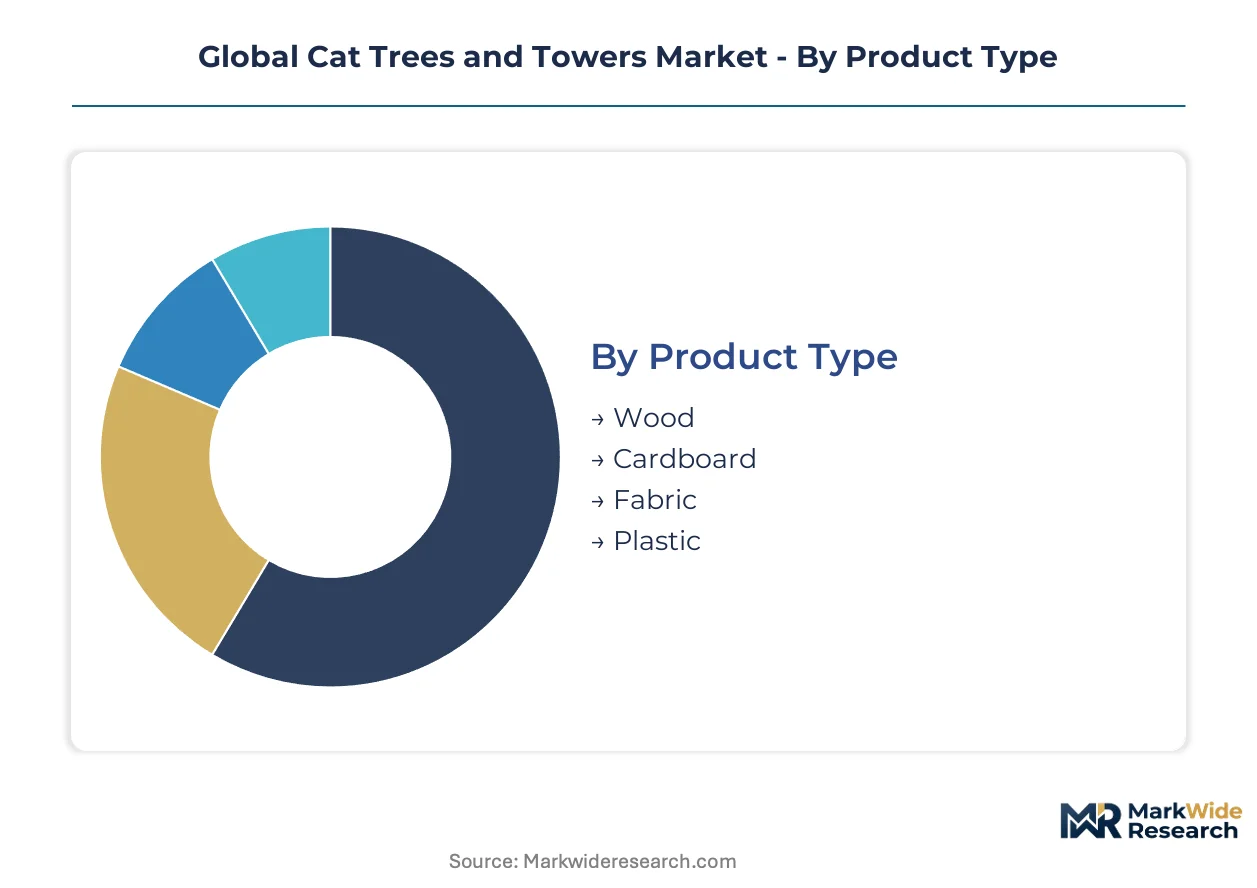
Cat trees and towers segment across material hierarchies, user procurement channels, functional configurations, and dimensional classes that reshape inventory strategies and margin architecture. Manufacturers optimize production lines around these divisions while retailers calibrate shelf space and pricing tiers to match substitution patterns between durability and convenience.
Product Type:
Mature wood-based construction dominates premium positioning as engineered alternatives carve volume share through cost efficiency and shipping logistics.
- Wood:Solid and engineered timber cores wrapped in sisal rope and natural fiber coverings command price premiums in Japanese and South Korean residential markets where interior aesthetics drive purchasing. FSC-certified plywood substitution is climbing fastest as EU REACH adhesive restrictions eliminate solvent-based bonding for imports into German and French distribution.
- Cardboard:Corrugated honeycomb structures with laminated surfaces reduce freight costs through flat-pack density and satisfy urban storage constraints in Manhattan and San Francisco apartment markets. Core material fatigue thresholds cap tower heights at 180 centimeters, limiting premium positioning for foldable designs despite expanding volume share.
- Fabric:Synthetic and natural textile coverings over metal or composite frames offer mid-tier pricing with modular replacement economics.
- Plastic:Injection-molded platforms and bases provide weather resistance for outdoor deployment and veterinary clinic sanitization protocols.
Wood retains volume leadership; cardboard holds the steepest expansion curve.
End User:
Procurement patterns diverge sharply between dispersed individual purchasing and concentrated institutional tendering with distinct specification requirements.
- Pet Owners:Individual households in US multi-cat apartments drive replacement demand for space-efficient vertical structures, with subscription-based scratching surface replenishment displacing single-transaction tower purchases through Chewy and Amazon recurring delivery programs.
- Retailers:Pet specialty chains and direct-to-consumer platforms source private-label inventory from Guangdong manufacturing clusters, creating single-point vulnerability for North American replenishment cycles.
- Veterinarians:Clinic procurement for behavioral enrichment programs concentrates in US metropolitan markets while remaining underdeveloped in Australian and Canadian channels.
- Shelters:Nonprofit and municipal adoption facilities prioritize durability-to-cost ratios and bulk sanitization compatibility.
Pet owners generate absolute volume; veterinarians present the most concentrated margin expansion opportunity.
Feature:
Functional differentiation increasingly determines price tier placement as urban consumers trade structural permanence for spatial flexibility.
- Multi-Level:Stacked platform configurations with integrated enclosures satisfy feline climbing instincts in compact footprints, dominating Japanese and South Korean direct-to-consumer adoption where living space constraints are acute.
- Interactive:Motorized elements, treat dispensers, and sensor-activated components attach to base structures as upgrade modules.
- Scratch-resistant:Reinforced sisal and alternative fiber surfaces extend component lifecycles and support subscription replacement economics.
- Foldable:Steel-frame core technology with collapsible joints enables flat-pack shipping densities that reduce freight costs by half, compressing inventory holding requirements for last-mile fulfillment networks.
Multi-level configurations anchor current revenue; foldable designs are climbing the fastest as steel-frame virtualization decouples final assembly from production geography.
Size:
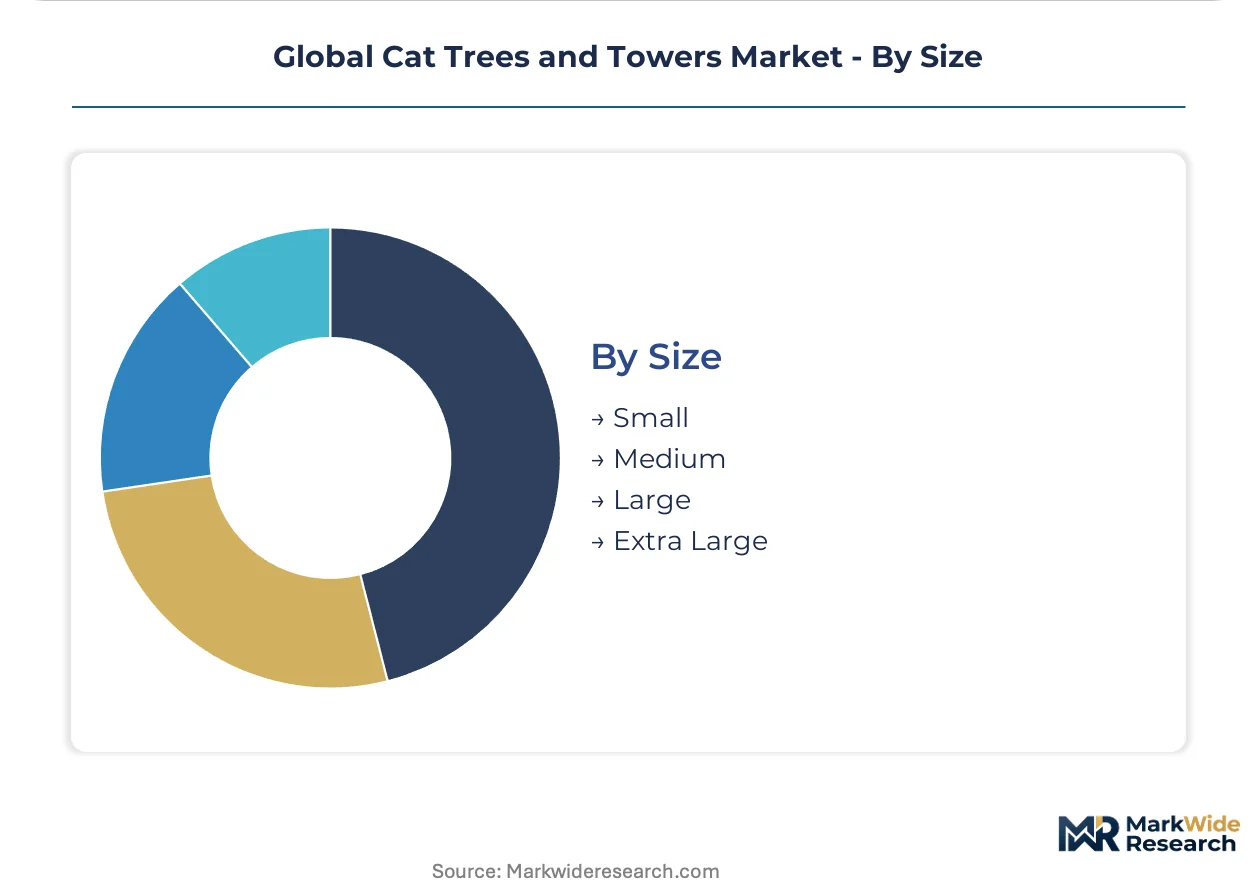
Dimensional segmentation maps directly to household pet density and residential square footage constraints across urban market tiers.
- Small:Under-90-centimeter structures target single-cat households and studio apartment deployments with platform counts of two to three.
- Medium:Mid-range towers balance vertical expansion against base footprint requirements for standard one-bedroom layouts.
- Large:Four-to-six platform configurations with multiple enclosures serve multi-cat households in suburban settings with dedicated pet spaces.
- Extra Large:Ceiling-height installations and modular wall-anchored systems dominate veterinary clinic behavioral enrichment programs and premium residential installations.
Medium sizes command the broadest addressable market; extra large installations gain share fastest through veterinary channel development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price premiums in Japanese residential markets exceed equivalent US products by margins reflecting interior aesthetics valuation, while Brazilian raw material volatility compresses exporter margins regardless of destination geography.
United States
Multi-cat household density in Manhattan and San Francisco zip codes drives subscription-based replacement cycles for scratching surfaces through Chewy and Amazon recurring delivery programs. The US Consumer Product Safety Commission monitors structural stability and small-part ingestion risks with active enforcement timelines. California's Proposition 65 labeling requirements create six-month compliance windows that delay product launches for adhesive-dependent assembly.
Japan
Interior aesthetics influence purchasing decisions in residential markets where FSC-certified plywood substitution commands measurable price premiums. METI standards for indoor air quality align with ISO 16000 frameworks governing adhesive emissions in fabric-laminated components. Tokyo and Osaka direct-to-consumer platforms adopt foldable steel-frame core technology fastest, compressing inventory holding requirements for last-mile fulfillment networks.
Germany
EU REACH Annex XVII restrictions on formaldehyde-releasing adhesives took full effect in 2023, eliminating solvent-based bonding for fabric-laminated components entering German distribution. ECHA enforcement concentrates compliance verification at Hamburg and Rotterdam port-of-entry inspections. Stuttgart and Munich pet boutiques anchor Vesper's design-forward positioning in European premium retail channels.
China
Guangdong Province manufacturing clusters in the Pearl River Delta supply private-label capacity for multiple North American retail banners, creating single-point vulnerability for inventory replenishment cycles. SAMR oversight of product safety standards intensifies for export-bound production lines. Shenzhen and Dongguan fabricators dominate cardboard honeycomb structure output for flat-pack shipping density optimization.
Brazil
Sisal fiber harvest fluctuations in northeastern growing regions generate agricultural commodity price volatility that compresses margins for rope-dependent producers. ANVISA maintains secondary oversight for imported pet product safety certifications. São Paulo distributors hedge exposure through forward contracting with Tanzanian alternative suppliers.
Global Cat Trees and Towers Market Vendor Landscape
Specialist manufacturers and diversified pet product conglomerates split the market along design-authentication versus scale-efficiency vectors. Consolidation pressure concentrates among mid-tier suppliers facing simultaneous REACH adhesive reformulation costs and sisal fiber price volatility. Three strategic archetypes dominate: design-forward European boutiques, North American distributor-anchored incumbents, and Guangdong-based private-label fabricators. Competitive moves center on M&A for in-house adhesive blending capabilities and veterinary clinic partnership development for behavioral enrichment procurement channels.
Among North American incumbents, Ware Pet Products exemplifies distributor-anchored market presence through sustained shelf relationships across specialty retail chains. Armarkat occupies a position within aggressive online pricing archetypes competing for volume share in direct-to-consumer channels. AeroMark represents private-label manufacturing scale, supplying multiple retail banners without consumer-facing brand investment. Vesper anchors design-forward positioning in European pet boutiques where aesthetic integration drives premium tier placement.
| Leading Market Players |
|---|
| Ware Pet Products |
| PetPals |
| New Cat Condos |
| Frisco |
| Vesper |
| AeroMark |
| Armarkat |
| Kitty Mansions |
| Molly and Friends |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Guangdong Province manufacturing clusters is compressing supplier margins while simultaneously enabling aggressive pricing postures for private-label buyers negotiating North American retail contracts.
Pricing Analysis
Configured-to-order pricing for FSC-certified wood-based towers commands spreads of 40-60% above standard cardboard-core SKUs in Japanese and South Korean residential channels. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and interior aesthetic integration, with EU REACH adhesive compliance acting as a gatekeeper to premium placement. Cost compression in mid-tier fabric-over-frame products is intensifying because Brazilian sisal fiber volatility transmits directly to rope-dependent producers. Individual pet owners in US urban zip codes show highest price sensitivity, while veterinary clinic procurement demonstrates lowest sensitivity due to behavioral enrichment program budgets.
Supply Chain Analysis
EU REACH Annex XVII restrictions on formaldehyde-releasing adhesives function as de facto export controls limiting flows of non-compliant fabric-laminated components into German and French distribution. Manufacturing capacity concentrates in China, Brazil, and Tanzania, with raw material dependencies resting on sisal fiber harvests, FSC-certified plywood, and water-based PUR adhesive formulations. Single-source vulnerability clusters in Pearl River Delta fabricators create inventory replenishment risk for North American retail banners. Distribution runs through pet specialty chains, direct-to-consumer platforms, and veterinary clinic procurement channels with diverging specification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary behavioral enrichment procurement channels remain underdeveloped relative to US penetration rates, signaling early-cycle expansion potential as clinics in Australia and Canada adopt anxiety-reduction programs.
For Market Incumbents: Entrench shelf presence through backward integration into in-house adhesive blending capabilities that satisfy EU REACH compliance without third-party dependency. Defend margin position by securing multi-year FSC-certified plywood offtake agreements before engineered wood substitution accelerates pricing premiums in East Asian markets. For New Entrants and Emerging Players: Australian and Canadian veterinary clinic procurement channels represent the most penetrable entry point for behavioral enrichment program suppliers lacking established distributor relationships. Subscription-based scratching surface replenishment in Manhattan and San Francisco zip codes offers a second white-space target with recurring-revenue economics. A direct-to-consumer platform partnership with Chewy or Amazon bypasses traditional retail gatekeeping. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among suppliers with subscription-based component replacement programs and veterinary clinic partnership networks. Over a five-to-ten year viability window, acquisition targets should demonstrate in-house adhesive formulation capabilities and certified material sourcing relationships. Watch for inflection when California Proposition 65 enforcement timelines compress to three-month disclosure windows.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Partnership Development | Behavioral enrichment procurement in Australian and Canadian clinics unlocks concentrated margin expansion. |
| Adhesive Formulation Capability Acquisition | In-house water-based PUR blending eliminates EU REACH compliance delays for wood-based premium lines. |
| Subscription Platform Integration | Chewy and Amazon recurring delivery programs capture replacement surface economics in storage-constrained urban markets. |
| FSC-Certified Plywood Supply Agreement | Engineered wood substitution commands measurable premiums in Japanese interior-aesthetic-driven purchasing. |
| Foldable Steel-Frame Technology Licensing | Flat-pack shipping density reduces freight costs by half for last-mile fulfillment networks in Tokyo and Osaka. |
Methodological Framework
A spread of perspectives from pet product manufacturing executives, veterinary behavioral specialists, pet specialty retail category buyers, and corrugated packaging engineers converged on the working assumptions. Primary interviews combined with secondary validation against customs records, pet industry trade association filings, and SEC disclosures from diversified pet product conglomerates. Bottom-up and top-down triangulation cross-checked production capacity estimates against retail inventory turnover data.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling segmentation dimensions including material hierarchy, end-user procurement channel, functional configuration, and dimensional class. CAGRs derived from unit volume trajectory analysis and value-per-unit progression across certification tiers. Industry-specific forecast inputs incorporated sisal fiber commodity price cycles and EU EPR packaging obligation compliance cost structures.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending indices or ocean freight rate volatility would shift the trajectory. Forecasts reflect documented assumptions on REACH enforcement intensity and veterinary clinic procurement adoption curves. Material shifts in California Proposition 65 disclosure timelines or Brazilian harvest yield patterns would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
DTC Pet Food Market
Pet Care Products
Cat Shampoo Market
Pet Care Products
Flea, Tick, and Heartworm Products Market
Pet Care Products
Global Pet Supplies Market
Pet Care Products
Pet Accessories Market
Pet Care Products
Pet Treats and Chews Market
Pet Care Products
Pet Tick and Flea Prevention Market
Pet Care Products
Pet Car Seat Protectors Market
Pet Care Products
Cat Mat Market
Pet Care Products
Inflatable Pet Collars Market
Pet Care Products
Plant-Based Pet Food Market
Pet Care Products
Cat Cage Market
Pet Care Products
South America Pet Treats Market
Pet Care Products
Mink Oil Market
Pet Care Products
Dog Crate Furniture Market
Pet Care Products
Pet Care Ingredients Market