
 Asia Pacific Household Electric Grills Market | 2026-2036
Asia Pacific Household Electric Grills Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Household Electric Grills Market Outlook
Subscription-based maintenance and software-defined temperature control is rebalancing how manufacturers monetize electric grills beyond the initial hardware sale. Weber Inc leverages its brand strength to anchor premium positioning across Australian and Japanese retail channels. Groupe SEB competes through manufacturing scale that sustains cost leadership in compact contact grill segments. Philips differentiates via R&D intensity in infrared heating elements that reduce preheat cycles for time-constrained urban households.
Asia Pacific household electric grills are countertop cooking appliances employing sheathed heating elements, typically rated between 1,000 and 2,500 watts, with non-stick coated aluminum or ceramic plates designed for smoke-reduced indoor grilling. Contact grills dominate volume sales due to space efficiency in dense urban kitchens across Tokyo, Singapore, and Hong Kong. Infrared technology leads the premium tier where faster heat-up justifies price positioning, while compact size categories capture the fastest growth as developers shrink apartment footprints throughout the region's megacities.
China's SAMR enforces GB standards for electrical safety and electromagnetic compatibility that determine market access for imported grills. India's BIS mandatory certification scheme for household electrical appliances creates compliance barriers that filter out uncertified imports. Australia's electrical safety regulators and Japan's METI product safety frameworks add further layering of technical requirements. Stakeholders must monitor divergence between national certification regimes as harmonization lags behind cross-border e-commerce expansion.
Market Dynamics
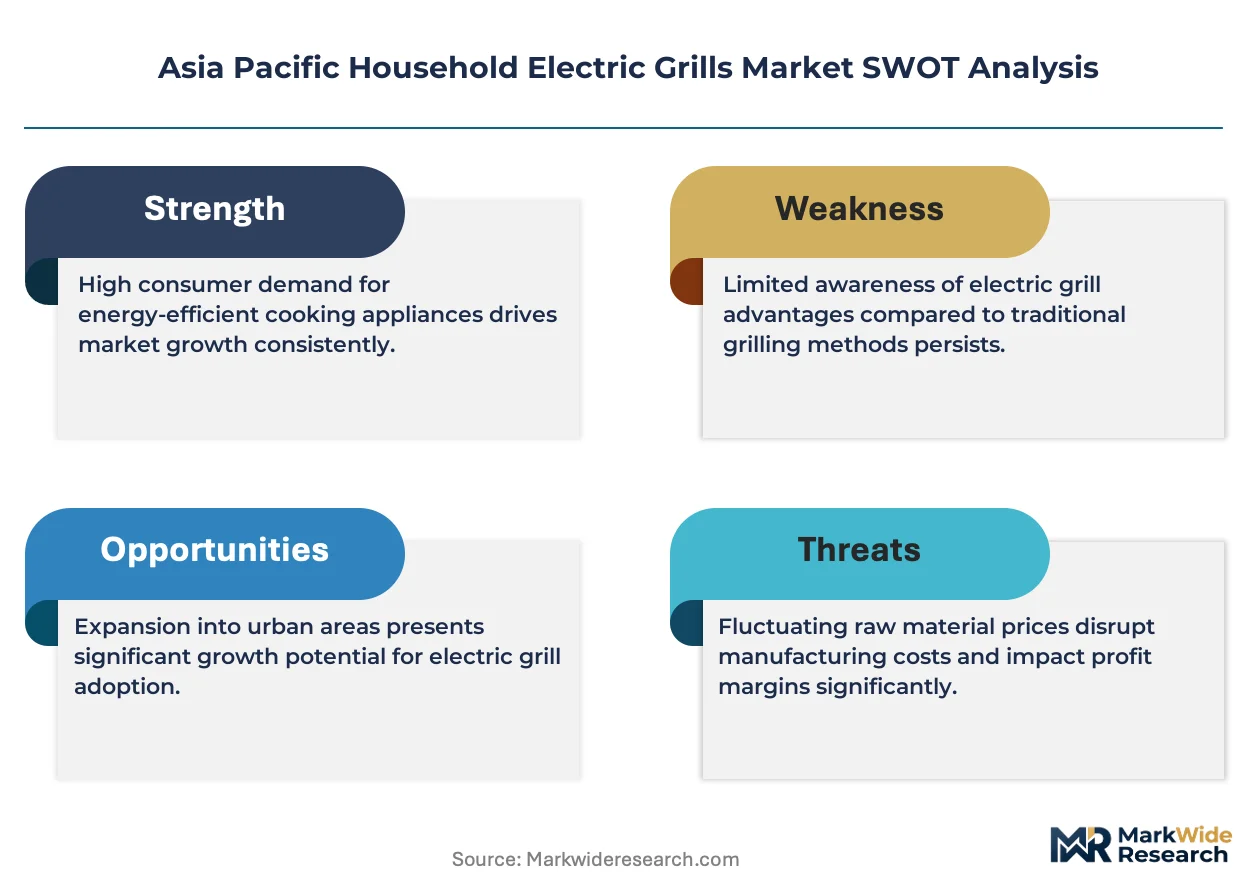
Compact kitchen formats across Asia Pacific megacities are compressing appliance footprints and forcing manufacturers to prioritize wattage efficiency over raw power output in product development cycles.
Growth Catalysts
- Urban residential densification:Apartment construction in Seoul, Tokyo, and Mumbai eliminates open-flame cooking options, creating captive demand for smoke-reduced electric alternatives.
- China's GB electrical safety standards:SAMR enforcement of electromagnetic compatibility requirements accelerates product quality upgrades that filter substandard imports from cross-border channels.
- Infrared heating technology:Reduced preheat cycles address time-constrained household routines in tier-one Chinese cities and Indian metropolitan corridors.
Market Restraints
- Aluminum and ceramic coating input volatility:Non-stick plate materials face price instability from energy-intensive smelting and rare earth supply concentration.
- Certification fragmentation:Divergent BIS, GB, and METI frameworks create compliance cost layering that advantages domestic incumbents over foreign entrants.
- Induction cooktop substitution:Multi-function appliances with grilling modes capture countertop space in premium Australian and Japanese households.
Strategic Opportunities
- India's PLI scheme for consumer appliances:Domestic manufacturing incentives reduce landed cost disadvantages for brands establishing local assembly.
- Subscription-based temperature control software:Firmware monetization creates recurring revenue streams beyond hardware margins in tech-forward Japanese and Korean markets.
- Southeast Asian e-commerce penetration:Platform logistics infrastructure in Indonesia, Vietnam, and Thailand opens direct-to-household distribution outside traditional retail.
Industry Challenges
- Cross-border certification timelines:BIS mandatory testing for household electrical appliances extends product launch windows by 4-8 months for unestablished brands.
- Sheathed heating element sourcing:Concentrated supply of nickel-chromium alloys in specific manufacturing clusters creates vulnerability to regional logistics disruptions.
- Legacy kitchen footprint standards:Developer specifications for built-in appliances in older residential stock resist retrofit of countertop electric formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Household Electric Grills Market |
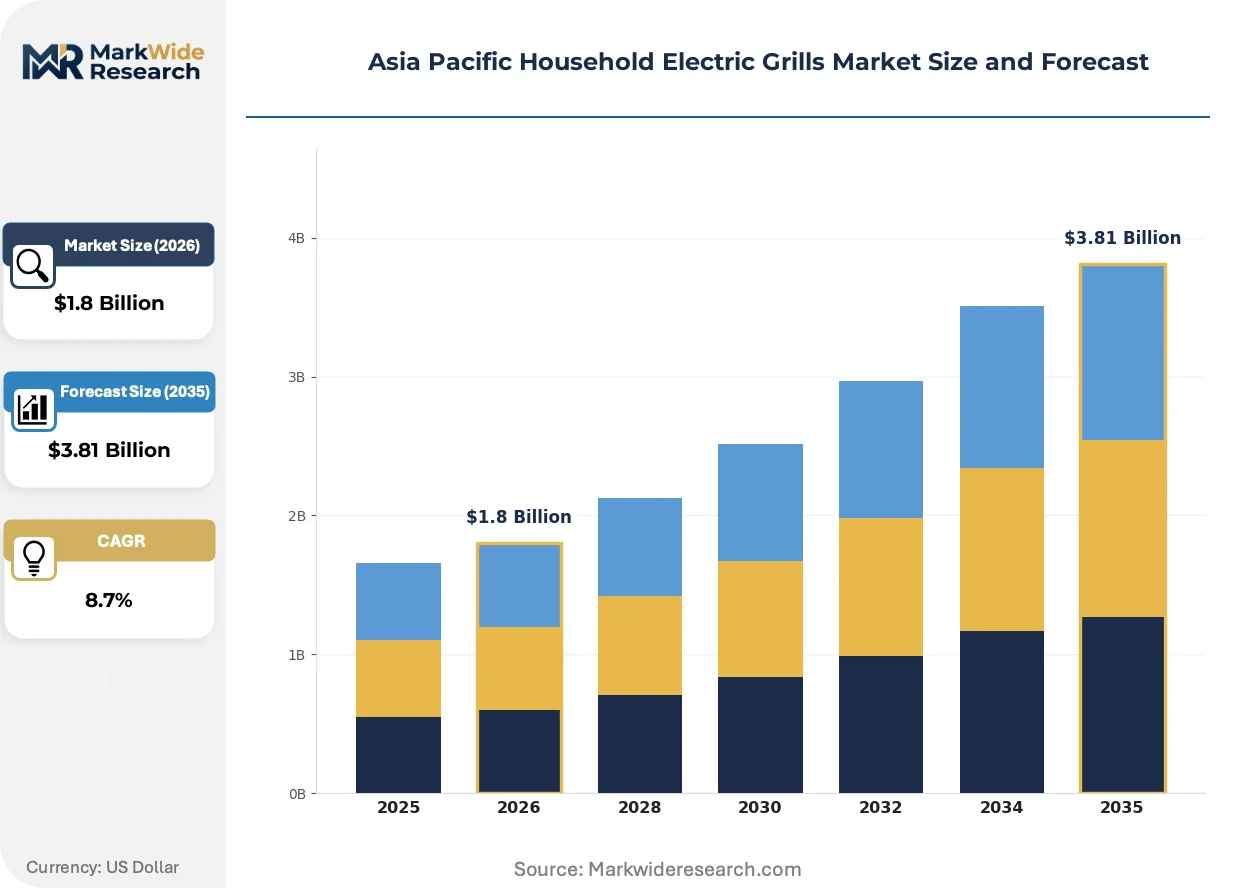
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contact Grills, Open Grills, Panini Presses, Griddle Plates Technology: Infrared, Induction, Convection, Electric End User: Households, Restaurants, Cafes, Catering Services Size: Compact, Standard, Large, Multi-functional |
| Companies Covered | Char-Broil, ElectriChef, Weber Inc, Cuisinart, Groupe SEB, Philips, George Foreman, Tefal, FIRE MAGIC, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Household Electric Grills Market Strategic Shifts
Smart connectivity and precision thermal management are repositioning electric grills from commodity appliances to data-generating kitchen endpoints with service attach potential.
Infrared ceramic heating elements are integrating into premium product tiers across Japanese and Australian retail channels. Urban households with sub-60-minute meal preparation windows adopt these configurations at accelerated rates. The technology is integrating temperature uniformity controls that compress the performance gap between electric and open-flame grilling in consumer perception.
India's BIS mandatory certification scheme for household electrical appliances is tightening market access requirements. Uncertified imports face systematic filtering at customs clearance points. Compact contact grill segments experience the greatest compliance friction as low-cost manufacturers struggle with testing cost absorption.
Apartment dwellers in Seoul, Tokyo, and Hong Kong are compressing replacement cycles for countertop cooking appliances. Traditional 7-10 year durability expectations contract to 3-5 year horizons as aesthetic and feature obsolescence accelerates. Premium retailers in Singapore and Sydney respond with trade-in programs that capture residual value and lock repeat purchase behavior.
Asia Pacific Household Electric Grills Market Segmentation
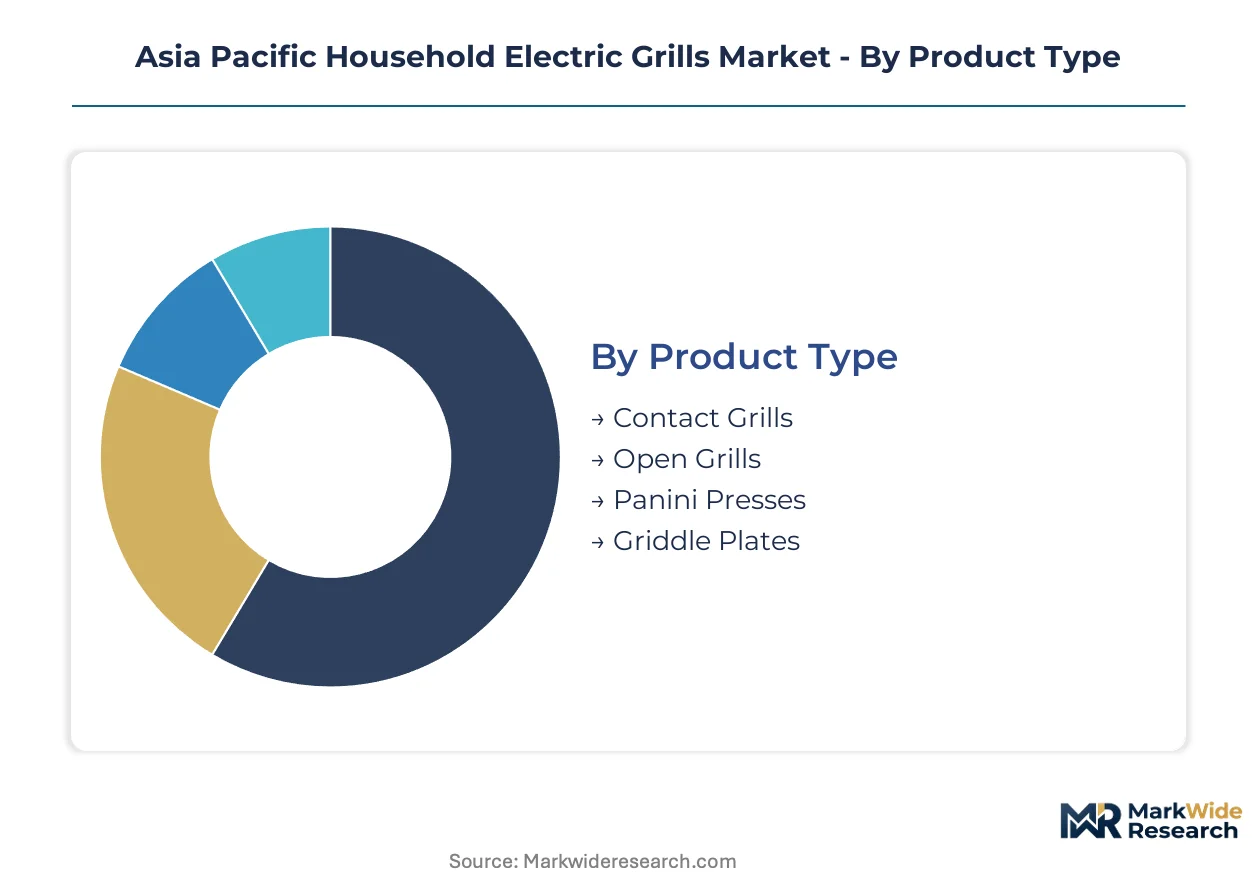
Asia Pacific electric grill manufacturers calibrate product portfolios against divergent kitchen footprints and regulatory environments across Seoul, Tokyo, Mumbai, and Sydney. Segmentation discipline separates volume leaders serving mass apartment markets from premium configurations targeting time-constrained professionals in tier-one Chinese and Indian cities.
Product Type:
Sheathed heating element supply concentrates in East Asian manufacturing clusters, forcing product type decisions around wattage efficiency and plate geometry rather than raw thermal output.
- Contact Grills:Dual-surface heating with non-stick coated aluminum plates delivers smoke-reduced cooking through clamped contact pressure. Demand concentrates in Tokyo, Hong Kong, and Singapore where sub-6-square-meter kitchen footprints eliminate open-flame alternatives and prioritize vertical storage.
- Open Grills:Single-surface configurations with exposed heating elements replicate open-flame aesthetics for balcony and terrace installations. Australian households in Sydney and Melbourne adopt these for outdoor-adjacent cooking where strata regulations permit limited open-flame use.
- Panini Presses:Compact hinged designs with ribbed cast-aluminum plates target sandwich preparation in Indian metropolitan corridors.
- Griddle Plates:Flat-surface configurations with uniform heat distribution serve multi-item breakfast preparation in Japanese and Korean urban households.
Contact grills absorb the bulk of installed capacity; open grills are expanding most quickly.
Technology:
Cost tier stratification separates premium thermal management systems from baseline resistive heating across Chinese and Indian retail channels.
- Infrared:Ceramic heating elements with quartz tubes achieve surface temperatures in under 90 seconds, compressing meal preparation windows for Seoul and Shanghai professionals. Premium positioning in Japanese electronics retail and Australian department stores justifies price multiples over conventional electric configurations.
- Induction:Magnetic field heating with ferrous plate requirements limits compatibility but delivers precise temperature control for Mumbai and Bangalore households with existing induction cooktop infrastructure.
- Convection:Forced-air circulation with integrated fans reduces surface temperature differentials across cooking zones.
- Electric:Resistive sheathed elements with bimetallic thermostats dominate entry-tier pricing in Southeast Asian e-commerce channels.
Infrared configurations command the steepest expansion trajectory as preheat time sensitivity intensifies across tier-one Asian cities.
End User:
Application context determines durability specifications and warranty structures across residential and commercial installation bases.
- Households:Countertop appliances rated for 3-5 year replacement cycles in Seoul, Tokyo, and Hong Kong where aesthetic obsolescence accelerates turnover. Compact contact formats dominate with wattage ratings between 1,000 and 1,500 watts optimized for apartment circuit limitations.
- Restaurants:Commercial-duty stainless steel housings with replaceable heating elements withstand continuous operation in Seoul's Korean barbecue establishments and Tokyo's izakaya chains.
- Cafes:Panini presses with rapid recovery times serve high-throughput sandwich preparation in Sydney and Melbourne coffee culture venues.
- Catering Services:Portable configurations with detachable plates facilitate event-based deployment across Indian wedding catering and Australian corporate hospitality.
Households absorb the bulk of installed capacity; restaurants are gaining share fastest.
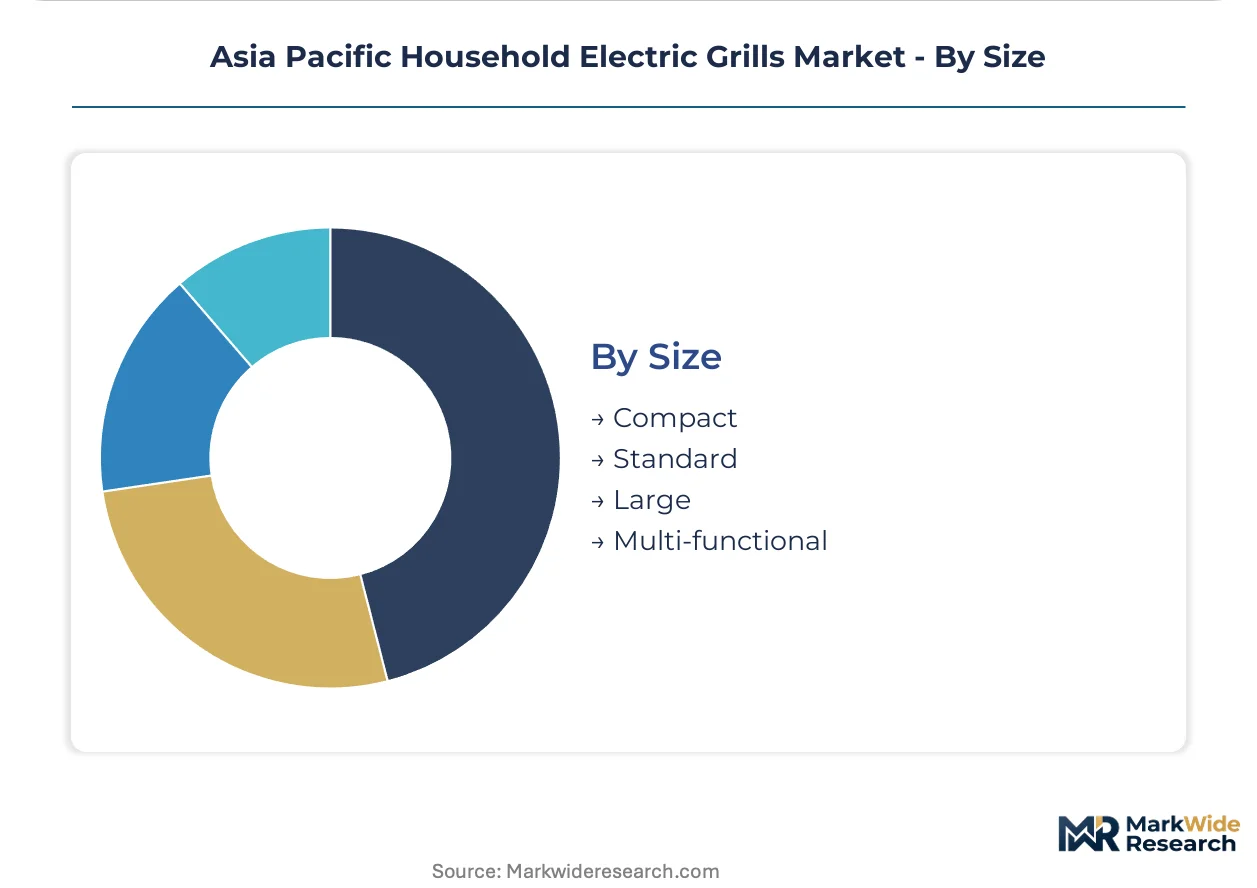
Size:
Customer type segmentation aligns with developer specifications for built-in versus countertop installation across aging and new residential stock.
- Compact:Footprints under 25 centimeters square with vertical storage profiles capture fastest growth as Mumbai, Manila, and Jakarta developers shrink apartment kitchens below 4 square meters. Wattage efficiency above 80 watts per square centimeter of cooking surface maintains thermal performance despite reduced element length.
- Standard:Mid-size configurations with 30-35 centimeter widths serve family meal preparation in Australian suburban households and Indian joint-family residences.
- Large:Professional-grade surfaces exceeding 40 centimeters target entertaining-focused households in Sydney's North Shore and Melbourne's eastern suburbs.
- Multi-functional:Interchangeable plate systems with grill, griddle, and waffle configurations maximize utility per unit of countertop space.
Standard sizes absorb the bulk of installed capacity; compact formats are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in China's Guangdong and Zhejiang provinces while consumption fragments across dense urban corridors from Seoul to Mumbai. Japanese and Australian households absorb premium-tier infrared configurations. Indian and Southeast Asian markets pull entry-level contact grill volumes through e-commerce channels.
China
Tier-one cities Shanghai, Beijing, and Shenzhen drive replacement demand as 3-5 year product cycles compress further. SAMR enforces GB standards for electromagnetic compatibility that filter substandard cross-border imports. Manufacturing clusters in Foshan and Ningbo supply sheathed heating elements to regional assembly operations.
Japan
Tokyo and Osaka metropolitan households prioritize preheat speed and countertop footprint over raw wattage. METI product safety frameworks layer technical requirements atop international IEC baselines. Premium electronics retail in Akihabara and Shibuya anchors infrared grill distribution for time-constrained professionals.
India
Mumbai, Delhi-NCR, and Bangalore corridors generate concentrated demand from compact apartment formats below 5 square meters. BIS mandatory certification for household electrical appliances extends launch timelines by 4-8 months for unestablished brands. The PLI scheme for consumer appliances incentivizes domestic assembly in Gujarat and Tamil Nadu industrial zones.
Australia
Sydney and Melbourne households balance balcony grilling permissions against strata open-flame restrictions. TGA electrical safety regulators and state-level energy efficiency programs shape product specifications. North Shore and eastern suburbs retail channels sustain premium positioning for entertaining-focused configurations.
South Korea
Seoul apartment dwellers face strict building codes eliminating gas grill alternatives in high-rise stock. MFDS electrical appliance safety standards align with international frameworks while maintaining national testing protocols. Gangnam and Jongno district electronics retail concentrates distribution for compact contact formats.
Asia Pacific Household Electric Grills Market Competitive Environment
Top-tier vendors anchor premium positioning through brand equity and R&D intensity, while mid-tier specialists compete on manufacturing scale and cost absorption. The vendor base stratifies across three archetypes: heritage outdoor brands pivoting indoor, diversified appliance conglomerates with contact grill portfolios, and contract manufacturers serving private-label retail. Consolidation pressure intensifies as certification costs rise and e-commerce platforms disintermediate traditional distribution. Strategic moves center on geographic licensing partnerships and firmware-based recurring revenue attachment.
Within the heritage brand tier, Weber Inc and Char-Broil occupy positions defined by outdoor grilling credibility translated to smoke-reduced indoor formats. Among diversified appliance conglomerates, Groupe SEB and Philips exemplify scale-driven competition through manufacturing breadth and component R&D respectively. Cuisinart and Tefal sit within the kitchen-electronics specialist archetype, leveraging countertop appliance distribution infrastructure across Australian and Japanese retail channels.
| Leading Market Players |
|---|
| Char-Broil |
| ElectriChef |
| Weber Inc |
| Cuisinart |
| Groupe SEB |
| Philips |
| George Foreman |
| Tefal |
| FIRE MAGIC |
| Others |
Value Chain & Pricing Dynamics
Infrared ceramic heating element adoption simultaneously compresses manufacturing cost curves and concentrates procurement leverage among East Asian component specialists. Chinese and Japanese suppliers of quartz tube assemblies now anchor tiered pricing structures across premium and standard product configurations.
Pricing Analysis
Margin tightening in entry-tier contact grills reflects BIS certification cost absorption by Indian market entrants. Three-tier pricing structure across premium infrared, standard electric, and economy resistive-heating levels segments buyer archetypes. Pricing pressure stems from aluminum plate input volatility and rare earth supply concentration. Southeast Asian e-commerce households exhibit highest price sensitivity; Australian entertaining-focused buyers show lowest.
Supply Chain Analysis
Direct-to-retail channels handle premium infrared grill distribution through Japanese electronics retail and Australian department stores. Manufacturing concentrates in China's Guangdong and Zhejiang provinces with sheathed heating element sourcing from Foshan and Ningbo clusters. Nickel-chromium alloy supply rests on concentrated East Asian metallurgical capacity. Single-source vulnerability in ceramic coating inputs creates disruption exposure. Distribution runs through platform logistics infrastructure in Indonesia, Vietnam, and Thailand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into sheathed heating element production represents the decisive upstream lever as manufacturers race to capture margin and de-risk supply concentration.
For Market Incumbents: Lock in component supply through captive production or long-term offtake agreements with Foshan and Ningbo metallurgical specialists. Secure BIS pre-certification for Indian market access before competitor filing windows close. Defend against induction cooktop substitution by accelerating infrared preheat performance gaps. For New Entrants and Emerging Players: Capture compact contact grill demand in Indonesia, Vietnam, and Thailand through platform-native distribution partnerships. Penetrate India's PLI-incentivized domestic assembly corridor before certification backlogs extend. Lead with subscription-enabled temperature control software to differentiate from hardware-commoditized incumbents. For Investors and Strategic Acquirers: Exit pathways concentrate in platform rollup opportunities and heritage brand licensing plays. Five-to-ten year viability hinges on firmware monetization attachment rates and certification barrier sustainability. Watch BIS testing queue lengths as inflection signal for Indian market access friction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heating Elements | Captive nickel-chromium supply from Foshan clusters secures margin and de-risks procurement. |
| BIS Pre-Certification Investment | Early filing in India's mandatory scheme compresses competitor launch windows by 4-8 months. |
| Subscription Firmware Launch | Recurring revenue attachment in Japanese and Korean markets transcends hardware commoditization. |
| Southeast Asian Platform Partnership | Direct-to-household logistics in Indonesia, Vietnam, and Thailand bypasses traditional retail gatekeepers. |
| Infrared Technology Licensing | Quartz tube assembly IP monetization extracts value from R&D intensity without capacity buildout. |
Study Parameters
Independent corroboration across product managers at Groupe SEB and Philips, procurement leads at Australian retail chains, and regulatory affairs specialists at India's BIS underwrites the qualitative findings. Primary interviews with Tokyo and Seoul apartment dwellers, supplemented by customs records from China's SAMR and Japan's METI filings, anchor demand-side validation. Secondary sources include GB standards documentation, BIS certification registries, and e-commerce platform transaction data from Indonesia and Vietnam. Bottom-up unit economics triangulate against top-down category spending estimates.
Comparable-period anchoring to 2026 baseline values structures the projection horizon across product type, technology tier, end-user segment, and size category dimensions. CAGRs derive from segmented growth rate modeling with cross-validation against residential construction permits in Seoul, Tokyo, and Mumbai. Infrared adoption curves and certification timeline elasticity inform technology-transition assumptions throughout the forecast period.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare earth supply disruptions and divergence between national certification regimes. Base assumptions reflect SAMR enforcement intensity, PLI scheme continuity, and platform logistics infrastructure buildout rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Tabletop Kitchen Products Market
Kitchen Appliances
India Mixer Grinder Market
Kitchen Appliances
US Range Cooker Market
Kitchen Appliances
Built-In Kitchen Appliances Market
Kitchen Appliances
Smart Kitchen Faucet Market
Kitchen Appliances
Smart Connectivity Kitchen Appliances Market
Kitchen Appliances
Canada Kitchen Appliances Market
Kitchen Appliances
Mixer Grinder Market
Kitchen Appliances
Global Stainless Woks Market
Kitchen Appliances
Luxury Kitchen Appliances Market
Kitchen Appliances
Middle East Electric Vegetable Chopper Market
Kitchen Appliances
Europe Kitchen Appliances Market
Kitchen Appliances
Cotton Candy Maker Market
Kitchen Appliances
Asia-Pacific Air Fryers Market
Kitchen Appliances
US Household Coffee Machine Market
Kitchen Appliances
Europe Air Fryers Market