
 Pet Tick and Flea Prevention Market | 2026-2036
Pet Tick and Flea Prevention Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Tick and Flea Prevention Market Analytics
The manufacturing scale gap between multinational pharmaceutical operators and regional generic houses is collapsing as active ingredient sourcing consolidates around a handful of isoxazoline suppliers. Zoetis leverages captive chemistry capacity to sustain margin on next-generation oral chewables. Boehringer Ingelheim anchors its position through vertical control over fipronil synthesis. Merck & Co. competes by dominating the veterinary clinic channel with rep-administered injectable platforms.
Pet tick and flea prevention encompasses ectoparasiticide formulations—topical spot-ons containing permethrin or selamectin, oral isoxazoline tablets, impregnated polymer collars, and residual premise sprays—engineered to interrupt arthropod nerve conduction or repel vectors before attachment. These products serve the commercial purpose of reducing zoonotic disease transmission and veterinary treatment costs in companion animal populations. Oral medications now capture the fastest expansion as pet owners shift from monthly topical application to longer-duration systemic protection, while topical treatments retain the largest volume base in emerging markets where price sensitivity shapes purchasing. Collars occupy a narrowing mid-tier as premium pet stores promote twelve-month sustained-release formulations against commodity alternatives.
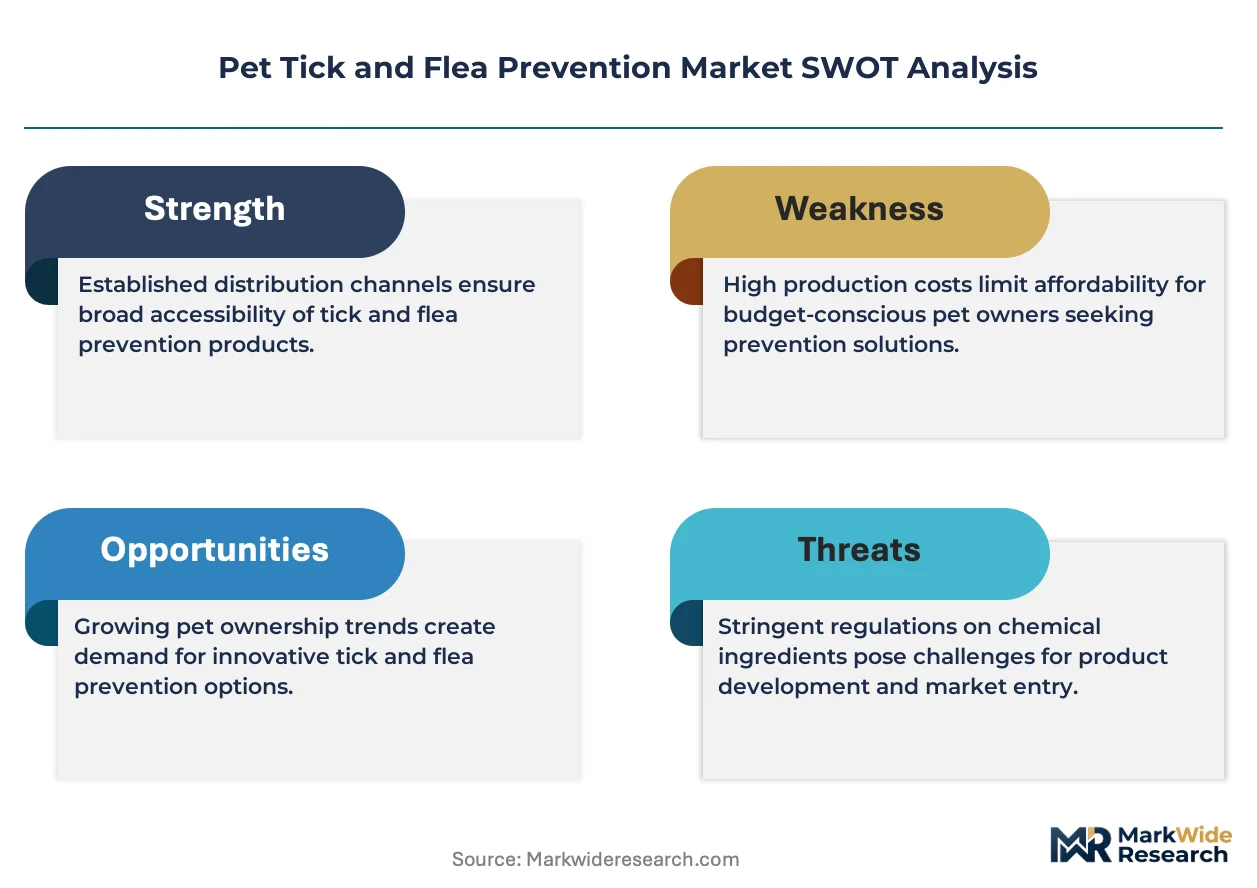
The EPA regulates environmental release profiles of permethrin-based premises sprays under FIFRA, while the FDA Center for Veterinary Medicine governs oral isoxazoline safety labeling and adverse event reporting. State veterinary boards in California and New York enforce prescription requirements that restrict online retail access to certain actives. Stakeholders must monitor how evolving residue tolerance thresholds and telemedicine prescribing rules reshape channel economics between clinics and direct-to-consumer platforms.
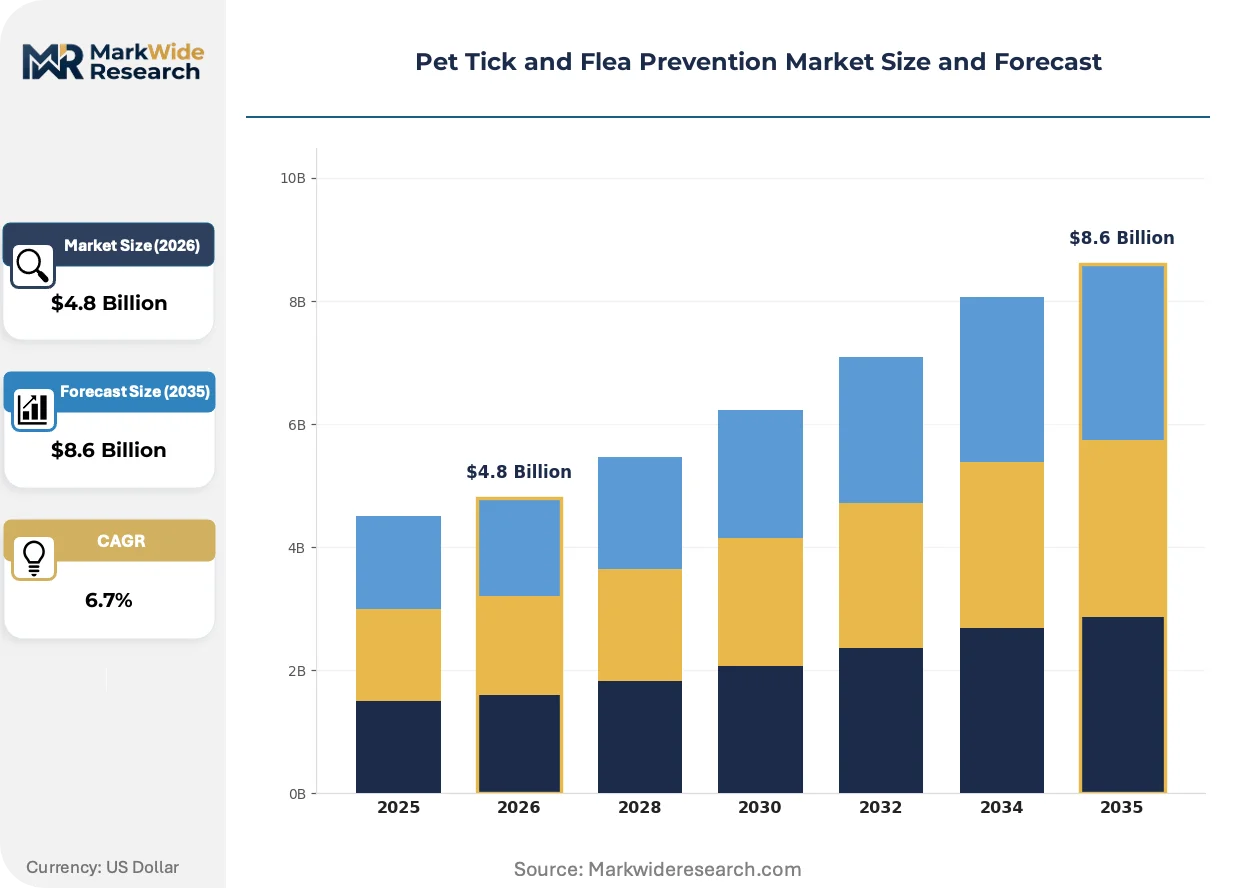
Market Dynamics
Consolidation around isoxazoline active ingredient suppliers is compressing formulation economics and forcing downstream manufacturers to secure captive chemistry capacity or accept margin erosion.
Growth Catalysts
- Pet Insurance Penetration:United States carriers now cover preventive parasiticide costs, reducing out-of-pocket resistance to prescription-grade oral medications.
- EPA Residue Threshold Tightening:Environmental release standards for permethrin-based premises sprays are elevating formulation barriers that favor capital-intensive operators with in-house toxicology testing.
- Veterinary Clinic Channel Expansion:Rep-administered injectable platforms are capturing companion animal owners seeking professional assurance over self-applied topicals.
Market Restraints
- Active Ingredient Concentration:Three isoxazoline suppliers control global feedstock for next-generation oral actives, creating single-source vulnerability.
- FIFRA Registration Timelines:EPA environmental fate studies for novel ectoparasiticide formulations extend commercialization cycles by 18-24 months.
- Generic Fipronil Oversupply:Indian and Chinese API manufacturers have flooded commodity topical markets, collapsing spot-on pricing in emerging economies.
Strategic Opportunities
- Telemedicine Prescribing Liberalization:State veterinary board rulings in Texas and Florida are opening online clinic channels previously restricted to physical examination requirements.
- Twelve-Month Sustained-Release Collars:Polymer matrix impregnation technology enables annual dosing cycles that capture premium pet store shelf space from monthly alternatives.
- Zoonotic Disease Prevention Mandates:CDC guidance on Lyme disease vector control is driving municipal and employer-sponsored pet prevention programs in endemic counties.
Industry Challenges
- Veterinary Pharmacovigilance Expertise:FDA Center for Veterinary Medicine adverse event reporting requirements demand specialized toxicologists that generic houses struggle to recruit.
- Cross-Contamination Controls:Multi-species manufacturing facilities face OSHA and EPA dual jurisdiction over airborne actives, requiring segregated production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Tick and Flea Prevention Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Treatments, Oral Medications, Collars, Sprays Animal Type: Dogs, Cats, Horses, Small Mammals Distribution Channel: Online Retail, Pet Stores, Veterinary Clinics, Pharmacies Customer Type: Pet Owners, Veterinarians, Pet Service Providers, Animal Shelters |
| Companies Covered | Boehringer Ingelheim, Zoetis, Merck & Co., Elanco Animal Health, Ceva Sante Animale, Virbac, Sergeant's Pet Care Products, The Hartz Mountain Corporation, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Tick and Flea Prevention Market Evolving Landscape
Systemic oral medications are fragmenting the historical dominance of topical spot-ons, while regulatory pressure on environmental residues and shifting owner preferences for convenience accelerate format turnover.
Isoxazoline class chemistry is decomposing the monthly application cycle that defined companion animal parasiticide markets for two decades. Veterinary clinics in the United States are converting preventive care protocols to 12-week oral dosing schedules. This shift is compressing retail pharmacy margins on legacy topical inventory while rewarding manufacturers with FDA-approved extended-duration formulations.
EPA FIFRA environmental fate assessments now require aquatic toxicity modeling for all permethrin-based premises sprays before state-level registration approval. The industrial consequence is exclusion of small-formulation houses lacking in-house ecotoxicology laboratories. Premise spray manufacturers serving kennel and boarding verticals are responding by outsourcing to contract research organizations or abandoning actives under enhanced scrutiny.
Subscription-based preventive care bundling is displacing transactional pharmacy purchasing among millennial pet owners. Direct-to-consumer platforms are capturing refill loyalty through automated dosing reminders and veterinary telehealth integration. This pattern concentrates in United States coastal metropolitan markets where pet insurance penetration exceeds national averages and same-day delivery infrastructure is mature.
Pet Tick and Flea Prevention Market Segmentation
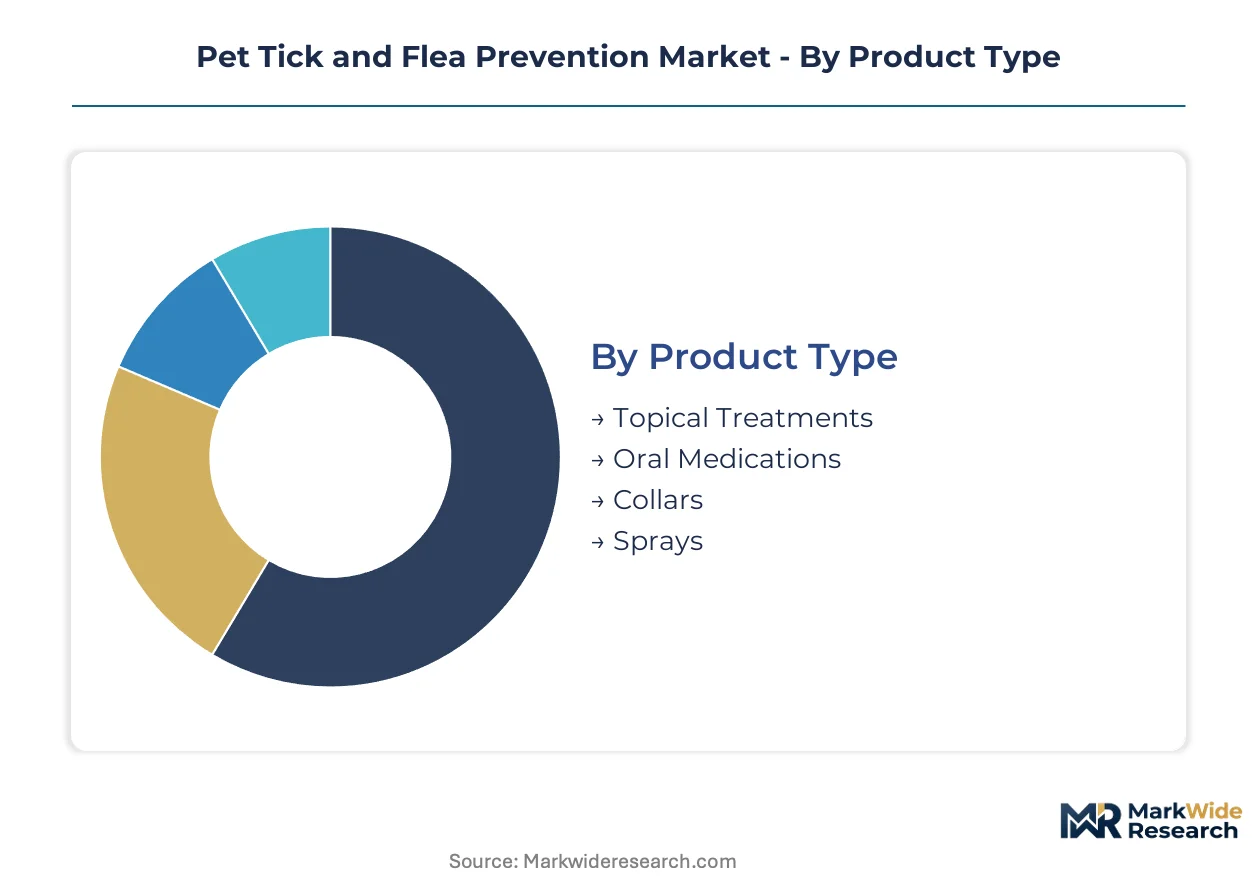
Format preferences and purchasing authority diverge sharply across pet tick and flea prevention segments. Veterinary channel concentration versus direct-to-consumer access reshapes margin structures and brand loyalty mechanics for manufacturers.
Product Type:
Domestic formulation dominates oral medication production, while topical treatments and collars flow through export-oriented contract manufacturers in India and China.
- Topical Treatments:Permethrin and selamectin spot-ons applied to skin at the neck base. Demand concentrates in emerging markets where price sensitivity sustains monthly application routines despite oral alternatives.
- Oral Medications:Isoxazoline tablets and chewables delivering systemic 12-week protection. United States veterinary clinics drive uptake as pet insurance covers prescription costs and owners prefer convenience over self-application.
- Collars:Polymer matrix devices releasing actives over 8-12 months.
- Sprays:Premise and direct-application formulations for kennel and household use.
Topical treatments command the established base. The steepest expansion runs through oral medications.
Animal Type:
Canine formulations generate the highest absolute volumes, yet feline-specific actives command premium pricing due to toxicity sensitivity and narrower approved chemistry portfolios.
- Dogs:Largest absolute consumption across all product formats. United States households with multiple large-breed animals drive prescription oral volumes through veterinary clinic channels.
- Cats:Pyrethroid-sensitive physiology restricts active ingredient options to selamectin and isoxazolines with feline-specific dosing. Premium pricing persists due to limited generic competition in approved actives.
- Horses:Equine-specific permethrin formulations for pasture and stable management.
- Small Mammals:Rabbit and ferret segments requiring species-adjusted dosing profiles.
Canine applications anchor volume throughput. Feline formulations capture the most favorable unit economics.
Distribution Channel:
Veterinary clinic and online retail channels are converging as telemedicine prescribing rules liberalize in Texas and Florida, eroding the historical physical-examination barrier.
- Online Retail:Subscription bundling and automated refill systems capture millennial pet owners in United States coastal metropolitan markets. Same-day delivery infrastructure and telehealth integration reduce friction for recurring purchases.
- Pet Stores:Premium shelf space for twelve-month sustained-release collars competes with commodity alternatives. Staff recommendation influence persists for first-time purchasers seeking tactile product evaluation.
- Veterinary Clinics:Rep-administered injectable platforms and prescription oral dispensing. State board requirements in California and New York restrict certain actives to professional channels.
- Pharmacies:Human retail chains expanding pet health sections with OTC topical inventory.
Veterinary clinics retain the highest-margin prescription tier. Online retail is climbing the fastest as telemedicine prescribing expands.
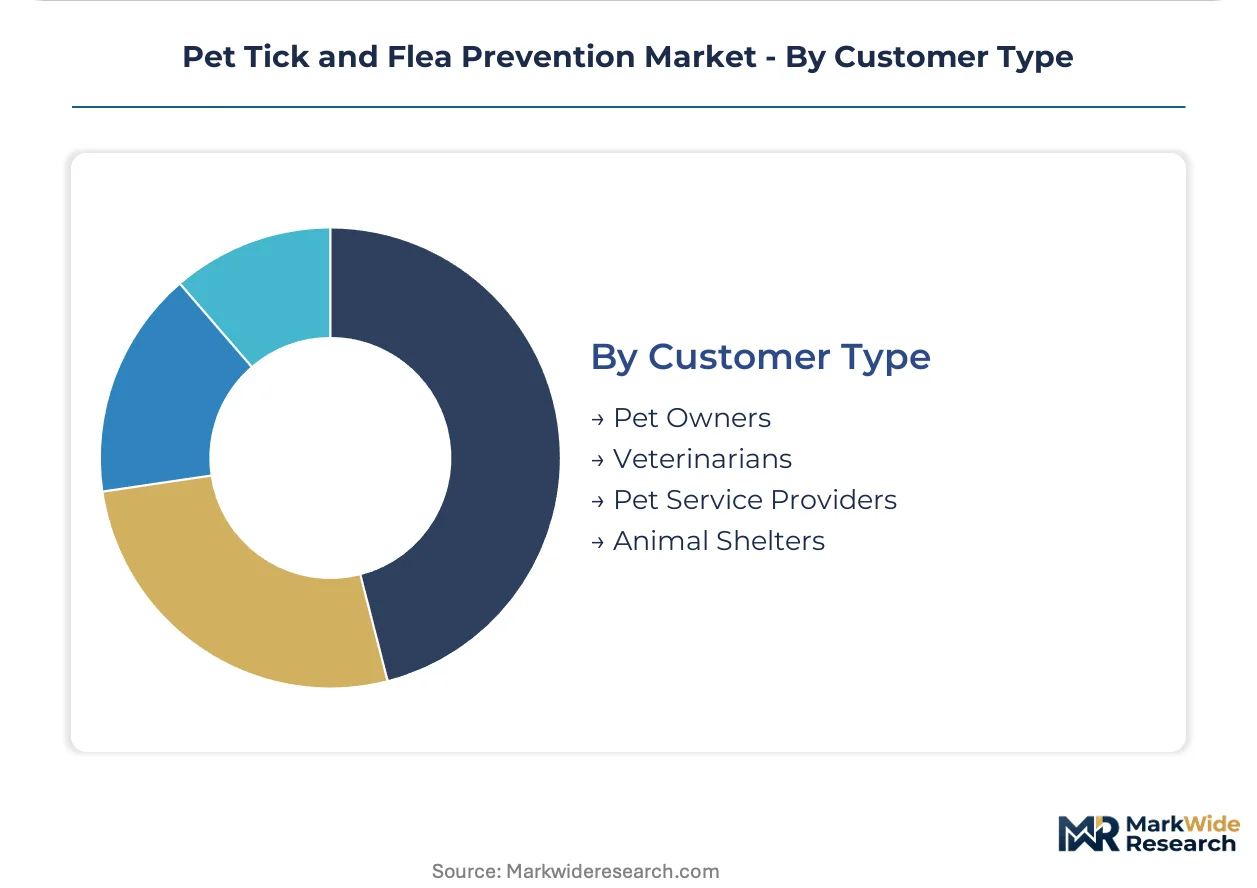
Customer Type:
Procurement authority fragments between emotional pet owner decision-making and veterinarian protocol enforcement, with service providers and shelters representing price-sensitive institutional volume.
- Pet Owners:Individual purchasers driving format preference shifts toward convenience and extended duration. Insurance coverage reduces out-of-pocket resistance to premium prescription options in United States markets.
- Veterinarians:Protocol gatekeepers controlling clinic inventory and rep-administered platform selection. FDA Center for Veterinary Medicine adverse event reporting requirements influence prescribing confidence.
- Pet Service Providers:Kennel and boarding operations requiring premise spray and collar inventory for liability protection.
- Animal Shelters:Municipal and nonprofit facilities prioritizing cost-minimized bulk procurement of generic topical treatments.
Pet owners represent the volume base. Veterinarian channel control is gaining strategic importance as prescription-grade oral formats expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented API synthesis concentrates in Asian manufacturing clusters, while formulation and prescription dispensing generate value capture in North American and European veterinary channels. Trade flows reflect this division: bulk isoxazoline and fipronil feedstocks move east-to-west, finished oral medications and clinic-administered platforms move west-to-east in smaller volumes at higher unit values.
United States
Pet insurance carriers now reimburse preventive parasiticide costs, reducing price resistance to prescription-grade oral medications in metropolitan markets. The FDA Center for Veterinary Medicine governs isoxazoline safety labeling and adverse event reporting requirements for all distributed products. California and New York state veterinary boards enforce prescription requirements that restrict online retail access to certain actives, channeling volume through clinic networks in Los Angeles and New York City corridors.
Germany
Specialty veterinary clinics in Bavaria and North Rhine-Westphalia drive uptake of extended-duration oral formulations among insured companion animal populations. The EMA and national regulators enforce pharmacovigilance standards that exceed baseline EU requirements, elevating compliance costs for generic entrants. Manufacturing concentration in the Rhine-Ruhr industrial zone supports formulation of fipronil-based topical actives for export to Central European markets.
China
Domestic API synthesis for isoxazoline intermediates supplies global pharmaceutical manufacturers, with production gravity in Jiangsu and Zhejiang provinces. The NMPA regulates veterinary drug manufacturing licenses under standards harmonizing with VICH international guidelines. Yangtze River Delta chemical parks host multi-ton capacity plants serving Boehringer Ingelheim and Zoetis captive requirements, though environmental inspections have tightened discharge permits for permethrin precursor synthesis.
India
Generic fipronil API oversupply from Gujarat and Maharashtra manufacturing clusters has collapsed spot-on pricing across emerging markets. The CDSCO regulates veterinary product registration timelines that typically lag OECD markets by 12-18 months, delaying novel oral formulation entry. Hyderabad and Ahmedabad house contract research organizations conducting EPA-mandated environmental fate studies for Western clients seeking FIFRA registration.
Brazil
Tropical climate conditions sustain year-round ectoparasite pressure, driving consistent demand for monthly topical applications over seasonal oral alternatives. ANVISA registration requirements for veterinary pharmaceuticals emphasize stability testing under high-humidity conditions. São Paulo state veterinary distribution networks channel products to Minas Gerais and Rio Grande do Sul agricultural zones where working dog populations require premise spray and collar combinations.
Pet Tick and Flea Prevention Market Competitive Landscape
Concentration sits with multinational pharmaceutical operators possessing captive chemistry capacity and FDA-approved manufacturing sites. Three strategic archetypes define competitive positioning: integrated API-to-formulation houses controlling isoxazoline synthesis, veterinary channel specialists dominating clinic-administered platforms, and regional generic manufacturers competing on fipronil commodity pricing. Dominant competitive moves include backward integration into active ingredient production and exclusive distribution partnerships with national veterinary clinic chains.
Among integrated pharmaceutical operators, Boehringer Ingelheim, Zoetis, and Merck & Co. exemplify the API-captive archetype through in-house synthesis or long-term offtake agreements with Asian feedstock suppliers. These companies occupy positions where regulatory compliance infrastructure and pharmacovigilance capabilities create defensive moats against generic entrants. Elanco Animal Health and Ceva Sante Animale represent the veterinary channel specialist model, with positioning tied to professional dispensing relationships rather than direct-to-consumer retail presence. Virbac anchors the European specialist tier with concentration in feline-specific formulations where toxicity sensitivity limits generic competition.
| Leading Market Players |
|---|
| Boehringer Ingelheim |
| Zoetis |
| Merck & Co. |
| Elanco Animal Health |
| Ceva Sante Animale |
| Virbac |
| Sergeant's Pet Care Products |
| The Hartz Mountain Corporation |
| Bayer AG |
| Others |
Value Network & Pricing Analysis
Captive isoxazoline synthesis capacity at Boehringer Ingelheim and Zoetis establishes minimum efficient scale thresholds that marginalize regional generic houses unable to secure backward integration into Asian API feedstocks. This concentration simultaneously elevates price floors for prescription-grade oral medications while compressing margins on commodity fipronil spot-ons sourced from Indian and Chinese contract manufacturers.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Premium prescription oral medications command brand loyalty through FDA Center for Veterinary Medicine safety labeling and veterinary clinic channel control. Standard-tier sustained-release collars compete on twelve-month convenience against monthly alternatives. Economy topical spot-ons face acute price erosion from generic fipronil oversupply in emerging markets. Cost compression in the economy tier intensifies because Indian and Chinese API manufacturers have flooded commodity channels, while insured pet owners in United States metropolitan markets show reduced price sensitivity for clinic-dispensed prescription formats.
Supply Chain Analysis
Jiangsu and Zhejiang province chemical parks underwrite global isoxazoline intermediate supply for integrated pharmaceutical operators. Gujarat and Maharashtra manufacturing clusters feed generic fipronil API to emerging market formulation houses. United States and German formulation facilities complete value-added finishing for veterinary clinic channels. Raw material dependencies center on permethrin precursors, selamectin fermentation feedstocks, and polymer matrix substrates for collar production. Single-source vulnerability concentrates in the three isoxazoline suppliers controlling global oral active feedstock. Distribution runs through veterinary clinic networks for prescription tiers, direct-to-consumer platforms for subscription refills, and pet store retail for collar and topical inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Preventive care subscription bundling generates recurring revenue attachment that outpaces standalone product margins, as millennial pet owners lock in automated refill loyalty through telehealth-integrated platforms.
For Market Incumbents: Fortify captive chemistry capacity in isoxazoline synthesis or secure long-term offtake agreements with Jiangsu and Zhejiang suppliers before feedstock consolidation tightens further. Deepen veterinary clinic channel control through exclusive distribution partnerships with national clinic chains, defending against telemedicine prescribing liberalization that erodes physical examination barriers in Texas and Florida. Invest in FDA Center for Veterinary Medicine pharmacovigilance infrastructure to sustain adverse event reporting capabilities that generic houses cannot replicate. For New Entrants and Emerging Players: Lead with twelve-month sustained-release collar formulations targeting premium pet store shelf space where tactile product evaluation and staff recommendation influence first-time purchasers. Target feline-specific actives where pyrethroid toxicity sensitivity restricts approved chemistry portfolios and sustains premium pricing with limited generic competition. Pursue contract research organization partnerships to conduct EPA-mandated environmental fate studies for Western clients seeking FIFRA registration, capturing service revenue from small-formulation houses abandoning permethrin-based premises sprays. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors veterinary channel specialists with professional dispensing relationships rather than direct-to-consumer retail exposure, as prescription-grade oral formats expand through clinic protocols. Long-term viability hinges on backward integration into active ingredient production or exclusive feedstock arrangements that survive isoxazoline supplier consolidation. Watch FDA Center for Veterinary Medicine adverse event reporting thresholds as an inflection indicator—escalating safety scrutiny would accelerate pharmacistovigilance capability scarcity and reward operators with in-house toxicology infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isoxazoline Synthesis | Captive API production secures margin protection against three-supplier feedstock concentration. |
| Veterinary Clinic Channel Partnership | Exclusive distribution with national chains defends prescription tier access against telemedicine erosion. |
| Twelve-Month Sustained-Release Collar Launch | Polymer matrix innovation captures premium pet store positioning from monthly alternatives. |
| Pharmacovigilance Infrastructure Investment | FDA adverse event reporting capabilities create defensive moats against generic entrants. |
| Telemedicine Platform Integration | Subscription bundling with automated dosing reminders locks in millennial refill loyalty. |
Research Methodology
Operator-level perspectives from veterinary clinic practice owners, pharmaceutical manufacturing executives, pet insurance product managers, and EPA regulatory compliance officers anchored the qualitative base. Secondary validation drew from FDA Center for Veterinary Medicine adverse event databases, EPA FIFRA registration filings, state veterinary board prescribing rule dockets, and pet insurance coverage policy disclosures. Bottom-up demand modeling across product formats, animal types, and distribution channels triangulated against top-down market sizing from API production capacity and finished goods trade flows.
Sensitivity analysis tested forecast outputs against variable assumptions for pet insurance penetration rates, telemedicine prescribing liberalization timelines, and isoxazoline supplier consolidation scenarios across the projection horizon. Segmentation dimensions modeled include product type, animal species, distribution channel, and customer procurement authority. CAGRs derived from annual growth rate interpolation between base and terminal year values, with veterinary clinic channel expansion and subscription bundling adoption as primary demand drivers.
Forecasts assume regulatory continuity in FDA Center for Veterinary Medicine safety labeling, EPA FIFRA environmental fate standards, and state veterinary board prescription requirements; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as telemedicine prescribing rules, isoxazoline feedstock availability, and generic fipronil oversupply conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Southeast Asia Pet Care Market
Pet Care Products
Pet Sitting Market
Pet Care Products
Europe Cat Food Market
Pet Care Products
Small Dog Harness Market
Pet Care Products
Vegan Dog Food Market
Pet Care Products
Taiwan Pet Food Market
Pet Care Products
India Pet Food Market
Pet Care Products
Cat Backpacks Market
Pet Care Products
Global Pet Stroller Market
Pet Care Products
Dog Boot for Winters Market
Pet Care Products
Dog Vitamins Market
Pet Care Products
US Pet Food Market
Pet Care Products
Pet Collar Market
Pet Care Products
Dog Bathing Systems Market
Pet Care Products
Pet Supplement Market
Pet Care Products
South Africa Pet Training Services Market