
 North America Pet Food Nutraceuticals Market | 2026-2036
North America Pet Food Nutraceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
North America Pet Food Nutraceuticals Market Analytics
Precision fermentation for bioactive peptides is reshaping how functional ingredients enter pet nutrition formulations. Nestle Purina PetCare leverages captive R&D pipelines to anchor its position in clinically validated health-enhancing ingredients. Mars, Incorporated sustains brand loyalty through vertical control over veterinary channel distribution. Hill's Pet Nutrition differentiates via prescription-grade positioning that commands premium shelf placement in specialty retail.
Pet food nutraceuticals comprise functional ingredients added to companion animal diets to deliver measurable physiological benefits beyond basic nutrition, including omega fatty acid profiles standardized to therapeutic thresholds and probiotic colony-forming units validated for gastric survival. The primary commercial purpose centers on addressing age-related mobility decline, digestive disorders, and immune modulation in aging pet populations. Functional treats occupy the largest margin pool as impulse-compatible formats with repeat purchase velocity, while probiotics represent the fastest-expanding segment driven by veterinary endorsement of gut-brain axis research. Soft chews lead form preferences due to palatability engineering and dosing precision, though powders gain traction among raw-feeding adherents seeking mix-in flexibility.
The FDA's Center for Veterinary Medicine oversees ingredient safety and health claim substantiation, while AAFCO model regulations guide state-level enforcement of nutritional adequacy statements across the United States and Canada. The National Animal Supplement Council's quality seal program shapes retailer acceptance criteria and consumer trust thresholds for non-prescription products. Stakeholders must monitor pending FDA guidance on hemp-derived cannabinoids in pet products, as this emerging ingredient class threatens to disrupt existing regulatory boundaries and competitive positioning.
Market Dynamics
Precision fermentation infrastructure is concentrating bioactive peptide production among vertically integrated ingredient suppliers, compressing formulation timelines for functional pet food manufacturers while FDA substantiation requirements extend clinical validation cycles.
Growth Catalysts
- AAFCO Model Bill Updates:State-level harmonization of nutritional adequacy statements reduces interstate compliance friction for multi-regional manufacturers. California and Texas have accelerated adoption timelines.
- Omega-3 Algal Sourcing:Marine ecosystem pressures are redirecting DHA/EPA procurement toward fermentation-derived alternatives with stable input costs.
- Veterinary Channel Expansion:Specialty retail clinics in the Pacific Northwest are creating dedicated functional nutrition sections with trained staff consultation.
Market Restraints
- Clinical Trial Cost Burden:FDA health claim substantiation requires multi-site canine studies with 18-24 month protocols, freezing smaller formulators out of therapeutic positioning.
- Probiotic Strain Proprietary Control:Two suppliers dominate gastric-survival-validated Lactobacillus and Bifidobacterium strains for companion animals.
- Hemp-Derived Ingredient Uncertainty:Pending FDA Center for Veterinary Medicine guidance on cannabinoid inclusion creates formulation freeze among risk-averse brands.
Strategic Opportunities
- Feline Functional Nutrition Gap:Dog-centric formulation R&D has left cat-specific mobility and urinary health segments underserved relative to population growth.
- Subscription Direct-to-Consumer Models:Soft chew personalization based on breed-specific metabolic profiles bypasses retail slotting fee structures.
- Canadian Regulatory Alignment:Health Canada PMRA and FDA CVM joint consultation processes may create streamlined North American approval pathways for novel ingredients.
Industry Challenges
- Cross-Functional Talent Scarcity:Veterinary nutrition PhDs with commercial formulation experience command premium compensation and limited geographic mobility.
- Legacy ERP Integration:Batch-level traceability requirements for probiotic CFU validation strain existing manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Pet Food Nutraceuticals Market |
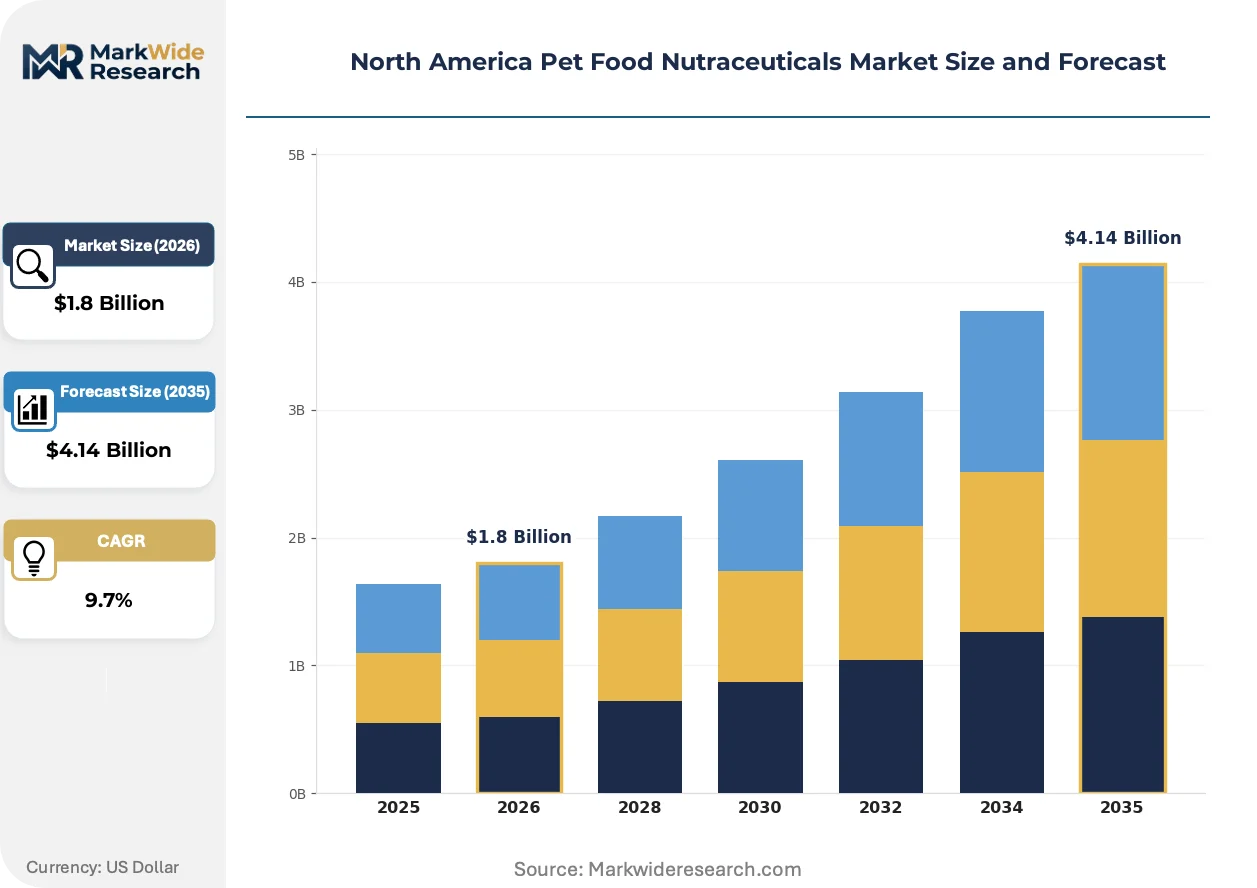
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Functional Treats, Dietary Supplements, Health-Enhancing Ingredients, Probiotics End User: Dog Owners, Cat Owners, Pet Stores, Veterinary Clinics Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pet Supply Stores Form: Soft Chews, Powders, Capsules, Liquid |
| Companies Covered | Wellness Pet Company, ADM, Mars, Incorporated, The J.M. Smucker Company, Nutramax Laboratories Veterinary Sciences, Nestle Purina PetCare, Vetoquinol, General Mills, Hill's Pet Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Pet Food Nutraceuticals Market Evolving Landscape
Biomanufacturing platforms are collapsing the traditional extraction-to-formulation value chain, while regulatory clarity gaps around novel ingredients force parallel-track development strategies.
Precision fermentation for bioactive peptides is digitizing supply chain transparency from strain banking to finished goods. Mid-size pet food manufacturers are adopting cloud-based batch records to compress ingredient provenance documentation from weeks to hours. This infrastructure is digitizing audit readiness for FDA inspections and retailer certification requirements.
Pending FDA guidance on hemp-derived cannabinoids in pet products is fragmenting competitive positioning. Manufacturers with existing veterinary drug approval experience are pre-positioning clinical data packages. Functional treat segments in California face the most acute compliance timeline pressure as state-level hemp regulations diverge from federal frameworks.
Raw-feeding adherents are driving powder format innovation for mix-in flexibility at home. Pacific Northwest specialty retailers are responding with refrigerated probiotic powder sections that bypass ambient supply chains. This channel evolution concentrates in urban markets with above-average veterinary nutritionist density.
North America Pet Food Nutraceuticals Market Segmentation
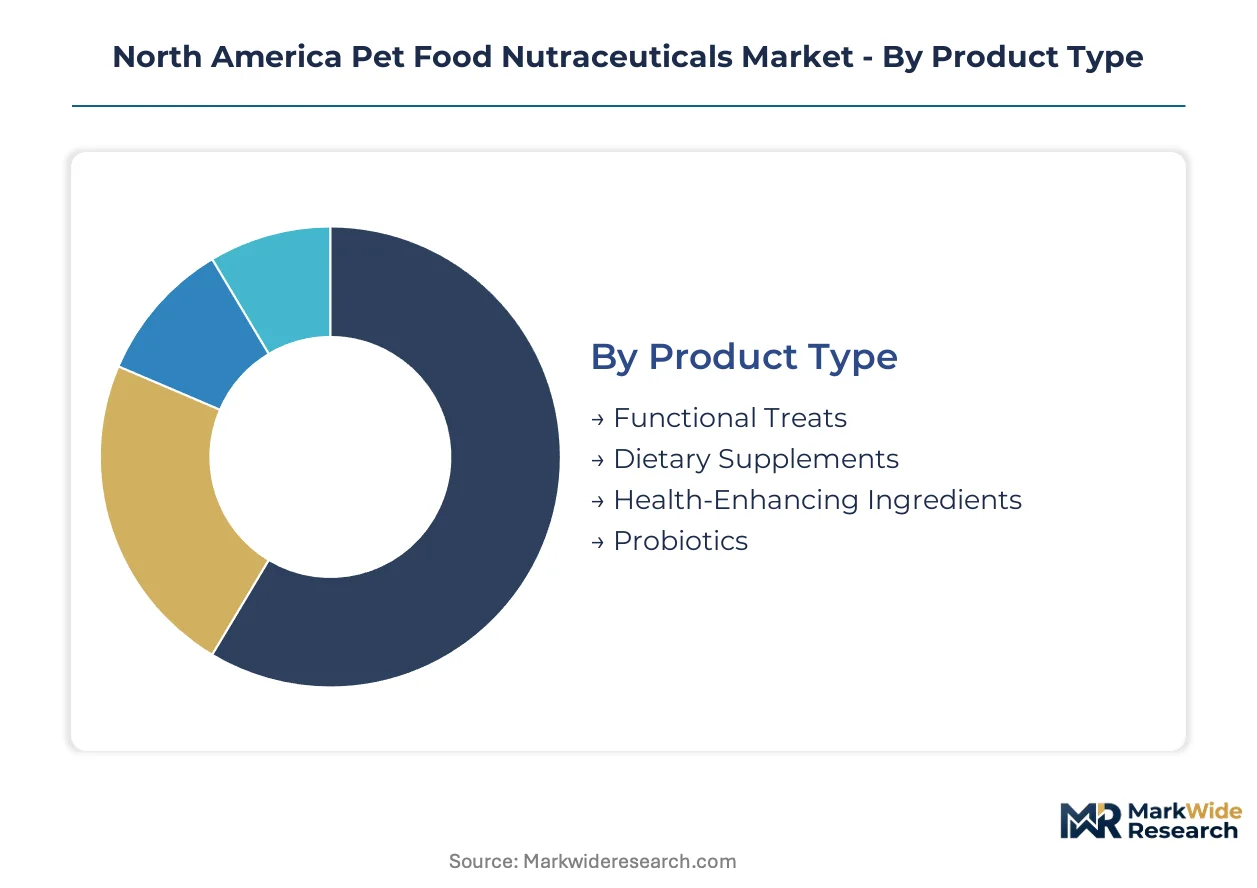
Segmentation in North American pet food nutraceuticals reveals how formulation complexity, channel control, and species-specific physiological requirements create distinct margin architectures. Manufacturers configure R&D and supply chain investments differently across each dimension.
Product Type:
After-sales intensity varies sharply by product type, with functional treats demanding continuous palatability optimization and probiotic formats requiring cold-chain logistics support.
- Functional Treats:Palatability-engineered formats with impulse-compatible packaging drive repeat purchase velocity in California's pet wellness cluster. Margin concentration here reflects premium positioning and veterinary endorsement protocols.
- Probiotics:Gastric-survival-validated colony-forming units with strain-specific metabolic profiling command technical premiums. Demand concentrates in Pacific Northwest specialty retail with refrigerated distribution infrastructure.
- Dietary Supplements:Standardized omega fatty acid profiles and therapeutic-threshold dosing for mobility support in aging companion animals.
- Health-Enhancing Ingredients:Bioactive peptides from precision fermentation platforms integrated into base kibble formulations.
Functional Treats holds the largest share; momentum sits with Probiotics.
End User:
Cost tier differentiation separates prescription-grade veterinary positioning from retail-accessible wellness formats.
- Dog Owners:Premiumization drivers concentrate spending on clinically validated mobility and digestive health solutions. California and Texas households show highest per-pet nutraceutical expenditure.
- Veterinary Clinics:Prescription-grade distribution with trained staff consultation creates captive demand for therapeutic-positioned products. Pacific Northwest specialty clinics lead functional nutrition section deployment.
- Cat Owners:Underserved segment relative to population growth, with limited feline-specific mobility and urinary health formulations available.
- Pet Stores:Staff training investments required to support non-prescription product recommendation credibility.
Dog Owners dominates current revenue; Cat Owners shows the steepest expansion trajectory as formulation R&D rebalances.
Distribution Channel:
Volume concentration in physical retail contrasts with margin expansion in direct-to-consumer subscription models.
- Specialty Stores:Pacific Northwest natural products corridor retailers with dedicated functional nutrition sections and trained consultation staff.
- Online Retail:Subscription personalization based on breed-specific metabolic profiles bypasses slotting fee structures. Cloud-based batch records enable rapid ingredient provenance documentation.
- Pet Supply Stores:National chain presence with standardized planogram placement for mainstream functional formats.
- Supermarkets:Mass-market penetration limited by shelf-space competition and lower staff expertise thresholds.
Specialty Stores anchors current volume; Online Retail is climbing the fastest on subscription model adoption.
Form:
Supply concentration in soft chew manufacturing reflects palatability engineering capabilities and dosing precision requirements.
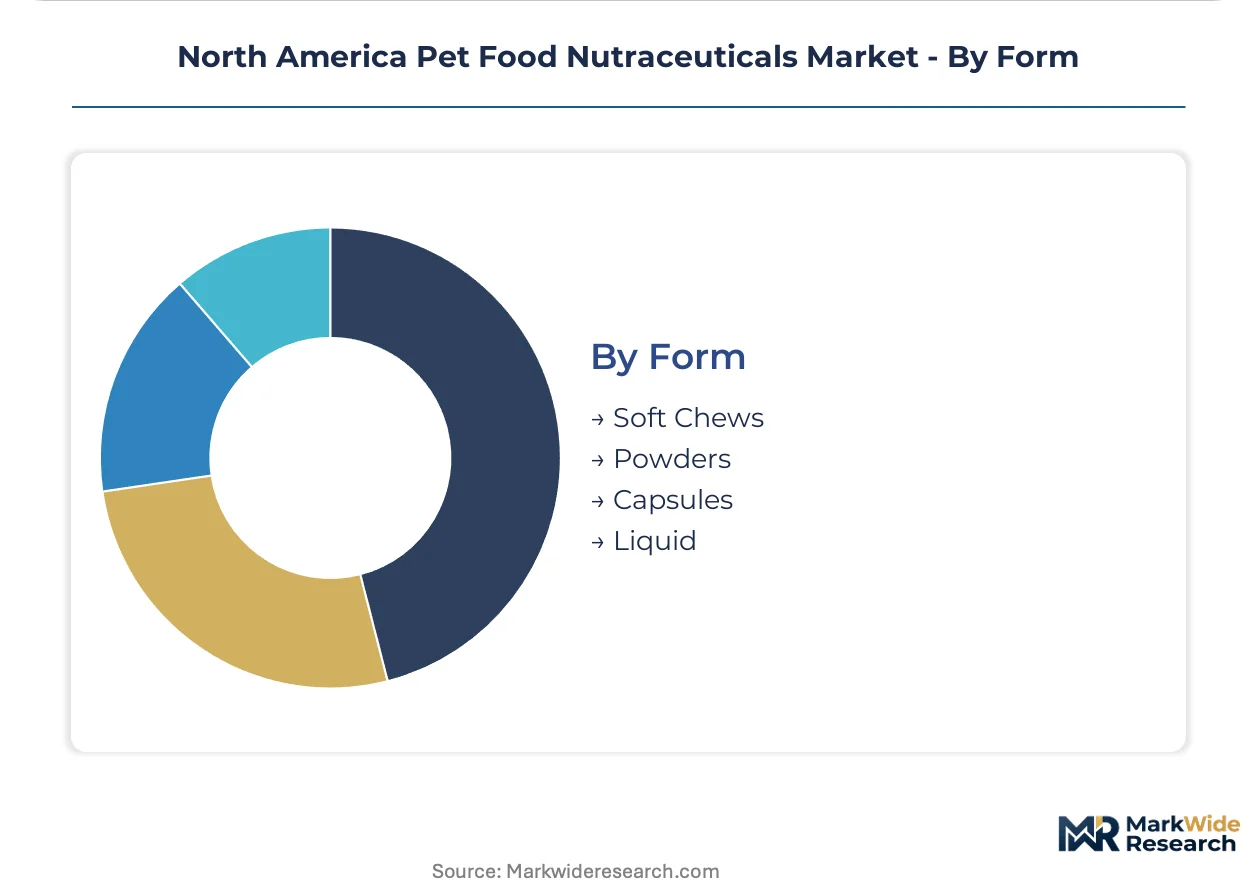
- Soft Chews:Palatability-optimized matrices with precise active ingredient dispersion. Manufacturing execution systems strain under batch-level traceability requirements for probiotic CFU validation.
- Powders:Mix-in flexibility for raw-feeding adherents drives urban market concentration. Pacific Northwest retailers deploy refrigerated sections bypassing ambient supply chains.
- Capsules:Human-pharma-adjacent formats with limited pet-specific palatability adaptation.
- Liquid:Specialized administration for therapeutic dosing in veterinary clinical settings.
Soft Chews maintains dominant share; Powders gains share fastest on raw-feeding format innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada exports precision-fermentation-derived bioactive peptides to U.S. pet food manufacturers concentrated in California and the Pacific Northwest. This cross-border ingredient flow anchors North American supply chain integration.
United States
Dog owner premiumization in California and Texas drives per-pet nutraceutical expenditure above national averages. FDA Center for Veterinary Medicine oversight of health claim substantiation shapes formulation timelines for multi-regional manufacturers. The Pacific Northwest natural products corridor hosts specialty retailers with dedicated functional nutrition sections and trained consultation staff.
Canada
Health Canada PMRA consultation with FDA CVM on novel ingredient approvals creates potential streamlined North American pathways. Fermentation infrastructure in Ontario and Quebec supplies bioactive peptide ingredients to U.S. formulators. Vancouver's pet wellness cluster concentrates refrigerated probiotic distribution for raw-feeding adherents.
Mexico
Middle-class pet ownership expansion in Mexico City and Monterrey generates demand for imported functional treats and supplements. COFEPRIS alignment with FDA safety standards facilitates cross-border product registration for U.S. brands. Guadalajara's manufacturing corridor hosts contract packagers serving North American private label programs.
North America Pet Food Nutraceuticals Market Competitive Landscape
Channel-controlling players compete with product-specialist players across prescription, specialty retail, and direct-to-consumer vectors. The market structure concentrates around vertically integrated nutrition conglomerates with captive R&D pipelines and veterinary distribution networks. Three archetypes dominate: prescription-grade therapeutic formulators, mass-market wellness brands with palatability-engineered formats, and ingredient-technology suppliers with fermentation-derived bioactive platforms. M&A activity targets probiotic strain portfolios and precision fermentation capacity, while strategic partnerships lock up exclusive veterinary channel access.
Within the prescription-grade tier, Hill's Pet Nutrition and Nutramax Laboratories Veterinary Sciences exemplify therapeutic positioning with veterinary endorsement protocols. Mars, Incorporated anchors mass-market functional nutrition through vertical control over specialty retail distribution. Nestle Purina PetCare occupies a position at the convergence of clinical validation and consumer packaged goods scale.
| Leading Market Players |
|---|
| Wellness Pet Company |
| ADM |
| Mars, Incorporated |
| The J.M. Smucker Company |
| Nutramax Laboratories Veterinary Sciences |
| Nestle Purina PetCare |
| Vetoquinol |
| General Mills |
| Hill's Pet Nutrition |
| Others |
Value Network & Pricing Analysis
The I-5 freight corridor linking California's pet wellness cluster to Pacific Northwest distribution centers imposes fuel surcharge volatility that amplifies price spreads between fermentation-derived bioactive peptides and commodity-grade functional ingredients. This logistics cost dynamic concentrates margin capture among vertically integrated manufacturers with captive cold-chain assets while forcing smaller formulators toward powder formats that bypass refrigerated distribution.
Pricing Analysis
Next-generation precision fermentation platforms command technical premiums over conventional extraction methods, while legacy algal-sourced omega fatty acids face cost compression from marine ecosystem supply constraints. Three-tier pricing structure across veterinary prescription, specialty retail, and mass-market economy levels segments buyers by clinical validation depth. Price differentiation hinges on FDA health claim substantiation tier and strain-specific probiotic validation protocols. Cost-sensitive mass-market buyers in supermarket channels resist premium positioning without visible veterinary endorsement, whereas prescription-grade therapeutic formats sustain inelastic demand through clinic-captive distribution.
Supply Chain Analysis
Export-control scrutiny on biomanufacturing equipment limits precision fermentation capacity expansion outside established North American facilities, constraining bioactive peptide supply growth to Ontario and Quebec production sites plus California contract manufacturers. Raw material flows draw from Canadian fermentation infrastructure, Midwest grain protein inputs, and Pacific Northwest algal cultivation pilots. Single-source vulnerability concentrates in gastric-survival-validated probiotic strains controlled by two dominant suppliers. Distribution runs through veterinary clinic networks for prescription tiers, specialty retail with trained consultation staff for premium segments, and direct-to-consumer subscription platforms for personalized soft chew formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America pet food nutraceuticals market sits in early-cycle expansion as veterinary endorsement of gut-brain axis research accelerates probiotic penetration beyond current specialty retail confines. This adoption tailwind creates asymmetric opportunity for positioned players.
For Market Incumbents: Harden regulatory submission capabilities ahead of pending FDA Center for Veterinary Medicine guidance on hemp-derived cannabinoids, as first-mover substantiation data packages will lock in therapeutic positioning. Deepen backward integration into precision fermentation capacity to secure bioactive peptide supply against Ontario-Quebec production bottlenecks. Channel control through exclusive veterinary clinic access agreements remains the critical defensive lever against direct-to-consumer subscription disintermediation. For New Entrants and Emerging Players: Establish a beachhead in feline-specific functional nutrition, where dog-centric R&D has left mobility and urinary health formulations underserved relative to cat population growth. Target Pacific Northwest specialty retailers with refrigerated probiotic powder sections that bypass ambient supply chain incumbents. A go-to-market angle anchored to raw-feeding adherent communities in urban veterinary nutritionist-dense markets offers the most penetrable entry vector. For Investors and Strategic Acquirers: Pending FDA guidance on hemp-derived cannabinoids reshapes the acquisition landscape by favoring targets with existing veterinary drug approval experience and pre-positioned clinical data packages. Long-term viability over a 5-10 year window rests on proprietary strain portfolios and fermentation infrastructure rather than brand equity alone. The signal to watch is Health Canada PMRA-FDA CVM joint consultation progress, as streamlined North American approval pathways would revalue cross-border ingredient technology suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Ontario and Quebec facilities anchor North American bioactive peptide supply security for U.S. formulators. |
| Veterinary Channel Partnership Lock-up | Exclusive clinic access agreements create captive demand moats against direct-to-consumer subscription erosion. |
| Feline-Specific R&D Pipeline | Underserved cat mobility and urinary health segments offer first-mover margin capture as population growth outpaces formulation supply. |
| Cloud-Based Batch Record Implementation | FDA audit readiness and retailer certification compliance compress from weeks to hours for mid-size manufacturers. |
| Subscription Personalization Platform | Breed-specific metabolic profiling bypasses retail slotting fee structures while capturing recurring revenue velocity. |
Research Methodology
A standing panel of veterinary nutrition PhDs, specialty retail category managers, contract manufacturing executives, and FDA regulatory affairs consultants provided ongoing calibration against market developments. Primary interviews with these stakeholders combined with secondary validation from AAFCO model bill documentation, FDA Center for Veterinary Medicine guidance filings, Health Canada PMRA consultation records, and National Animal Supplement Council quality seal program standards. Bottom-up segmentation sizing and top-down macro constraint checks ensured triangulation integrity across data streams.
Scenario-bracketing around regulatory timeline uncertainty for hemp-derived cannabinoids and precision fermentation capacity buildout rates framed projection boundaries across the analysis window. Segmentation dimensions modeled include product type, species-specific end user, distribution channel control tier, and form factor logistics requirements. CAGRs derived from fitted growth curves incorporating veterinary endorsement velocity, subscription adoption patterns, and state-level AAFCO harmonization progress. Industry-specific inputs encompassed probiotic strain validation timelines and cold-chain infrastructure expansion rates.
Sensitivities concentrate around FDA guidance publication timing for novel ingredients and Health Canada PMRA alignment acceleration. Forecasts reflect assumptions on veterinary channel expansion rates and precision fermentation cost curves. Material shifts in cannabinoid regulatory classification or cross-border ingredient approval reciprocity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Asia-Pacific Pet Clothing Market
Pet Care Products
Japan Pet Food Market
Pet Care Products
Flea, Tick, and Heartworm Products Market
Pet Care Products
Europe Pet Clothing Market
Pet Care Products
Dog Pad Market
Pet Care Products
Europe Dog Food Market
Pet Care Products
Philippines Pet Food Market
Pet Care Products
Gcc Pet Food Market
Pet Care Products
Pet Bathing Supplies Market
Pet Care Products
Pet Selfie Tools Market
Pet Care Products
Netherlands Pet Boarding Market
Pet Care Products
Japan Dog Food Market
Pet Care Products
Dog Litter Boxes Market
Pet Care Products
Germany Pet Food Market
Pet Care Products
Outdoor Dog Bed Market
Pet Care Products
China Pet Training Services Market