
 Retail Bags Market | 2026-2036
Retail Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Bags Market Intelligence
A shift from single-source to multi-source material procurement is repositioning how retail bag manufacturers secure resin and fiber supplies. Amcor plc leverages global polymer sourcing networks to maintain cost discipline across regions. Novolex Holdings Inc. anchors North American production through integrated film extrusion and converting operations. Smurfit Westrock competes with recycled kraft paper capacity scaled for European supermarket private-label contracts.
Retail bags are flexible containers manufactured from polyethylene film, kraft paper, woven textiles, or biopolymer substrates, designed for point-of-sale merchandise transport and brand presentation. Specifications span load-bearing capacity, seal strength, and print resolution for barcode scanning and promotional graphics. Paper bags command premium positioning in fashion boutiques and department stores where tactile branding differentiates unboxing experiences. Biodegradable bags represent the fastest-expanding material category as polylactic acid formulations achieve cost parity with conventional films in grocery retail channels. Plastic bags retain volume dominance in convenience stores and discount formats where unit economics prioritize durability over sustainability signaling.
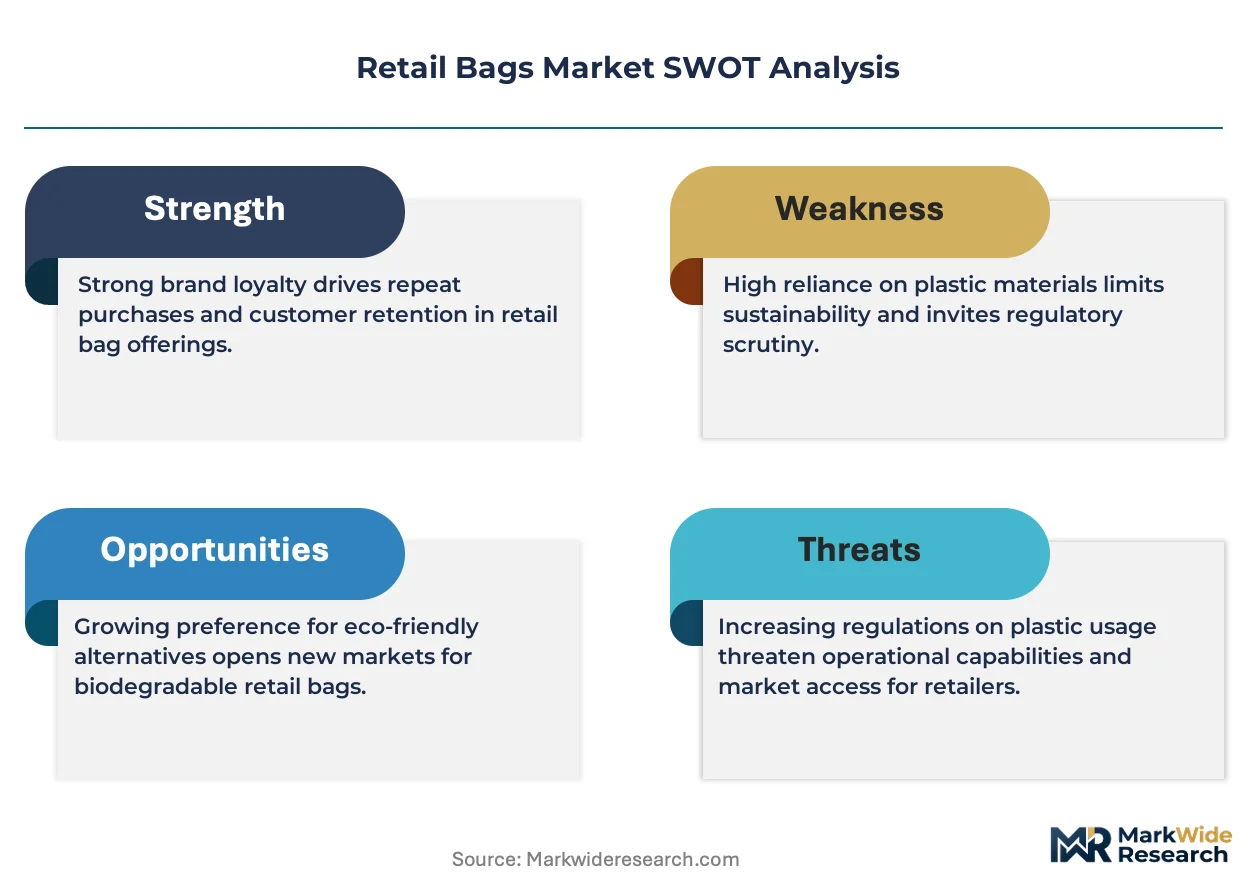
The EU Green Deal and F-Gas Regulation constrain virgin polymer use in member-state retail supply chains, while REACH compliance adds testing burdens for imported textile substrates. The US EPA and state-level bag ban legislation in California and New York fragment regulatory requirements for multinational suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks and material certification standards to anticipate compliance-driven sourcing shifts.
Market Dynamics
Single-use plastic bans across Germany, France, and Italy are forcing grocery retailers to requalify entire bag supply chains around compostable substrates and recycled fiber content, compressing supplier response windows to under eighteen months.
Growth Catalysts
- EU Green Deal Packaging Mandates:Member-state supermarkets must achieve 70% recyclable content by 2030, pulling polylactic acid and kraft paper formulations into high-volume grocery channels previously dominated by polyethylene.
- Biopolymer Cost Parity:Fermentation-scale expansion in corn-starch feedstock processing has collapsed polylactic acid unit costs to within striking distance of virgin LDPE, unlocking price-competitive substitution in discount retail formats.
- German EPR Framework:Extended producer responsibility licensing now covers retail carry bags, creating compliance-driven demand for certified compostable alternatives that carry traceable environmental product declarations.
Market Restraints
- Resin Supply Concentration:European biopolymer production clusters in Belgium and the Netherlands, exposing bag converters to single-source risk when fermentation facilities encounter batch contamination or energy curtailment.
- Paper Fiber Cost Volatility:Recycled kraft pulp pricing fluctuates with Chinese import demand for OCC bales, squeezing margin structures for converters locked into twelve-month supermarket supply contracts.
- REACH Testing Burdens:Textile substrate imports from non-EU suppliers face twelve-to-eighteen-month chemical safety dossier reviews, delaying time-to-market for woven bag lines targeting fashion boutique segments.
Strategic Opportunities
- Italian Fashion Corridor:Milan and Florence luxury houses are specifying unbleached cotton canvas with blockchain-tracked organic certification, opening premium positioning for bag producers that master digital traceability integration.
- Reuse-System Infrastructure:French grocery cooperatives are piloting deposit-return schemes for durable polypropylene totes, creating recurring revenue streams for manufacturers that design modular repairable constructions.
- Digital Printing Convergence:UV-cured inkjet systems married to on-demand converting lines enable lot sizes below five hundred units, collapsing minimum order thresholds for regional supermarket private-label programs.
Industry Challenges
- Composting Certification Timelines:EN 13432 and OK Compost HOME approvals require six-to-nine-month laboratory degradation testing, blocking seasonal promotional bag launches unless development cycles start eighteen months ahead.
- Legacy Heat-Sealing Retrofit:Converters operating solvent-based adhesive lines face seven-figure capital outlays to install ultrasonic welding stations capable of processing biopolymer films without thermal degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Bags Market |
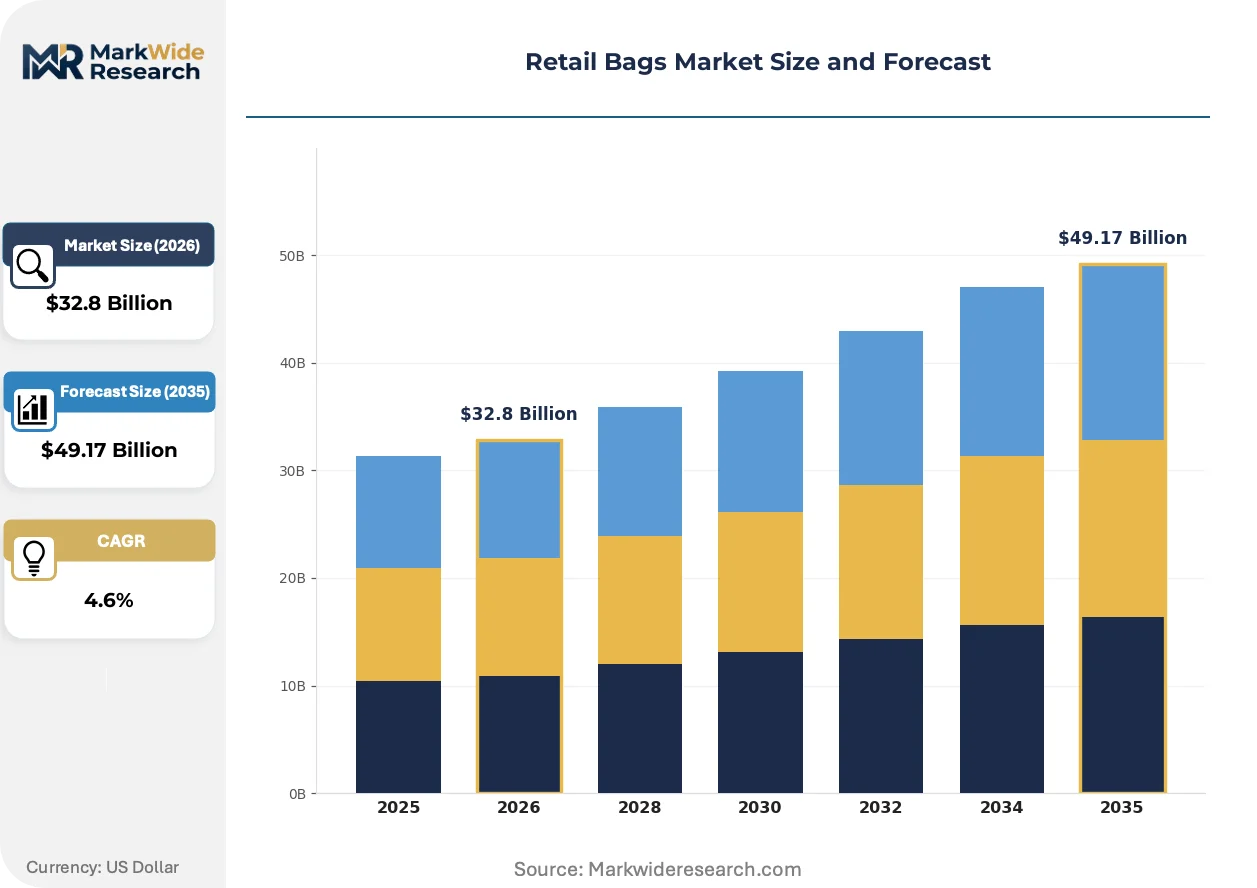
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $49.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Bags, Paper Bags, Cloth Bags, Biodegradable Bags, Jute Bags Material: Polyethylene, Kraft Paper, Non-Woven Fabric, Cotton, Polylactic Acid Distribution Channel: Supermarkets, Specialty Stores, Online Retailers, Convenience Stores, Department Stores End User: Fashion Boutiques, Grocery Retailers, Electronics Shops, Gift Shops, Pharmacies |
| Companies Covered | Amcor plc, Advance Polybag Inc., Smurfit Westrock, Coveris Holdings SA, Wisconsin Converting Inc., Mondi Group plc, Novolex Holdings Inc., ProAmpac LLC, International Paper Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Bags Market Strategic Shifts & Innovations
Material science advances and regulatory compliance automation are compressing product development cycles while fragmenting procurement authority across sustainability, operations, and merchandising functions within retail buying organizations.
Ultrasonic welding systems are automating the transition from solvent-adhesive bag construction to thermal bonding methods compatible with temperature-sensitive biopolymer films. German discount chains are retrofitting supplier qualification programs to prioritize converters with installed ultrasonic capacity. This equipment shift is automating quality consistency while eliminating volatile organic compound emissions that previously triggered workplace safety inspections.
REACH Annex XVII restrictions on perfluorinated compounds are eliminating oil-and-grease-resistant coatings from food-contact paper bags across EU member states. Converters must reformulate barrier layers using bio-wax or clay-mineral alternatives that sacrifice some moisture resistance. Bakery and prepared-food retail segments in France and Belgium are absorbing higher unit costs to maintain regulatory compliance without switching to plastic alternatives.
Supermarket sustainability officers now hold veto authority over bag procurement decisions previously owned by purchasing managers focused on unit economics. This organizational shift is elevating lifecycle assessment documentation and carbon footprint certifications above price-per-thousand metrics in supplier scorecards. German and Dutch grocery banners are piloting this governance change before broader European rollout.
Retail Bags Market Segmentation
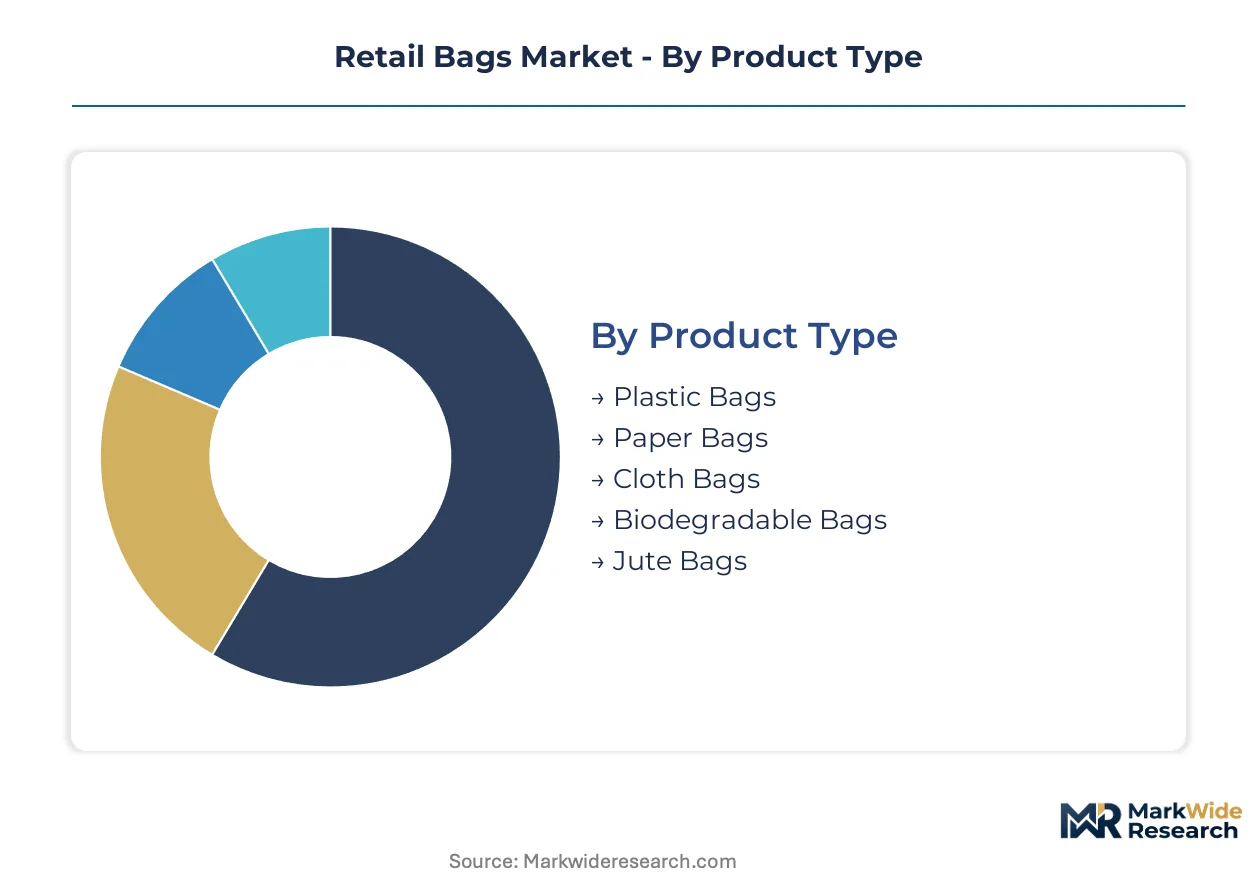
Retail bag procurement fractures across incompatible performance requirements, forcing converters to maintain parallel production lines for load-bearing grocery formats and tactile fashion presentations. Material selection, distribution channel, and end-use specifications rarely overlap cleanly, amplifying SKU complexity for suppliers serving diversified retail portfolios.
Product Type:
Customization intensity spans from commodity polyethylene units to bespoke canvas constructions with embroidered brand identifiers.
- Plastic Bags:LDPE and HDPE formulations dominate convenience store and discount grocery channels where unit cost and tear resistance outweigh sustainability positioning. German discount chains still move substantial volumes despite EU Green Deal phase-down timelines, though private-label programs now mandate recycled content thresholds.
- Biodegradable Bags:Polylactic acid and starch-blend substrates are displacing conventional films in French and Italian supermarket produce sections where composting infrastructure supports end-of-life claims. EN 13432 certification requirements extend development cycles but unlock access to EPR-compliant supply chains.
- Paper Bags:Recycled kraft constructions with twisted paper handles serve bakery and prepared-food retail in Belgium and the Netherlands where grease-resistant barriers face REACH reformulation pressures.
- Cloth Bags:Woven polypropylene and cotton canvas formats support reuse-system pilots in French grocery cooperatives, with durability specifications targeting fifty-plus use cycles.
- Jute Bags:Hessian substrates carry organic certification appeal in German natural-food retail channels, though moisture sensitivity limits application to dry goods categories.
Most installed capacity flows through Plastic Bags. Expansion is steepest in Biodegradable Bags.
Material:
Feedstock sourcing geography determines landed cost structures more than conversion technology for bag manufacturers.
- Polyethylene:Virgin and post-consumer recycled resin grades anchor high-volume grocery supply contracts, with rLDPE pricing indexed to European collection infrastructure yields. Belgian compounders supply major German supermarket banners under twelve-month rolling agreements.
- Polylactic Acid:Corn-starch fermentation output from Netherlands-based biorefineries has achieved cost convergence with virgin LDPE in tonnage terms, accelerating adoption in discount formats previously price-prohibited for biopolymers.
- Kraft Paper:Recycled pulp availability fluctuates with Chinese OCC import policies, squeezing margin predictability for converters locked into fixed-price department store contracts.
- Non-Woven Fabric:Spunbond polypropylene serves reusable tote specifications in French deposit-return schemes, with gsm weights calibrated to automated washing system compatibility.
- Cotton:Organic certification and blockchain traceability integration command premium positioning in Milan and Florence fashion corridors, where unbleached canvas differentiates luxury unboxing rituals.
Polyethylene retains the largest production footprint. Polylactic Acid is climbing the fastest.
Distribution Channel:
Channel-specific packaging specifications create divergent margin profiles, from high-volume supermarket tenders to low-MOQ specialty store programs.
- Supermarkets:Centralized procurement functions at German and French grocery banners now require lifecycle assessment documentation and carbon footprint certifications alongside unit pricing, elevating sustainability officers to veto authority over bag selection decisions.
- Online Retailers:E-commerce fulfillment demands shift toward lightweight polymailer alternatives, though corrugated-boxed apparel shipments still specify tissue-lined paper bags for brand presentation within unboxing experiences.
- Specialty Stores:Fashion boutiques in Italian urban centers specify sub-five-hundred-unit production runs with UV-cured inkjet personalization, collapsing traditional minimum order thresholds.
- Convenience Stores:High-velocity polyethylene carryout formats prioritize durability and cost efficiency over material innovation, with regulatory compliance limited to state-level bag ban adherence.
- Department Stores:Multi-department retailers balance premium paper bag positioning in cosmetics and accessories against commodity plastic deployment in housewares and electronics, complicating supplier consolidation efforts.
Supermarkets absorb the majority of converter output. Online Retailers are gaining share fastest.
End User:
End-use differentiation separates commodity supply relationships from value-added partnerships requiring co-development capabilities.
- Grocery Retailers:Produce, bakery, and checkout-counter applications each demand distinct barrier properties and handle constructions, with German EPR frameworks now mandating certified compostable alternatives carrying traceable environmental product declarations.
- Fashion Boutiques:Tactile branding requirements prioritize unbleached cotton canvas and embossed kraft paper with ribbon handles, where procurement decisions emphasize supplier digital traceability integration over unit economics.
- Pharmacies:Discrete packaging specifications favor opaque paper constructions with tamper-evident closures, regulated under national pharmaceutical packaging standards rather than general retail bag directives.
- Electronics Shops:Anti-static inner linings and die-cut foam inserts differentiate electronics retail bags from standard merchandise formats, with volume concentration in urban flagship locations.
- Gift Shops:Seasonal demand spikes and promotional calendar alignment require converters with on-demand converting lines capable of sub-two-week turnaround on custom graphic treatments.
Grocery Retailers command the deepest supplier relationships. Fashion Boutiques are expanding specification complexity most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr industrial corridor anchors European retail bag manufacturing capacity, with converter clusters concentrated around Düsseldorf and Cologne serving major supermarket banners. Regulatory pressure from Brussels and national capitals is fragmenting supply chain requirements across member states. Material transitions toward compostable substrates are compressing supplier qualification timelines.
Germany
EPR licensing under the German Packaging Act now mandates certified compostable alternatives for retail carry bags, pulling polylactic acid formulations into discount grocery channels. The Federal Environment Agency enforces traceable environmental product declarations through the ZSVR registry. Converter operations cluster in North Rhine-Westphalia, where ultrasonic welding retrofit investments are accelerating to meet biopolymer processing requirements.
France
French grocery cooperatives are piloting deposit-return schemes for durable polypropylene totes, creating recurring revenue opportunities for modular bag designs. ANSM oversees food-contact compliance for bakery and prepared-food retail formats. Industrial capacity concentrates in the Hauts-de-France region, where REACH Annex XVII reformulation pressures are eliminating perfluorinated barrier coatings from paper bag constructions.
Italy
Milan and Florence luxury houses are specifying unbleached cotton canvas with blockchain-tracked organic certification, elevating digital traceability integration above unit economics in supplier selection. The Ministry of Ecological Transition aligns national implementation with EU Green Deal packaging mandates. Converter specialization in the Veneto and Lombardy regions supports sub-five-hundred-unit production runs for fashion boutique private-label programs.
United States
State-level bag ban legislation in California and New York fragments regulatory requirements for multinational suppliers, while the EPA maintains baseline chemical safety standards. Convenience store channels retain polyethylene volume dominance where unit economics prioritize durability. Converting operations concentrate in the Midwest and Southeast, with integrated film extrusion capacity serving discount retail formats.
Netherlands
Corn-starch fermentation output from Netherlands-based biorefineries has achieved cost convergence with virgin LDPE, accelerating biopolymer adoption across Benelux supermarket banners. The National Institute for Public Health and the Environment coordinates REACH compliance enforcement for imported textile substrates. Rotterdam-Antwerp port logistics support resin supply concentration that exposes converters to single-source risk during facility curtailments.
Retail Bags Market Key Industry Players
Global majors compete with regional champions across material technology and sustainability certification dimensions, producing a tiered structure where scale-driven polymer processors coexist with specialty fiber converters. Market concentration remains moderate, with top-tier players commanding supermarket private-label contracts while mid-cap specialists capture fashion and boutique segments. Three archetypes dominate: integrated resin-to-bag converters, recycled fiber specialists, and biopolymer technology licensors. Capacity expansion and M&A activity represent the dominant competitive moves, with ultrasonic welding retrofit investments and composting certification capabilities serving as differentiation vectors.
Among North American integrated converters, Novolex Holdings Inc. and Wisconsin Converting Inc. exemplify the scale-driven archetype through captive film extrusion and converting operations. European recycled fiber leadership clusters around Mondi Group plc, which anchors kraft paper capacity scaled for supermarket private-label contracts. Amcor plc represents the global polymer sourcing archetype, leveraging multinational resin networks to maintain cost discipline across regional markets. These three companies illustrate the strategic segmentation between virgin polymer scale, recycled fiber specialization, and global supply chain integration.
| Leading Market Players |
|---|
| Amcor plc |
| Advance Polybag Inc. |
| Smurfit Westrock |
| Coveris Holdings SA |
| Wisconsin Converting Inc. |
| Mondi Group plc |
| Novolex Holdings Inc. |
| ProAmpac LLC |
| International Paper Company |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between EN 13432-compliant biopolymer bags and commodity polyethylene units manifests divergent margin structures across European retail procurement. Premium compostable formats command four-to-six-month development cycles and pass through fermentation-scale input volatility, while discount grocery channels anchor pricing to recycled resin spot markets indexed to Belgian compounder output.
Pricing Analysis
Input-cost pass-through from corn-starch fermentation output and recycled kraft pulp fluctuations governs converter margin stability across material tiers. Three-tier pricing structure across premium compostable, standard recycled-content, and economy virgin-polyethylene levels separates sustainability-certified supermarket contracts from convenience store spot purchases. Pricing pressure stems from Chinese OCC import demand squeezing fixed-price department store agreements. Discount grocery banners exhibit highest price sensitivity; Milan fashion houses prioritize blockchain traceability premiums over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Netherlands-based biorefinery concentration for polylactic acid feedstock and Belgian compounder clusters for recycled polyethylene resin. Raw material dependencies center on corn-starch fermentation output, European OCC bale collection yields, and imported cotton fiber from South Asian organic certification programs. Supply chain risk concentrates in energy-curtailment exposure at fermentation facilities. Distribution runs through Rotterdam-Antwerp port logistics serving German supermarket banners and French grocery cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU Green Deal packaging mandates pull material transitions ahead of cost curves, with 70% recyclable content thresholds redefining supplier qualification windows.
For Market Incumbents: Deepen ultrasonic welding retrofit investments across North Rhine-Westphalia converter clusters to secure biopolymer processing capacity ahead of German EPR enforcement waves. Anchor backward integration into Netherlands fermentation supply through long-term offtake structures that insulate against batch contamination risks. Prioritize EN 13432 certification pipelines to defend supermarket private-label positioning against emerging fiber specialists.
For New Entrants and Emerging Players: EU Green Deal mandates in France and Italy open a window for modular polypropylene tote designs targeting deposit-return scheme pilots in grocery cooperatives. White-space concentrates in sub-five-hundred-unit digital printing runs for Italian fashion boutique segments where legacy converters lack UV-cured inkjet flexibility. Go-to-market leverage rests on blockchain traceability integration for unbleached cotton canvas specifications.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-cap converters lack capital depth for composting certification timelines and ultrasonic equipment retrofits simultaneously. Long-term viability favors targets with installed biopolymer processing capacity and ZSVR registry compliance documentation. Watch German discount chain supplier qualification program announcements as inflection signals for accelerated material transition velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Ultrasonic Welding Retrofit | Enables biopolymer film processing without thermal degradation for EPR-compliant formats. |
| Blockchain Traceability Integration | Unlocks premium positioning in Milan and Florence luxury fashion supply chains. |
| Composting Certification Pipeline | Secures EN 13432 and OK Compost HOME approvals for German supermarket access. |
| Deposit-Return Scheme Partnership | Creates recurring revenue streams through French grocery cooperative pilot programs. |
| Digital Printing Convergence | Collapses minimum order thresholds below five hundred units for specialty store segments. |
Research Approach
Coverage spans Germany, France, Italy, the Netherlands, and the United States, with primary inputs from each market cluster through interviews with supermarket sustainability officers, converter plant managers, biopolymer procurement leads, and fashion boutique supply chain directors. Secondary validation draws from EU Packaging and Packaging Waste Directive implementation reports, ZSVR registry disclosures, REACH Annex XVII restriction updates, and customs data on OCC bale trade flows. Bottom-up volume estimates triangulate against top-down regulatory mandate timelines.
Rate-of-change decomposition separates volume shifts by material substrate from value migration across premium and economy tiers. Segmentation dimensions span product type, material feedstock, distribution channel, and end-use application, with regional regulatory cluster as an overlay. CAGRs derive from modeled substitution curves between polyethylene and polylactic acid in grocery channels, calibrated against biorefinery capacity expansion announcements and EPR licensing rollout schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under fermentation facility curtailment scenarios or abrupt Chinese OCC import policy shifts. Forecasts reflect assumptions on EU member-state implementation timelines and biopolymer cost convergence trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Packaging
Floor POP Display Market
Retail Packaging
Retail Ready Packaging (RRP) Market
Retail Packaging
Black Friday Packaging Market
Retail Packaging
Table Tent Market
Retail Packaging
Club Store Packaging Market
Retail Packaging
Global Shoe Packaging Market
Retail Packaging
Retail E Commerce Packaging Market
Retail Packaging
Free Standing Display Units Market
Retail Packaging
Retail Ready Trays Market