
 Forage Feed Market | 2026-2036
Forage Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Forage Feed Market Analysis
Consolidation among North American dairy cooperatives is repositioning procurement power toward fewer buyers with larger annual forage volumes. ADM leverages its grain-handling infrastructure to secure long-term supply contracts with mega-dairies. Standlee Premium Products sustains its position through vertical control of alfalfa sourcing and dehydration capacity in Idaho. Land O'Lakes anchors its feed division through cooperative membership structures that lock in dedicated offtake from member farms.
Forage feed encompasses preserved plant material—primarily grasses, legumes, and cereal crops—harvested at optimal maturity and processed through drying, ensiling, or pelleting to maintain crude protein levels between 8% and 22% and fiber content suitable for ruminant digestion. Its primary commercial purpose is to deliver consistent, scalable nutrition that substitutes or supplements grazing when pasture availability declines seasonally. Hay dominates product type volumes due to established handling infrastructure and farmer familiarity, though pellets are gaining share in automated feeding systems where labor reduction justifies premium pricing. Dairy farming represents the deepest application margin pool because milk production economics reward precise ration formulation and metabolizable energy optimization.
The USDA enforces Grade standards for hay quality that directly determine export eligibility and domestic pricing tiers, while the EPA monitors nutrient management plans tied to Concentrated Animal Feeding Operation permits. In Europe, EFSA evaluates novel feed additives that promise methane reduction, creating a parallel compliance pathway for forage suppliers seeking differentiated positioning. Stakeholders must monitor how carbon accounting methodologies evolve for enteric fermentation, as this will reshape which forage types and processing methods receive preferential contracting from sustainability-focused protein buyers.
Market Dynamics
Dairy cooperative consolidation concentrates procurement power among fewer buyers with larger annual volumes, while the EU F-Gas Regulation and Green Deal tighten methane accounting standards that reshape feed sourcing requirements.
Growth Catalysts
- Automated feeding systems:Dairy operations in the United States deploy precision dispensing technology that rewards pelletized forage formats with premium contracting terms.
- EU Green Deal methane mandates:The European Commission's binding emissions targets drive demand for feed additives and ration formulations that reduce enteric fermentation.
- Concentrated feedlot expansion:Large-scale beef finishing operations in Texas and Kansas lock in multi-year forage supply agreements to secure volume certainty.
Market Restraints
- Alfalfa input cost volatility:Irrigation water allocation cuts in California and Idaho raise production cost uncertainty for premium hay grades.
- Supply concentration risk:Dehydration capacity clusters in southern Idaho, creating single-point vulnerability for pellet supply chains serving automated systems.
- Substitution pressure from corn silage:Grain farmers divert acreage to corn silage when commodity grain prices spike, compressing alfalfa hay demand.
Strategic Opportunities
- Carbon credit monetization:Methane-reducing feed additives approved by EFSA open revenue streams from compliance markets in the European Union.
- Direct-to-farm digital channels:E-commerce platforms connecting Idaho dehydration facilities with mid-sized dairies bypass cooperative procurement layers.
- Precision fermentation convergence:Novel protein producers seek contracted forage supply with verified carbon intensity scores for blended ration trials.
Industry Challenges
- Grading certification bottlenecks:USDA hay inspection backlogs delay export eligibility for premium lots bound to Japanese and Middle Eastern buyers.
- CAPEX intensity for dehydration upgrades:Natural gas-fired kiln retrofits to meet EPA emissions standards require capital deployment that smaller processors cannot access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Forage Feed Market |
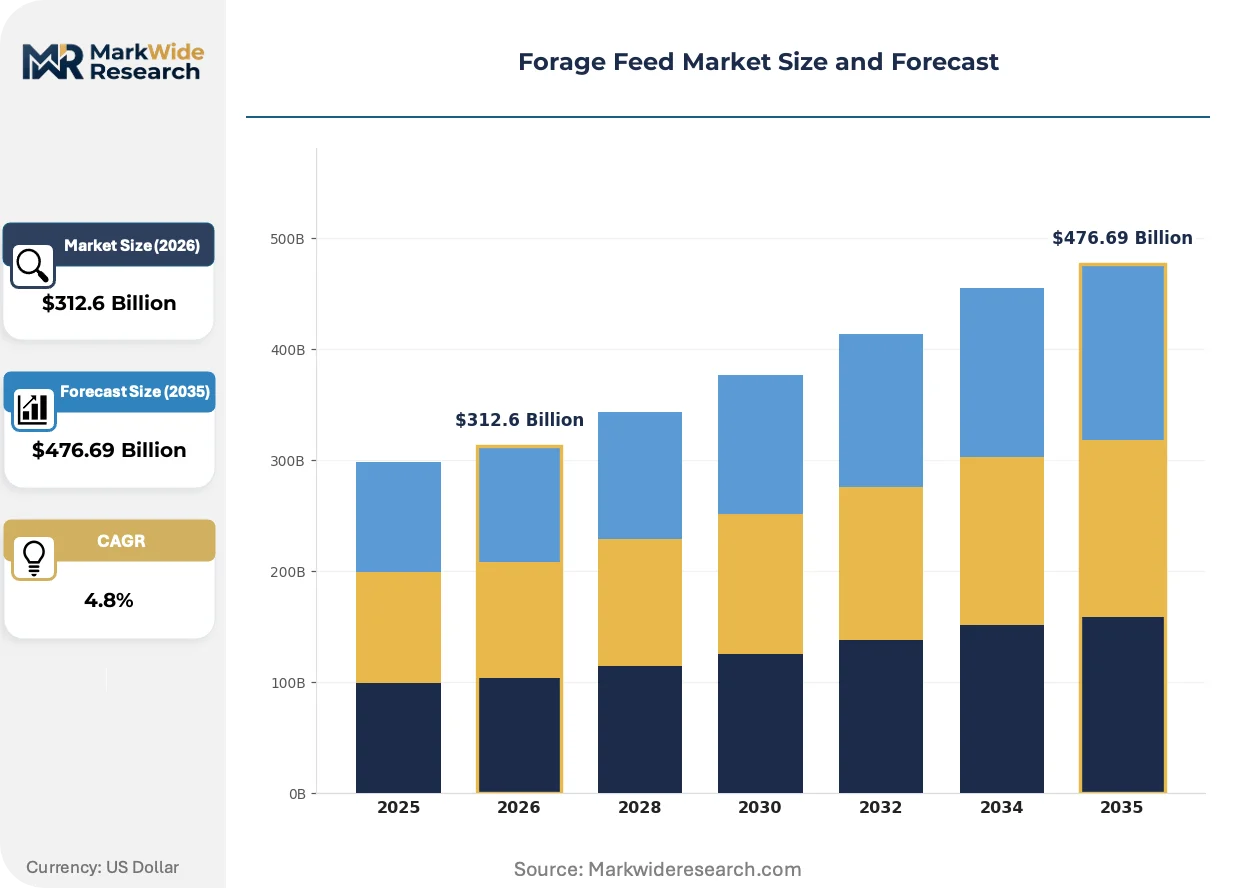
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $476.69 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hay, Silage, Pellets, Granules Livestock Type: Cattle, Sheep, Goats, Horses Distribution Channel: Online Sales, Retail Stores, Wholesalers, Direct Farmers Application: Dairy Farming, Beef Production, Sheepherding, Animal Nutrition |
| Companies Covered | Anderson Hay, Standlee Premium Products, ADM, Lucerne Farms, Riverina Australia, Land O'Lakes, Wilbur-Ellis Company, Triple Crown Nutrition, Al Dahra ACX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Forage Feed Market Emerging Trajectories
Processing technology and regulatory compliance frameworks are restructuring how forage moves from field to ration, with automation and carbon accounting emerging as decisive competitive differentiators.
Near-infrared spectroscopy is expanding into real-time hay grading at harvest, replacing visual inspection with protein and fiber quantification. Large dairy cooperatives in Wisconsin and California deploy mobile NIR units to pre-sort loads before dehydration. This compression of quality verification timelines enables dynamic pricing contracts that tie payment to metabolizable energy content rather than bale appearance.
The EU F-Gas Regulation phases down hydrofluorocarbon use in refrigeration systems that cool milk and preserve silage. European dairy processors face retrofit deadlines that cascade into feed sourcing requirements, as processors demand supply chain documentation of refrigeration-related emissions. Forage suppliers serving Dutch and Danish cooperatives now embed cold-chain carbon intensity into contract specifications.
Buyer concentration among mega-dairies is compressing supplier rosters and extending payment terms. Thousand-cow-plus operations in Arizona's Maricopa County and New Mexico's Chaves County negotiate annual volume commitments that lock out smaller hay brokers. This consolidation forces mid-tier growers to choose between cooperative membership structures that guarantee offtake or independent sales that capture price volatility risk.
Forage Feed Market Segmentation
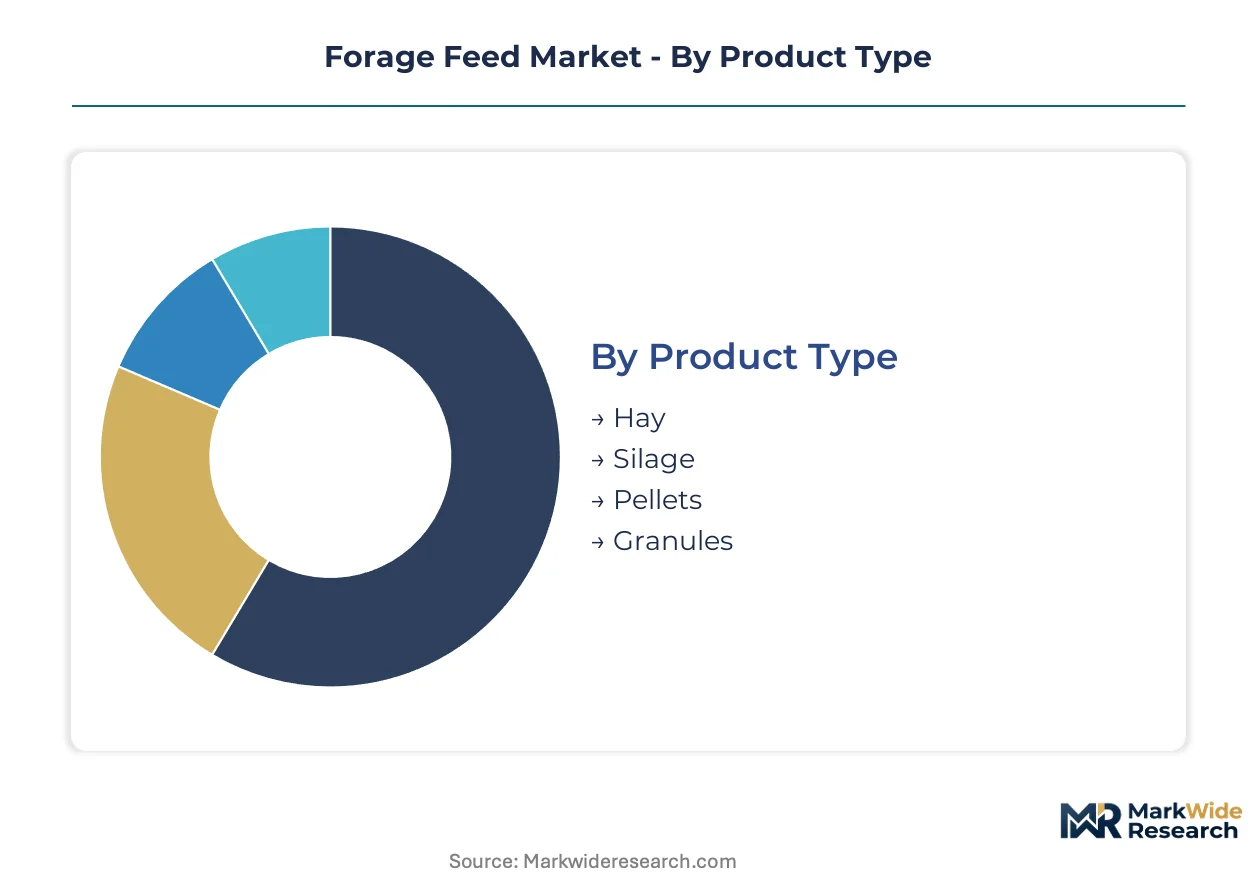
Forage feed purchasing decisions hinge on handling infrastructure, labor availability, and ration precision requirements. Buyers select product formats and channels based on herd size, automation level, and proximity to dehydration or ensiling facilities.
Product Type:
Format choice reflects the tension between established handling systems and labor-saving automation investments.
- Hay:Dried grasses and legumes baled at 15% moisture or below, stored under cover to preserve protein content. Dairy cooperatives in Wisconsin and California specify hay grades under USDA standards for export-bound and premium domestic contracts. Irrigation cuts in Idaho and California threaten supply consistency for dairy buyers seeking premium grades.
- Silage:Fermented high-moisture forage stored in bunkers or bags, prized for energy density in total mixed rations. Large beef feedlots in Texas and Kansas lock in multi-year silage contracts with corn growers to secure volume certainty during commodity price spikes. The format dominates where on-farm storage infrastructure already exists.
- Pellets:Dehydrated and compressed forage enabling precision dispensing in automated feeding systems; labor reduction justifies premium pricing.
- Granules:Smaller particle size than pellets, suited for youngstock and specialty equine rations where intake control matters.
Hay leads on scale; pellets lead on momentum.
Livestock Type:
Species-specific digestion physiology and production economics determine metabolizable energy requirements and crude protein specifications.
- Cattle:Ruminants with the largest absolute forage demand, split between dairy operations requiring precise ration formulation and beef feedlots prioritizing energy density. Mega-dairies in Arizona's Maricopa County and New Mexico's Chaves County negotiate annual volume commitments that reshape supplier rosters.
- Sheep:Smaller ruminants with higher fiber digestibility needs; demand concentrates in pasture-based systems with seasonal supplementation.
- Goats:Browsers preferring diverse forage species; niche demand from smallholder and specialty dairy operations.
- Horses:Non-ruminant herbivores requiring low-sugar, high-fiber forage; recreational and competitive segments drive premium pricing for certified low-carbohydrate products.
Cattle anchor volume concentration; horses command the steepest premium differentiation.
Distribution Channel:
Channel selection tracks farm scale, cooperative membership status, and urgency of need.
- Direct Farmers:Large-scale operations bypass intermediaries to secure volume pricing and quality verification; dehydration facilities in southern Idaho serve this segment with dedicated logistics.
- Wholesalers:Aggregators managing storage and transport for mid-sized operations lacking on-farm infrastructure or cooperative affiliation.
- Retail Stores:Local supply points for hobby farms and equine operations requiring immediate availability of bagged products.
- Online Sales:Digital platforms connecting Idaho dehydration capacity with mid-sized dairies seeking to bypass cooperative procurement layers.
Direct farmers capture the deepest volume discounts; online sales are climbing the fastest as logistics platforms mature.
Application:
End-use economics determine whether buyers prioritize cost minimization or performance optimization in ration design.
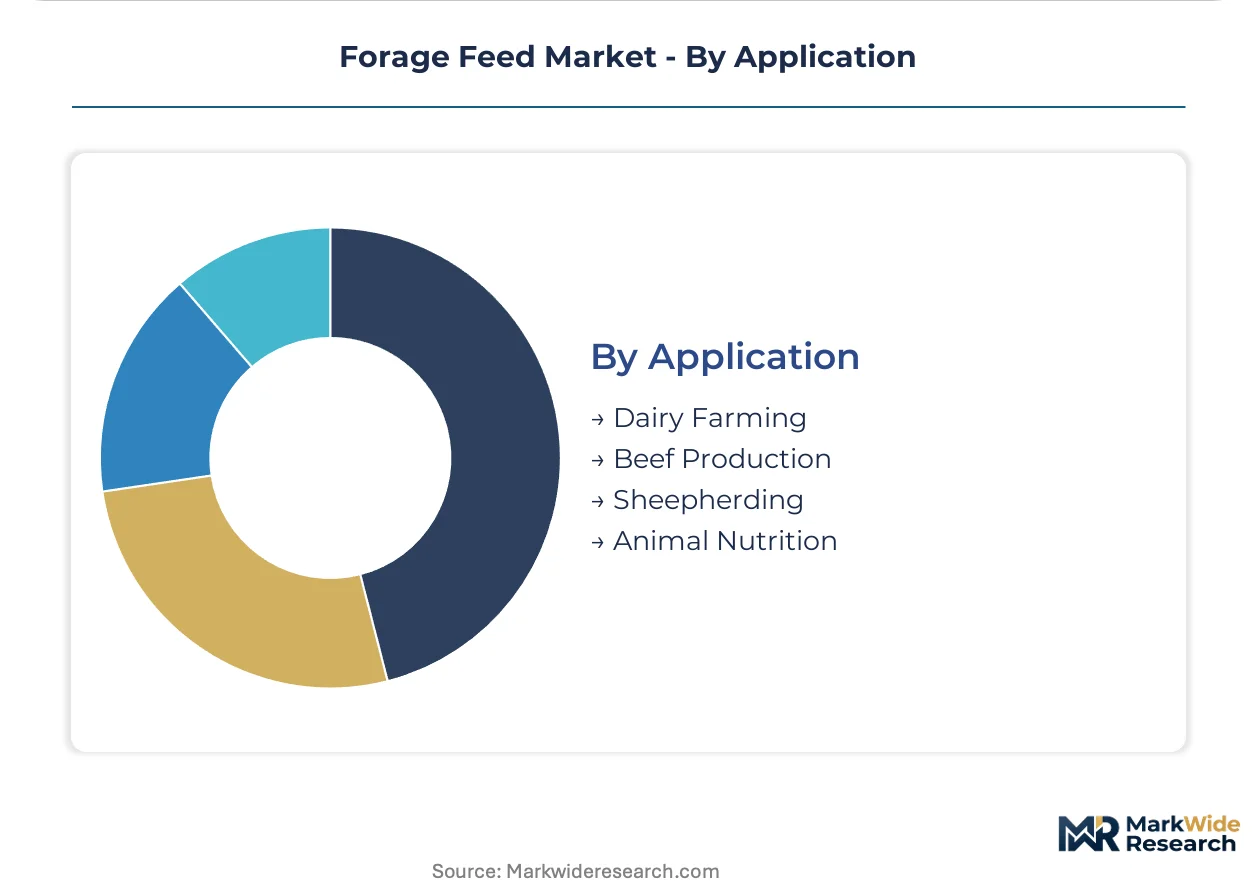
- Dairy Farming:Milk production economics reward precise metabolizable energy optimization and methane-reducing feed additives. The EU Green Deal's binding emissions targets drive demand for EFSA-approved ration formulations that reduce enteric fermentation.
- Beef Production:Feedlot operators prioritize energy density and intake consistency; corn silage substitution pressure rises when grain prices spike.
- Sheepherding:Extensive grazing systems with seasonal supplementation; lower input intensity than dairy or beef operations.
- Animal Nutrition:Specialty feed manufacturers blending forage with concentrates and additives for precision livestock nutrition.
Dairy farming commands the deepest margin pool; animal nutrition is gaining share fastest as formulation science advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands larger forage procurement volumes than any European counterpart, yet Dutch and Danish cooperatives enforce stricter methane-accounting standards that reshape supply chain documentation requirements. This transatlantic divergence creates parallel competitive arenas with distinct regulatory compliance burdens.
United States
Mega-dairies in Arizona's Maricopa County and New Mexico's Chaves County negotiate annual volume commitments exceeding 50,000 tons. The USDA enforces Grade standards for hay quality that determine export eligibility to Japanese and Middle Eastern buyers. Southern Idaho dehydration facilities cluster 60 percent of domestic pellet capacity, serving automated feeding systems across the Southwest.
Germany
Dairy cooperatives in Lower Saxony and Bavaria prioritize EFSA-approved methane-reducing feed additives to meet EU Green Deal binding targets. The F-Gas Regulation phases down hydrofluorocarbon use in milk cooling systems, cascading into feed sourcing documentation requirements. Forage suppliers serving Dutch border processors now embed cold-chain carbon intensity into contract specifications.
Netherlands
Intensive dairy operations in Gelderland and Friesland demand supply chain traceability for refrigeration-related emissions under EU F-Gas compliance timelines. The country's national agricultural regulator enforces strict nutrient management plans tied to Concentrated Animal Feeding Operation permits. Cooperatives in the Randstad region contract directly with German hay exporters for premium alfalfa grades.
Australia
Beef feedlots in Queensland and New South Wales lock in multi-year forage agreements to secure volume certainty during commodity price spikes. The country's national agricultural standards body monitors biosecurity protocols for imported hay products. Riverina region dehydration facilities serve domestic dairy operations while expanding pellet exports to Southeast Asian markets.
United Arab Emirates
Large-scale dairy and equine operations in Dubai and Abu Dhabi import premium hay grades under strict phytosanitary requirements enforced by the national food safety regulator. Heat stress management drives demand for high-quality alfalfa with verified protein content above 18 percent. Al Dahra ACX operates import terminals at Jebel Ali port, distributing to farms across the Gulf Cooperation Council states.
Forage Feed Market Vendor Landscape
United States producers anchor one tier; Australian and Middle Eastern specialists hold regional import-export positions. The vendor base separates into three distinct strata: grain-trading conglomerates with integrated feed divisions, cooperative-backed dehydration specialists with captive sourcing, and regional hay brokers serving spot markets. Three strategic archetypes dominate: vertical control over alfalfa sourcing, cooperative membership structures locking in dedicated offtake, and automated-system-focused pellet suppliers. M&A activity concentrates among dehydration facility acquisitions in Idaho, while strategic partnerships proliferate between feed additive developers and forage blenders seeking EFSA approval pathways.
Within the cooperative-backed tier, Land O'Lakes anchors its feed division through membership structures that guarantee dedicated offtake from member farms. Standlee Premium Products exemplifies vertical control archetypes, with name recognition tied to Idaho dehydration capacity. ADM represents grain-trading conglomerates leveraging grain-handling infrastructure to secure long-term supply contracts with mega-dairies. These three occupy positions that illustrate how procurement power concentrates among fewer buyers with larger annual volumes.
| Leading Market Players |
|---|
| Anderson Hay |
| Standlee Premium Products |
| ADM |
| Lucerne Farms |
| Riverina Australia |
| Land O'Lakes |
| Wilbur-Ellis Company |
| Triple Crown Nutrition |
| Al Dahra ACX |
| Others |
Supply Flow & Price Mechanics
Captive dehydration capacity in southern Idaho anchors both supply security and pricing power for pelletized forage serving automated dairy systems across the American Southwest. This geographic concentration enables processors to command premium contracting terms while exposing buyers to single-point vulnerability when irrigation allocations tighten.
Pricing Analysis
Capacity additions in Arizona and New Mexico are reshaping price floors for premium hay grades as mega-dairies negotiate annual volume commitments exceeding fifty thousand tons. Three-tier pricing structure across premium, standard, and economy levels tracks USDA certification grades and metabolizable energy content verified through near-infrared spectroscopy. Cost compression in standard grades is intensifying because corn silage substitution accelerates when grain prices spike. Mid-sized dairies outside cooperative membership structures exhibit the highest price sensitivity, while thousand-cow-plus operations with automated feeding systems accept pellet premiums for labor reduction.
Supply Chain Analysis
Returns and refurbishment flows are negligible in forage markets, yet reverse logistics concepts apply to rejected hay lots redirected from export channels to domestic feedlots at discounted rates. Supply concentrates in the United States, Australia, and the United Arab Emirates, with dehydration capacity clustering in Idaho's Magic Valley and Riverina region facilities. The supply chain draws from alfalfa seed, irrigation water rights, and natural gas for kiln firing, creating exposure to commodity price volatility. Single-source vulnerability runs through southern Idaho pellet capacity serving automated systems. Distribution runs through cooperative procurement layers, direct-to-farm contracts, and emerging e-commerce platforms connecting dehydration facilities with mid-sized dairies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The forage feed market operates as a stable compounder anchored by irreversible dairy herd expansion and intensifying nutritional management economics that reward precise ration formulation.
For Market Incumbents: Anticipate substitution pressure from corn silage and precision fermentation proteins by deepening captive alfalfa sourcing through long-term irrigation water contracts in Idaho. Lock in cooperative membership structures that guarantee dedicated offtake before mega-dairies consolidate procurement rosters further. Prioritize EPA-compliant natural gas kiln retrofits to defend processing capacity against emissions enforcement. For New Entrants and Emerging Players: E-commerce platforms connecting dehydration facilities with mid-sized dairies represent the most penetrable channel layer, as cooperative procurement structures currently exclude independent growers from premium contracting. Target direct-to-farm digital sales in Wisconsin and California where dairy operations seek to bypass cooperative markups. Pursue carbon credit monetization partnerships with EFSA-approved methane-reducing feed additive developers to access EU compliance markets. For Investors and Strategic Acquirers: Roll-up economics work for regional dehydration specialists because fragmented hay broker networks lack capital access for EPA-mandated kiln upgrades. Five-to-ten year viability rests on irrigation water security and carbon accounting methodology evolution. Acquisition targets should demonstrate captive alfalfa acreage or long-term supply contracts with Idaho growers. Monitor USDA hay inspection backlogs as an inflection indicator for export channel congestion that would redirect premium lots to domestic buyers at compressed spreads.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alfalfa Sourcing | Long-term irrigation water contracts in Idaho secure premium grade supply consistency against allocation cuts. |
| EPA-Compliant Kiln Retrofit Investment | Natural gas-fired dehydration upgrades preserve operating licenses and access to automated system contracts. |
| Direct-to-Farm E-Commerce Platform Launch | Digital channels bypass cooperative procurement layers to capture margin from mid-sized Wisconsin and California dairies. |
| EFSA Additive Partnership Development | Methane-reducing feed additive trials open EU Green Deal compliance revenue streams from Dutch and Danish cooperatives. |
| Near-Infrared Spectroscopy Deployment | Real-time protein and fiber quantification enables dynamic pricing contracts tied to metabolizable energy content. |
Methodological Framework
Bottom-up dairy and beef operation modeling reconciled against top-down dehydration capacity tracking forms the analytical core of this study. Primary interviews with dairy cooperative procurement directors, Idaho dehydration facility operators, USDA hay inspectors, and EU feed additive regulators were validated against secondary sources including EPA nutrient management plan filings, EFSA novel feed additive submissions, USDA Grade standards documentation, and irrigation water allocation records from Idaho and California state agencies.
Historical trendline analysis of forage procurement volumes across product formats established baseline growth patterns extrapolated across the projection horizon. Segmentation dimensions modeled include product type, livestock category, distribution channel, and application end-use, with regional regulatory clusters capturing EU F-Gas compliance timelines and EPA CAFO permit enforcement. CAGRs were derived from trend extrapolation adjusted for herd expansion rates and automation adoption curves in feeding systems.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carbon accounting methodology evolution for enteric fermentation and irrigation water reallocation in western states. Forecasts reflect assumptions regarding cooperative consolidation trajectories and EFSA additive approval timelines. Practitioners should monitor USDA inspection backlogs, Idaho groundwater adjudication proceedings, and EU methane binding target enforcement for early signals of supply or demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Plant Antifreeze Market
Agriculture and Agri Products
Henequen Market
Agriculture and Agri Products
Chaga Mushroom Market
Agriculture and Agri Products
Bee Pollen Market
Agriculture and Agri Products
Tunisia Agriculture Market
Agriculture and Agri Products
Floriculture Market
Agriculture and Agri Products
Animal Derivatives Market
Agriculture and Agri Products
Brazil Rice Market
Agriculture and Agri Products
Alfalfa Protein Concentrate Market
Agriculture and Agri Products
South Africa Agriculture Market
Agriculture and Agri Products
Brazil Compound Feed Market
Agriculture and Agri Products
Inulin Market
Agriculture and Agri Products
Asia-Pacific Poultry Meat Market
Agriculture and Agri Products
United States Compound Feed Market
Agriculture and Agri Products
Canada Bamboos Market
Agriculture and Agri Products
Uncaria Tomentosa Market