
 Rape Seed Meal Market | 2026-2036
Rape Seed Meal Market Size, Share, and Industry Trends Forecast 2026-2036
Rape Seed Meal Market Analytics
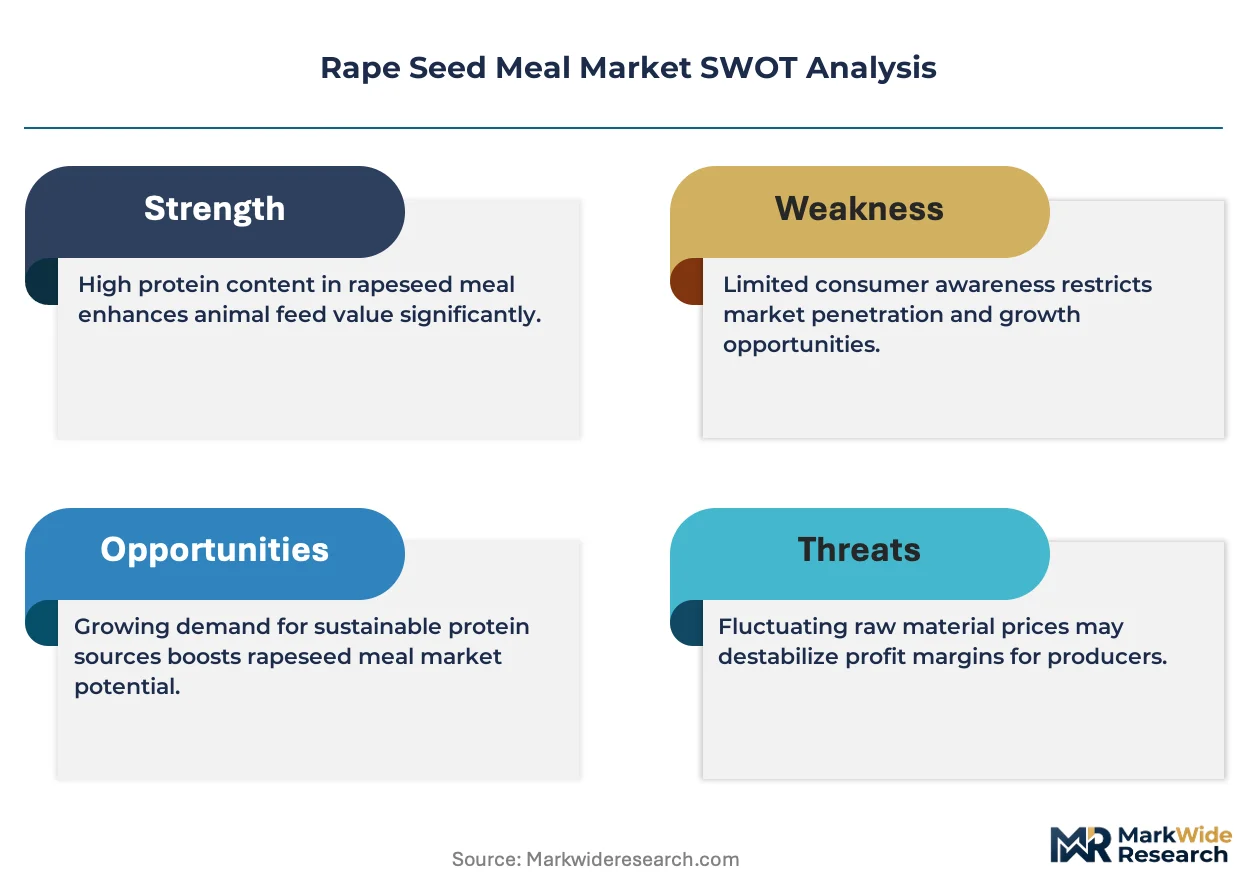
Subscription-based nutritional advisory services bundled with rape seed meal procurement contracts is expanding the value capture model beyond commodity trading. Cargill leverages its integrated crush-to-feed logistics network across North American prairie corridors. Bunge Limited anchors South American origination capacity while extending formulator technical support to European dairy cooperatives. Archer Daniels Midland Company dominates North American processing scale with backward integration into seed genetics and crop protection inputs.
Rape seed meal is the protein-rich residue remaining after oil extraction from Brassica napus seeds, typically containing 35-40% crude protein and variable glucosinolate levels depending on cultivar and desolventizing method. Its primary commercial purpose centers on livestock ration formulation where amino acid profiles complement soybean meal in monogastric and ruminant diets. The meal and cake categories within Product Type concentrate the bulk of volume flows, with de-oiled and pelletized forms commanding logistics premiums in aquaculture and compound feed channels. Livestock and aquaculture segments under Market Segment are drawing processor investment as aquafeed producers reformulate away from marine ingredients.
Feed safety frameworks from EFSA and China's SAMR set maximum contaminant thresholds that determine which crush facilities gain market access for food-chain applications. The EU F-Gas Regulation and REACH chemical protocols indirectly shape processing technology choices by restricting solvent recovery systems and emission profiles at extraction plants. Stakeholders must monitor evolving protein digestibility certification standards and carbon border adjustment mechanisms that will redraw competitive advantage between origin-exporting and destination-processing configurations.
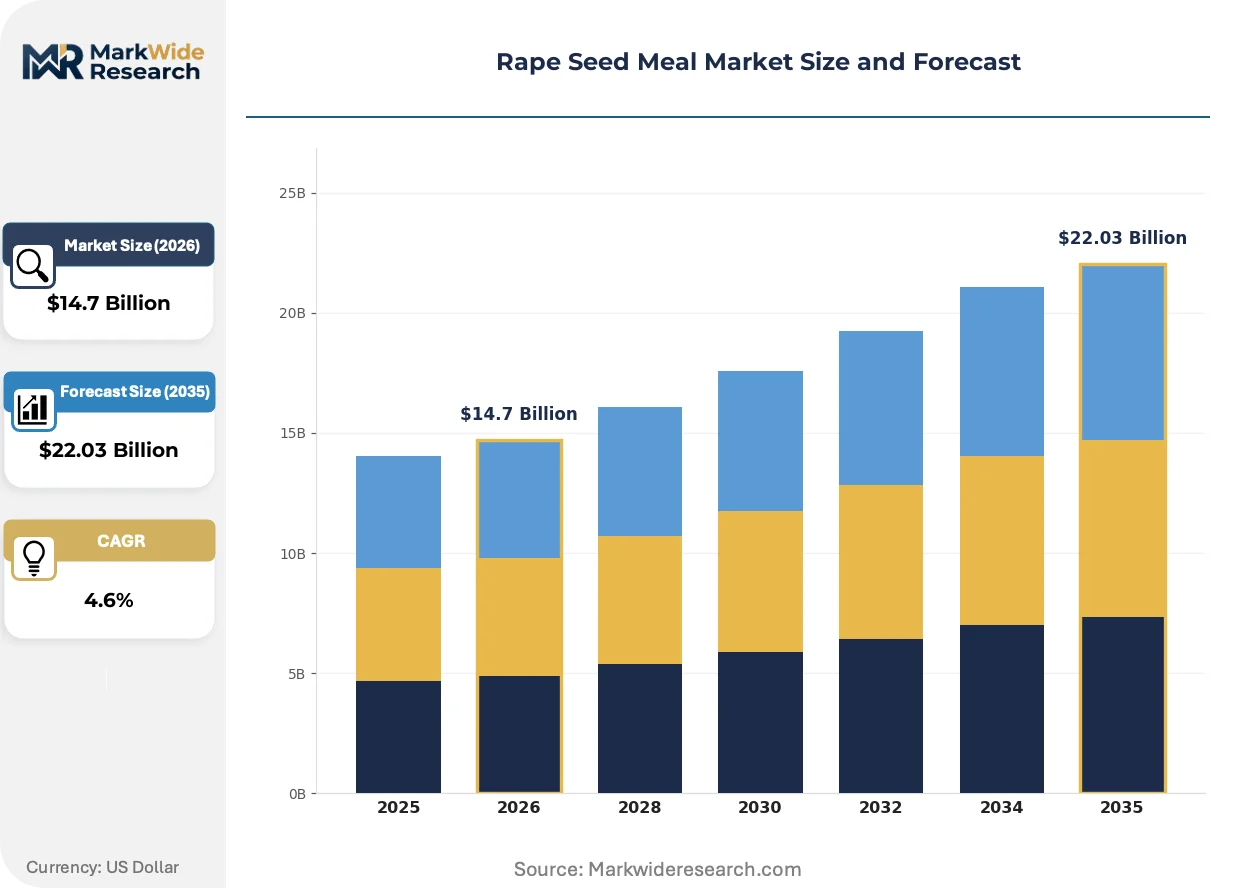
Market Dynamics
Protein substitution mandates in European dairy rations and China's aquafeed reformulation programs are compressing demand timelines for rape seed meal processors, forcing crush capacity expansion ahead of traditional investment cycles.
Growth Catalysts
- EU Green Deal agricultural reforms:Sustainability-linked procurement requirements are redirecting compound feed formulators toward verified low-carbon protein sources, with rape seed meal qualifying under emerging carbon accounting protocols for livestock operations.
- Glucosinolate reduction breeding programs:Seed genetics advances are producing Brassica napus cultivars with sub-20 micromole glucosinolate content, expanding permissible inclusion rates in poultry and swine diets previously constrained by anti-nutritional thresholds.
- Aquaculture feed channels:Marine ingredient displacement strategies in Norwegian and Chilean salmon farming are absorbing de-oiled rape seed meal at premium specifications for extruded aquafeed matrices.
Market Restraints
- Canola seed price volatility:Canadian prairie weather variability and Chinese import policy swings transmit directly to crush margin compression, constraining processor willingness to commit long-term supply contracts.
- Soybean meal substitution economics:Argentine and Brazilian soybean crush expansions maintain price-undercutting capacity in protein markets, capping rape seed meal premium capture in price-sensitive poultry sectors.
- REACH solvent recovery compliance:European extraction facilities face capital-intensive hexane emission control retrofits, disadvantaging older plants against North American competitors with integrated hexane-loop systems.
Strategic Opportunities
- Indian compound feed expansion:FSSAI feed safety standard harmonization and dairy cooperative consolidation are creating first-mover advantages for processors establishing direct distribution to Haryana and Punjab livestock clusters.
- Pelletized meal for automated feeding:Flowability-engineered product formats are penetrating Vietnamese and Indonesian shrimp farming operations seeking to reduce manual handling and dust exposure in closed-system aquaculture.
- Carbon border adjustment positioning:EU CBAM scope expansion into agricultural inputs rewards crush facilities with verified supply chain emissions data, privileging Canadian processors with integrated farm-to-port traceability systems.
Industry Challenges
- Protein digestibility certification timelines:PDCAAS and DIAAS assay standardization delays across ISO reference laboratories are prolonging product registration cycles for novel rape seed protein isolates targeting human nutrition applications.
- Legacy solvent extraction reconfiguration:Transitioning European plants from hexane-based to aqueous or enzyme-assisted oil recovery requires multi-year engineering retrofits without guaranteed offtake premiums for the capital deployed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rape Seed Meal Market |
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $22.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meal, Oil, Cake, Protein Powder End Use Industry: Animal Feed, Food Processing, Biofuel, Nutraceuticals Market Segment: Human Consumption, Livestock, Aquaculture, Soil Fertility Form: De-oiled, Crushed, Pelletized, Flaked |
| Companies Covered | Cargill, Bunge Limited, Archer Daniels Midland Company, Wilmar International, Cofco International, Viterra, CHS Inc, Louis Dreyfus Company, Jiusan Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rape Seed Meal Market Evolving Landscape
Digital traceability infrastructure and precision fermentation adjacencies are recasting how protein-rich oilseed residues move from commodity status toward ingredient-grade positioning in formulated feed and food systems.
Near-infrared spectroscopy calibration networks for real-time glucosinolate and protein content verification is unifying quality assurance across decentralized crush facilities. Large European dairy cooperatives are mandating NIR-certified shipments to standardize ration formulation consistency. This technology compression is eliminating laboratory turnaround delays that previously fragmented procurement decisions across multiple supplier relationships.
China's SAMR feed safety recall protocols and dual carbon goals are tightening contaminant surveillance and energy intensity disclosure requirements for oilseed processors seeking market access. Facilities must now document aflatoxin and pesticide residue testing frequencies alongside Scope 2 emissions profiles. The regulatory pressure concentrates most severely on imported meal shipments entering Guangdong and Jiangsu port clusters, where customs inspection automation is accelerating rejection velocities.
Subscription-based nutritional advisory bundles are displacing spot-market procurement patterns among mid-scale European poultry integrators. These service-layer contracts embed rape seed meal specification guarantees within herd performance optimization programs, locking in volume commitments through multi-year frameworks. The model has penetrated deepest in Germany's Lower Saxony region, where vertically organized producer cooperatives prioritize feed conversion ratio predictability over commodity price minimization.
Rape Seed Meal Market Segmentation
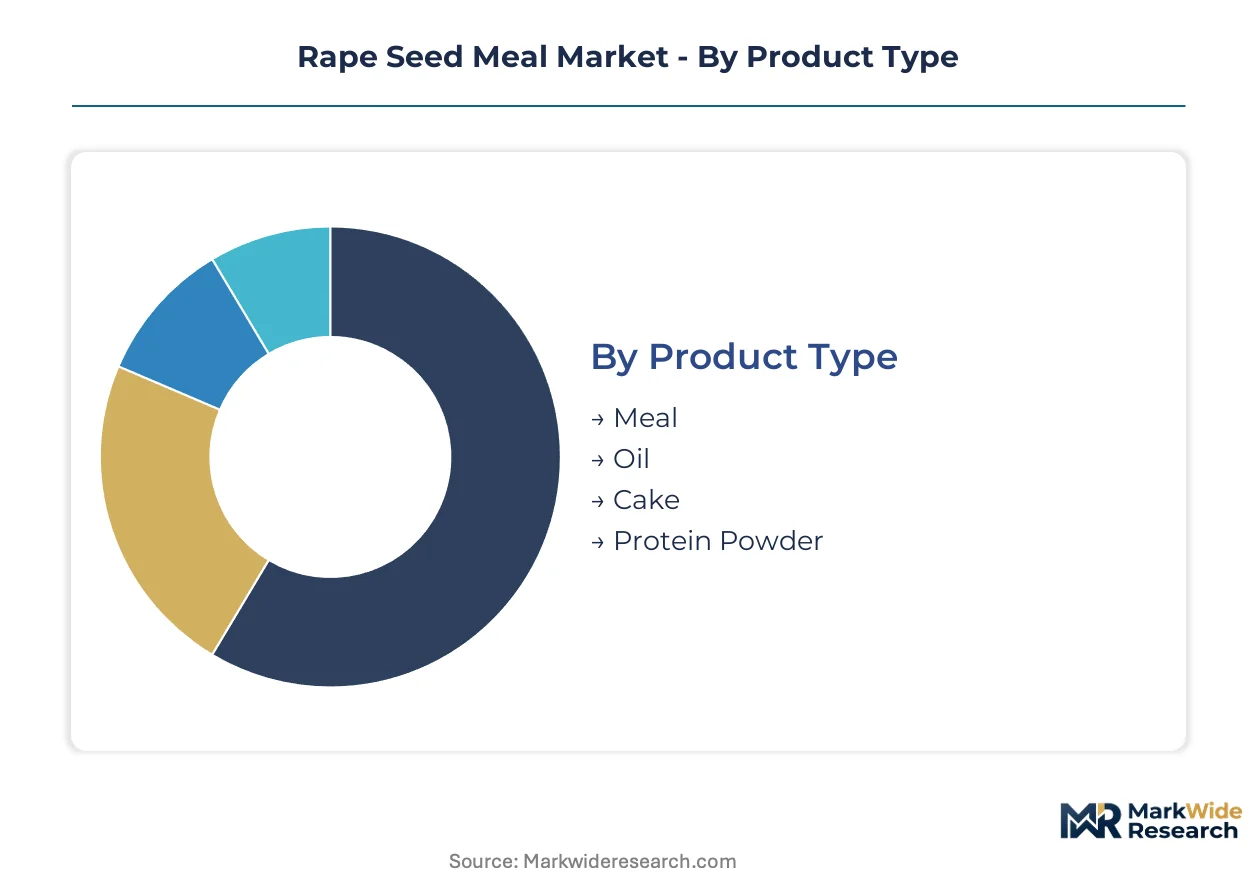
Rape seed meal segmentation tracks how protein content, glucosinolate thresholds, and physical form determine pricing tiers and channel access. Buyers sort across these dimensions based on livestock species tolerance, automated handling requirements, and carbon accounting protocols.
Product Type:
Buyers differentiate by protein concentration thresholds and oil residue specifications that dictate inclusion rates in compound feed formulations.
- Meal:Solvent-extracted material containing 35-40% crude protein with sub-2% residual oil content. Dairy operations in Germany and the Netherlands specify meal for high-performance rations where amino acid density drives milk yield metrics. EFSA contaminant thresholds restrict which crush facilities qualify for food-chain applications.
- Cake:Mechanical-pressed residue retaining 8-12% oil content and coarser particle structure. Ruminant feed blenders in Canada's prairie provinces absorb cake volumes where energy density compensates for lower protein concentration. Cold-press extraction methods preserve glucosinolate profiles that limit inclusion rates in monogastric diets.
- Oil:Crude and refined rape seed oil moves through food processing and biofuel channels rather than feed applications. Crush economics hinge on oil premiums in biodiesel mandate jurisdictions.
- Protein Powder:Protein isolate formats target human nutrition and specialty aquafeed segments. PDCAAS certification delays constrain registration timelines for novel isolate products.
Volume sits with Meal; growth tilts toward Protein Powder.
End Use Industry:
Application concentration follows regulatory pathway complexity and margin structure across feed safety frameworks.
- Animal Feed:Compound feed manufacturers represent the dominant absorption channel, with poultry and swine integrators specifying glucosinolate-reduced cultivars. China's SAMR feed safety recall protocols intensify testing frequency requirements for imported shipments entering Jiangsu port clusters.
- Food Processing:Oil refining and protein isolate extraction for human consumption face stricter contaminant thresholds than feed-grade channels. FSSAI standard harmonization in India is opening formulation opportunities for dairy alternative products.
- Biofuel:Biodiesel mandates in the EU and Canada anchor oil offtake, with meal as the co-product determining crush facility economics.
- Nutraceuticals:Omega fatty acid concentrates and protein isolates for supplement formulations command premium specifications.
Margin concentrates in Nutraceuticals; volume flows through Animal Feed.
Market Segment:
Species-specific digestive tolerance and carbon accounting protocols segment demand across livestock, aquaculture, and human nutrition channels.
- Livestock:Dairy and beef cattle operations tolerate higher glucosinolate levels than monogastric species, absorbing cake and standard meal grades. European dairy cooperatives mandate NIR-certified shipments to standardize ration formulation consistency.
- Aquaculture:Salmon farming operations in Norway and Chile specify de-oiled, pelletized meal for extruded aquafeed matrices. Marine ingredient displacement strategies are compressing demand timelines for premium specifications.
- Human Consumption:Protein isolates and oil products for food applications face the most stringent contaminant surveillance.
- Soil Fertility:Organic farming operations in Germany's Lower Saxony region utilize meal as nitrogen-rich soil amendments.
Livestock commands current volume; aquaculture exhibits the steepest expansion trajectory.
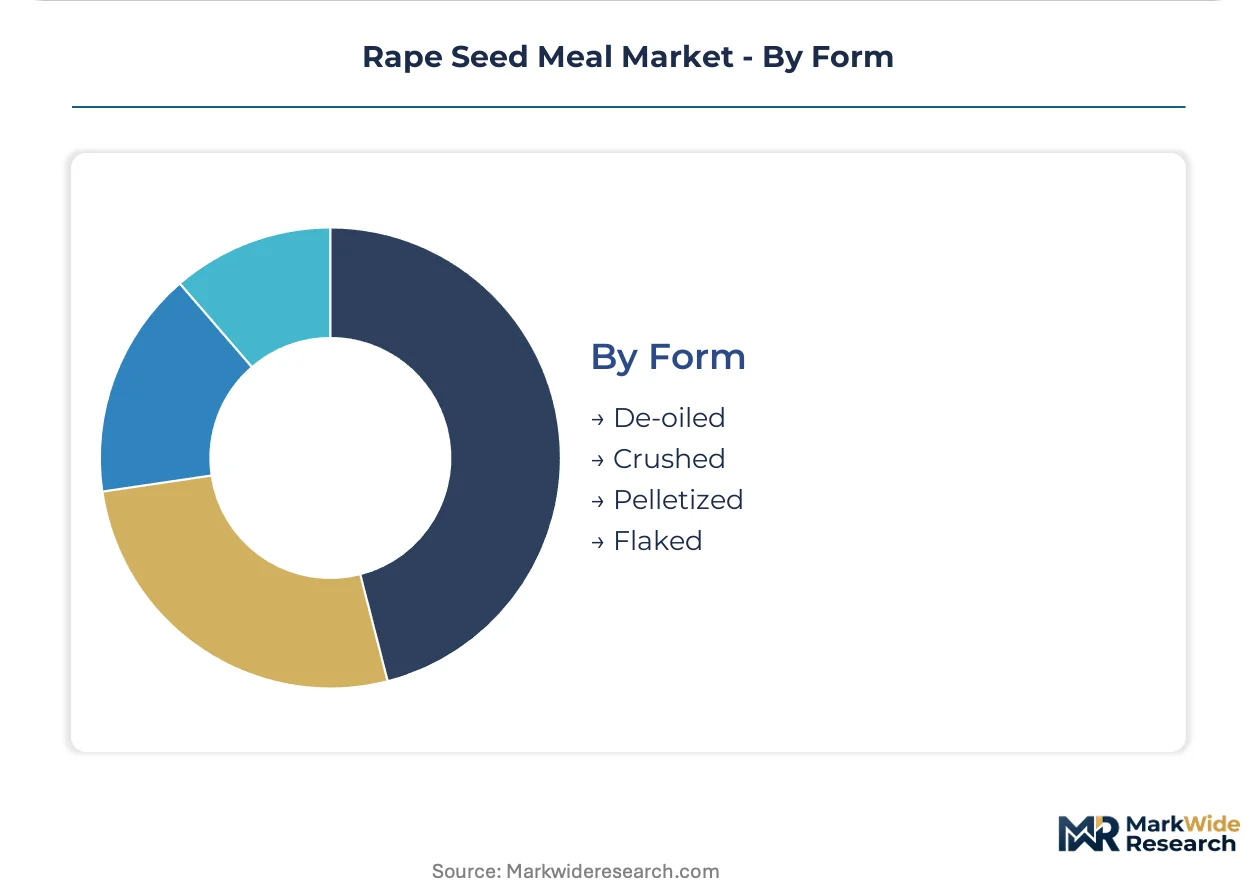
Form:
Physical processing determines logistics economics, storage stability, and automated handling compatibility across distribution channels.
- De-oiled:Solvent-extracted meal with minimal residual oil maximizes protein concentration for high-performance aquafeed. Vietnamese shrimp farming operations specify flowability-engineered formats to reduce dust exposure in closed-system aquaculture.
- Pelletized:Densified forms improve handling efficiency and reduce storage degradation. Automated feeding systems in Indonesian aquaculture operations prioritize pelletized product to minimize manual labor.
- Crushed:Coarsely processed material retains fiber structure suitable for ruminant digestion.
- Flaked:Thin-pressed flakes optimize oil extraction efficiency in subsequent processing stages.
Crushed dominates raw volume; pelletized formats gain share fastest in automated distribution channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian prairie crush capacity exceeds domestic livestock absorption, forcing meal export dependency on Chinese and European ports. German dairy cooperatives and Chinese aquafeed mills now drive procurement timelines that prairie processors must synchronize. This production-consumption asymmetry concentrates pricing power in destination markets while origin facilities compete on carbon certification and logistics reliability.
Canada
Prairie crush expansion in Saskatchewan and Alberta outpaces domestic ruminant feed demand, pressuring port logistics toward Vancouver and Prince Rupert for Asian export. Health Canada and PMRA pesticide residue protocols determine which facilities qualify for EU-bound shipments. Winnipeg-based trading houses coordinate farm-to-port traceability systems that satisfy emerging carbon border adjustment documentation requirements.
Germany
Lower Saxony dairy cooperatives mandate NIR-certified rape seed meal shipments to standardize milk yield optimization across member herds. EU Green Deal agricultural reforms and EFSA feed safety frameworks redirect compound feed formulators toward verified low-carbon protein sourcing. Crush facilities in Hamburg and Magdeburg port zones retrofit hexane recovery systems to satisfy REACH emission protocols.
China
Jiangsu and Guangdong port clusters absorb imported rape seed meal volumes for aquafeed reformulation programs displacing marine ingredients. SAMR feed safety recall protocols and dual carbon goals intensify customs inspection automation, accelerating rejection velocities for contaminant threshold violations. Shandong Province livestock cooperatives scale compound feed production with protein substitution mandates in poultry rations.
India
Haryana and Punjab dairy clusters generate procurement pull for FSSAI-compliant rape seed meal as feed safety standards harmonize across state cooperatives. BIS quality certification and DGFT import tariff schedules determine crush facility market access for food-chain applications. Gujarat oilseed processors expand solvent extraction capacity to capture compound feed demand from Maharashtra poultry integrators.
United States
Midwest crush facilities in Iowa and Illinois leverage integrated rail networks to supply Great Lakes dairy operations and Southeast poultry integrators. USDA livestock feed guidelines and EPA emission standards at extraction plants shape processor investment decisions. North Dakota and Minnesota farm cooperatives backward integrate into seed genetics programs to secure low-glucosinolate cultivar supply.
Rape Seed Meal Market Competitive Landscape
Top-tier vendors anchor integrated crush-to-feed logistics networks, while mid-scale regional processors compete on procurement proximity to livestock clusters. The vendor base stratifies across three tiers: multinational agribusiness conglomerates with origination-to-export infrastructure, cooperative-affiliated crush facilities serving captive dairy demand, and independent toll processors without seed supply control. Strategic archetypes include carbon-certified premium positioning, aquafeed technical service bundling, and cooperative backward integration into breeding programs. Dominant competitive moves encompass port-adjacent capacity expansion and subscription-based nutritional advisory contract layering.
Within the multinational agribusiness tier, Cargill, Bunge Limited, and Archer Daniels Midland Company exemplify divergent geographic anchoring strategies. Cargill occupies a position emphasizing North American prairie corridor integration. Bunge Limited represents South American origination capacity extension toward European dairy technical support. Archer Daniels Midland Company anchors scale-driven North American processing with upstream control over seed genetics inputs. These three entities collectively demonstrate how crush margin capture depends on origination geography, port logistics ownership, and formulator relationship depth rather than processing technology differentiation alone.
| Leading Market Players |
|---|
| Cargill |
| Bunge Limited |
| Archer Daniels Midland Company |
| Wilmar International |
| Cofco International |
| Viterra |
| CHS Inc |
| Louis Dreyfus Company |
| Jiusan Group |
| Others |
Value Network & Pricing Analysis
Captive origination-to-crush integration across Canadian prairie corridors anchors supply positioning and pricing power for multinational processors. This integration choice concentrates margin capture in seed procurement and port logistics ownership rather than extraction technology differentiation. Buyers in Jiangsu and Guangdong port clusters face asymmetric bargaining positions against vertically organized suppliers with farm-to-vessel traceability systems.
Pricing Analysis
Cost-down pressure on de-oiled meal grades accelerates because Vietnamese shrimp farming operations demand flowability-engineered formats at commodity-equivalent price points. Three-tier pricing structure across premium, standard, and economy levels separates NIR-certified shipments for German dairy cooperatives from standard meal for Canadian ruminant blenders and cake for regional poultry integrators. Price differentiation rests on glucosinolate certification thresholds and carbon accounting documentation rather than protein concentration alone. Poultry integrators in India's Maharashtra state exhibit highest price sensitivity; Norwegian salmon farming operations show lowest sensitivity due to marine ingredient displacement premiums.
Supply Chain Analysis
EFSA and SAMR certification gating determines which crush facilities gain food-chain market access, concentrating qualified supply in Germany, Canada, and China's Shandong Province. Raw material flows draw from Brassica napus cultivar breeding programs, hexane solvent recovery systems, and pelletizing equipment capacity. Single-source vulnerability manifests in Vancouver and Prince Rupert port logistics chokepoints for Asian export dependency. Distribution runs through cooperative-affiliated crush facilities serving captive dairy demand and multinational trading houses coordinating farm-to-port traceability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Near-infrared spectroscopy calibration networks are displacing laboratory-based glucosinolate verification, compressing quality assurance timelines from days to minutes across decentralized crush facilities.
For Market Incumbents: Acquire NIR-certified crush facilities in port-adjacent locations to preempt EU carbon border adjustment documentation requirements. Consolidate backward integration into low-glucosinolate seed genetics programs before REACH solvent recovery compliance deadlines force capital-intensive European retrofits. Lock in multi-year subscription advisory contracts with German Lower Saxony dairy cooperatives to defend volume commitments against spot-market procurement patterns. For New Entrants and Emerging Players: Enter via FSSAI-compliant toll processing arrangements serving Haryana and Punjab dairy clusters where feed safety standard harmonization is consolidating procurement pull. Target pelletized meal specifications for Vietnamese and Indonesian aquaculture automation upgrades as the most penetrable white-space segment. Lead with carbon certification documentation as the go-to-market angle to differentiate against incumbent commodity offerings. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational agribusiness conglomerates seeking origination-to-export infrastructure in prairie corridor geographies. Long-term viability favors processors with integrated farm-to-port traceability systems and verified supply chain emissions data. Watch for EU CBAM scope expansion into agricultural inputs as the inflection indicator rewarding carbon-certified facility valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Port-Adjacent Capacity Expansion | Positions crush facilities to satisfy SAMR inspection automation requirements at Jiangsu and Guangdong entry points. |
| Backward Integration into Seed Genetics | Secures sub-20 micromole glucosinolate cultivar supply for poultry and swine diet inclusion rate expansion. |
| Subscription Advisory Service Bundling | Locks in multi-year volume commitments from Germany's Lower Saxony dairy cooperatives through feed conversion ratio optimization. |
| Carbon Certification Investment | Qualifies Canadian processors for EU CBAM documentation advantages against older European hexane-loop facilities. |
| Aquafeed Technical Service Partnership | Captures premium specifications from Norwegian and Chilean salmon farming marine ingredient displacement programs. |
Research Methodology
Document review covered customs trade databases, EFSA contaminant threshold filings, and SAMR feed safety protocols, complemented by interviews with crush facility operations managers, compound feed formulators at European dairy cooperatives, aquafeed procurement leads in Norwegian salmon farming, and seed genetics program directors. Secondary validation drew from Canadian Grain Commission export statistics, EU Green Deal agricultural reform documentation, and FSSAI standard harmonization circulars. Bottom-up volume estimates from crush capacity utilization rates were triangulated against top-down protein substitution mandate projections.
Cross-referencing historical crush margin patterns against expert panel input on glucosinolate reduction breeding timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass product type, end use industry, market segment, and physical form specifications. CAGRs were derived from demand absorption curves in dairy, poultry, and aquaculture channels, with adjustments for REACH compliance capital expenditure cycles and Chinese dual carbon goal implementation velocities.
Revisions become necessary when Canadian prairie weather variability disrupts seed supply, Chinese import policy swings alter crush margin economics, or ISO reference laboratory standardization delays prolong PDCAAS certification timelines. A model refresh is warranted upon material change in EU carbon border adjustment scope expansion schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Middle East Animal Protein Market
Agriculture and Agri Products
China Compound Feed Market
Agriculture and Agri Products
Global Palm Oil Market
Agriculture and Agri Products
Elaeis Guineensis (Palm) Fruit Extract Market
Agriculture and Agri Products
Global Industrial Hemp Market
Agriculture and Agri Products
South America Swine Feed Premix Market
Agriculture and Agri Products
Forage Feed Market
Agriculture and Agri Products
Centella Asiatica Market
Agriculture and Agri Products
Global Vermicompost Market
Agriculture and Agri Products
Rice Straw Market
Agriculture and Agri Products
Italy Alfalfa Market
Agriculture and Agri Products
Global Warm Water Aquaculture Feed Market
Agriculture and Agri Products
Canada Bamboos Market
Agriculture and Agri Products
Netherlands Floriculture Market
Agriculture and Agri Products
Colombia Floriculture Market
Agriculture and Agri Products
Alfalfa Market