
 Cutter-Box Packaging Market | 2026-2036
Cutter-Box Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Cutter-Box Packaging Market Outlook
Single-source to multi-source procurement is rebalancing how converters secure linerboard and folding carton substrates. International Paper leverages its integrated pulp-to-box network across North American mills. Smurfit Kappa anchors European supply through recycled corrugated operations. WestRock differentiates via coated unbleached kraft capacity for food-contact cutter boxes.
Cutter-box packaging denotes precision-cut paperboard or corrugated containers engineered with pre-scored fold lines and die-cut apertures, typically manufactured through rotary or flatbed die-cutting with caliper tolerances between 0.4 mm and 1.2 mm, designed for protective containment and retail-ready presentation. Corrugated material dominates shipping applications where burst strength and stack compression govern specification, while rigid paper occupies premium display and promotional packaging where structural rigidity and print fidelity command margin pools. Custom cutter boxes represent the fastest-growing product type as SKU proliferation and brand personalization compel shorter run lengths.
The EU Packaging and Packaging Waste Regulation and FDA food-contact substance notifications shape material compliance and market access thresholds for cutter-box suppliers serving cross-border accounts. REACH chemical restrictions and FSC chain-of-custody certification further constrain substrate sourcing and adhesive formulations. Stakeholders must monitor evolving extended producer responsibility schemes and decide whether to internalize recycling infrastructure or outsource compliance to specialized recovery operators.
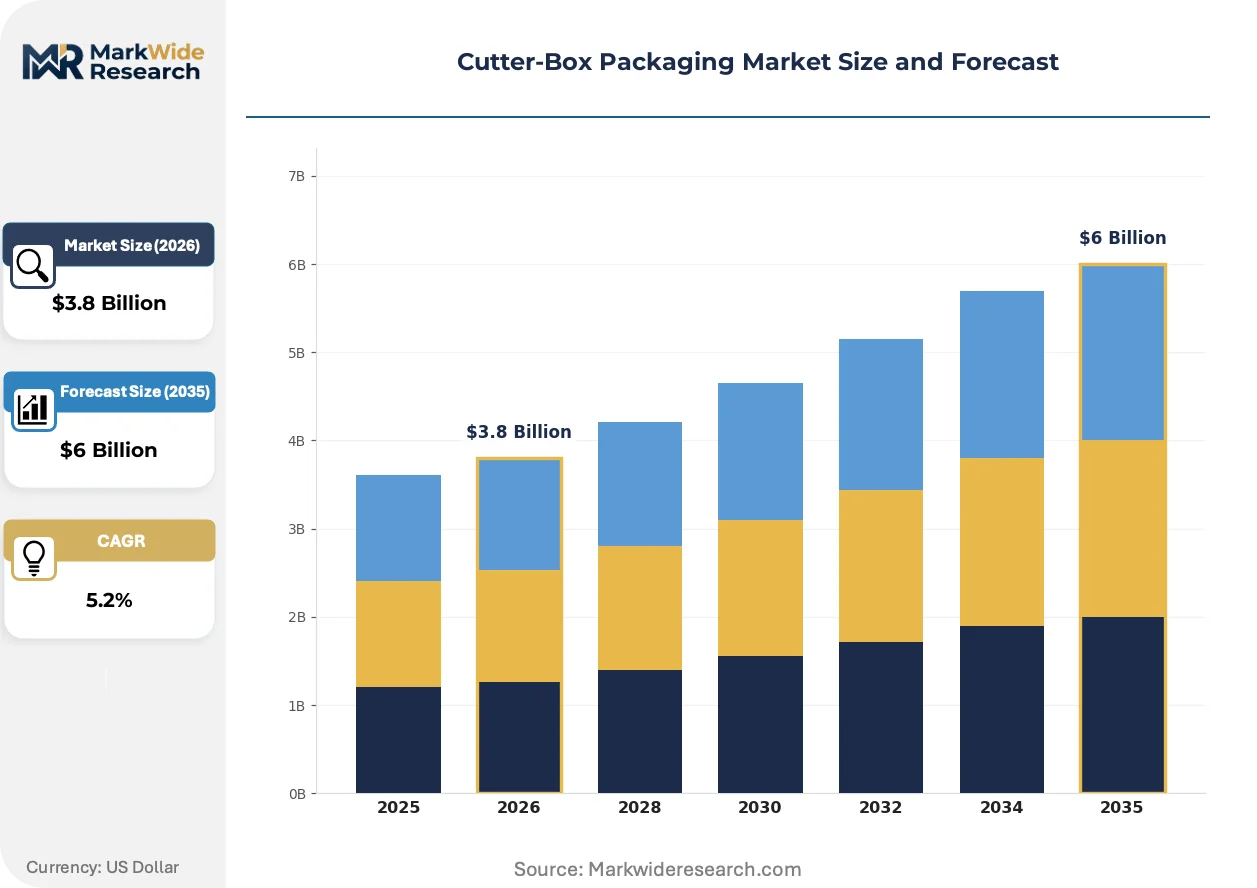
Market Dynamics
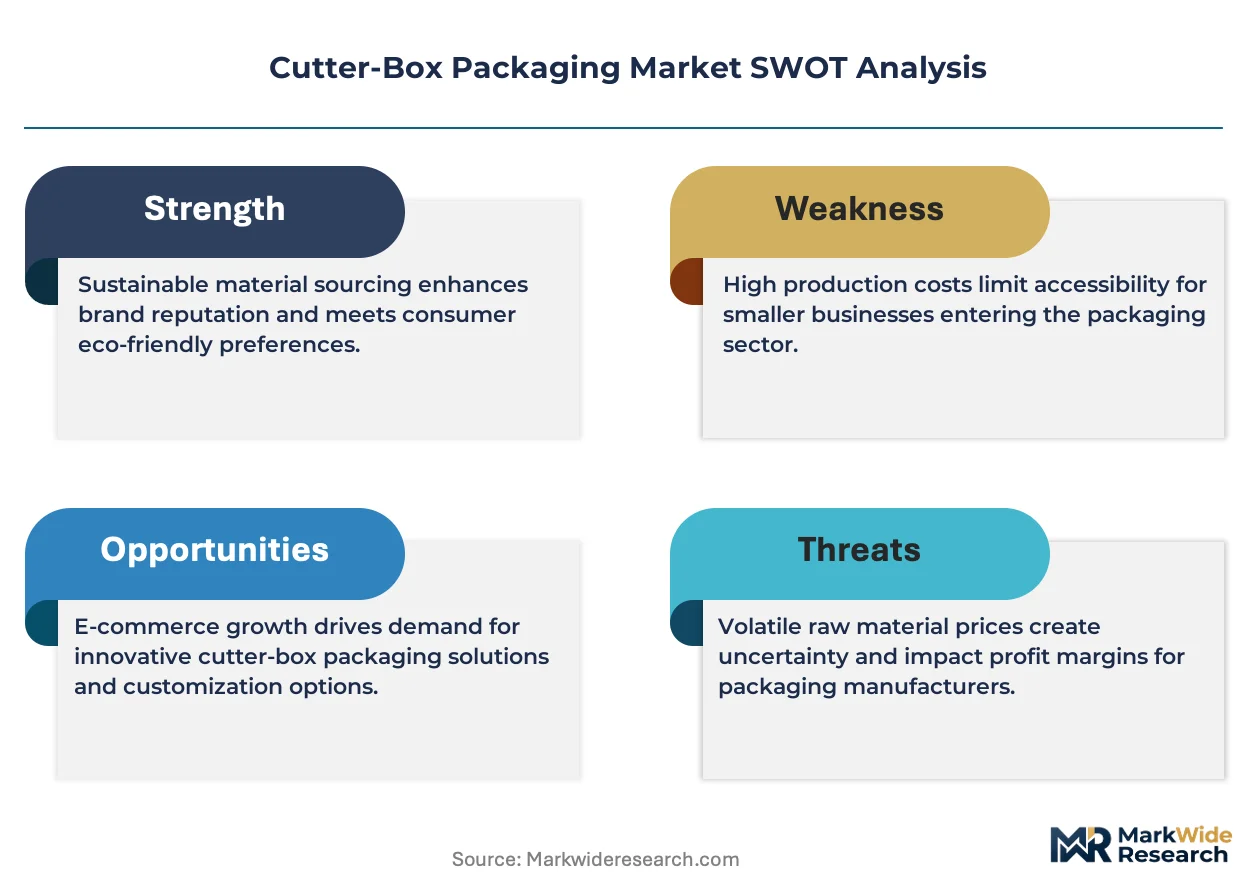
E-commerce fulfillment velocity is compressing order-to-delivery windows, forcing converter investment in digital die-cutting and just-in-time blanking capacity to match SKU proliferation without inventory bloat.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Recyclability mandates above 70% threshold are pulling fiber-based formats ahead of plastic alternatives in German retail supply chains.
- Custom die-cut formats:Direct-to-consumer brands in apparel and cosmetics are specifying short-run, brand-unique box geometries that rotary die-cutting cannot economically produce.
- Germany's industrial packaging corridor:Concentrated automotive and machinery OEM demand in Baden-Württemberg and Bavaria sustains high-volume contracts for protective cutter-box specifications.
Market Restraints
- OCC price volatility:Old corrugated container input costs swing with Chinese import policy shifts, squeezing converter margins on fixed-price annual contracts.
- Linerboard supply concentration:North American integrated producers control 60% of kraftliner capacity, creating bottleneck risk for independent box plants.
- Coated board technical limitation:Polyethylene barrier coatings complicate repulping and disqualify food-contact cutter boxes from EU recyclability certification.
Strategic Opportunities
- India's organized retail expansion:Modern trade penetration in Mumbai and Delhi NCR is creating first-mover advantage for retail-ready display boxes in FMCG.
- Bio-based barrier coatings:Convergence of cellulose nanofiber and polylactic acid technologies is unlocking food-contact compliance without fossil-derived plastics.
- Amazon Vendor Central direct procurement:Bypassing traditional distributor networks lets converters capture margin and demand signals from the largest e-commerce fulfillment operation.
Industry Challenges
- Die-making artisan shortage:Flatbed die production requires skilled steel-rule bending expertise that vocational programs no longer replenish at replacement rate.
- Digital press-to-finisher integration:Matching inkjet web speeds with downstream die-cutting registration tolerance demands capital coordination that mid-scale converters struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cutter-Box Packaging Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cutter Boxes, Custom Cutter Boxes, Die-Cut Boxes, Folding Boxes Material: Cardboard, Corrugated, Kraft Paper, Rigid Paper End User: Retail, E-commerce, Food Industry, Healthcare Application: Storage, Shipping, Display, Promotional Packaging |
| Companies Covered | International Paper, WestRock, Smurfit Kappa, Amcor, Mondi Group, Packaging Corporation of America, DS Smith, Huhtamaki, Oji Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cutter-Box Packaging Market Strategic Shifts
Digital finishing workflows are collapsing the traditional separation between print production and box fabrication, enabling lot-size-one economics that analog tooling cannot match.
High-speed inkjet embellishment combined with in-line laser die-cutting is electrifying the premium unboxing segment. Beauty and electronics brands in South Korea and Japan are specifying micro-flute structures with spot-UV and soft-touch varnish in runs below five hundred units. This capability is compressing minimum viable order quantities and eroding the volume advantage of conventional rotary die setups.
REACH chemical restrictions on per- and polyfluoroalkyl substances are forcing adhesive reformulation across European cutter-box supply chains. PFAS-free hot-melt alternatives exhibit reduced tack on recycled fiber surfaces, compelling substrate pre-treatment investments. Food-contact and pharmaceutical secondary packaging segments in Germany and France are absorbing the steepest compliance costs and accelerating qualification timelines.
Brand procurement teams are consolidating vendor bases around converters with integrated design-to-delivery platforms. Retail and e-commerce verticals in the United States are replacing transactional spot-buying with multi-year framework agreements tied to sustainability scorecards. This behavior concentrates volume with suppliers capable of real-time carbon footprint reporting and FSC chain-of-custody documentation.
Cutter-Box Packaging Market Segmentation
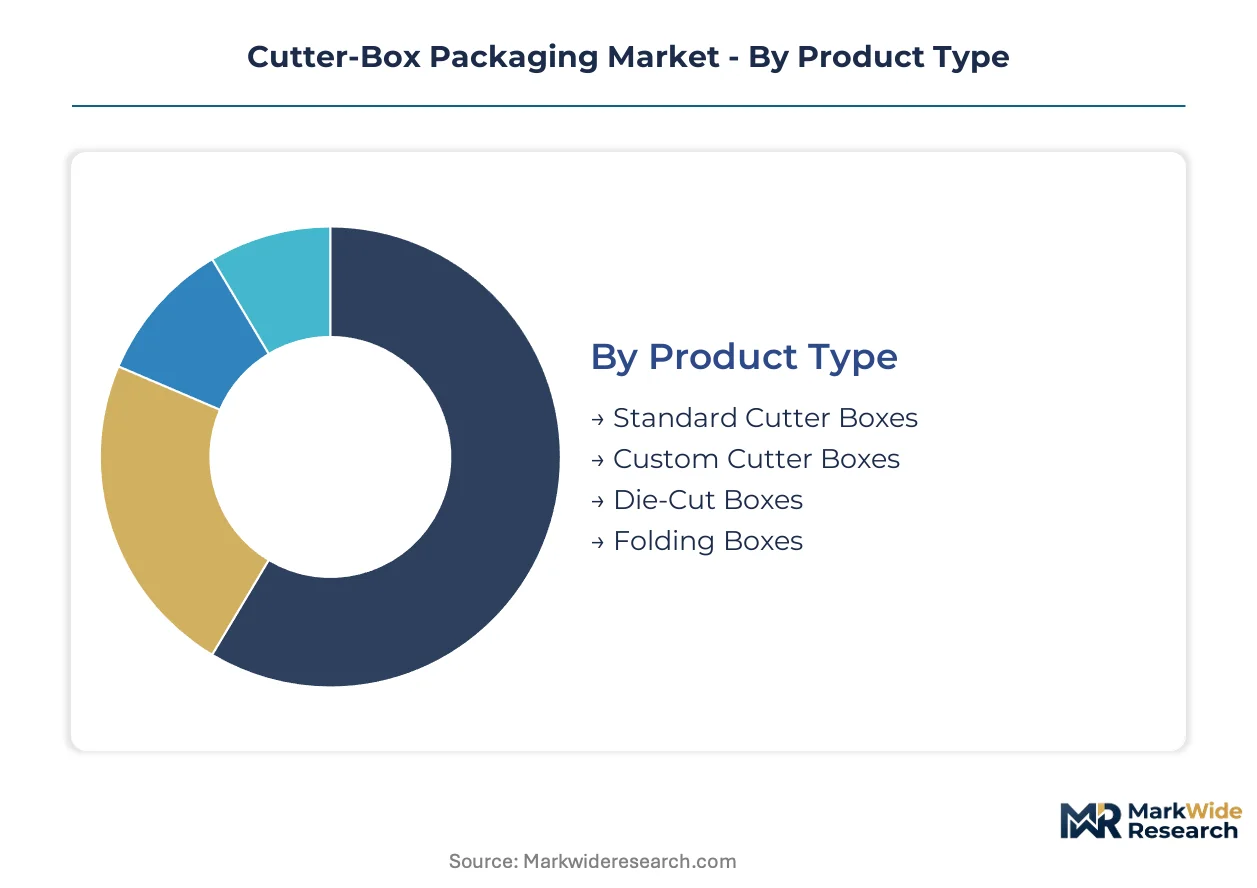
Cutter-box packaging segments carry divergent compliance burdens that reshape procurement patterns. FDA food-contact notifications govern material choices for food industry applications, while EU Packaging and Packaging Waste Regulation thresholds separate recyclable from non-recyclable formats in cross-border trade.
Product Type:
FDA and EU recyclability certifications cluster differently across these formats, with food-contact and pharmaceutical applications demanding the most stringent substrate documentation.
- Standard Cutter Boxes:Pre-scored, uniform geometries manufactured through rotary die-cutting at high throughput. German automotive suppliers in Baden-Württemberg specify these for protective parts containment under fixed annual contracts with burst-strength guarantees.
- Custom Cutter Boxes:Brand-unique apertures and fold patterns produced via flatbed or digital die-cutting. Direct-to-consumer cosmetics brands in South Korea and Japan drive demand for lot-size-one production with soft-touch varnish and spot-UV embellishment.
- Die-Cut Boxes:Precision-cut containers with engineered openings for product visibility or handling. Electronics OEMs favor these for retail-ready unboxing experiences.
- Folding Boxes:Rigid paperboard structures with pre-glued or tuck-end closures. Premium spirits and beauty brands specify these for shelf presence in duty-free retail.
Standard Cutter Boxes sits at the top of the volume ranking, with Custom Cutter Boxes climbing the fastest.
Material:
Cost tiers separate these substrates, with integrated producers capturing margin at kraftliner grades and independents fighting for corrugated share.
- Corrugated:Fluted medium sandwiched between linerboard facings, delivering burst strength and stack compression. E-commerce fulfillment centers in the United States specify this for shipping protection against drop and vibration hazards.
- Cardboard:Uncoated or clay-coated paperboard with caliper range 0.4-1.2 mm. Indian FMCG modern trade in Mumbai and Delhi NCR adopts this for retail-ready display boxes as organized retail expands.
- Kraft Paper:Unbleached sulfate pulp with high tear resistance and printability. Food-contact applications require FDA notification and barrier coating compliance.
- Rigid Paper:Thick, non-bending paperboard for premium structural packaging. Luxury goods and high-end electronics specify this for unboxing theater.
Corrugated dominates shipment volumes, though Rigid Paper commands the steepest per-unit margins.
End User:
Application velocity and order-to-delivery compression vary sharply across these customer types, dictating converter equipment investments.
- E-commerce:Velocity-driven demand for protective, right-sized packaging with minimal void fill. Amazon Vendor Central direct procurement is bypassing traditional distributor networks for demand signal capture.
- Retail:Shelf-ready presentation requirements with print fidelity and structural rigidity. German retail chains enforce EU Packaging and Packaging Waste Regulation recyclability thresholds above 70%.
- Food Industry:FDA food-contact substance notifications and barrier coating compliance dominate material selection. PFAS-free adhesive reformulation under REACH is extending qualification timelines.
- Healthcare:Pharmaceutical secondary packaging with serialization and tamper-evidence requirements. Cleanroom-compatible production environments constrain supplier qualification.
E-commerce sits at the top of the volume ranking, with Food Industry climbing the fastest due to bio-based barrier coating adoption.
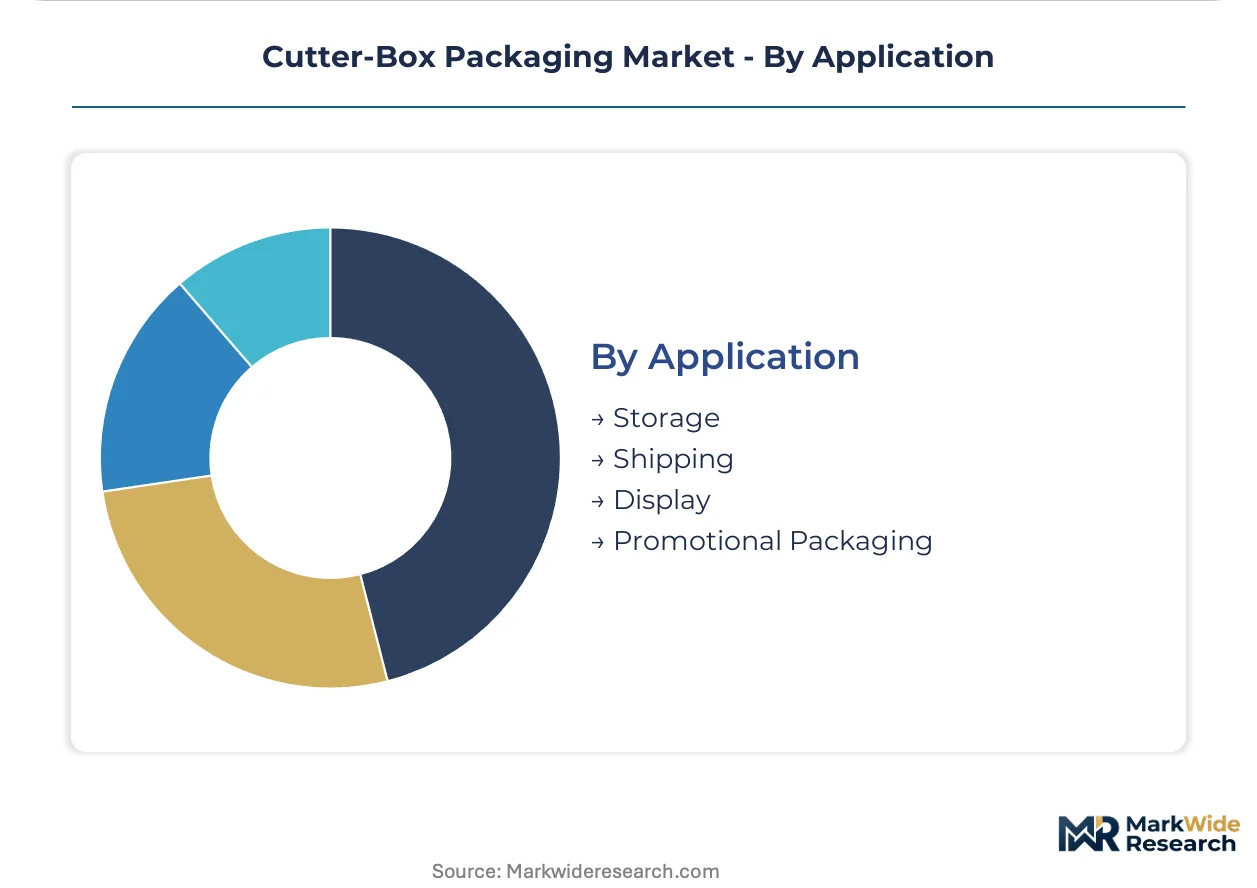
Application:
Margin pools concentrate in display and promotional formats where print embellishment and structural innovation command pricing power.
- Shipping:Protective containment for distribution hazards. Corrugated burst strength and edge crush test specifications govern converter qualification.
- Storage:Long-term archival or warehouse organization. Industrial packaging corridors in Germany specify these for automotive parts inventory.
- Display:Retail-ready presentation with graphics-facing surfaces. High-speed inkjet embellishment combined with laser die-cutting enables micro-flute structures in sub-five-hundred-unit runs.
- Promotional Packaging:Limited-edition brand campaigns with unique geometries. SKU proliferation is compressing minimum viable order quantities.
Shipping sits at the top of the volume ranking, with Display climbing the fastest on digital finishing workflow adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are redirecting cutter-box production toward jurisdictions with lower compliance costs and abundant fiber supply. Integrated producers in North America and Europe face margin compression from extended producer responsibility schemes, while Asian converters exploit feedstock advantages and evolving environmental enforcement gaps.
United States
Amazon Vendor Central direct procurement is compressing order-to-delivery windows for e-commerce fulfillment centers in Indiana and Kentucky. EPA industrial effluent guidelines govern adhesive formulation in food-contact applications. The Pacific Northwest pulp-to-box corridor around Seattle and Portland anchors kraftliner supply for West Coast converter networks.
Germany
Baden-Württemberg automotive OEMs sustain high-volume protective cutter-box contracts with burst-strength specifications. EU Packaging and Packaging Waste Regulation recyclability thresholds above 70% disqualify polyethylene-coated formats from retail supply chains. Bavaria's industrial packaging corridor concentrates converter capacity serving machinery exporters.
China
E-commerce platform consolidation is driving demand for right-sized corrugated shipping boxes in Yangtze River Delta fulfillment hubs. MIIT green manufacturing standards are tightening VOC emissions from solvent-based printing. Zhejiang and Jiangsu provinces host the densest clustering of rotary die-cutting capacity serving export manufacturers.
India
Organized retail expansion in Mumbai and Delhi NCR is creating first-mover demand for retail-ready display boxes in FMCG. BIS packaging standards govern dimensional tolerances for corrugated containers. Gujarat's recycled paperboard mills supply substrate to converter clusters in Ahmedabad and Surat.
Japan
Premium unboxing experiences for electronics and cosmetics brands drive micro-flute specifications with embellishment in runs below five hundred units. METI resource circulation policies mandate recycled fiber content minimums. Kansai region converters around Osaka specialize in high-value folding carton formats for duty-free retail.
Cutter-Box Packaging Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue digital finishing and bio-based barrier coatings as differentiation vectors. The vendor base stratifies across integrated pulp-to-box networks, independent sheet plants, and specialized display converters. Three archetypes dominate: fiber-integrated multinationals with captive linerboard supply, regional converters with digital die-cutting agility, and niche specialists in pharmaceutical and food-contact compliance. Competitive moves center on backward integration into recycled pulp operations and strategic partnerships with e-commerce platforms for direct procurement access.
Among North American integrated producers, International Paper and WestRock exemplify the fiber-captive archetype with mill networks spanning the Southeast and Pacific Northwest. Smurfit Kappa anchors European supply through recycled corrugated operations concentrated in Germany and the Benelux region. These three entities represent distinct geographic postures within a structurally tiered competitive field where scale advantages in substrate supply confront agility premiums in short-run digital production.
| Leading Market Players |
|---|
| International Paper |
| WestRock |
| Smurfit Kappa |
| Amcor |
| Mondi Group |
| Packaging Corporation of America |
| DS Smith |
| Huhtamaki |
| Oji Holdings |
| Others |
Value Chain & Pricing Dynamics
Digital die-cutting adoption is compressing cost economics for short-run production while concentrating supply power among converters with in-house inkjet finishing lines. This technology shift simultaneously erodes rotary-die volume premiums and rewards capital-heavy players who can amortize equipment across Amazon Vendor Central direct contracts and EU recyclability-certified formats.
Pricing Analysis
Distributor margin compression is reshaping cutter-box economics as Amazon Vendor Central direct procurement bypasses traditional wholesale layers. Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified custom formats from commodity corrugated shipping boxes. Cost compression in standard corrugated is intensifying because Chinese OCC import policies swing Old Corrugated Container input costs. E-commerce fulfillment centers exhibit highest price sensitivity, while pharmaceutical and food-contact buyers absorb premiums for FDA notification compliance and PFAS-free adhesive qualification.
Supply Chain Analysis
Regional distribution centers in Germany's Baden-Württemberg and Bavaria industrial corridors anchor European cutter-box fulfillment through hub-and-spoke patterns serving automotive OEMs. Supply concentrates in the United States, Germany, and China, with North American integrated producers controlling kraftliner capacity. The chain draws from Old Corrugated Container pulp, coated unbleached kraft, and bio-based barrier coating feedstocks. Single-source vulnerability runs through Chinese OCC export policy as a structural risk. Distribution runs through converter direct-to-platform models and traditional distributor networks serving mid-scale box plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cutter-box packaging reads as a late-cycle quality story where SKU proliferation and EU recyclability mandates pull demand toward premium custom formats with certified substrate documentation.
For Market Incumbents: Lock in fiber supply through backward integration into recycled pulp operations or long-term linerboard offtake agreements with Pacific Northwest mills. Digital die-cutting entrants threaten rotary-die volume tiers; defend through Amazon Vendor Central direct procurement relationships that capture demand signals and margin pools from e-commerce fulfillment centers. For New Entrants and Emerging Players: Capture white-space in India's organized retail expansion across Mumbai and Delhi NCR, where modern trade penetration creates first-mover advantage for retail-ready display boxes. Target bio-based barrier coating qualification for food-contact applications, where REACH PFAS restrictions extend incumbent qualification timelines and create entry windows for compliant alternatives. For Investors and Strategic Acquirers: Valuations sit cheapest among independent sheet plants with stranded rotary-die capacity and undigitized workflow infrastructure. Long-term viability hinges on converters with integrated design-to-delivery platforms and real-time carbon footprint reporting capabilities. Watch Amazon Vendor Central supplier consolidation as the signal for margin compression or expansion in the e-commerce fulfillment segment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Pulp | Captures margin from OCC volatility while securing EU recyclability certification compliance. |
| Digital Die-Cutting Capacity Expansion | Enables lot-size-one economics for South Korean and Japanese cosmetics brand specifications. |
| Amazon Vendor Central Direct Enrollment | Bypasses distributor networks to capture demand signals from Indiana and Kentucky fulfillment hubs. |
| PFAS-Free Adhesive Qualification | Unlocks German and French food-contact contracts under REACH chemical restrictions. |
| FSC Chain-of-Custody Certification | Satisfies retail procurement sustainability scorecards consolidating vendor bases in the United States. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining converter operations directors, e-commerce procurement leads at fulfillment platforms, brand packaging managers, and adhesive formulation specialists. Secondary validation draws from EPA industrial effluent guidelines, EU Packaging and Packaging Waste Regulation documentation, FDA food-contact substance notification databases, and trade customs data for linerboard and folding carton substrates. Bottom-up demand modeling triangulates against top-down macroeconomic indicators across the analysis window.
Rate-of-change decomposition separates volume growth from value expansion across product type, material grade, end-user vertical, and application format dimensions. CAGRs derive from segment-level demand elasticity modeling against e-commerce fulfillment velocity, EU recyclability threshold enforcement, and SKU proliferation trends. Industry-specific inputs include Amazon Vendor Central supplier onboarding rates and German automotive OEM protective packaging contract renewal patterns.
OCC price volatility, Chinese export policy shifts, and REACH chemical restriction enforcement are the dominant revision risks that could compress or extend converter margin assumptions. Forecasts reflect documented assumptions about digital die-cutting adoption curves and bio-based barrier coating qualification timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Automatic Liquid Filling Machines Market
Packaging Machinery
Tray and Sleeve Packing Machines Market
Packaging Machinery
Deblistering Machines Market
Packaging Machinery
Flow Pack Machine Market
Packaging Machinery
Case Packaging Machinery Market
Packaging Machinery
Molded Pulp Packaging Machines Market
Packaging Machinery
Pre-Made Pouch Packaging Machines Market
Packaging Machinery
Global Vial Cap Sealing Machines Market
Packaging Machinery
Overwrapping Machines Market
Packaging Machinery
Stick Pack Packaging Machine Market
Packaging Machinery
Flow Wrap Machines Market
Packaging Machinery
Soap Stamping Machine Market
Packaging Machinery
Poly Bagging Machines Market
Packaging Machinery
Global Blow Fill Seal Equipment Market
Packaging Machinery
Side Load Case Packing Machines Market
Packaging Machinery
Global Hand Wrapping Machine Market