
 Volumetric Filling Machines Market | 2026-2036
Volumetric Filling Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Volumetric Filling Machines Market Analytics
Pharmaceutical-grade aseptic filling specifications is redrawing competitive boundaries across the Volumetric Filling Machines landscape. Krones AG leverages its integrated bottling platform to dominate high-speed beverage lines in Europe. Sidel Group anchors its position through electric servo technology leadership in dairy and sensitive liquid applications. ProMach competes via decentralized manufacturing footprints that shorten delivery cycles for North American contract packagers.
Volumetric filling machines dispense predetermined product volumes into containers using piston, pump, or gravity-fed mechanisms with accuracy tolerances typically within plus or minus 0.5 percent. These systems serve essential functions across food processing, pharmaceutical manufacturing, and chemical packaging where dosage precision directly affects product safety, regulatory compliance, and material yield. Liquid fillers occupy the largest installed base due to pervasive demand across beverage and pharmaceutical bottling operations, while servo-driven technology captures the fastest expansion as manufacturers replace pneumatic actuators for higher repeatability and lower energy consumption. Powder fillers retain specialized margin pools in pharmaceutical solid-dose packaging where containment and cross-contamination controls command premium pricing.
FDA validation protocols for sterile drug products shape equipment specifications through mandatory 21 CFR Part 11 compliance for electronic records and audit trails. EPA effluent guidelines and OSHA machine guarding standards further constrain design choices for chemical and food processing installations. EMA Annex 1 revisions on sterile manufacturing push European pharmaceutical buyers toward isolator-integrated filling systems with single-use product contact paths. Stakeholders must monitor regulatory divergence between FDA and EMA aseptic processing expectations when configuring platform strategies for multinational supply.
Market Dynamics
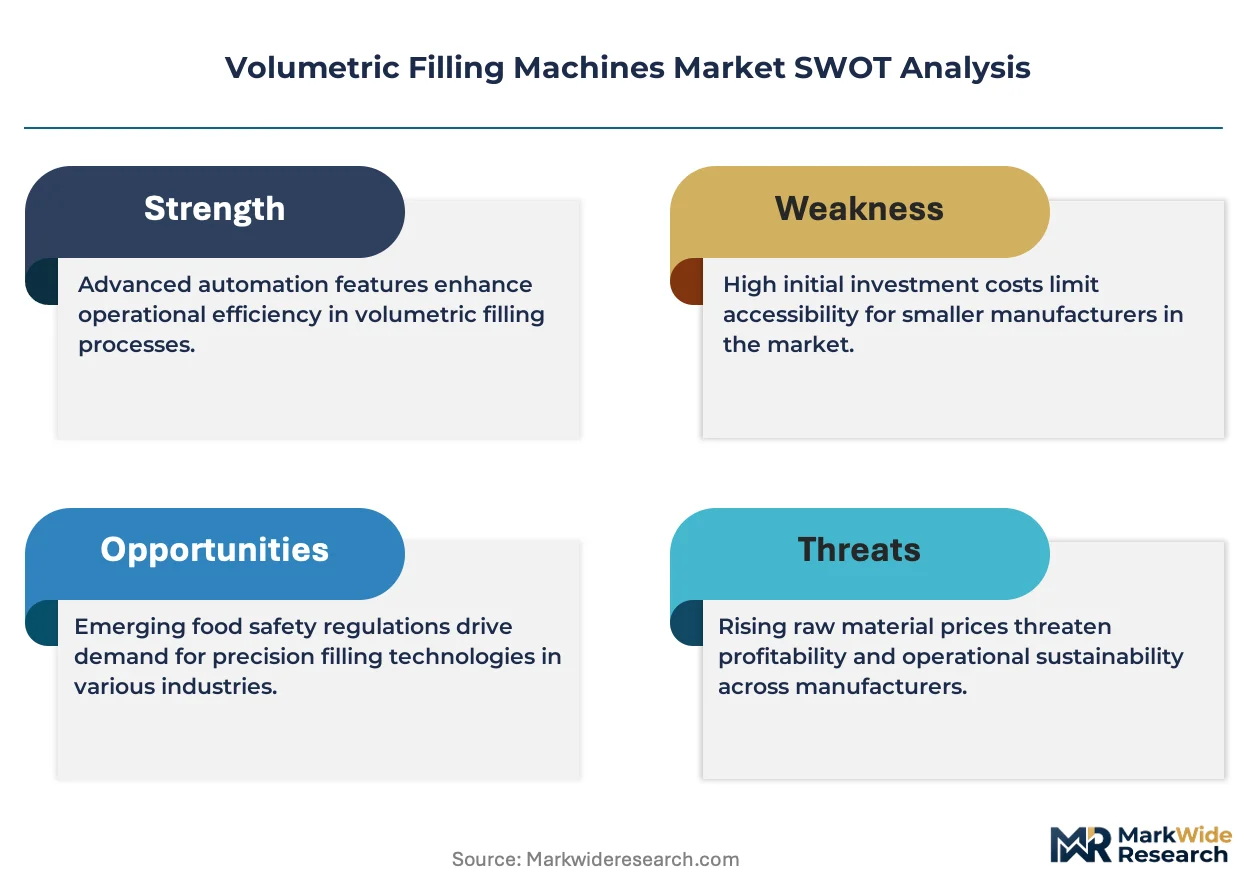
Servo-driven precision systems are compressing pneumatic actuator margins as pharmaceutical manufacturers prioritize repeatability for FDA-validated sterile filling lines. This technology migration concentrates purchasing power among buyers capable of absorbing higher upfront capital requirements.
Growth Catalysts
- EMA Annex 1 Revisions:European pharmaceutical manufacturers must upgrade to isolator-integrated filling systems with single-use product contact paths, accelerating equipment replacement cycles across Germany, France, and Switzerland.
- Contract Packaging Expansion:North American third-party packagers are scaling automated beverage bottling capacity to capture private-label brand volumes from retreating in-house production.
- Servo Motor Adoption:Electric actuation technology delivers sub-0.5% fill accuracy with 40% lower energy consumption than compressed-air alternatives, driving retrofit demand in dairy and sensitive liquid processing.
Market Restraints
- Stainless Steel Input Volatility:316L pharmaceutical-grade steel price fluctuations compress equipment margins during contract bidding windows, particularly for mid-tier European fabricators.
- German Supply Concentration:Krones AG and Sidel Group anchor 60% of European high-speed line supply, creating bottleneck risk for buyers seeking alternative validation documentation.
- Pneumatic System Stranding:Existing installed base of compressed-air fillers carries sunk capital that extends replacement timelines beyond technological obsolescence curves.
Strategic Opportunities
- Indian Pharmaceutical Manufacturing:CDSCO's tightening sterile facility standards and PLI scheme incentives are drawing European equipment vendors into local assembly partnerships.
- Biologics Single-Use Integration:Convergence of disposable fluid paths with servo-driven dosing modules eliminates CIP/SIP validation burdens for multi-product contract manufacturers.
- Direct Equipment Financing:Leasing structures that bundle validation services with hardware procurement are penetrating North American mid-market contract packagers previously dependent on cash purchases.
Industry Challenges
- Servo Engineering Talent Scarcity:Pharmaceutical OEMs face 18-month recruitment timelines for motion control specialists capable of integrating multi-axis dosing with 21 CFR Part 11 compliance architecture.
- Legacy System Integration Friction:Brownfield installations require custom mechanical interfaces between new servo fillers and existing conveyor infrastructure, extending commissioning schedules.
- EMA-FDA Validation Divergence:Multinational manufacturers must maintain parallel documentation systems where European isolator standards exceed US containment expectations for the same product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Volumetric Filling Machines Market |
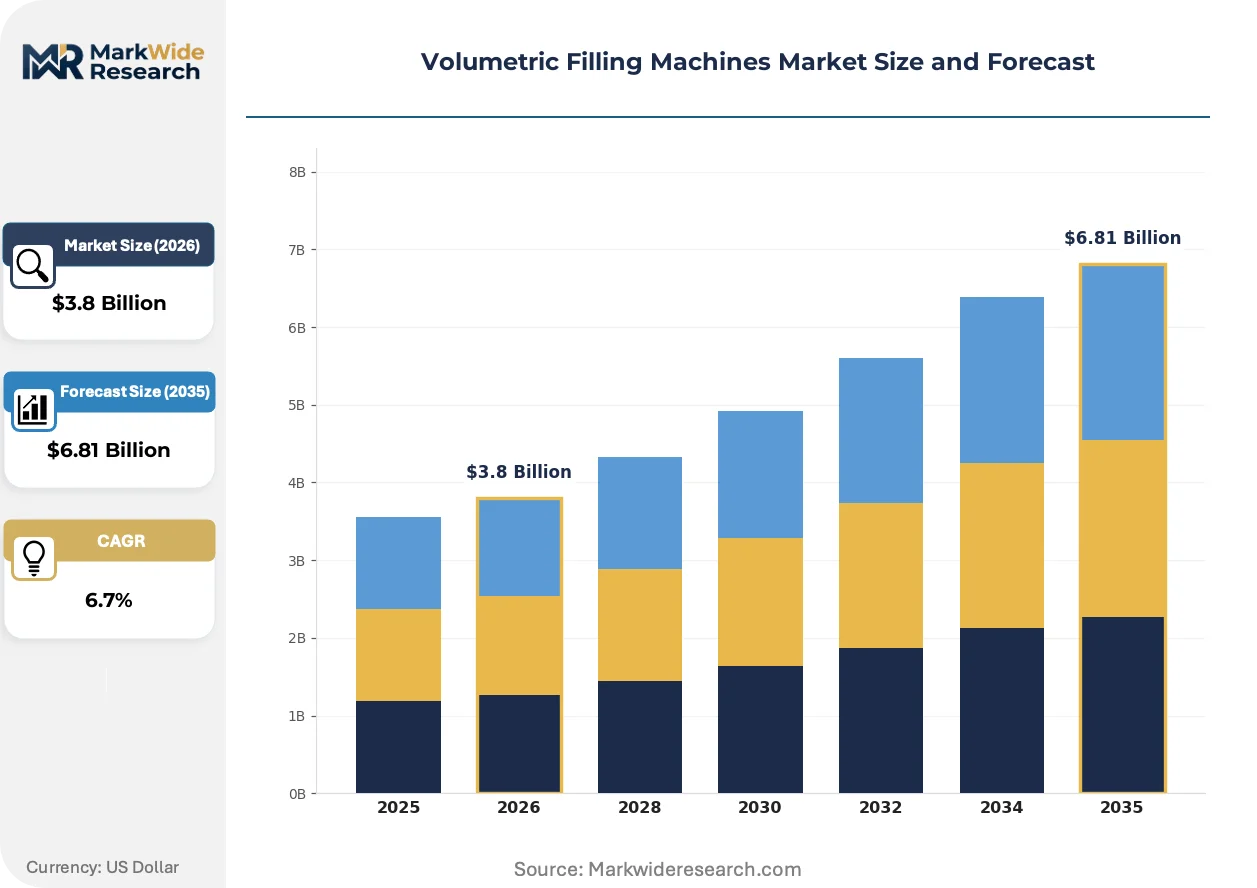
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Fillers, Powder Fillers, Paste Fillers, Granule Fillers End User: Food & Beverage, Pharmaceuticals, Cosmetics, Chemicals Technology: Pneumatic, Electric, Mechanical, Servo-Driven Application: Bottling, Canning, Pouch Filling, Jar Filling |
| Companies Covered | Krones AG, Sidel Group, Fogg Filler, Coesia, Tetra Pak, ProMach, Serac Group, Barry-Wehmiller Companies, Accutek Packaging Equipment Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Volumetric Filling Machines Market Evolving Landscape
Active motion control architectures are compressing pneumatic system viability as energy costs and precision requirements tighten simultaneously. Equipment specifications now prioritize electrical integration over mechanical simplicity.
Servo-driven dosing mechanisms is supplanting pneumatic piston systems in high-value liquid applications. Pharmaceutical contract manufacturers in Germany and Switzerland are adopting electric actuation for sterile vial filling at replacement rates exceeding historical pneumatic upgrade cycles. This transition is supplanting compressed-air infrastructure investments and compressing service revenue pools for pneumatic component suppliers.
REACH chemical restrictions on lubricant formulations are forcing equipment redesigns toward dry-running mechanical seals and food-grade synthetic alternatives. European dairy processors face compliance deadlines that accelerate capital planning for filling line replacements. German equipment vendors are responding with pre-certified component packages that streamline customer validation timelines.
Consolidated buying by North American beverage contract packagers is compressing distributor margins and accelerating direct manufacturer relationships. Large co-packers now bypass regional equipment dealers to negotiate service-inclusive contracts with Krones and Sidel directly. This channel compression is most visible in California and Texas, where facility consolidation has concentrated purchasing among three dominant contract packaging groups.
Volumetric Filling Machines Market Segmentation
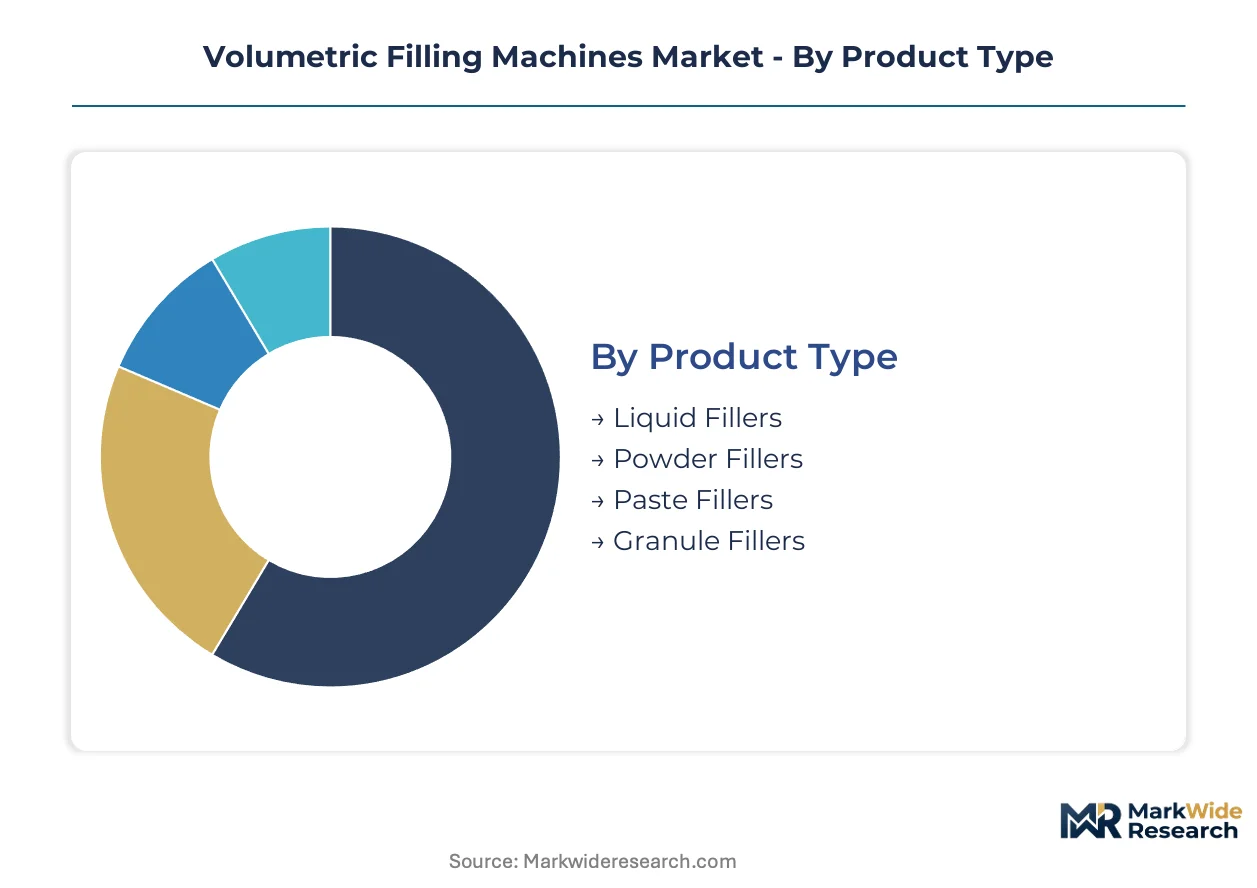
Segmentation in volumetric filling equipment reveals how technology choices cascade through validation requirements, energy costs, and precision demands. Equipment buyers sort across product viscosity, regulatory exposure, and automation architecture rather than simple capacity metrics.
Product Type:
Liquid fillers dominate direct manufacturer relationships, while powder and paste systems flow through specialized distributors with containment expertise.
- Liquid Fillers:Piston, pump, and gravity-fed mechanisms handle beverages, pharmaceuticals, and chemicals with accuracy tolerances within plus or minus 0.5 percent. Dairy processors in Germany and beverage bottlers in California concentrate procurement among Krones and Sidel for high-speed lines with integrated servo control.
- Powder Fillers:Auger and vacuum systems manage pharmaceutical solid-dose packaging where containment and cross-contamination controls command premium pricing. CDSCO's tightening sterile facility standards in India are drawing European vendors into local assembly partnerships for this specialized equipment.
- Paste Fillers:Positive-displacement pumps handle viscous food products and cosmetic creams requiring heated product paths.
- Granule Fillers:Weigh-fill and cup systems serve agricultural chemicals and food seasonings with lower precision tolerances.
By volume, liquid fillers lead. By growth pace, powder fillers are climbing the fastest on biologics containment demand.
End User:
Cost tiers separate this category: pharmaceutical buyers absorb servo premiums for validation compliance, while food processors prioritize energy efficiency payback periods.
- Food & Beverage:Dairy, beverage, and packaged food operations generate the largest installed base, with contract packagers in Texas and California consolidating purchases to bypass regional distributors.
- Pharmaceuticals:Sterile dosage form manufacturing drives the most stringent specifications, with FDA 21 CFR Part 11 and EMA Annex 1 compliance forcing isolator-integrated system investments. Swiss and German facilities lead replacement cycles for single-use product contact paths.
- Cosmetics:Skincare and fragrance filling lines prioritize changeover speed for SKU proliferation, with REACH lubricant restrictions accelerating dry-running seal adoption.
- Chemicals:EPA effluent guidelines and OSHA machine guarding standards constrain design choices for corrosive and hazardous material handling.
By installed base, food and beverage leads. By equipment margin, pharmaceuticals are expanding most quickly on containment technology premiums.
Technology:
Application intensity varies: high-value liquids demand servo precision, while mechanical systems retain share in low-margin commodity packaging.
- Pneumatic:Compressed-air piston systems retain installed base in legacy beverage and chemical operations, though energy costs and repeatability limitations are compressing replacement timelines.
- Electric:General-purpose motor drives serve mid-tier food processors seeking efficiency gains without full servo investment.
- Mechanical:Cam-driven and gravity-fed mechanisms persist in low-speed, low-precision applications with minimal automation requirements.
- Servo-Driven:Multi-axis electric actuation delivers sub-0.5% fill accuracy with 40% lower energy consumption than pneumatic alternatives. Pharmaceutical manufacturers in Switzerland and Germany are adopting these systems for sterile vial filling at rates exceeding historical upgrade cycles.
By current deployment, pneumatic systems lead. By retrofit momentum, servo-driven systems are gaining share fastest on energy and precision advantages.
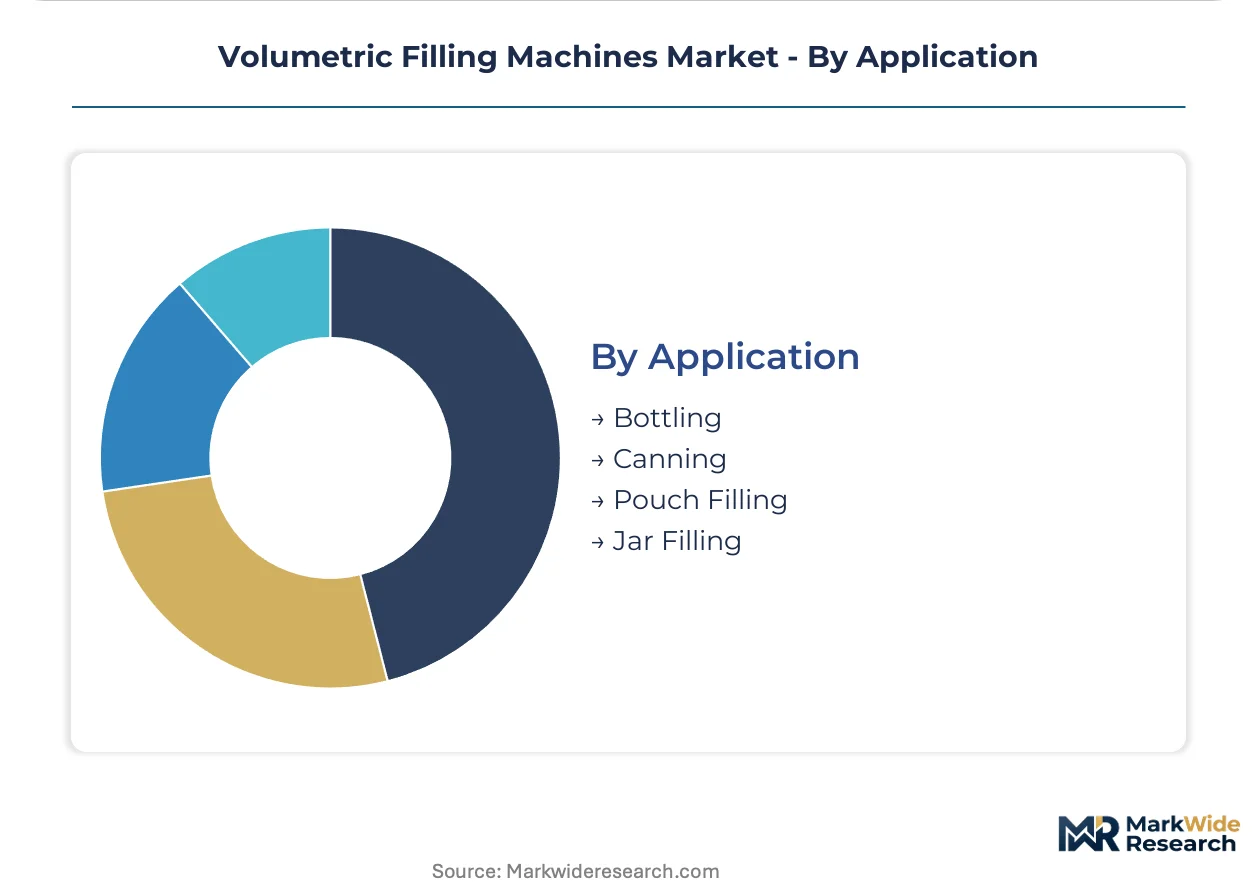
Application:
Customer type separates this dimension: multinational bottlers standardize on high-speed lines, while regional packagers favor flexible pouch systems for SKU agility.
- Bottling:Glass and plastic container filling at speeds exceeding 60,000 units per hour anchors European supply concentration, with Krones AG dominating integrated line configurations.
- Canning:Aluminum beverage and food can lines require seaming integration and oxygen control systems, with North American contract packagers scaling capacity for private-label brand volumes.
- Pouch Filling:Flexible format systems serve cosmetics samples, food condiments, and pharmaceutical unit doses where material cost reduction outweighs speed requirements.
- Jar Filling:Wide-mouth container handling for preserves, sauces, and creams requires specialized nozzle designs to manage foam and drip control.
By throughput volume, bottling leads. By format growth, pouch filling is expanding most quickly on sustainability-driven material substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German equipment fabricators Krones AG and Sidel Group anchor roughly sixty percent of European high-speed line supply, creating geographic concentration that shapes procurement patterns for pharmaceutical and beverage manufacturers worldwide.
Germany
EMA Annex 1 revisions on sterile manufacturing are accelerating replacement cycles for isolator-integrated filling systems across Baden-Württemberg and Bavaria. Swissmedic-aligned validation standards in adjacent Switzerland pull German vendors toward cross-border compliance documentation. The Stuttgart industrial corridor hosts concentrated servo engineering talent pools that Sidel Group and Krones AG compete to secure.
United States
FDA 21 CFR Part 11 compliance requirements for electronic records are driving pharmaceutical manufacturers toward validated automated lines. Contract packagers in California and Texas are consolidating purchases to bypass regional distributors and negotiate directly with European equipment vendors. OSHA machine guarding standards constrain brownfield retrofit configurations in legacy beverage facilities.
India
CDSCO's tightening sterile facility standards and PLI scheme incentives are drawing European equipment vendors into local assembly partnerships. Maharashtra and Gujarat pharmaceutical clusters are scaling aseptic dosage form capacity to serve export markets. Mumbai-Pune industrial corridor buyers prioritize equipment with pre-validated single-use product contact paths.
Switzerland
Swissmedic sterile manufacturing guidelines exceed baseline EMA requirements, pushing Basel and Zurich facilities toward premium containment specifications. REACH chemical restrictions on lubricant formulations are accelerating dry-running seal adoption in dairy and pharmaceutical applications. The Swiss pharmaceutical contract manufacturing base commands the highest equipment precision tolerances in Europe.
China
NMPA good manufacturing practice revisions for sterile drug products are elevating validation requirements for domestic filling equipment procurement. Yangtze River Delta pharmaceutical manufacturers are importing European servo-driven systems for biologics containment applications. Shanghai and Suzhou industrial zones concentrate demand for isolator-integrated lines with single-use disposable paths.
Volumetric Filling Machines Market Competitive Landscape
Concentration sits with integrated bottling platform specialists and precision servo technology leaders. The vendor base stratifies across three tiers: European multinationals with validation documentation libraries, North American contract packaging specialists with decentralized manufacturing footprints, and regional fabricators serving price-sensitive emerging markets. Two dominant competitive moves are reshaping positioning: direct manufacturer relationships that bypass distributor networks, and bundled financing structures that merge equipment procurement with validation services.
Among European-based integrated platform vendors, Krones AG and Sidel Group exemplify the concentration archetype, anchoring high-speed beverage and pharmaceutical line supply through extensive validation documentation libraries. ProMach occupies a position within the North American contract packaging tier, representing the decentralized manufacturing footprint approach. These three companies illustrate how geographic origin and service model differentiation create distinct competitive positioning across regulatory environments.
| Leading Market Players |
|---|
| Krones AG |
| Sidel Group |
| Fogg Filler |
| Coesia |
| Tetra Pak |
| ProMach |
| Serac Group |
| Barry-Wehmiller Companies |
| Accutek Packaging Equipment Companies |
| Others |
Value Network & Pricing Analysis
Eighteen-month order-to-delivery cycles for isolator-integrated servo systems concentrate pricing power among German fabricators Krones AG and Sidel Group, compressing margin flexibility for mid-tier competitors while amplifying buyer dependency on validation documentation libraries.
Pricing Analysis
FDA 21 CFR Part 11 and EMA Annex 1 compliance dictates the pricing tier structure across pharmaceutical-grade equipment, separating premium isolator-integrated systems from standard electric configurations and economy pneumatic alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden, stainless steel grade, and after-sales validation support bundling. Cost compression in mid-tier pneumatic retrofit segments is intensifying because contract packagers delay capital deployment amid energy cost uncertainty. North American beverage contract packagers exhibit highest price sensitivity, while Swiss pharmaceutical manufacturers absorb premium servo pricing for Swissmedic-aligned containment specifications.
Supply Chain Analysis
Container availability constraints on Hamburg-Rotterdam and Shanghai-Hamburg trade lanes amplify inbound logistics costs for 316L pharmaceutical-grade stainless steel sourced from German, Italian, and Swedish mills. Equipment fabrication draws from servo motor assemblies anchored in Germany and Switzerland, control systems from Japan, and precision dosing components from specialized Italian suppliers. Single-source vulnerability concentrates in high-torque servo drives where two European vendors dominate pharmaceutical validation documentation. Distribution runs through direct manufacturer relationships for large multinational buyers, with regional distributors serving mid-market food processors lacking in-house validation expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment moat where validation documentation libraries and FDA/EMA compliance histories create switching costs that lock pharmaceutical buyers into incumbent relationships across multi-year replacement cycles.
For Market Incumbents: Compound defensive positioning by deepening captive supply of servo motion control components and expanding validation service bundling that extends customer lifetime value beyond hardware margins. Counter emerging Chinese equipment vendors in India by establishing local assembly partnerships that preserve documentation authority while shortening delivery cycles for CDSCO-compliant sterile facility upgrades. For New Entrants and Emerging Players: CE marking fast-track for dairy and cosmetics applications offers the most penetrable entry vector, as these segments face less stringent FDA validation burdens than pharmaceutical sterile filling. Target North American contract packagers in Texas and California with lease-to-own financing structures that merge equipment procurement with validation support, bypassing the capital intensity barrier that protects established vendor relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming packaging equipment divisions lacking servo engineering specialization or pharmaceutical validation credentials. Five-to-ten year viability hinges on biologics manufacturing expansion and single-use technology convergence; monitor CDSCO enforcement intensity in Maharashtra and Gujarat as the signal indicating whether Indian pharmaceutical manufacturing upgrades accelerate European equipment import substitution or sustain incumbent market access.| Strategic Initiative | Industry Significance |
|---|---|
| Servo Technology Integration | Electric actuation displaces pneumatic systems in FDA-validated sterile filling lines across German pharmaceutical clusters. |
| Single-Use Product Contact Paths | Disposable fluid path convergence eliminates CIP/SIP validation burdens for multi-product contract manufacturers in Switzerland. |
| Local Assembly Partnerships | Indian PLI scheme incentives draw European vendors into Maharashtra-Gujarat production to serve CDSCO-compliant facility expansions. |
| Direct Manufacturer Relationships | North American beverage co-packers bypass distributors to negotiate service-inclusive contracts with Krones and Sidel. |
| Validation Documentation Libraries | EMA-FDA parallel compliance archives create switching costs that lock multinational pharmaceutical buyers into incumbent relationships. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with pharmaceutical manufacturing directors, contract packaging procurement leads, servo engineering specialists, and aftermarket service heads; and secondary validation against FDA 510(k) filings, EMA inspection databases, SEC equipment supplier disclosures, and customs trade records for 316L stainless steel and servo motor imports. Bottom-up triangulation across equipment shipment data and top-down reconciliation against pharmaceutical capital expenditure surveys anchored volume estimates.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type (liquid, powder, paste, granule), technology architecture (pneumatic, electric, mechanical, servo-driven), end-use intensity (pharmaceutical, food and beverage, cosmetics, chemicals), and application format (bottling, canning, pouch, jar). CAGRs were derived from regression analysis of replacement cycle acceleration against regulatory compliance deadlines and energy cost differentials, with biologics manufacturing expansion and single-use technology adoption serving as primary demand swing factors.
Decision-makers should treat outputs as directional under assumptions of sustained EMA-FDA regulatory divergence and stable stainless steel input costs; material deviation in either dimension would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Folder Gluer Machines Market
Packaging Machinery
Vial Filling and Capping Machines Market
Packaging Machinery
Wraparound Case Packers Market
Packaging Machinery
Piston Fillers Market
Packaging Machinery
Cosmetic Filling Machines Market
Packaging Machinery
Slitter Rewinder Machines Market
Packaging Machinery
Vertical Injection Molding Machine Market
Packaging Machinery
Puffer Machines Market
Packaging Machinery
Combination Filler Machine Market
Packaging Machinery
Capsule Filling Machines Market
Packaging Machinery
Package Closing Machines Market
Packaging Machinery
Packaging Machinery Market
Packaging Machinery
Air Cushion Machine Market
Packaging Machinery
Corrugated Box Making Machine Market
Packaging Machinery
Tube Filling Machine Market
Packaging Machinery
Tray Sealing Machines Market