
 Cup Filling Machine Market | 2026-2036
Cup Filling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Cup Filling Machine Market Analysis
After-sales service contracts and predictive maintenance software is expanding as a recurring revenue layer for OEMs serving high-volume dairy and beverage plants. Barry-Wehmiller leverages its broad service network to lock in multi-year maintenance agreements across North American dairy cooperatives. Mespack SL specializes in compact rotary fillers for emerging-market juice processors seeking European hygiene certification. Serac Group dominates aseptic filling upgrades through its installed base of ESL dairy lines in France and Brazil.
A cup filling machine is an automated or semi-automated packaging system that doses liquid, powder, granule, or paste products into pre-formed cups or containers at speeds ranging from 30 to 600 units per minute, then seals them with foil, film, or lidding material for retail distribution. Stainless steel construction with IP65 washdown ratings dominates food and pharmaceutical installations where CIP/SIP protocols apply. Automatic fillers anchor the highest margin pool due to integration complexity with upstream blow-molding and downstream case-packing systems. Powder filling functionality is gaining share in nutraceutical contract manufacturing where dose accuracy and dust containment drive specification.
FDA 21 CFR Part 110 governs sanitary design for food-contact surfaces, while EU Machinery Directive 2006/42/EC mandates CE-marked guarding and interlock systems for automated fillers sold in Europe. China's SAMR enforces GB standards for food machinery hygiene that increasingly mirror Codex Alimentarius principles. Stakeholders must monitor how divergent national certification timelines for hygienic design standards affect cross-border equipment procurement decisions.
Market Dynamics
Dairy cooperatives and ready-to-drink beverage producers are consolidating filling operations into fewer, larger automated lines to capture scale economies while navigating stricter FDA and EU hygiene mandates.
Growth Catalysts
- ESL Dairy Expansion:Extended shelf-life milk processors in Germany and Brazil are retrofitting aseptic rotary fillers to reduce cold-chain dependency and expand retail distribution radius.
- GB Standards Alignment:China's SAMR enforcement of Codex-mirrored food machinery hygiene rules is accelerating stainless-steel equipment replacement cycles in domestic yogurt and probiotic plants.
- Powder Dosing Accuracy:Nutraceutical contract manufacturers are specifying servo-driven auger fillers with real-time checkweighing to meet FDA 21 CFR Part 111 supplement cGMP requirements.
Market Restraints
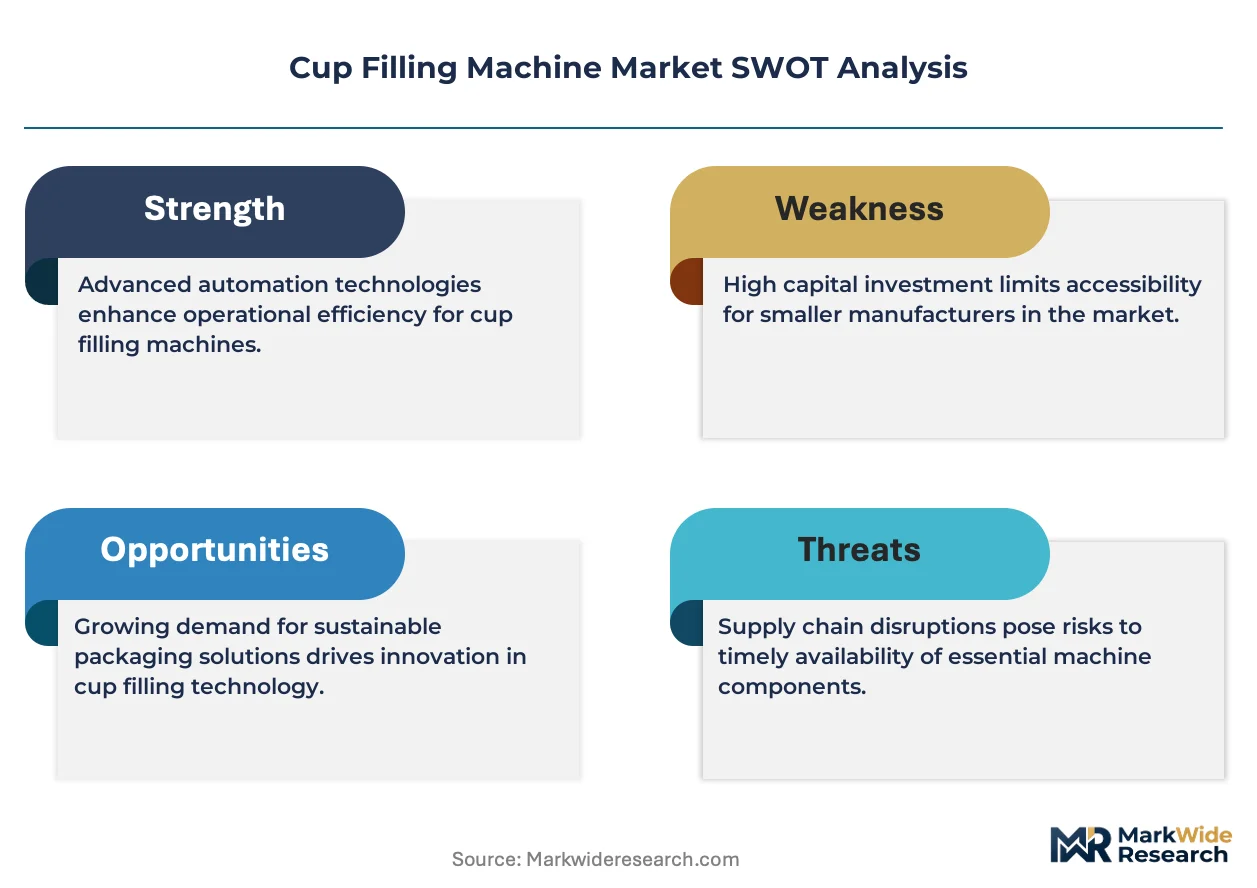
- Stainless Steel Input Volatility:Grade 316L stainless price swings constrain OEM margin stability and extend quotation validity periods for large dairy line contracts.
- CE Certification Backlogs:EU Machinery Directive 2006/42/EC conformity assessment delays at notified bodies are stretching delivery timelines for rotary filler exports to European juice processors.
- Flexible Pouch Substitution:Spouted stand-up pouch lines from Mespack and competing OEMs are capturing portion-control beverage volumes that previously flowed into cup formats.
Strategic Opportunities
- Indian Dairy Modernization:FSSAI enforcement of packaged food hygiene rules and cooperative sector consolidation is creating first-mover openings for automatic cup filling lines in Gujarat and Punjab milk unions.
- Pharma-Grade Crossover:FDA 21 CFR Part 210/211 pharmaceutical equipment standards are converging with food machinery design, enabling OEMs to serve dual-use contract manufacturing facilities with validated CIP/SIP protocols.
- Predictive Maintenance SaaS:Barry-Wehmiller's remote diagnostics platform demonstrates recurring revenue potential through vibration sensing and spare-part subscription models anchored to high-volume dairy installations.
Industry Challenges
- Mechatronics Talent Scarcity:Servo motion programming and hygienic welding certification shortages are extending commissioning timelines for integrated rotary filler installations.
- Legacy PLC Integration:Brownfield dairy plants running Allen-Bradley SLC 500 architectures face protocol translation complexity when retrofitting Ethernet/IP-connected automatic fillers with MES connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cup Filling Machine Market |
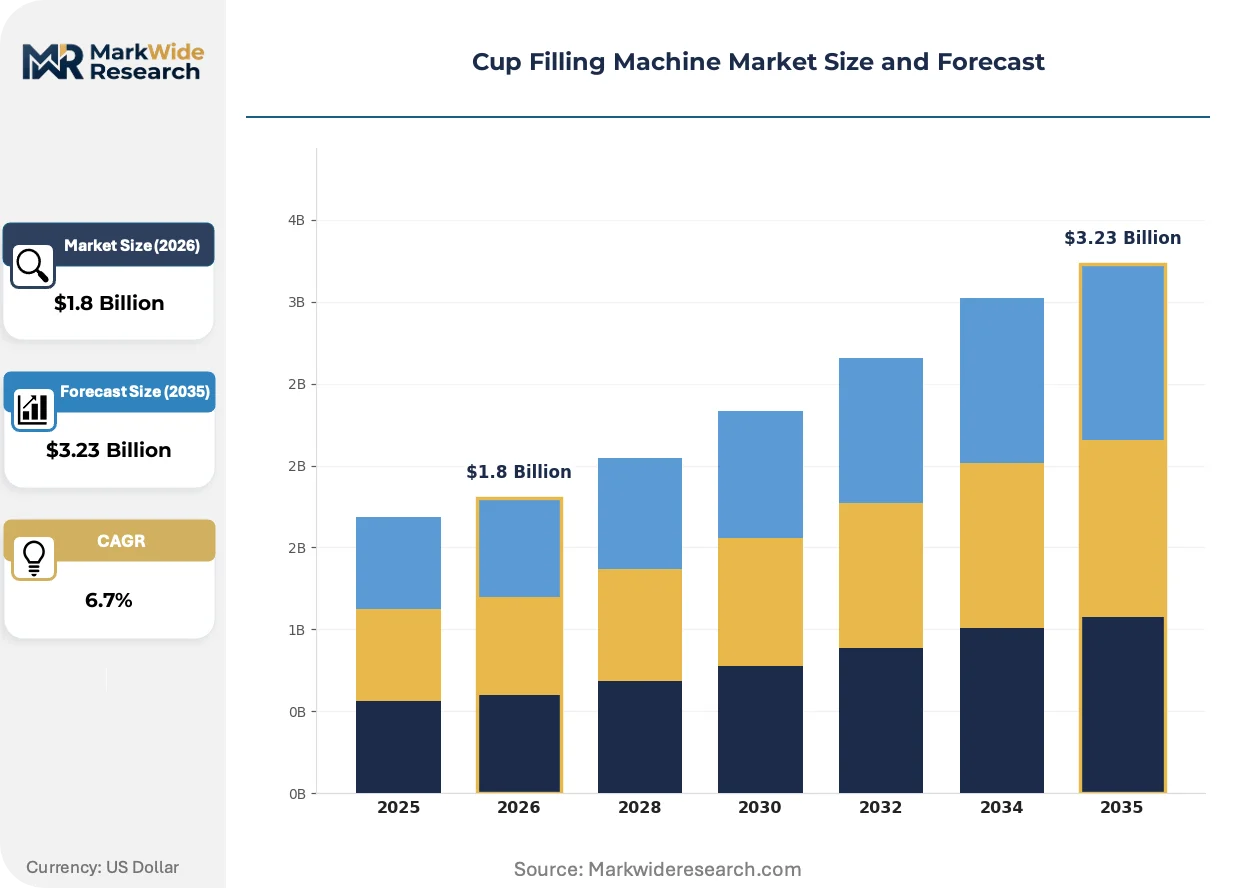
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Fillers, Semi-Automatic Fillers, Manual Fillers, Portable Fillers End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Products Functionality: Liquid Filling, Powder Filling, Granule Filling, Paste Filling Material Type: Plastic, Stainless Steel, Aluminum, Others |
| Companies Covered | Paxiom Group, AMS Filling Systems, Serac Group, Volumetric Technologies, Frain Industries, Barry-Wehmiller, Cemre Cup Filling Machines, Mespack SL, R.A. Jones, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cup Filling Machine Market Emerging Trajectories
Machine learning-enabled vision inspection and modular filler architectures are compressing changeover times while raising the hygiene verification bar across dairy and pharmaceutical packaging halls.
Electromagnetic flowmeters with AI-based foam detection are rewriting liquid filling precision standards. High-speed yogurt producers in France are adopting these sensors to eliminate overfill waste during fruit-on-bottom cup production. The technology is compressing giveaway margins and enabling single-point calibration protocols that reduce line downtime.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing lidding material reformulation across European dairy packaging. Foil-to-plastic seal integrity testing now dominates R&D spending at cup sealing subsystem suppliers. German OEMs are responding with induction sealing modules that maintain hermetic performance without fluoropolymer coatings.
Cooperative buyers in the United States are consolidating maintenance spend under multi-year service agreements rather than transactional spare-part purchasing. Dairy Farmers of America and similar procurement groups are unbundling OEM service contracts from equipment finance to benchmark performance metrics across their plant networks. This behavioral shift is visible most acutely in Wisconsin and California processing clusters where uptime guarantees now determine vendor selection.
Cup Filling Machine Market Segmentation
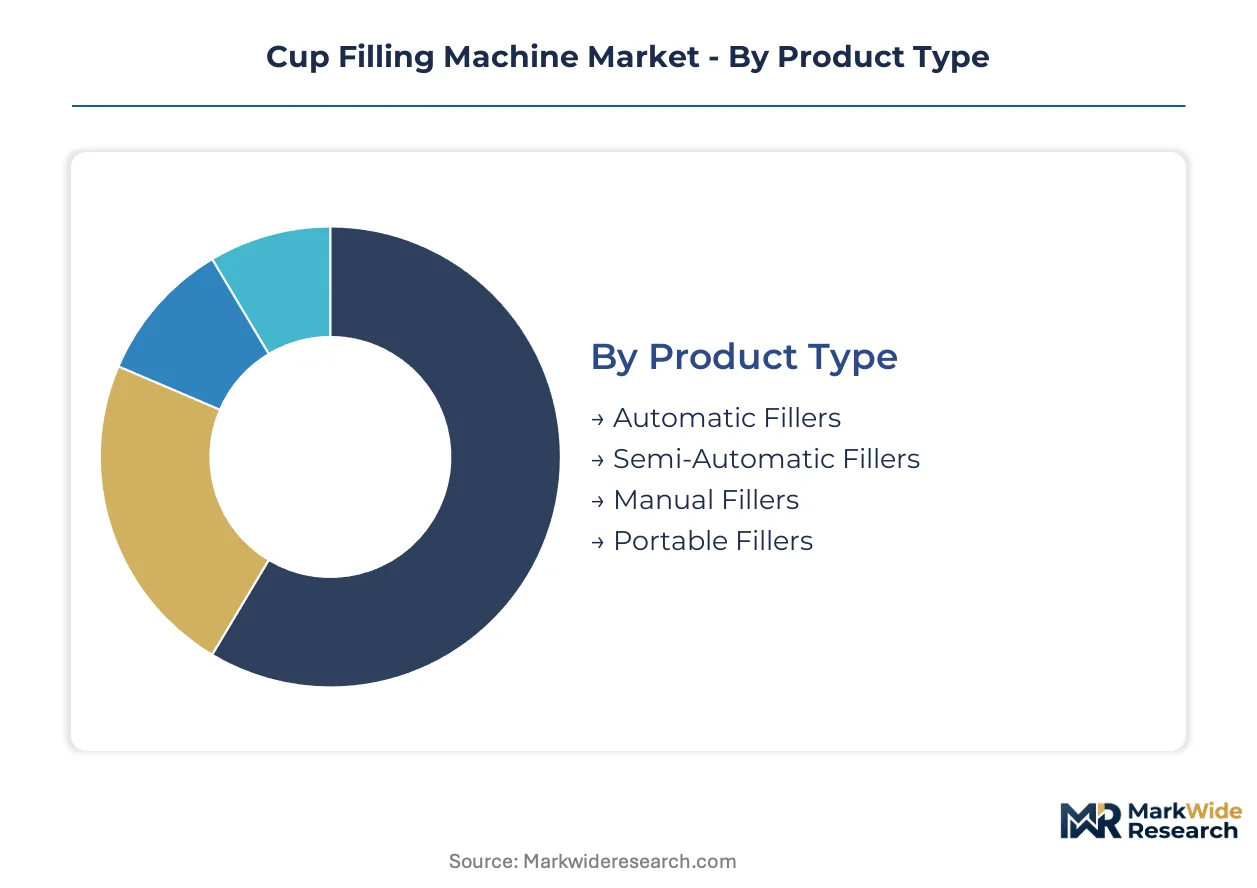
Cup filling machine procurement patterns diverge sharply across product tiers and end-use applications. Capital allocation decisions hinge on hygiene certification requirements, throughput targets, and integration complexity with upstream packaging systems.
Product Type:
Automatic fillers demand the heaviest upfront capital outlays due to servo-driven motion systems, MES connectivity architectures, and clean-in-place validation protocols. Semi-automatic and manual configurations trade throughput for lower barrier-to-entry pricing.
- Automatic Fillers:Rotary and linear architectures with Allen-Bradley or Siemens PLC control dominate high-volume dairy installations. German ESL milk processors and Brazilian aseptic cooperatives specify these for 400+ units per minute with integrated checkweighing and foil sealing.
- Semi-Automatic Fillers:Pneumatic indexing tables with operator-assisted lidding suit mid-scale juice processors in emerging markets. Chinese SAMR hygiene enforcement is accelerating stainless-steel retrofits of these units in domestic yogurt plants.
- Manual Fillers:Benchtop volumetric pistons serve artisanal dairy and small-batch nutraceutical contract manufacturers.
- Portable Fillers:Mobile cart-mounted units with quick-change tooling address seasonal fruit-processing operations and pop-up beverage production.
Most installed capacity flows through automatic fillers. Expansion is steepest in semi-automatic configurations as emerging-market processors bridge manual methods and full automation.
End User:
Application-specific hygiene mandates reshape specification priorities across customer verticals. Pharmaceutical and food-grade installations converge on 316L stainless construction while cosmetics and household segments tolerate broader material latitude.
- Food & Beverage:Dairy cooperatives and ready-to-drink bottlers anchor volume demand. FDA 21 CFR Part 110 sanitary design rules and EU Machinery Directive guarding requirements drive specification in Wisconsin and Bavaria processing clusters.
- Pharmaceuticals:FDA 21 CFR Part 210/211 validated CIP/SIP protocols command premium positioning. Dual-use contract manufacturers in India and Germany are specifying servo-driven auger fillers for powder supplement dosing.
- Cosmetics:Cream and lotion viscosity handling with piston or peristaltic pump architectures.
- Household Products:Detergent and cleaning chemical filling with corrosion-resistant wetted parts.
Food and beverage commands the dominant installed base. Pharmaceutical applications are gaining share fastest as nutraceutical contract manufacturing scales validated production.
Functionality:
Product rheology determines dosing mechanism selection and drives divergence in capital intensity. Liquid systems leverage electromagnetic flowmeters while powder applications demand explosion-rated containment and dust collection.
- Liquid Filling:Electromagnetic flowmeters with AI-based foam detection are compressing giveaway margins in French high-speed yogurt production. Fruit-on-bottom cup lines specify these for single-point calibration protocols.
- Powder Filling:Servo-driven auger mechanisms with real-time checkweighing meet FDA 21 CFR Part 111 cGMP requirements. Nutraceutical contract manufacturers in the United States specify these for dose accuracy and dust containment.
- Granule Filling:Volumetric cup or weigh-fill systems for sugar, salt, and dry ingredient portioning.
- Paste Filling:Positive-displacement piston pumps for high-viscosity sauces and condiments.
Liquid filling anchors the majority of operational capacity. Powder filling is climbing the fastest as supplement and probiotic manufacturing scales precision dosing requirements.
Material Type:
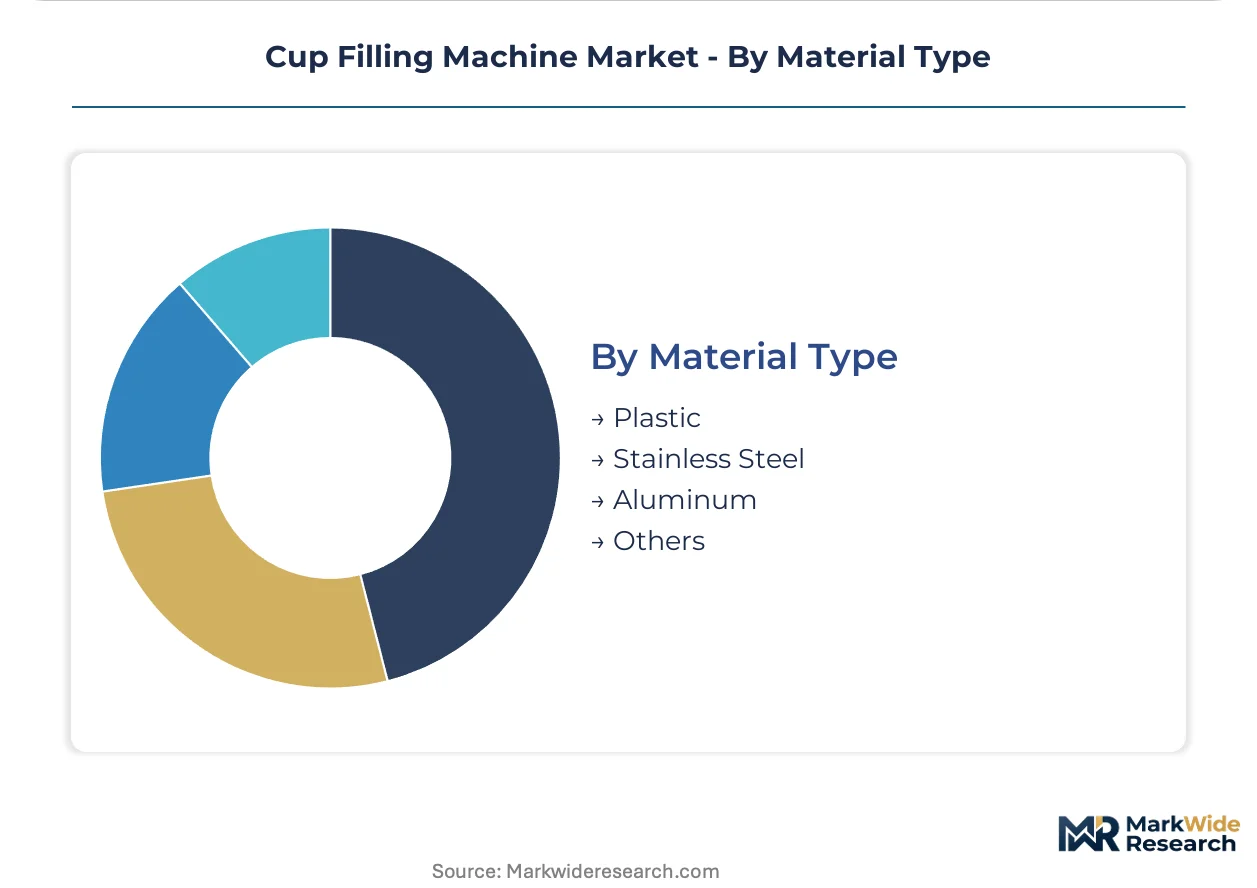
Surface finish specifications and corrosion resistance dictate material selection economics. Grade 316L stainless commands substantial premiums over plastic and aluminum alternatives but dominates regulated food and pharmaceutical environments.
- Stainless Steel:Grade 316L with IP65 washdown ratings and Ra 0.8 µm surface finish dominates dairy and pharmaceutical installations. EU Machinery Directive conformity and FDA food-contact rules effectively mandate this specification in Germany, France, and the United States.
- Plastic:Polypropylene and UHMW-PE housings suit low-acid beverage and cosmetics applications where cost sensitivity exceeds hygiene stringency.
- Aluminum:Anodized frames with stainless contact surfaces for mid-tier juice and water bottling.
- Others:Composite and coated carbon steel for non-food industrial applications.
Stainless steel represents the bulk of regulated-environment installations. Plastic configurations are expanding most quickly in emerging-market cosmetics and household product segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping equipment procurement as Brazilian and Indian processors exploit compliance-cost gaps against European and North American OEM pricing. Dairy cooperatives in lower-regulation jurisdictions are importing certified used lines from Germany and Wisconsin while domestic stainless-steel fabrication scales.
United States
Dairy Farmers of America and similar cooperatives are consolidating maintenance spend under multi-year OEM service agreements in Wisconsin and California processing clusters. FDA 21 CFR Part 110 sanitary design rules drive specification for Grade 316L stainless builds with IP65 washdown ratings. Greater Green Bay anchors high-volume ESL milk line installations where uptime guarantees determine vendor selection.
Germany
Bavarian dairy processors are retrofitting aseptic rotary fillers to reduce cold-chain dependency and expand retail distribution radius for extended shelf-life milk. EU Machinery Directive 2006/42/EC mandates CE-marked guarding and interlock systems for automated fillers. The Munich-Stuttgart corridor concentrates OEM engineering talent and hygienic welding certification capacity.
Brazil
Aseptic cooperatives in Minas Gerais and São Paulo states are capturing scale economies through fewer, larger automated lines while navigating ANVISA hygiene mandates. Grade 316L stainless price volatility constrains OEM margin stability and extends quotation validity periods for large dairy line contracts. The Campinas dairy cluster drives rotary filler demand for fruit-on-bottom yogurt production.
China
Domestic yogurt and probiotic plants are accelerating stainless-steel equipment replacement cycles under SAMR enforcement of GB standards mirroring Codex Alimentarius principles. The Yangtze River Delta and Pearl River Delta concentrate contract packaging hubs modernizing filling operations. Shanghai-based processors are specifying European hygiene certification for export-oriented dairy lines.
India
FSSAI enforcement of packaged food hygiene rules and cooperative sector consolidation is creating first-mover openings for automatic cup filling lines in Gujarat and Punjab milk unions. Servo motion programming and hygienic welding certification shortages are extending commissioning timelines for integrated rotary filler installations. The Anand dairy cooperative cluster represents the primary demand concentration for ESL retrofit projects.
Cup Filling Machine Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with dairy OEMs commanding premium positioning through validated CIP/SIP protocols while emerging-market fabricators compete on stainless-steel fabrication cost. The vendor base organizes around three archetypes: full-line systems integrators with MES connectivity expertise, regional stainless specialists serving mid-scale juice processors, and service-heavy incumbents monetizing installed base through predictive maintenance subscriptions. Consolidation is accelerating through multi-year maintenance agreement bundling and geographic expansion into Indian dairy cooperative modernization.
Among North American service-heavy incumbents, Barry-Wehmiller exemplifies the recurring-revenue archetype through remote diagnostics platforms and vibration-sensing spare-part subscriptions. Serac Group and Mespack SL occupy positions on the European hygiene-certification vector, with the former anchoring aseptic dairy line upgrades and the latter representing compact rotary filler specialization for emerging-market juice processors seeking European compliance. These three names illustrate how geographic origin and organizational structure map to distinct competitive positioning in a market where certification timelines and after-sales contract terms increasingly determine procurement outcomes.
| Leading Market Players |
|---|
| Paxiom Group |
| AMS Filling Systems |
| Serac Group |
| Volumetric Technologies |
| Frain Industries |
| Barry-Wehmiller |
| Cemre Cup Filling Machines |
| Mespack SL |
| R.A. Jones |
| Others |
Supply Flow & Price Mechanics
Grade 316L stainless steel price volatility propagates through equipment quotations as OEMs buffer margin risk with extended validity periods for dairy cooperative contracts in Wisconsin and Bavaria. Input cost uncertainty compresses tiered pricing spreads between automatic rotary fillers and semi-automatic configurations while procurement teams at Dairy Farmers of America negotiate multi-year service bundling to lock in aftermarket margins.
Pricing Analysis
Distributor margins on European hygiene-certified equipment widen against direct-to-OEM procurement in emerging markets. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked automatic fillers with MES connectivity from pneumatic semi-automatic units and manual benchtop configurations. Cost compression in mid-tier stainless-steel builds is intensifying because Brazilian and Indian fabricators scale domestic production. Contract packaging hubs in the Yangtze River Delta exhibit highest price sensitivity; validated pharmaceutical-grade installations in Germany show least.
Supply Chain Analysis
CE marking and FDA 21 CFR Part 110 qualification requirements gate supplier participation in regulated dairy and pharmaceutical segments. Manufacturing concentrates in Germany, China, and the United States for precision servo systems and hygienic welding capacity. Supply chains draw from Grade 316L stainless mills, Allen-Bradley/Siemens PLC distributors, and induction sealing module specialists. Single-source vulnerability around hygienic welding certification in India extends commissioning timelines. Distribution runs through OEM direct sales for large dairy cooperatives and regional distributors for mid-scale juice processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cup filling machine market compounds steadily as dairy cooperatives consolidate filling operations into fewer automated lines to capture scale economies and comply with tightening hygiene mandates.
For Market Incumbents: Cement recurring revenue streams through predictive maintenance SaaS platforms and multi-year service agreements that lock in spare-part subscriptions at high-volume dairy installations. Defend against flexible pouch substitution by integrating downstream case-packing systems and offering turnkey line responsibility. Prioritize backward integration into stainless-steel fabrication to buffer Grade 316L price volatility. For New Entrants and Emerging Players: Capture first-mover positioning in Indian dairy cooperative modernization where FSSAI enforcement creates demand for automatic cup filling lines and servo motion talent scarcity delays incumbent deployments. Target semi-automatic stainless-steel retrofits in Chinese domestic yogurt plants facing SAMR hygiene acceleration. Lead with European hygiene certification as a differentiated go-to-market anchor for export-oriented processors in Shanghai and Campinas. For Investors and Strategic Acquirers: Roll-up economics work for regional stainless specialists with hygienic welding certification because OEM service contract unbundling by cooperative procurement groups creates fragmentation for consolidation. Five-to-ten year viability rests on installed base monetization shifting from equipment finance to outcome-based uptime guarantees. Monitor predictive maintenance platform adoption rates at Dairy Farmers of America as the inflection signal for recurring revenue model maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Fabrication | Mitigates Grade 316L price volatility exposure for large dairy line contracts in Germany and Brazil. |
| Predictive Maintenance SaaS Launch | Barry-Wehmiller's vibration-sensing platform demonstrates recurring revenue potential anchored to high-volume installations. |
| CE Marking Acceleration for Indian Exports | EU Machinery Directive compliance unlocks European dairy retrofit demand for emerging-market fabricators. |
| Pharmaceutical-Grade Crossover Certification | FDA 21 CFR Part 210/211 validation enables dual-use contract manufacturing facility targeting in India and Germany. |
| Modular Filler Architecture Development | Machine learning-enabled vision inspection compresses changeover times for French high-speed yogurt producers. |
Methodological Framework
Coverage spans North America, Europe, Asia-Pacific, and Latin America, with primary inputs from each region combined with secondary validation. Interviews with dairy plant engineers, OEM procurement teams, aftermarket service heads, and contract manufacturing executives informed demand-side dynamics. Secondary sources include FDA 21 CFR filings, EU Machinery Directive conformity databases, SAMR GB standard publications, and customs trade records for stainless-steel equipment. Bottom-up unit economics triangulated against top-down market sizing across product tiers.
Granularity-level modeling operated at product type, end user, functionality, and material type dimensions with regional regulatory cluster overlays. CAGRs derived from segmented growth rate reconciliation against macro dairy processing capacity expansion indicators. Forecast inputs incorporated ESL dairy retrofit pipeline data from Bavaria and Minas Gerais, plus nutraceutical contract manufacturing capacity announcements in the United States and India.
Underlying measurement precision varies by segment; automatic filler shipments carry tighter precision than manual configurations due to OEM disclosure practices. Forecasts reflect documented assumptions on stainless-steel price trajectory and regulatory enforcement timelines. A model refresh is warranted upon material change in FSSAI or SAMR hygiene rule implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Soap Stamping Machine Market
Packaging Machinery
Plastic Extruding Equipment Market
Packaging Machinery
Box Filling Machine Market
Packaging Machinery
Robotic Carton Loading Machine Market
Packaging Machinery
Capping Machine Market
Packaging Machinery
Piston Fillers Market
Packaging Machinery
Wraparound Case Packers Market
Packaging Machinery
Post Press Machine Market
Packaging Machinery
Folding Gluing Machines Market
Packaging Machinery
Slitter Rewinder Machines Market
Packaging Machinery
Autofill Drums & Totes Machines Market
Packaging Machinery
Plastic Blow Molding Machine Market
Packaging Machinery
Precision Dispensing Machine Market
Packaging Machinery
Oil Packing Machine Market
Packaging Machinery
EPS Pre-Expander Machines Market
Packaging Machinery
Cling Wrap Machine Market