
 Paper Embossing Machine Market | 2026-2036
Paper Embossing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Embossing Machine Market Analytics
EU Green Deal packaging sustainability targets is hardening specifications for recyclable and fiber-based decorative materials across European converters. Bobst Group leverages its rotary embossing platform dominance to anchor premium packaging lines for cosmetics and spirits brands. Windmöller & Hölscher sustains technology leadership through in-house production of precision embossing cylinders and integrated inline systems. Comexi Group differentiates via digital workflow integration that reduces makeready waste on complex multi-substrate jobs.
A paper embossing machine mechanically deforms paper or board substrates using engraved dies or rollers to create raised or recessed patterns without ink application, typically operating at pressures between 50 and 500 tons depending on substrate caliper and pattern depth. These systems serve primarily to enhance tactile aesthetics, brand differentiation, and perceived value in packaging, stationery, and security document applications. Automatic machines capture the dominant installed base among high-volume packaging manufacturers, while digital embossing represents the fastest-expanding segment as converters chase lot-size-one flexibility for personalized greeting cards and limited-edition decorative items. Heat transfer technology occupies the largest technology share due to its established reliability on coated stocks, though laser die methods are gaining traction in artisan and prototyping end user segments where toolless setup commands premium pricing.
REACH chemical restrictions and CE machinery safety directives shape European equipment specifications, while China's GB standards and SAMR quality certifications govern import eligibility for foreign-built embossing systems. The US EPA and OSHA frameworks influence solvent-based release coating formulations and operator safety enclosures on heat transfer installations. Stakeholders must monitor evolving extended producer responsibility schemes and decide whether to retrofit existing mechanical platforms or migrate to digital architectures before regulatory compliance costs escalate.
Market Dynamics
Digital embossing architectures are compressing lot-size economics and eroding the rotary platform's lock on high-mix decorative production, forcing incumbents to recalibrate service models around toolless setup capabilities.
Growth Catalysts
- EU Green Deal packaging rules:Tightening material specifications for recyclable fiber-based substrates are expanding embossed paper capacity at luxury packaging houses in France and Germany.
- Heat transfer technology reliability:Established performance on coated stocks sustains dominant installed base among high-volume packaging manufacturers seeking consistent tactile output.
- Zhejiang packaging belt concentration:China's industrial cluster density creates localized demand aggregation for automated embossing systems serving export-oriented decorative board producers.
Market Restraints
- Precision embossing cylinder supply concentration:In-house production capabilities at Windmöller & Hölscher and limited qualified suppliers create bottleneck risk for converters dependent on engraved tooling.
- REACH chemical restrictions on release coatings:Solvent-based formulations face reformulation costs and performance uncertainty during transition to compliant alternatives.
- Laser die technology substitution ceiling:Premium pricing and throughput limitations constrain adoption beyond artisan prototyping segments despite toolless advantages.
Strategic Opportunities
- Baden-Württemberg printing cluster digital retrofit:Rotary-dominant infrastructure presents upgrade pathway for inline workflow integration and makeready waste reduction.
- Security document application expansion:Tactile authentication features create specification pull from government and financial issuance authorities.
- Extended producer responsibility scheme alignment:Early architecture migration to digital platforms before compliance cost escalation captures regulatory positioning advantage.
Industry Challenges
- CE machinery safety directive certification timelines:Operator enclosure and pressure-guarding redesign cycles delay European market entry for heat transfer system upgrades.
- Legacy mechanical platform integration complexity:Digital workflow architectures require control system overhaul and operator retraining at established rotary-dominant converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Embossing Machine Market |
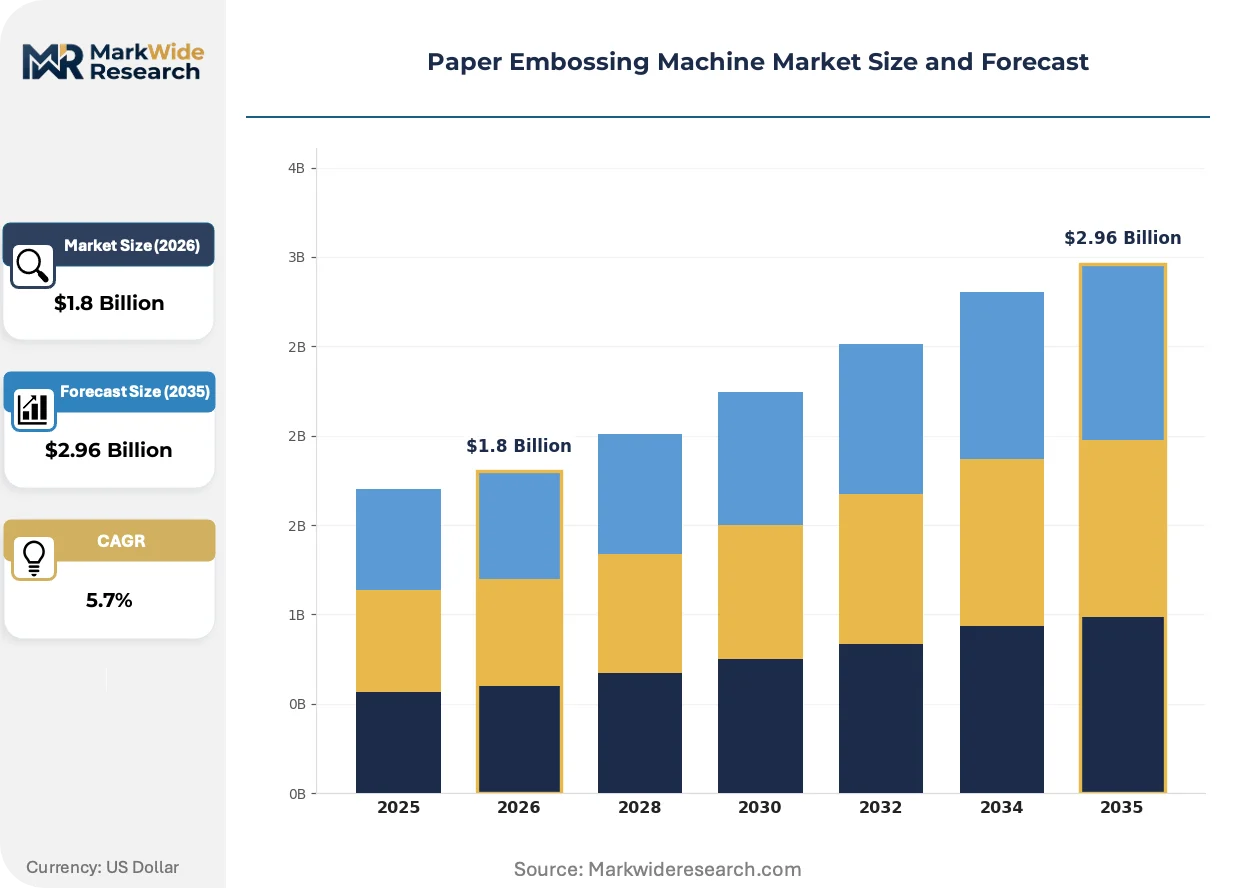
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Semi-Automatic, Automatic, Digital Application: Greeting Cards, Packaging, Stationery, Decorative Items End User: Manufacturers, Artisans, Retailers, Hobbyists Technology: Heat Transfer, Cold Foil, Laser, Laser Die |
| Companies Covered | Comexi Group, Nilpeter, Bobst Group, Henghao Machinery Co., Ltd., Gallus Group, Windmöller & Hölscher, Uteco Converting, Edale Ltd., Mark Andy Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Embossing Machine Market Evolving Landscape
Active transformation centers on the collision between toolless digital architectures and precision mechanical tooling, with regulatory material mandates and compressed order cycles accelerating platform replacement decisions across converter bases.
Laser die embossing is consolidating prototyping and artisan production segments by eliminating engraved cylinder lead times and enabling same-day pattern changes. Small-batch decorative stationery producers in Germany and limited-edition greeting card houses adopt this capability to serve personalized order flows. The technology is consolidating makeready economics around lot-size-one flexibility while compressing the addressable market for short-run rotary services.
REACH chemical restrictions and CE machinery safety directives are hardening equipment specifications across European converter installations. Release coating reformulations face performance validation gaps during solvent-to-water transitions. Heat transfer system manufacturers serving cosmetics and spirits packaging lines in France and Germany absorb redesign costs for operator safety enclosures ahead of enforcement windows.
Service unbundling from hardware procurement is restructuring converter vendor relationships in China's Zhejiang packaging belt. After-sales contracts separate from initial equipment purchase, with maintenance and cylinder resupply negotiated on consumption-based terms. This pattern is most visible among export-oriented board producers managing currency exposure through operational expenditure preference.
Paper Embossing Machine Market Segmentation
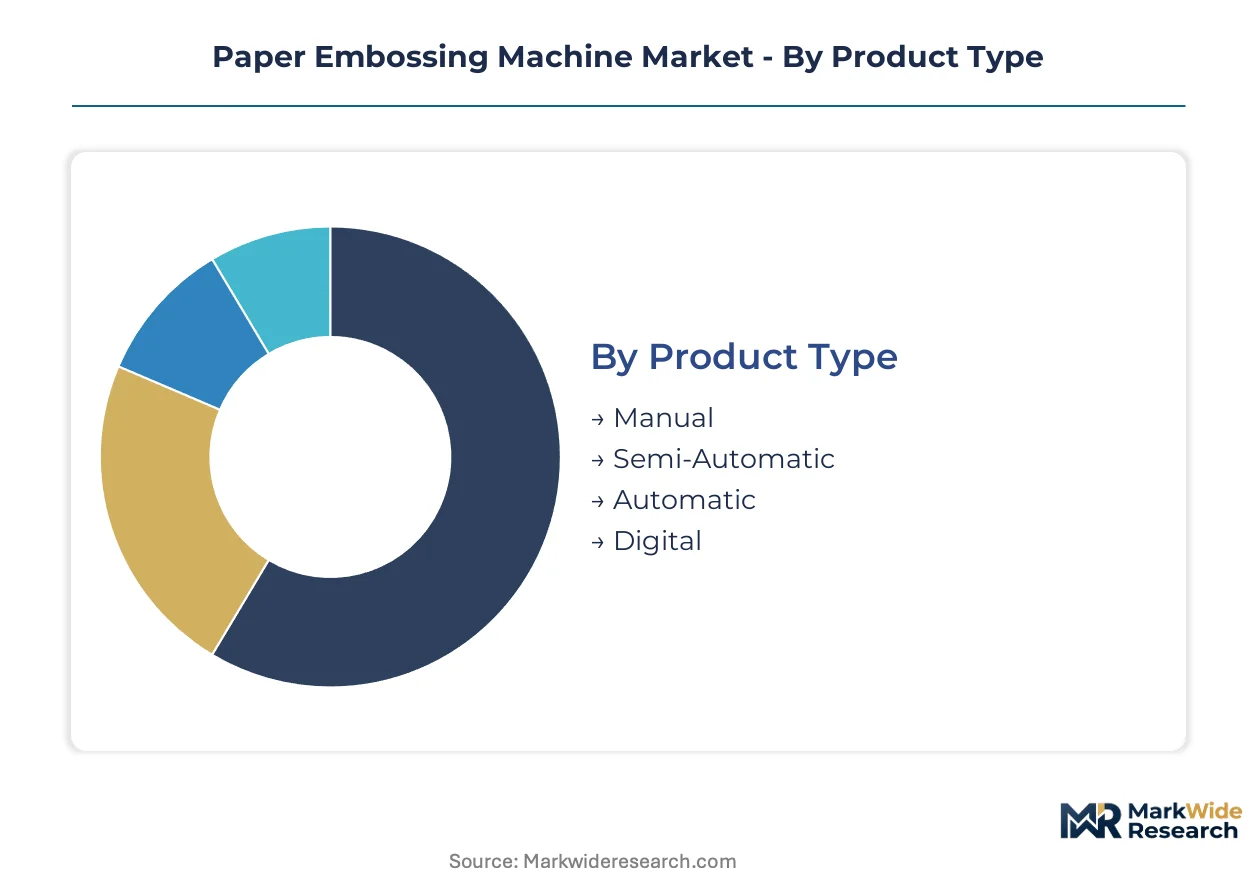
Paper embossing machine segmentation reveals divergent capital requirements across automation tiers and technology architectures. Converters align procurement decisions with lot-size economics, regulatory compliance horizons, and substrate versatility demands.
Product Type:
Capital intensity escalates sharply across automation tiers, with digital platforms demanding the highest upfront investment but compressing per-unit tooling costs.
- Automatic:These systems integrate inline feeding, pressure modulation, and quality inspection at operating pressures between 50 and 500 tons. Germany's Baden-Württemberg printing cluster sustains dominant installed base among high-volume packaging manufacturers seeking consistent tactile output on coated stocks.
- Digital:Toolless architectures eliminate engraved cylinder procurement and enable same-day pattern changes through software-defined pressure control. Demand concentrates among limited-edition decorative stationery producers in Germany and personalized greeting card houses chasing lot-size-one flexibility.
- Manual:Hand-cranked presses serve artisan prototyping and educational institutions with minimal capital outlay.
- Semi-Automatic:Hybrid configurations balance operator intervention with powered pressure application for mid-volume converters.
Most installed capacity flows through Automatic systems. Expansion is steepest in Digital as converters recalibrate around compressed order cycles.
Application:
Margin profiles vary by application based on substrate complexity, authentication requirements, and brand premium capture potential.
- Packaging:Luxury cosmetics and spirits brands in France and Germany specify embossed tactile features to differentiate shelf presence. EU Green Deal packaging rules tighten material specifications for recyclable fiber-based substrates, expanding capacity investment at European converters.
- Greeting Cards:Personalized order flows and seasonal volume spikes favor digital embossing adoption. Small-batch producers leverage laser die capabilities to serve same-day customization demands without cylinder lead times.
- Stationery:Corporate identity systems and premium writing paper sustain rotary platform dominance for standardized repeat patterns.
- Decorative Items:Artisan and limited-edition production segments tolerate lower throughput for design flexibility.
Packaging commands the largest revenue pool. Greeting Cards is expanding most quickly as digital workflows penetrate consumer personalization markets.
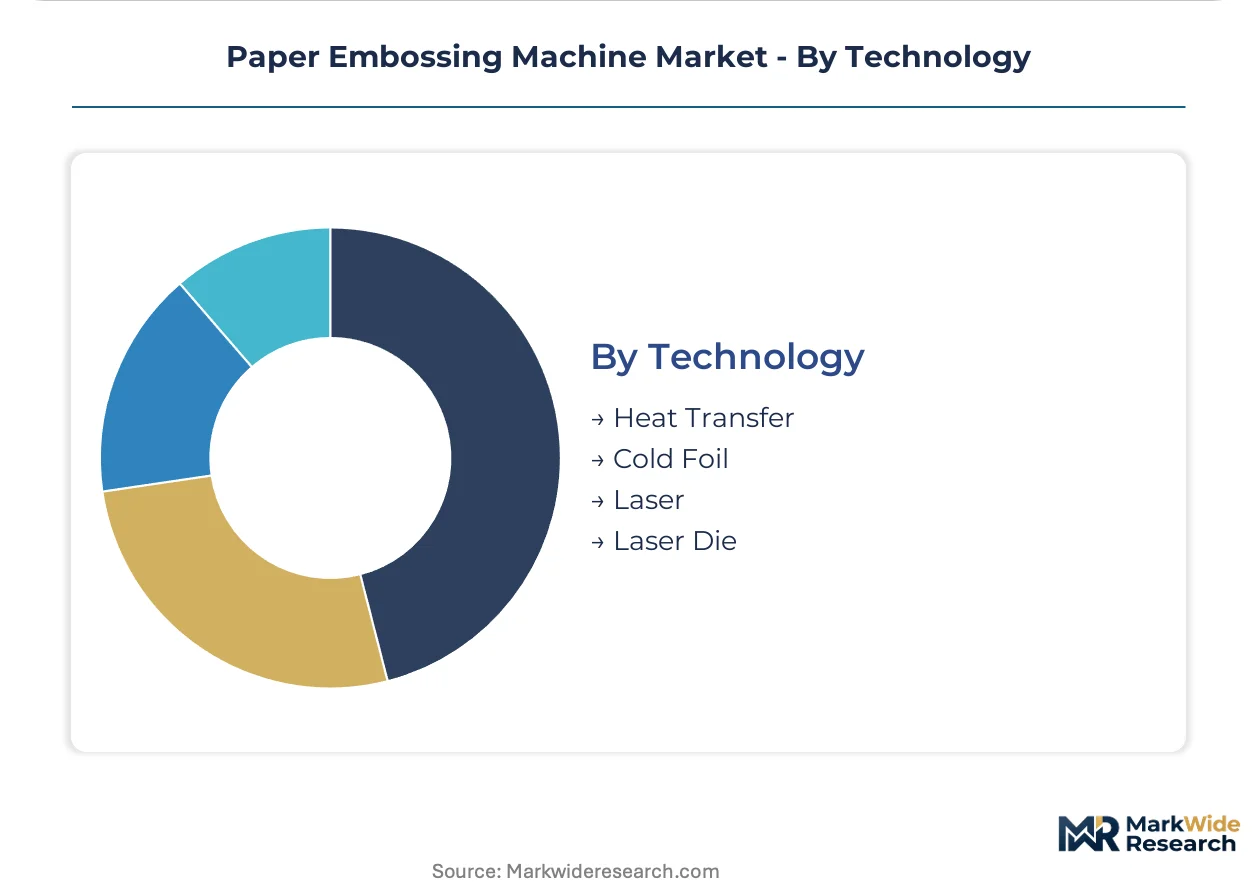
Technology:
Supply concentration for precision components shapes technology selection and total cost of ownership calculations.
- Heat Transfer:Established reliability on coated stocks sustains dominant technology share among high-volume manufacturers. CE machinery safety directives and REACH chemical restrictions on solvent-based release coatings are forcing redesign cycles for operator enclosures and formulation transitions.
- Laser Die:Toolless setup eliminates engraved cylinder dependency and enables pattern changes without physical tooling. Artisan prototyping segments absorb premium pricing for throughput limitations in exchange of design agility.
- Cold Foil:Metallic transfer without thermal activation serves temperature-sensitive substrates in specialty packaging.
- Laser:Direct substrate ablation creates recessed patterns for security document applications requiring tactile authentication features.
Heat Transfer retains the largest installed base. Laser Die is gaining share fastest in high-mix, short-run decorative production.
End User:
Procurement authority and technical specification complexity diverge sharply across buyer categories.
- Manufacturers:High-volume packaging and board producers in China's Zhejiang belt negotiate consumption-based service contracts separating maintenance and cylinder resupply from initial equipment purchase. Currency exposure management drives operational expenditure preference among export-oriented converters.
- Artisans:Individual practitioners and small studios prioritize capital accessibility and pattern customization over throughput metrics.
- Retailers:Private-label packaging programs and in-store customization services create specification pull for compact digital systems.
- Hobbyists:Entry-level manual and semi-automatic units serve craft market demand with minimal technical support requirements.
Manufacturers deploy the majority of system capacity. Retailers are climbing the fastest as brand owners internalize packaging differentiation capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paper embossing machinery originated in European printing centers during the nineteenth century, with German and Swiss engineering traditions establishing precision rotary platforms that still dominate high-volume packaging lines across the continent.
Germany
Luxury cosmetics and spirits brands in Baden-Württemberg and Bavaria specify embossed tactile features for shelf differentiation. REACH chemical restrictions and CE machinery safety directives force redesign cycles for solvent-based release coatings and operator enclosures. The Stuttgart printing cluster anchors rotary-dominant infrastructure now facing digital retrofit pressure.
China
Export-oriented decorative board producers in Zhejiang province aggregate demand for automated systems serving international packaging contracts. GB standards and SAMR quality certifications govern import eligibility for foreign-built embossing equipment. The Wenzhou packaging belt drives consumption-based service contracts separating maintenance from capital expenditure.
France
Paris-based luxury packaging houses expand embossed paper capacity ahead of EU Green Deal enforcement windows. ECHA oversight of chemical formulations tightens material specifications for recyclable fiber-based substrates. The Île-de-France cosmetics corridor concentrates specification authority for premium tactile finishes.
United States
Cosmetics and spirits brands in New Jersey and California specify embossed security features for authentication. EPA frameworks influence solvent-based release coating formulations on heat transfer installations. The Chicago-Milwaukee printing corridor sustains rotary platform dominance for standardized repeat patterns.
Italy
Milan and Turin packaging specialists serve European fashion and luxury goods brands with high-fidelity embossing. CE marking requirements and extended producer responsibility schemes shape equipment procurement timelines. The Lombardy converting belt integrates inline quality inspection for coated stock applications.
Paper Embossing Machine Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent technology architectures. The installed base concentrates among rotary platform specialists with in-house cylinder production capabilities, while digital entrants erode lock-in through toolless setup economics. Three archetypes dominate: precision tooling fabricators with captive engraving capacity, integrated inline system providers, and software-defined digital workflow specialists. Consolidation pressure favors backward integration into precision components and strategic partnerships around consumables resupply.
Among Swiss and German engineering houses, Bobst Group and Windmöller & Hölscher occupy positions anchored by rotary platform heritage and precision cylinder fabrication. Zhengzhou-based Henghao Machinery Co., Ltd. exemplifies the Chinese fabrication tier serving export-oriented converters through cost-optimized automatic systems. These three represent divergent competitive vectors: European precision tooling dominance, integrated inline architecture control, and scale-driven emerging market supply.
| Leading Market Players |
|---|
| Comexi Group |
| Nilpeter |
| Bobst Group |
| Henghao Machinery Co., Ltd. |
| Gallus Group |
| Windmöller & Hölscher |
| Uteco Converting |
| Edale Ltd. |
| Mark Andy Inc. |
| Others |
Value Network & Pricing Analysis
EU Green Deal packaging sustainability mandates gate both qualified supply and premium-tier pricing access, as converters must demonstrate compliant fiber sourcing and recyclable substrate compatibility to serve luxury cosmetics and spirits brands in France and Germany. This regulatory filter segments the vendor base between certified system providers commanding premium positioning and non-compliant fabricators facing downstream exclusion.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates equipment procurement, with premium tiers capturing CE-certified automatic systems with integrated inline workflows while economy tiers serve manual presses for artisan prototyping. Price differentiation rests on certification grade and after-sales service bundling, with REACH-compliant release coating formulations commanding sustained premiums. Cost compression in mid-tier rotary platforms is intensifying because digital toolless alternatives erode cylinder resupply economics. Hobbyists and educational institutions exhibit highest price sensitivity; luxury packaging houses in Baden-Württemberg demonstrate lowest sensitivity due to brand premium capture requirements.
Supply Chain Analysis
China's GB standards and SAMR quality certifications are reshaping sourcing for foreign-built embossing systems, compelling European and Swiss engineering houses to establish localized assembly partnerships or absorb extended certification timelines. Precision embossing cylinder fabrication concentrates in Germany and Switzerland, with engraved tooling supply anchored in Windmöller & Hölscher's in-house production and limited qualified secondary suppliers. Raw material dependencies span hardened steel alloys for cylinder engraving, specialty release coatings subject to REACH reformulation, and precision pressure-modulation components. Single-source vulnerability around qualified cylinder suppliers creates bottleneck risk for converters scaling embossed paper capacity. Distribution runs through direct OEM sales for large manufacturers and regional distributor networks serving mid-volume converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Paper embossing machinery represents a late-cycle quality story as EU Green Deal enforcement hardens material specifications and luxury brands prioritize tactile differentiation over cost minimization. This demand-shift toward premium specifications rewards vendors with certified sustainable architectures and precision tooling heritage.
For Market Incumbents: Anchor rotary platform dominance through backward integration into precision embossing cylinder production, eliminating supplier dependency that constrains converter scaling timelines. Invest in CE machinery safety directive pre-certification for heat transfer system upgrades ahead of enforcement windows, converting regulatory redesign cycles into competitive moats against emerging digital entrants.
For New Entrants and Emerging Players: Regional distributor partnerships in China's Zhejiang packaging belt offer the most penetrable channel architecture, as export-oriented board producers preference consumption-based service contracts over capital-heavy direct procurement. Target laser die digital workflows for artisan prototyping segments in Germany where toolless setup commands premium pricing and established rotary vendors underinvest in short-run flexibility.
For Investors and Strategic Acquirers: Roll-up economics work for precision tooling fabricators with captive engraving capacity because cylinder supply concentration creates pricing power and recurring resupply revenue streams. Five-to-ten-year viability hinges on regulatory positioning advantage as extended producer responsibility schemes escalate compliance costs for mechanical platforms. Monitor digital architecture adoption rates among Baden-Württemberg converters as inflection indicator for platform replacement cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Architecture Migration | Toolless laser die platforms capture lot-size-one flexibility in German greeting card personalization markets. |
| Precision Cylinder Backward Integration | In-house engraving capacity eliminates supplier bottlenecks and secures recurring resupply revenue from rotary-dependent converters. |
| CE Pre-Certification Investment | Early operator enclosure redesign captures market entry timing ahead of REACH chemical restriction enforcement. |
| Consumption-Based Service Contracts | Operational expenditure preference among Zhejiang exporters reduces currency exposure and extends customer lifetime value. |
| Security Document Application Expansion | Tactile authentication features create specification pull from government issuance authorities with long-term contract visibility. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers at packaging converters, procurement leads at luxury cosmetics brands, aftermarket service heads at OEMs, and technical R&D directors at precision tooling fabricators with secondary validation against customs trade data, machinery safety directive filings, and SEC disclosures from listed equipment manufacturers. Bottom-up demand aggregation across automation tiers and top-down supply-side capacity assessment were cross-referenced for convergence.
Historical reference periods anchored the projection horizon to observed replacement cycles and regulatory enforcement timelines, with segmentation modeling across automation level, technology architecture, application category, and regional production cluster. CAGRs were derived from installed base turnover rates and digital adoption curve inflection patterns, incorporating embossing pressure requirements by substrate caliper and pattern depth as industry-specific demand drivers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal material specification evolution and digital platform cost-performance trajectories. Forecasts reflect documented assumptions about regulatory enforcement timing and converter capital allocation priorities. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Bakery Packaging Machine Market
Packaging Machinery
Cup Fill and Seal Machine Market
Packaging Machinery
Beverage Can Seamers Market
Packaging Machinery
Wet Ink Coding Machines Market
Packaging Machinery
Tray and Sleeve Packing Machines Market
Packaging Machinery
Post Press Machine Market
Packaging Machinery
Cigarette Packaging Machine Market
Packaging Machinery
Foil Embossing Machine Market
Packaging Machinery
Shrink - Sleeve Wrapping Machinery Market
Packaging Machinery
Lidding Machines Market
Packaging Machinery
Sack Fillers Market
Packaging Machinery
Auger Powder Filling Machines Market
Packaging Machinery
Tube Sealing Machines Market
Packaging Machinery
Clamshell Labeling Machines Market
Packaging Machinery
Tissue Paper Unwinding Machine Market
Packaging Machinery
Global Filling Machines Market