
 Blow Fill Seal (BFS) Technology Market | 2026-2036
Blow Fill Seal (BFS) Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Blow Fill Seal (BFS) Technology Market Outlook
Polyethylene is expanding its share in BFS container production as converters seek lower-temperature processing economics and improved moisture barrier performance versus legacy glass alternatives. Rommelag AG leverages its five-decade equipment heritage to dominate high-speed rotary BFS system supply. Catalent Inc. sustains one of the largest contract BFS manufacturing footprints across North American and European pharmaceutical corridors. Weiler Engineering Inc. specializes in custom-engineered linear BFS machines for niche fill volumes and specialized polymer formulations.
Blow Fill Seal technology constitutes an automated aseptic packaging process where thermoplastic resin is extruded into a parison, formed into a container, filled with liquid product, and hermetically sealed in a single continuous operation within a classified cleanroom environment, typically achieving contamination rates below one per million units. The process eliminates human intervention during critical sterile phases, satisfying the most stringent pharmaceutical parenteral and ophthalmic dosing requirements. Ampoules and vials capture the dominant volume share within product type segmentation, driven by unit-dose ophthalmic and respiratory therapy formats where sterility assurance levels must meet EU GMP Annex 1 and FDA guidance thresholds. Pharmaceutical applications command the largest application segment, though nutraceuticals represent the fastest-growing demand pool as probiotic and liquid supplement brands adopt BFS for shelf-life extension without preservative systems. Contract manufacturers occupy a pivotal end-user position, consolidating fill-finish outsourcing decisions that directly determine BFS equipment investment cycles.
The FDA enforces current Good Manufacturing Practice standards for sterile drug products through its Center for Drug Evaluation and Research, while the European Medicines Agency coordinates EU GMP Annex 1 implementation across member state competent authorities, with both frameworks now mandating enhanced contamination control strategies for aseptic processing. ISO 13485 and ISO 15378 quality management standards govern BFS equipment qualification and pharmaceutical packaging material traceability, creating compliance cost barriers that favor established suppliers with validated quality systems. Stakeholders must monitor evolving polymer recycling regulations and bio-based feedstock certification schemes, as sustainability criteria increasingly penetrate pharmaceutical procurement specifications and supplier qualification protocols.
Market Dynamics
The FDA's updated sterile manufacturing guidelines and EU GMP Annex 1 revisions are forcing pharmaceutical manufacturers to eliminate human intervention from aseptic processing, accelerating capital redeployment toward closed-system BFS infrastructure.
Growth Catalysts
- EU GMP Annex 1 revisions:The European Medicines Agency's contamination control mandates now require continuous monitoring systems that BFS technology natively provides, compelling fill-finish facility upgrades across EU member states.
- Unit-dose ophthalmic formats:Preservative-free eye care products require hermetic single-use packaging that BFS ampoules deliver without secondary sterilization steps.
- Probiotic liquid supplements:Nutraceutical brands are adopting BFS to achieve shelf-life extension without chemical preservatives, opening new demand pools beyond traditional pharmaceutical applications.
Market Restraints
- High-purity polymer feedstock volatility:Medical-grade polyethylene and polypropylene resin prices fluctuate with crude oil derivatives, compressing converter margins during energy price spikes.
- Equipment supply concentration:Advanced rotary BFS systems depend on specialized German and Swiss machinery suppliers, creating procurement bottlenecks during order surges.
- Glass vial substitution limits:Certain biologics and high-pH formulations still require borosilicate glass compatibility that standard BFS polymers cannot match.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO's push for domestic sterile production capacity creates openings for BFS equipment vendors to establish local technical service networks.
- Bio-based polymer certification:EU Green Deal procurement criteria are beginning to reward packaging with certified renewable feedstock content, favoring early BFS material innovators.
- Home healthcare respiratory therapies:Nebulizer solution unit-dose formats are migrating from multi-dose bottles to BFS ampoules for infection control in patient-administered settings.
Industry Challenges
- Cleanroom-qualified technician scarcity:BFS operation requires personnel certified in aseptic technique and polymer extrusion parameters, with training pipelines failing to match facility expansion rates.
- Legacy line integration complexity:Pharmaceutical manufacturers face validation burdens when connecting new BFS units to existing track-and-trace serialization infrastructure.
- ISO 15378 audit compression:Pharmaceutical packaging material suppliers face intensified certification renewal cycles that strain quality documentation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blow Fill Seal (BFS) Technology Market |
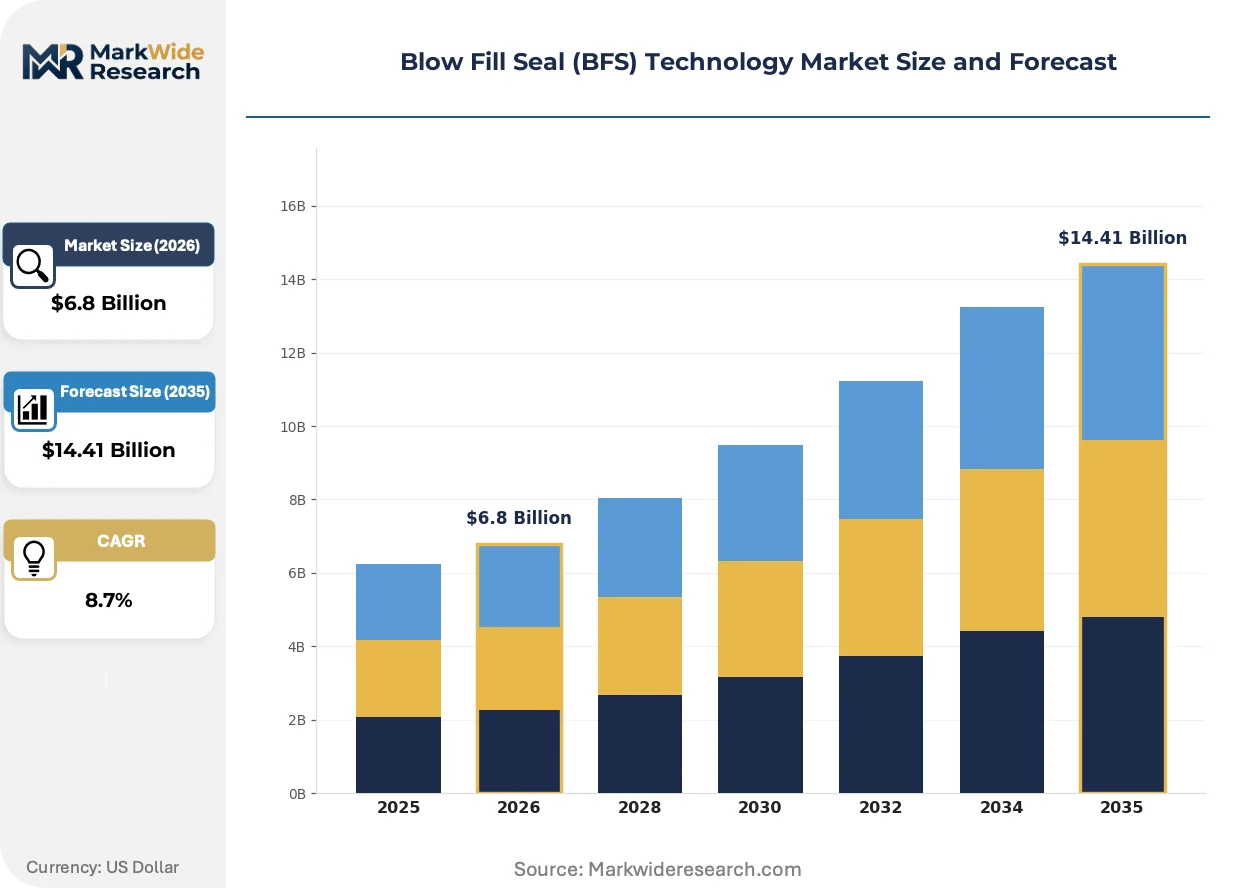
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ampoules, Bottles, Vials, Containers Application: Pharmaceuticals, Nutraceuticals, Cosmetics, Medical Devices End User: Hospitals, Pharmacies, Research Labs, Contract Manufacturers Material: Polypropylene, Polyethylene, PET, Others |
| Companies Covered | Unither Pharmaceuticals, Weiler Engineering Inc., Rommelag AG, Takeda Pharmaceuticals, The Ritedose Corporation, Catalent Inc., Recipharm AB, Nipro Corporation, Gerresheimer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blow Fill Seal (BFS) Technology Market Strategic Shifts
Automation architectures and material science advances are compressing cycle times while expanding the range of pharmaceutical formulations compatible with blow fill seal processing.
Multi-layer co-extrusion technology is absorbing moisture-sensitive and oxygen-sensitive drug categories previously excluded from BFS packaging. Ophthalmic manufacturers in Switzerland and Japan are deploying five-layer barrier structures for prostaglandin formulations. This capability expansion is absorbing market share from glass ampoules in high-value preservative-free segments.
REACH polymer registration requirements are forcing European BFS converters to document full supply chain substance composition. The European Chemicals Agency's expanded authorization list now covers several plasticizers common in medical packaging. German and French pharmaceutical packagers are responding by qualifying alternative resin grades ahead of sunset date deadlines.
Contract development and manufacturing organizations are consolidating fill-finish outsourcing decisions into fewer, larger-volume agreements. Small and mid-sized pharmaceutical innovators now access BFS capacity through platform partnerships rather than dedicated line investments. This concentration pattern is most pronounced in the Boston-Cambridge and Research Triangle pharmaceutical corridors.
Blow Fill Seal (BFS) Technology Market Segmentation
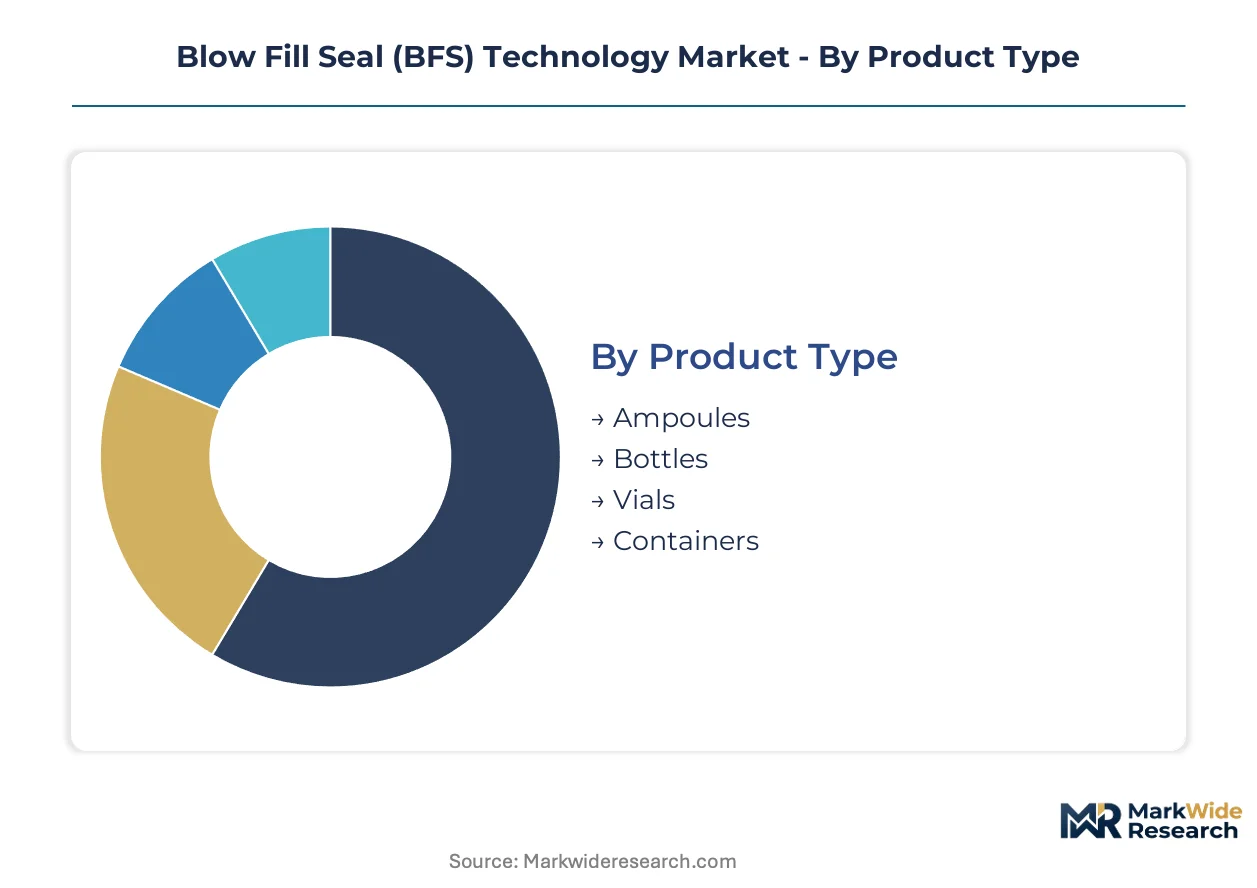
Blow Fill Seal technology serves distinct packaging needs across pharmaceutical, nutraceutical, and medical device sectors where aseptic integrity requirements vary by container geometry and end-use sterility thresholds. Segment boundaries reflect material compatibility constraints, regulatory validation burdens, and automation integration depth across fill-finish operations.
Product Type:
Ampoules and vials embed directly into high-speed rotary BFS systems for unit-dose pharmaceutical distribution, while bottles and larger containers often deploy in standalone linear configurations for multi-dose or bulk formats.
- Ampoules:Single-unit hermetic containers formed from extruded parison with tear-off neck designs. Demand concentrates in ophthalmic and respiratory therapy manufacturing across Germany and Switzerland, driven by EU GMP Annex 1 contamination control mandates for preservative-free formulations.
- Vials:Cylindrical containers with formed neck finishes accommodating standard closure systems. Research labs and hospital pharmacies in the United States favor these formats for parenteral compounding under FDA sterile processing guidance.
- Bottles:Larger-volume containers typically ranging above 100ml capacity. Nutraceutical brands adopt these for probiotic liquid supplements requiring shelf-life extension without chemical preservatives.
- Containers:Custom-profiled geometries for specialized medical device irrigation solutions and diagnostic reagents. Japanese ophthalmic manufacturers specify these for intraoperative balanced salt solutions.
Volume placements concentrate in ampoules; the faster expansion belongs to bottles.
Application:
Application segments stratify by sterility assurance level requirements and regulatory pathway complexity, with pharmaceutical formats commanding the most intensive validation protocols.
- Pharmaceuticals:Injectable, ophthalmic, and respiratory drug products subject to FDA Center for Drug Evaluation and Research oversight and EMA centralized marketing authorization. Contract manufacturers in Catalent's North American and European network anchor capacity deployment here.
- Nutraceuticals:Liquid dietary supplements and functional beverages where BFS eliminates preservative systems. German and French brands are qualifying bio-based polyethylene grades under EU Green Deal procurement criteria.
- Cosmetics:Preservative-free skincare ampoules and single-use serum formats. Swiss and Japanese beauty manufacturers specify multi-layer co-extrusion for oxygen-sensitive active ingredients.
- Medical Devices:Sterile irrigation solutions, wound care fluids, and diagnostic reagents. Hospital procurement in Saudi Arabia and the UAE is migrating from glass to BFS polymer formats under SFDA and MOHAP device registration pathways.
Pharmaceutical formats dominate installed base; nutraceuticals are climbing the fastest.
End User:
End user segments diverge by batch size requirements and in-house versus outsourced fill-finish economics, with contract manufacturers consolidating decisions that drive equipment investment cycles.
- Contract Manufacturers:CDMOs and specialized fill-finish providers operating validated multi-client BFS lines. The Boston-Cambridge and Research Triangle corridors concentrate platform partnership agreements for small and mid-sized pharmaceutical innovators.
- Hospitals:In-house compounding pharmacies preparing patient-specific parenteral formulations. US health systems face 503B outsourcing facility regulations that favor pre-sterilized BFS containers over traditional glass vial preparation.
- Pharmacies:Retail and specialty pharmacy chains dispensing unit-dose ophthalmic and respiratory therapies. German pharmacy networks specify Rommelag-format ampoules for prostaglandin eye drops.
- Research Labs:Clinical trial material manufacturing and stability testing operations. Weiler Engineering's custom linear systems serve niche fill volumes for early-phase biologic candidates.
Contract manufacturers absorb the largest equipment procurement volumes; research labs show steepest expansion trajectory for specialized polymer formulations.
Material:
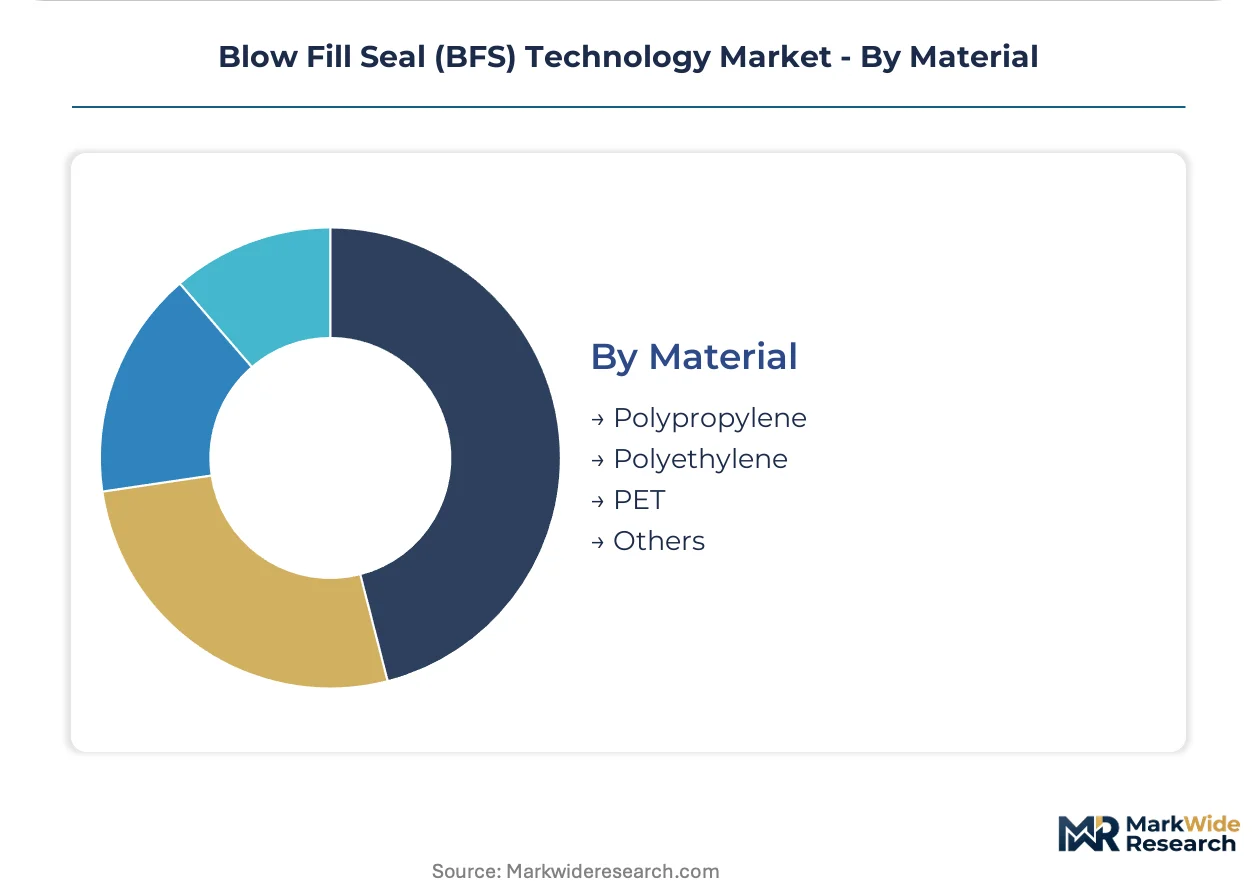
Material selection hinges on processing temperature economics, moisture barrier requirements, and evolving sustainability certification demands across pharmaceutical procurement specifications.
- Polyethylene:Lower-temperature processing resin with superior moisture barrier performance versus glass alternatives. Converters across Germany and France are accelerating qualification of bio-based grades ahead of ECHA authorization list sunset dates.
- Polypropylene:Higher thermal stability enabling steam sterilization compatibility and broader pharmaceutical formulation ranges. Medical-grade resin prices track crude oil derivative volatility, compressing converter margins during energy price spikes.
- PET:Transparent barrier material for oxygen-sensitive categories previously excluded from BFS packaging. Japanese ophthalmic manufacturers deploy five-layer co-extrusion structures incorporating PET layers for prostaglandin formulations.
- Others:Specialty polymers including cyclic olefin copolymers and bio-based alternatives. REACH polymer registration requirements force European converters to document full supply chain substance composition for these emerging grades.
Polyethylene commands current volume leadership; PET and bio-based alternatives are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical fill-finish capacity concentrates in Germany, Switzerland, and the United States, where regulatory stringency and contract manufacturing density drive BFS equipment deployment. Japan and India are expanding sterile production infrastructure to capture ophthalmic and respiratory therapy demand.
United States
FDA sterile processing guidance and 503B outsourcing facility regulations compel hospital systems toward pre-sterilized BFS containers. The Boston-Cambridge corridor concentrates platform partnership agreements for small and mid-sized pharmaceutical innovators seeking contract fill-finish capacity.
Germany
EU GMP Annex 1 contamination control mandates force fill-finish facility upgrades across member states. Rommelag AG anchors advanced rotary BFS system supply chains from Baden-Württemberg, serving preservative-free ophthalmic manufacturers throughout the Rhine-Main industrial cluster.
Switzerland
Swissmedic oversight of sterile drug products and prostaglandin formulation manufacturing drives multi-layer co-extrusion adoption. Basel-based pharmaceutical packagers specify five-layer barrier structures for oxygen-sensitive active ingredients in unit-dose formats.
Japan
PMDA marketing authorization pathways for preservative-free ophthalmic therapies accelerate BFS ampoule qualification. The Kanto region around Tokyo hosts ophthalmic manufacturers deploying advanced barrier technologies for intraoperative balanced salt solutions.
India
CDSCO's push for domestic sterile production capacity creates openings for BFS equipment vendors. Maharashtra and Gujarat pharmaceutical manufacturing zones are consolidating fill-finish outsourcing decisions that determine capital investment cycles in automated aseptic packaging.
Blow Fill Seal (BFS) Technology Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with equipment vendors and fill-finish service providers occupying distinct competitive tiers. German and Swiss machinery fabricators concentrate supply of advanced rotary systems, while North American and European contract manufacturers consolidate multi-client production capacity. Two strategic archetypes dominate: integrated equipment-to-service providers and pure-play contract development and manufacturing organizations. Competitive moves center on capacity expansion in high-growth pharmaceutical corridors and technology licensing agreements to penetrate emerging markets.
Within the integrated equipment tier, Rommelag AG and Weiler Engineering Inc. occupy positions spanning machinery fabrication and technical service networks. Catalent Inc. exemplifies the contract manufacturing archetype, anchoring fill-finish capacity across North American and European pharmaceutical corridors. These three entities represent the convergence of equipment heritage and production scale that defines competitive positioning in sterile liquid packaging.
| Leading Market Players |
|---|
| Unither Pharmaceuticals |
| Weiler Engineering Inc. |
| Rommelag AG |
| Takeda Pharmaceuticals |
| The Ritedose Corporation |
| Catalent Inc. |
| Recipharm AB |
| Nipro Corporation |
| Gerresheimer AG |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between ISO 15378-validated pharmaceutical packaging suppliers and unqualified converters manifests in both pricing power and supply chain access. EU GMP Annex 1 compliance investments create tiered procurement eligibility that pharmaceutical buyers enforce through supplier qualification protocols, while commodity resin traders operate outside these gated channels entirely.
Pricing Analysis
Volume-margins split sharply between high-speed rotary BFS equipment lines and custom-engineered linear configurations. Three-tier pricing structure across premium, standard, and economy levels reflects validation depth, with FDA-registered contract manufacturers commanding premiums over nutraceutical converters. Cost compression in standard-grade polyethylene resin supply is intensifying because crude oil derivative volatility compresses converter margins. Hospital compounding pharmacies exhibit highest price sensitivity; ophthalmic innovators demonstrate lowest sensitivity due to sterility assurance requirements.
Supply Chain Analysis
Single-source vulnerability sits with German and Swiss precision machinery fabricators for advanced rotary BFS systems. Medical-grade polyethylene and polypropylene resin supply draws from Saudi Arabia, South Korea, and the United States. Regulatory restriction risk intensifies as REACH polymer registration requirements force European converters to document full supply chain substance composition ahead of ECHA sunset dates. Distribution runs through pharmaceutical contract manufacturing organizations consolidating multi-client fill-finish capacity in the Boston-Cambridge and Research Triangle corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EU GMP Annex 1 contamination control mandates erect barrier-to-entry moats favoring validated incumbents with established quality documentation systems.
For Market Incumbents: Lock in multi-year platform partnership agreements with small and mid-sized pharmaceutical innovators before CDSCO's domestic sterile production push seeds Indian contract manufacturing competitors. Prioritize backward integration into bio-based polyethylene resin qualification under EU Green Deal procurement criteria to preempt sustainability-driven supplier switches.
For New Entrants and Emerging Players: Begin with nutraceutical liquid supplement applications where preservative-free shelf-life extension demand outpaces qualified BFS converter supply. Target probiotic and functional beverage brands in Germany and France seeking bio-based packaging certification; deploy technical service partnerships with Weiler Engineering-format linear systems to bypass rotary equipment procurement bottlenecks.
For Investors and Strategic Acquirers: Exit pathways concentrate in contract development and manufacturing organization roll-ups as fill-finish outsourcing decisions consolidate into fewer larger-volume agreements. Five-to-ten year viability favors vertically integrated equipment-to-service providers with validated quality systems across multiple regulatory jurisdictions. Monitor CDSCO domestic sterile production capacity announcements as inflection indicator for Indian market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-layer Co-extrusion Technology Deployment | Japanese ophthalmic manufacturers absorb oxygen-sensitive prostaglandin formulations previously excluded from BFS packaging. |
| Bio-based Polymer Certification Investment | German and French converters qualify renewable feedstock grades ahead of ECHA authorization list sunset deadlines. |
| Indian Technical Service Network Establishment | Maharashtra and Gujarat pharmaceutical zones require localized equipment support as CDSCO pushes domestic sterile capacity. |
| Home Healthcare Respiratory Format Migration | Nebulizer solution brands shift from multi-dose bottles to unit-dose BFS ampoules for patient-administered infection control. |
| Serialization Infrastructure Integration | Legacy line validation burdens ease when connecting new BFS units to existing track-and-trace systems in European corridors. |
Study Parameters
Independent corroboration across BFS equipment engineering directors, pharmaceutical regulatory affairs leads, contract manufacturing procurement officers, and polymer resin supply managers underwrites the qualitative findings. Primary interview data combined with FDA sterile processing guidance documents, EMA centralized marketing authorization submissions, EU GMP Annex 1 revision drafts, and ISO 15378 certification databases provided secondary validation. Bottom-up equipment installation tracking and top-down pharmaceutical packaging spend analysis enabled triangulation across modeling approaches.
Rate-of-change decomposition across the analysis window separated volume growth from value expansion by product type, application segment, end-user category, and material formulation compatibility. CAGRs were derived from installed base depreciation schedules and replacement demand cycles intersecting with regulatory-driven facility upgrade timelines. Modeled inputs included ophthalmic unit-dose format adoption curves and nutraceutical preservative-free packaging conversion rates.
Underlying measurement precision varies by segment; pharmaceutical applications with established FDA and EMA filing histories carry tighter precision than emerging nutraceutical categories. Forecasts reflect documented assumptions about regulatory implementation timelines and polymer feedstock price trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
North America Automatic Carton Erector Market
Packaging Machinery
Glazing Machine Market
Packaging Machinery
Puffer Machines Market
Packaging Machinery
Glue Machine Market
Packaging Machinery
Plastic Extruding Equipment Market
Packaging Machinery
Cosmetic Filling Machines Market
Packaging Machinery
Flow Pack Machine Market
Packaging Machinery
Pick Fill Seal Machines Market
Packaging Machinery
Global Food and Beverage Packaging Machinery Market
Packaging Machinery
Clamshell Labeling Machines Market
Packaging Machinery
Toilet Roll Converting Lines Market
Packaging Machinery
Post Press Machine Market
Packaging Machinery
In-Line Thermoforming Machine Market
Packaging Machinery
Tablet Packing Machine Market
Packaging Machinery
Thermal Laminating Machine Market
Packaging Machinery
Hardgel Liquid Capsule Filling Machines Market