
 Carpet Spot Remover Market | 2026-2036
Carpet Spot Remover Market Size, Share, and Industry Trends Forecast 2026-2036
Carpet Spot Remover Market Analysis
Leasing and rental-based equipment models is narrowing the capital barrier for mid-sized cleaning contractors seeking commercial-grade systems. Bissell leverages its direct-to-consumer channel strength to sustain recurring revenue from concentrated cleaning solutions. Hoover anchors its position through retail distribution density and private-label partnerships with home improvement chains.
Carpet spot remover denotes a targeted cleaning agent engineered to lift localized stains from synthetic or natural fiber substrates without full-surface extraction, typically formulated with surfactant blends, enzymatic catalysts, or oxygenated bleaches operating at pH ranges between 6.5 and 9.0 for fiber safety. The product serves residential consumers, commercial facilities, and automotive detailers requiring rapid remediation between deep-cleaning cycles. Foam formulations dominate residential impulse purchases due to controlled dispensing and reduced oversaturation risk, while enzymatic chemistry commands premium positioning in pet-stain segments where protein-specific breakdown drives repeat buying. Solvent-based variants retain industrial share where grease and oil contamination demands aggressive dissolution, though biodegradable alternatives are capturing contract-specified procurement from corporate sustainability mandates.
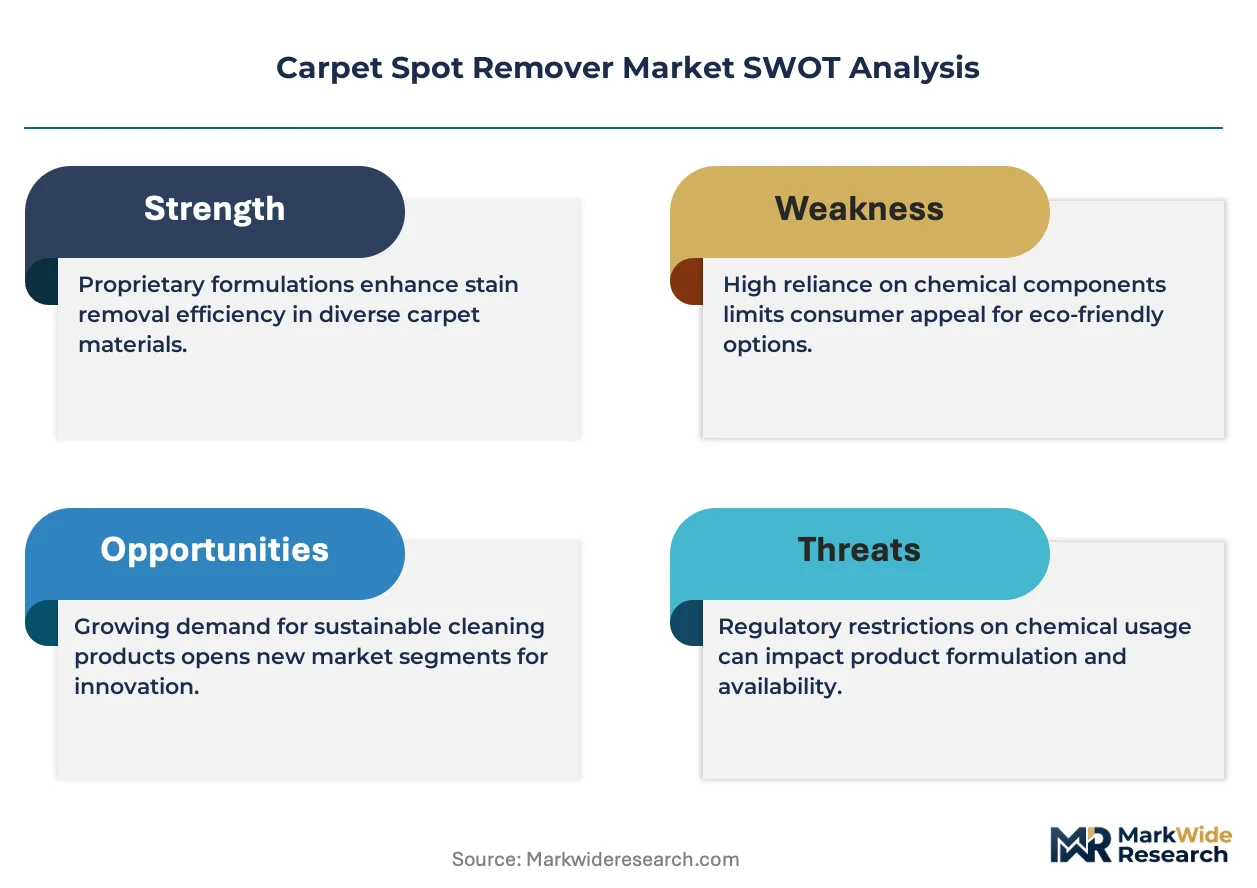
EPA Safer Choice standards and state-level VOC regulations in California and New York constrain permissible solvent concentrations and mandate ingredient disclosure, reshaping formulation pipelines toward low-emission chemistries. The Federal Trade Commission's Green Guides further govern environmental marketing claims, creating compliance costs that favor established suppliers with dedicated regulatory affairs functions. Stakeholders must monitor pending amendments to VOC limits and biobased content thresholds that will determine which formulation platforms retain shelf access across the largest state markets.
Market Dynamics
EPA Safer Choice standards and state-level VOC limits are compressing formulation pipelines toward low-emission chemistries, forcing suppliers to rebuild active ingredient portfolios or surrender shelf access in California and New York.
Growth Catalysts
- California Air Resources Board VOC limits:Facilities in Los Angeles and San Diego accelerate replacement cycles for compliant equipment, sustaining above-average demand for certified low-emission spot removal systems.
- Enzymatic catalyst technology:Protein-specific breakdown chemistry commands premium positioning in pet-stain segments, driving repeat purchasing among residential consumers with companion animals.
- Commercial hospitality procurement:Hotel renovation cycles in Florida, Nevada, and Texas sustain replacement rates for professional-grade carpet cleaning consumables ahead of peak tourism seasons.
Market Restraints
- Petrochemical feedstock volatility:Surfactant and solvent input costs fluctuate with crude oil indices, compressing margin stability for mid-tier formulation suppliers without long-term supply agreements.
- Concentrated supplier geography:Specialty enzyme production clusters in Denmark and the Netherlands create single-source risk for North American brands dependent on European catalyst imports.
- Technical performance ceiling:Oxygenated bleach chemistry cannot match solvent-based dissolution rates on heavy grease contamination, limiting penetration in industrial maintenance contracts.
Strategic Opportunities
- Biobased content thresholds:USDA BioPreferred program specifications create procurement preference in federal facility management contracts, rewarding suppliers with verified renewable feedstock ratios.
- Leasing and rental equipment models:Mid-sized cleaning contractors in Ohio and Illinois access commercial-grade systems without capital outlay, expanding addressable market for consumable chemistry suppliers.
- Automotive detailing aftermarket:Rapid remediation demand between deep-cleaning cycles creates application white space for portable foam formulations targeting fleet maintenance operators.
Industry Challenges
- Formulation chemist talent scarcity:Specialized expertise in pH-stable surfactant blending commands premium compensation, constraining R&D velocity for regional suppliers.
- EPA registration timeline compression:New active ingredient approvals require multi-year toxicology dossiers, delaying pipeline commercialization for novel biodegradable alternatives.
- Legacy equipment compatibility:Low-VOC formulations often require recalibrated dispensing systems, creating friction in retrofit adoption among established cleaning contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carpet Spot Remover Market |
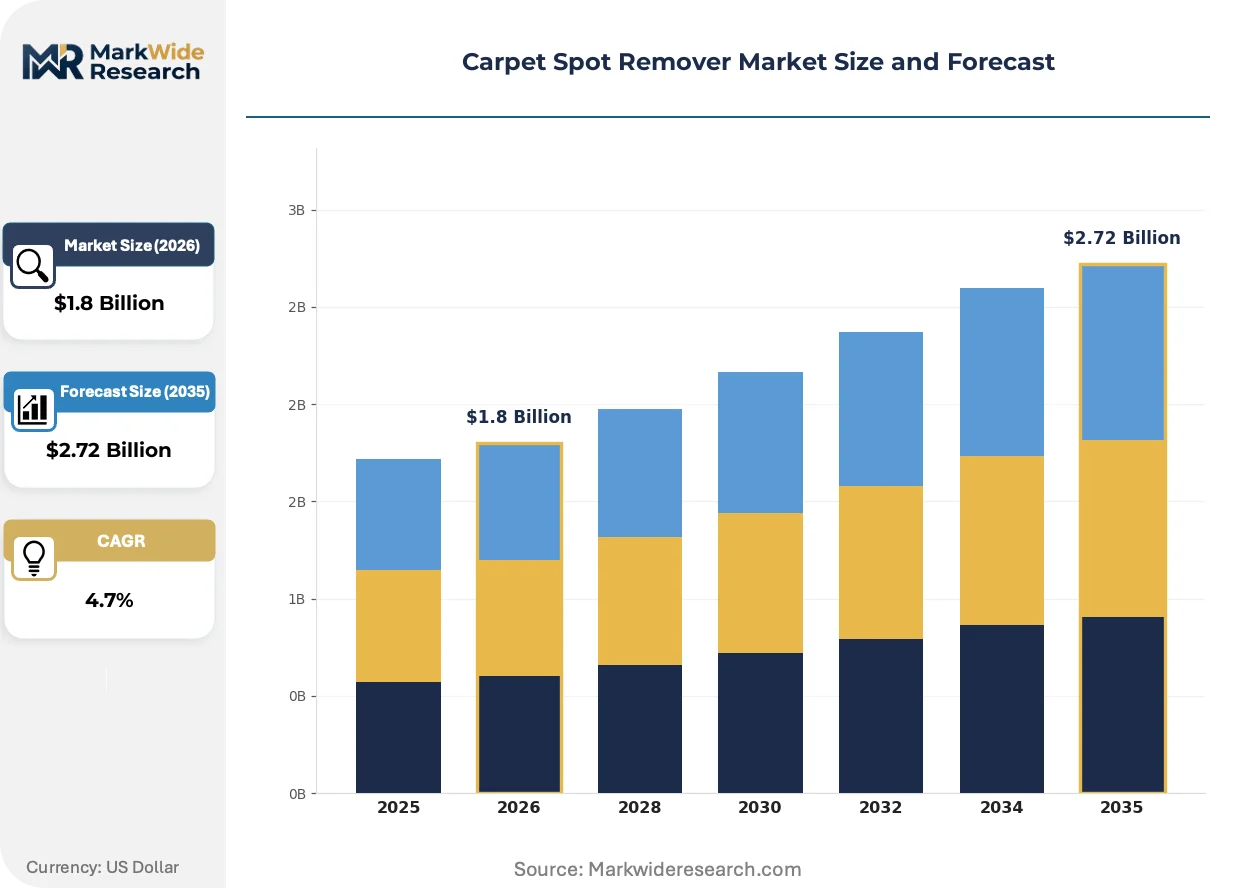
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam, Spray, Liquid, Wipes Application: Residential, Commercial, Automotive, Industrial Formulation: Enzymatic, Solvent-Based, Biodegradable, Non-Toxic Distribution Channel: Online, Retail Stores, Wholesale, Direct Sales |
| Companies Covered | Stanley Steemer Carpet Cleaner, Shark, Chem-Dry Carpet & Upholstery Cleaning, Hoover, Bissell, Oxi Fresh Carpet Cleaning, Zerorez, Rug Doctor, Heaven's Best Carpet Cleaning, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carpet Spot Remover Market Emerging Trajectories
Connected dispensing systems and IoT-enabled inventory tracking are digitizing how commercial facilities manage consumable chemistry, compressing the traditional distributor role while creating data-rich service relationships.
Smart dispensing hardware embedded with usage sensors is digitizing procurement workflows for facility management operators in Texas and Arizona. Real-time chemistry consumption data streams to centralized procurement platforms, enabling automated replenishment triggers. This compression of manual inventory cycles is displacing traditional distributor relationships with direct manufacturer subscriptions.
REACH Annex XVII restrictions on perfluorinated compounds are forcing European formulation houses to rebuild stain-repellent additive portfolios. Industrial laundries and hospitality operators in Germany and France face compliance deadlines that accelerate substitution toward silicone-based alternatives. Carpet spot remover suppliers with pre-validated PFAS-free chemistries capture specification advantages in cross-border procurement.
Subscription-based replenishment models are restructuring residential purchasing from episodic retail trips to automated delivery cycles. Pet-owning households in suburban markets receive enzymatic formulations on fixed schedules, reducing brand switching and compressing price sensitivity. Direct-to-consumer channels in Colorado and Washington demonstrate highest conversion rates for this behavior shift.
Carpet Spot Remover Market Segmentation
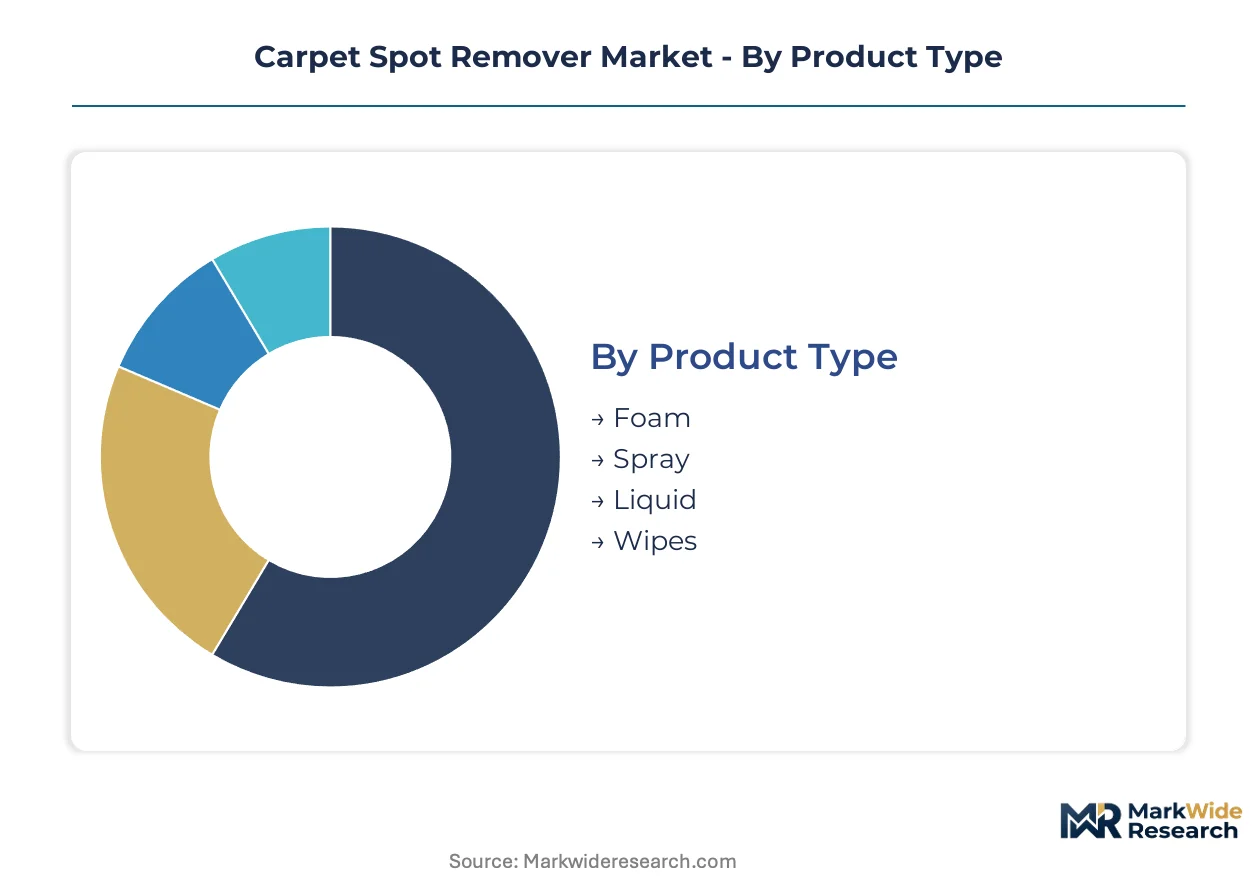
Carpet spot remover segmentation reveals distinct performance requirements across surface types, contamination chemistry, and procurement workflows. Formulation choices and delivery mechanisms determine shelf placement, pricing architecture, and regulatory compliance burdens for suppliers.
Product Type:
Mature dispensing formats dominate residential impulse purchases while emerging delivery systems target precision application in commercial settings.
- Foam:Controlled-expansion surfactant matrices reduce oversaturation risk on synthetic fiber substrates. Demand concentrates in United States suburban retail channels where consumers prioritize visible application control and minimal drying time between cleaning cycles.
- Spray:Aerosol and trigger-dispersed liquid formulations enable rapid coverage of large stain areas. Hospitality operators in Florida and Nevada specify spray systems for housekeeping efficiency during peak occupancy turnover.
- Liquid:Concentrated pour formulations serve professional extraction equipment requiring calibrated dilution ratios.
- Wipes:Pre-saturated single-use substrates target automotive detailing and emergency spot treatment portability.
Foam handles the majority of throughput; spray is the fastest mover on share.
Application:
Customer type determines performance specifications, with residential tolerance for slower action contrasting commercial requirements for immediate visual remediation.
- Residential:Pet-stain enzymatic chemistry drives repeat purchasing among companion-animal households. Subscription replenishment models in Colorado and Washington demonstrate highest conversion rates for automated delivery cycles.
- Commercial:Facility management contracts mandate low-VOC certification for indoor air quality compliance. California and New York procurement specifications accelerate replacement cycles for compliant equipment ahead of regulatory deadlines.
- Automotive:Fleet maintenance operators demand portable foam formulations for rapid remediation between deep-cleaning cycles.
- Industrial:Grease and oil contamination requires aggressive solvent dissolution rates that oxygenated bleach chemistry cannot match.
Commercial commands the largest revenue base; automotive represents the steepest expansion trajectory.
Formulation:
Margin structure varies sharply across chemistry platforms, with biobased feedstocks commanding procurement preference in federal contracts.
- Enzymatic:Protein-specific catalyst technology breaks down biological contamination through targeted molecular action. Pet-owning households sustain premium pricing acceptance for repeat stain remediation.
- Solvent-Based:Aggressive dissolution chemistry retains industrial maintenance share where petroleum-derived contamination demands rapid breakdown. EPA and state-level VOC limits in California compress permissible concentrations and mandate ingredient disclosure.
- Biodegradable:USDA BioPreferred program specifications create procurement preference in federal facility management contracts.
- Non-Toxic:pH-stable surfactant blends operating between 6.5 and 9.0 prioritize fiber safety over maximum extraction power.
Enzymatic formulations capture the highest margin tier; biodegradable alternatives are climbing the fastest on specification mandates.
Distribution Channel:
Channel selection determines working capital intensity and customer data access, with direct relationships displacing traditional distributor intermediaries.
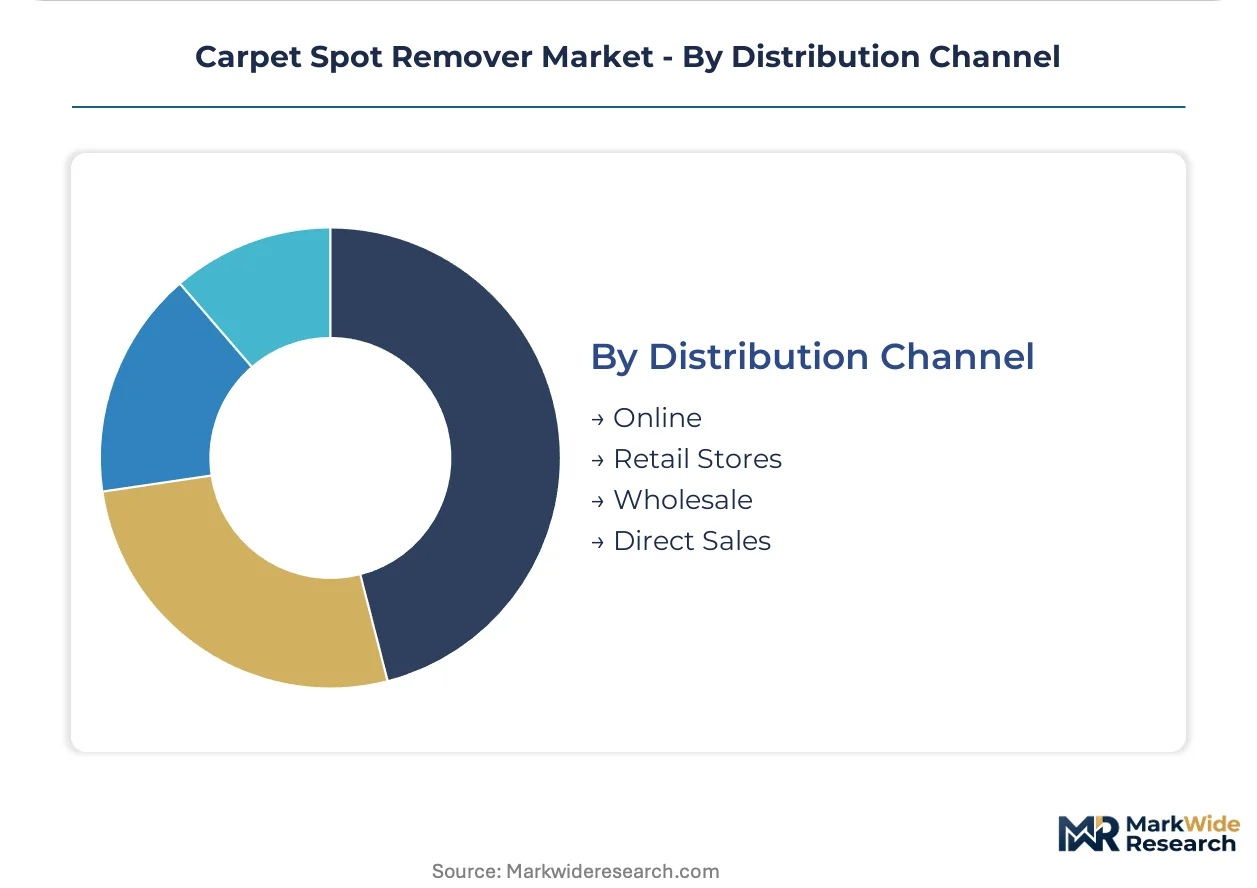
- Online:Direct-to-consumer platforms enable subscription-based replenishment with automated reorder triggers. Real-time consumption data streams to centralized procurement systems.
- Retail Stores:Big-box and home improvement chains sustain impulse purchase velocity through shelf placement density and private-label partnerships.
- Wholesale:Janitorial supply distributors serve mid-sized cleaning contractors with bulk chemistry and equipment bundling.
- Direct Sales:Manufacturer field representatives secure facility management contracts with customized dispensing system installations.
Retail stores maintain the broadest reach; online channels are gaining share fastest on subscription conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility management contractors and hospitality operators concentrate procurement power in markets with stringent indoor air quality enforcement and high commercial real estate turnover.
United States
Hotel renovation cycles in Florida, Nevada, and Texas sustain replacement rates for professional-grade cleaning consumables ahead of peak tourism seasons. EPA Safer Choice standards and California Air Resources Board VOC limits compress permissible solvent concentrations and mandate ingredient disclosure. Los Angeles and San Diego facilities accelerate replacement cycles for compliant equipment, driving above-average demand for certified low-emission systems.
Germany
Industrial laundries and hospitality operators face REACH Annex XVII compliance deadlines that accelerate substitution away from perfluorinated compounds. ECHA restrictions on PFAS force European formulation houses to rebuild stain-repellent additive portfolios. Carpet spot remover suppliers with pre-validated PFAS-free chemistries capture specification advantages in cross-border procurement serving German and French contract markets.
United Kingdom
Commercial facility management contracts in London and Southeast England mandate low-VOC certification for indoor air quality compliance. The country's national environmental regulator enforces emissions standards that reshape procurement specifications for professional cleaning services. Manchester and Birmingham service hubs concentrate mid-sized cleaning contractors accessing leasing models for commercial-grade equipment.
France
Hospitality operators in Paris and Provence-Alpes-Côte d'Azur accelerate compliant chemistry procurement ahead of tourism season peaks. ANSM and national environmental authorities coordinate enforcement of chemical substance restrictions affecting formulation imports. Lyon-based industrial clusters supply silicone-based alternatives to PFAS-dependent stain repellents for cross-border hospitality contracts.
Japan
Automotive detailing aftermarket demand concentrates in Osaka and Nagoya fleet maintenance corridors requiring portable remediation solutions. METI guidelines on chemical substance management influence procurement specifications for professional cleaning operators. Tokyo metropolitan facility managers specify connected dispensing systems with IoT-enabled inventory tracking for centralized procurement platforms.
Carpet Spot Remover Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. Mass-market retail density and direct-to-consumer platform strength define the upper competitive layer, while regional formulation houses serve contract-specified procurement with customized chemistry. Three archetypes dominate: brand-recognized equipment manufacturers with consumable ecosystems, private-label suppliers to home improvement chains, and specialized service franchises with captive chemistry requirements. M&A activity concentrates on consumable chemistry portfolios, while strategic partnerships between equipment makers and formulation houses accelerate low-VOC product pipelines.
Among equipment-manufacturer incumbents, Bissell and Hoover exemplify divergent channel strategies within the residential segment. Bissell occupies a position anchored in direct-to-consumer subscription models for concentrated cleaning solutions. Hoover represents retail distribution density through private-label partnerships with home improvement chains. Stanley Steemer Carpet Cleaner sits within the service-franchise archetype, where captive chemistry requirements create pull-through demand for professional-grade formulations.
| Leading Market Players |
|---|
| Stanley Steemer Carpet Cleaner |
| Shark |
| Chem-Dry Carpet & Upholstery Cleaning |
| Hoover |
| Bissell |
| Oxi Fresh Carpet Cleaning |
| Zerorez |
| Rug Doctor |
| Heaven's Best Carpet Cleaning |
| Others |
Supply Flow & Price Mechanics
Petrochemical feedstock volatility determines both pricing tier spreads and supply chain shape in carpet spot remover manufacturing. Crude oil index fluctuations compress margin stability for mid-tier suppliers lacking long-term surfactant supply agreements, while enzymatic catalyst premiums widen as European single-source dependencies harden.
Pricing Analysis
Cost-plus contracts with crude oil indexation dominate solvent-based formulation procurement between North American brands and Gulf Coast petrochemical suppliers. Price differentiation hinges on USDA BioPreferred certification tier and enzymatic catalyst concentration grade. Cost compression in standard surfactant tiers is intensifying because surfactant input costs fluctuate with crude indices. Residential subscription buyers demonstrate lowest price sensitivity due to automated replenishment lock-in, while mid-sized commercial contractors in Ohio and Illinois exhibit highest sensitivity to capital equipment bundling costs.
Supply Chain Analysis
Tariff exposure between Denmark and the United States dominates specialty enzyme procurement risk for North American formulation houses. Manufacturing gravity centers on Ohio and Illinois for equipment assembly, with surfactant feedstock production concentrated in Texas and Louisiana. Raw material dependencies include petroleum-derived solvents, protein-specific enzymatic catalysts, and oxygenated bleach precursors. Single-source vulnerability from Danish and Dutch enzyme production clusters threatens pipeline continuity. Distribution runs through janitorial supply wholesalers serving mid-sized contractors, with direct-to-consumer platforms compressing traditional retail intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. EPA Safer Choice certification creates switching costs that cement incumbent positions ahead of pending VOC limit amendments.
For Market Incumbents: Build regulatory entrenchment through preemptive EPA Safer Choice portfolio expansion ahead of California Air Resources Board deadline compression. Consolidate position by acquiring specialty enzyme supply agreements with Danish and Dutch production houses to neutralize single-source vulnerability. Channel control through IoT-enabled dispensing system installations locks in consumable chemistry pull-through demand.
For New Entrants and Emerging Players: Establish a beachhead in automotive detailing aftermarket applications where portable foam formulation demand outpaces established supplier coverage. Target fleet maintenance operators in Osaka and Nagoya corridors with rapid remediation solutions between deep-cleaning cycles. Deploy direct-to-consumer subscription mechanics to bypass entrenched retail shelf access barriers.
For Investors and Strategic Acquirers: REACH Annex XVII PFAS restrictions reshape the acquisition landscape toward pre-validated PFAS-free chemistry portfolios. Long-term viability favors suppliers with verified renewable feedstock ratios and captive regulatory affairs functions. Monitor California Air Resources Board enforcement intensity as the signal indicating acceleration in compliant equipment replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Formulation Rebuild | REACH Annex XVII compliance deadlines in Germany and France accelerate substitution toward silicone-based alternatives. |
| Subscription Platform Launch | Direct-to-consumer channels in Colorado and Washington demonstrate highest conversion rates for automated delivery cycles. |
| Enzyme Supply Agreement | Specialty catalyst production clusters in Denmark and Netherlands create single-source risk requiring contractual mitigation. |
| IoT Dispensing System Deployment | Connected hardware in Texas and Arizona facilities compresses manual inventory cycles and displaces distributor relationships. |
| BioPreferred Certification Investment | USDA program specifications create procurement preference in federal facility management contracts. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EPA registration databases, customs trade records, and state-level air quality board filings. Interviews with formulation chemists, janitorial supply distributors, facility management procurement officers, and commercial cleaning contractors provided operational validation. Secondary sources include California Air Resources Board enforcement records, Federal Trade Commission Green Guides documentation, and REACH Annex XVII restriction timelines. Bottom-up demand modeling triangulates against top-down market sizing across product type, application, and formulation chemistry segments.
Forecast inputs incorporate enzymatic catalyst adoption curves, VOC regulatory compliance cost trajectories, and commercial hospitality renovation cycle timing across the analysis window. Segmentation dimensions span dispensing format, end-use customer type, chemistry platform, and distribution channel structure. CAGRs derive from regression analysis against historical replacement rates and regulatory deadline acceleration patterns. Industry-specific inputs include petrochemical feedstock price volatility indices and subscription platform conversion rate benchmarks.
Stress conditions across crude oil price bands, enzyme supply disruption scenarios, and California enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory timeline adherence and hospitality sector capital expenditure continuity. Material shifts in EPA VOC limit amendment timing or REACH PFAS restriction scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
US Cleaning Products Market
Cleaning Equipment
Hand Wash Market
Cleaning Equipment
Commercial Cleaning Service Market
Cleaning Equipment
Spin Mops Market
Cleaning Equipment
Commercial Vacuum Cleaners Market
Cleaning Equipment
Carpet Cleaner Market
Cleaning Equipment
Carpet Cleaning Products Market
Cleaning Equipment
Janitorial Service Market
Cleaning Equipment
Furniture Polish Wipes Market
Cleaning Equipment
Fabric Freshener Market
Cleaning Equipment
Laundry Care Market
Cleaning Equipment
Bathroom Mirror Wiper Market
Cleaning Equipment
Vacuum Cleaner Filter Market
Cleaning Equipment
Countertop Spray Market
Cleaning Equipment
Laundry Sanitizer Market
Cleaning Equipment
Household Cleaning Products Market