
 Fabric Care Market | 2026-2036
Fabric Care Market Size, Share, and Industry Trends Forecast 2026-2036
Fabric Care Market Analysis
The EU Green Deal is broadening reformulation requirements across European supply chains, compelling manufacturers to eliminate phosphates and reduce aquatic toxicity in detergent formulations. Henkel AG & Co. KGaA leverages its European manufacturing base to sustain compliance leadership in concentrated liquid formats. Procter & Gamble Co. anchors North American market presence through pod-based delivery systems. Unilever PLC competes across emerging economies with refill and dilutable product architectures.
Fabric care encompasses chemical formulations and mechanical treatments designed to clean, soften, preserve, and restore textile fibers, with surfactant concentrations typically ranging from 15% to 40% in heavy-duty liquids and enzyme blends stabilizing performance across temperature gradients. The primary commercial purpose centers on extending garment lifespan while meeting hygiene standards in consumer and institutional settings. Detergents command the largest value share among product types, though pods and sheets are gaining fastest as single-dose convenience reshapes household purchasing patterns. Liquid formulations dominate developed markets while powder retains structural importance in price-sensitive regions and commercial laundries.
EPA Safer Choice standards in the United States, REACH registration requirements in Europe, and India's BIS quality certification collectively determine market access thresholds and permissible ingredient profiles across major supply corridors. These frameworks elevate compliance costs for imported formulations while creating competitive shelter for domestic producers with established regulatory dossiers. Stakeholders must monitor tightening state-level chemical disclosure mandates and biodegradability benchmarks that will determine which formulation platforms retain shelf space.
Market Dynamics
Concentrated liquid and single-dose pod formats are compressing traditional powder volumes as hospitality and healthcare procurement teams prioritize storage efficiency and dosing precision in commercial laundry operations.
Growth Catalysts
- REACH chemical restrictions:European manufacturers reformulating toward biodegradable surfactants gain preferential shelf placement in EU retail channels, creating compliance-based competitive shelter.
- India urban household penetration:Modern retail expansion in Mumbai, Delhi, and Bangalore accelerates adoption of pod-format detergents and fabric softeners among first-time appliance owners.
- Enzyme stabilization technology:Cold-water enzyme blends enable performance parity at reduced temperatures, cutting energy costs for commercial laundries operating across variable utility tariffs.
Market Restraints
- Phosphate elimination costs:Reformulation to meet EU Green Deal aquatic toxicity standards raises raw material expenses for imported surfactant bases.
- Linear alkylbenzene sulfonate concentration:Asia-Pacific petrochemical supply corridors dominate this feedstock, exposing European formulators to freight and currency volatility.
- Pod water solubility thresholds:Film dissolution failures in low-temperature wash cycles limit deployment in northern European municipal water conditions.
Strategic Opportunities
- Refill station networks:Dilutable concentrate architectures align with France's anti-gaspillage regulations, enabling packaging reduction claims in sustainability-sensitive retail segments.
- Healthcare linen services:Hospital-acquired infection protocols in Germany and the Netherlands create demand for peracetic acid-compatible softener formulations.
- BIS quality certification:Domestic Indian producers with established dossiers capture market access advantages as import compliance costs rise for multinational entrants.
Industry Challenges
- Surfactant toxicology expertise:Shortage of formulation chemists trained in aquatic ecotoxicology slows biodegradability certification timelines for mid-tier manufacturers.
- Legacy powder asset stranding:Spray-drying tower investments in price-sensitive markets face utilization pressure as liquid and pod formats capture volume share.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fabric Care Market |
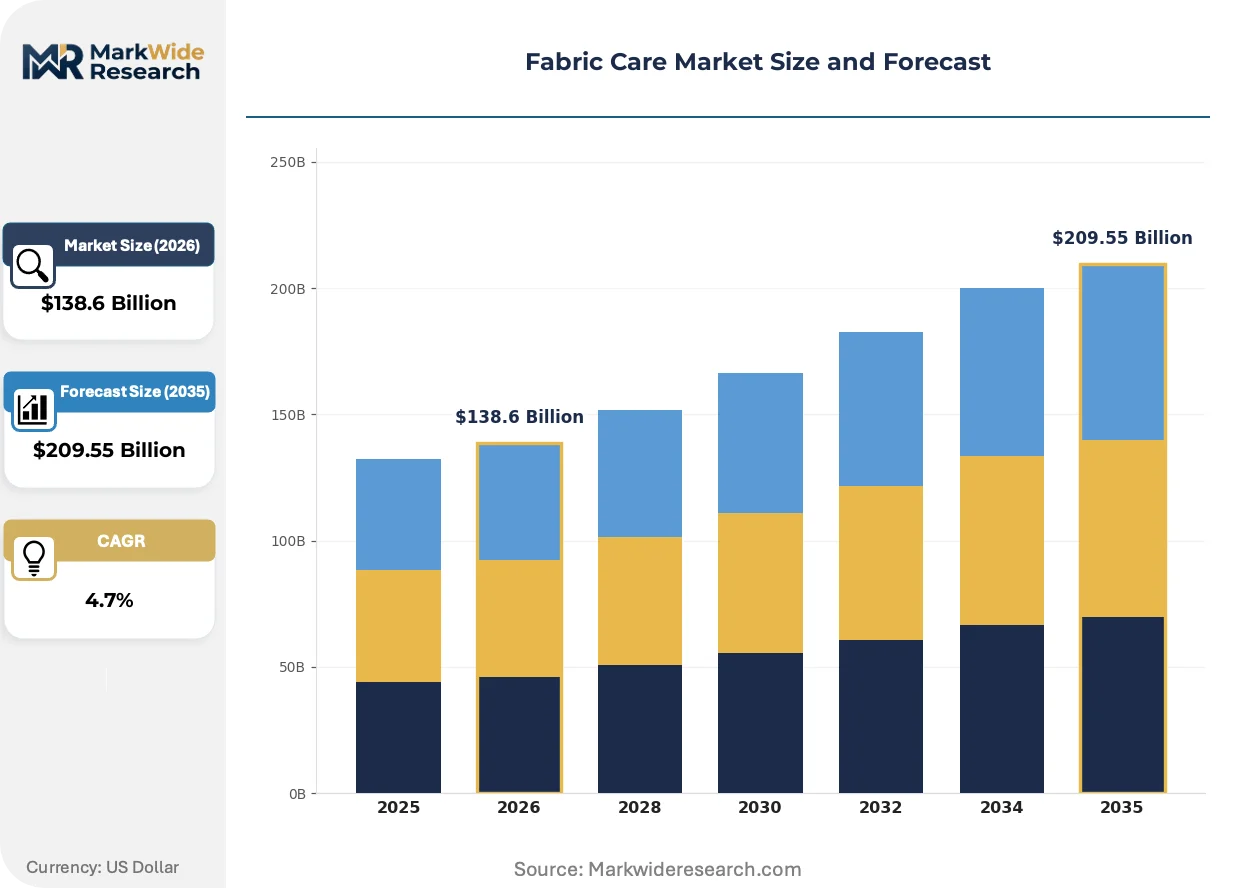
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $209.55 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Detergents, Softeners, Stain Removers, Whitener Form: Liquid, Powder, Pods, Sheets End User: Household, Commercial, Industrial, Institutional Distribution Channel: Online, Supermarkets, Convenience Stores, Specialty Retailers |
| Companies Covered | Henkel AG & Co. KGaA, Kao Corporation, Procter & Gamble Co., Reckitt Benckiser Group plc, LG Household and Healthcare, Unilever PLC, Godrej Consumer Products Limited, Church & Dwight Co., Inc, Colgate-Palmolive Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fabric Care Market Emerging Trajectories
Water-activated sheet formats and concentrated refill systems are fragmenting traditional bottle-based purchasing patterns, forcing packaging suppliers and retail shelf planners to reconfigure logistics and merchandising assumptions simultaneously.
Water-soluble detergent sheets are decentralizing distribution infrastructure by eliminating liquid freight weight and enabling direct-to-consumer postal economics. Boutique hospitality chains in Scandinavia and Japan are adopting sheet formats for guest amenity programs, compressing traditional supplier relationships with regional chemical distributors. This format shift is decentralizing procurement authority from centralized housekeeping supply contracts toward individual property-level purchasing decisions.
EPA Safer Choice standards are tightening disclosure requirements for fragrance components and preservative systems in US formulations. Manufacturers must submit full ingredient inventories to maintain certification eligibility for federal and municipal procurement channels. Institutional buyers in California and New York are prioritizing Safer Choice-labeled products in hospitality and school district tenders, forcing reformulation of legacy preservative packages.
Subscription-based auto-replenishment is compressing traditional grocery channel fabric care purchasing. Direct-to-consumer platforms in the United Kingdom and Australia are capturing repeat-purchase loyalty through calibrated dosing algorithms and refill scheduling. This behavioral shift is most visible among millennial-headed households in London and Sydney, where pantry storage constraints favor concentrated formats with reduced packaging footprint.
Fabric Care Market Segmentation
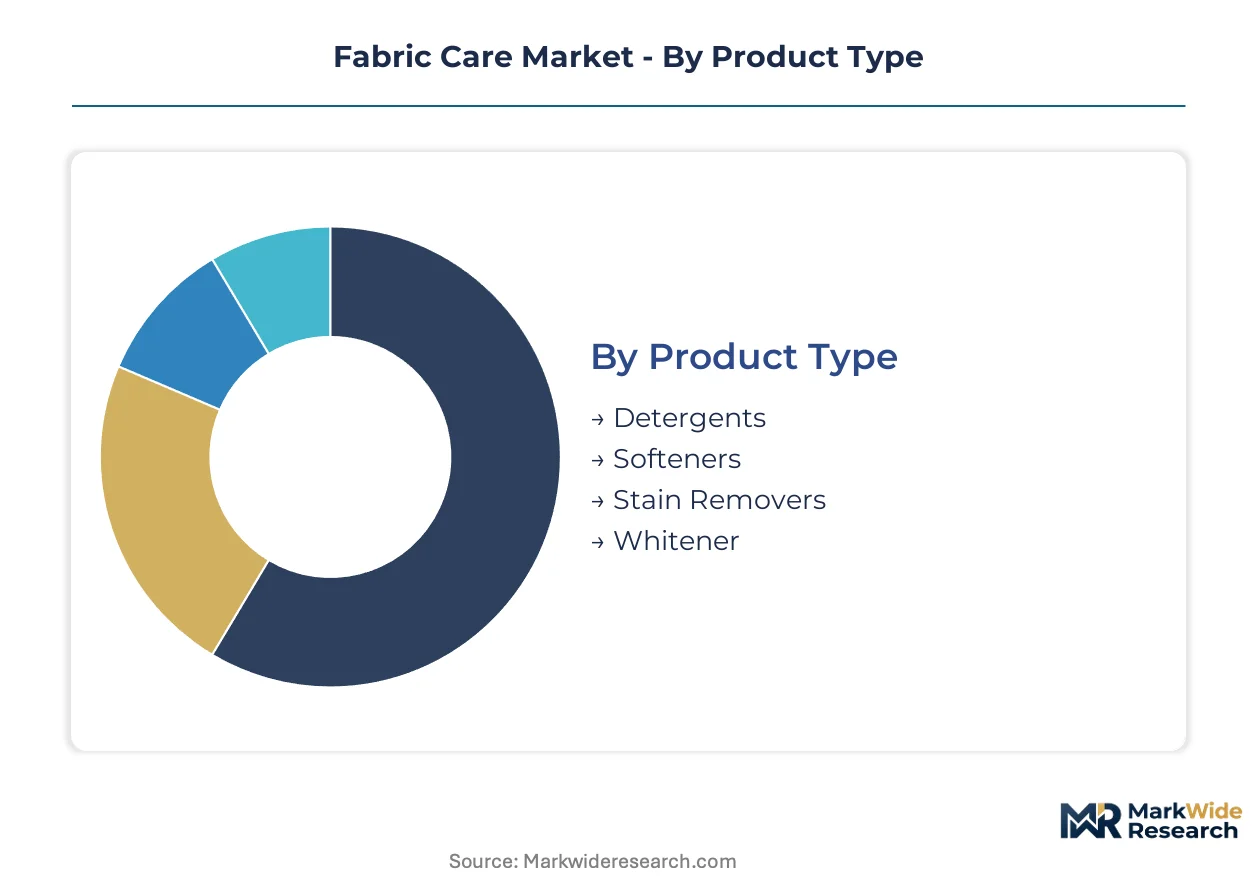
Fabric care purchasing decisions fragment across formulation chemistry, delivery format, and procurement setting. Manufacturers must align R&D investment with the specific performance thresholds and regulatory constraints governing each segment cluster.
Product Type:
Performance requirements and margin structures vary sharply by textile treatment function.
- Detergents:Surfactant-based formulations with enzyme blends typically comprise 15% to 40% active content by weight. Demand concentrates in commercial laundry services across Germany and the Netherlands, where hospital-acquired infection protocols mandate high-efficacy cleaning chemistry.
- Softeners:Cationic conditioning agents deposit lubricating films on fiber surfaces to reduce static and preserve hand-feel. Adoption accelerates in urban Indian households as washing machine penetration rises alongside modern retail expansion in Mumbai and Delhi.
- Stain Removers:Targeted oxidizing and enzymatic pre-treatment formulations address protein, oil, and tannin-based soiling.
- Whitener:Optical brightening agents absorb UV radiation and emit visible blue light to mask yellowing in cotton and synthetic blends.
Detergents lead on scale; softeners lead on momentum.
Form:
Storage density and dosing precision determine format preference across consumer and institutional channels.
- Liquid:Pump-dispensed concentrates enable flexible dosing and rapid dissolution across temperature gradients. Hospitality procurement teams in France prioritize concentrated liquids under anti-gaspillage regulations that reward packaging reduction claims.
- Pods:Single-dose water-soluble film enclosures eliminate measurement error and reduce pantry storage footprint. Film dissolution failures in low-temperature municipal water conditions constrain deployment in northern European markets.
- Powder:Spray-dried granules retain structural importance in price-sensitive regions and commercial laundries with bulk dosing infrastructure.
- Sheets:Water-activated cellulose substrates eliminate liquid freight weight and enable direct-to-consumer postal distribution.
Liquid formulations dominate current volume; pods and sheets climb the fastest as convenience and sustainability preferences reshape purchasing.
End User:
Volume scale and specification stringency diverge across private, commercial, and regulated institutional settings.
- Household:Individual consumers selecting formulations based on fragrance preference, fabric type compatibility, and appliance manufacturer recommendations.
- Commercial:Hospitality linen services and on-premise laundries operating under cost-per-pound procurement metrics.
- Industrial:Large-scale textile processing facilities requiring bulk chemical delivery and automated dosing systems.
- Institutional:Healthcare and educational facilities subject to EPA Safer Choice disclosure mandates and infection control protocols.
Household channels anchor volume absorption; institutional segments command premium pricing through compliance-linked specification barriers.
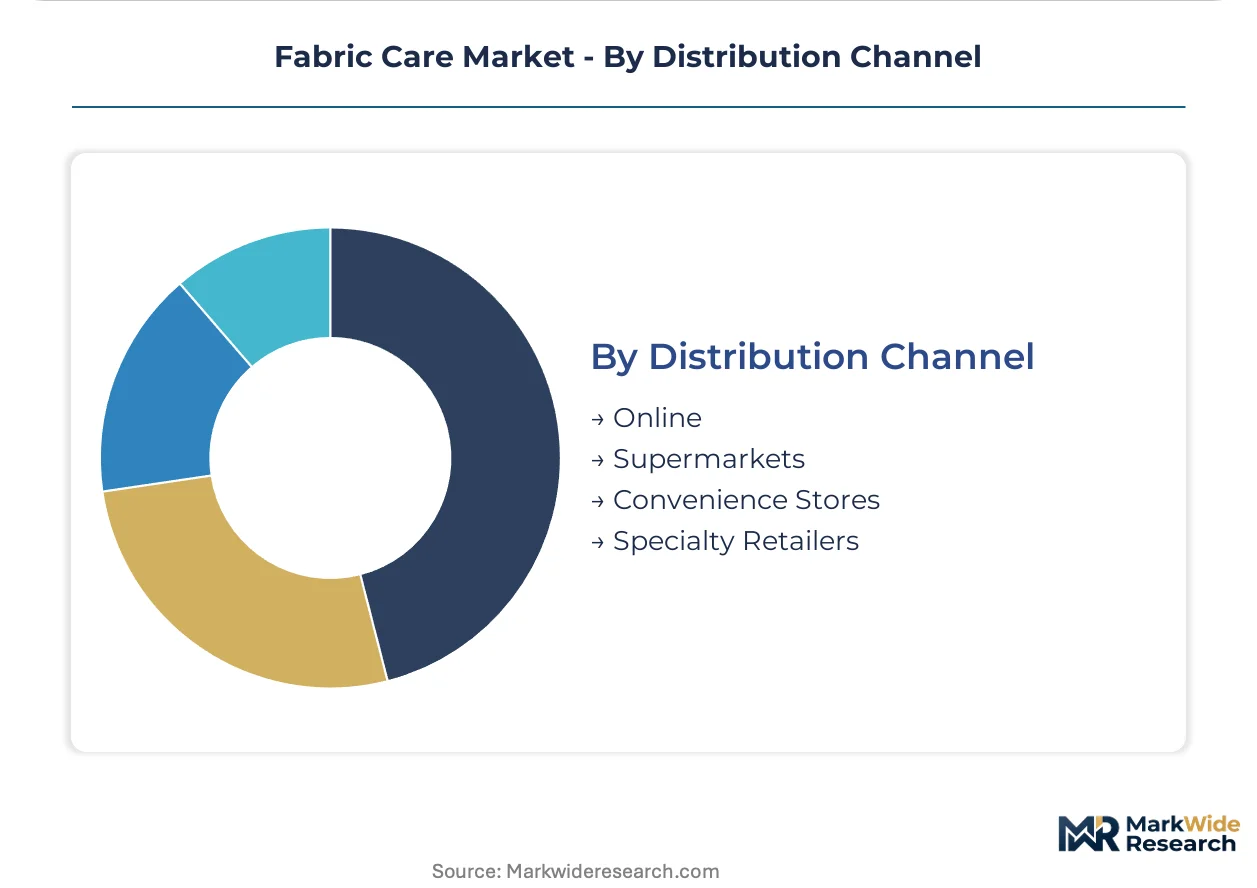
Distribution Channel:
Channel selection reflects purchase frequency, storage constraints, and replenishment automation preferences.
- Online:Subscription auto-replenishment platforms capture repeat-purchase loyalty through calibrated dosing algorithms. Millennial-headed households in London and Sydney favor concentrated formats with reduced packaging footprint delivered through direct-to-consumer logistics.
- Supermarkets:Mass merchandisers retain dominance for unplanned and promotional purchasing across standard-format liquids and powders.
- Convenience Stores:Emergency replenishment and travel-size formats address immediate-need purchasing with limited SKU depth.
- Specialty Retailers:Premium and eco-certified formulations targeting sustainability-sensitive consumers with full ingredient transparency.
Supermarkets maintain the widest reach; online channels expand most quickly as subscription mechanics lock in recurring revenue streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fabric care chemistry originated in German industrial laboratories during the early synthetic surfactant era, with BASF and Henkel establishing the foundational formulation science that spread through European manufacturing before reaching North American and Asian production centers.
Germany
Hospital-acquired infection protocols in Berlin and Munich drive institutional procurement of peracetic acid-compatible softeners. REACH registration requirements administered by ECHA enforce aquatic toxicity thresholds that eliminate phosphate content from retail formulations. The Rhine-Ruhr chemical corridor hosts concentrated liquid production facilities supplying hospitality chains across the Benelux region.
United States
Subscription auto-replenishment platforms in New York and Los Angeles capture millennial household loyalty through calibrated dosing algorithms. EPA Safer Choice disclosure mandates tighten fragrance component transparency for federal procurement eligibility. The Gulf Coast petrochemical belt supplies linear alkylbenzene sulfonate feedstocks to formulators serving institutional buyers in California and Texas.
India
Urban washing machine penetration in Mumbai and Delhi accelerates adoption of pod-format detergents among first-time appliance owners. BIS quality certification requirements create compliance barriers for imported formulations while sheltering domestic producers with established dossiers. The Gujarat chemical cluster manufactures spray-dried powder for price-sensitive rural markets alongside liquid concentrates for modern retail channels.
Japan
Boutique hospitality chains in Tokyo and Osaka adopt water-activated detergent sheets for guest amenity programs. METI-administered JIS standards govern biodegradability benchmarks for surfactant discharge into municipal water systems. The Nagoya industrial zone supplies precision film-forming polymers for pod water-solubility thresholds tested across variable temperature gradients.
France
Anti-gaspillage regulations in Paris and Lyon reward refill station networks with packaging reduction claims in sustainability-sensitive retail segments. ANSM monitors preservative system safety in formulations targeting sensitive-skin consumer segments. The Lyon chemical basin produces enzyme stabilization technologies enabling cold-water performance parity for commercial laundries operating under variable utility tariffs.
Fabric Care Market Vendor Landscape
Capital-heavy producers with integrated surfactant manufacturing compete with asset-light formulators outsourcing feedstock supply. The vendor base separates into three tiers: multinational diversified consumer goods conglomerates with global distribution infrastructure, regional specialists concentrating on single-format excellence, and private-label contractors serving retail channel consolidation. Strategic moves center on backward integration into enzyme biotechnology and geographic licensing agreements that transfer formulation IP into emerging market joint ventures.
Among European-headquartered conglomerates, Henkel AG & Co. KGaA and Unilever PLC exemplify the compliance-first archetype leveraging established regulatory dossiers across EU Green Deal jurisdictions. Procter & Gamble Co. occupies a position as the North American pod-format anchor, while Kao Corporation represents Japanese precision-chemistry positioning in Asian hospitality supply chains.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Kao Corporation |
| Procter & Gamble Co. |
| Reckitt Benckiser Group plc |
| LG Household and Healthcare |
| Unilever PLC |
| Godrej Consumer Products Limited |
| Church & Dwight Co., Inc |
| Colgate-Palmolive Company |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists in Germany and India anchor regional supply clusters while exercising pricing discipline through captive enzyme biotechnology and established regulatory dossiers. Their ownership structures enable long-term feedstock contracting that insulates formulated product pricing from petrochemical volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the fabric care market by certification grade and volume commitment. Premium tiers command shelf placement through EPA Safer Choice and EU Ecolabel credentials, while economy positioning serves price-sensitive bulk procurement in commercial laundries. Cost compression in standard-tier liquids is intensifying because linear alkylbenzene sulfonate feedstock exposure ties margins to Asia-Pacific petrochemical pricing. Institutional buyers in healthcare and hospitality exhibit lowest price sensitivity due to infection-control specification barriers, whereas rural household segments in emerging markets demonstrate highest elasticity.
Supply Chain Analysis
Surfactant feedstock supply rests on Germany, China, and India as the dominant production anchors for linear alkylbenzene sulfonate and biodegradable alcohol ethoxylates. Key dependencies include palm-derived fatty alcohols, petroleum-based alkylbenzene, and precision enzyme cultures from Danish biotechnology suppliers. Single-source vulnerability concentrates in water-soluble pod films, where Japanese polymer specialists control dissolution-threshold formulations. Distribution runs through modern retail chains in urban India, direct-to-consumer platforms in the United Kingdom, and contract chemical distributors serving European hospitality procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fabric care manufacturing arbitrage between EU REACH compliance costs and India's BIS certification shelter creates margin expansion opportunities for regional producers with established dossiers.
For Market Incumbents: Deploy backward integration into enzyme stabilization technology to defend against cold-water performance parity demands from commercial laundries. Consolidate spray-drying tower assets in price-sensitive markets before utilization pressure accelerates. Lock in long-term supply agreements with Gujarat chemical cluster producers to hedge against import compliance cost escalation. For New Entrants and Emerging Players: Capture refill station network expansion in France under anti-gaspillage regulations as the most penetrable white-space target. Target boutique hospitality chains in Scandinavia and Japan adopting water-activated sheet formats for guest amenity programs. Lead with direct-to-consumer postal economics enabled by lightweight cellulose substrate distribution. For Investors and Strategic Acquirers: Consumer goods conglomerates with global distribution infrastructure are the most active acquirer in this space, seeking regional specialists with established regulatory dossiers. Five-to-ten year viability hinges on biodegradability certification pipelines and cold-water enzyme portfolios. Watch for REACH chemical restriction expansion beyond phosphates as the inflection signal for accelerated consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enzyme Biotechnology | Henkel and Kao leverage captive enzyme stabilization to meet EU cold-water performance mandates. |
| Refill Station Network Expansion | Unilever's dilutable concentrate architectures align with France's anti-gaspillage packaging reduction requirements. |
| Direct-to-Consumer Platform Launch | Subscription auto-replenishment in London and Sydney captures millennial loyalty through calibrated dosing algorithms. |
| Peracetic Acid-Compatible Formulation Development | Healthcare linen services in Germany and Netherlands demand softeners meeting hospital-acquired infection protocols. |
| BIS Quality Certification Investment | Godrej Consumer Products leverages established Indian dossiers as import compliance costs rise for multinational entrants. |
Methodological Framework
Bottom-up household and institutional procurement modeling reconciled against top-down surfactant manufacturing capacity tracking forms the analytical core of this study. Primary interviews with brand managers, category buyers at modern retail chains, plant managers at Gujarat chemical facilities, and technical R&D directors at European formulators were validated against secondary sources including customs and trade data, SEC 10-K filings, Nielsen retail audit data, and ECHA REACH registration databases. Triangulation between consumption-side demand signals and production-side supply confirmations resolves data gaps.
Historical trendline analysis of formulation format shifts from powder through liquid to pod and sheet architectures informed projection assumptions across the analysis window. Segmentation dimensions modeled include product chemistry, delivery format, end-user procurement setting, and regional regulatory cluster. CAGRs derive from calibrated adoption curves for concentrated and single-dose formats, cross-referenced against washing machine penetration rates in urban India and subscription platform growth in the United Kingdom and Australia.
REACH chemical restriction expansion, BIS certification enforcement intensity, and cold-water enzyme performance threshold failures are the dominant revision risks to modeled outputs. Material deviation in any named trigger warrants pause and re-evaluation of volume and value assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Drain Sponges Market
Cleaning Equipment
Carpet Extraction Cleaner Market
Cleaning Equipment
Floor Cleaning Device Market
Cleaning Equipment
Household Cleaning Tools and Supplies Market
Cleaning Equipment
Countertop Spray Market
Cleaning Equipment
Carpet Cleaning Products Market
Cleaning Equipment
Fabric Freshener Market
Cleaning Equipment
Cleaning Services Market
Cleaning Equipment
Commercial Vacuum Cleaners Market
Cleaning Equipment
Household Cleaning Products Market
Cleaning Equipment
Commercial Cleaning Service Market
Cleaning Equipment
Commercial Laundry Detergent Market
Cleaning Equipment
Global Carpet and Upholstery Cleaning Services Market
Cleaning Equipment
Carpet Cleaner Market
Cleaning Equipment
Furniture Polish Market
Cleaning Equipment
Janitorial Cleaning Equipment and Supplies Market