
 Europe Garment Steamers Market | 2026-2036
Europe Garment Steamers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Garment Steamers Market Insights
Multi-source component procurement is recalibrating how European garment steamer manufacturers balance cost against supply resilience. Koninklijke Philips N.V. leverages its vertically integrated electronics supply chain to control semiconductor sourcing for precision temperature controls. Groupe SEB anchors its competitive stance through deep brand equity in premium kitchen and garment care segments across French and Benelux retail channels. AB Electrolux competes by extending its sustainability-certified manufacturing footprint into Eastern European assembly plants.
Garment steamers are electrically heated appliances that generate saturated steam at temperatures typically between 98°C and 150°C to relax fabric fibers and remove wrinkles without mechanical pressing. These devices employ aluminum or stainless-steel heating elements with wattage ratings from 800W for handheld units to 1800W for standing commercial systems, serving residential consumers, hospitality operators, and professional textile services. Handheld and portable segments dominate unit volumes in European markets due to space constraints in dense urban housing, while standing and commercial systems capture disproportionate margin pools from hotel procurement contracts and dry cleaner fleet replacements. Steam and continuous-flow technologies lead the installed base, though pressurized systems are gaining traction among fashion retailers requiring faster cycle times for delicate fabrics.
The EU Ecodesign Directive and CE marking requirements shape product development cycles by mandating standby power thresholds and electrical safety testing protocols before market access. France's ANSM and Germany's KBA do not regulate garment steamers directly, but national consumer protection agencies enforce EU-wide product safety standards through market surveillance and recall authority. Stakeholders must monitor evolving Ecodesign tier requirements and battery-related amendments that could affect cordless handheld variants entering the European market.
Market Dynamics
The EU Ecodesign Directive's tightening standby power thresholds are forcing rapid redesign cycles across European garment steamer portfolios, compressing development timelines while simultaneously creating compliance-driven product differentiation.
Growth Catalysts
- Boutique hotel linen service expansion:Southern European hospitality operators are building in-house pressing capabilities to replace outsourced contracts, creating fleet demand for standing commercial systems.
- REACH compliance as quality signal:Manufacturers achieving full substance restriction transparency command shelf preference in French and German premium retail channels.
- Urban apartment density:Space-constrained households in Paris, Berlin, and Milan favor handheld steaming solutions over traditional ironing equipment.
Market Restraints
- Semiconductor supply concentration:Precision temperature control chips face sourcing bottlenecks from concentrated Asian foundry capacity, extending lead times for smart-enabled units.
- Aluminum heating element cost volatility:Raw material price swings for 800W-1800W rated components compress margin predictability across the product stack.
- Traditional iron substitution threat:Established ironing equipment retains price advantage and consumer familiarity in Eastern European markets with lower disposable income.
Strategic Opportunities
- Cordless handheld penetration in Benelux:Battery-powered variants remain underrepresented in Dutch and Belgian retail despite strong urban consumer profiles.
- Fashion retailer pressurized system adoption:Delicate fabric handling requirements in Milan and Barcelona retail operations create demand for faster-cycle professional equipment.
- EU Green Deal circularity incentives:Repairable design certifications and extended producer responsibility schemes reward modular construction and spare parts availability.
Industry Challenges
- CE marking timeline compression:Electrical safety testing protocols and documentation requirements strain smaller manufacturers with limited regulatory affairs capacity.
- Multi-tier distribution integration:Aligning warranty and service networks across specialty retail, mass merchants, and direct-to-consumer channels creates operational friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Garment Steamers Market |
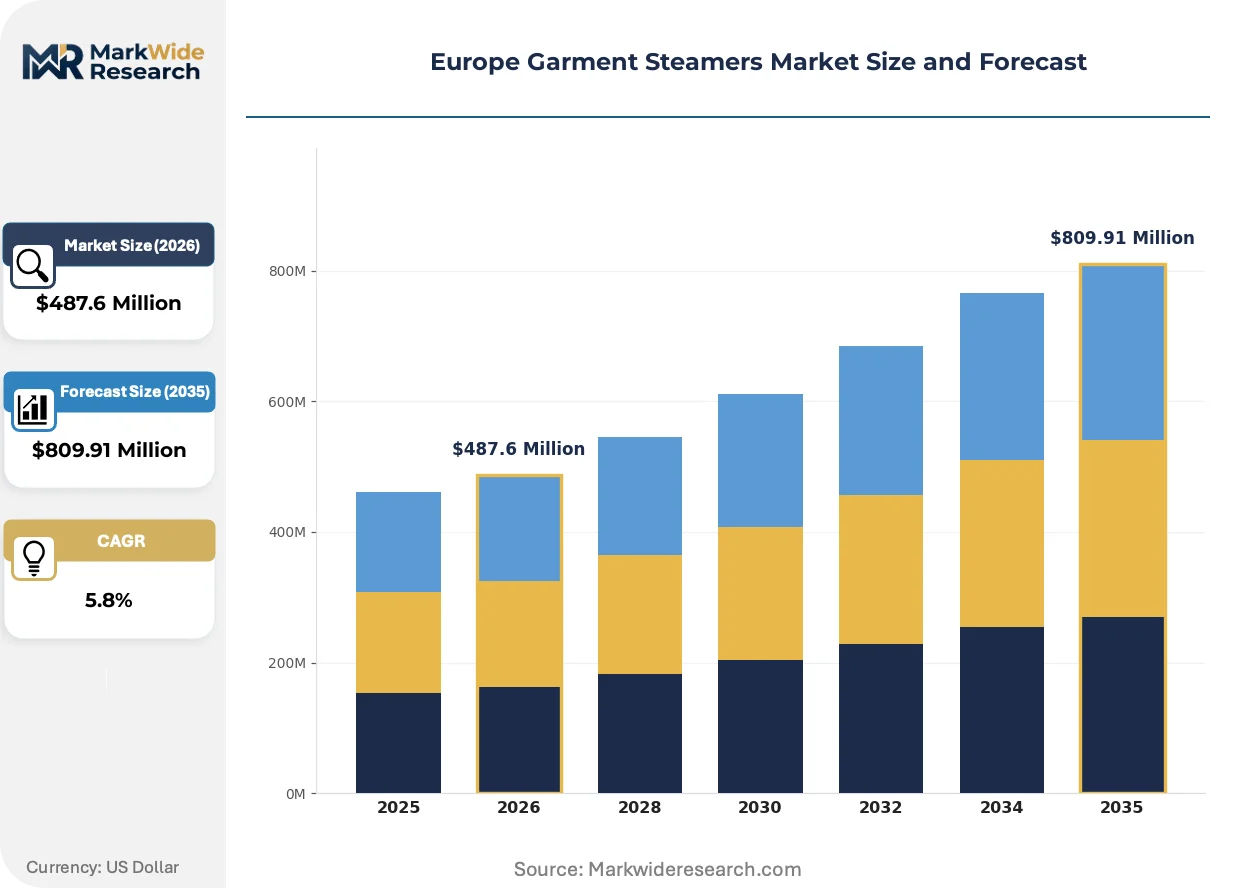
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Standing, Commercial, Portable End User: Household, Fashion Retailers, Hotels, Dry Cleaners Technology: Steam, Pressurized, Continuous Flow, Compact Distribution Channel: Online Retail, Specialty Stores, Hypermarkets, Others |
| Companies Covered | Koninklijke Philips N.V., Groupe SEB, Conair LLC, AB Electrolux, Rowenta, Haier Group Corporation, Jiffy Steamer, Panasonic Holdings Corporation, Hamilton Beach Brands, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Garment Steamers Market Trends and Innovations
Pressurized steam generation is displacing conventional continuous-flow systems in professional segments, while connectivity features and sustainability certifications reshape consumer purchase criteria across European retail channels.
Pressurized boiler technology is electrifying garment steamer performance benchmarks by delivering saturated steam at sustained 150°C outputs for delicate fabric processing. Italian fashion houses and Spanish hospitality procurement teams are specifying these systems for 40% faster cycle completion. The technology is electrifying competitive positioning by compressing the performance gap between mid-tier standing units and premium commercial installations.
REACH substance restriction amendments are forcing reformulation of heating element coatings and plastic housing compounds before 2026 compliance deadlines. Manufacturers serving German and French markets face accelerated testing cycles for SVHC (Substances of Very High Concern) screening. The professional textile services segment is responding fastest, with dry cleaner cooperatives pooling certification costs to maintain fleet access.
Direct-to-consumer subscription models for garment care accessories are fragmenting traditional retail attachment strategies. Dutch and Scandinavian consumers increasingly source descaling solutions and fabric brushes through manufacturer apps rather than brick-and-mortar replenishment. This channel pivot is most visible in Amsterdam and Copenhagen urban demographics, where digital-native purchasing patterns support recurring revenue architectures over one-time equipment sales.
Europe Garment Steamers Market Segmentation
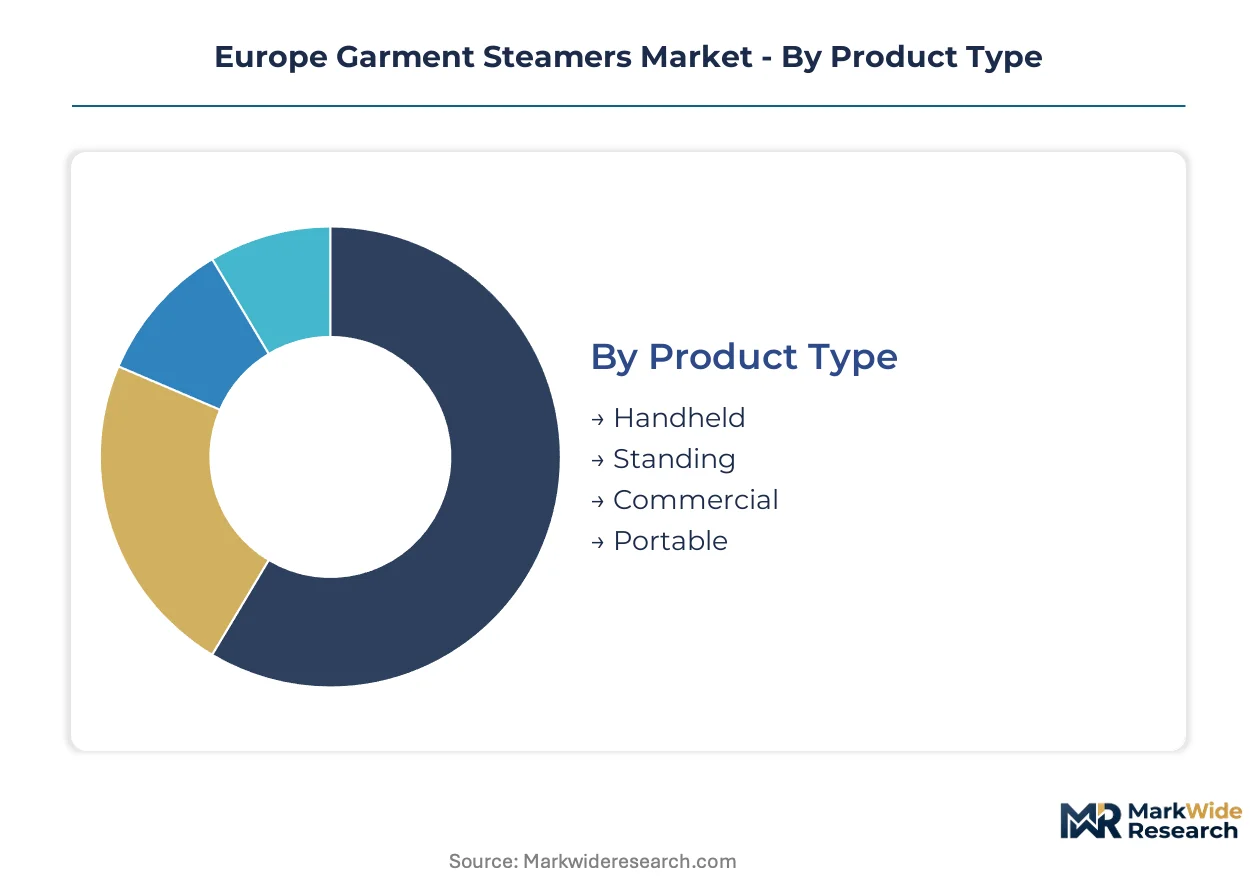
Segmentation in the Europe garment steamers market reveals how regulatory requirements, space constraints, and professional throughput demands split demand across distinct product configurations and customer profiles. CE marking thresholds and Ecodesign standby power tiers apply unevenly across these segments, creating compliance-driven differentiation that shapes manufacturer portfolio priorities.
Product Type:
CE marking intensity varies sharply across this category, with commercial systems facing extended electrical safety testing protocols while handheld units navigate streamlined self-certification pathways.
- Handheld:Compact 800W-1200W aluminum heating element configurations dominate Paris and Berlin apartment households where storage space is severely constrained. French urban consumers drive disproportionate volume through specialty retail channels seeking rapid garment refresh without ironing board deployment.
- Standing:Vertical pole designs with integrated hangers and 1500W-1800W stainless steel boilers serve hospitality procurement teams in Barcelona and Rome building in-house linen services. Boutique hotel operators across Southern Europe specify these systems for outsourced pressing replacement, prioritizing cycle speed over acquisition cost.
- Commercial:Continuous-duty pressurized boilers rated for 8+ hour operation cycles support Milan fashion house atelier requirements and high-volume dry cleaner fleets.
- Portable:Collapsible designs with dual-voltage capability target cross-border travelers and second-home owners in Benelux corridors.
Leading the category by volume: Handheld. Growing fastest: Standing.
End User:
Cost tier stratification separates residential price sensitivity from professional equipment ROI calculations across this dimension.
- Household:Space-constrained urban apartments in Milan, Berlin, and Amsterdam favor compact steaming solutions over traditional ironing equipment, with purchase decisions driven by countertop footprint and descaling maintenance intervals.
- Fashion Retailers:Milan and Barcelona flagship stores specify pressurized systems for delicate fabric handling, where 40% faster cycle completion justifies premium equipment acquisition against showroom preparation labor costs.
- Hotels:Southern European boutique properties from Lisbon to Athens are expanding in-house linen services as an alternative to outsourced pressing contracts.
- Dry Cleaners:Fleet replacement cycles concentrate in German cooperative networks pooling REACH compliance certification costs for SVHC screening requirements.
Dominating unit shipments: Household. Steepest expansion trajectory: Hotels.
Technology:
Application intensity separates consumer convenience from professional throughput requirements across heating system architectures.
- Steam:Saturated vapor generation at 98°C-120°C through aluminum heating elements serves baseline residential demand across French mass retail channels, where simplicity and repairability outweigh performance specifications.
- Pressurized:Sustained 150°C output from sealed boiler systems is electrifying competitive positioning in professional segments, compressing the performance gap between mid-tier standing units and premium commercial installations for Italian fashion house procurement teams.
- Continuous Flow:Direct water connection designs eliminate reservoir refill interruptions for high-volume hospitality operations in Madrid and Lisbon.
- Compact:Miniaturized heat exchanger configurations target Benelux urban demographics with severe storage constraints.
Widest installed base: Steam. Gaining share fastest: Pressurized.
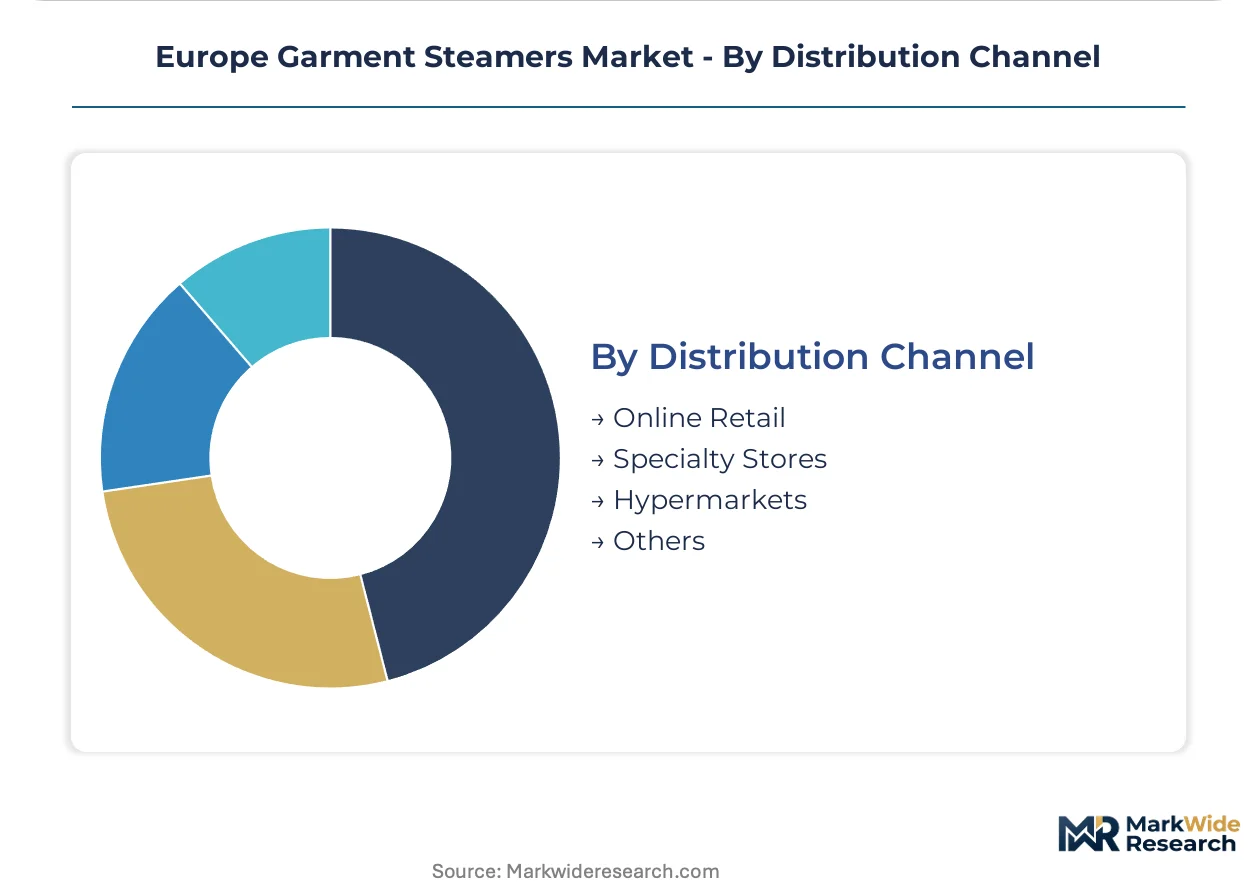
Distribution Channel:
Customer type fragmentation splits warranty service expectations and attachment selling opportunities across physical and digital touchpoints.
- Online Retail:Direct-to-consumer subscription models for descaling solutions and fabric brushes are fragmenting traditional replenishment strategies, with Amsterdam and Copenhagen urban demographics driving recurring revenue architectures through manufacturer apps.
- Specialty Stores:Demonstration-driven conversion in German and French premium retail channels rewards REACH compliance transparency with shelf preference and trained sales staff endorsement.
- Hypermarkets:Price-focused mass merchant placement concentrates handheld volume in Eastern European markets with lower disposable income.
- Others:Hospitality procurement direct contracts and dry cleaner cooperative purchasing networks bypass retail markup for fleet-scale standing system deployment.
Highest transaction volume: Online Retail. Expanding most quickly: Specialty Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum and stainless-steel heating element supply chains anchor manufacturing footprints in Germany and Italy, with precision electronics sourcing concentrated in Dutch and Belgian distribution corridors. REACH compliance costs and Ecodesign standby power tiers fragment competitive positioning across national retail channels.
Germany
Urban apartment density in Berlin and Hamburg drives handheld steamer volumes through specialty retail, where KBA-aligned consumer protection enforcement elevates electrical safety documentation requirements. The country's Ecodesign implementation timeline accelerates standby power redesign cycles for 800W-1200W residential units. Manufacturing gravity concentrates in North Rhine-Westphalia assembly plants serving Benelux export channels.
France
Parisian space constraints favor compact steaming solutions over traditional ironing equipment, with ANSM oversight reinforcing REACH SVHC transparency as a shelf-preference signal in premium retail. The Île-de-France corridor anchors hospitality procurement for boutique hotel linen service expansion. French mass retail channels concentrate baseline steam technology volumes through demonstration-driven conversion.
Italy
Milan fashion houses specify pressurized systems for 40% faster delicate fabric processing, with atelier procurement teams driving professional equipment specifications. The country's machinery heritage supports heating element fabrication clusters in Lombardy and Veneto. Southern European hospitality operators from Rome to Naples build in-house pressing capabilities through standing system fleet deployment.
Spain
Barcelona retail flagships adopt pressurized boiler technology for showroom preparation labor cost reduction, with Madrid hospitality procurement teams sourcing continuous-flow designs for high-volume operations. The country's EU Green Deal circularity incentives reward repairable design certifications. Andalusian boutique properties from Seville to Málaga expand linen services as outsourced pressing alternatives.
Netherlands
Amsterdam urban demographics drive direct-to-consumer subscription models for garment care accessories through manufacturer apps, with Randstad distribution networks enabling rapid replenishment logistics. The country's dense retail environment supports cordless handheld underpenetration recovery in Benelux corridors. Eindhoven-region electronics sourcing channels serve precision temperature control semiconductor procurement.
Europe Garment Steamers Market Competitive Landscape
Global majors compete with regional champions across electronics integration and heating system fabrication, producing a tiered structure where scale-driven portfolios intersect with specialized professional equipment lines. The vendor base stratifies across vertically integrated electronics houses, diversified appliance conglomerates, and focused steaming specialists. Three archetypes dominate: precision control technology leaders, multi-category brand equity holders, and hospitality-focused commercial system fabricators. Competitive moves concentrate on REACH compliance certification pooling and Ecodesign-driven product redesign acceleration.
Among diversified European appliance conglomerates, Koninklijke Philips N.V. and Groupe SEB occupy positions spanning residential and professional segments, with AB Electrolux representing the sustainability-certified manufacturing archetype through Eastern European assembly footprint expansion. These Netherlands-origin, France-origin, and Sweden-origin entities exemplify how brand equity in adjacent garment care and kitchen categories translates into retail channel access across German and French premium markets.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Groupe SEB |
| Conair LLC |
| AB Electrolux |
| Rowenta |
| Haier Group Corporation |
| Jiffy Steamer |
| Panasonic Holdings Corporation |
| Hamilton Beach Brands, Inc. |
| Others |
Pricing and Supply Chain Analysis
Aluminum price index volatility on the London Metal Exchange cascades through European garment steamer manufacturing, compressing margins on 800W-1200W handheld units while amplifying pricing power for stainless steel boiler fabricators serving hospitality procurement.
Pricing Analysis
Warranty and service bundling separates premium standing systems with multi-year coverage from economy handheld units sold unprotected through mass retail. Three-tier pricing structure across premium, standard, and economy levels reflects CE marking intensity, REACH certification transparency, and after-sales network density. Pricing pressure stems from semiconductor sourcing bottlenecks for precision temperature controls. Household segments in Eastern European markets exhibit highest price sensitivity, while Italian fashion house procurement teams prioritize cycle speed over acquisition cost.
Supply Chain Analysis
Freight cost inflation across Asia-Europe container corridors elevates landed costs for precision electronics sourced from Taiwanese and South Korean foundries. Heating element fabrication concentrates in Germany, Italy, and China, with aluminum and stainless steel as core inputs. Single-source vulnerability in semiconductor procurement for smart-enabled units threatens production continuity. Distribution runs through Dutch and Belgian logistics hubs serving specialty retail channels across the Benelux corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European garment steamer manufacturing is becoming a vertical-integration race, with players pursuing captive control over precision temperature control semiconductor sourcing to defend margin structures against Asian foundry concentration.
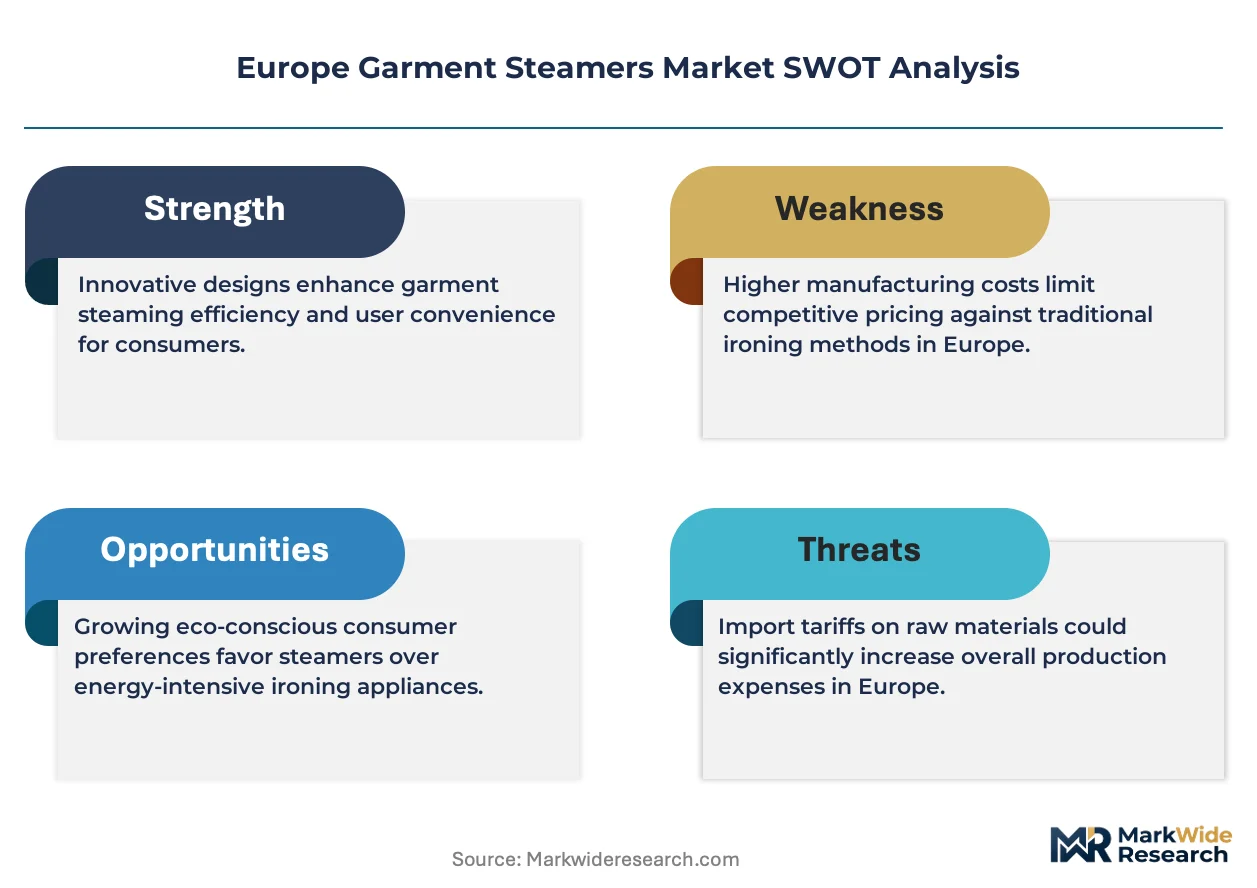
For Market Incumbents: Deploy backward integration into heating element fabrication to offset aluminum cost volatility and secure supply continuity for 1500W-1800W standing systems. Incumbents should consolidate service network density across German specialty retail channels to counter direct-to-consumer subscription models fragmenting accessory replenishment. REACH certification pooling through dry cleaner cooperatives offers defensive moat construction against regulatory compliance cost escalation. For New Entrants and Emerging Players: The 40-60% price gap between premium pressurized systems and economy steam units opens white-space opportunity in mid-tier standing configurations for Southern European boutique hotel procurement. Benelux cordless handheld penetration recovery represents the most penetrable geography, with Amsterdam urban demographics supporting digital-native go-to-market architectures through manufacturer app ecosystems rather than brick-and-mortar retail establishment. For Investors and Strategic Acquirers: Distressed-cycle entries favor hospitality-focused commercial system fabricators with established fleet maintenance contracts in Italian and Spanish markets over consumer electronics generalists facing margin compression. Long-term viability hinges on repairable design certification alignment with EU Green Deal circularity incentives. The signal to monitor is Ecodesign tier acceleration forcing redesign cycle compression on smaller manufacturers with limited regulatory affairs capacity.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Compliance Certification Pooling | Dry cleaner cooperatives in Germany share SVHC screening costs to maintain fleet market access. |
| Pressurized Boiler Technology Migration | Milan fashion houses specify 150°C sustained output systems for 40% faster delicate fabric processing. |
| Direct-to-Consumer Subscription Launch | Amsterdam and Copenhagen demographics drive recurring revenue for descaling solutions through manufacturer apps. |
| Eastern European Assembly Footprint Expansion | Sustainability-certified manufacturing in Poland and Romania serves Benelux export channels with reduced carbon intensity. |
| Cordless Handheld Product Line Introduction | Battery-powered variants address underpenetration in Dutch and Belgian urban retail corridors. |
Research Methodology
Independent corroboration across hospitality procurement directors, dry cleaner cooperative managers, and specialty retail category buyers underwrites the qualitative findings in this study. Primary interviews with plant engineers at heating element fabrication facilities, regulatory affairs leads navigating Ecodesign compliance, and brand managers at diversified appliance conglomerates combined with secondary validation from CE marking documentation, REACH SVHC registration databases, and EU customs trade records. Bottom-up unit shipment modeling and top-down value triangulation anchored the market sizing framework.
Comparable-period anchoring to historical installation base data and fleet replacement cycle analysis established the forecast window boundaries. Segmentation dimensions modeled include product type configuration, end-user application intensity, heating system technology architecture, and distribution channel structure. CAGRs were derived from elasticity-adjusted demand projections incorporating urban apartment density trends, boutique hotel linen service expansion rates, and professional textile services fleet refresh patterns across the analysis window.
Inputs from regulatory filing databases and hospitality procurement contract registries were available through the study window; gaps in real-time semiconductor inventory positioning introduce uncertainty bands around smart-enabled unit shipment forecasts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Global Electric Water Heaters Market
Appliances
United States Multi-Functional Oven Market
Appliances
United States Commercial Laundry Appliances Market
Appliances
Portable Dishwasher Market
Appliances
Glass Ceramic Cooktop Market
Appliances
Industrial Gas Stove Market
Appliances
Cordless Vacuum Cleaner Market
Appliances
Triple Barrel Waver Market
Appliances
UAE Dishwasher Market
Appliances
North America Washing Machine Market
Appliances
Global Massage Chairs Market
Appliances
AI Washing Machine Market
Appliances
Tumble Dryer Market
Appliances
Qatar Dishwashers Market
Appliances
Mexico Washing Machine Market
Appliances
Egypt Microwave Ovens Market