
 Stain Remover Products Market | 2026-2036
Stain Remover Products Market Size, Share, and Industry Trends Forecast 2026-2036
Stain Remover Products Market Outlook
China is tilting toward expanded surfactant and enzyme production capacity for household cleaning chemicals. Procter & Gamble leverages integrated supply chains across Asia-Pacific manufacturing zones. Henkel AG & Co. KGaA anchors European demand through specialized enzyme-based formulations. Church & Dwight Co. competes in the North American private-label segment with baking-soda-derived chemistry platforms.
Stain remover products comprise formulated cleaning agents containing surfactants, enzymes, oxidizers, or solvents designed to break down and lift discoloration from substrates without damaging base materials. These formulations typically operate within pH ranges of 6.5 to 11.0 depending on target stain chemistry, with protease and amylase enzymes handling protein and carbohydrate soils respectively. Liquid formulations dominate retail shelf space due to dosing convenience and pre-treatment functionality, while gel formats command premium positioning for targeted application on vertical surfaces and upholstery. The hospitality end-user segment represents the fastest-growing demand pool as hotel operators standardize on concentrated professional products to reduce linen replacement costs.
The EPA regulates antimicrobial claims under FIFRA, requiring registration for sanitizing stain removers while state-level Proposition 65 enforcement in California mandates disclosure of trace contaminants. The EU REACH framework restricts specific surfactant chemistries, pushing reformulation toward bio-based alternatives in exported product lines. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions, as these compounds historically served as grease-resistant treatments in carpet and upholstery applications.
Market Dynamics
Enzyme-based formulation chemistry is compressing surfactant volumes across professional cleaning segments, as hospitality operators prioritize protein-targeting performance over legacy oxidizer platforms to cut linen replacement costs.
Growth Catalysts
- California Proposition 65 enforcement:Chemical disclosure mandates are pulling reformulation investment toward trace-contaminant-free supply chains, opening premium positioning for compliant manufacturers.
- Commercial laundry service consolidation:Large-scale linen processors in the United States are standardizing procurement around concentrated professional-grade products to reduce per-pound chemistry costs.
- Enzyme stabilization technology:Cold-water protease activation is expanding addressable applications into temperature-sensitive upholstery and carpet cleaning protocols.
Market Restraints
- Surfactant input cost volatility:Palm kernel oil and petroleum-derived ethoxylate feedstocks face price pressure from competing biodiesel demand and refinery output shifts.
- Supply concentration in China:Bulk surfactant and intermediate manufacturing clusters in coastal provinces create single-source exposure for formulators dependent on imported alkyl polyglucosides.
- Technical limitation in PFAS replacement:Fluorinated grease-barrier chemistry for carpet applications lacks drop-in bio-based alternatives at equivalent performance thresholds.
Strategic Opportunities
- Underpenetrated institutional foodservice:Restaurant chains and contract catering operators in the United States represent untapped demand for pre-soak and spot-treatment protocols beyond current household penetration.
- EPA Safer Choice certification tailwind:Federal procurement preference for labeled products creates channel access advantages for qualifying formulations in government and educational facility contracts.
- Convergence of enzyme encapsulation with IoT-enabled dosing:Smart dispenser systems that adjust protease/amylase ratios based on soil sensors are enabling subscription-based supply models.
Industry Challenges
- Formulation chemist talent scarcity:Specialized expertise in enzyme-surfactant compatibility and pH stability optimization is concentrating at a handful of contract research organizations.
- REACH compliance timeline compression:EU notification requirements for novel bio-based surfactants are extending product development cycles by 18-24 months.
- Legacy equipment integration friction:Concentrated enzymatic formulations require recalibration of existing commercial laundry dosing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stain Remover Products Market |
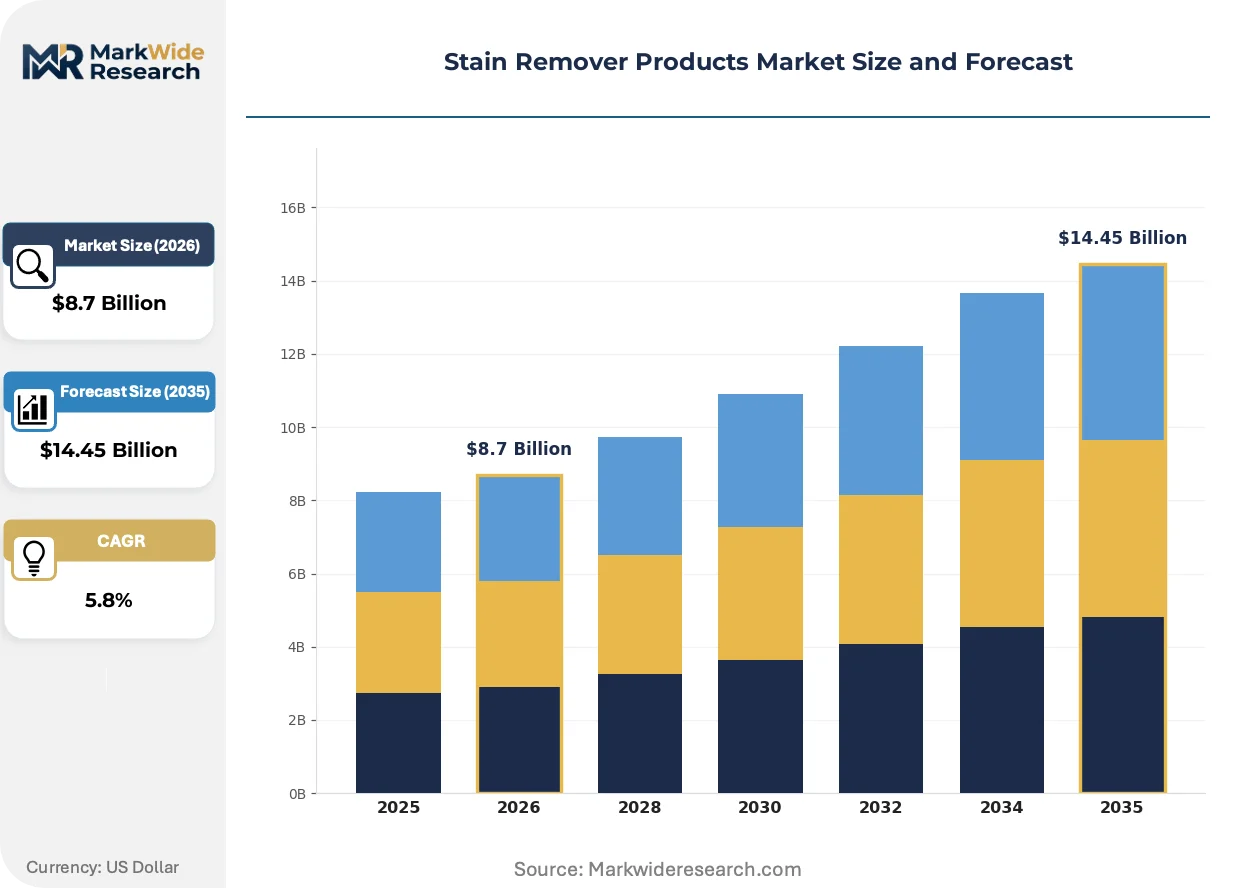
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Gel, Wipe End User: Household, Commercial, Industrial, Hospitality Application: Fabric, Carpet, Upholstery, Hard Surface Distribution Channel: Online, Supermarket, Specialty Store, Wholesale |
| Companies Covered | Unilever, Reckitt Benckiser Group, Procter & Gamble, Kao Corporation, Church & Dwight Co., The Clorox Company, Henkel AG & Co. KGaA, Seventh Generation, S.C. Johnson & Son, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stain Remover Products Market Strategic Shifts
Digital integration across formulation development and dosing control is compressing the gap between laboratory optimization and field performance, while regulatory chemistry restrictions and buyer procurement consolidation reshape competitive positioning.
Machine learning-assisted molecular design is digitizing enzyme discovery pipelines, reducing protease variant screening timelines from months to weeks. Contract manufacturers serving North American hospitality chains are deploying these platforms to customize stain-targeting cocktails for regional water hardness profiles. The structural consequence is digitizing the traditional surfactant-supplier relationship, as formulators gain in-house capability to specify enzyme properties rather than accepting off-the-shelf biocatalysts.
EU REACH restrictions on nonylphenol ethoxylate surfactants are forcing wholesale reformulation of industrial degreasing pre-treatments historically used in foodservice linen processing. German and Dutch formulators are accelerating bio-based alkyl polyglucoside substitution, though cold-water performance gaps persist. Private-label suppliers exporting to European hospitality operators face compressed margins as dual-registration costs for legacy and replacement chemistries overlap.
Centralized procurement by multi-property hotel groups is consolidating supplier relationships around integrated chemistry-plus-dispenser contracts. Third-party linen service providers in the United States are replacing transactional spot-buying with multi-year performance agreements tying pricing to soil-removal metrics. This concentration is most visible in the Southwest and Southeast, where regional hospitality chains are unbundling chemical supply from equipment leasing to capture direct formulation savings.
Stain Remover Products Market Segmentation
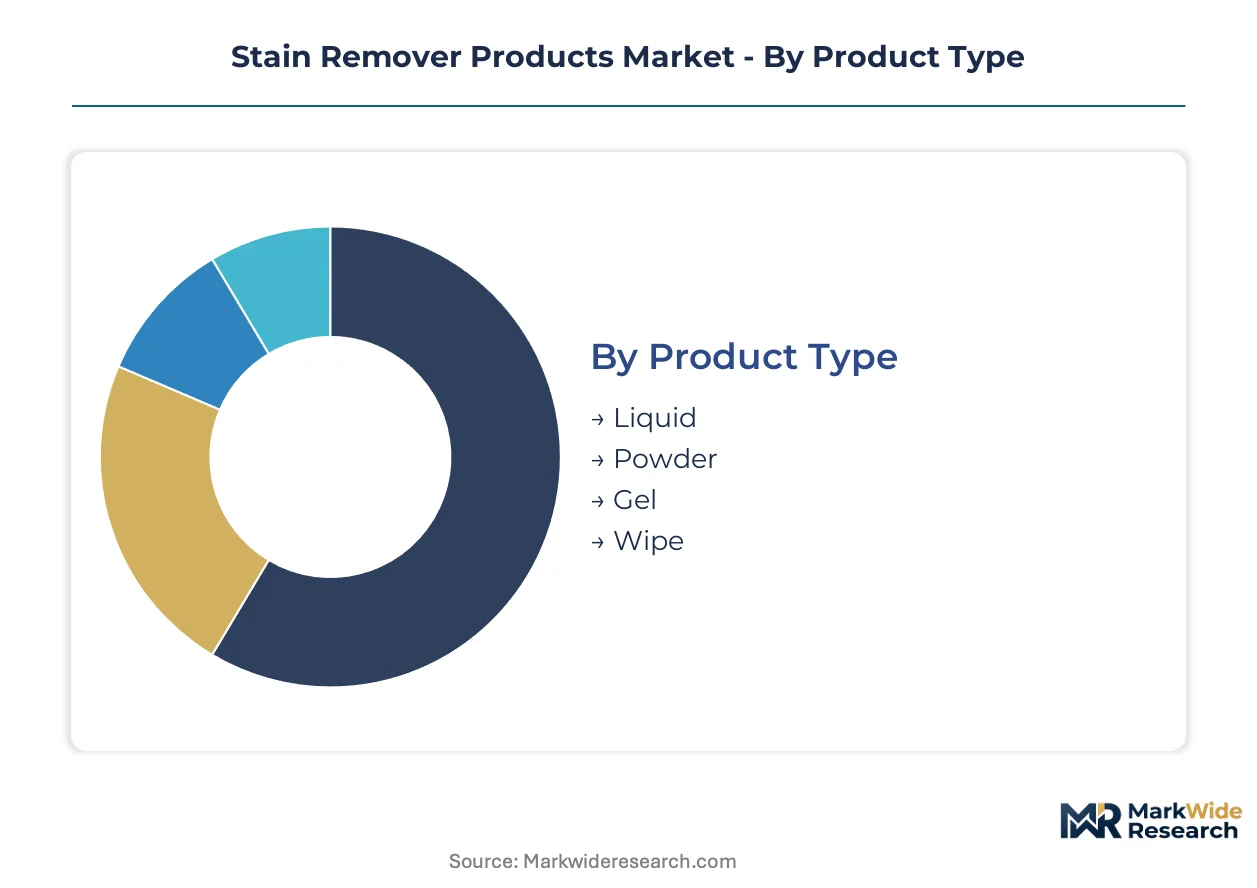
Segmentation in stain remover products reveals how formulation chemistry, end-use intensity, and procurement channels create divergent margin structures. Manufacturers configure supply chains differently for retail household formats versus concentrated professional deliveries to hospitality operators.
Product Type:
Mature liquid formats dominate shelf economics while emerging gel technologies capture premium positioning through targeted application control.
- Liquid:Surfactant-enzyme suspensions in aqueous bases enable pre-treatment dosing and washing machine compatibility. Hospitality procurement in the United States concentrates here as hotel chains standardize on concentrated bulk deliveries to reduce per-pound chemistry costs.
- Powder:Granular oxidizer-enzyme blends with extended shelf stability suit price-sensitive retail segments and hard-water geographies. Demand concentrates in developing markets where cold-chain logistics for liquid enzymes remain underdeveloped.
- Gel:Thickened formulations cling to vertical surfaces and upholstery fibers for controlled dwell time.
- Wipe:Pre-saturated substrates deliver single-use convenience for travel and emergency spot treatment.
Liquid handles the majority of throughput; gel is the fastest mover on share.
End User:
Cost tier separation runs from mass-market household purchasing to performance-contracted industrial operators with soil-removal metric pricing.
- Household:Retail-packaged formats with fragrance differentiation and dosing convenience drive repeat purchase. E-commerce subscription models in the United States are capturing pantry-loading behavior through auto-replenishment algorithms.
- Commercial:Contract laundry services and facility management operators procure concentrated formulations through integrated dispenser contracts. Regional hospitality chains in the Southwest and Southeast are unbundling chemical supply from equipment leasing to capture direct formulation savings.
- Industrial:Heavy-duty solvent and alkaline formulations serve manufacturing uniform services and disaster restoration contractors.
- Hospitality:Linen replacement cost pressure drives enzyme-based standardization across multi-property hotel groups.
Household moves the largest unit volumes; hospitality climbs the fastest as procurement consolidates around performance agreements.
Application:
Volume concentration aligns with substrate replacement economics—fabric commands scale while upholstery justifies premium chemistry.
- Fabric:Garment and linen processing represents the foundational use case across all end-user tiers. Commercial laundry service consolidation in the United States is standardizing procurement around concentrated professional-grade products to reduce per-pound chemistry costs.
- Carpet:Extraction-compatible formulations with low-foaming surfactant systems serve professional cleaning contractors. PFAS replacement challenges persist as fluorinated grease-barrier chemistry lacks drop-in bio-based alternatives at equivalent performance thresholds.
- Upholstery:pH-neutral enzyme systems protect delicate synthetic and natural fiber blends.
- Hard Surface:Alkaline degreasers and oxidizers target foodservice and institutional kitchen environments.
Fabric handles the majority of throughput; carpet is expanding most quickly on professional service contract growth.
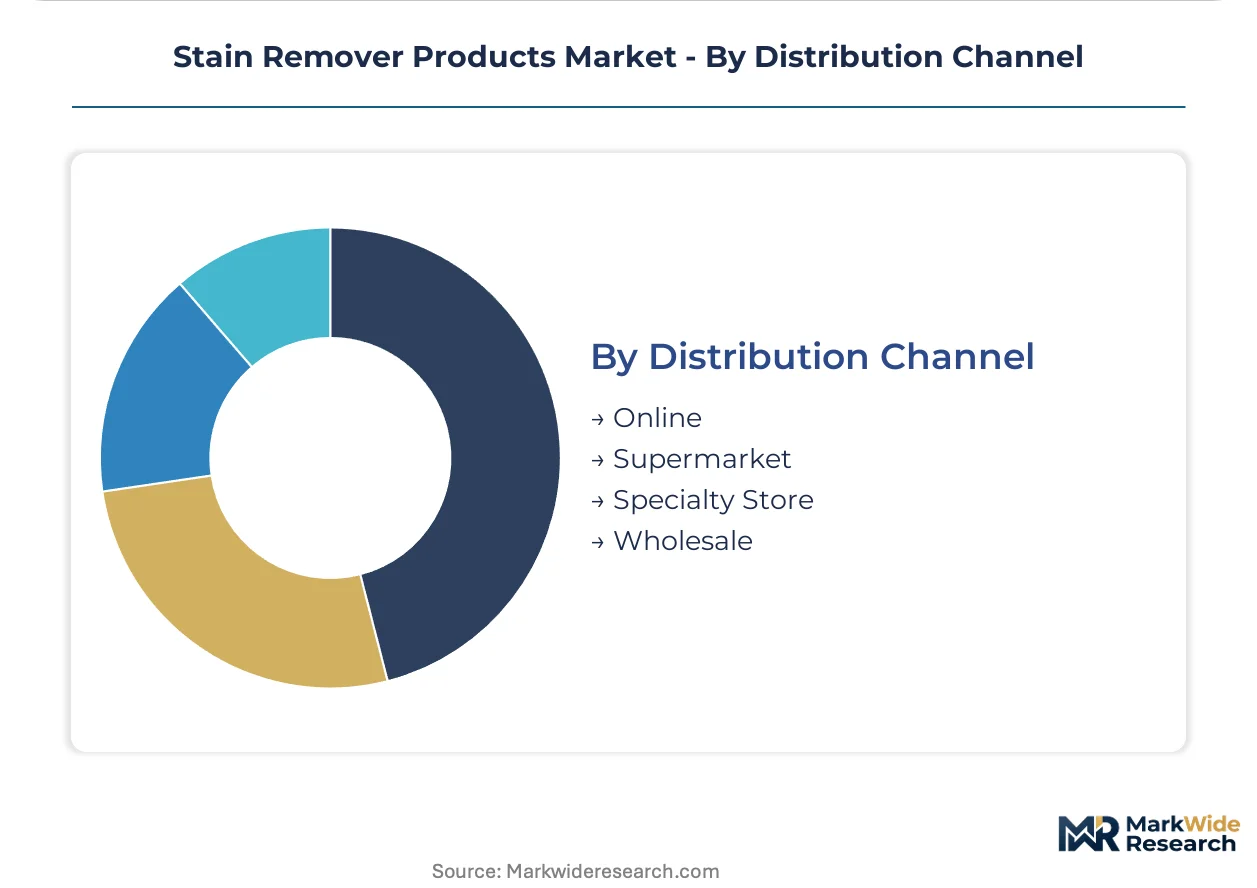
Distribution Channel:
Customer type separation distinguishes transactional retail purchasing from negotiated wholesale procurement with multi-year performance terms.
- Online:Direct-to-consumer subscription models and marketplace fulfillment capture convenience-oriented household demand. Smart dispenser systems that adjust protease/amylase ratios based on soil sensors are enabling subscription-based supply models through this channel.
- Supermarket:Mass retail shelf space competition drives packaging innovation and promotional frequency for household liquid formats.
- Specialty Store:Janitorial supply and home improvement channels serve commercial contractor and serious DIY segments.
- Wholesale:Institutional procurement through group purchasing organizations and linen service supply houses dominates hospitality and industrial volume.
Supermarket retains the largest transaction count; wholesale gains share fastest as hospitality procurement centralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bulk surfactant manufacturing clusters in China's coastal provinces supply intermediate chemistry to formulators worldwide, while enzyme production capacity expansion in Asia-Pacific feeds professional-grade product lines serving North American hospitality operators.
United States
Commercial laundry service consolidation drives concentrated procurement of professional-grade enzymatic formulations across the Southwest and Southeast. The EPA Safer Choice program creates federal procurement preference for certified products in government and educational facilities. Regional hospitality chains in Texas and Florida are unbundling chemical supply from equipment leasing to capture direct formulation savings.
China
Coastal manufacturing zones in Jiangsu and Zhejiang provinces anchor global alkyl polyglucoside and ethoxylate surfactant output for cleaning chemical formulators. The Ministry of Ecology and Environment enforces dual carbon goals that tighten emissions standards at chemical processing facilities. Yangtze River Delta industrial parks are expanding cold-chain logistics infrastructure to support liquid enzyme distribution for domestic household brands.
Germany
Specialized enzyme-based formulation development concentrates among contract research organizations serving European hospitality and industrial operators. ECHA REACH restrictions on nonylphenol ethoxylate surfactants force wholesale reformulation of industrial degreasing pre-treatments. The Rhine-Ruhr chemical corridor hosts bio-based surfactant substitution pilots targeting cold-water performance gaps in professional cleaning applications.
Japan
Precision enzyme stabilization technology development supports temperature-sensitive upholstery and carpet cleaning protocols for premium household segments. METI industrial standards guide pH-neutral formulation specifications for delicate fiber protection. The Kansai region maintains concentrated expertise in protease variant screening for customized stain-targeting cocktails.
India
Powder-format oxidizer-enzyme blends dominate price-sensitive retail segments where cold-chain logistics for liquid enzymes remain underdeveloped. BIS quality standards govern surfactant content disclosures in household cleaning products. Maharashtra and Gujarat industrial corridors are attracting contract manufacturing investment from multinational formulators seeking regional production bases.
Stain Remover Products Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in enzyme and surfactant supply. The vendor base organizes around three distinct tiers: multinational consumer goods conglomerates with integrated supply chains, regional formulators serving private-label and institutional accounts, and specialized enzyme technology licensors. Consolidation pressure concentrates at the middle tier as hospitality procurement centralization favors scale. Dominant competitive moves include multi-year performance agreements tying pricing to soil-removal metrics and backward integration into captive enzyme production.
Among diversified consumer goods conglomerates, Unilever, Procter & Gamble, and Henkel AG & Co. KGaA occupy positions that exemplify platform integration across household and professional segments. Unilever represents the Anglo-Dutch archetype with broad retail distribution infrastructure. Procter & Gamble anchors North American market presence through integrated Asia-Pacific manufacturing zones. Henkel AG & Co. KGaA exemplifies European specialization in enzyme-based chemistry platforms. These three entities sit within the top tier where formulation development, brand equity, and procurement scale reinforce competitive position.
| Leading Market Players |
|---|
| Unilever |
| Reckitt Benckiser Group |
| Procter & Gamble |
| Kao Corporation |
| Church & Dwight Co. |
| The Clorox Company |
| Henkel AG & Co. KGaA |
| Seventh Generation |
| S.C. Johnson & Son |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in China's Jiangsu and Zhejiang surfactant manufacturing corridors is compressing feedstock quotations while simultaneously eroding pricing power for formulators dependent on imported alkyl polyglucosides. This utilization imbalance rewards integrated producers with captive enzyme capacity while forcing merchant suppliers toward volume-based contract structures.
Pricing Analysis
EPA Safer Choice certification dictates the pricing tier structure across institutional procurement channels, separating premium-compliant formulations from standard-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with hospitality operators least sensitive due to linen replacement cost economics. Pricing pressure stems from palm kernel oil and petroleum-derived ethoxylate feedstock volatility driven by competing biodiesel demand. Household retail segments exhibit highest price sensitivity, gravitating toward private-label baking-soda-derived platforms.
Supply Chain Analysis
Palm kernel oil derivatives and petroleum-based ethoxylates anchor upstream feedstock exposure for surfactant-dependent formulators. Manufacturing concentrates in China, Germany, and the United States, with coastal Chinese provinces dominating bulk intermediate output. The supply chain draws from single-source vulnerability in Yangtze River Delta surfactant clusters subject to MEE emissions enforcement. Distribution runs through wholesale institutional procurement and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around EPA Safer Choice and REACH compliance creates durable defensive moats for incumbent formulators with established certification infrastructure and reformulation expertise.
For Market Incumbents: Insulate market position through backward integration into captive enzyme production and multi-year performance agreements tying pricing to soil-removal metrics. Cold-water protease activation R&D counters emerging gel-format specialists threatening upholstery applications. Certification investment in bio-based surfactant alternatives preempts REACH timeline compression risks. For New Entrants and Emerging Players: Pursue underpenetrated institutional foodservice segments in the United States where restaurant chains lack standardized pre-soak protocols. Smart dispenser integration with IoT-enabled dosing systems offers subscription-based entry against legacy equipment-dependent incumbents. Direct-to-commercial sales models bypass supermarket shelf-space barriers. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because hospitality procurement centralization favors scale players with integrated chemistry-plus-dispenser contracts. Acquisition targets include mid-tier contract manufacturers with EPA Safer Choice certification and Southwest/Southeast regional hospitality relationships. Monitor PFAS regulatory acceleration as inflection signal for bio-based formulation premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enzyme Production | Captive protease supply secures margin control against surfactant volatility and Chinese intermediate concentration. |
| EPA Safer Choice Certification Investment | Federal procurement preference unlocks government and educational facility contracts with multi-year revenue visibility. |
| IoT-Enabled Smart Dispenser Deployment | Soil-sensor-adjusted protease/amylase ratios enable subscription recurring revenue and customer lock-in. |
| Bio-Based Surfactant Substitution | REACH-compliant alkyl polyglucoside platforms preempt EU regulatory restriction and margin compression. |
| Multi-Property Hospitality Performance Agreements | Soil-removal metric pricing aligns supplier incentives with hotel operator linen replacement cost reduction goals. |
Study Parameters
Desk research of customs trade databases, EPA registration filings, and hospitality procurement contract disclosures preceded structured interviews with formulation chemists, commercial laundry procurement directors, hotel chain operations executives, and janitorial supply distributors. Primary fieldwork across Jiangsu manufacturing zones and Southwest United States hospitality clusters validated secondary trade flow analysis. Bottom-up product-level volume builds triangulated against top-down category spend estimates from institutional purchasing cooperatives.
Assumptions held fixed include regulatory enforcement timelines for PFAS restrictions and MEE emissions standards, while surfactant feedstock price trajectories and hospitality occupancy recovery patterns varied across scenario branches. Segmentation modeling spanned formulation chemistry, end-user tier, application substrate, and distribution channel dimensions. CAGRs derived from fitted growth curves against historical procurement volume patterns and enzyme adoption S-curve penetration rates.
Sensitivities concentrate around REACH notification delays extending bio-based surfactant commercialization timelines and California Proposition 65 enforcement acceleration forcing trace-contaminant supply chain restructuring. Forecasts reflect these documented assumptions with acknowledged revision triggers from palm kernel oil commodity shocks or hospitality sector consolidation waves. Cross-checking against Cefic surfactant production statistics and AHLA hospitality linen spend surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Car Wash Detergents and Soaps Market
Cleaning Equipment
Smart Cleaning and Hygiene Market
Cleaning Equipment
Cleaning Trolleys Market
Cleaning Equipment
US Cleaning Products Market
Cleaning Equipment
Canister Vacuum Cleaners Market
Cleaning Equipment
Laundry Detergent Market
Cleaning Equipment
Brush Cleaner Market
Cleaning Equipment
Floor Cleaning Device Market
Cleaning Equipment
Laundry Scent Booster Market
Cleaning Equipment
North America Smart Commercial Restroom Products Market
Cleaning Equipment
Carpet Cleaning Products Market
Cleaning Equipment
Spin Mops Market
Cleaning Equipment
Screen Cleaner Market
Cleaning Equipment
Hand Cleaning Accessories Market
Cleaning Equipment
Bathroom Mirror Wiper Market
Cleaning Equipment
Laundry Sanitizer Market