
 Europe Paint Packaging Market | 2026-2036
Europe Paint Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Paint Packaging Market Analytics
Skilled metal-forming and polymer-coating labor availability is redrawing competitive boundaries across the Europe Paint Packaging Market. Trivium Packaging leverages its integrated steel and aluminum capabilities to serve premium coating brands with consistent specification adherence. Blechwarenfabrik Limburg GmbH anchors its position through deep specialization in tinplate pails for industrial solvent-based paints. Crown Holdings competes via scale advantages in drawn-and-ironed can production across multiple European manufacturing sites.
Europe paint packaging encompasses rigid containers engineered to store, transport, and dispense liquid, paste, or powder coatings while preventing contamination, evaporation, and hazardous leakage; specifications typically address chemical resistance, stack-load tolerance, and compatibility with automated filling lines at viscosities ranging from stains to high-build epoxies. Metal drums and pails retain dominance in industrial and automotive applications where UN-certified hazardous-goods compliance and mechanical durability command premium positioning. Plastic pails and cans are gaining structural share in residential and DIY channels where weight reduction and rust elimination drive specification changes.
REACH compliance through ECHA, CE marking under EU harmonized standards, and the EU Packaging and Packaging Waste Regulation collectively mandate recyclability thresholds and substance restrictions that reshape material selection and design protocols for paint containers. EMA and national environmental agencies in France and Germany enforce extended producer responsibility schemes that transfer end-of-life collection costs upstream to packaging manufacturers. Stakeholders must monitor PPWR implementation timelines and recyclability performance benchmarks to align capital allocation with compliance-driven specification shifts.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing design cycles across Europe Paint Packaging Market, forcing converters to requalify materials and accelerate mono-material transitions before recyclability mandates take full effect.
Growth Catalysts
- Residential renovation activity:Germany and France are experiencing sustained demand for decorative coatings as homeowners prioritize energy-efficient building envelope upgrades. DIY retailers are expanding pail and can assortments to capture this volume.
- REACH substance restrictions:ECHA's evolving candidate list is eliminating legacy stabilizers and pigments, creating specification windows for compliant container linings and barrier technologies that prevent chemical leaching.
- Automotive OEM clustering:Germany's industrial corridor concentrates coating demand from vehicle manufacturers and tier suppliers, generating predictable drum and pail offtake with stringent quality protocols.
Market Restraints
- Tinplate supply concentration:European steel mill capacity for food-grade and packaging-grade tinplate is narrowing, exposing pail manufacturers to input cost volatility and allocation risk during mill maintenance cycles.
- Recycled polymer feedstock scarcity:Post-consumer recycled polypropylene suitable for paint contact applications remains limited, constraining converters' ability to meet PPWR recycled-content thresholds at scale.
- UN certification bottlenecks:Hazardous goods testing facilities for industrial solvent-based paints are backlogged, extending time-to-market for new drum designs serving automotive and marine coatings.
Strategic Opportunities
- Poland's manufacturing expansion:Central European coating production is migrating eastward, creating demand for regional pail and can supply that reduces logistics costs from traditional German and Benelux sources.
- Waterborne coating transition:Architectural paint formulators are reformulating away from solvents, enabling lighter plastic pail specifications that eliminate corrosion barriers and reduce shipping weight.
- Digital printing integration:Direct-to-object inkjet systems are converging with automated filling lines, allowing batch-specific labeling and eliminating pre-printed inventory risk for seasonal color collections.
Industry Challenges
- Polymer-coating technician scarcity:Specialized skills for applying internal linings to metal drums are retiring from European workforce faster than apprenticeship programs can replenish, constraining quality throughput.
- Legacy filling line incompatibility:Automated paint plants built for cylindrical steel pails require mechanical retrofitting to handle tapered plastic alternatives, extending capital payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Paint Packaging Market |
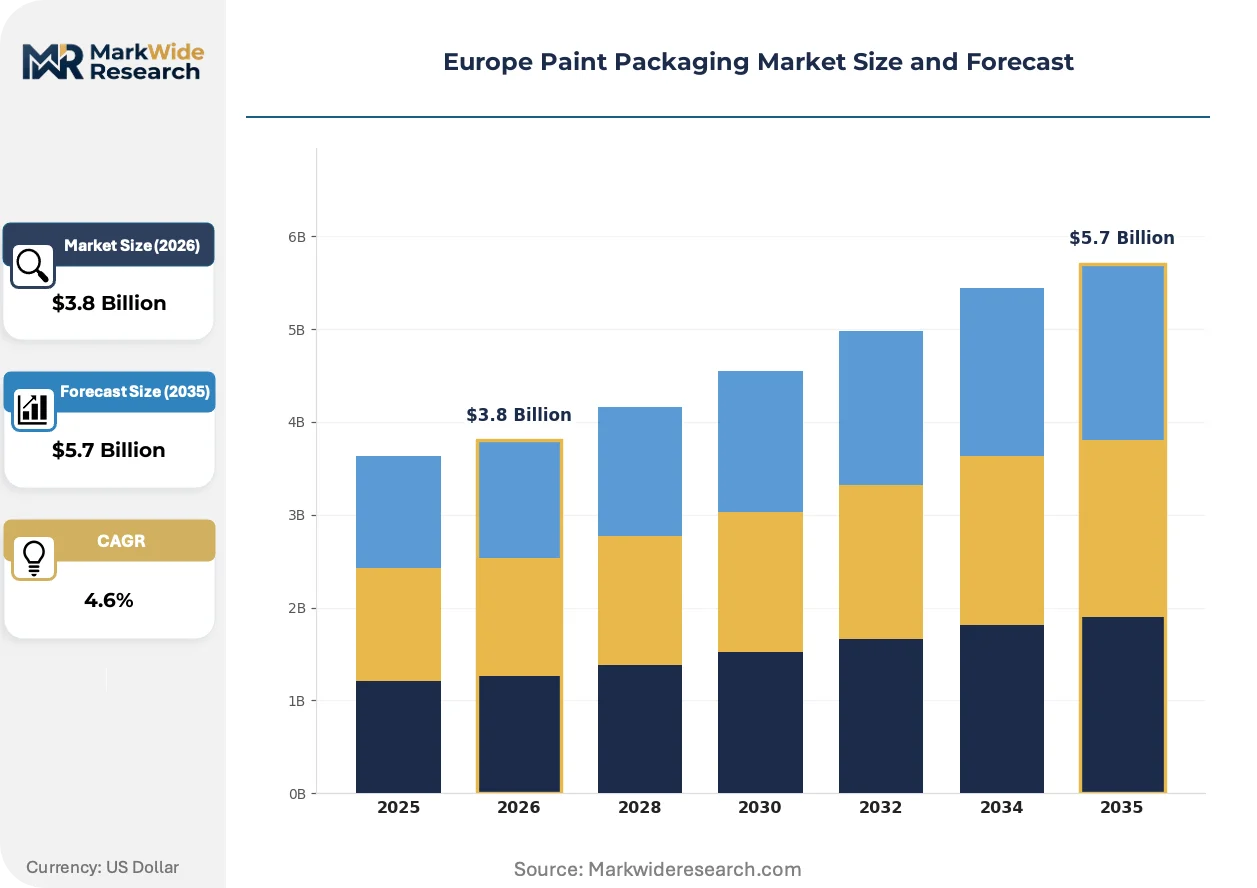
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Drums, Cans, Pails, Cartons Material: Plastic, Metal, Glass, Paperboard Application: Residential, Commercial, Industrial, Automotive End User: Contractors, DIY Enthusiasts, Retailers, Wholesalers |
| Companies Covered | Trivium Packaging, Blechwarenfabrik Limburg GmbH, Sonoco Products Company, Crown Holdings, Emballator Packaging Ltd, Colep Packaging, Muhr & Söhne, P. Wilkinson Containers Ltd, Silgan Holdings Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Paint Packaging Market Evolving Landscape
Material science and regulatory compliance are colliding across Europe Paint Packaging Market, producing container designs that must simultaneously satisfy chemical resistance, mechanical durability, and end-of-life recyclability without trade-off penalties.
Mono-material polypropylene pails are bifurcating the residential paint segment. These containers eliminate metal components and multi-layer barriers, enabling pure polymer recycling streams. German and French DIY chains are specifying them for waterborne interior paints. The technology is compressing demand for traditional tinplate cans in non-hazardous architectural applications.
REACH authorization requirements are tightening substance controls for packaging materials in contact with coatings. ECHA's sunset dates for specific phthalates and heavy metal pigments are forcing reformulation of internal drum linings. Industrial paint manufacturers serving automotive OEMs are most affected, accelerating qualification of fluoropolymer and epoxy-phenolic alternatives.
Renovation contractors are consolidating paint purchasing through specialized distributors rather than retail channels. These intermediaries demand private-label pail programs with customized sizing and color-matched lids. France's professional painting sector exhibits this pattern most visibly, with regional cooperatives capturing specification influence from national retailers.
Europe Paint Packaging Market Segmentation
Packaging specification varies sharply across Europe's paint value chain. Container selection depends on coating chemistry, distribution channel, and regulatory compliance requirements rather than cost alone.
Packaging Type:
German and French domestic demand concentrates in rigid formats for waterborne architectural coatings, while export-led industrial segments favor UN-certified configurations for hazardous solvent-based systems.
- Drums:Steel drums with epoxy-phenolic linings handle solvent-based industrial coatings and marine paints. German automotive OEMs in Baden-Württemberg specify these for two-component epoxy primers requiring mechanical durability and chemical resistance.
- Cans:Drawn-and-ironed tinplate cans dominate decorative paint retail in France and Italy. DIY chains specify these for interior latex paints where rust elimination and lightweight handling drive specification shifts toward polymer alternatives.
- Pails:Injection-molded polypropylene pails with integrated handles serve professional contractors across Benelux and Scandinavia.
- Cartons:Bag-in-box formats for powder coatings and specialty stains reduce shipping cube in Nordic export markets.
Drums command the established base. The steepest expansion runs through pails.
Material:
Cost tiers separate commodity residential applications from premium industrial specifications requiring certified barrier performance.
- Plastic:Polypropylene homopolymer and copolymer resins enable mono-material recyclability under PPWR mandates. French retailers are specifying these for waterborne interior paints to eliminate corrosion risk and reduce shelf weight.
- Metal:Tinplate and cold-rolled steel with internal polymer coatings retain dominance in hazardous-goods applications. REACH authorization timelines for legacy lining chemistries are forcing qualification of fluoropolymer alternatives in German automotive coating supply chains.
- Glass:Borosilicate and soda-lime containers serve specialty artist colors and high-value wood stains in Italian and Spanish craft segments.
- Paperboard:Liquid packaging board with polymer barriers targets powder coatings and dry-mix plasters in Central European distribution.
Metal retains the volume base. Plastic is climbing the fastest as waterborne formulations expand.
Application:
Customer maturity separates price-sensitive residential renovation from specification-driven industrial procurement.
- Residential:Decorative coatings for home renovation and new construction. German homeowners prioritizing energy-efficient envelope upgrades are driving pail demand through Baumarkt and Obi retail networks.
- Commercial:Architectural coatings for offices, retail, and institutional buildings. French professional painting cooperatives specify private-label formats with color-matched lids.
- Industrial:Protective and marine coatings requiring UN-certified packaging. Solvent-based epoxies for offshore platforms and infrastructure concentrate demand in Dutch and Belgian port logistics corridors.
- Automotive:OEM and refinish coatings with stringent quality protocols. Stuttgart and Munich manufacturing clusters generate predictable drum offtake with specification adherence requirements.
Industrial applications anchor the revenue base. Residential renovation is gaining share fastest.
End User:
Procurement patterns diverge between specification-influencing intermediaries and volume-driven retail channels.
- Contractors:Professional painting firms purchasing through specialized distributors. French regional cooperatives are consolidating specification influence away from national retailers.
- DIY Enthusiasts:Homeowners buying through hardware superstores and online marketplaces. German energy renovation subsidies are expanding this segment's pail and can volume.
- Retailers:DIY chains and home improvement centers with private-label programs. Leroy Merlin and Bauhaus specify customized sizing for seasonal color collections.
- Wholesalers:Industrial coating distributors serving automotive and marine OEMs. These intermediaries demand just-in-time drum supply with batch-specific documentation.
Contractors command the specification base. DIY enthusiasts are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH framework anchors German specification leadership across the Europe Paint Packaging Market, with national regulators in France and Italy enforcing complementary substance restrictions that reshape container design protocols.
Germany
Energy-efficient building renovation subsidies are expanding decorative paint demand through Obi and Bauhaus retail networks. ECHA's sunset dates for phthalate-based drum linings are accelerating fluoropolymer qualification timelines. Stuttgart and Munich automotive clusters generate predictable drum offtake for two-component epoxy primers with stringent mechanical durability requirements.
France
Professional painting cooperatives are consolidating specification influence away from national retailers through private-label pail programs with color-matched lids. ANSM enforces extended producer responsibility schemes that transfer end-of-life collection costs upstream to packaging manufacturers. Île-de-France and Provence-Alpes-Côte d'Azur distribution corridors concentrate demand for waterborne interior paint containers.
Italy
Specialty artist colors and high-value wood stains sustain borosilicate glass container demand in craft segments across Tuscany and Emilia-Romagna. CE marking under EU harmonized standards mandates recyclability thresholds for packaging entering Italian distribution. Lombardy and Veneto coating formulators are qualifying mono-material polypropylene alternatives to traditional tinplate cans.
Poland
Central European coating production migration is creating regional pail and can demand that reduces logistics costs from traditional German and Benelux sources. The country's national environmental agency implements PPWR-aligned recyclability benchmarks for imported packaging. Warsaw and Kraków manufacturing zones are attracting filling line investments serving export markets.
Netherlands
Rotterdam and Antwerp port logistics corridors concentrate demand for UN-certified drums serving solvent-based marine and offshore platform coatings. The Dutch national packaging regulator enforces EPR schemes that accelerate mono-material transitions before full PPWR implementation. North Sea protective coatings generate specialized hazardous-goods container specifications.
Europe Paint Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the Europe Paint Packaging Market exhibiting tiered concentration around metal-forming capabilities and polymer-coating expertise. The upper tier commands specification influence through captive steel and aluminum supply chains, while mid-tier fabricators compete on regional responsiveness and custom sizing. Three archetypes dominate: integrated metal converters with upstream material control, specialized tinplate pail manufacturers with deep industrial solvent expertise, and plastic injection molders capturing waterborne architectural transitions. Competitive moves center on mono-material requalification investments and Poland manufacturing expansion to serve eastward production migration.
Among German-based fabricators, Blechwarenfabrik Limburg GmbH exemplifies the specialized tinplate tier through its concentration on industrial solvent-based paint containers. Trivium Packaging anchors the integrated metal converter archetype with steel and aluminum capabilities serving premium coating brands. Crown Holdings occupies a position within the scale-driven drawn-and-ironed can segment across multiple European manufacturing sites. These three entities represent distinct capability configurations that shape procurement alternatives for automotive OEMs, DIY retailers, and professional painting cooperatives.
| Leading Market Players |
|---|
| Trivium Packaging |
| Blechwarenfabrik Limburg GmbH |
| Sonoco Products Company |
| Crown Holdings |
| Emballator Packaging Ltd |
| Colep Packaging |
| Muhr & Söhne |
| P. Wilkinson Containers Ltd |
| Silgan Holdings Inc. |
| Others |
Value Network & Pricing Analysis
UN certification requirements for hazardous-goods containers gate both supplier qualification timelines and price differentiation across the Europe Paint Packaging Market, compressing margins for converters unable to secure Rotterdam or Hamburg testing facility slots while allowing certified incumbents to command sustained premiums for automotive and marine coating applications.
Pricing Analysis
Price spreads between German automotive drum specifications and Polish residential pail alternatives reflect certification-grade stratification rather than raw material cost alone. Three-tier pricing structure across UN-certified industrial, food-grade compliant, and standard residential tiers separates hazardous-goods containers with epoxy-phenolic linings from waterborne architectural alternatives. Cost compression in the mid-tier standard segment is intensifying because tinplate mill allocation cycles expose fabricators to input volatility. DIY retailers exhibit highest price sensitivity, while automotive OEM procurement teams prioritize specification adherence over unit cost.
Supply Chain Analysis
Rotterdam port congestion and container availability fluctuations on Asia-Europe trade lanes are elevating inbound logistics costs for polymer resin shipments serving Central European injection molders. Supply concentrates in Germany, Poland, and the Netherlands, with steel drum fabrication anchored in the Ruhr industrial corridor and polypropylene pail molding expanding around Warsaw manufacturing zones. Raw material dependencies center on cold-rolled steel from ThyssenKrupp and Borealis polymer feedstock. Single-source vulnerability runs through tinplate mill concentration in Western Europe. Distribution runs through specialized coating distributors and DIY retail networks with regional consolidation patterns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across the Europe Paint Packaging Market as waterborne coating transitions and PPWR recyclability mandates create specification niches that reward specialized qualification capabilities over scale economics.
For Market Incumbents: Consolidate polymer-coating technician training programs through German and Polish apprenticeship partnerships to offset workforce attrition threatening quality throughput. Secure captive tinplate supply agreements with ArcelorMittal or Tata Steel Europe to defend against mill allocation risk during maintenance cycles. Prioritize fluoropolymer lining qualification investments ahead of ECHA sunset dates for legacy phthalate-based chemistries.
For New Entrants and Emerging Players: ECHA fast-track authorization for recycled-content polypropylene formulations offers entry pathway into French and German DIY private-label programs. Target Poland's Central European manufacturing expansion with regional pail supply reducing logistics costs from traditional Benelux sources. Pursue waterborne architectural segment penetration through mono-material recyclability positioning aligned with retailer sustainability procurement criteria.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across polypropylene injection molding as equipment standardization reduces barrier to entry for recycled-content production. Long-term viability favors fabricators with dual metal-and-plastic capability portfolios serving both industrial hazardous-goods and residential waterborne transitions. Watch ECHA authorization timelines for fluoropolymer alternatives as signal for margin compression in legacy lining-dependent drum manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Transition Investment | Enables PPWR compliance for waterborne paint containers in French DIY networks. |
| Poland Manufacturing Footprint Expansion | Captures Central European coating production migration reducing German logistics dependency. |
| Fluoropolymer Lining Qualification | Secures automotive OEM drum supply ahead of ECHA phthalate sunset dates. |
| Recycled Polypropylene Feedstock Partnership | Addresses scarcity constraining converters' ability to meet PPWR content thresholds. |
| Digital Printing Integration | Eliminates pre-printed inventory risk for seasonal color collections at Leroy Merlin. |
Research Methodology
The analysis maps metal drum fabrication, plastic pail molding, and hybrid container sub-sectors, each validated through procurement managers at automotive OEMs, technical directors at industrial coating formulators, category buyers at DIY retail chains, and polymer-coating technicians at German fabricators. Primary interview findings triangulate against secondary sources including ECHA REACH substance databases, EU Packaging and Packaging Waste Regulation implementation documents, Cefic chemical industry reports, and customs trade flow data. Bottom-up capacity assessments and top-down demand modeling converge through cross-validation against automotive production clusters and renovation subsidy disbursement records.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include packaging format, material chemistry, coating application, and end-user procurement channel. CAGRs derive from trend extrapolation of waterborne formulation penetration, PPWR implementation phase-ins, and Central European manufacturing relocation patterns. Industry-specific inputs incorporate ECHA authorization timelines, tinplate mill capacity utilization, and recycled polymer feedstock availability curves.
Underlying assumptions cover regulatory implementation schedules, raw material cost stability, and technician workforce replenishment rates, with deviation risk concentrated in ECHA substance restriction acceleration, tinplate supply disruption events, and Poland infrastructure buildout delays. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Liquid Encapsulation Market
Packaging Materials
Global Adherence Packaging Market
Packaging Materials
Non-Plastic Punnets Market
Packaging Materials
Insulated Thermal Box Liners Market
Packaging Materials
Foil Laminates Market
Packaging Materials
Single-Use Packaging Market
Packaging Materials
Cold Form Foil Market
Packaging Materials
Cavitated Films Market
Packaging Materials
Neoprene Coffee Sleeves Market
Packaging Materials
Crimped End Mailing Tubes Market
Packaging Materials
Construction Films Market
Packaging Materials
France Packaging Market
Packaging Materials
PCR Packaging Market
Packaging Materials
Primary Packaging Market
Packaging Materials
Cutting Tool Packaging Market
Packaging Materials
Lubricant Packaging Market