
 Acid Chlorides Market | 2026-2036
Acid Chlorides Market Size, Share, and Industry Trends Forecast 2026-2036
Acid Chlorides Market Outlook
Multi-source procurement for thionyl chloride and benzoyl chloride intermediates is hardening across pharmaceutical and agrochemical value chains. CABB Group GmbH anchors European supply through integrated chlorination infrastructure at its German manufacturing sites. BASF leverages backward integration into acetyl chloride to secure feedstock for its downstream agrochemical portfolio. Shiva Pharmachem Ltd. specializes in chlorobenzoyl chloride variants for dye intermediate producers across South Asia.
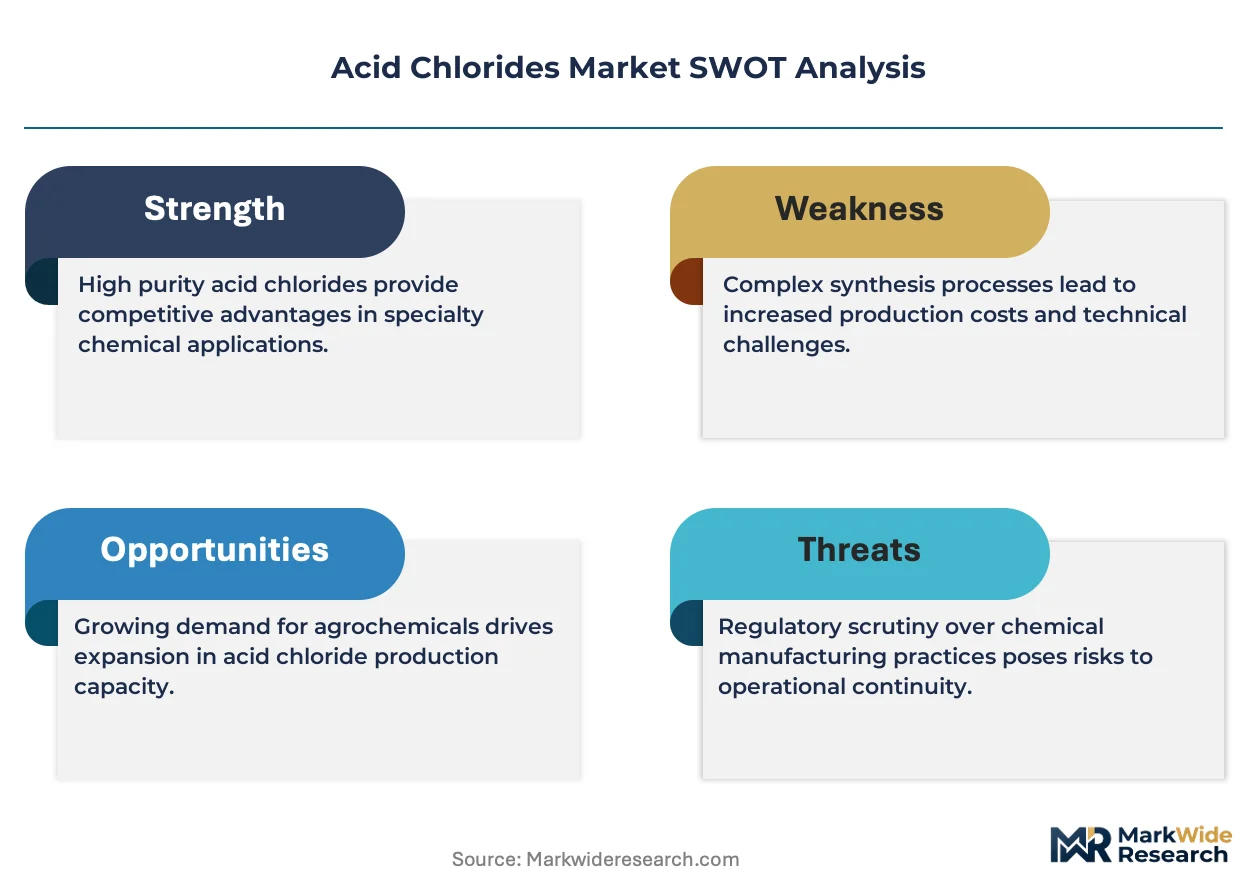
Acid chlorides are acyl derivatives synthesized via reaction of carboxylic acids with thionyl chloride, phosphorus trichloride, or phosgene, yielding highly reactive carbonyl electrophiles that acylate alcohols, amines, and aromatic substrates. Pharmaceutical applications command the largest value share, as benzoyl chloride serves as a critical building block for benzamide APIs and local anesthetics, while agrochemical demand for acetyl chloride in acetanilide herbicides shows the fastest volume growth. Thionyl chloride dominates product-type revenue due to its dual role as chlorinating agent and acid chloride precursor, though chlorobenzoyl chloride carries premium pricing for specialized dye chemistry.
EPA oversight in the United States governs emissions from phosgene-based production routes, while REACH registration in Europe mandates full toxicological dossiers for chlorinated acyl derivatives imported above one-ton thresholds. China's MEE enforces wastewater discharge limits on thionyl chloride manufacturers in the Yangtze River basin, reshaping plant relocation decisions. Stakeholders must monitor regulatory divergence on chlorinated intermediate classifications to anticipate compliance cost fragmentation across manufacturing footprints.
Market Dynamics
Pharmaceutical API synthesis is pulling benzoyl and acetyl chloride consumption upward, while REACH and RoHS compliance in Europe is hardening purity specifications and waste-handling protocols for chlorinated intermediates across manufacturing footprints.
Growth Catalysts
- Active pharmaceutical ingredient demand:Benzoyl chloride serves as a critical building block for benzamide APIs and local anesthetics, with pharmaceutical companies expanding acylation chemistry capacity.
- REACH registration thresholds:Full toxicological dossiers for chlorinated acyl derivatives imported above one-ton thresholds are consolidating supplier bases toward compliant manufacturers.
- Acetanilide herbicide production:Agrochemical formulators are scaling acetyl chloride consumption for crop protection chemistry across South Asian and Chinese manufacturing clusters.
Market Restraints
- Phosgene route emissions:EPA oversight in the United States governs emissions from phosgene-based production, elevating compliance costs for non-integrated producers.
- Thionyl chloride supply concentration:Captive production in Chinese agrochemical and dye manufacturers limits third-party availability for European and North American buyers.
- Alcohol-amine acylation substitutes:Carbodiimide coupling reagents and activated ester methods are displacing acid chloride routes in peptide synthesis applications.
Strategic Opportunities
- India specialty chemical expansion:Chlorobenzoyl chloride variants for dye intermediate producers present white space as domestic Indian manufacturers seek backward integration.
- Green chlorination chemistry:Catalytic thionyl chloride recycling and phosgene-free acylation protocols align with EU Green Deal decarbonization mandates.
- Multi-source procurement platforms:Digital marketplaces for thionyl chloride and benzoyl chloride intermediates are emerging to reduce pharmaceutical value chain concentration risk.
Industry Challenges
- Chlorination process safety expertise:Phosgene and thionyl chloride handling requires specialized occupational safety competencies that contract manufacturers struggle to staff.
- Wastewater discharge compliance:China's MEE enforces stringent limits on thionyl chloride manufacturers in the Yangtze River basin, forcing plant relocation decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acid Chlorides Market |
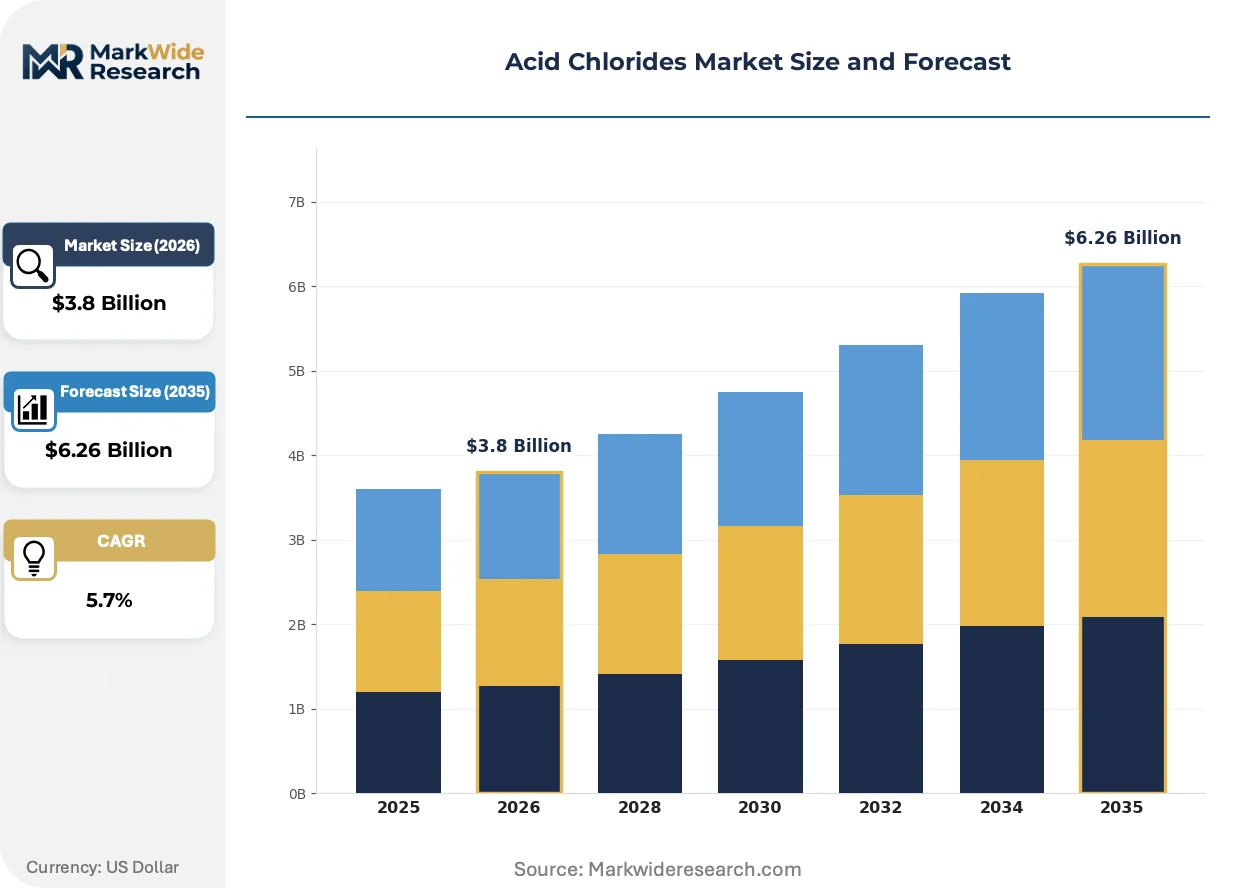
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acetyl Chloride, Benzoyl Chloride, Thionyl Chloride, Chlorobenzoyl Chloride Application: Pharmaceuticals, Agrochemicals, Dyes, Polymers End User: Chemical Manufacturers, Research Institutions, Pharmaceutical Companies, Agricultural Firms Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | VanDeMark, NOF, BASF, Transpek Industry Limited, Wilmar International, ALTIVIA, Nippon Fine Chemical, Shiva Pharmachem Ltd., CABB Group GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acid Chlorides Market Strategic Shifts
Continuous flow chlorination reactors and closed-loop thionyl chloride recovery systems are reshaping production economics, while regulatory divergence on chlorinated intermediate classifications is fragmenting compliance architectures across manufacturing footprints.
Continuous flow microreactor technology for acid chloride synthesis is electrifying process safety and yield consistency in pharmaceutical intermediate manufacturing. Contract development and manufacturing organizations are adopting these systems to reduce hold-up volumes of reactive chlorinating agents. This technology is electrifying the displacement of batch phosgenation in high-value API precursor production.
REACH authorization and restriction procedures for chlorinated acyl derivatives are tightening substance dossier requirements across European value chains. ECHA evaluations of persistent organic pollutant characteristics are extending registration timelines for thionyl chloride derivatives. Specialty chemical importers are responding by establishing EU-based toll manufacturing partnerships to maintain market access.
Pharmaceutical buyers are consolidating acid chloride supplier panels to dual-source minimums from REACH-registered and FDA-inspected facilities. Long-term offtake agreements with integrated chlorination specialists are displacing spot market procurement for benzoyl chloride and chlorobenzoyl variants. This consolidation is most visible among generic API manufacturers in India seeking audit-ready supply chains for US and European filings.
Acid Chlorides Market Segmentation
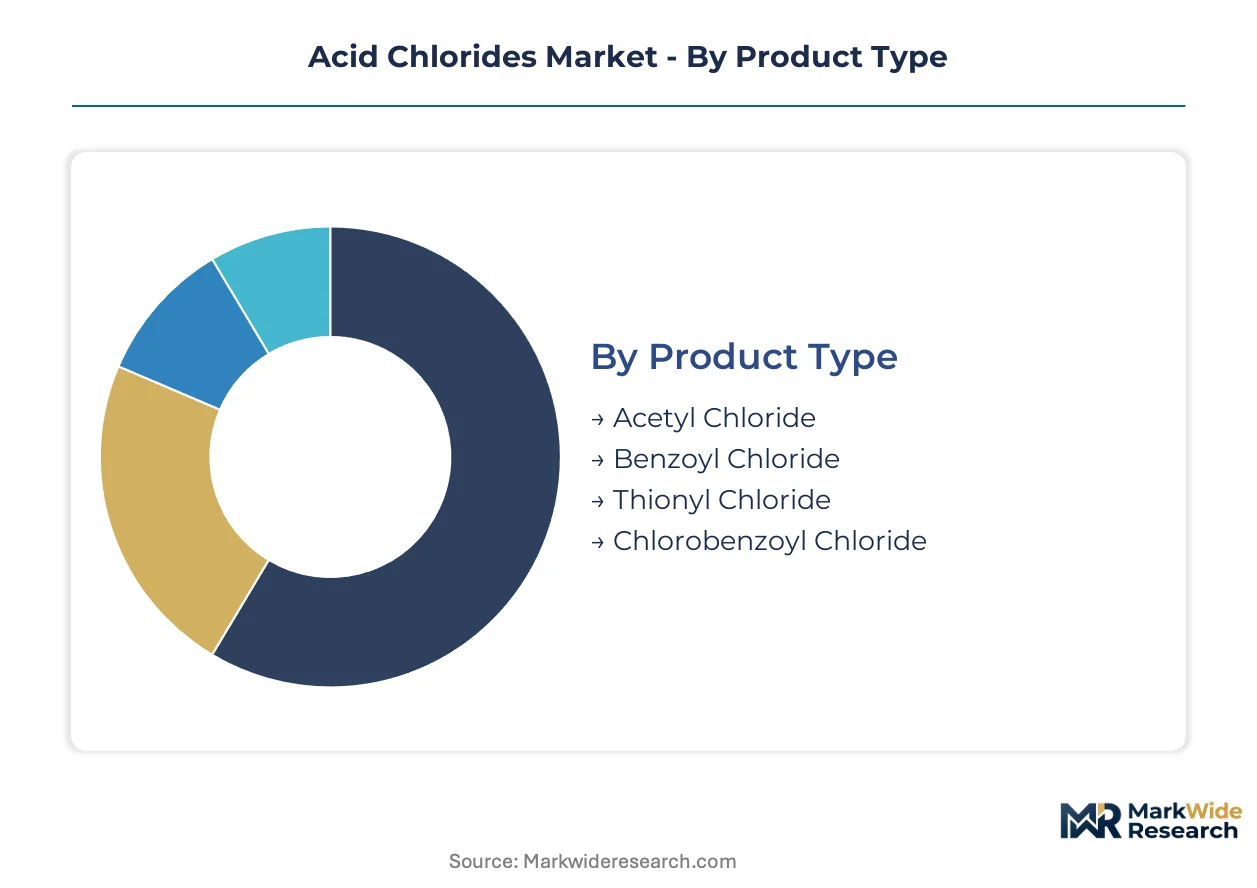
Acid chloride procurement patterns diverge sharply across product chemistries and end-use specifications. Pharmaceutical formulators prioritize benzoyl chloride purity grades, while agrochemical buyers optimize acetyl chloride volume contracts. Understanding these segment boundaries reveals where margin pools concentrate and where supply security risks accumulate.
Product Type:
Supply concentration for chlorinating agents and acid chloride precursors varies dramatically by molecular complexity and regulatory burden.
- Thionyl Chloride:This dual-use chlorinating agent dominates revenue due to its role as both reagent and precursor for acetyl and benzoyl chloride synthesis. Chinese agrochemical and dye manufacturers in the Yangtze River basin have scaled captive production, limiting third-party availability for European and North American pharmaceutical buyers.
- Benzoyl Chloride:Critical building block for benzamide APIs and local anesthetics, this aromatic acid chloride commands premium pricing for pharmaceutical-grade specifications. REACH-registered supply is consolidating toward integrated German chlorination specialists with full toxicological dossiers.
- Acetyl Chloride:Simplest aliphatic acid chloride, produced via acetic acid chlorination for acetanilide herbicide intermediates. BASF leverages backward integration to secure feedstock for its downstream agrochemical portfolio.
- Chlorobenzoyl Chloride:Specialized dye chemistry applications in South Asia drive demand for these ring-substituted variants. Shiva Pharmachem Ltd. anchors regional supply for Indian dye intermediate producers seeking audit-ready supply chains.
Today's leader: Thionyl Chloride. Tomorrow's challenger: Chlorobenzoyl Chloride.
Application:
End-use value chains impose distinct purity, volume, and certification requirements that reshape supplier economics.
- Pharmaceuticals:Benzoyl chloride acylation chemistry for benzamide APIs and local anesthetics commands the largest value share. FDA-inspected and REACH-registered supply is consolidating toward dual-source minimums from audit-ready facilities in Germany and India.
- Agrochemicals:Acetyl chloride consumption for acetanilide herbicides shows the steepest expansion trajectory across South Asian and Chinese manufacturing clusters. EPA oversight of phosgene-based production elevates compliance costs for non-integrated formulators.
- Dyes:Chlorobenzoyl chloride variants serve specialized azo and anthraquinone intermediate synthesis. China's MEE wastewater discharge limits are forcing plant relocation decisions among thionyl chloride-dependent manufacturers.
- Polymers:Acid chloride monomers for polyamide and polyester modifications represent a smaller volume pool with specification-driven procurement.
Pharmaceuticals capture margin premiums. Agrochemicals drive volume expansion.
End User:
Customer scale and integration depth determine contract structures and technical service intensity.
- Pharmaceutical Companies:Generic API manufacturers in India are consolidating supplier panels to dual-source minimums from REACH-registered and FDA-inspected facilities. Long-term offtake agreements displace spot market procurement for benzoyl chloride and chlorobenzoyl variants.
- Chemical Manufacturers:Integrated chlorination specialists like CABB Group GmbH anchor European supply through captive thionyl chloride infrastructure at German manufacturing sites.
- Agricultural Firms:Acetanilide herbicide formulators scale acetyl chloride consumption through volume contracts with backward-integrated suppliers.
- Research Institutions:Small-batch procurement of high-purity acid chlorides for method development and scale-up studies.
Pharmaceutical companies set compliance standards. Chemical manufacturers control supply security.
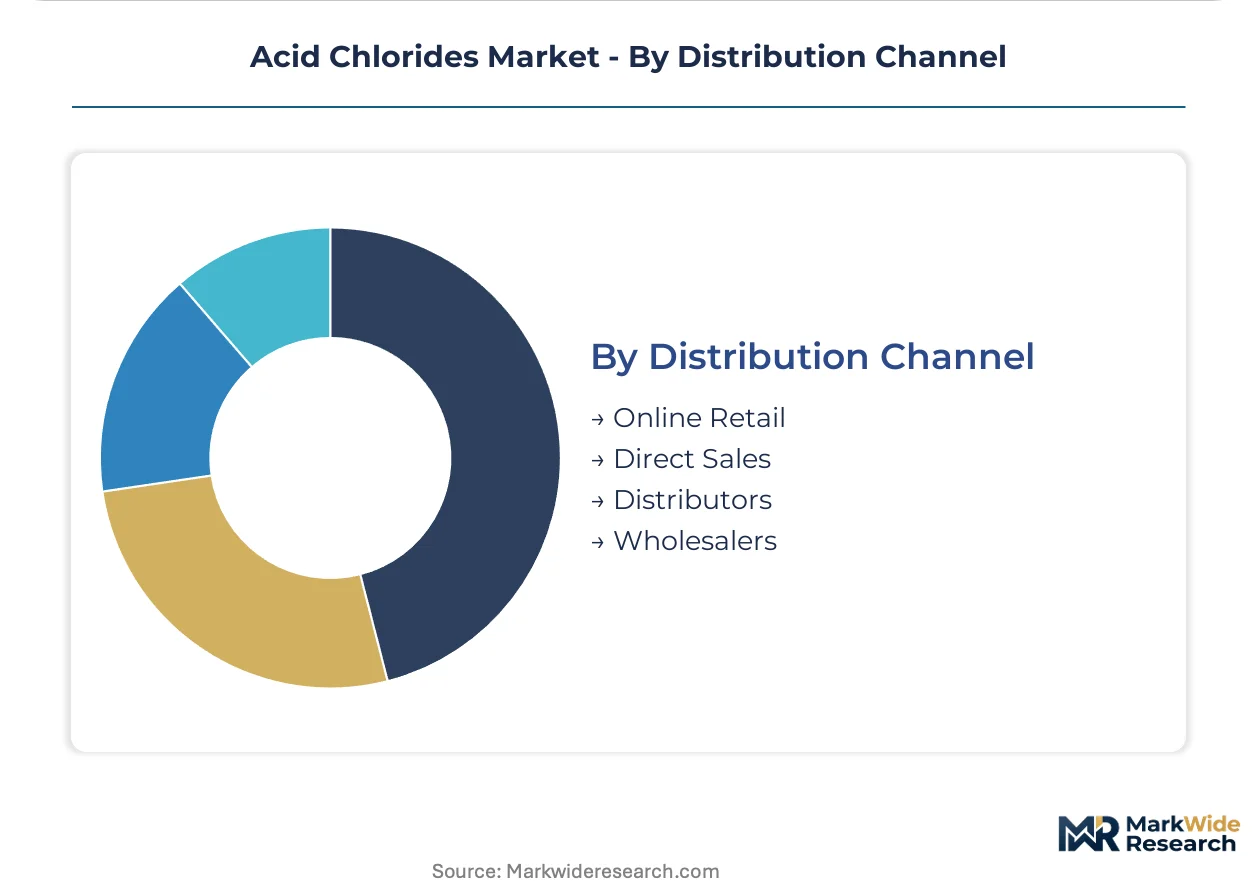
Distribution Channel:
Channel selection reflects order size, technical support needs, and regulatory documentation requirements.
- Direct Sales:Long-term offtake agreements dominate pharmaceutical and large agrochemical procurement, with integrated producers bypassing intermediaries for benzoyl chloride and thionyl chloride volumes.
- Distributors:Regional chemical distributors handle smaller volume acid chloride shipments with REACH documentation and safety data sheet compliance for mid-tier chemical manufacturers.
- Wholesalers:Bulk thionyl chloride and acetyl chloride for non-integrated agrochemical and dye producers in China and India.
- Online Retail:Emerging digital marketplaces for spot procurement of standardized grades, though safety constraints limit adoption for reactive chlorinated intermediates.
Direct sales lock in strategic supply. Digital channels test spot market liquidity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping acid chloride manufacturing footprints as producers migrate toward jurisdictions with manageable compliance burdens while maintaining market access. Cost-of-compliance gaps between EPA-regulated US operations and China's MEE-enforced Yangtze basin are accelerating plant relocation decisions.
China
Domestic agrochemical and dye manufacturers drive captive thionyl chloride production across Jiangsu and Zhejiang provinces. MEE wastewater discharge limits in the Yangtze River basin are forcing capacity consolidation toward compliant coastal zones. Nantong and Taizhou chemical parks absorb relocated chlorination assets from inland prefectures.
Germany
Integrated chlorination specialists anchor European benzoyl chloride supply through REACH-registered manufacturing complexes. ECHA authorization procedures for chlorinated acyl derivatives extend registration timelines, consolidating supplier bases toward dossier-compliant producers. Ludwigshafen and Frankfurt-Höchst chemical corridors maintain phosgene-handling competencies.
United States
Pharmaceutical API manufacturers source benzoyl chloride under EPA emissions oversight for phosgene-based production routes. FDA inspection requirements drive dual-source procurement from audit-ready domestic and imported supply. Gulf Coast chemical infrastructure supports acetyl chloride feedstock for regional agrochemical formulators.
India
Generic API producers in Gujarat and Maharashtra consolidate chlorobenzoyl chloride supplier panels toward REACH-registered and FDA-inspected facilities. CDSCO manufacturing license requirements align with export-oriented quality standards. Ankleshwar and Vapi industrial estates specialize in dye intermediate chemistry.
Japan
Specialty chemical manufacturers maintain high-purity acid chloride production for domestic pharmaceutical and electronics applications. METI chemical substance management frameworks govern chlorinated intermediate handling protocols. Osaka-Kobe industrial zone preserves acylation chemistry expertise for fine chemical synthesis.
Acid Chlorides Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue green chlorination chemistry and digital procurement platforms. The supplier base concentrates around integrated chlorination specialists with captive thionyl chloride infrastructure and regional distributors handling REACH-compliant documentation. Three archetypes dominate: backward-integrated agrochemical conglomerates, toll-manufacturing specialists for pharmaceutical grades, and regional dye-intermediate suppliers. Capacity expansion and strategic toll-manufacturing partnerships constitute the dominant competitive moves.
Among European integrated specialists, CABB Group GmbH anchors regional supply through German manufacturing infrastructure. BASF exemplifies backward-integrated agrochemical conglomerates with captive acetyl chloride production. Shiva Pharmachem Ltd. represents South Asian regional specialists serving dye intermediate value chains.
| Leading Market Players |
|---|
| VanDeMark |
| NOF |
| BASF |
| Transpek Industry Limited |
| Wilmar International |
| ALTIVIA |
| Nippon Fine Chemical |
| Shiva Pharmachem Ltd. |
| CABB Group GmbH |
| Others |
Value Chain & Pricing Dynamics
Phosgene-handling expertise concentration in Germany's Ludwigshafen corridor and Frankfurt-Höchst chemical belt feeds directly into pricing-tier spreads, with REACH-registered benzoyl chloride commanding substantial premiums over standard industrial grades due to occupational safety competency scarcity and toxicological dossier compliance costs.
Pricing Analysis
Distributor margins for thionyl chloride and benzoyl chloride intermediates compress as pharmaceutical buyers consolidate toward direct long-term offtake agreements with integrated producers. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and industrial-grade specifications reflects certification intensity and FDA inspection status. Pricing pressure stems from REACH registration cost absorption as ECHA authorization timelines extend. Generic API manufacturers in India exhibit highest price sensitivity, while patented drug developers in Japan and Switzerland show lowest elasticity due to quality assurance imperatives.
Supply Chain Analysis
Single-source vulnerability sits with Chinese thionyl chloride production concentrated in Jiangsu and Zhejiang provinces, where MEE wastewater enforcement is forcing capacity relocation. Raw material flows draw from chlorinated acetic acid feedstocks, sulfur-based chlorinating agents, and aromatic hydrocarbon precursors. Tariff exposure on phosgene-derived intermediates elevates risk for non-integrated European formulators. Distribution runs through integrated producer direct sales for pharmaceutical volumes, with regional distributors handling REACH-compliant documentation for mid-tier chemical manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acid chlorides market functions as a regulatory compounder, with ECHA REACH authorization milestones for chlorinated acyl derivatives consolidating supplier bases and amplifying demand for dossier-compliant production capacity.
For Market Incumbents: Acquire closed-loop thionyl chloride recovery systems and continuous flow microreactor assets to neutralize carbodiimide coupling reagent substitution threats in peptide synthesis. Expand captive chlorination infrastructure in coastal Chinese chemical parks to preempt MEE-driven supply disruptions. Prioritize REACH registration maintenance as ECHA persistent organic pollutant evaluations extend competitor exclusion timelines. For New Entrants and Emerging Players: Begin with chlorobenzoyl chloride variants for Indian dye intermediate producers, where backward integration demand from Ankleshwar and Vapi industrial estates creates penetrable white space. Target toll-manufacturing partnerships with EU-based pharmaceutical CDMOs seeking audit-ready supply chains for US and European filings. Establish digital procurement platforms for spot-market thionyl chloride liquidity as pharmaceutical buyers diversify sourcing. For Investors and Strategic Acquirers: Valuations sit cheapest among non-integrated Chinese thionyl chloride producers facing MEE relocation mandates and REACH-registered European specialists with full toxicological dossiers. Long-term viability centers on regulatory moat sustainability across the analysis window. Monitor ECHA authorization timeline acceleration as the critical inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thionyl Chloride | BASF's captive acetyl chloride production secures agrochemical feedstock against Chinese supply concentration. |
| Green Chlorination Chemistry Transition | Catalytic thionyl chloride recycling aligns with EU Green Deal decarbonization mandates for chlorinated intermediates. |
| Long-term Supply Agreement | Pharmaceutical generic API manufacturers in India consolidate dual-source minimums from REACH-registered facilities. |
| Joint Venture for EU Toll Manufacturing | Specialty chemical importers establish EU-based partnerships to maintain market access amid ECHA registration delays. |
| Capacity Expansion in Coastal China | Nantong and Taizhou chemical parks absorb relocated chlorination assets from Yangtze River basin enforcement zones. |
Study Parameters
Multiple input streams — regulatory filing databases, customs trade records, and producer capacity disclosures — were reconciled with primary interviews involving chlorination plant managers, pharmaceutical procurement leads at generic API manufacturers, REACH regulatory consultants, and specialty chemical distribution channel partners. Secondary validation drew from ECHA substance dossiers, SEC 10-K filings for listed chemical producers, ACC and Cefic industry reports, and MEE environmental enforcement notices. Bottom-up volume modeling and top-down value reconciliation triangulated segment estimates.
Data-stream reconciliation across product chemistry, application end-use, grade tier, and regional production hub dimensions anchored the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate synthesis and cross-referencing with macroeconomic chemical demand indicators. Forecast inputs incorporated REACH registration timeline trajectories, MEE wastewater enforcement intensity, and pharmaceutical API pipeline acylation chemistry requirements.
Several conditions sit outside the modeled scope, including unannounced ECHA substance restriction decisions, abrupt MEE enforcement escalation beyond coastal relocation patterns, and breakthrough displacement of acid chloride routes by activated ester methods in commercial peptide synthesis. Forecasts reflect documented assumptions regarding regulatory continuity and technology substitution pace. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Global Textile Finishing Chemicals Market
Chemical Intermediates
Lauoryl Chloride Market
Chemical Intermediates
Duloxetine Intermediate and Atorvastatin Intermediates Market
Chemical Intermediates
Bromate Substitute Market
Chemical Intermediates
Triisobutyl Phosphate Market
Chemical Intermediates
Glycidyl Methacrylate Market
Chemical Intermediates
Hydroxyisobutyric Acid Market
Chemical Intermediates
Epoxy Silanes Market
Chemical Intermediates
1, 3, 5-Triazine Market
Chemical Intermediates
Penicillin Intermediate Market
Chemical Intermediates
Pharmaceutical Intermediates Market
Chemical Intermediates
3-Chloropropionyl Chloride Market
Chemical Intermediates
Nickel Acetate Market
Chemical Intermediates
Japan Formic Acid Market
Chemical Intermediates
Potential Hydrogen (Ph) Adjusters Market
Chemical Intermediates
Thioesters Market