
 Diketene Derivatives Market | 2026-2036
Diketene Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Diketene Derivatives Market Analysis
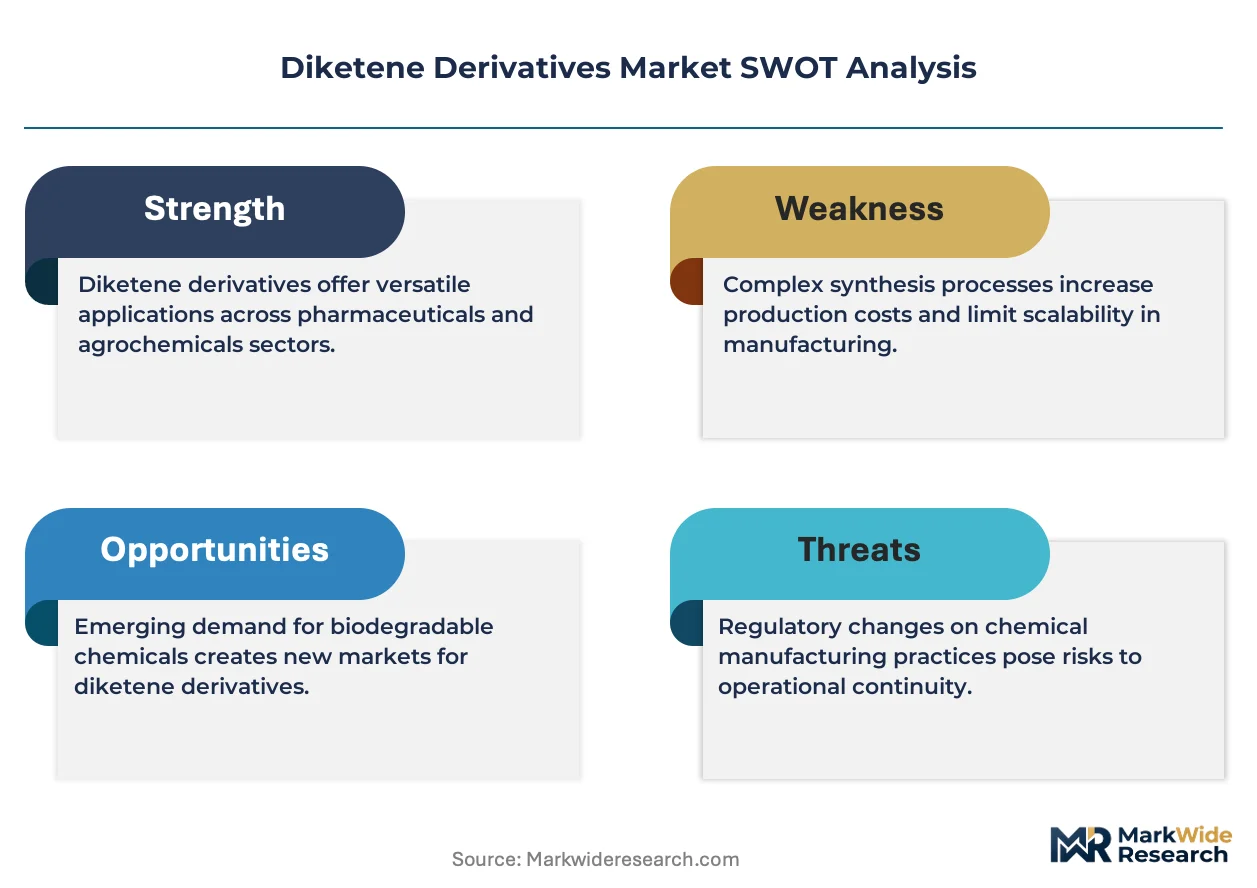
Specialized organic chemist availability is collapsing across Western manufacturing hubs, forcing pharmaceutical and agrochemical formulators to depend more heavily on Asian production networks. Laxmi Organic Industries Ltd. leverages backward integration into acetic anhydride to secure feedstock cost advantages. Mitsubishi Chemical Co., Ltd. anchors its position through proprietary diketene esterification technology. Eastman Chemical Company sustains North American supply security via long-term contracts with agricultural end-users.
Diketene derivatives comprise reactive organic intermediates synthesized from diketene dimerization, typically containing beta-keto ester or acetoacetyl functional groups that enable nucleophilic substitution for pharmaceutical and agrochemical active ingredient production. The compounds require controlled temperature storage below 20 degrees Celsius to prevent polymerization during transport. Pesticides applications dominate volume consumption due to pyrethroid and herbicide intermediate demand from Brazilian and Indian agriculture. Pharmaceutical-grade ethyl acetoacetate commands premium pricing as manufacturers navigate FDA and EMA impurity profiling requirements. Direct sales channels control bulk transactions while distributors serve fragmented textile dye houses in South Asia.
EPA toxicity evaluations and REACH substance registration obligations are elevating analytical documentation burdens for cross-border shipments. China's MEE enforces stricter volatile organic compound emission limits at diketene production facilities, affecting regional supply availability. Stakeholders must monitor regulatory divergence between OECD-aligned hazard assessment protocols and emerging economy enforcement practices to anticipate supply chain reconfiguration needs.
Market Dynamics
Feedstock cost volatility and regulatory fragmentation are restructuring diketene derivative supply economics, forcing formulators to reassess procurement geography and inventory depth against polymerization risk during extended logistics cycles.
Growth Catalysts
- Agrochemical intermediate demand:Pyrethroid and herbicide synthesis in Brazilian and Indian agriculture consumes volume-grade diketene derivatives at accelerating rates, with formulators expanding dedicated production lines for crop protection actives.
- REACH substance registration:EU Green Deal compliance timelines are compressing purity specifications for pharmaceutical-grade imports, creating premium positioning for manufacturers with validated impurity profiling capabilities.
- Acetic acid feedstock integration:China's integrated petrochemical corridors enable cost-advantaged diketene production through captive acetic anhydride supply, concentrating exportable capacity in Shandong and Jiangsu provinces.
Market Restraints
- Acetic anhydride price volatility:Feedstock cost swings directly compress diketene derivative margins, with spot market exposure punishing non-integrated producers during energy price spikes.
- Specialized chemist scarcity:Western manufacturing hubs face collapsing availability of organic synthesis expertise capable of handling reactive beta-keto ester chemistry, forcing dependency on Asian technical talent pools.
- Controlled temperature logistics:Sub-20°C storage requirements for polymerization prevention elevate cold-chain costs and constrain distribution radius for smaller volume shipments.
Strategic Opportunities
- Pharmaceutical-grade ethyl acetoacetate:FDA and EMA impurity profiling requirements create pricing premiums for validated manufacturers, with CDMOs in Switzerland and Singapore building dedicated diketene derivative suites.
- Textile dye house fragmentation:South Asian fabric processors present distributor-led channel opportunities for acetoacetyl-based coupling agents, bypassing bulk direct sales structures.
- Dual carbon policy alignment:China's MEE emission limits and EU carbon border adjustments are accelerating process efficiency investments, rewarding low-VOC production configurations with regulatory preference.
Industry Challenges
- Nucleophilic substitution expertise gaps:Pharmaceutical API synthesis requires precise beta-keto ester functionalization knowledge that contract manufacturers struggle to staff, extending qualification timelines.
- Cross-border documentation burdens:EPA toxicity evaluations and REACH substance registration obligations multiply analytical testing requirements, delaying shipment clearances at customs interfaces.
- Legacy batch reactor integration:Continuous flow diketene chemistry adoption confronts capital-intense retrofit requirements at established Western facilities with depreciated asset bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diketene Derivatives Market |
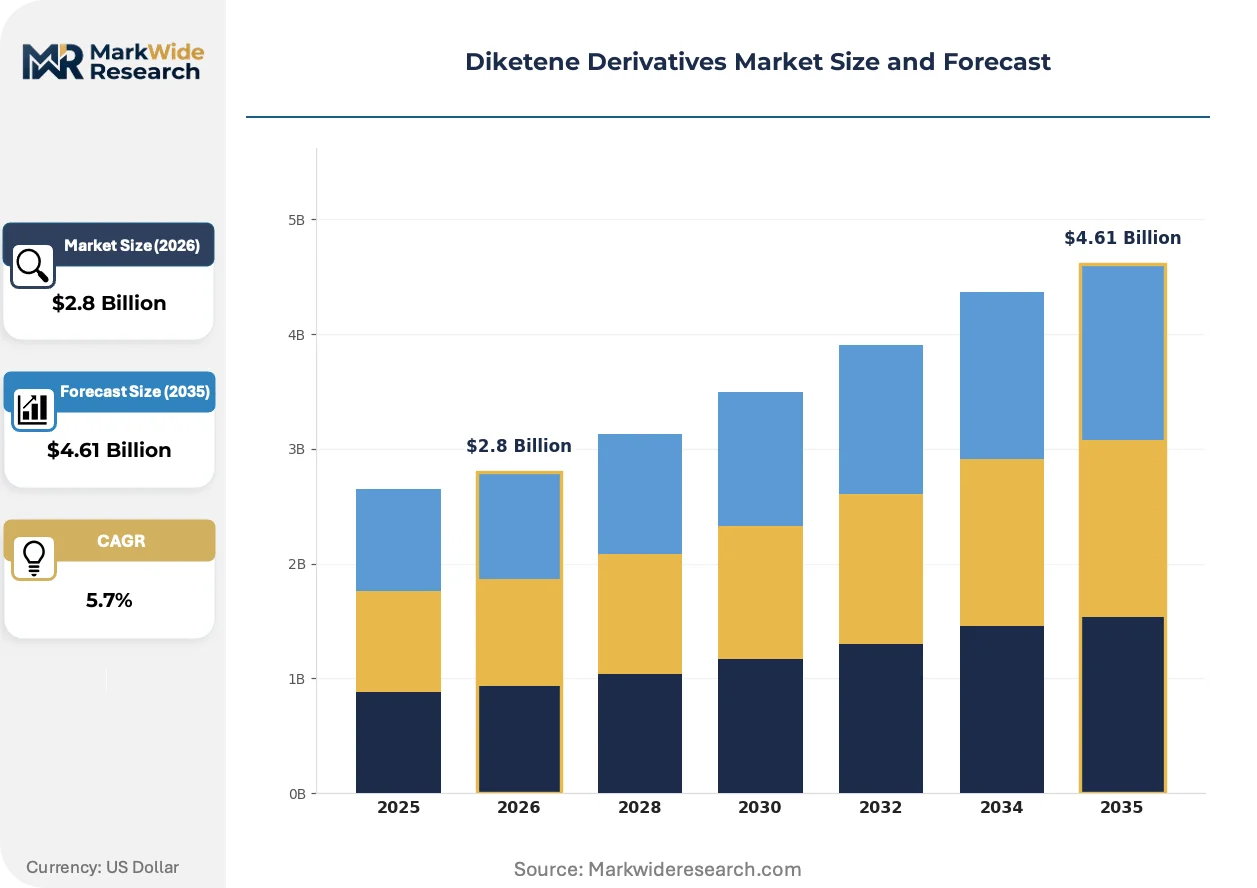
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diketene, Acetic Anhydride, Acetic Acid, Ethyl Acetoacetate Application: Pesticides, Pharmaceuticals, Dyes, Coatings End User: Agriculture, Chemical Manufacturing, Textile, Healthcare Distribution Channel: Direct Sales, Wholesalers, Online Retailers, Distributors |
| Companies Covered | Laxmi Organic Industries Ltd., Zhang Jiagang Hope Chemicals, Lonza, Mitsubishi Chemical Co., Ltd., Jubilant Life Sciences, Eastman Chemical Company, Nantong Acetic Acid Chemical Co., Ltd., Jiangsu Tiancheng Biochemical Product, Daicel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diketene Derivatives Market Emerging Trajectories
Process intensification and regulatory disclosure requirements are compressing traditional batch manufacturing economics while opening pathways for differentiated purity positioning in pharmaceutical applications.
Continuous flow microreactor technology for diketene dimerization is decomposing the cost structure of conventional batch production. Pharmaceutical CDMOs in Switzerland and Singapore are piloting these systems for GMP-grade ethyl acetoacetate output. The technology is decomposing volume-scale advantages previously held by large-batch commodity producers, enabling mid-scale facilities to achieve comparable unit economics with superior impurity control.
ECHA's tightening REACH substance registration requirements and the EU Green Deal's chemical sustainability criteria are elevating analytical documentation burdens for cross-border shipments. Industrial consequence includes mandatory third-party purity certification for pharmaceutical-grade derivatives entering European customs zones. Agrochemical formulators with Brazilian export exposure are accelerating pre-registration dossier preparation to avoid Q4 supply interruptions.
Buyer consolidation among agricultural end-users is compressing supplier negotiation cycles and unbundling technical service from material pricing. Long-term offtake agreements with volume commitments are displacing spot market transactions for pyrethroid intermediates. This pattern concentrates procurement leverage with Brazilian and Indian crop protection multinationals, pressuring smaller diketene derivative traders to specialize in textile or pharmaceutical niche grades.
Diketene Derivatives Market Segmentation
Diketene derivative procurement channels vary sharply by purity grade and shipment scale. Pharmaceutical-grade ethyl acetoacetate flows through validated direct sales agreements, while agrochemical intermediates concentrate in distributor-led bulk channels serving Brazilian and Indian formulators.
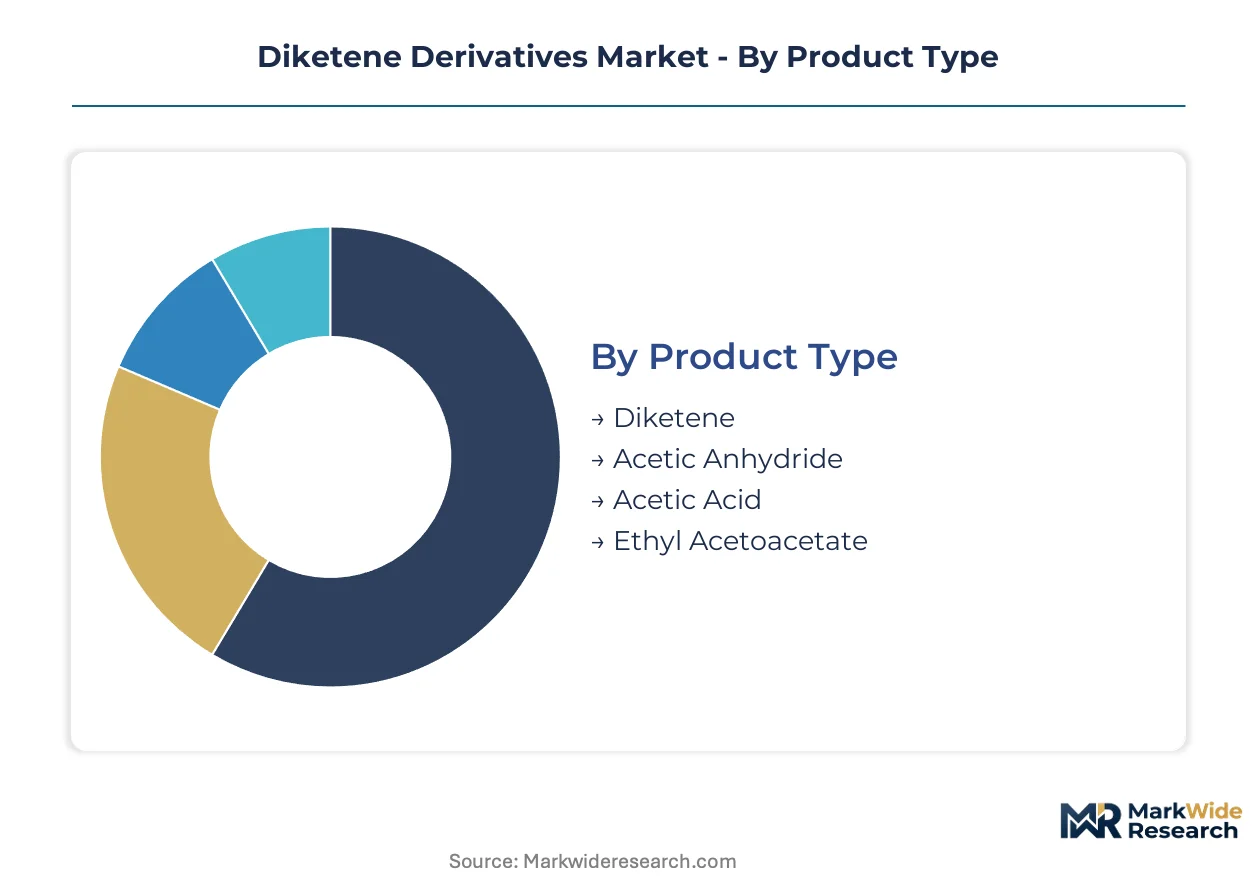
Product Type:
Channel mix splits between captive acetic anhydride supply for integrated producers and merchant market purchases for non-integrated derivative manufacturers.
- Diketene:Reactive dimer of ketene requiring immediate derivative conversion due to polymerization risk. Chinese Shandong and Jiangsu corridor producers dominate merchant supply through backward integration into acetic anhydride.
- Acetic Anhydride:Primary feedstock for diketene synthesis, with pricing volatility directly compressing derivative margins. Laxmi Organic Industries leverages captive production to secure cost advantages against spot-market exposed competitors.
- Acetic Acid:Upstream precursor routed through carbonylation units in integrated petrochemical complexes. Sinopec and Celanese supply chains anchor regional cost structures.
- Ethyl Acetoacetate:Beta-keto ester intermediate commanding pharmaceutical-grade premiums under FDA and EMA impurity profiling protocols. CDMOs in Switzerland and Singapore pilot continuous flow microreactors for GMP output.
By volume, acetic anhydride leads. By growth pace, ethyl acetoacetate is climbing the fastest.
Application:
Cost tier separation emerges between commodity agrochemical intermediates and validated pharmaceutical actives with documentation burdens.
- Pesticides:Pyrethroid and herbicide synthesis consumes volume-grade diketene derivatives at scale. Brazilian crop protection formulators expand dedicated production lines, consolidating procurement leverage through long-term offtake agreements.
- Pharmaceuticals:API synthesis demands precise beta-keto ester functionalization with nucleophilic substitution expertise. EMA and FDA impurity profiling requirements elevate analytical documentation burdens for cross-border shipments.
- Dyes:Acetoacetyl-based coupling agents for textile coloration. South Asian fabric processors present distributor channel opportunities bypassing bulk direct sales structures.
- Coatings:Reactive intermediates for specialty polymer crosslinking. Sub-20°C storage requirements constrain distribution radius for smaller volume shipments.
Pesticides anchor volume consumption. Pharmaceuticals capture the steepest margin expansion trajectory.
End User:
Customer type fragmentation drives divergent service models from technical partnership for healthcare to price-sensitive commodity supply for agriculture.
- Agriculture:Brazilian and Indian crop protection multinationals concentrate procurement leverage, compressing supplier negotiation cycles and unbundling technical service from material pricing.
- Chemical Manufacturing:Merchant diketene derivative producers serving downstream formulators face collapsing organic synthesis expertise availability in Western manufacturing hubs.
- Textile:South Asian dye house fragmentation sustains distributor-led channel economics for acetoacetyl coupling agents.
- Healthcare:Pharmaceutical CDMOs building dedicated diketene derivative suites in Switzerland and Singapore to serve FDA and EMA compliance requirements.
Agriculture dominates shipment tonnage. Healthcare exhibits the most rapid contract value escalation.
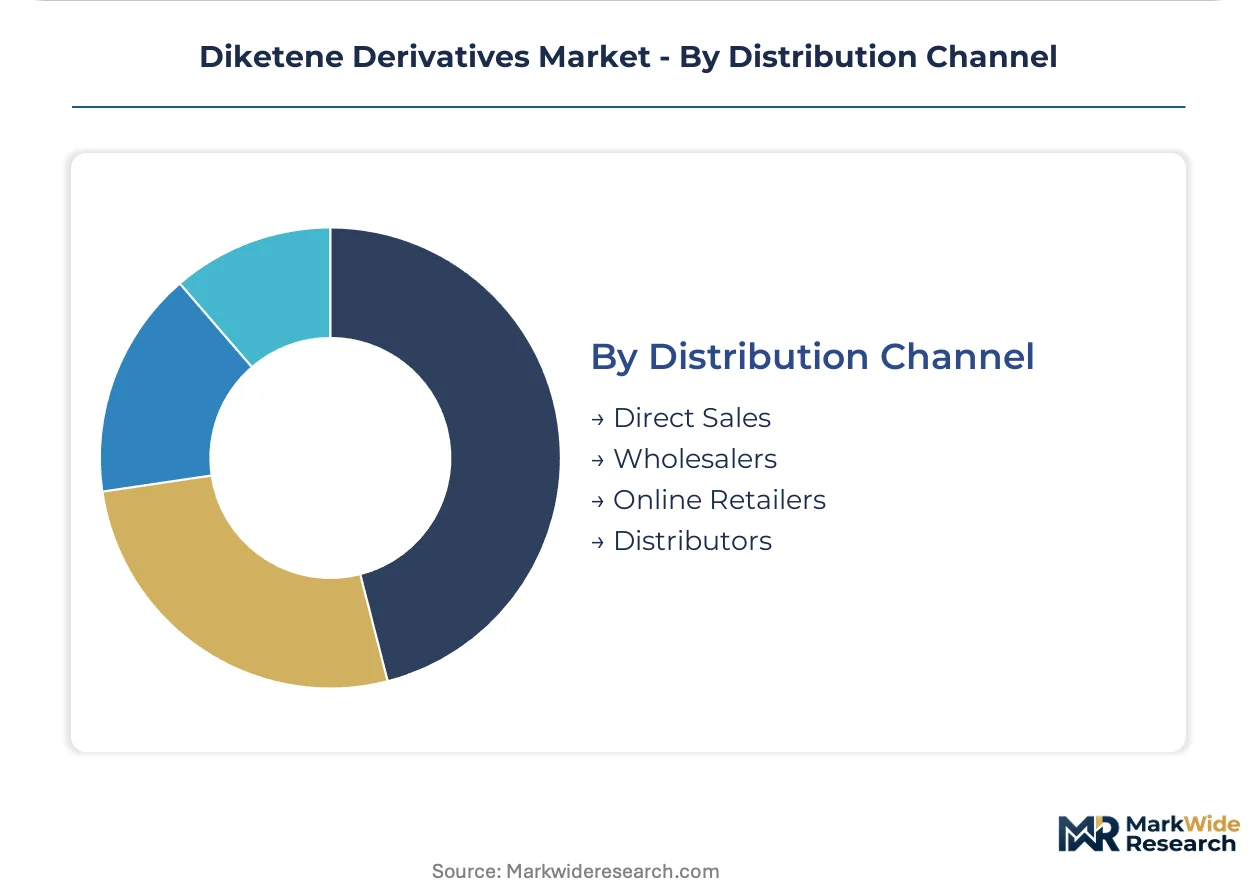
Distribution Channel:
Supply concentration geography dictates channel structure, with integrated producers favoring direct engagement and fragmented end-users requiring intermediary layers.
- Direct Sales:Controls bulk transactions for agrochemical intermediates and pharmaceutical-grade ethyl acetoacetate. Eastman Chemical sustains North American supply security through long-term contracts with agricultural end-users.
- Wholesalers:Aggregates smaller volume orders from textile dye houses and regional coating formulators. Inventory depth requirements elevate working capital intensity.
- Online Retailers:Laboratory-scale quantities for research institutions and pilot-scale pharmaceutical development. Limited penetration due to controlled substance documentation requirements.
- Distributors:Serves fragmented South Asian textile processors with acetoacetyl-based coupling agents, bridging specification translation between producers and small-scale fabric finishers.
Direct sales commands value share. Distributors are expanding most quickly in emerging economy textile corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE anchors diketene derivative production through integrated petrochemical corridors in Shandong and Jiangsu provinces. Regulatory divergence between OECD-aligned hazard protocols and emerging economy enforcement practices reshapes supply chain geography. Manufacturers must navigate volatile organic compound limits and carbon border adjustments simultaneously.
China
Shandong and Jiangsu provinces concentrate exportable diketene capacity through captive acetic anhydride supply chains. The MEE enforces stricter VOC emission limits at production facilities, affecting regional supply availability. Integrated producers leverage backward integration into acetic acid feedstock to secure cost advantages against merchant market competitors.
United States
EPA toxicity evaluations elevate analytical documentation burdens for cross-border shipments of pharmaceutical-grade derivatives. Agricultural end-users in the Midwest and Southeast sustain demand for pyrethroid intermediates through long-term offtake agreements. Eastman Chemical anchors North American supply security via contracted volume commitments with crop protection formulators.
Germany
REACH substance registration and EU Green Deal compliance timelines compress purity specifications for chemical imports entering Rotterdam and Hamburg ports. ECHA's tightening disclosure requirements mandate third-party certification for pharmaceutical-grade derivatives. Specialty chemical clusters in North Rhine-Westphalia face collapsing organic synthesis expertise availability.
Brazil
ANVISA pre-registration dossier requirements accelerate compliance preparation for agrochemical formulators exporting crop protection actives. Pyrethroid and herbicide synthesis consumes volume-grade diketene derivatives from São Paulo and Minas Gerais production lines. Buyer consolidation among agricultural multinationals concentrates procurement leverage through compressed negotiation cycles.
Switzerland
Swissmedic and EMA impurity profiling requirements create premium positioning for validated pharmaceutical-grade ethyl acetoacetate manufacturers. CDMOs in Basel and Geneva pilot continuous flow microreactors for GMP-compliant output. The country's technical talent pool attracts mid-scale facilities seeking superior impurity control over volume-scale commodity production.
Diketene Derivatives Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the diketene derivative landscape. Integrated petrochemical conglomerates with captive acetic anhydride supply dominate volume economics, while specialized pharmaceutical CDMOs command premium positioning through validated impurity profiling. Three archetypes define competitive structure: backward-integrated feedstock controllers, continuous-flow technology specialists, and distributor-led regional aggregators. Capacity expansion in Chinese chemical corridors and technology licensing for microreactor systems represent the dominant competitive moves reshaping supply economics.
Among Indian chemical manufacturers, Laxmi Organic Industries Ltd. and Jubilant Life Sciences exemplify the backward-integrated archetype through in-house acetic anhydride production. Mitsubishi Chemical Co., Ltd. anchors the technology-specialist position, while Eastman Chemical Company represents North American supply security through long-term agricultural contracting. These three entities occupy distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Laxmi Organic Industries Ltd. |
| Zhang Jiagang Hope Chemicals |
| Lonza |
| Mitsubishi Chemical Co., Ltd. |
| Jubilant Life Sciences |
| Eastman Chemical Company |
| Nantong Acetic Acid Chemical Co., Ltd. |
| Jiangsu Tiancheng Biochemical Product |
| Daicel Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between agrochemical formulators and diketene derivative producers lock in both supply access and price visibility, insulating integrated producers from acetic anhydride spot volatility while compressing margin flexibility for merchant market participants exposed to Chinese MEE emission compliance costs.
Pricing Analysis
Chinese Shandong and Jiangsu corridor producers command price premiums over Indian and Western competitors due to captive acetic anhydride integration. Three-tier pricing structure across pharmaceutical-grade, agrochemical-grade, and industrial-grade levels separates FDA-validated ethyl acetoacetate from volume pyrethroid intermediates. Cost compression in agrochemical-grade derivatives is intensifying because Brazilian buyer consolidation concentrates procurement leverage. Agriculture represents the most price-sensitive segment; healthcare exhibits the least.
Supply Chain Analysis
China and India anchor global diketene derivative production through integrated petrochemical corridors and backward-integrated acetic anhydride facilities. Manufacturing draws from acetic acid, ketene gas, and specialized catalyst feedstocks. Single-source vulnerability concentrates in Chinese Shandong province where MEE emission enforcement affects regional supply availability. Distribution runs through direct sales for bulk agrochemical transactions and distributor networks for fragmented South Asian textile processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent diketene derivative producers face substitution pressure from bio-based beta-keto ester alternatives and continuous flow microreactor technology that decomposes traditional batch economics.
For Market Incumbents: Fortify captive acetic anhydride supply through backward integration into carbonylation units, securing feedstock cost advantages against spot-market exposed competitors. Deepen technical service bundling for pharmaceutical CDMOs to offset unbundling pressure from agricultural buyer consolidation. Monitor Swiss and Singaporean continuous flow pilot programs as technology substitution threats. For New Entrants and Emerging Players: Anchor in pharmaceutical-grade ethyl acetoacetate production where FDA and EMA impurity profiling requirements create validation barriers protecting premium positioning. Target Switzerland and Singapore CDMO corridors with GMP-compliant microreactor installations. Pursue distributor-led channel partnerships for South Asian textile dye house fragmentation. For Investors and Strategic Acquirers: Capital is best deployed toward backward-integrated mid-cap specialists with captive acetic anhydride supply and established REACH registration dossiers. Long-term viability over the projection horizon favors producers with validated impurity profiling capabilities and low-VOC process configurations. Watch for MEE enforcement intensity in Chinese chemical corridors as supply availability inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetic Anhydride | Captive feedstock supply insulates margin compression from energy price spikes affecting spot market competitors. |
| Continuous Flow Microreactor Adoption | GMP-compliant output enables Swiss and Singaporean CDMOs to achieve superior impurity control over batch producers. |
| REACH Registration Dossier Completion | Third-party purity certification unlocks Rotterdam and Hamburg port access for pharmaceutical-grade derivatives. |
| Long-term Supply Agreement with Agriculture | Volume commitments with Brazilian crop protection multinationals secure offtake against spot market displacement. |
| Distributor Channel Expansion in Textiles | Acetoacetyl coupling agent access for South Asian fabric processors bypasses bulk direct sales concentration. |
Methodological Framework
Desk research of customs trade databases, SEC chemical company filings, and ECHA REACH registration records preceded structured interviews with diketene plant managers, downstream agrochemical procurement leads, pharmaceutical CDMO technical directors, and South Asian textile chemical distributors. Primary fieldwork captured operating cost structures, emission compliance investments, and channel economics. Secondary validation drew from Sinopec capacity disclosures, Celanese segment reporting, and ACC industry statistics. Bottom-up capacity modeling and top-down demand triangulation cross-checked volume estimates.
Variance decomposition across product grade, end-use industry, and regional production hub dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro chemical demand indicators. Forecast inputs incorporated acetic anhydride price elasticity, MEE enforcement trajectory, and pharmaceutical impurity profiling requirement adoption curves.
Decision-makers should treat outputs as directional under assumptions of sustained Chinese petrochemical corridor dominance and stable REACH compliance timelines; material deviation in feedstock cost volatility or regulatory enforcement intensity would warrant model refresh. Recalibration cycles align with material shifts in emission policy enforcement and continuous flow technology adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Thiochemicals Market
Chemical Intermediates
Myristoyl Chloride Market
Chemical Intermediates
Global Glycinates Market
Chemical Intermediates
Metal Alkyls Market
Chemical Intermediates
Copper Chemicals Market
Chemical Intermediates
Methacrylic Ester Market
Chemical Intermediates
Polyamide Intermediate Chemicals Market
Chemical Intermediates
Global Electrophoresis Reagents Market
Chemical Intermediates
Ethylene Diamine Tetra Acetic Acid (EDTA) Market
Chemical Intermediates
Dimethyl Dicarbonate Market
Chemical Intermediates
2-Acetylthiophene Market
Chemical Intermediates
Acid Chlorides Market
Chemical Intermediates
US Acids Market
Chemical Intermediates
Nutrition Chemicals Market
Chemical Intermediates
Chemical Synthesizer Market
Chemical Intermediates
Grignard Reagents Market