
 Remote Car Starter Market | 2026-2036
Remote Car Starter Market Size, Share, and Industry Trends Forecast 2026-2036
Remote Car Starter Market Analysis
The automotive aftermarket distribution network is reconfiguring around direct-to-consumer digital channels and mobile-installer partnerships. Denso Corporation leverages its OEM supply relationships to anchor premium professional-installation segments. Compustar specializes in DIY and plug-and-play configurations, competing aggressively through enthusiast-focused retail placement. HELLA GmbH & Co. KGaA extends its European electronics manufacturing scale into North American fleet channels, sustaining volume through dealer-program contracts.
A remote car starter is an electronic device that enables engine ignition from a distance via radio frequency or cellular transmission, typically operating on 315 MHz or 433 MHz bands with encrypted rolling-code protocols to prevent signal interception. The unit interfaces with a vehicle's ignition, immobilizer, and climate-control systems to precondition cabin temperature and defrost surfaces before operator entry. Smartphone-controlled products command the fastest expansion as cellular connectivity and OEM telematics integration displace legacy one-way fob architectures. Professional installation still dominates value capture due to complex immobilizer bypass requirements and warranty preservation needs, though plug-and-play formats are eroding this margin pool in older vehicle parc segments.
NHTSA oversees keyless-system safety standards including carbon-monoxide exposure mitigation and rollaway-prevention protocols, while FCC regulates radio-frequency emissions across transmitter bands. State-level insurance frameworks in California and New York increasingly reference aftermarket electronics installation certification, shaping installer licensing and product liability exposure. Stakeholders must monitor evolving cybersecurity mandates from regulators and OEM telematics lockout policies that could restrict third-party device interoperability.
Market Dynamics
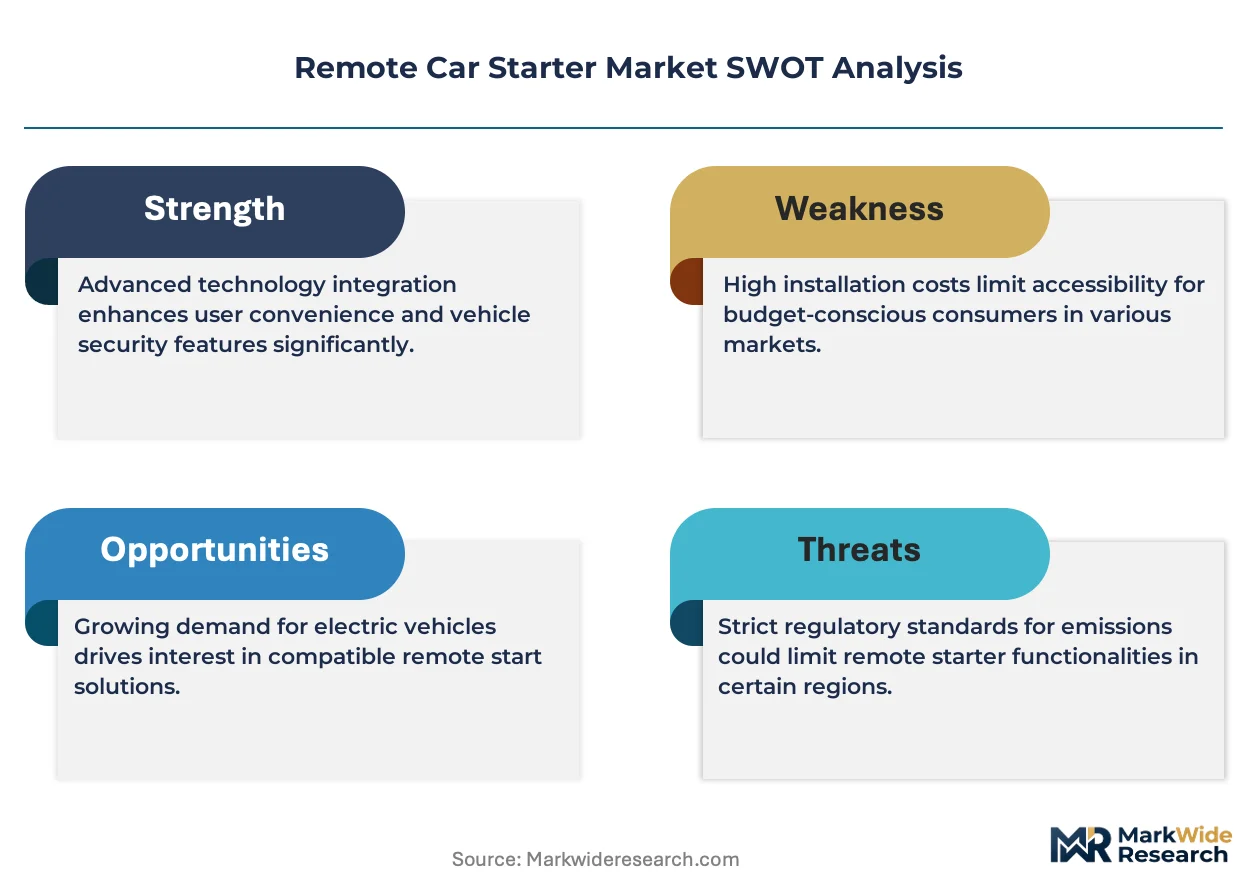
Cellular-enabled smartphone control is rendering legacy one-way radio-frequency fob architectures structurally marginal, compressing installer margins and forcing channel reconfiguration toward direct-to-consumer digital platforms.
Growth Catalysts
- Fleet Telematics Mandates:Commercial fleet operators in Texas and California corridors are mandating centralized vehicle preconditioning to reduce idle fuel burn and driver wait times.
- NHTSA Keyless Safety Protocols:Carbon-monoxide exposure mitigation and rollaway-prevention standards are accelerating replacement cycles for non-compliant legacy installations.
- Encrypted Rolling-Code Technology:Signal-interception countermeasures operating on 433 MHz bands are expanding addressable vehicle parc into premium segments previously blocked by immobilizer complexity.
Market Restraints
- Immobilizer Bypass Component Costs:Specialized cryptographic modules required for modern vehicle integration carry input cost volatility tied to semiconductor foundry allocation.
- OEM Telematics Lockout Policies:Manufacturer software restrictions on third-party device interoperability are structurally limiting aftermarket penetration in vehicles produced after 2020.
- Professional Installation Dependency:Complex wiring integration and warranty preservation requirements maintain cost structures that plug-and-play alternatives cannot fully replicate.
Strategic Opportunities
- Underpenetrated Cold-Climate States:Minnesota, North Dakota, and Alaska present white space where smartphone-controlled preconditioning remains below national penetration rates.
- Insurance Certification Incentives:California and New York state-level frameworks referencing aftermarket electronics installation certification are creating preference premiums for certified products.
- Climate-Control Integration Convergence:Pairing remote start with battery-electric vehicle cabin preconditioning and seat-heating systems opens addressable applications beyond internal-combustion engines.
Industry Challenges
- Automotive Electronics Technician Shortage:Installer licensing requirements and immobilizer-specific training gaps are constraining service capacity expansion in high-demand corridors.
- Cybersecurity Certification Timelines:FCC radio-frequency emission testing combined with evolving NHTSA cybersecurity mandates are extending product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Remote Car Starter Market |
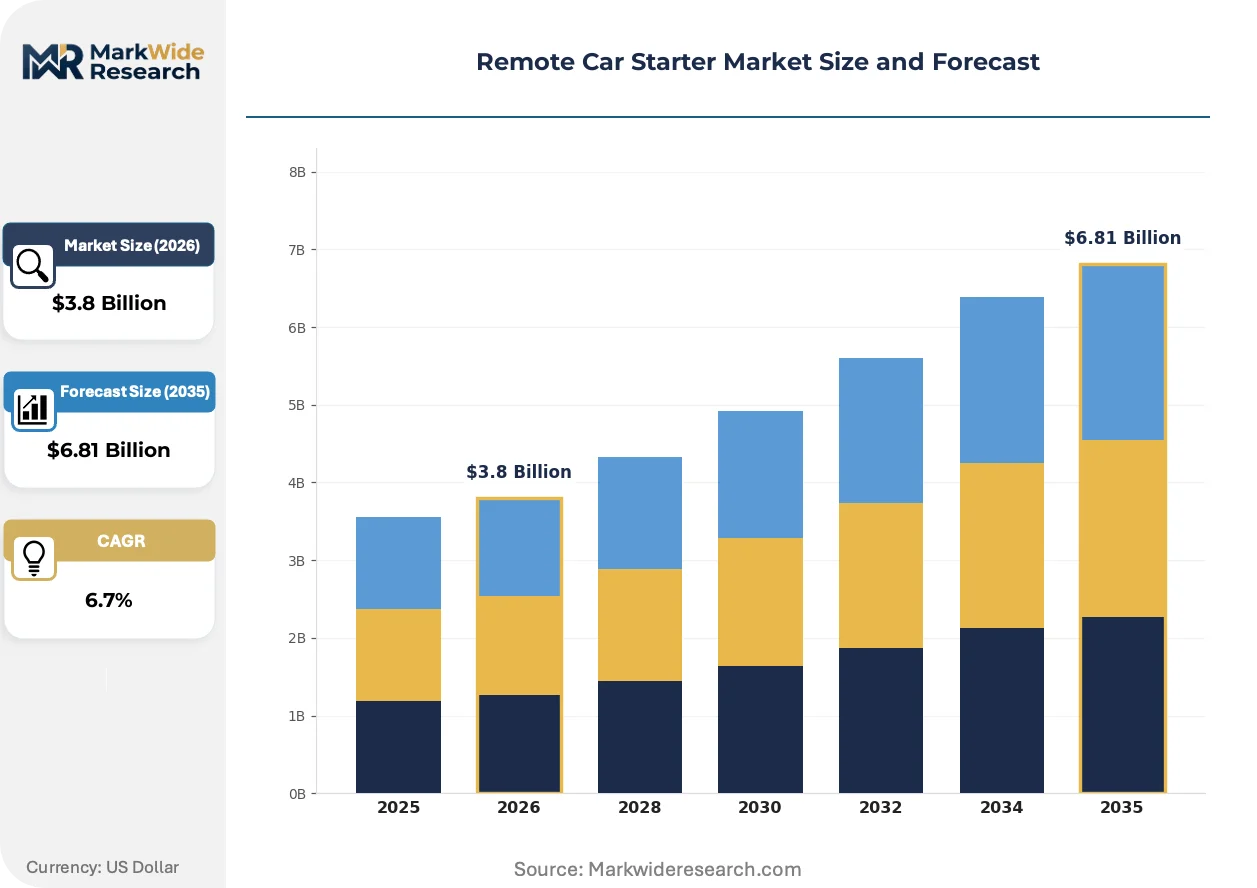
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Keyless Entry, Smartphone-Controlled, Remote Start with Alarm, Two-Way Remote Installation Type: DIY, Professional, Dealer Installed, Plug-and-Play End User: Automotive Enthusiasts, Fleet Operators, Personal Vehicles, Rental Services Connectivity: Bluetooth, Cellular, Wi-Fi, RFID |
| Companies Covered | Mitsubishi Corporation, HELLA GmbH & Co. KGaA, Denso Corporation, DIRECTED, Compustar, ZF Friedrichshafen AG, Faurecia SE, Firstech LLC, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Remote Car Starter Market Emerging Trajectories
Software-defined vehicle architectures and cellular connectivity protocols are dissolving the boundary between factory-installed and aftermarket remote start functionality, forcing stakeholders to reposition around data services rather than hardware margins.
Biometric vehicle access integration—combining fingerprint authentication with smartphone proximity detection—is rendering obsolete standalone key fob form factors across premium vehicle segments. Fleet operators and luxury consumer buyers are adopting these systems at accelerated replacement cycles. The shift is compressing aftermarket hardware margins while expanding recurring-software revenue pools for telematics platform providers.
NHTSA cybersecurity guidelines for keyless entry systems are mandating encrypted communication protocols and over-the-air update capabilities for all new aftermarket installations. The regulation is forcing firmware architecture redesigns and supplier qualification changes. Professional installation channels are absorbing compliance costs through extended service contracts and certification premiums.
Subscription-based remote start services bundled with vehicle security monitoring are displacing one-time hardware purchases in consumer segments. Mobile-installer partnerships and direct-to-consumer digital channels are capturing this shift faster than traditional retail storefronts. The pattern concentrates in coastal metropolitan areas where smartphone dependency and parking security concerns overlap.
Remote Car Starter Market Segmentation
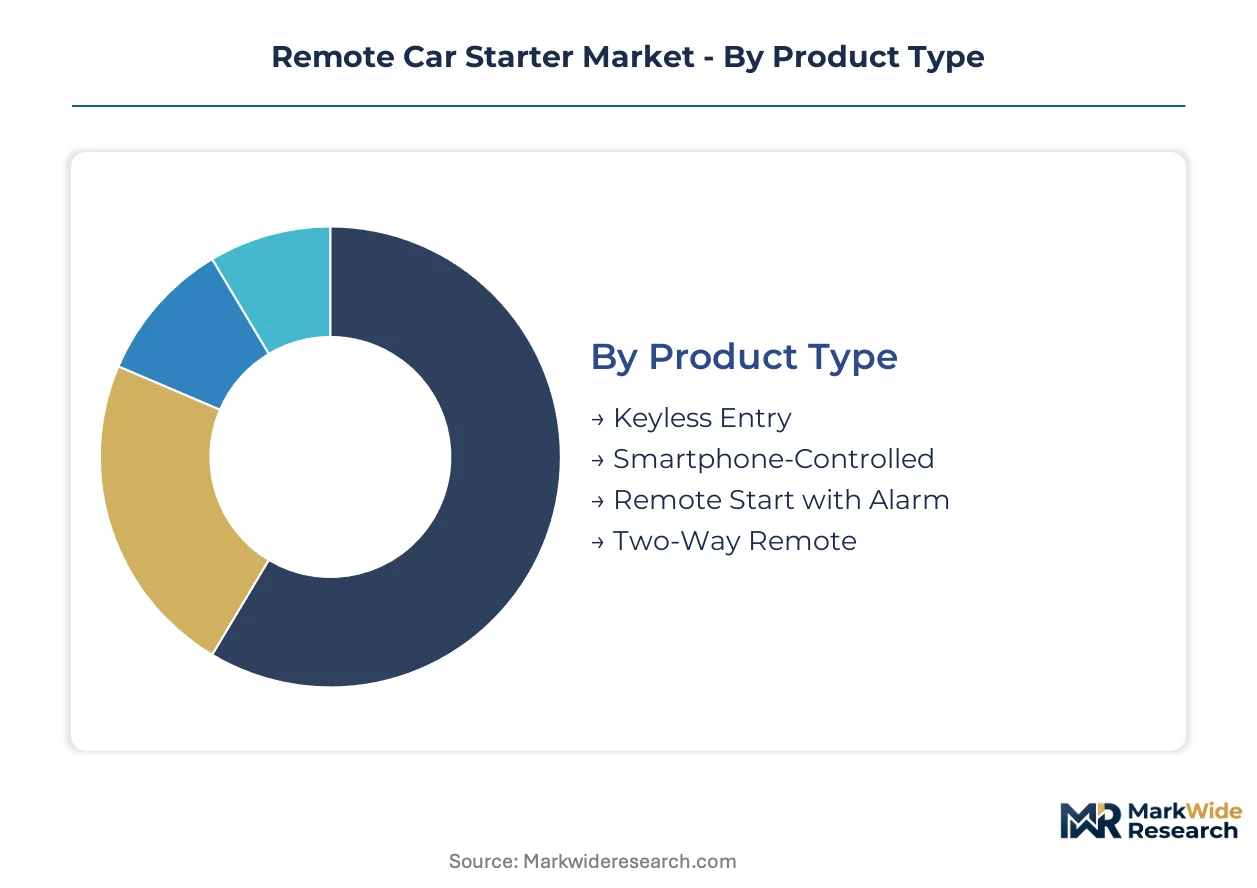
Remote car starter segmentation reveals divergent technology investment cycles across consumer convenience, fleet efficiency, and security applications. Product architecture choices determine whether vendors capture hardware margins or recurring service revenue.
Product Type:
The use-case spectrum spans basic engine ignition to integrated vehicle security ecosystems with climate preconditioning.
- Smartphone-Controlled:Cellular-enabled units leverage encrypted data protocols to enable unlimited-range engine start, cabin temperature preset, and GPS location tracking through dedicated mobile applications. Fleet operators in Texas and California corridors are mandating these systems for centralized vehicle preconditioning to eliminate driver idle time and reduce fuel burn.
- Remote Start with Alarm:Combined engine ignition and intrusion-detection architectures integrate shock sensors, door triggers, and starter-kill relays into unified control modules. Personal vehicle owners in high-theft metropolitan areas prioritize these configurations for insurance premium reductions and parking security assurance.
- Keyless Entry:Proximity-based passive entry systems using low-frequency radio triggers for door unlock and push-button ignition activation.
- Two-Way Remote:Transceiver-equipped fobs providing visual or tactile confirmation of command execution and vehicle status feedback.
The dominant share belongs to Remote Start with Alarm, while Smartphone-Controlled is closing the gap fastest.
Installation Type:
Channel economics separate margin capture between certified technician networks and direct-to-consumer hardware sales.
- Professional:Licensed automotive electronics technicians execute complex immobilizer bypass programming, CAN-bus integration, and warranty-preserving installation protocols. Modern vehicle architectures with encrypted ignition systems require specialized cryptographic modules and factory-scan tool access, preserving this channel's value capture despite higher labor costs.
- Plug-and-Play:Pre-configured harnesses matching specific vehicle model-year connectors enable consumer self-installation without wire splicing. Older vehicle parc segments in cold-climate states support this format's expansion where immobilizer complexity remains minimal.
- DIY:Hardwired universal kits requiring customer execution of ignition harness identification and relay installation.
- Dealer Installed:Factory-authorized service departments offering OEM-branded or approved aftermarket units with new vehicle financing integration.
Professional installation commands the value pool, though Plug-and-Play is gaining share fastest among price-sensitive consumers with compatible vehicle vintages.
End User:
Customer archetypes drive divergent feature prioritization between operational efficiency and convenience optimization.
- Fleet Operators:Commercial vehicle managers deploy centralized telematics platforms enabling dispatch-controlled preconditioning, geofenced operation zones, and driver accountability logging. Texas and California fleet corridors are expanding adoption fastest as fuel cost pressures and driver retention challenges intensify.
- Automotive Enthusiasts:Hobbyist installers and modification communities prioritize feature customization, expandability, and community-supported programming capabilities.
- Personal Vehicles:Individual consumers seeking cabin comfort and security convenience for daily driver applications.
- Rental Services:Short-term vehicle providers implementing remote fleet management and customer self-service retrieval systems.
Fleet Operators concentrate the highest per-unit spending, while Automotive Enthusiasts are expanding fastest through digital community channels.
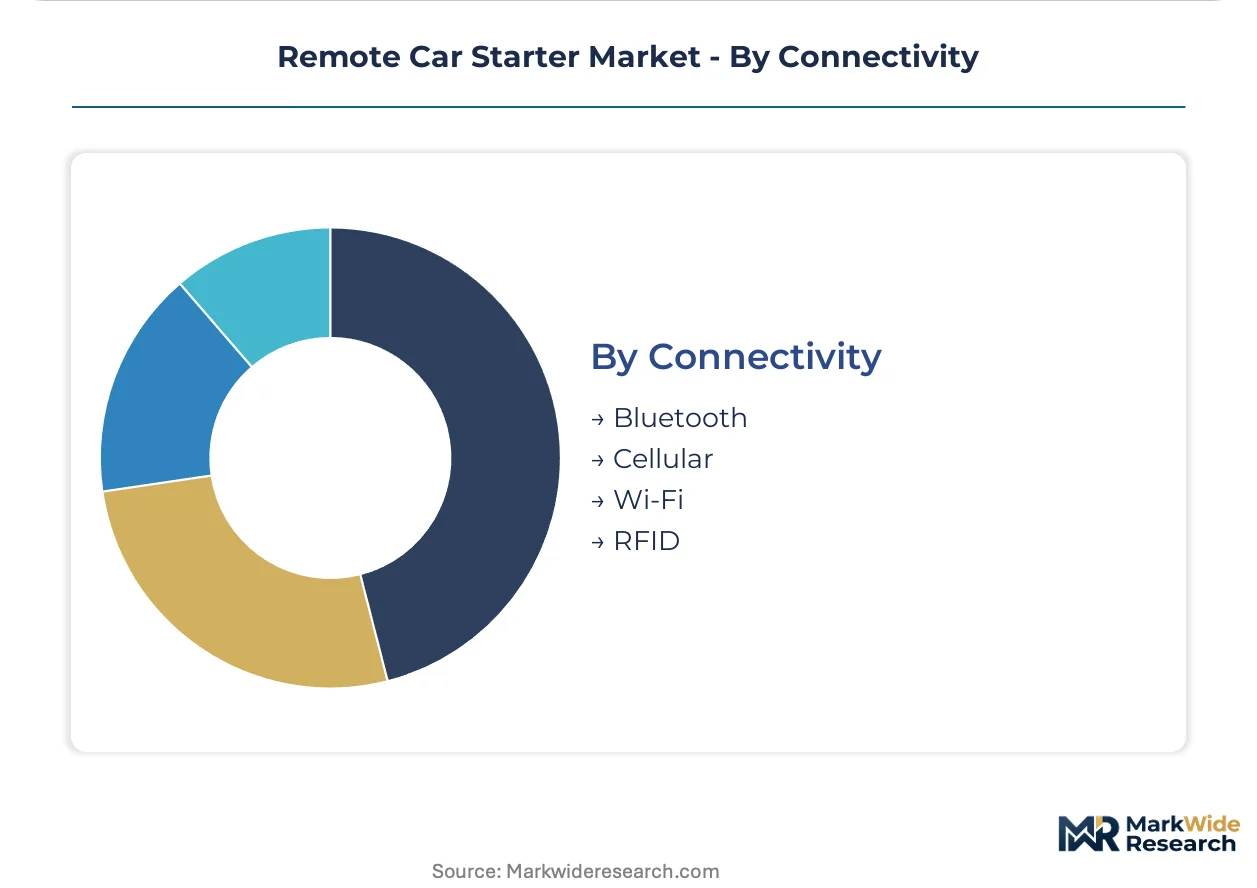
Connectivity:
Transmission protocol selection determines range, reliability, and service revenue potential across deployment environments.
- Cellular:LTE and 5G-enabled modules provide unlimited geographic range, over-the-air firmware updates, and subscription-based feature unlocking. NHTSA cybersecurity guidelines are mandating encrypted communication protocols for these installations, extending product launch cycles but creating certification barriers for non-compliant competitors.
- Bluetooth:Short-range personal area networking enables smartphone proximity detection without recurring carrier fees. Personal vehicle applications in urban parking environments favor this protocol for its zero-subscription cost structure.
- Wi-Fi:Home network-tethered operation enabling vehicle preconditioning scheduling through residential internet connectivity.
- RFID:Passive radio-frequency identification tags for proximity-based authorization without battery-dependent transmitters.
Cellular dominates forward investment, while Bluetooth retains volume leadership in cost-sensitive consumer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States commands premiums roughly double those in Mexico, reflecting divergent regulatory stringency and fleet-operator purchasing concentration. Canada occupies an intermediate position, balancing NHTSA-aligned safety mandates with smaller-scale fleet deployment. European markets fragment across national certification regimes, while Asian manufacturing centers supply componentry without capturing equivalent value downstream.
United States
Fleet operators in Texas and California corridors drive concentrated demand for smartphone-controlled preconditioning systems that reduce idle fuel burn. NHTSA cybersecurity guidelines for keyless entry systems mandate encrypted communication protocols and over-the-air update capabilities, extending product launch cycles. Installation capacity clusters around Dallas-Fort Worth and Los Angeles metropolitan areas where certified technician networks service high-volume commercial accounts.
Canada
Cold-climate consumer demand in Alberta and Manitoba sustains plug-and-play format penetration where immobilizer complexity remains minimal. Transport Canada aligns with NHTSA safety protocols while maintaining distinct radio-frequency emission testing through Innovation, Science and Economic Development Canada. Toronto and Calgary anchor professional installation networks serving both retail consumers and cross-border fleet operators.
Mexico
Manufacturing operations in Baja California and Chihuahua supply transceiver modules and cryptographic components to North American assembly plants. PROFECO consumer protection standards govern aftermarket electronics warranty disclosures without matching US cybersecurity certification depth. Guadalajara and Monterrey emerging as technical service hubs for regional installer training and warranty administration.
Germany
OEM supply relationships from Baden-Württemberg electronics manufacturers anchor premium professional-installation segments across European markets. KBA type-approval requirements for vehicle immobilizer interfaces create certification barriers that favor established supplier relationships. Stuttgart and Munich industrial corridors concentrate engineering talent for CAN-bus integration and encrypted protocol development.
China
MIIT radio-frequency allocation standards for 315 MHz and 433 MHz bands enable component manufacturing scale without equivalent downstream brand capture. Shenzhen and Dongguan electronics clusters produce rolling-code transceivers and cellular connectivity modules for global aftermarket brands. Domestic demand concentrates in Beijing and Shanghai metropolitan areas where smartphone-controlled vehicle preconditioning gains traction among luxury vehicle owners.
Remote Car Starter Market Vendor Landscape
OEM-anchored suppliers and enthusiast-focused specialists split the market into divergent margin structures. Consolidation around telematics platforms and cellular connectivity protocols favors players with software development capabilities and carrier partnership networks. Three archetypes dominate: automotive electronics conglomerates leveraging factory relationships, DIY-oriented brands competing through retail placement, and fleet-telematics pure-plays capturing recurring service revenue. Competitive moves concentrate on strategic partnerships with cellular carriers and backward integration into cryptographic module sourcing.
Among automotive electronics conglomerates, Denso Corporation and HELLA GmbH & Co. KGaA exemplify the OEM-supply archetype, occupying positions sustained by dealer-program contracts and professional-installation channel control. Compustar represents the enthusiast-facing tier, sitting within DIY and plug-and-play market segments where community-supported programming capabilities differentiate positioning. These three anchors illustrate how divergent channel strategies—factory-authorized service departments versus direct-to-consumer digital platforms—partition value capture across the aftermarket ecosystem.
| Leading Market Players |
|---|
| Mitsubishi Corporation |
| HELLA GmbH & Co. KGaA |
| Denso Corporation |
| DIRECTED |
| Compustar |
| ZF Friedrichshafen AG |
| Faurecia SE |
| Firstech LLC |
| Honeywell International Inc. |
| Others |
Supply Flow & Price Mechanics
Los Angeles-Long Beach port congestion cycles amplify cost volatility for cryptographic module imports from Shenzhen, compressing margins for installer networks while widening the spread between certified professional installations and consumer self-install kits across Texas and California fleet corridors.
Pricing Analysis
The configured-to-order premium spans roughly 40-60% above standard SKUs, reflecting immobilizer bypass programming complexity and NHTSA cybersecurity certification tier. Pricing stratifies across premium, standard, and economy tiers based on cellular connectivity grade and encrypted protocol sophistication. Cost compression in the DIY segment is intensifying because semiconductor foundry allocation volatility for rolling-code transceivers feeds through to component pricing. Fleet operators exhibit lowest price sensitivity due to fuel burn reduction ROI, while personal vehicle owners in warm-climate states show highest elasticity.
Supply Chain Analysis
Export-control restrictions on cryptographic processors limit flows from Taiwan and South Korea into North American assembly plants, forcing suppliers to qualify secondary foundry sources. Manufacturing draws from China for transceiver modules, Mexico for harness assembly, and Germany for CAN-bus controllers. Single-source vulnerability concentrates in 433 MHz band RF components where two vendors dominate qualified supplier lists. Distribution runs through mobile-installer partnerships and direct-to-consumer digital channels rather than traditional retail storefronts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The remote car starter market is recovering from cyclical compression in aftermarket hardware margins, with replacement demand accelerating as NHTSA cybersecurity mandates force non-compliant legacy system upgrades.
For Market Incumbents: Insulate certified installation networks from plug-and-play erosion by embedding subscription telematics services into professional service contracts. Deepen backward integration into cryptographic module sourcing to buffer semiconductor foundry allocation volatility. OEM telematics lockout policies represent the primary threat requiring defensive patent positioning around immobilizer bypass protocols.
For New Entrants and Emerging Players: Establish a beachhead in Minnesota, North Dakota, and Alaska where smartphone-controlled preconditioning penetration lags national benchmarks. Cold-climate consumer segments with older vehicle parc offer lowest competitive intensity. A mobile-installer partnership model with zero upfront retail footprint minimizes capital requirements while capturing fleet operator accounts through geofenced operation zone capabilities.
For Investors and Strategic Acquirers: Carve-out targets emerge from automotive electronics conglomerates divesting non-core aftermarket divisions to focus on OEM telematics integration. Long-term viability hinges on software-defined vehicle architecture compatibility and recurring service revenue conversion. The signal to watch is NHTSA rulemaking timeline acceleration on third-party device interoperability standards.
| Strategic Initiative | Industry Significance |
|---|---|
| Cellular Carrier Partnership | Secures subscription revenue streams through LTE/5G module bundling with Verizon or T-Mobile fleet programs. |
| Cryptographic Module Backward Integration | Captures margin pool currently absorbed by Taiwan and South Korean foundry suppliers. |
| Mobile-Installer Network Expansion | Aligns channel economics with direct-to-consumer digital acquisition in coastal metropolitan markets. |
| NHTSA Cybersecurity Certification Investment | Creates regulatory moat against non-compliant competitors in professional installation segments. |
| Climate-Control Integration Development | Opens battery-electric vehicle cabin preconditioning applications beyond internal-combustion engines. |
Methodological Framework
A spread of perspectives from automotive electronics technicians, fleet operations managers, aftermarket distributors, and cellular carrier IoT specialists converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with installer licensing bodies and telematics platform engineers alongside secondary validation through FCC equipment authorization databases, NHTSA safety recall filings, vehicle production registration data, and SEC 10-K disclosures from listed automotive suppliers. Bottom-up unit economics triangulated against top-down market sizing across connectivity protocol and installation type segments.
Demand-supply balance modeling anchored volume projections across the analysis window, with segmentation dimensions spanning product architecture, installation channel, end-user archetype, and connectivity protocol. CAGRs derived from fitted growth curves adjusted for replacement cycle acceleration under NHTSA compliance mandates and fleet telematics adoption curves in Texas and California corridors. Industry-specific inputs included immobilizer bypass complexity indices by vehicle model year and cellular module cost trajectories from carrier partnership negotiations.
Stress conditions across semiconductor foundry allocation, OEM telematics lockout enforcement, and installer technician shortage severity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding NHTSA rulemaking timelines and fleet operator procurement centralization. Material shifts in encrypted protocol standardization or cybersecurity certification scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Digital Tachograph System Market
Automotive Electronics & Wiring
Automotive Over-The-Air (OTA) Updates Market
Automotive Electronics & Wiring
Global Automotive Audio Speakers Market
Automotive Electronics & Wiring
Global Automotive Junction Box Market
Automotive Electronics & Wiring
Automotive Wireless Charger Market
Automotive Electronics & Wiring
Global Automotive Active Window Display Market
Automotive Electronics & Wiring
Automotive Data Cables Market
Automotive Electronics & Wiring
Automotive Console Box Market
Automotive Electronics & Wiring
Russia Automotive Camera Market
Automotive Electronics & Wiring
Electric Vehicle High Voltage Wire Harness Market
Automotive Electronics & Wiring
Automotive HV Junction Box Busbar Insulator Market
Automotive Electronics & Wiring
Automotive Control Cable Market
Automotive Electronics & Wiring
Steering Roll Connector Market
Automotive Electronics & Wiring
Automotive Glow Plug Market
Automotive Electronics & Wiring
Boat Wiring Harness Market
Automotive Electronics & Wiring
Bluetooth in Automotive Market