
 Canine Weight Loss Drugs Market | 2026-2036
Canine Weight Loss Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Canine Weight Loss Drugs Market Outlook
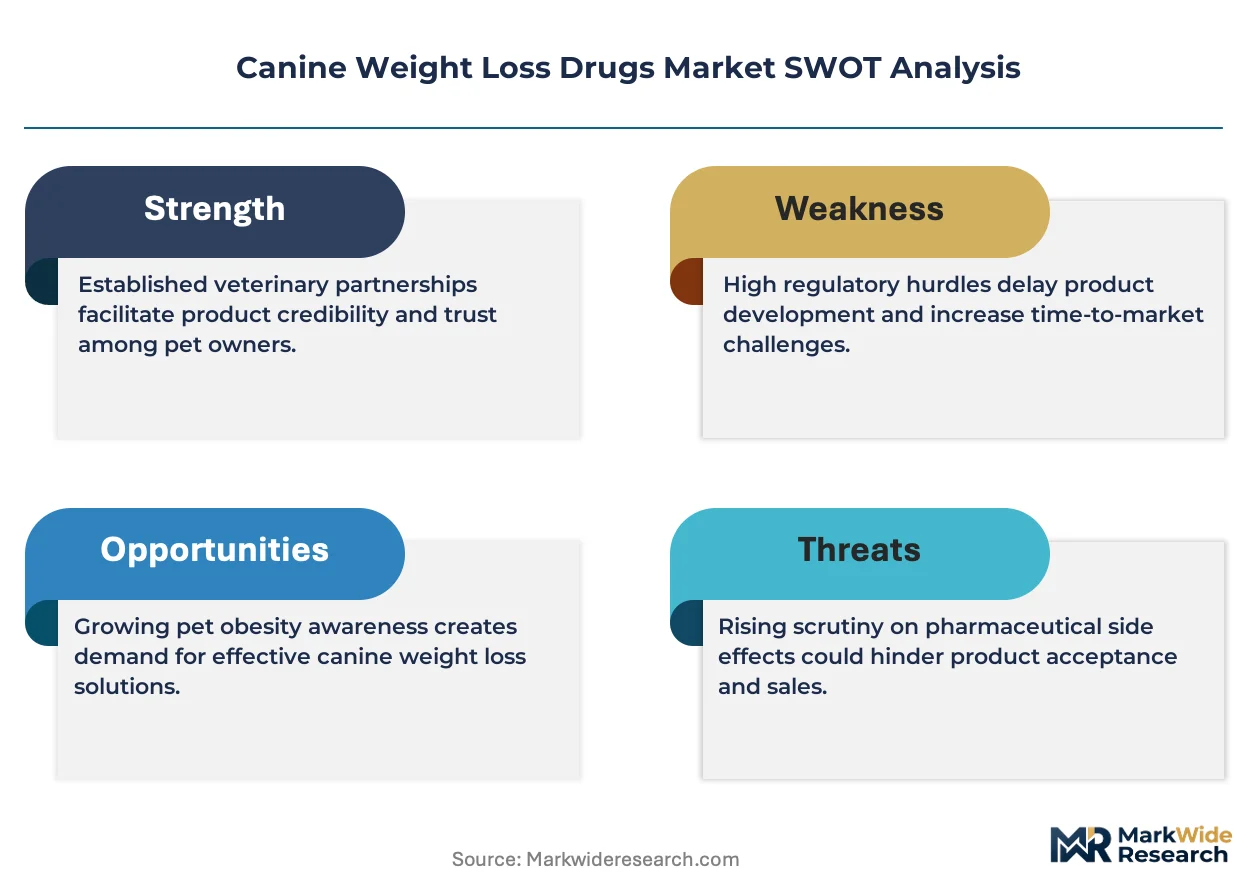
The FDA-CVM's evolving guidance on veterinary drug development is broadening the regulatory pathway for species-specific obesity therapeutics. Mars, Incorporated leverages its integrated pet care ecosystem to sustain distribution advantages across veterinary and retail channels. Novo Nordisk anchors its animal health ambitions through translational research from human metabolic science. Teva Pharmaceutical Industries competes via generic manufacturing scale that supports cost-sensitive oral tablet segments.
Canine weight loss drugs comprise pharmacological agents formulated to reduce adiposity, modulate satiety signaling, or alter metabolic rate in dogs, typically administered as injectable solutions, oral tablets, or palatable chewable matrices with defined dosing protocols calibrated by body condition score. Prescription drugs dominate current revenue pools due to veterinary oversight requirements and higher price realization, while nutraceuticals represent the fastest-expanding category as pet owners seek preventive obesity interventions without clinic visits. Delivery mode selection increasingly tracks owner compliance preferences, with chewable treats capturing share from traditional oral tablets in the companion-animal retail channel.
FDA-CVM oversight governs active pharmaceutical ingredient safety and efficacy claims for prescription canine therapeutics, while the USDA-APHIS regulates certain biologic obesity interventions under veterinary biologics frameworks. The Association for Pet Obesity Prevention and World Pet Obesity Association shape clinical standards and owner education that indirectly influence product positioning and veterinary prescribing behavior. Stakeholders must monitor how evolving FDA-CVM accelerated approval pathways for veterinary drugs reshape competitive timelines and investment thresholds for novel canine metabolic therapies.
Market Dynamics
GLP-1 analog formulation pipelines are compressing development timelines as translational research from human metabolic science accelerates veterinary drug candidate progression. This cross-species knowledge transfer is restructuring competitive entry barriers and reshaping capital allocation toward injectable satiety-modulating therapeutics.
Growth Catalysts
- FDA-CVM Accelerated Approval Pathways:Streamlined veterinary drug review frameworks are shortening time-to-market for novel obesity therapeutics, enabling faster commercialization of species-specific metabolic interventions.
- Companion Animal Obesity Prevalence:Rising adiposity rates in pet populations are driving veterinary clinic demand for prescription-grade weight management protocols calibrated by body condition scoring systems.
- Chewable Matrix Technology:Palatable treat-form drug delivery systems are improving owner compliance and capturing retail channel share from traditional oral tablet formats.
Market Restraints
- API Manufacturing Concentration:Active pharmaceutical ingredient supply for peptide-based therapeutics clusters among specialized contract manufacturers, creating single-source vulnerability for GLP-1 analog production.
- Veterinary Oversight Requirements:Prescription-status mandates under FDA-CVM frameworks limit direct-to-consumer distribution and inflate per-unit costs through clinic-mediated dispensing.
- Biologic Stability Constraints:Temperature-sensitive storage requirements for injectable protein formulations restrict distribution reach and elevate cold-chain logistics expenditure.
Strategic Opportunities
- Preventive Nutraceutical Segments:Non-prescription obesity intervention products targeting pre-clinical weight gain represent underserved white space in companion animal retail channels.
- Telemedicine-Enabled Prescribing:Remote veterinary consultation platforms are emerging as compliant distribution channels for prescription refill maintenance and dosing protocol adjustments.
- Metabolic Biomarker Integration:Convergence of wearable activity monitors with blood-based adipokine testing is enabling personalized drug dosing algorithms calibrated to individual metabolic profiles.
Industry Challenges
- Translational Pharmacology Expertise:Scarcity of veterinary metabolic specialists capable of bridging human drug discovery with canine physiology validation creates recruitment bottlenecks for development teams.
- Multi-Site Clinical Trial Coordination:Efficacy demonstration across diverse breed populations and body condition scores demands geographically dispersed study execution with standardized endpoint measurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canine Weight Loss Drugs Market |
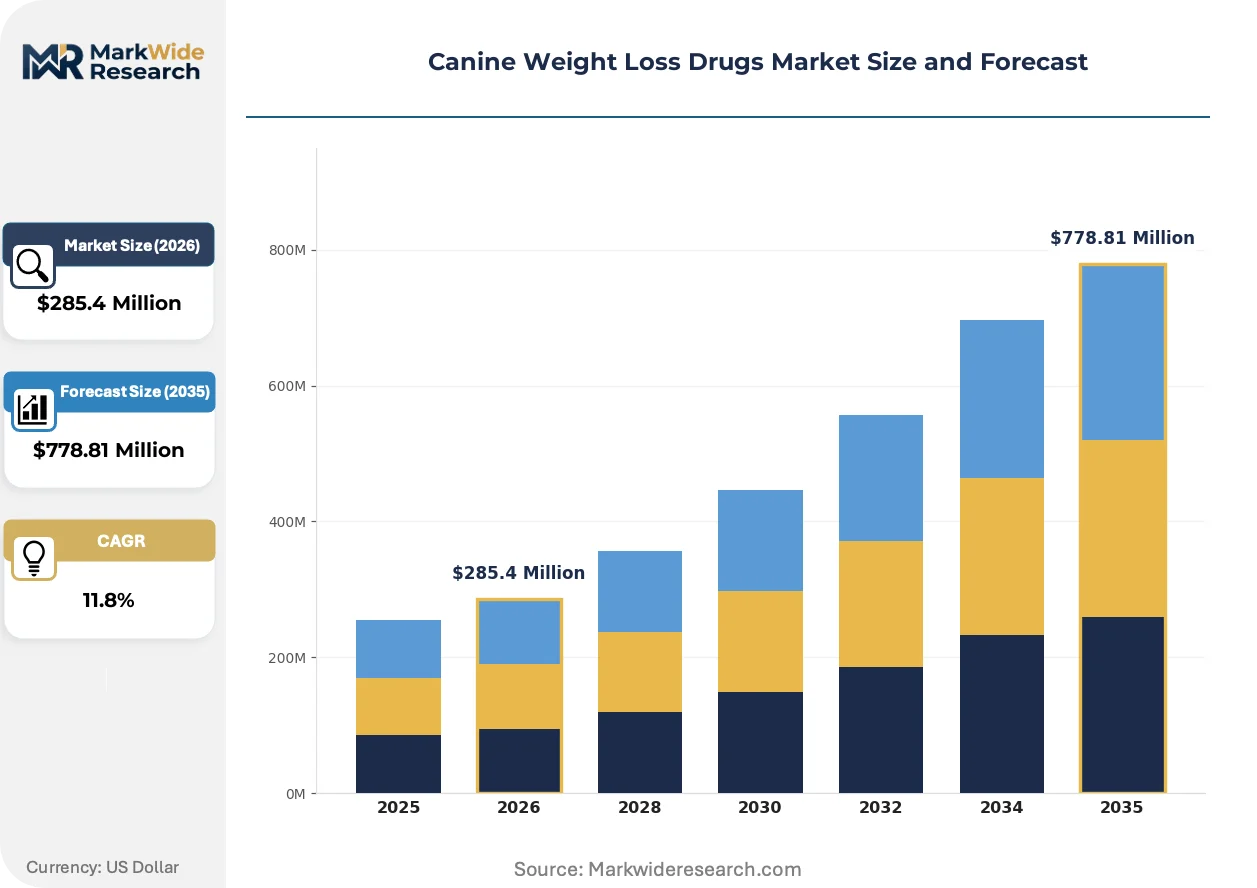
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $778.81 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Drugs, Over-the-Counter Products, Nutraceuticals, Supplements Therapy Area: Obesity Management, Metabolic Disorders, Weight Maintenance, Appetite Regulation Delivery Mode: Injectable, Oral Tablets, Chewable Treats, Powder End User: Veterinarians, Pet Owners, Animal Hospitals, Rescue Organizations |
| Companies Covered | Mars, Incorporated, AstraZeneca, Okava Pharmaceuticals, Association for Pet Obesity Prevention, Teva Pharmaceutical Industries, Better Choice Company, Novo Nordisk, World Pet Obesity Association, Royal Canin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canine Weight Loss Drugs Market Strategic Shifts
Formulation science and delivery mechanism innovation are compressing the gap between human and veterinary metabolic therapeutics. Cross-species pharmacology platforms are enabling faster candidate identification while owner-facing product formats are reshaping compliance expectations.
Long-acting injectable depot formulations are unifying dosing convenience with sustained plasma concentration maintenance. Specialty veterinary pharmaceutical developers are adopting these platforms to reduce injection frequency from daily to weekly or monthly intervals. This convergence of human drug delivery technology with canine metabolic targets is compressing the competitive differentiation window between pipeline candidates and enabling premium pricing for compliance-optimized products.
EU MDR harmonization pressure is extending to veterinary device-drug combination products incorporating delivery mechanisms. Manufacturers of automated injection systems must now navigate dual regulatory scrutiny under both pharmaceutical and medical device frameworks. Injectable solution segments with integrated delivery hardware are responding by front-loading quality management system investments to preempt conformity assessment delays.
Subscription-based preventive care models are displacing episodic clinic visits for obesity management. Corporate veterinary chains and pet insurance underwriters are bundling weight monitoring, nutritional counseling, and pharmaceutical intervention into recurring revenue packages. This behavioral shift is most visible in United States metropolitan markets where pet humanization indices correlate with willingness-to-pay for continuous metabolic health oversight.
Canine Weight Loss Drugs Market Segmentation
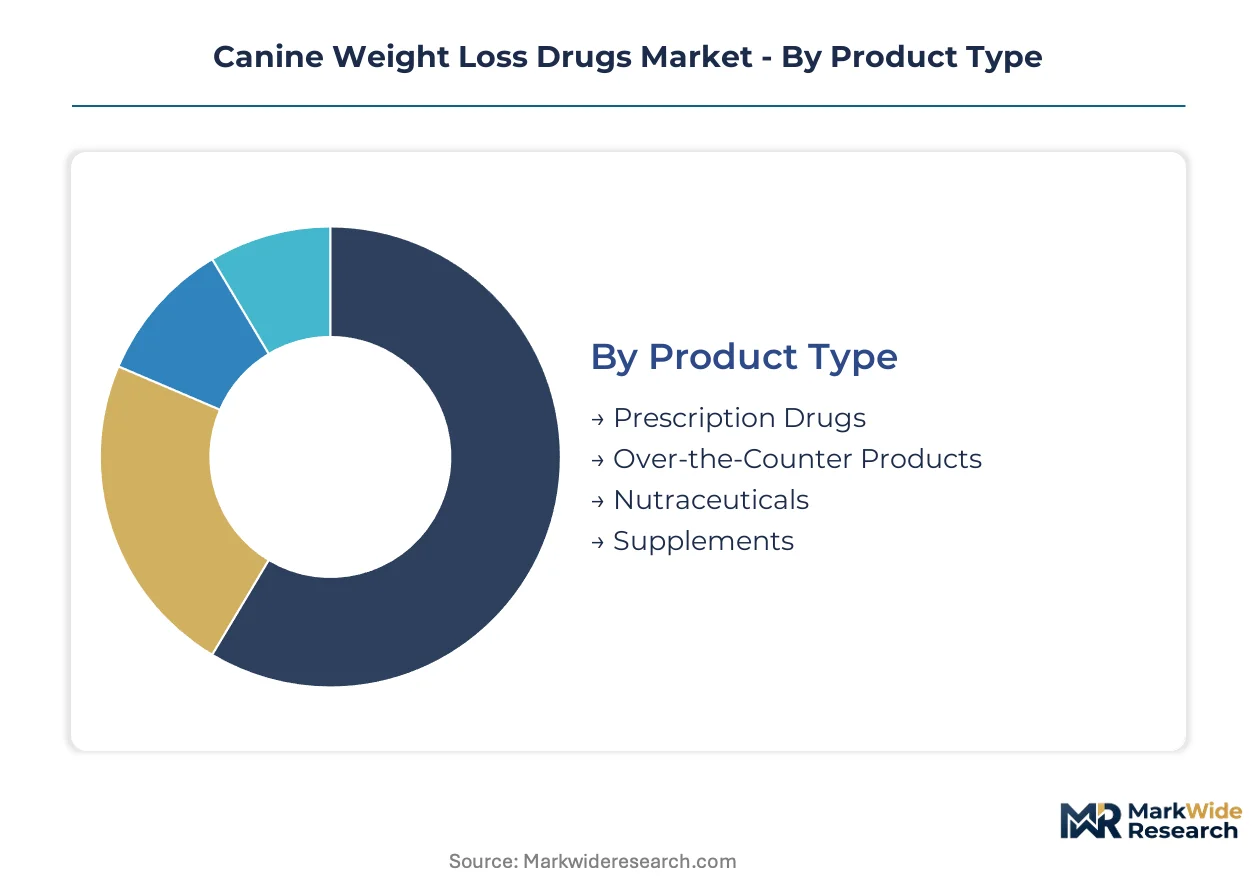
Canine weight loss drug manufacturers calibrate portfolio depth across four distinct segmentation axes. Each dimension reflects divergent buyer economics, compliance constraints, and channel access requirements that shape formulation strategy and pricing architecture.
Product Type:
Veterinary oversight intensity and owner price sensitivity split buyers into four distinct procurement tiers with radically different margin profiles and distribution protocols.
- Prescription Drugs:FDA-CVM-approved formulations requiring veterinary diagnosis and dispensing authorization. Demand concentrates in specialty veterinary clinics across the United States where obesity management protocols integrate body condition scoring with pharmaceutical intervention. Clinic-mediated distribution inflates per-unit realization but limits volume expansion to appointment-constrained channels.
- Nutraceuticals:Non-prescription functional ingredients positioned for preventive adiposity management without clinical oversight. Pet specialty retailers and direct-to-consumer e-commerce platforms in metropolitan United States markets capture the steepest expansion trajectory as owners seek pre-clinical intervention options.
- Over-the-Counter Products:General wellness formulations with limited metabolic claims navigating FDA-CVM enforcement discretion. Mass-market pet retailers and grocery channels distribute these SKUs to cost-conscious owner segments prioritizing accessibility over clinical validation.
- Supplements:Adjunctive fiber, probiotic, and micronutrient blends supporting weight management through digestive modulation. Independent pet stores and veterinary-adjacent retail position these as protocol complements rather than standalone interventions.
Volume sits with Prescription Drugs; growth tilts toward Nutraceuticals.
Therapy Area:
Clinical endpoint severity and intervention timing separate cases requiring acute metabolic correction from maintenance-oriented protocols.
- Obesity Management:Primary therapeutic indication targeting clinically diagnosed adiposity with measurable body condition score elevation. United States veterinary teaching hospitals and specialty referral centers concentrate demand for pharmaceutical-grade interventions with documented efficacy endpoints.
- Metabolic Disorders:Secondary indications addressing insulin dysregulation, hepatic lipidosis, and orthopedic load complications arising from excess adiposity. Endocrinology-focused veterinary practices in academic medical centers drive prescribing for these complex, multi-morbidity cases.
- Weight Maintenance:Post-intervention protocols preventing adiposity recurrence following successful initial reduction. Corporate veterinary chains bundle these into subscription preventive care packages with recurring pharmaceutical dispensing.
- Appetite Regulation:Satiety-modulating interventions targeting behavioral overconsumption patterns. Behavioral medicine specialists and nutrition-focused practices prescribe these for owner-reported feeding dysfunction.
Revenue concentrates in Obesity Management; Metabolic Disorders command the highest per-case pharmaceutical expenditure.
Delivery Mode:
Owner compliance capacity and storage infrastructure availability determine format selection across home-administered and clinic-dependent populations.
- Injectable:GLP-1 analog and peptide-based formulations requiring parenteral administration with cold-chain storage. United States specialty veterinary pharmaceutical developers concentrate investment here, leveraging translational platforms from human metabolic science.
- Chewable Treats:Palatable matrix formulations masking active pharmaceutical ingredients in treat-compatible formats. Retail channel expansion accelerates fastest in companion-animal e-commerce platforms where owner convenience drives repurchase behavior.
- Oral Tablets:Conventional compressed dosage forms with established manufacturing scale and generic competition. Cost-sensitive clinic formularies and rescue organization procurement favor this format for budget-constrained populations.
- Powder:Reconstitutable formulations enabling dose titration and multi-pet household administration. Niche positioning in large-breed and multi-dog environments where tablet count economics prove prohibitive.
Injectable solutions capture premium pricing; Chewable Treats expand most quickly in retail channels.
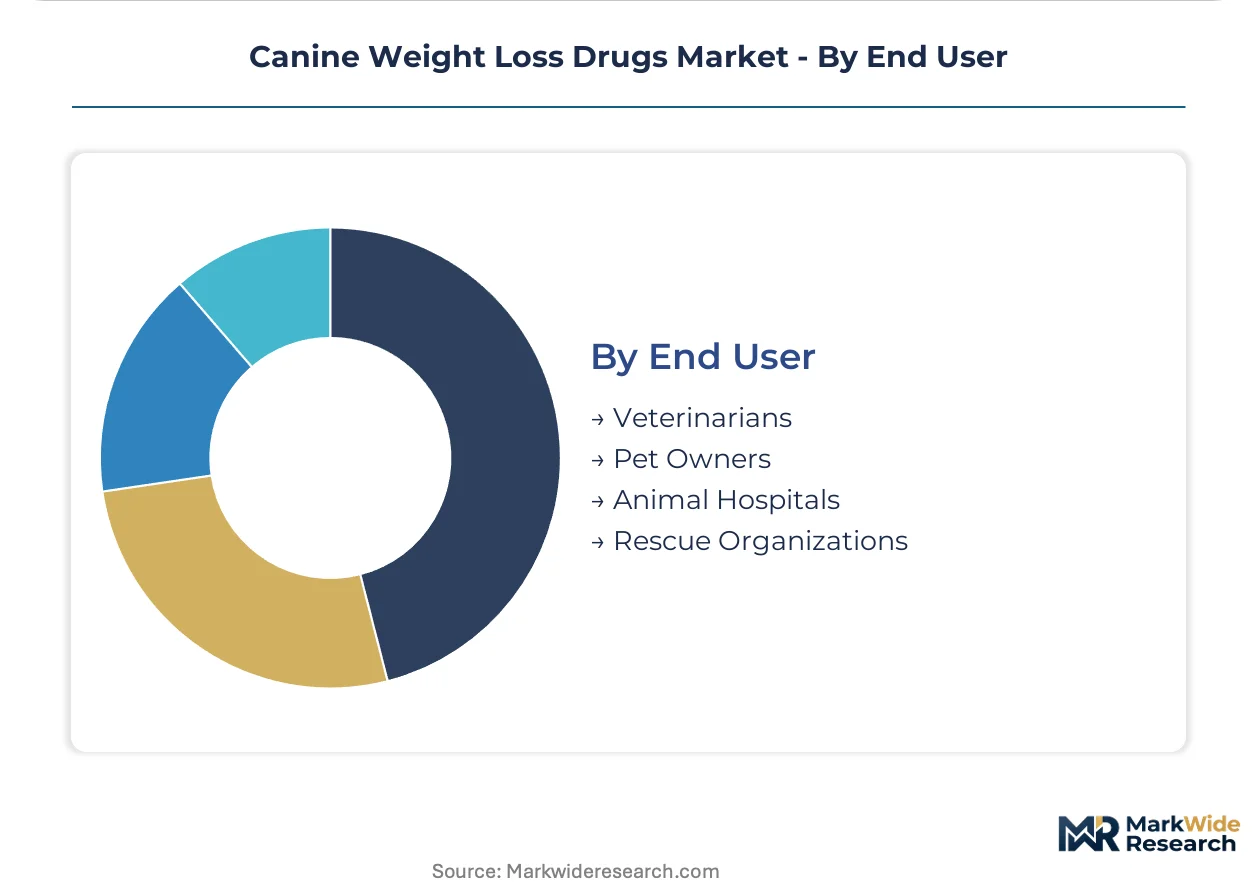
End User:
Decision-making authority and purchasing mechanism fragment the customer base across clinically mediated and direct-access channels.
- Veterinarians:Licensed practitioners with exclusive prescribing authority for FDA-CVM-regulated therapeutics. United States general practice and specialty clinics control access to prescription-grade GLP-1 analogs and metabolic interventions.
- Pet Owners:Final consumers exercising choice within prescription constraints and autonomous selection for non-regulated categories. Urban and suburban United States households with elevated pet humanization indices demonstrate willingness-to-pay for preventive obesity products.
- Animal Hospitals:Institutional purchasers with formulary committees and volume contracting leverage. Academic veterinary medical centers and corporate hospital networks negotiate preferred supplier arrangements for metabolic therapeutic protocols.
- Rescue Organizations:Non-profit and municipal shelters managing adiposity in intake populations with constrained pharmaceutical budgets. Generic oral tablet procurement and donated product access dominate this segment.
Transaction volume flows through Veterinarians; direct-to-owner access is expanding fastest via telemedicine-enabled prescribing platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's veterinary pharmaceutical corridor anchors translational research pipelines for GLP-1 analog development. Corporate veterinary chains in Manhattan and Los Angeles deploy subscription obesity management protocols at scale. Regulatory divergence across national frameworks fragments market entry sequencing.
United States
FDA-CVM accelerated approval pathways compress development timelines for peptide-based therapeutics. The Association for Pet Obesity Prevention shapes clinical standards that influence veterinary prescribing behavior. Specialty pharmaceutical developers cluster in Massachusetts and California to access academic veterinary medical centers.
Germany
Pet humanization indices in metropolitan Berlin and Munich drive willingness-to-pay for preventive obesity interventions. EMA veterinary guidance harmonizes with national pharmaceutical regulations through the Federal Office for Consumer Protection and Food Safety. Industrial formulation specialists in Baden-Württemberg supply palatable matrix technologies to European markets.
Japan
Aging pet demographics in Tokyo and Osaka elevate demand for metabolic disorder management. PMDA veterinary drug review frameworks emphasize species-specific safety documentation. Pharmaceutical developers in Kansai region leverage human diabetes research infrastructure for cross-species therapeutic translation.
United Kingdom
Veterinary practice consolidation in London and Southeast England enables formulary standardization for obesity protocols. The Veterinary Medicines Directorate regulates prescription status under national frameworks. Telemedicine-enabled prescribing platforms emerge from Manchester and Cambridge technology clusters.
Australia
High companion animal ownership rates in Sydney and Melbourne sustain clinic demand for weight management services. TGA veterinary prescription requirements mirror FDA-CVM oversight intensity. Nutraceutical distribution concentrates in Queensland manufacturing zones serving Asia-Pacific export markets.
Canine Weight Loss Drugs Market Competitive Environment
Premium-margin players sit above commodity-margin players across regulatory sophistication and distribution channel control. The market exhibits tiered concentration with integrated pet care conglomerates occupying prescription channels while generic manufacturers compete on oral tablet cost structures. Three archetypes dominate: translational pharmaceutical developers leveraging human metabolic science, diversified pet care ecosystems capturing clinic and retail simultaneously, and contract manufacturing specialists supplying API and finished dosage forms. Competitive moves center on veterinary channel exclusivity arrangements and chewable matrix formulation patents.
Among diversified pet care conglomerates, Mars, Incorporated and Royal Canin exemplify integrated ecosystem strategies spanning nutrition and pharmaceutical adjacencies. Novo Nordisk anchors the translational pharmaceutical tier, drawing on human GLP-1 analog expertise to structure veterinary development pipelines. Teva Pharmaceutical Industries occupies the generic manufacturing position, supplying cost-sensitive oral tablet segments through scale-driven production economics.
| Leading Market Players |
|---|
| Mars, Incorporated |
| AstraZeneca |
| Okava Pharmaceuticals |
| Association for Pet Obesity Prevention |
| Teva Pharmaceutical Industries |
| Better Choice Company |
| Novo Nordisk |
| World Pet Obesity Association |
| Royal Canin |
| Others |
Value Chain & Pricing Dynamics
Prescription-to-nutraceutical tier divergence separates FDA-CVM-regulated therapeutics from retail-accessible preventive formulations, with this bifurcation manifesting in clinic-mediated premium capture versus mass-market cost compression and parallel cold-chain infrastructure versus ambient distribution networks.
Pricing Analysis
Value-based pricing anchored to body condition score improvement outcomes dominates prescription segments, with FDA-CVM approval status and veterinary dispensing authorization commanding substantial premiums over retail channels. Price differentiation rests on clinical validation depth and cold-chain handling certification, while cost compression in oral tablet generics intensifies due to Teva Pharmaceutical Industries' scale manufacturing. Rescue organizations and municipal shelters exhibit acute price sensitivity, whereas specialty veterinary clinics demonstrate inelastic demand for GLP-1 analog injectables.
Supply Chain Analysis
Regional distribution centers in Massachusetts, California, and Baden-Württemberg coordinate hub-and-spoke patterns for temperature-sensitive peptide formulations, with these facilities drawing from API concentration in Switzerland, Denmark, and India. Peptide synthesis reagents, sterile fill-finish capacity, and specialized cold-chain packaging constitute critical input dependencies. Single-source vulnerability for GLP-1 analog active pharmaceutical ingredients presents structural risk. Distribution runs through veterinary clinic networks for prescription tiers and pet specialty retail for nutraceutical segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API manufacturing capacity constraints for peptide-based therapeutics prop pricing power, with contract manufacturing slot scarcity limiting generic entrant scale-up and sustaining margin structures for incumbent developers.
For Market Incumbents: Acquire sterile fill-finish manufacturing assets to capture captive capacity for GLP-1 analog production, insulating against CMO queue delays. Deepen backward integration into peptide synthesis reagents to reduce dependence on Swiss and Danish chemical suppliers. Patent chewable matrix formulation technologies to defend against generic erosion in retail channels. For New Entrants and Emerging Players: Telemedicine-enabled veterinary platforms offer the most penetrable channel for prescription refill maintenance, bypassing clinic appointment bottlenecks. Target preventive nutraceutical segments in United States metropolitan markets where pet humanization indices correlate with subscription willingness. Deploy direct-to-consumer e-commerce with veterinary telehealth partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with translational pharmaceutical developers given FDA-CVM accelerated approval pathway utilization for canine metabolic therapeutics. Long-term viability favors platforms bridging human GLP-1 analog expertise with veterinary physiology validation. Monitor GLP-1 analog pipeline advancement signals as inflection indicators for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA-CVM accelerated review compresses time-to-market for novel peptide therapeutics. |
| Manufacturing Scale-Up | Sterile fill-finish capacity expansion in Massachusetts reduces CMO dependency risks. |
| Pipeline Diversification | Cross-species pharmacology platforms leverage Novo Nordisk human metabolic expertise. |
| Distribution Channel Expansion | Telemedicine-enabled prescribing platforms unlock direct-to-owner prescription access. |
| Strategic Partnership | Corporate veterinary chain bundling secures recurring revenue for obesity protocols. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted among veterinary pharmaceutical development executives, regulatory affairs specialists at FDA-CVM, formulary directors at corporate veterinary chains, and companion animal retail category buyers. Secondary sources encompassed FDA-CVM approval databases, EMA veterinary guidance documents, USDA-APHIS biologics filings, and Association for Pet Obesity Prevention prevalence surveys. Bottom-up prescription volume modeling and top-down metabolic therapeutic expenditure estimates were triangulated for convergence validation.
Granularity-level modeling operated at product type, therapy area, delivery mode, and end user dimensions, with geographic disaggregation to country-specific regulatory clusters. CAGRs were derived from logistic diffusion curves fitted to veterinary adoption patterns, with inputs including FDA-CVM approval timeline assumptions, pet obesity prevalence trajectory projections, and cold-chain infrastructure expansion rates across distribution networks throughout the forecast period.
Caveats apply where FDA-CVM regulatory timeline revisions or API manufacturing supply disruptions could materially shift the outlook. Forecasts reflect documented assumptions regarding veterinary prescribing behavior and owner compliance rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Global Effervescent Tablet Market
Dietary Supplements
Bone and Teeth Supplements Market
Dietary Supplements
Pet Allergy Immune Supplements Market
Dietary Supplements
Global Melatonin Market
Dietary Supplements
Global Lipid Regulators Market
Dietary Supplements
Immune Health Supplements Market
Dietary Supplements
Cardiovascular Health Supplements Market
Dietary Supplements
Global Nicotine Lozenges Market
Dietary Supplements
Sleep Supplement Market
Dietary Supplements
Glucosamine Market
Dietary Supplements
Herbal Medicinal Products Market
Dietary Supplements
Melatonin Sleep Supplements Market
Dietary Supplements
Australia Nicotine Replacement Therapy Market
Dietary Supplements
Androgens and Anabolic Steroids Market
Dietary Supplements
Herbal Medicine Market
Dietary Supplements
Mediterranean Mood and Stress Support Complexes Market