
 Pet Allergy Immune Supplements Market | 2026-2036
Pet Allergy Immune Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Allergy Immune Supplements Market Analytics
The EU Green Deal is realigning ingredient sourcing standards for pet immune supplements across European supply chains. Nutramax leverages its veterinary channel dominance to sustain premium positioning in practitioner-recommended formulations. Zesty Paws competes through direct-to-consumer chewable formats that anchor brand recognition among millennial pet owners. NaturVet differentiates via botanical-forward recipes that occupy the hypoallergenic positioning tier.
Pet allergy immune supplements are orally administered formulations containing bioactive compounds such as quercetin, omega-3 fatty acids, and targeted probiotic strains, designed to modulate histamine response and support mucosal immunity in companion animals. These products undergo cold-processing or microencapsulation to preserve thermolabile actives, then serve primarily as adjunctive interventions for atopic dermatitis and seasonal allergic rhinitis in clinical and home settings. Chewable treats lead volume due to palatability engineering and dosing compliance advantages, while probiotic-active ingredient pairings represent the fastest-growing margin pool as veterinary microbiome research advances. Online retail channels capture expanding share through subscription models, though veterinarian clinics retain the highest trust-conversion rates for first-time immune supplement purchases.
The FDA Center for Veterinary Medicine and the Association of American Feed Control Officials shape ingredient approval pathways and labeling claims for U.S. manufacturers, while the EU's Feed Additives Regulation governs novel immune modulators entering European markets. These frameworks elevate compliance costs for botanical and probiotic entrants but simultaneously filter unsubstantiated efficacy claims that would erode practitioner confidence. Stakeholders must monitor evolving substantiation requirements for microbiome-targeted claims as regulatory science catches up to formulation innovation.
Market Dynamics
The pet allergy immune supplements market pivots on veterinary microbiome research, which is rewiring formulation pipelines and channel authority structures as practitioners demand strain-specific substantiation for probiotic claims.
Growth Catalysts
- Microbiome sequencing advances:Veterinary researchers at university hospitals now map canine atopic dermatitis to specific bacterial imbalances, creating demand for targeted Lactobacillus and Bifidobacterium formulations that manufacturers must match with strain-level documentation.
- FDA Center for Veterinary Medicine guidance evolution:The agency's draft framework for animal dietary supplement substantiation is clarifying permissible structure-function claims, reducing regulatory uncertainty that previously deterred R&D investment in novel immune modulators.
- Suburban veterinary clinic expansion:Dispensing programs at these practices convert diagnostic encounters into supplement recommendations with higher compliance rates than retail channels, anchoring volume in clinical settings.
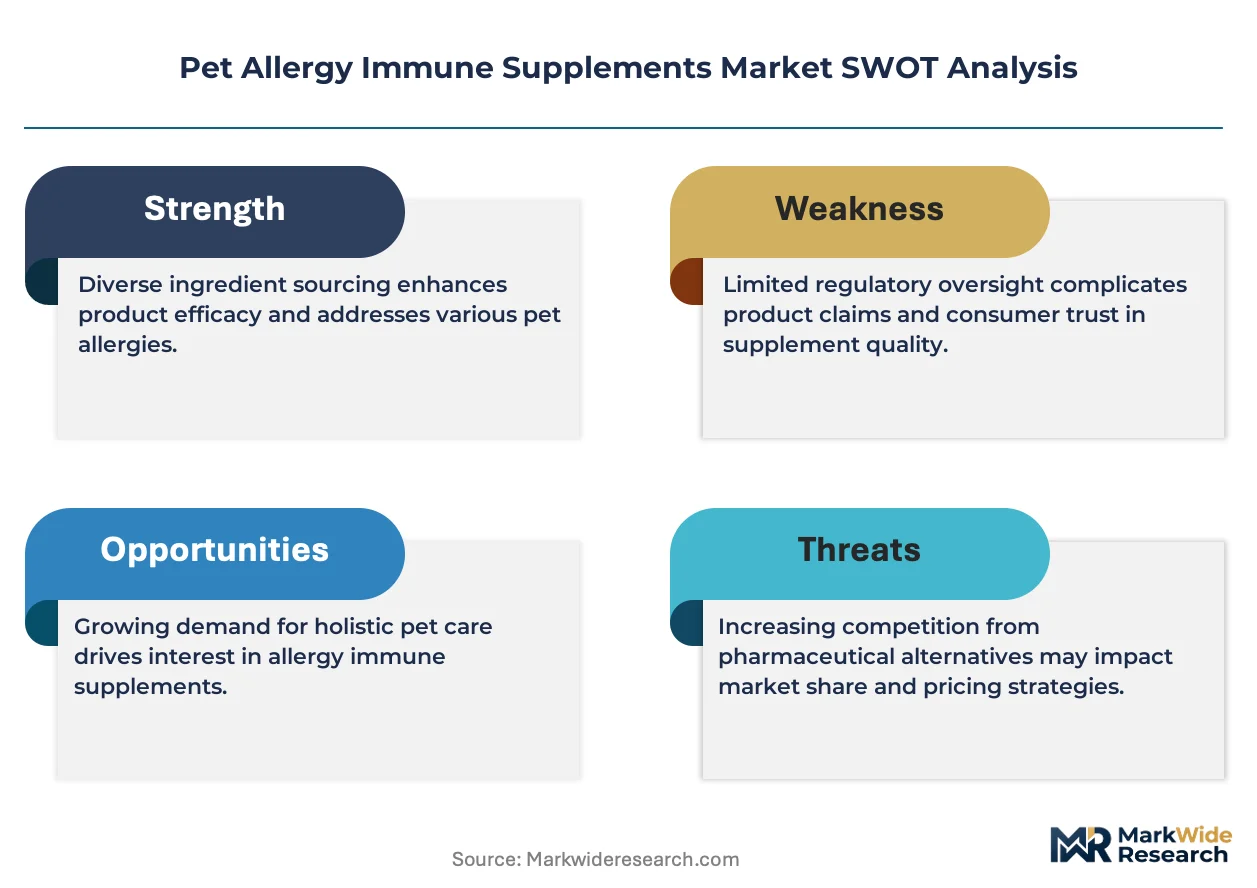
Market Restraints
- Cold-chain logistics costs:Thermolabile probiotic strains require refrigerated transport and storage, elevating distribution expenses that compress margins for products without premium positioning.
- Quercetin raw material concentration:Sophora japonica extract supply clusters in specific agricultural regions, exposing formulators to harvest volatility and price spikes that disrupt cost planning.
- EU Feed Additives Regulation compliance timelines:Novel immune-modulating botanicals face 18-24 month novel food approval processes that delay European market entry and tie up capital in pending dossiers.
Strategic Opportunities
- Subscription-based direct-to-consumer models:Auto-ship platforms bypass veterinary gatekeepers for maintenance-phase purchases, capturing recurring revenue from millennial pet owners who initiated therapy through clinics but seek convenience for refills.
- Feline atopic dermatitis expansion:Canine formulations dominate current SKUs, leaving underserved demand for palatable, low-volume immune supplements calibrated to feline metabolism and taste preferences.
- EU Green Deal sustainable sourcing incentives:Botanical suppliers certified under regenerative agriculture protocols gain preferential access to European veterinary chains that now audit ingredient provenance for environmental credentials.
Industry Challenges
- Microbiome assay standardization gaps:Lack of harmonized methods for quantifying live probiotic counts at end-of-shelf-life creates disputes between manufacturers and contract laboratories over release specifications.
- Veterinary formulary integration complexity:Practice management software systems require custom coding to incorporate immune supplements alongside pharmaceuticals, delaying adoption by multi-location clinic groups.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Allergy Immune Supplements Market |
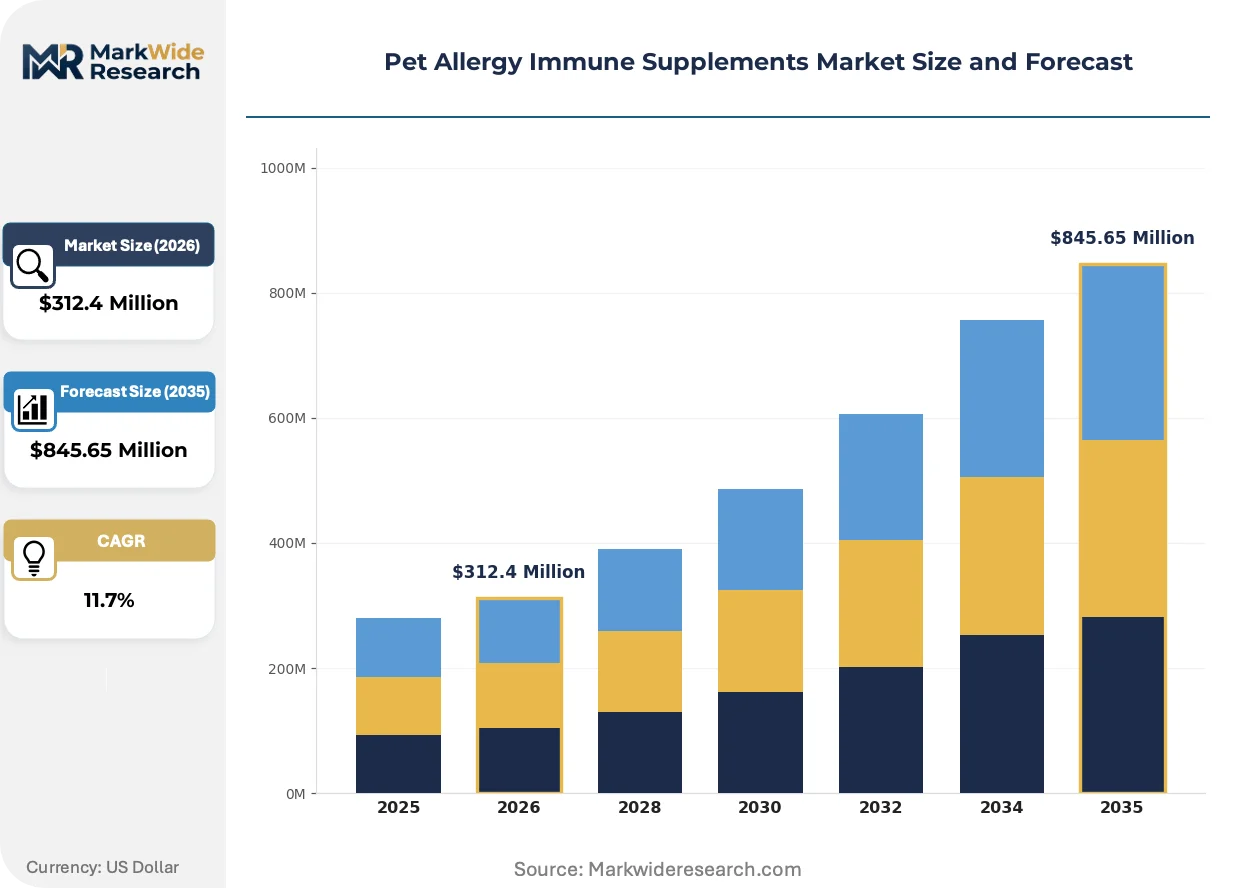
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $845.65 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Chewable Treats, Powders, Liquid Drops Active Ingredient: Quercetin, Omega-3 Fatty Acids, Probiotics, Botanicals Pet Type: Dogs, Cats, Rabbits, Ferrets Distribution Channel: Online Retail, Pet Specialty Stores, Veterinarian Clinics, Supermarkets |
| Companies Covered | Nutramax, Nestlé Purina, Zesty Paws, NaturVet, PetLab Co., PetHonesty, Elanco, VetriScience, Virbac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Allergy Immune Supplements Market Evolving Landscape
Formulation science and channel economics are diverging as microencapsulation technologies enable new delivery formats while regulatory substantiation demands reshape competitive barriers.
Microencapsulation via spray-drying and lipid-coating technologies protects quercetin and omega-3 fatty acids from oxidation and gastric degradation, extending shelf stability from 12 to 24 months. Premium veterinary brands are adopting these processes to justify practitioner-recommended pricing tiers. The technology is expanding into combination products that layer probiotics with bioactive flavonoids, compressing the addressable market for single-ingredient supplements.
EU Green Deal implementation is tightening botanical sourcing documentation requirements, forcing manufacturers to map supply chains back to cultivation plots. Immune supplement producers must now submit geolocation data and pesticide residue testing for quercetin-bearing plants. Small and mid-sized formulators lacking traceability infrastructure face exclusion from European veterinary dispensing programs.
Millennial pet owners are consolidating purchases through veterinary telehealth platforms that bundle diagnostic consultations with supplement subscriptions. These channels displace traditional retail discovery by embedding immune products into treatment protocols during virtual follow-ups. The shift concentrates most visibly in United States metropolitan markets where pet insurance penetration supports ongoing veterinary relationships.
Pet Allergy Immune Supplements Market Segmentation
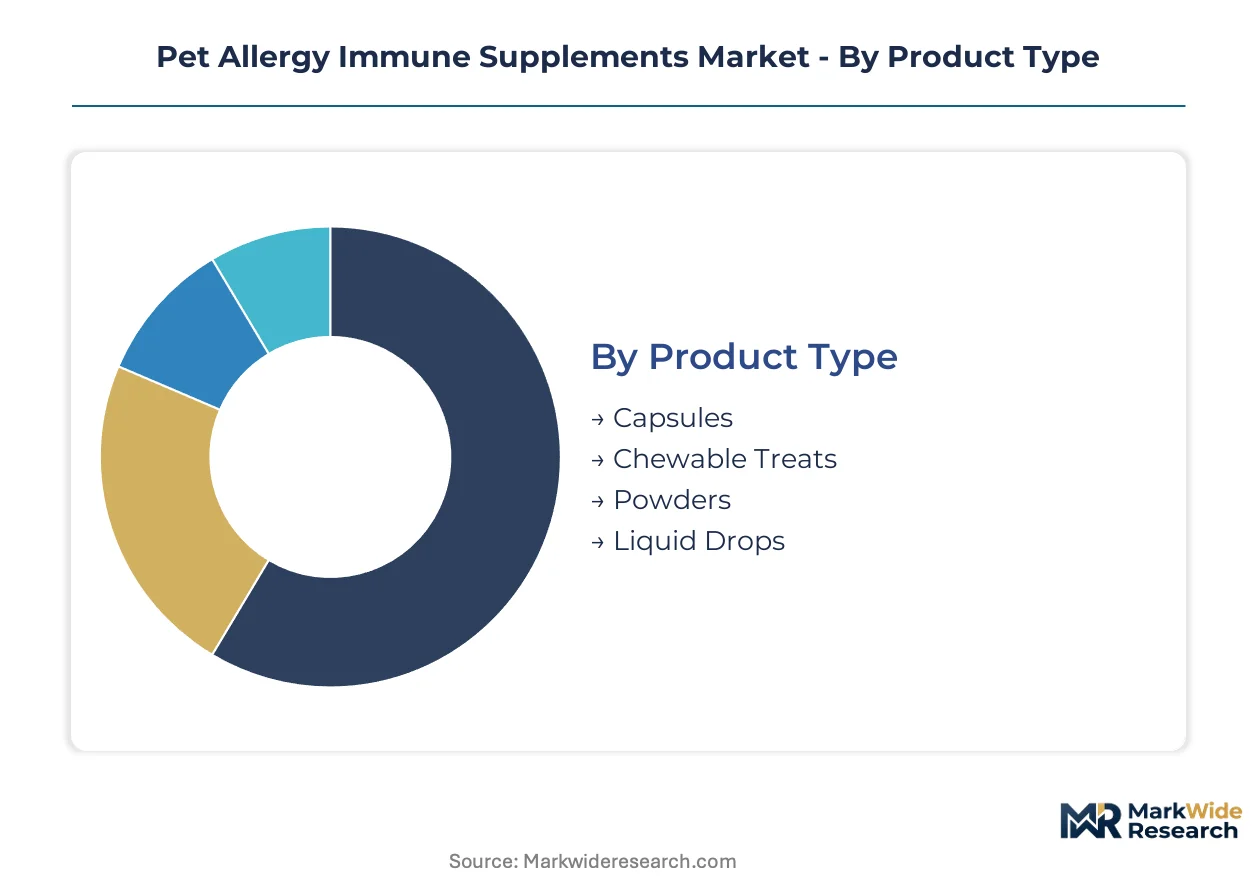
Segmentation in pet allergy immune supplements reveals distinct capital requirements across formulation technologies and channel infrastructures. Manufacturers must align R&D spending with thermolabile ingredient processing while calibrating distribution investments to veterinary versus direct-to-consumer pathways.
Product Type:
Capital intensity varies sharply across delivery formats, with cold-processing infrastructure and palatability engineering driving differential upfront investment thresholds.
- Capsules:Hard-shell gelatin and vegetable-based encapsulation systems require precision dosing equipment and humidity-controlled production suites. Demand clusters in Germany and Switzerland where veterinary clinics prioritize exact-unit dosing for atopic dermatitis protocols; compliance with EMA stability guidelines elevates facility costs.
- Chewable Treats:Palatability engineering demands extrusion and flavor-masking R&D alongside sensory testing facilities. United States suburban veterinary networks favor this format for dispensing program compliance; pet humanization trends justify premium positioning that amortizes equipment spend.
- Powders:Spray-drying and granulation equipment requires moderate capital outlay with shorter depreciation cycles.
- Liquid Drops:Aseptic filling lines and preservative-free formulation suites represent lower barrier to entry for contract manufacturers.
Chewable treats absorb the bulk of installed capacity; liquid drops are expanding most quickly among home-administration segments.
Active Ingredient:
Supply chain concentration and substantiation burden determine which ingredient categories command the highest working capital commitments.
- Quercetin:Sophora japonica extraction and purification requires solvent recovery systems and HPLC validation laboratories. Japanese and Korean botanical suppliers dominate raw material flows; harvest volatility forces manufacturers to carry 6-9 month inventory buffers.
- Omega-3 Fatty Acids:Molecular distillation and microencapsulation protect EPA/DHA from oxidation, demanding nitrogen-flush processing infrastructure. Norwegian and Peruvian marine oil refiners anchor supply; sustainability certification from the Marine Stewardship Council gates access to EU veterinary chains.
- Probiotics:Strain banking, cryopreservation, and live-count validation at end-of-shelf-life create persistent capital absorption.
- Botanicals:Regenerative agriculture certification and geolocation traceability under EU Green Deal protocols elevate documentation costs without comparable processing investment.
Omega-3 fatty acids absorb the bulk of installed capacity; probiotics are gaining share fastest as veterinary microbiome research advances.
Pet Type:
Formulation complexity and metabolic calibration drive divergent development cost structures across species-specific product lines.
- Dogs:Canine metabolism studies and palatability panels for large-breed versus small-breed dosing generate substantial clinical trial expenditure. United States and United Kingdom veterinary universities anchor efficacy research; atopic dermatitis prevalence in Labrador Retrievers and French Bulldogs concentrates demand.
- Cats:Felinine metabolism requires distinct bioavailability studies and low-volume, high-concentration dosing formats. Underpenetration relative to canine SKUs creates first-mover R&D incentives for palatability breakthroughs in finicky feeders.
- Rabbits:Hindgut fermentation physiology limits compatible active ingredients and delivery formats.
- Ferrets:Small mammal veterinary protocols restrict channel access and volume scale.
Dogs absorb the bulk of installed capacity; cats are climbing the fastest as feline atopic dermatitis recognition spreads.
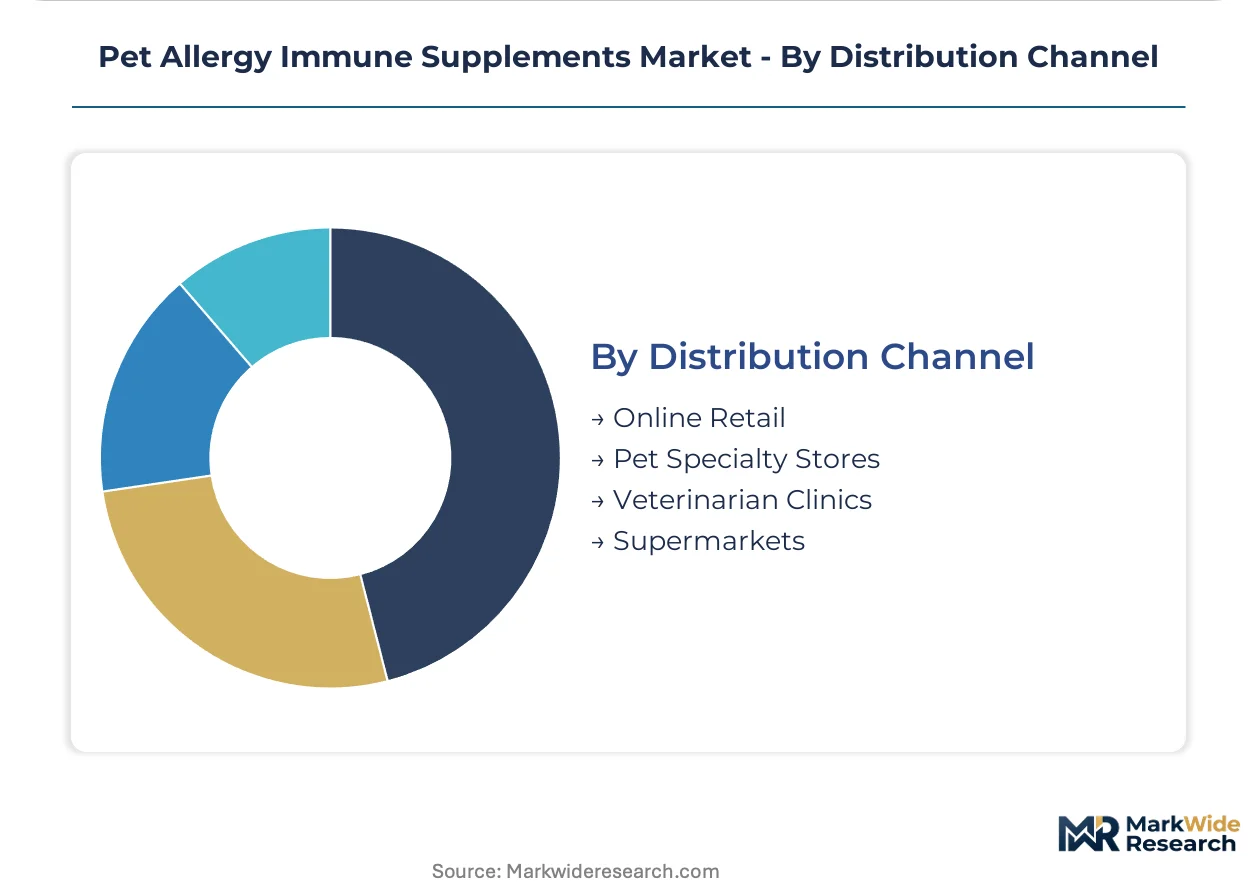
Distribution Channel:
Trust architecture and customer acquisition economics segment channel investments across high-touch clinical and scaled digital infrastructures.
- Online Retail:Subscription platform development, cold-chain logistics integration, and millennial-targeted digital marketing require sustained technology spend. United States metropolitan markets with high pet insurance penetration favor auto-ship models; customer lifetime value calculations justify acquisition cost premiums.
- Veterinarian Clinics:Practice management software integration, field sales forces, and diagnostic protocol development create front-loaded relationship investments. Suburban North American clinic expansion concentrates dispensing program volume; trust-conversion rates exceed retail channels for first-time immune supplement purchases.
- Pet Specialty Stores:Planogram negotiations and staff training programs demand moderate trade marketing budgets.
- Supermarkets:Slotting fees and mass-market packaging standardization compress margins despite volume potential.
Veterinarian clinics absorb the bulk of installed capacity; online retail is expanding most quickly through subscription retention mechanics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Suburban veterinary networks across the United States anchor dispensing program volume for pet allergy immune supplements, with metropolitan clusters in Texas, Florida, and Georgia driving subscription conversion rates through telehealth-integrated platforms.
United States
Millennial pet owners in metropolitan markets with high pet insurance penetration favor auto-ship immune supplement models. The FDA Center for Veterinary Medicine's evolving guidance on animal dietary ingredient substantiation clarifies permissible structure-function claims for manufacturers. Veterinary clinics in suburban Atlanta and Dallas-Fort Worth corridors are expanding in-house dispensing programs that convert diagnostic encounters into supplement recommendations.
Germany
EMA stability guidelines elevate facility costs for hard-shell gelatin encapsulation systems serving exact-unit dosing protocols. The EU Green Deal's regenerative agriculture certification requirements force botanical suppliers to map supply chains back to cultivation plots. University veterinary hospitals in Munich and Leipzig are mapping canine atopic dermatitis to specific bacterial imbalances, creating demand for targeted probiotic formulations.
United Kingdom
Canine atopic dermatitis prevalence in Labrador Retrievers and French Bulldogs concentrates demand for breed-specific immune supplement protocols. The country's national veterinary regulator maintains stringent efficacy substantiation requirements for novel immune modulators. Veterinary universities in London and Edinburgh anchor clinical trial expenditure for canine metabolism studies and palatability panels.
Japan
Sophora japonica extraction and purification infrastructure clusters in specific agricultural regions, exposing formulators to harvest volatility. The PMDA governs novel immune-modulating botanical approvals with timelines that delay market entry for pending dossiers. Botanical suppliers in Osaka and Tokyo prefectures are investing in solvent recovery systems and HPLC validation laboratories to serve premium veterinary brands.
France
Pet humanization trends in Paris and Lyon metropolitan areas justify premium positioning for palatability-engineered chewable formats. The ANSM enforces pesticide residue testing requirements for quercetin-bearing plants under EU Green Deal implementation. Veterinary chains in the Île-de-France region now audit ingredient provenance for environmental credentials, favoring certified regenerative agriculture protocols.
Pet Allergy Immune Supplements Market Competitive Landscape
The competitive structure tilts toward veterinary channel specialists with established practitioner relationships and direct-to-consumer brands with digital-native subscription platforms. Tiered positioning separates premium practitioner-recommended formulations from mass-market chewable formats. Three archetypes dominate: legacy veterinary pharmaceutical companies with dispensing program integration, digitally native pet wellness brands with millennial consumer acquisition engines, and botanical-forward specialists with hypoallergenic positioning. M&A activity concentrates on microbiome research capabilities and cold-chain logistics infrastructure.
Within the veterinary channel tier, Nutramax and Virbac exemplify practitioner-recommended positioning through clinical substantiation investments and practice management software integration. Zesty Paws occupies the direct-to-consumer archetype with subscription retention mechanics and palatability-engineered formats that anchor brand recognition among millennial pet owners. These three companies represent the dominant competitive vectors reshaping channel authority structures as telehealth platforms displace traditional retail discovery.
| Leading Market Players |
|---|
| Nutramax |
| Nestlé Purina |
| Zesty Paws |
| NaturVet |
| PetLab Co. |
| PetHonesty |
| Elanco |
| VetriScience |
| Virbac |
| Others |
Value Network & Pricing Analysis
Veterinary clinic dispensing programs in suburban North America command premium pricing through practitioner endorsement authority, anchoring a value-based model where clinical trust-conversion rates justify elevated per-unit margins over retail alternatives.
Pricing Analysis
Practitioner-recommended efficacy anchors value-based pricing tiers that stratify across clinical validation depth, ingredient traceability certification, and cold-chain integrity guarantees. Subscription-based direct-to-consumer models compress unit economics through auto-ship retention mechanics, while mass-market chewable formats face margin erosion from palatability R&D amortization demands. Price sensitivity concentrates among millennial pet owners initiating therapy through telehealth platforms, whereas veterinary gatekeepers exhibit lowest sensitivity due to diagnostic protocol integration.
Supply Chain Analysis
EU Green Deal regenerative agriculture certification requirements are reshaping botanical sourcing documentation, compelling manufacturers to map quercetin-bearing Sophora japonica cultivation back to specific Japanese and Korean agricultural plots. Raw material flows draw from Norwegian and Peruvian marine oil refiners for omega-3 fatty acids, Japanese botanical extractors for flavonoid purification, and North American cryopreservation facilities for probiotic strain banking. Single-source vulnerability clusters in Sophora japonica harvest regions expose formulators to climate-driven supply interruptions. Distribution runs through veterinary clinic dispensing programs for premium tiers and cold-chain-integrated subscription platforms for direct-to-consumer volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microencapsulation technology is displacing legacy cold-processing methods for thermolabile actives, rewriting formulation economics and shelf-stability benchmarks across practitioner-recommended product lines.
For Market Incumbents: Anchor market position through backward integration into cryopreservation infrastructure for strain-specific probiotic banking, defending against emerging entrants with veterinary microbiome research partnerships. Deepen practice management software integration to lock dispensing program relationships before telehealth platforms disintermediate clinic gatekeepers. For New Entrants and Emerging Players: Feline atopic dermatitis protocols represent the most penetrable white-space segment, given chronic underdevelopment of palatable, low-volume formulations calibrated to finicky feeder metabolism. Millennial pet owners in United States metropolitan markets with high pet insurance penetration offer the clearest go-to-market path through subscription-based telehealth bundling. For Investors and Strategic Acquirers: The window for entry favors cold-chain logistics specialists with veterinary channel relationships, as microbiome-targeted substantiation requirements elevate competitive barriers beyond capital reach of pure-brand entrants. Long-term viability hinges on acquisition targets possessing strain-level documentation capabilities and EU Green Deal traceability infrastructure. Watch for FDA Center for Veterinary Medicine final guidance on animal dietary supplement substantiation as the critical inflection signal for regulatory clarity-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Adoption | Spray-drying and lipid-coating processes extend shelf stability from 12 to 24 months for thermolabile quercetin and omega-3 formulations. |
| Veterinary Telehealth Platform Integration | Embedding immune supplements into diagnostic consultation workflows captures millennial pet owner subscription retention through convenience bundling. |
| EU Green Deal Supply Chain Certification | Regenerative agriculture documentation gates access to European veterinary dispensing programs auditing ingredient provenance. |
| Feline Formulation R&D Expansion | Palatability breakthroughs in low-volume, high-concentration dosing formats address underserved atopic dermatitis demand in cats. |
| Strain-Specific Probiotic Banking | Cryopreservation infrastructure for targeted Lactobacillus and Bifidobacterium formulations matches university hospital microbiome sequencing advances. |
Research Methodology
Independent corroboration across veterinary microbiome researchers at university hospitals, regulatory affairs specialists at the FDA Center for Veterinary Medicine, and procurement leads at suburban clinic dispensing networks underwrites the qualitative findings. Primary interviews with formulation scientists at contract manufacturers, cold-chain logistics operators, and subscription platform developers combined with secondary validation from FDA guidance documents, EMA stability guidelines, EU Feed Additives Regulation submissions, and veterinary trade association procurement surveys. Bottom-up SKU-level volume triangulation against top-down expenditure flow analysis ensures cross-verified demand estimation.
Rate-of-change decomposition across the projection horizon segments growth by product type (chewable treats, capsules, powders, liquid drops), active ingredient category (quercetin, omega-3 fatty acids, probiotics, botanicals), pet species (canine, feline, small mammal), and distribution channel (veterinary clinics, online retail, pet specialty stores). CAGRs derive from veterinary dispensing program expansion trajectories, pet insurance penetration curves, and microbiome research publication velocity as leading indicators of practitioner recommendation propensity.
Revisions become necessary when FDA substantiation guidance finalization, EU novel food approval timeline shifts, or Sophora japonica harvest disruptions materialize beyond modeled assumptions. Forecasts reflect documented assumptions regarding cold-chain infrastructure investment rates and telehealth platform subscription conversion mechanics. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Bone and Joint Health Supplements Market
Dietary Supplements
Global Slimming Aids Market
Dietary Supplements
Herbal Medicinal Products Market
Dietary Supplements
Postpartum Health Supplements Market
Dietary Supplements
Cold and Flu Supplements Market
Dietary Supplements
Diabetic Food Market
Dietary Supplements
Immune Health Supplements Market
Dietary Supplements
Pet Herbal Supplements Market
Dietary Supplements
Postnatal Health Supplements Market
Dietary Supplements
Glucosamine Supplements Market
Dietary Supplements
Colostrum Chewable Tablets Market
Dietary Supplements
Global Nicotine Lozenges Market
Dietary Supplements
Testosterone Injectable Market
Dietary Supplements
Global Effervescent Tablet Market
Dietary Supplements
Cold Remedies Market
Dietary Supplements
Detox Products Market