
 Global Nicotine Lozenges Market | 2026-2036
Global Nicotine Lozenges Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nicotine Lozenges Market Foresight
The pharmacy-to-consumer channel is narrowing as online retail platforms and direct-to-patient subscription models capture share from traditional brick-and-mortar dispensaries. Johnson & Johnson Services, Inc. leverages its heritage in consumer health to sustain shelf presence across major pharmacy chains. GlaxoSmithKline plc anchors its position through clinician-directed smoking cessation programs that drive prescription-adjacent volume. Perrigo Company plc competes aggressively on private-label formulations, undercutting branded pricing in supermarket and convenience store placements.
Nicotine lozenges are oral-dissolving dosage forms containing nicotine polacrilex or nicotine bitartrate, typically formulated at 2 mg or 4 mg strengths to deliver controlled buccal absorption over 20 to 30 minutes for tobacco dependence management. The mint and cherry flavor variants dominate unit volume due to palatability-driven repeat purchase behavior, though sugar-free formulations are gaining fastest as diabetic and dental-conscious quitters reject sucrose-based alternatives. Distribution through pharmacies still captures the highest margin pools because pharmacist counseling justifies premium pricing, while online retail is compressing those spreads through bulk-discount subscription mechanics.
The FDA regulates nicotine lozenges as over-the-counter drug products under its Center for Drug Evaluation and Research, enforcing Good Manufacturing Practice standards that raise barriers to market entry. The European Medicines Agency and national competent authorities such as Germany's Federal Institute for Drugs and Medical Devices apply divergent labeling and advertising restrictions that fragment go-to-market strategies across EU member states. Japan's Ministry of Health, Labour and Welfare maintains tighter pharmacy-only distribution rules that limit convenience store penetration. Stakeholders must monitor whether emerging regulatory frameworks for reduced-risk nicotine products in Brazil and India will open parallel pathways or erect additional compliance hurdles.
Market Dynamics
The pharmacy-to-consumer channel is narrowing as online retail platforms and direct-to-patient subscription models capture share from traditional brick-and-mortar dispensaries. This structural compression is forcing incumbents to rebuild their distribution architecture around digital-first fulfillment and clinician-directed patient support programs.
Growth Catalysts
- FDA Deeming Rule Authority:The FDA's expanded oversight over nicotine replacement therapies is streamlining approval pathways for novel formulations, accelerating product innovation cycles and reducing time-to-market for compliant entrants.
- Hospital Outpatient Programs:Smoking cessation protocols integrated into cardiac and oncology discharge planning are driving institutional procurement volume for nicotine lozenges as standard-of-care adjuncts.
- Sugar-Free Formulation Chemistry:Advances in non-cariogenic sweetener systems are expanding addressable demand among diabetic quitters and dental-conscious consumers previously excluded from sucrose-based products.
Market Restraints
- API Supply Concentration:Nicotine polacrilex active pharmaceutical ingredient production concentrates in a limited number of specialized chemical manufacturers, creating vulnerability to supply disruption and input cost volatility.
- EMA Labeling Fragmentation:Divergent national advertising and packaging restrictions across EU member states force redundant compliance investments and prevent standardized European marketing campaigns.
- Heat-Not-Burn Substitution:Heated tobacco products and modern oral nicotine pouches are capturing switching smokers who might otherwise initiate lozenge-based cessation, compressing the addressable pool for traditional NRT formats.
Strategic Opportunities
- Brazil ANVISA Pathway:Emerging regulatory frameworks for reduced-risk nicotine products in Brazil may open parallel approval channels distinct from pharmaceutical NRT classification, enabling novel positioning strategies.
- Subscription Direct-to-Patient Models:Telehealth-integrated recurring delivery services are capturing adherence-driven revenue streams previously lost to intermittent pharmacy purchases.
- Artificial Intelligence Counseling:Convergence of AI-driven behavioral support apps with lozenge distribution is creating bundled digital therapeutics eligible for expanded reimbursement codes.
Industry Challenges
- Pharmacovigilance Talent Scarcity:The specialized skill set required for post-market adverse event reporting and signal detection in nicotine products is concentrating in a small pool of regulatory professionals, inflating hiring costs.
- Legacy Manufacturing Equipment Retrofit:Existing solid-dose production lines require substantial capital expenditure to meet evolving FDA Good Manufacturing Practice standards for extractable and leachable testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nicotine Lozenges Market |
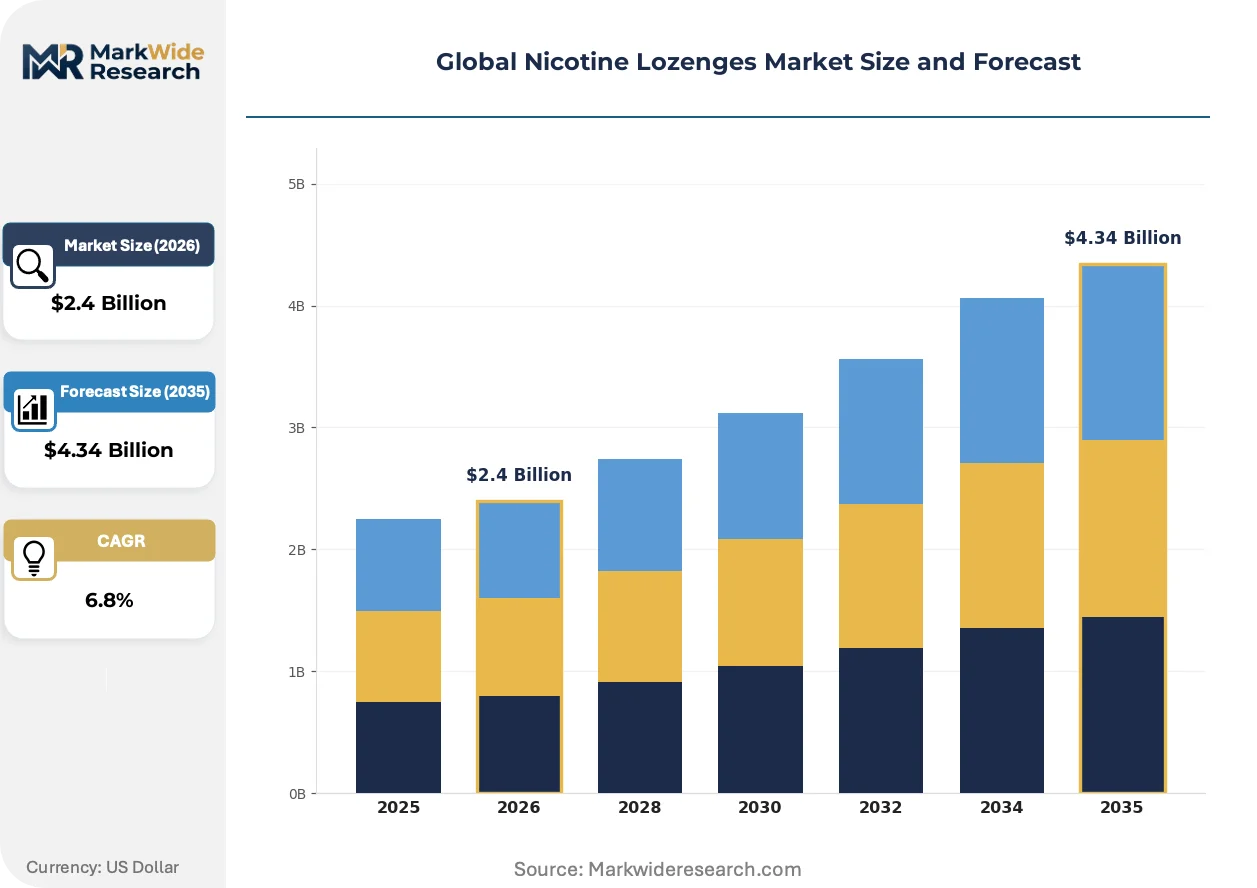
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mint, Cherry, Honey, Lemon Distribution Channel: Pharmacies, Supermarkets, Online Retail, Convenience Stores End User: Smokers, Non-Smokers, Quitters, Healthcare Professionals Formulation: Chewable, Dissolvable, Sugar-Free, Standard |
| Companies Covered | GlaxoSmithKline plc, Johnson & Johnson Services, Inc., Perrigo Company plc, Pfizer Inc., Novartis AG, Cipla Ltd., Fertin Pharma A/S, Dr. Reddy's Laboratories Ltd., Pierre Fabre Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nicotine Lozenges Market Shifts & Advancements
Formulation science and distribution architecture are converging to reshape how nicotine lozenges reach dependent smokers. Three distinct vectors—dissolution technology acceleration, regulatory recalibration, and purchasing behavior digitization—are compressing legacy operating models.
Buccal absorption enhancement technology is collapsing the functional gap between lozenges and faster-acting nicotine delivery systems. Manufacturers are deploying pH-modifying excipient matrices that accelerate nicotine release kinetics without compromising taste masking. Hospital discharge planners and telehealth prescribers are adopting these rapid-onset formats for acute craving management. The structural consequence is compression of market space for conventional 20-to-30-minute dissolution profiles.
REACH chemical registration requirements in the European Union are tightening scrutiny of excipient purity and polymer composition in nicotine polacrilex complexes. Industrial consequence includes mandatory reformulation of legacy products containing non-compliant binder systems. Sugar-free and natural-flavor variants face the steepest compliance timelines as ECHA evaluates novel sweetener metabolites, forcing German and French manufacturers to accelerate substitution programs.
Pharmacy benefit managers are unbundling smoking cessation products from traditional formulary tiers into standalone digital health carve-outs. Employer-sponsored wellness programs are replacing retail reimbursement with direct fulfillment partnerships. This channel migration is most visible in United States self-insured health plans, where integrated behavioral support platforms are capturing patient adherence data previously inaccessible to manufacturers.
Global Nicotine Lozenges Market Segmentation
Nicotine lozenge manufacturers calibrate portfolio depth across flavor chemistry, channel economics, and patient adherence profiles. Each segmentation dimension reveals distinct margin structures and regulatory exposure that shape resource allocation decisions.
Product Type:
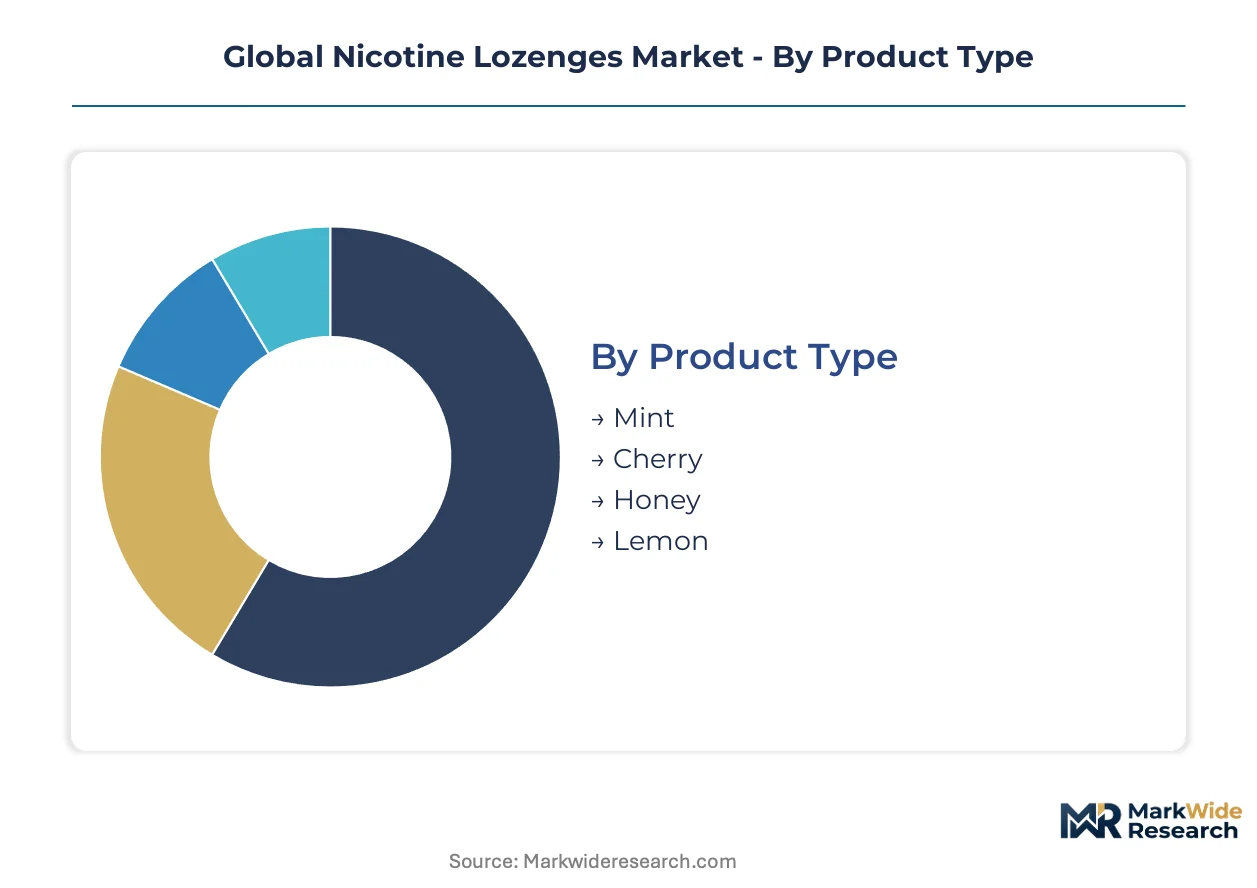
Flavor chemistry determines repeat purchase rates and pharmacy shelf positioning through palatability engineering and masking technology.
- Mint:Formulated with menthol and peppermint oil variants that deliver cooling sensation to counter nicotine bitterness. Demand concentrates in United States pharmacy chains where Johnson & Johnson Services, Inc. maintains dominant shelf presence through heritage brand recognition.
- Cherry:Incorporates artificial and natural cherry flavoring systems with higher sweetener load to mask alkaline nicotine taste. Germany's Federal Institute for Drugs and Medical Devices scrutinizes these formulations under stricter pediatric exposure warnings, compressing marketing flexibility.
- Honey:Natural honey-derived flavoring appeals to consumers seeking reduced-artificial positioning. Japan's Ministry of Health, Labour and Welfare classifies honey-containing variants under enhanced stability testing requirements.
- Lemon:Citrus-based masking systems target consumers with mint sensitivity or preference for acidic taste profiles. Lemon variants rotate up the share rankings in Mediterranean markets where citrus flavoring enjoys cultural familiarity.
Mint holds installed capacity. Cherry is rotating up the share rankings.
Distribution Channel:
Channel selection dictates pricing power, pharmacist counseling integration, and patient data capture depth.
- Pharmacies:Brick-and-mortar dispensaries with licensed pharmacist consultation justify premium pricing through clinical credibility. United States pharmacy benefit managers increasingly bundle lozenges with telehealth smoking cessation protocols.
- Supermarkets:Mass-market retail placements compete on price visibility and impulse purchase location near checkout. Perrigo Company plc deploys private-label formulations aggressively in this channel.
- Online Retail:Direct-to-consumer platforms and subscription services compress margins through bulk discounting while capturing adherence data. This channel is expanding most quickly as telehealth-integrated fulfillment models proliferate.
- Convenience Stores:Immediate-access positioning targets acute craving episodes with single-unit or small-pack formats. Japan's pharmacy-only distribution rules severely restrict this channel's development.
Pharmacies hold installed capacity. Online Retail is rotating up the share rankings.
End User:
Patient segmentation aligns product positioning with cessation stage, nicotine dependence severity, and clinical supervision requirements.
- Smokers:Active tobacco users seeking reduction or preparation for quit attempts. Demand concentrates in hospital outpatient programs where cardiac and oncology discharge planning integrates lozenges as standard-of-care adjuncts.
- Non-Smokers:Minimal addressable population occasionally targeted for off-label cognitive or recreational use. Regulatory scrutiny from FDA and EMA constrains marketing toward this segment.
- Quitters:Individuals in active cessation protocols with highest adherence requirements and longest treatment duration. This segment commands premium pricing through prescription-adjacent positioning in clinician-directed programs.
- Healthcare Professionals:Institutional procurement for protocol-driven distribution in clinical settings. Germany's hospital formulary committees drive volume through standardized smoking cessation order sets.
Quitters hold installed capacity. Healthcare Professionals is rotating up the share rankings.
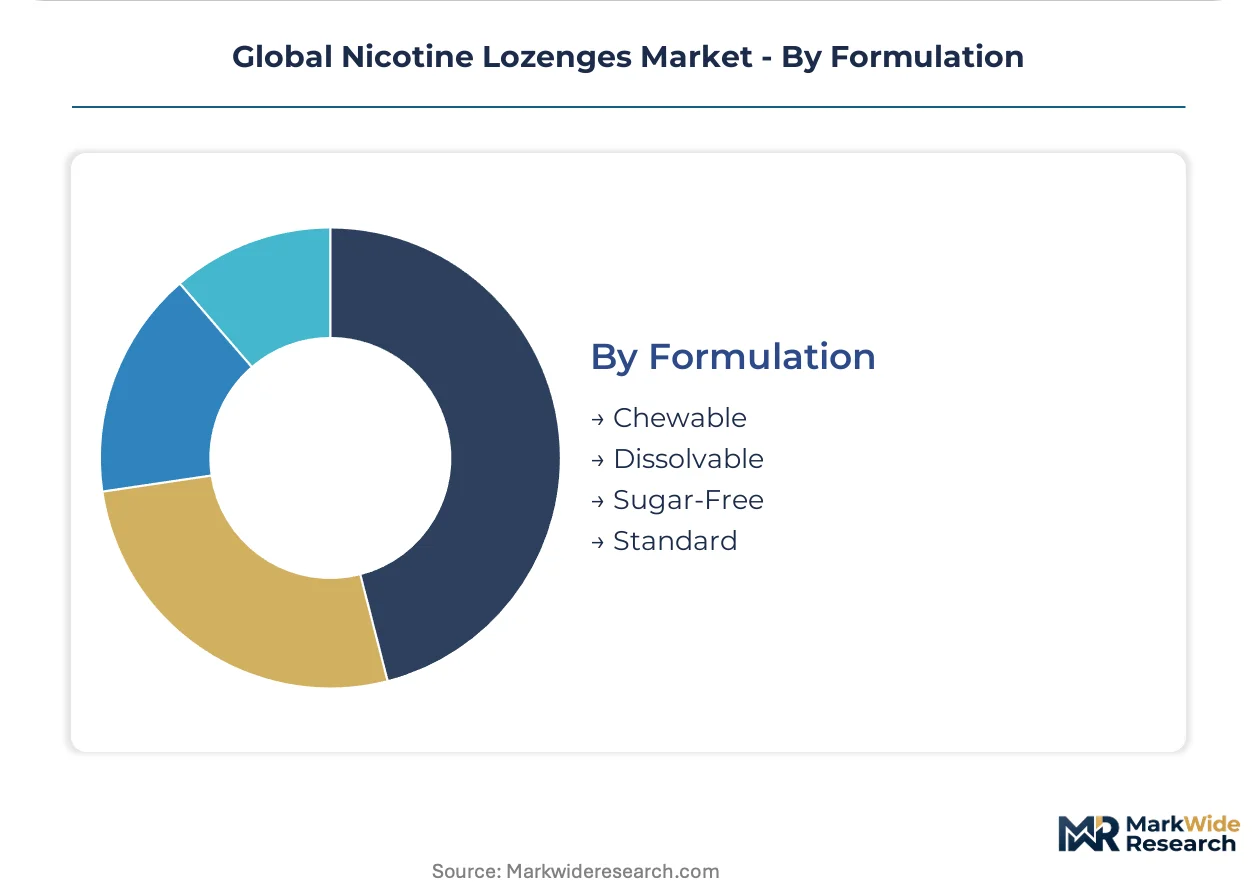
Formulation:
Dosage form engineering balances dissolution kinetics, taste masking, and metabolic compatibility for diverse patient populations.
- Chewable:Bite-activated release systems allowing user-controlled nicotine delivery pacing. Demand concentrates in convenience store channels where immediate craving management drives format preference.
- Dissolvable:Buccal absorption through passive dissolution over 20-30 minutes with controlled release matrices. Japan's PMDA favors this format for pharmacy-only distribution due to predictable pharmacokinetic profiles.
- Sugar-Free:Non-cariogenic sweetener systems replacing sucrose for diabetic and dental-conscious consumers. This formulation is climbing the fastest as REACH chemical registration tightens scrutiny of novel sweetener metabolites in the European Union.
- Standard:Conventional sucrose-based formulations with established manufacturing processes and lowest unit cost. Legacy products face reformulation pressure from ECHA evaluations of binder system compliance.
Dissolvable holds installed capacity. Sugar-Free is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA's deeming rule authority over nicotine replacement therapies anchors the United States as the dominant geography, while divergent regulatory frameworks across Germany, Japan, Brazil, and India fragment go-to-market strategies and reshape distribution architectures.
United States
Hospital outpatient programs and pharmacy benefit managers drive institutional procurement volume for nicotine lozenges as standard-of-care adjuncts in cardiac and oncology discharge planning. The FDA's Center for Drug Evaluation and Research enforces Good Manufacturing Practice standards that raise barriers to market entry. New Jersey-based manufacturing clusters concentrate production capacity for nicotine polacrilex active pharmaceutical ingredient.
Germany
The Federal Institute for Drugs and Medical Devices applies stricter pediatric exposure warnings to cherry-flavored formulations, compressing marketing flexibility for palatability-driven variants. REACH chemical registration requirements tighten scrutiny of excipient purity and polymer composition in nicotine polacrilex complexes. Frankfurt and Munich anchor distribution networks serving EU member states with divergent national labeling restrictions.
Japan
The Ministry of Health, Labour and Welfare maintains pharmacy-only distribution rules that limit convenience store penetration and favor predictable pharmacokinetic profiles. Tokyo and Osaka metropolitan areas concentrate smoking cessation protocol integration within employer-sponsored wellness programs. PMDA regulatory preferences accelerate demand for rapid-onset buccal absorption formats.
Brazil
ANVISA's emerging regulatory frameworks for reduced-risk nicotine products may open parallel approval channels distinct from pharmaceutical NRT classification. São Paulo state anchors private-label manufacturing for Latin American export markets. Hospital formulary committees in Rio de Janeiro pilot institutional procurement programs modeled on European smoking cessation protocols.
India
CDSCO oversight of over-the-counter drug classification creates compliance complexity for multinational entrants seeking pharmacy distribution. Mumbai and Hyderabad concentrate contract manufacturing capacity for sugar-free formulation chemistry serving diabetic and dental-conscious consumer segments. State-level tobacco control programs in Maharashtra integrate lozenge distribution into primary health center outreach.
Global Nicotine Lozenges Market Competitive Landscape
Consumer health conglomerates and pharmaceutical specialists split the market between pharmacy-centric heritage positioning and private-label value engineering. The vendor base concentrates around three strategic archetypes: multinational consumer health divisions leveraging clinician-directed program integration, generic manufacturers competing on formulation cost, and contract development organizations serving emerging market licensing. Consolidation pressure intensifies as telehealth-integrated fulfillment models displace traditional pharmacy shelf presence. Vertical integration into active pharmaceutical ingredient supply and backward integration into flavor chemistry masking technology represent dominant competitive vectors.
Within the heritage consumer health tier, Johnson & Johnson Services, Inc. and GlaxoSmithKline plc exemplify archetypes built on pharmacist counseling integration and prescription-adjacent volume capture. Perrigo Company plc occupies a position representing private-label specialists competing through supermarket and convenience store channel penetration. These three anchors illustrate the structural divergence between premium-priced clinical credibility and mass-market price visibility.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Johnson & Johnson Services, Inc. |
| Perrigo Company plc |
| Pfizer Inc. |
| Novartis AG |
| Cipla Ltd. |
| Fertin Pharma A/S |
| Dr. Reddy's Laboratories Ltd. |
| Pierre Fabre Group |
| Others |
Supply & Pricing Matrix
Overcapacity in New Jersey-based nicotine polacrilex API manufacturing is compressing supplier pricing power while simultaneously forcing contract manufacturers toward extended payment terms to preserve working capital. This utilization dynamic creates divergent margin pressure across branded and private-label tiers, with pharmacy-channel incumbents absorbing cost volatility through formulary bundling while supermarket-positioned generics face spot-market exposure.
Pricing Analysis
Geographic price spreads between United States pharmacy chains and European supermarket channels exceed two-to-one ratios for equivalent 4 mg formulations. Three-tier pricing structure across premium, standard, and economy levels stratifies around pharmacist counseling integration, FDA registration tier, and private-label sourcing. Cost compression in economy tiers is intensifying because Perrigo Company plc's private-label aggression forces branded repositioning toward adherence-program bundling. Hospital procurement committees exhibit lowest price sensitivity due to protocol-driven standard-of-care mandates, while convenience-store impulse purchasers demonstrate highest elasticity.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now characterize API procurement contracts as specialized chemical manufacturers absorb working-capital strain from overcapacity conditions. Nicotine polacrilex production concentrates in the United States, India, and China, with formulation finishing clustered in Germany and Japan. Supply chains draw from tobacco-derived nicotine resin, pharmaceutical-grade binders, and non-cariogenic sweetener systems. Single-source vulnerability in menthol cooling-agent supply creates exposure to botanical harvest volatility. Distribution runs through pharmacy benefit manager formularies, direct-to-patient subscription platforms, and mass-market retail procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The narrow pipeline of regulatory professionals capable of navigating FDA pharmacovigilance reporting and EMA labeling fragmentation represents the critical capability gap constraining competitive response speed. Organizations that secure this talent or automate compliance workflows will outmaneuver capacity-constrained rivals.
For Market Incumbents: Insulate formulary positioning by acquiring captive supply of nicotine polacrilex API and deploying AI-driven adherence platforms that lock hospital discharge protocols into recurring subscription models. Heat-not-burn substitution and modern oral nicotine pouches threaten patient initiation pools; vertical integration into rapid-onset buccal absorption technology defends against format displacement. For New Entrants and Emerging Players: Brazil's ANVISA reduced-risk product pathway represents the most penetrable entry point for novel positioning outside pharmaceutical NRT classification. Sugar-free formulation chemistry for diabetic and dental-conscious quitters offers white-space expansion with lower incumbent saturation. Telehealth-integrated direct-to-patient subscription models provide the most viable go-to-market angle bypassing pharmacy shelf-access barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among telehealth-integrated adherence platforms with pharmacy benefit manager carve-out contracts. Long-term viability across the analysis window favors targets with FDA Master File documentation and EMA centralized procedure access. The signal to watch is ANVISA regulatory guidance publication timing, which will indicate parallel pathway opening for reduced-risk positioning.| Strategic Initiative | Industry Significance |
|---|---|
| API Supply Backward Integration | Captive nicotine polacrilex production insulates Johnson & Johnson Services, Inc. from input cost volatility. |
| AI Counseling Platform Launch | Behavioral support app bundling creates digital therapeutic eligibility for expanded reimbursement codes. |
| Sugar-Free Formulation Expansion | Non-cariogenic sweetener systems capture diabetic quitters excluded from sucrose-based alternatives. |
| Telehealth Subscription Partnership | Direct-to-patient fulfillment captures adherence data previously inaccessible through pharmacy channels. |
| Brazil ANVISA Pathway Investment | Reduced-risk product classification enables novel positioning distinct from pharmaceutical NRT regulation. |
Research Methodology
Initial hypotheses were tested against primary input from regulatory affairs directors, pharmacy benefit manager formulary leads, hospital procurement managers, and smoking cessation protocol coordinators and refined through secondary validation against FDA 510(k) filings, EMA centralized procedure assessments, ClinicalTrials.gov protocol registries, and pharmacy retail audit databases. Bottom-up demand modeling across flavor variants, distribution channels, and patient adherence segments was triangulated against top-down market sizing from API production capacity and import-export customs records.
Demand-supply balance modeling across the analysis window incorporated hospital discharge protocol integration rates, telehealth subscription adoption curves, and heat-not-burn substitution elasticity. Segmentation dimensions included flavor chemistry, distribution channel economics, patient cessation stage, and formulation technology tier. CAGRs were derived from patient population flow modeling and pricing trajectory assumptions calibrated to pharmacy reimbursement rate negotiations and private-label penetration curves.
Macroeconomic conditions sit as an overlay; deviation in employer wellness program spending, FDA enforcement discretion, or EU REACH chemical registration timelines would shift the trajectory. Forecasts reflect documented assumptions regarding smoking cessation protocol standardization and reduced-risk product regulatory pathway evolution. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Sleep Aid Supplements Market
Dietary Supplements
Concentrated Angelica Pills Market
Dietary Supplements
Testosterone Injectable Market
Dietary Supplements
Detox Products Market
Dietary Supplements
Bisglycinate Market
Dietary Supplements
Global Effervescent Tablet Market
Dietary Supplements
Nausea Relief Chews Market
Dietary Supplements
Hair Loss Supplement Market
Dietary Supplements
Diabetic Food Market
Dietary Supplements
Global Vitamin D Therapy Market
Dietary Supplements
Herbal Tincture Market
Dietary Supplements
Menopause Supplement Market
Dietary Supplements
Fertility Supplements Market
Dietary Supplements
Colostrum Chewable Tablets Market
Dietary Supplements
Global Melatonin Market
Dietary Supplements
Sleep Supplement Market