
 Tea Beer Market | 2026-2036
Tea Beer Market Size, Share, and Industry Trends Forecast 2026-2036
Tea Beer Market Analytics
The price-performance gap between premium craft tea beer and mass-market flavored malt beverages is hardening as raw material costs diverge. Dogfish Head Craft Brewery Inc. leverages its experimental brewing pedigree to command shelf space in specialty channels. The Boston Beer Company sustains national distribution density through its established wholesaler relationships. Anheuser-Busch Companies LLC anchors the volume tier with production scale that undercuts craft pricing.
Tea beer denotes a fermented malt beverage incorporating brewed tea or tea extracts as a flavoring adjunct, typically produced through secondary fermentation or cold-steeping processes that preserve volatile aromatic compounds while achieving alcohol contents ranging from non-alcoholic to imperial strengths above 8% ABV. Hazy IPA and Sour Ale variants capture the fastest growth trajectories as brewers exploit hop-tea synergy and acidity balance for differentiation. Black Tea formulations dominate current volume due to familiar flavor profiles and robust tannin structure, while Oolong Tea segments attract premium positioning through sourcing complexity and limited-batch scarcity.
The US TTB mandates precise labeling of tea-derived ingredients and alcohol content thresholds, while the FDA exercises jurisdiction over health claims and adulteration standards for cross-category beverages. State-level alcohol control boards in California, Colorado, and Oregon impose additional permitting requirements for tea-beer hybrids that complicate multi-state distribution. Stakeholders must monitor evolving ingredient classification disputes between malt beverage and ready-to-drink tea regulatory frameworks.
Market Dynamics
Regulatory divergence between malt beverage and ready-to-drink tea frameworks is fragmenting compliance pathways and forcing brewers into dual-track formulation strategies that strain R&D budgets.
Growth Catalysts
- TTB Ingredient Disclosure Mandates:The US Alcohol and Tobacco Tax and Trade Bureau's tightening labeling requirements for hybrid beverages are accelerating transparency investments that build consumer trust in craft channels.
- Cold-Steeping Process Innovation:Advances in low-temperature extraction technology are preserving volatile aromatic compounds in tea beers, enabling flavor consistency at commercial scale.
- Portland-Denver-Brooklyn Cluster Density:Urban craft beer corridors are concentrating specialty retail shelf space and on-premise tap rotation programs that incubate experimental formats.
Market Restraints
- Input Cost Volatility:Specialty tea leaf procurement from Fujian and Assam faces climate-driven harvest inconsistency that compresses gross margins on premium Oolong formulations.
- Multi-State Permitting Friction:California, Colorado, and Oregon alcohol control boards impose divergent hybrid-beverage licensing that complicates national distribution for mid-size brewers.
- Flavor Stability Limitations:Tannin-oxidation during secondary fermentation creates shelf-life constraints that restrict export viability for unpasteurized tea beer variants.
Strategic Opportunities
- Non-Alcoholic Segment White Space:The sub-0.5% ABV category remains underdeveloped in North American markets, offering first-mover positioning for brewers mastering dealcoholization without flavor degradation.
- Direct-to-Consumer Subscription Channels:Brewery-owned membership programs bypass three-tier distribution constraints and capture full margin on limited-batch releases.
- Hoppy-Tea Convergence:Cross-utilization of hop and tea supply chains is creating ingredient sourcing efficiencies and novel aromatic profiles that differentiate Hazy IPA variants.
Industry Challenges
- Cross-Category Formulation Expertise Gap:Brewers lack in-house competency in tea chemistry and tannin management, forcing reliance on external consultants for recipe development.
- Dual Jurisdiction Compliance Timelines:Simultaneous FDA health-claim review and TTB formula approval processes extend product launch cycles by 8-14 months.
- Cold-Chain Infrastructure Capex:Temperature-controlled distribution requirements for volatile aromatic preservation demand fleet investments that strain regional brewery balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tea Beer Market |
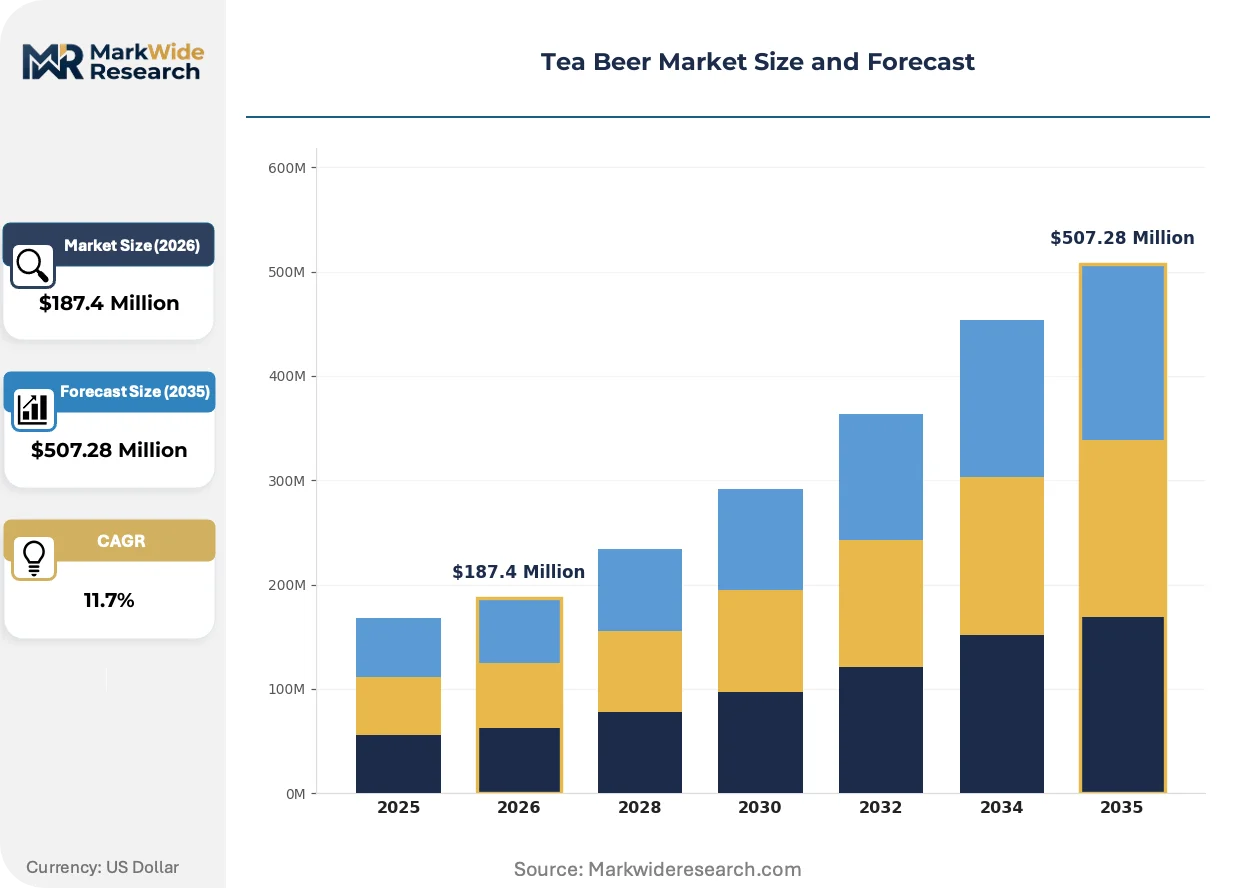
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hazy IPA, Sour Ale, Lager, Stout Tea Type: Green Tea, Black Tea, Herbal Tea, Oolong Tea Alcohol Content: Low Alcohol, Moderate Alcohol, High Alcohol, Non-Alcoholic Packaging Type: Cans, Bottles, Kegs, Draft |
| Companies Covered | Breakside Brewery, Dangerous Man Brewing Co., Dogfish Head Craft Brewery Inc., I and I Brewing, Lakefront Brewery, Inc., The Boston Beer Company, Pabst, Twisted Tea, Anheuser-Busch Companies LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tea Beer Market Evolving Landscape
Automation of quality control and formulation precision is compressing batch-to-batch variation while regulatory clarity emerges around cross-category beverage classification.
In-line spectroscopy combined with machine-learning flavor profiling is automating real-time adjustment of tea extraction parameters during brewing. Mid-size craft breweries in Colorado and Oregon are deploying these systems to reduce sensory panel dependency. The technology is automating consistency assurance that previously required master brewer intervention, enabling scale without diluting artisanal positioning.
The US TTB's 2023 guidance on tea-derived ingredient disclosure has triggered reformulation across the malt beverage industry. Brewers must now separate tea extract sourcing from alcohol content statements on labels. Small-batch producers in Brooklyn face the steepest compliance costs, while national distributors absorb labeling changes through existing packaging refresh cycles.
Urban consumers are rotating toward lower-ABV session formats that emphasize botanical complexity over alcohol intensity. Specialty bottle shops in Portland are displacing high-gravity imperial stouts with 4-5% ABV tea-infused sours in prime cooler positioning. This preference shift concentrates in coastal metropolitan markets where wellness-oriented drinking occasions intersect with craft exploration behavior.
Tea Beer Market Segmentation
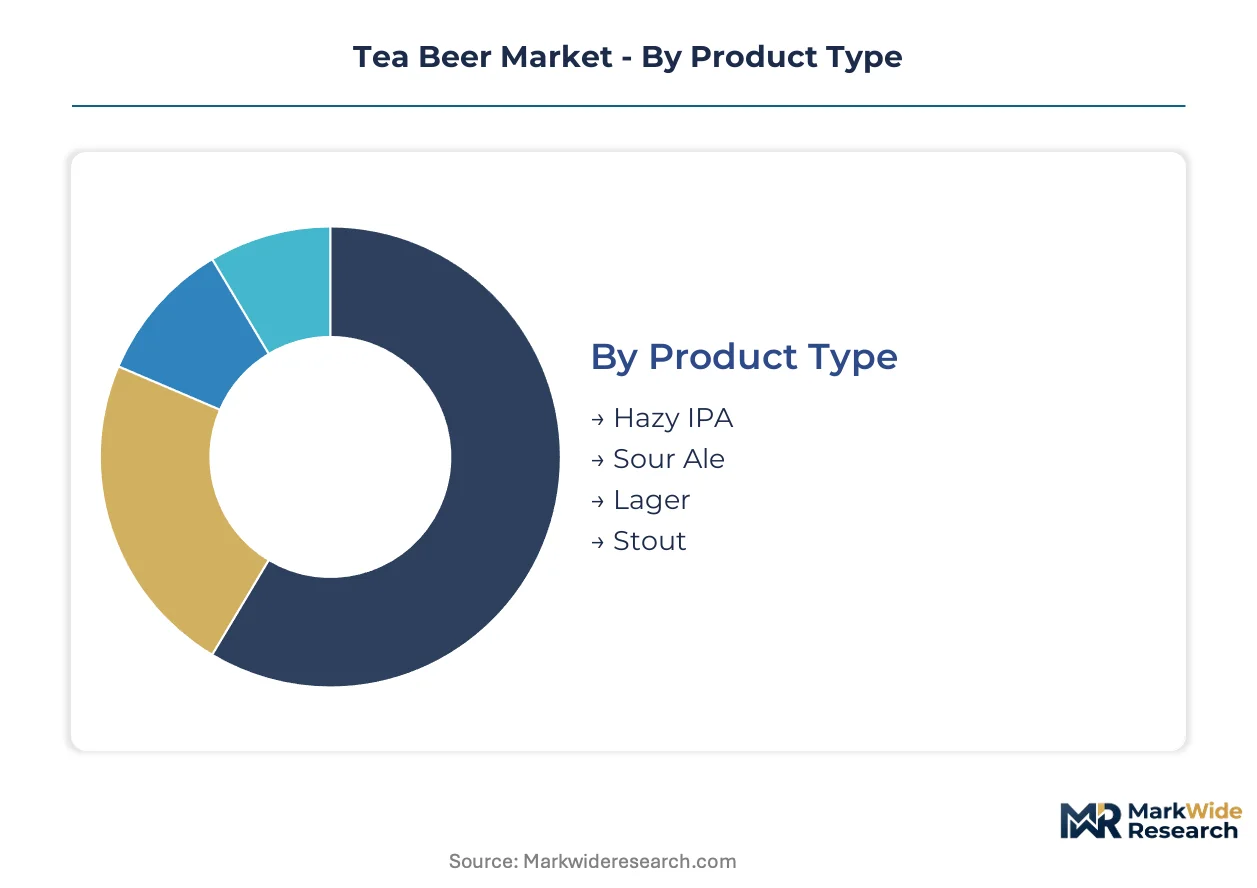
Tea beer segmentation reveals how brewing technique, botanical sourcing, and alcohol positioning create distinct competitive arenas. Each category fragments demand across craft enthusiasts, wellness-oriented consumers, and experimental drinkers with divergent willingness-to-pay thresholds.
Product Type:
Buyers differentiate primarily by tolerance for acidity, opacity, and fermentation complexity rather than price alone.
- Hazy IPA:Turbid malt body carries suspended hop oils and tea tannins in suspension. Brooklyn and Portland taprooms rotate these heavily for their aromatic intensity and Instagram visual appeal.
- Sour Ale:Lactobacillus fermentation layered with tea extracts creates sharp, refreshing profiles. Colorado breweries exploit this format for summer seasonal releases that command premium pricing.
- Lager:Clean fermentation allows subtle tea aromatics to surface without competing with yeast character.
- Stout:Roasted malt backbone supports darker tea varieties; limited seasonal traction outside winter months.
Hazy IPA leads volumes today; Sour Ale is gaining share fastest.
Tea Type:
Procurement sophistication and origin traceability separate mass-market from craft-positioned offerings.
- Black Tea:Assam and Ceylon leaf varieties provide tannic structure that stabilizes during secondary fermentation. Volume concentrates in national craft brands seeking consistent year-round production.
- Oolong Tea:Fujian and Taiwanese sourcing commands scarcity-based pricing. Denver specialty retailers allocate prime shelf space to limited-batch Oolong releases from established craft breweries.
- Green Tea:Japanese sencha and Chinese gunpowder varieties dominate wellness-positioned SKUs.
- Herbal Tea:Rooibos, chamomile, and hibiscus enable non-caffeinated line extensions for evening consumption occasions.
Black Tea anchors current production; Oolong Tea climbs the fastest among premium-positioned brewers.
Alcohol Content:
Distribution channel access and consumption occasion targeting hinge on ABV classification thresholds.
- Non-Alcoholic:Sub-0.5% ABV formats require vacuum distillation or arrested fermentation. Brooklyn breweries are pioneering this white space for wellness-focused urban professionals.
- Low Alcohol:2-4% ABV session formats align with Portland's daytime drinking culture and extended on-premise consumption.
- Moderate Alcohol:4-6% ABV represents the volume core for grocery and convenience distribution.
- High Alcohol:Imperial strengths above 8% ABV concentrate in specialty bottle shops and direct-to-consumer channels.
Moderate Alcohol dominates shipment volumes; Non-Alcoholic shows steepest expansion trajectory.
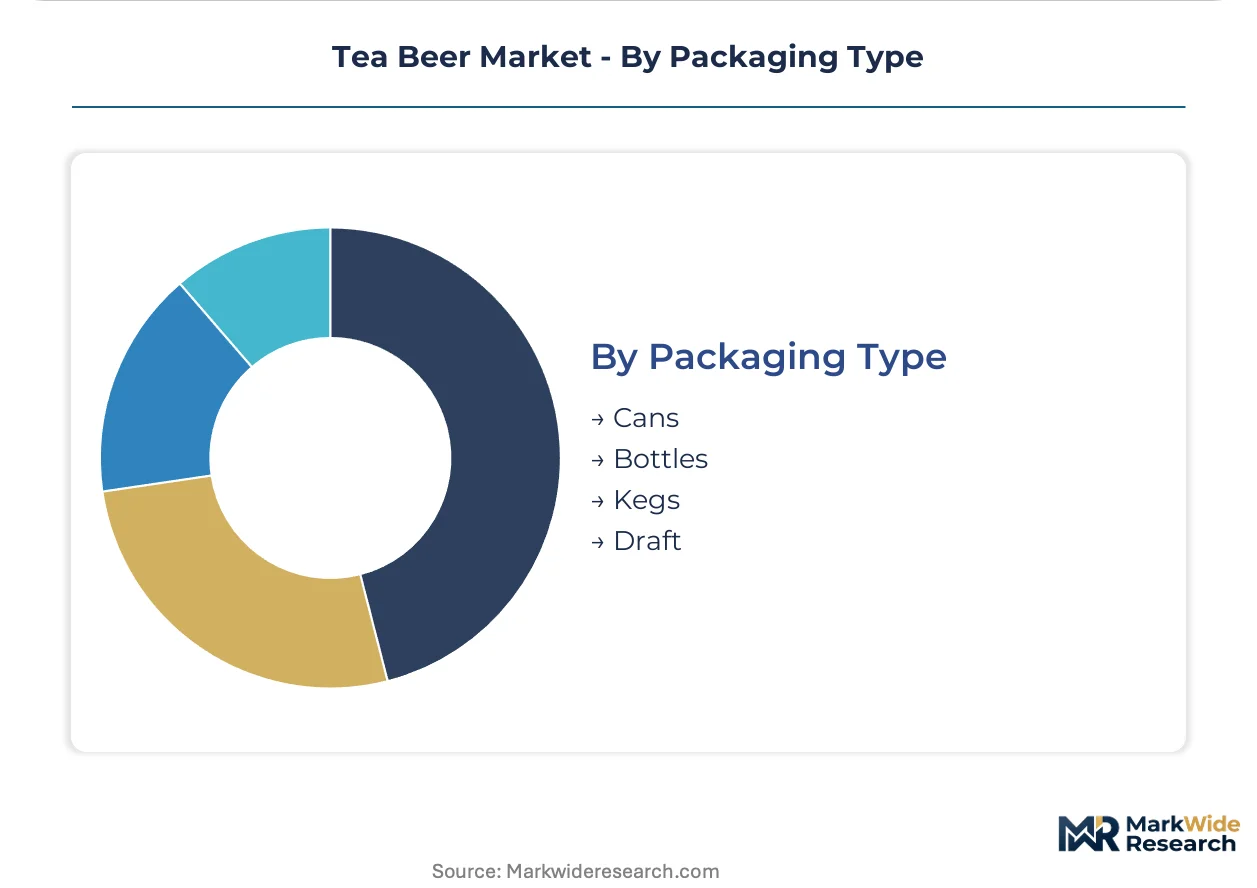
Packaging Type:
Margin structure and brand positioning separate formats with radically different capital intensity requirements.
- Cans:Aluminum sourcing from domestic smelters enables lightweight, light-protected distribution. Portland and Denver breweries favor cans for outdoor recreation associations and retail portability.
- Draft:Keg-based on-premise sales capture highest margins per ounce served. Brooklyn taprooms build brand identity through rotating draft-exclusive releases.
- Bottles:Amber and clear glass options persist for premium gifting and cellar-aging programs.
- Kegs:Stainless steel sixth-barrel and half-barrel formats dominate hospitality wholesale.
Cans lead production volumes; Draft is expanding most quickly in urban craft corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Master brewers and tea sommeliers cluster in urban craft corridors where experimental fermentation traditions intersect with specialty beverage retail density.
United States
The TTB mandates dual-track compliance for tea-beer hybrids, requiring separate formula approval and ingredient disclosure that extends launch timelines. Portland, Denver, and Brooklyn anchor production gravity through concentrated taproom cultures and specialty distributor networks. Cold-steeping innovation accelerates in Colorado facilities seeking flavor consistency at commercial scale.
Germany
Bavarian brewing heritage combines with wellness-oriented consumption shifts driving sub-0.5% ABV experimentation. The BfR evaluates novel food ingredients in fermented beverages under EU Novel Food Regulation frameworks. Berlin craft breweries exploit loopholes in the Reinheitsgebot tradition to introduce tea-adjunct lagers for export markets.
United Kingdom
Session-strength preferences below 4% ABV align with pub culture evolution and daytime drinking normalization. HMRC alcohol duty structures incentivize lower-ABV innovation through reduced tax bands. London microbreweries partner with specialty tea importers from Fujian to secure Oolong supply chains for limited releases.
Australia
Climate-adaptive brewing techniques address tannin oxidation challenges in temperature-variable distribution environments. FSANZ governs additive permissions and labeling for cross-category beverages with botanical ingredients. Melbourne and Sydney craft clusters pioneer hoppy-tea convergence formats for summer seasonal programs.
Japan
Precision fermentation expertise from sake production transfers to tea-extraction protocols for aromatic preservation. The National Tax Agency regulates happoshu-style hybrids with specific malt-content thresholds affecting formulation. Tokyo specialty retailers curate premium Oolong tea beers through direct-import relationships with Taiwanese producers.
Tea Beer Market Competitive Landscape
Top-tier vendors anchor national distribution density, while regional craft specialists occupy experimental niches through rotating taproom releases. The vendor base stratifies across three tiers: multinational brewers with production scale, established craft breweries with wholesaler relationships, and microbreweries with direct-to-consumer channels. Two strategic archetypes dominate—experimental innovators leveraging brewing pedigree for shelf space, and scale operators undercutting craft pricing through volume efficiency. Competitive moves concentrate on portfolio diversification into non-alcoholic white space and geographic expansion through state-level permitting navigation.
Within the experimental craft tier, Dogfish Head Craft Brewery Inc. and Breakside Brewery exemplify brewing pedigree translated into specialty channel positioning. The Boston Beer Company occupies a position bridging craft authenticity with national distribution infrastructure. Anheuser-Busch Companies LLC anchors the volume-driven segment where production scale enables price positioning below craft competitors.
| Leading Market Players |
|---|
| Breakside Brewery |
| Dangerous Man Brewing Co. |
| Dogfish Head Craft Brewery Inc. |
| I and I Brewing |
| Lakefront Brewery, Inc. |
| The Boston Beer Company |
| Pabst |
| Twisted Tea |
| Anheuser-Busch Companies LLC |
| Others |
Value Network & Pricing Analysis
The premium-craft-to-mass-FMB divergence separates tea beer pricing into two sourcing ecosystems with radically different margin structures and procurement strategies. Craft-positioned Oolong formulations draw from Fujian and Taiwanese terroir-specific estates with scarcity-based pricing power, while volume-tier Black Tea variants anchor Assam commodity contracts that compress margins through production-scale efficiency.
Pricing Analysis
The bundled-ingredient-plus-approval-service split distinguishes craft tea beer economics from mass-market alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects tea-origin traceability, TTB formula complexity, and cold-chain fulfillment guarantees. Pricing pressure stems from climate-driven harvest inconsistency in Fujian that elevates Oolong leaf costs. Wellness-oriented urban professionals show lowest price sensitivity for limited-batch releases, while grocery-channel shoppers in secondary markets resist premiums above mass-FMB benchmarks.
Supply Chain Analysis
Domestic-content mandates in Oregon and Colorado alcohol control frameworks are reshaping sourcing toward regional malt suppliers and Pacific Northwest hop growers. Tea leaf procurement draws from China, India, and Taiwan with Fujian Oolong commanding longest lead times. Stainless steel keg and aluminum can dependencies rest on domestic smelter capacity with tariff exposure on Chinese aluminum. Distribution runs through three-tier wholesaler networks with direct-to-consumer subscription channels bypassing traditional markup structures for limited releases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tea beer operates as a regulatory compounder where TTB's 2023 ingredient disclosure guidance accelerated transparency investments that now differentiate craft channel positioning. This regulatory milestone elevated compliance capability from cost center to competitive moat.
For Market Incumbents: To counter margin compression from climate-volatile Oolong sourcing, secure backward integration into Fujian estate partnerships with exclusive harvest allocations. Add cold-chain capacity in Denver and Portland distribution hubs to preserve aromatic integrity and justify premium positioning against mass-market entrants.
For New Entrants and Emerging Players: Wellness-focused urban professionals seeking sub-0.5% ABV alternatives represent the most penetrable buyer archetype with unmet demand in Brooklyn and Portland craft corridors. Target direct-to-consumer subscription models for first-mover positioning, leveraging dealcoholization partnerships with existing brewing facilities to bypass capital-intensive fermentation infrastructure.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-size craft breweries lack in-house tea chemistry competency and rely on external consultants for recipe development. Long-term viability favors targets with established TTB formula approval track records and captive Oolong supply relationships. Watch FDA health-claim enforcement intensity as inflection indicator for wellness-positioned SKU expansion viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Steeping Process Patent Filing | Secures aromatic preservation IP that TTB disclosure requirements make defensible against replication. |
| Oolong Estate Exclusive Supply Agreement | Captures Fujian and Taiwanese terroir scarcity that commands premium shelf space in Denver specialty retail. |
| Non-Alcoholic Line Extension Launch | Addresses Brooklyn wellness demand with vacuum distillation capabilities that differentiate from arrested fermentation alternatives. |
| Direct-to-Consumer Subscription Platform | Bypasses three-tier distribution constraints and captures full margin on limited-batch releases in Portland urban clusters. |
| Multi-State Permitting Compliance Automation | Reduces California, Colorado, and Oregon licensing friction that currently extends launch cycles for regional brewers. |
Research Methodology
Direct dialogue with master brewers, tea procurement specialists, TTB regulatory consultants, and specialty distributor category managers grounded qualitative findings in operational reality. Secondary validation drew from TTB formula approval databases, FDA health-claim enforcement records, state alcohol control board permitting disclosures, and customs import data for specialty tea leaf shipments. Bottom-up volume estimates from brewery production capacities triangulated against top-down addressable market calculations derived from craft beer consumption patterns and tea-adjunct penetration assumptions.
Bottom-up modeling aggregated individual brewery capacities, SKU-level velocity data from Portland and Brooklyn specialty retailers, and taproom rotation frequencies across Denver craft corridors. Top-down analysis applied tea-adjunct adoption rates to regional craft beer consumption baselines, segmented by product type, tea variety, alcohol content tier, and packaging format. CAGRs were derived from regression analysis of historical volume trajectories and regulatory milestone impacts on launch cadence. Forecast inputs incorporated climate projection models for Fujian and Assam harvest yields alongside TTB staffing capacity assumptions for formula review timelines.
Underlying measurement precision varies by segment; Hazy IPA and Sour Ale product types carry tighter precision than emerging non-alcoholic formats with limited historical data. Forecasts reflect assumptions regarding regulatory clarity evolution, climate adaptation in tea cultivation, and urban craft corridor consumption stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Global Malted Barley Market
Alcoholic Beverages
Bioalcohols Market
Alcoholic Beverages
CBD Wine Market
Alcoholic Beverages
Global Premium Gin Market
Alcoholic Beverages
Automated Brewing System Market
Alcoholic Beverages
Europe Craft Beer Market
Alcoholic Beverages
US Alcohol E-Commerce Market
Alcoholic Beverages
Middle East and Africa Kegs Market
Alcoholic Beverages
Wine Bottle Sterilizer Market
Alcoholic Beverages
North America Spirits Market
Alcoholic Beverages
Hookah Charcoal Market
Alcoholic Beverages
High-End Baijiu Market
Alcoholic Beverages
Italy Alcohol E-Commerce Market
Alcoholic Beverages
Brewing Supplies Market
Alcoholic Beverages
Citrus Alcohol Market
Alcoholic Beverages
Premium Wine Cooler Market