
 United States Adhesives Market | 2026-2036
United States Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
United States Adhesives Market Analytics
Texas is fragmenting adhesive supply chains as new petrochemical-adjacent production capacity draws formulators away from traditional Midwest hubs. H.B. Fuller Company anchors its position through backward integration into polymer resin operations. Dow competes on manufacturing scale across hot-melt and water-based platforms. Henkel AG & Co. KGaA differentiates via R&D intensity in electronics-grade formulations.
Adhesives are non-metallic substances applied to substrate surfaces that develop structural or semi-structural bonds through mechanical interlocking, chemical reaction, or physical curing, typically formulated from synthetic polymers, tackifiers, and curing agents with viscosities ranging from thin liquids to pastes exceeding one million centipoise. Their primary industrial purpose is to replace mechanical fasteners in assemblies where weight reduction, stress distribution, or sealing against environmental exposure matters. Water-based technology leads volume shipments but carries thinner margins due to commodity competition, while UV-curable systems represent the fastest-expanding margin pool as electronics and medical device assemblers demand precision curing with minimal thermal exposure. Epoxy formulations dominate aerospace and wind energy structural bonding where lap-shear strength requirements exceed two thousand psi.
EPA VOC emission standards, OSHA workplace exposure limits, and FDA indirect food contact regulations collectively shape permissible solvent content, hazard communication requirements, and packaging adhesive migration thresholds. The EPA National Emission Standards for Hazardous Air Pollutants have forced solvent-based product lines toward reformulation or facility emission control investments. Stakeholders must monitor state-level PFAS restriction proposals in California and Maine that threaten fluorinated adhesion promoters.
Market Dynamics
Water-based adhesive technology is displacing solvent formulations across the United States as EPA VOC enforcement tightens and automotive OEMs in Michigan and Ohio specify low-emission bonding systems for electric vehicle battery assembly.
Growth Catalysts
- Electric Vehicle Battery Assembly:Automotive OEMs in Michigan and Ohio are expanding bonding material procurement for battery pack structural bonding and thermal management module attachment.
- EPA National Emission Standards for Hazardous Air Pollutants:These standards are forcing solvent-based product lines toward reformulation, accelerating water-based and hot-melt platform adoption across packaging and construction applications.
- Southeast Manufacturing Clustering:New packaging and construction material plants near Atlanta and Charlotte are concentrating demand for industrial adhesives in the region.
Market Restraints
- Petrochemical Feedstock Volatility:Crude oil and natural gas price swings directly impact synthetic polymer resin costs, compressing formulator margins on commodity water-based products.
- Texas Production Concentration:New petrochemical-adjacent capacity in Texas is fragmenting supply chains and drawing formulators away from traditional Midwest technical service hubs.
- Fluorinated Adhesion Promoter Restrictions:State-level PFAS restriction proposals in California and Maine threaten fluorinated adhesion promoters used in high-performance electronics and medical device bonding.
Strategic Opportunities
- UV-Curable Electronics Formulations:Medical device assemblers and semiconductor packaging operations demand precision curing with minimal thermal exposure, opening premium margin pools outside commodity competition.
- Wind Energy Structural Bonding:Epoxy formulations for turbine blade assembly represent underpenetrated demand as domestic renewable energy manufacturing expands.
- Georgia and North Carolina Industrial Zones:The Southeast packaging and construction material plant clustering creates geographic white space for localized technical service and just-in-time supply models.
Industry Challenges
- Polymer Chemistry Talent Scarcity:Formulation science expertise in water-based emulsion and UV-curable resin systems remains concentrated among retiring specialists in Midwest industrial corridors.
- Legacy Equipment Retrofit Costs:Converting solvent-based coating and laminating lines to handle water-based or UV-curable chemistries requires substantial capital investment in drying and curing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Adhesives Market |
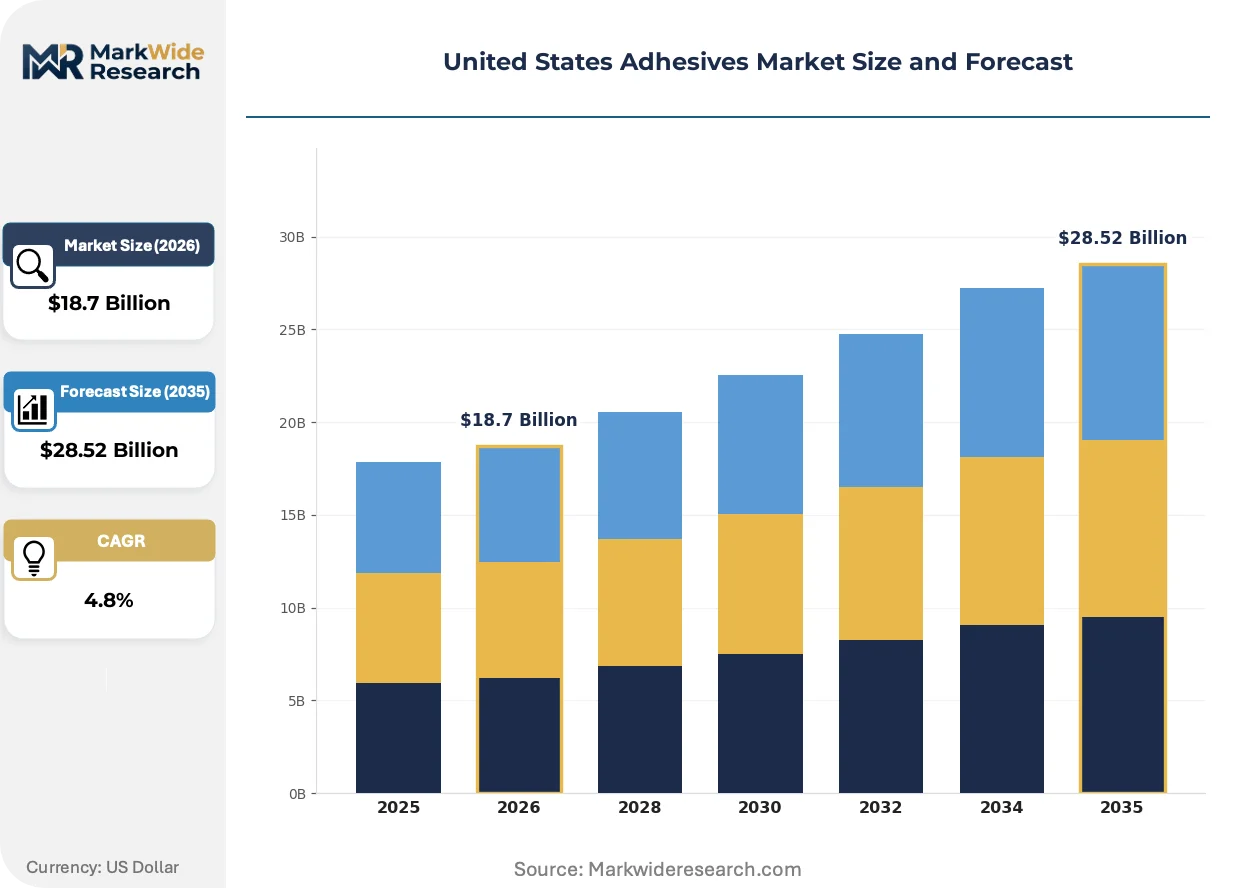
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Silicone End Use Industry: Aerospace, Automotive, Construction, Electronics Application: Packaging, Woodworking, Assembly, Automotive Repair Technology: Hot Melt, Water-Based, Solvent-Based, UV-Curable |
| Companies Covered | 3M, H.B. Fuller Company, Henkel AG & Co. KGaA, Arkema Group, Sika AG, Dow, Huntsman International LLC, Avery Dennison Corporation, Illinois Tool Works Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Adhesives Market Evolving Landscape
Formulation priorities across the United States are pivoting toward precision curing technologies and low-emission chemistries as end-use specifications tighten and regulatory enforcement intensifies.
UV-curable adhesive systems are migrating from niche electronics assembly into broader medical device and semiconductor packaging applications. Medical device manufacturers are specifying these systems for catheter and diagnostic equipment bonding where thermal damage to sensitive components must be eliminated. This migration is compressing the addressable market for conventional two-part epoxies in temperature-sensitive assembly operations.
EPA enforcement of National Emission Standards for Hazardous Air Pollutants is accelerating solvent-based product line phaseouts across industrial coating and laminating operations. Manufacturers face facility emission control investments or complete reformulation to water-based and hot-melt alternatives. The packaging segment, particularly flexible film converters in the Midwest, is absorbing the highest compliance costs and fastest technology transition timelines.
Automotive OEMs are consolidating adhesive specifications around single-supplier platform agreements for electric vehicle programs. Tier-1 suppliers must qualify through extended validation cycles covering thermal cycling, crash performance, and recyclability. This consolidation is most visible in Michigan and Ohio battery assembly operations where bonding material procurement now flows through centralized technical centers rather than distributed plant-level purchasing.
United States Adhesives Market Segmentation
Adhesive performance requirements diverge sharply across end-use specifications, with aerospace structural bonding demanding lap-shear strength above two thousand psi while packaging converters prioritize set speed and food-contact compliance. Segmentation reveals how formulation chemistry, curing technology, and application method combine to determine margin structure and competitive intensity within each slice.
Product Type:
Cost tier separates commodity formulations from engineered structural systems commanding premium pricing.
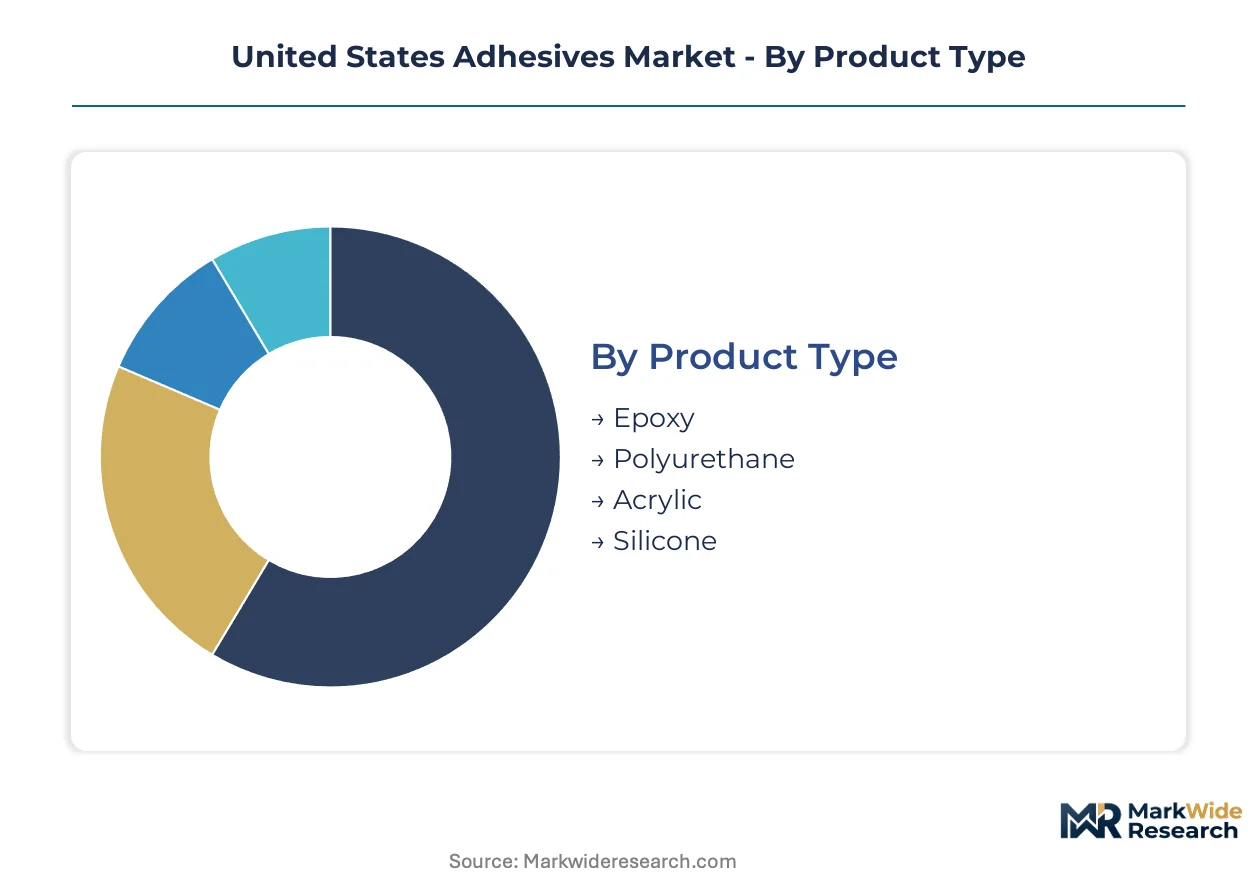
- Epoxy:Two-part thermosetting systems cure through chemical reaction to form rigid, high-strength bonds with excellent chemical resistance. Demand concentrates in aerospace manufacturing clusters and wind turbine blade assembly operations where structural integrity under cyclic loading is non-negotiable.
- Polyurethane:These systems offer flexibility and toughness across broad temperature ranges through isocyanate-hydroxyl reactions. Automotive OEMs in Michigan and Ohio specify polyurethane formulations for battery pack structural bonding and thermal management module attachment where vibration damping matters.
- Acrylic:Fast-curing systems bond diverse substrates with minimal surface preparation.
- Silicone:Elastomeric formulations maintain adhesion across extreme temperature swings.
Epoxy commands the established base in high-value structural applications. The steepest expansion runs through polyurethane as electric vehicle battery assembly scales.
End Use Industry:
Application environment dictates formulation specifications from FAA-certified aerospace systems to FDA-compliant food packaging.
- Aerospace:Bonding systems must meet FAA flame-smoke-toxicity standards and maintain structural integrity from minus 65 to 180 degrees Celsius. Boeing and Airbus tier-1 suppliers in Kansas and Washington state drive qualification cycles exceeding 24 months for primary structural adhesives.
- Automotive:Specifications now center on electric vehicle battery assembly where thermal cycling resistance and crash performance determine platform approval. OEM technical centers in Michigan and Ohio have consolidated adhesive procurement through single-supplier agreements covering structural, sealing, and thermal management applications.
- Construction:Field-applied systems face moisture, temperature, and substrate variability challenges.
- Electronics:Miniaturization and thermal sensitivity drive precision curing requirements.
Automotive commands the established base as the largest volume consumer. The steepest expansion runs through electronics as semiconductor packaging and medical device assembly demand UV-curable precision.
Application:
Volume throughput and line speed requirements separate high-speed packaging operations from precision assembly environments.
- Packaging:Hot-melt and water-based systems dominate flexible film lamination and corrugated box sealing where set speed determines line efficiency. Southeast converters near Atlanta and Charlotte are absorbing the fastest EPA compliance-driven technology transitions as solvent-based laminating lines retrofit or retire.
- Woodworking:Polyvinyl acetate emulsions and polyurethane reactive hot-melts bond panel products and furniture assemblies. Carolina and Georgia millwork operations specify low-formaldehyde systems as CARB ATCM and EPA TSCA Title VI compliance tightens.
- Assembly:Structural bonding replaces mechanical fasteners in appliances, HVAC equipment, and industrial machinery.
- Automotive Repair:Aftermarket collision shops use rapid-curing systems for panel replacement and structural reassembly.
Packaging commands the established base by sheer volume throughput. The steepest expansion runs through assembly as manufacturers lightweight products through bonded joints.
Technology:
Regulatory pressure on volatile organic compound emissions is accelerating platform substitution across industrial coating and laminating operations.
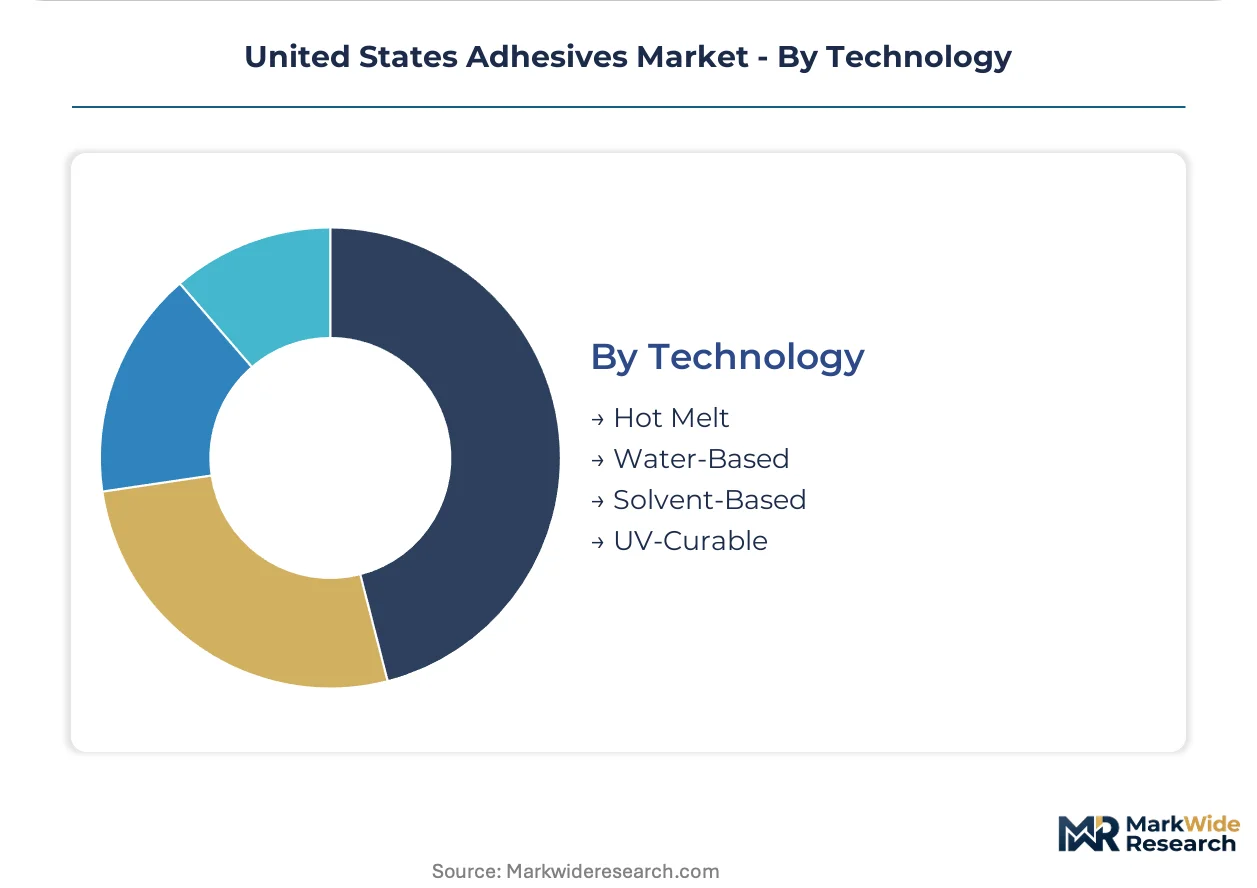
- Hot Melt:One-hundred-percent solids thermoplastic systems eliminate solvent emissions and cure through cooling rather than chemical reaction. Packaging converters favor hot-melt for high-speed case sealing and tray forming where instant handling strength supports palletization.
- Water-Based:Acrylic and polyurethane dispersions carry polymer in aqueous phase, requiring energy-intensive drying but meeting stringent EPA VOC limits. Commodity competition has compressed margins despite volume leadership across paper packaging and wood adhesive applications.
- Solvent-Based:High-performance systems face phaseout pressure under EPA National Emission Standards for Hazardous Air Pollutants.
- UV-Curable:Photoinitiator-triggered polymerization delivers instant cure with minimal thermal exposure. Electronics assemblers and medical device manufacturers specify UV systems for catheter bonding and semiconductor packaging where heat-sensitive components require precision processing.
Water-based commands the established base by shipment volume. The steepest expansion runs through UV-curable as precision electronics and medical device assembly scales fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA VOC enforcement anchors adhesive formulation priorities across the United States, with state-level PFAS restrictions adding compliance complexity in coastal jurisdictions. Regional demand concentrates where automotive electrification, packaging conversion, and construction material manufacturing cluster.
Southeast
Flexible film converters near Atlanta and Charlotte drive water-based adhesive adoption as EPA National Emission Standards for Hazardous Air Pollutants force solvent-based laminating line retrofits. Georgia and North Carolina industrial zones absorb the fastest compliance-driven technology transitions. New packaging and construction material plants cluster around these metro areas, concentrating procurement demand for hot-melt and water-based systems.
Midwest
Automotive OEM technical centers in Michigan and Ohio consolidate bonding material procurement through single-supplier platform agreements for electric vehicle battery assembly. NHTSA crash performance standards and thermal cycling requirements extend adhesive qualification cycles beyond 24 months. Detroit and Toledo battery plants specify polyurethane formulations for structural bonding and thermal management module attachment.
Texas Gulf Coast
Petrochemical-adjacent production capacity draws formulators away from traditional Midwest technical service hubs, fragmenting supply chain configurations. OSHA workplace exposure limits apply alongside EPA emission controls at integrated resin and adhesive manufacturing sites. Houston and Beaumont chemical corridors host backward-integrated operations supplying synthetic polymer feedstocks to regional formulators.
Pacific Coast
California CARB regulations and Maine PFAS restriction proposals threaten fluorinated adhesion promoters used in electronics and medical device bonding. FDA indirect food contact regulations shape packaging adhesive migration thresholds for West Coast converters. San Jose semiconductor packaging operations and San Diego medical device assemblers specify UV-curable systems for precision curing with minimal thermal exposure.
United States Adhesives Market Competitive Landscape
Backward-integrated resin producers and formulation specialists split the market into distinct capability tiers. The vendor base concentrates among multinational chemical conglomerates with captive polymer supply and mid-cap specialists with deep application expertise. Two strategic archetypes dominate: scale-driven manufacturers competing on throughput and platform breadth, and technology-intensive players differentiating through R&D investment in precision curing chemistries. Competitive moves center on backward integration into resin operations and geographic repositioning toward petrochemical feedstock access.
Among scale-driven manufacturers, Dow occupies a position exemplifying manufacturing breadth across hot-melt and water-based platforms, while H.B. Fuller Company anchors the backward-integrated archetype through in-house polymer resin operations. Henkel AG & Co. KGaA sits within the technology-intensive tier, representing R&D-focused differentiation in electronics-grade formulations. These three entities illustrate how competitive positioning stratifies across production scale, supply chain control, and formulation sophistication.
| Leading Market Players |
|---|
| 3M |
| H.B. Fuller Company |
| Henkel AG & Co. KGaA |
| Arkema Group |
| Sika AG |
| Dow |
| Huntsman International LLC |
| Avery Dennison Corporation |
| Illinois Tool Works Inc. |
| Others |
Value Network & Pricing Analysis
Petrochemical feedstock volatility determines both margin compression in commodity water-based tiers and the geographic redistribution of formulator capacity toward Texas Gulf Coast resin access. EPA VOC enforcement simultaneously widens price spreads between reformulated low-emission systems and legacy solvent-based products while accelerating supplier consolidation around backward-integrated producers with captive polymer supply.
Pricing Analysis
Midwest automotive OEMs pay premium contract rates for qualified battery assembly adhesives while Southeast packaging converters face commodity pricing pressure on high-volume water-based shipments. Three-tier pricing structure across aerospace-certified, automotive-qualified, and industrial-commodity levels reflects qualification investment and performance certification. Pricing pressure stems from crude oil derivative cost swings compressing formulator margins on standardized emulsion products. Tier-1 automotive buyers exhibit lowest price sensitivity due to 24-month qualification lock-in; flexible film converters demonstrate highest sensitivity as they absorb EPA-driven line retrofit costs.
Supply Chain Analysis
Extended payment terms from automotive OEMs in Michigan and Ohio strain working capital for non-integrated formulators competing against resin-backed rivals. Supply concentration rests on Texas petrochemical corridors for synthetic polymer feedstocks, Midwest technical service hubs for formulation expertise, and Southeast manufacturing zones for end-use demand proximity. Crude oil and natural gas price volatility, isocyanate supply tightness, and tackifier resin availability constitute critical input dependencies. Single-source vulnerability runs through Gulf Coast petrochemical infrastructure exposed to hurricane disruption. Distribution runs through direct technical service relationships with automotive OEMs and distributor networks serving packaging converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat arena where EPA qualification requirements and 24-month automotive validation cycles create switching-cost barriers that protect incumbent positions.
For Market Incumbents: Harden platform consolidation through single-supplier agreements covering electric vehicle battery structural, sealing, and thermal management applications. Deepen backward integration into polymer resin operations to offset petrochemical feedstock volatility. Expand technical service presence in Georgia and North Carolina industrial zones to capture Southeast packaging and construction demand clustering.
For New Entrants and Emerging Players: Establish a beachhead in UV-curable electronics formulations for semiconductor packaging and medical device assembly where precision curing commands premium margins outside commodity competition. Target Georgia and North Carolina geographic white space with localized just-in-time supply models. Pursue qualification partnerships with San Jose semiconductor operations and San Diego medical device assemblers as anchor customers.
For Investors and Strategic Acquirers: The market sits at a regulatory-intensification phase that favors backward-integrated formulators with captive resin supply and established EPA compliance infrastructure. Long-term viability centers on 5-10 year positioning around water-based and UV-curable platform transitions. Acquisition target archetype: mid-cap specialists with deep polyurethane battery assembly expertise or UV-curable electronics formulation capabilities. Signal to watch: state-level PFAS restriction passage in California and Maine that would eliminate fluorinated adhesion promoter competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin Operations | H.B. Fuller anchors margin control through captive synthetic polymer supply at Texas Gulf Coast facilities. |
| UV-Curable Platform Expansion | Henkel differentiates via R&D intensity in electronics-grade formulations for semiconductor packaging. |
| Southeast Technical Service Localization | Georgia and North Carolina industrial zones create geographic white space for just-in-time supply models. |
| Automotive Single-Supplier Platform Consolidation | Michigan and Ohio OEM technical centers consolidate procurement through extended validation cycle agreements. |
| EPA Compliance-Driven Solvent Line Phaseout | Flexible film converters absorb fastest technology transitions as solvent-based laminating lines retrofit. |
Research Methodology
Initial hypotheses were tested against primary input from adhesive formulator R&D directors, automotive OEM procurement managers, packaging converter operations heads, and petrochemical resin supply specialists and refined through secondary validation. Primary fieldwork combined structured interviews with plant-level technical service personnel and Tier-1 supplier qualification engineers. Secondary sources included EPA enforcement action records, SEC 10-K filings from disclosed adhesive producers, ACC industry shipment data, and customs trade flow documentation. Bottom-up demand modeling across end-use segments was triangulated against top-down petrochemical feedstock consumption analysis.
Demand-supply balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompassed product chemistry tier, curing technology platform, end-use industry specification, and regional manufacturing cluster concentration. CAGRs were derived from elasticity-adjusted volume projections and value-per-unit trends by performance tier. Industry-specific forecast inputs incorporated electric vehicle battery assembly content-per-vehicle trajectories and EPA National Emission Standards for Hazardous Air Pollutants compliance timelines for solvent-based product phaseout.
Stress conditions across crude oil price bands, PFAS regulatory restriction scenarios, and automotive platform qualification failure rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding petrochemical feedstock availability and EPA enforcement intensity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Europe Automotive Adhesives and Sealants Market
Adhesives & Sealants
Dispersion Adhesives Market
Adhesives & Sealants
Europe EVA Adhesives Market
Adhesives & Sealants
Global Isobutyl Acrylate Market
Adhesives & Sealants
Global Adhesive Coating Market
Adhesives & Sealants
Middle-East and Africa Cyanoacrylate Adhesives Market
Adhesives & Sealants
Acetate Silicone Sealant Market
Adhesives & Sealants
EV Adhesives Market
Adhesives & Sealants
Fabric Adhesive Market
Adhesives & Sealants
UV Glue Market
Adhesives & Sealants
Global Adhesives Market
Adhesives & Sealants
Australia Sealants Market
Adhesives & Sealants
South Korea Adhesives Market
Adhesives & Sealants
South Africa Adhesives Market
Adhesives & Sealants
Active Metal Brazing (AMB) Paste Market
Adhesives & Sealants
Global Contact Adhesives Market