
 Canada Industrial Food and Beverages Filtration System Market | 2026-2036
Canada Industrial Food and Beverages Filtration System Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Industrial Food and Beverages Filtration System Market Insights
Membrane-grade filtration specification is rotating through Canadian dairy and brewing facilities as processors replace legacy cartridge systems. Alfa Laval leverages its separation technology portfolio to dominate ultrafiltration skids for cheese whey concentration. Pall Corporation sustains R&D intensity in polyethersulfone membrane chemistry, anchoring its position in beverage clarification lines.
Canada industrial food and beverages filtration systems encompass mechanical and membrane-based separation equipment engineered to remove particulates, microorganisms, and dissolved solids from process streams, with pore ratings spanning 0.1 micron microfiltration to 0.0001 micron reverse osmosis and operating pressures from 1 to 80 bar depending on technology tier. These systems serve primary industrial purposes of product sterilization, concentration, and quality standardization across liquid food manufacturing. Membrane filters command the dominant installed base in dairy protein fractionation where margin pools concentrate around spiral-wound polymeric configurations. Reverse osmosis technology leads growth velocity in brewing water treatment and juice concentration circuits, displacing thermal evaporation for energy-sensitive operations.
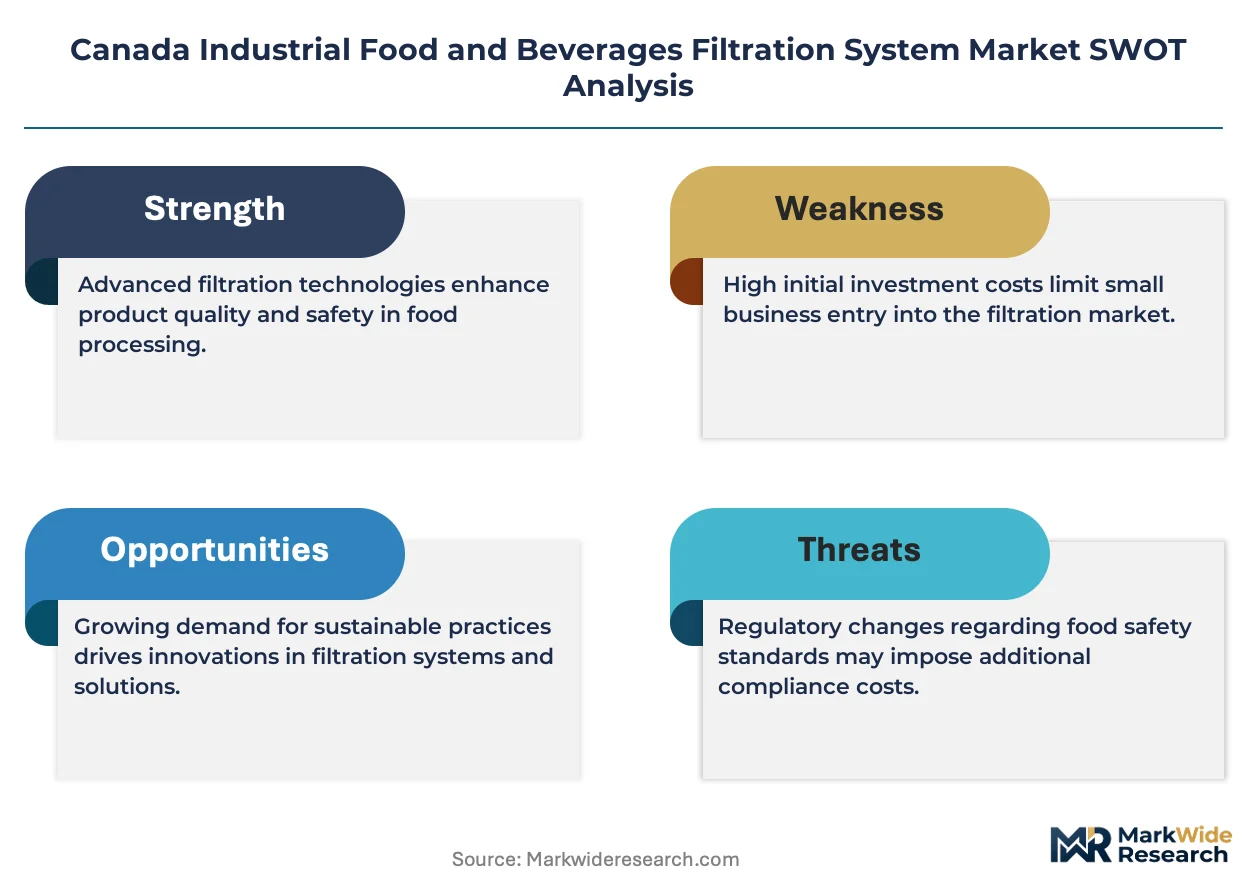
Health Canada enforces the Safe Food for Canadians Regulations through the Canadian Food Inspection Agency, mandating validated pathogen reduction steps that directly specify membrane pore size requirements for high-risk dairy and juice categories. The Canadian Standards Association and NSF International certification frameworks govern equipment material safety and cleanability protocols, shaping supplier qualification criteria for national food manufacturers. Buyers must monitor evolving CFIA guidance on allergen cross-contact prevention through dedicated filtration line configurations as enforcement priorities shift.
Market Dynamics
Membrane technology replacement cycles across Canadian dairy and brewing corridors are compressing as processors confront simultaneous pressure from Health Canada's evolving purity mandates and margin erosion from energy-intensive thermal alternatives.
Growth Catalysts
- Safe Food for Canadians Regulations:The Canadian Food Inspection Agency's pathogen reduction mandates are forcing membrane pore size upgrades in high-risk dairy categories, accelerating equipment refresh cycles in Quebec and Ontario processing clusters.
- Cheese whey fractionation:Ultrafiltration skids for protein concentration are expanding installed base as Canadian dairy cooperatives pursue value-added ingredient streams from former waste streams.
- Brewing water treatment:Reverse osmosis systems are displacing thermal evaporation in craft and mid-scale breweries across British Columbia and Alberta, driven by energy cost sensitivity and sustainability positioning.
Market Restraints
- Polymeric membrane import dependence:Spiral-wound polyethersulfone configurations rely heavily on US and European suppliers, exposing Canadian processors to currency volatility and cross-border logistics friction.
- Clean-in-place chemical costs:Sodium hydroxide and nitric acid cleaning protocols for membrane regeneration have seen input cost volatility, compressing operating margins for high-frequency cycling operations.
- Skilled technician scarcity:Membrane system optimization and fouling diagnosis require specialized expertise concentrated in Montreal and Toronto, leaving Prairie and Atlantic facilities underserved.
Strategic Opportunities
- Atlantic Canada seafood processing:Underpenetrated membrane bioreactor applications in fish protein recovery and process water reuse present white space as Nova Scotia and New Brunswick facilities modernize.
- Plant-based beverage expansion:Oat, pea, and almond milk filtration infrastructure is creating demand for ceramic microfiltration systems that handle higher solids loading than traditional dairy membranes.
- Canadian Standards Association certification harmonization:Emerging alignment between CSA and NSF International protocols is reducing duplicate testing burdens for equipment suppliers, accelerating time-to-market for novel membrane chemistries.
Industry Challenges
- Legacy cartridge system integration:Retrofitting membrane skids into 1980s-era dairy plants requires custom piping and control system adaptation, extending commissioning timelines and inflating project contingency budgets.
- CFIA validation documentation:Pathogen reduction step verification for novel membrane configurations demands extensive laboratory challenge studies, creating regulatory approval bottlenecks for innovative suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Industrial Food and Beverages Filtration System Market |
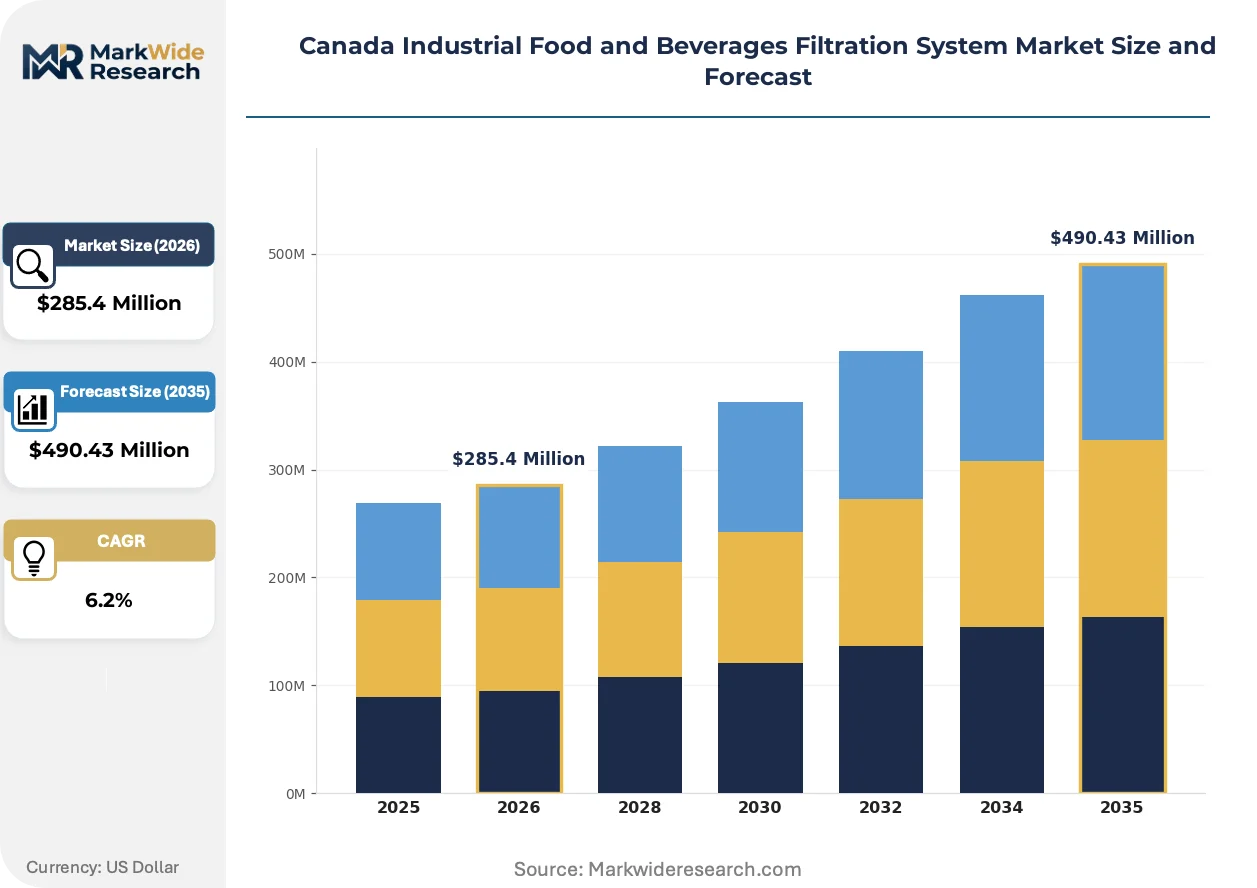
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $490.43 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane Filters, Cartridge Filters, Depth Filters, Gravity Filters Technology: Microfiltration, Ultrafiltration, Nanofiltration, Reverse Osmosis Application: Beverage Production, Dairy Processing, Juice Filtration, Brewing End User: Food Manufacturers, Beverage Companies, Dairy Plants, Distilleries |
| Companies Covered | Alfa Laval, Parker Hannifin, Eaton Corporation, Donaldson Company, Inc., GEA Group, Pall Corporation, 3M, Freudenberg Filtration Technologies, MANN+HUMMEL, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Industrial Food and Beverages Filtration System Market Trends and Innovations
Ceramic membrane technology is penetrating Canadian food filtration as processors seek durability advantages over polymeric alternatives in high-temperature, aggressive-cleaning environments. Three developments are restructuring competitive positioning.
Ceramic alumina and silicon carbide membranes are fragmenting the dairy ultrafiltration segment previously dominated by spiral-wound polymers. Alberta beef and pork processors are piloting these systems for fat and protein recovery from wastewater streams, attracted by chemical resistance and extended service intervals. The technology is compressing total cost of ownership calculations for operations running 20-plus daily cleaning cycles.
Health Canada's Safe Food for Canadians Regulations are tightening allergen cross-contact prevention protocols, mandating dedicated filtration line configurations or validated cleaning verification between allergen and non-allergen runs. Dairy processors in Ontario are responding by segregating membrane skids for nut-flavored versus conventional product streams, inflating capital requirements but reducing recall liability exposure.
Service unbundling is altering procurement patterns as Canadian food manufacturers separate membrane element supply from skid fabrication and aftermarket technical support. Large dairy cooperatives are negotiating direct contracts with membrane chemistry specialists while sourcing stainless steel fabrication from domestic metalworkers, fragmenting the traditional integrated supplier relationship and pressuring margin pools at equipment OEMs.
Canada Industrial Food and Beverages Filtration System Market Segmentation
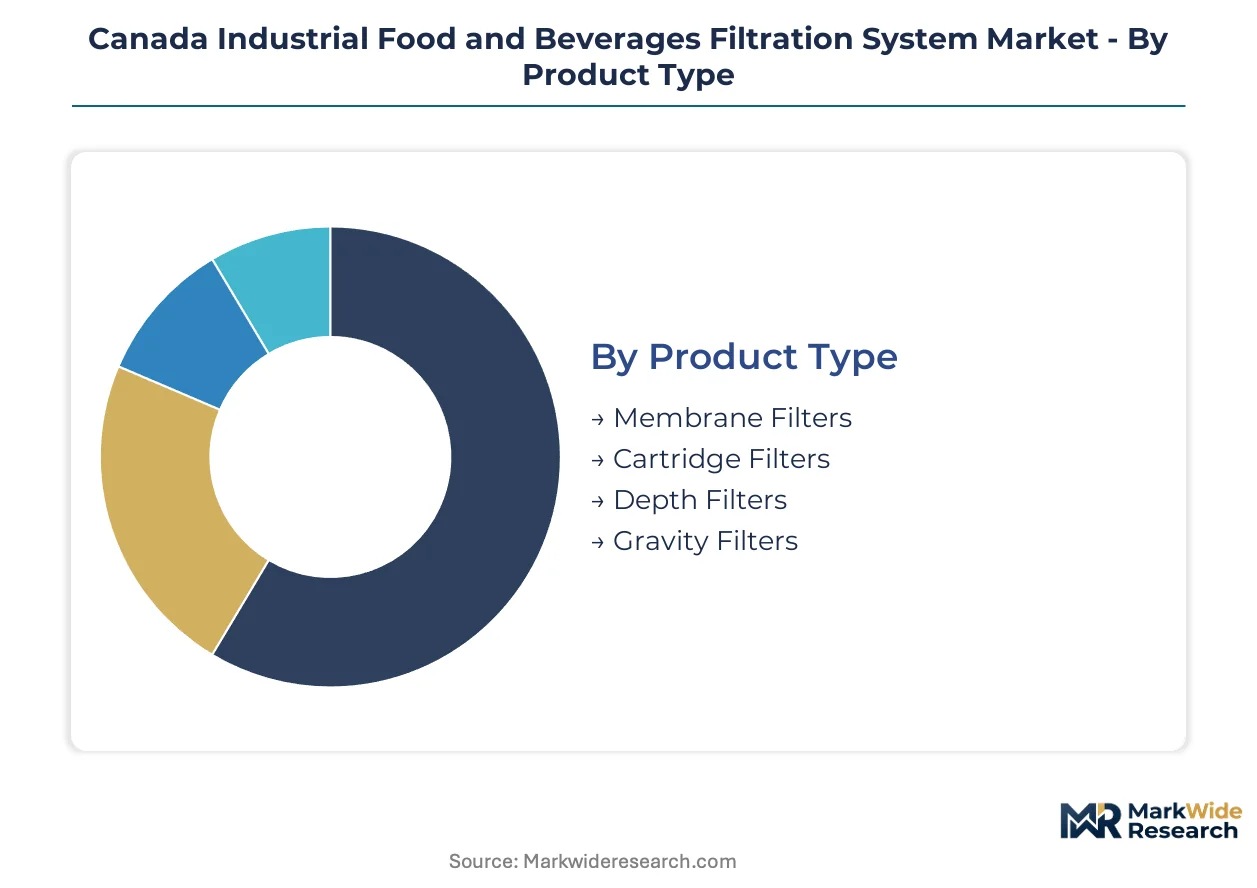
Technology-product pairings in Canadian food filtration are fragmenting as membrane chemistry advances outpace legacy equipment refresh cycles. Application-specific specifications now dominate procurement decisions, with Health Canada's pathogen mandates forcing tighter alignment between segment selection and regulatory risk exposure.
Product Type:
Margin pools concentrate in membrane configurations where polyethersulfone chemistry commands premium pricing against commoditized cartridge alternatives.
- Membrane Filters:Spiral-wound and hollow-fiber configurations dominate dairy protein fractionation in Quebec and Ontario. Polyethersulfone and polysulfone chemistries anchor ultrafiltration skids for cheese whey concentration, with Health Canada pore-size mandates accelerating replacement of legacy systems in Montreal-Toronto processing corridors.
- Cartridge Filters:Pleated polypropylene and cellulose acetate constructions retain installed base in pre-filtration and guard-filter roles. British Columbia craft breweries deploy these for cost-sensitive water polishing, though membrane displacement is compressing growth trajectories in beverage clarification lines.
- Depth Filters:Graded-density cellulose and diatomaceous earth matrices handle high-solids loading in juice and brewing applications. Alberta facilities utilize these for primary clarification before membrane finishing steps.
- Gravity Filters:Simple sand and multimedia beds persist in rural Atlantic Canada plants with limited technical staffing and low throughput requirements.
Membrane filters hold installed capacity in high-value dairy corridors. Cartridge filters are rotating up the share rankings in craft beverage water treatment.
Technology:
Operating pressure tiers separate capital-intensive reverse osmosis installations from lower-barrier microfiltration deployments across provincial processing clusters.
- Microfiltration:0.1-10 micron ceramic and polymeric membranes sterilize beer and wine without heat damage. Ontario craft breweries favor ceramic configurations for chemical resistance during aggressive clean-in-place protocols mandated by CFIA allergen prevention guidance.
- Ultrafiltration:0.001-0.1 micron spiral-wound systems concentrate whey proteins and fractionate milk components. Quebec dairy cooperatives anchor demand as value-added ingredient streams replace former waste disposal costs.
- Nanofiltration:Selective ion rejection softens brewing water and concentrates juice sugars at lower energy intensity than thermal evaporation. British Columbia fruit processors pilot these for organic acid preservation.
- Reverse Osmosis:0.0001 micron desalination and concentration technology displaces evaporators in water-scarce Prairie provinces. Alberta and Saskatchewan brewing facilities prioritize these for energy cost containment.
Ultrafiltration dominates protein recovery value streams. Reverse osmosis is climbing the fastest as thermal displacement accelerates in water-stressed regions.
Application:
Regulatory scrutiny intensity varies sharply across categories, with dairy and juice facing explicit CFIA pathogen reduction step validation.
- Beverage Production:Carbonated soft drink and bottled water filtration emphasizes taste consistency and particulate removal. Toronto-area contract packers drive standardization demand across multi-brand filling lines.
- Dairy Processing:Fluid milk, cheese, and whey operations face the strictest membrane pore-size mandates under Safe Food for Canadians Regulations. Montreal and Toronto corridors concentrate upgrade spending as legacy plants confront simultaneous regulatory and margin pressures.
- Juice Filtration:Enzymatic clarification and microbial stabilization requirements vary by fruit matrix. Quebec apple and Ontario grape processors deploy differing membrane configurations for tannin and pectin handling.
- Brewing:Water treatment and beer stabilization span microfiltration through reverse osmosis tiers. British Columbia and Alberta craft segments prioritize sustainability positioning through energy-efficient membrane alternatives.
Dairy processing holds installed capacity. Brewing is rotating up the share rankings as craft segment expansion outpaces mature category growth.
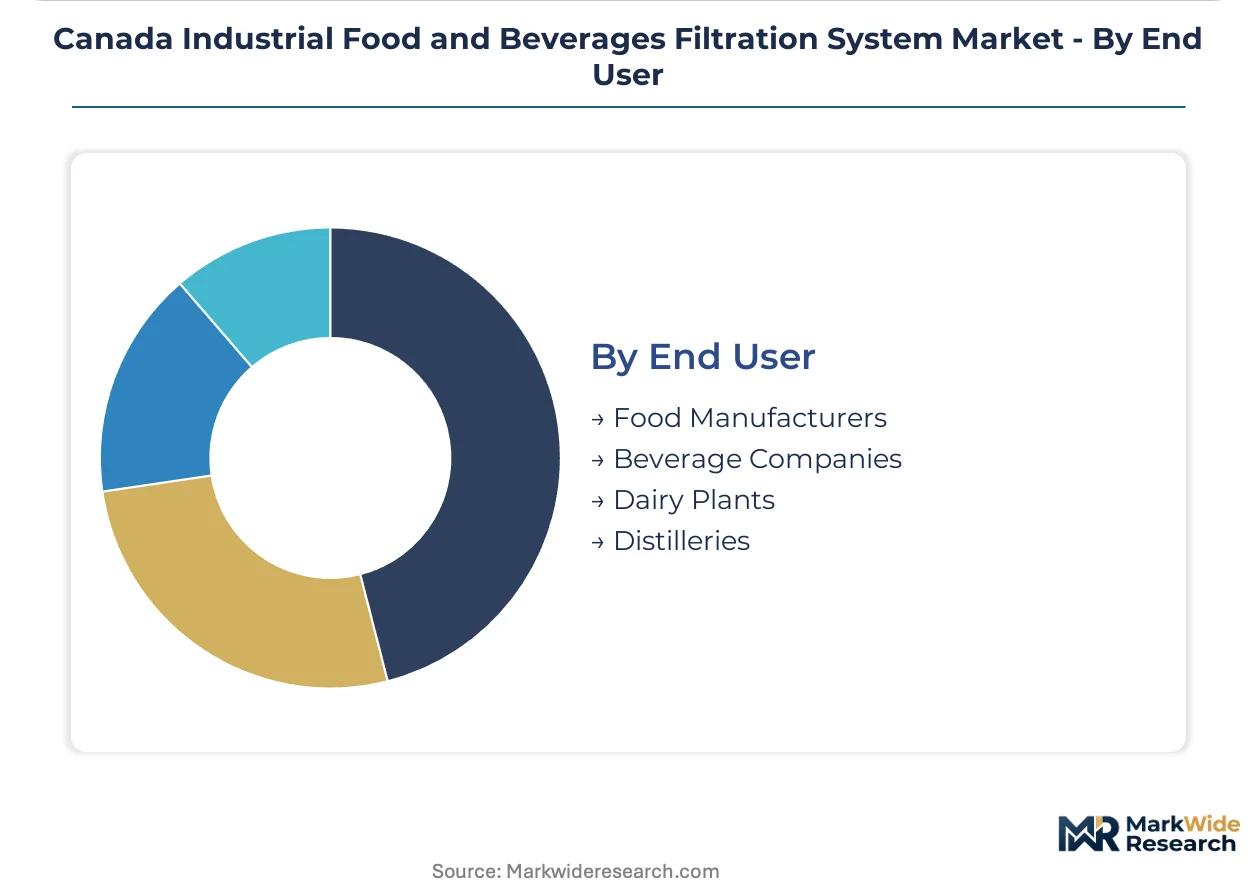
End User:
Procurement sophistication tiers separate national dairy cooperatives from regional beverage contract manufacturers.
- Food Manufacturers:Diverse sauce, soup, and ingredient processors deploy filtration for viscosity control and spoilage organism reduction. Ontario and Quebec facilities dominate capital deployment.
- Beverage Companies:Multi-brand portfolios require flexible filtration infrastructure accommodating frequent changeovers. CFIA allergen segregation mandates are inflating capital requirements for nut-flavored versus conventional product lines.
- Dairy Plants:Cooperatives and integrated processors command the deepest membrane expertise and longest replacement cycles. Whey fractionation investments concentrate in Quebec and Ontario.
- Distilleries:Ethanol and spirits producers utilize filtration for polishing and barrel sediment removal. Smaller installed base limits segment scale relative to brewing counterparts.
Dairy plants hold installed capacity. Beverage companies are rotating up the share rankings as plant-based milk expansion diversifies filtration requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Ontario and Quebec demonstrate low price elasticity as regulatory mandates override cost concerns, while Prairie and Atlantic facilities exhibit higher sensitivity to capital expenditure timing.
Ontario
Toronto-area dairy cooperatives and contract beverage packers anchor membrane system procurement as Health Canada's Safe Food for Canadians Regulations tighten pathogen reduction protocols. The Canadian Food Inspection Agency enforces validated pore-size specifications for high-risk dairy categories, accelerating equipment refresh cycles. Concentrated demand spans the Golden Horseshoe processing corridor where legacy plants confront simultaneous compliance deadlines and margin compression from energy-intensive thermal alternatives.
Quebec
Montreal's cheese whey fractionation facilities drive ultrafiltration skid deployment as cooperatives pursue value-added protein ingredient streams from former waste disposal cost centers. The province's dairy processing modernization aligns with evolving CFIA guidance on allergen cross-contact prevention through dedicated filtration line configurations. Quebec's ultrafiltration concentration exceeds other provinces as margin pools concentrate around spiral-wound polymeric configurations for protein recovery operations.
Alberta
Calgary and Edmonton brewing facilities prioritize reverse osmosis water treatment systems as energy cost sensitivity displaces thermal evaporation in water-scarce Prairie operations. The province's craft and mid-scale brewery expansion creates demand for membrane alternatives with sustainability positioning. Alberta beef and pork processors pilot ceramic membrane systems for fat and protein recovery from wastewater streams, attracted by chemical resistance advantages.
British Columbia
Vancouver Island and Lower Mainland craft breweries deploy microfiltration for beer stabilization without heat damage, favoring ceramic configurations for aggressive clean-in-place protocol compliance. The province's fruit processors pilot nanofiltration for organic acid preservation in juice concentration circuits. British Columbia's beverage filtration demand concentrates in sustainability-focused operations seeking energy-efficient membrane alternatives to thermal processing.
Atlantic Canada
Nova Scotia and New Brunswick seafood processing facilities present underpenetrated membrane bioreactor applications in fish protein recovery and process water reuse. Limited technical staffing and lower throughput requirements sustain gravity filter persistence in rural operations. The region's modernization cycles lag Ontario-Quebec corridors, creating white space for ceramic membrane penetration as facilities confront effluent discharge regulations.
Canada Industrial Food and Beverages Filtration System Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Canadian filtration equipment landscape. The market structure consolidates around integrated separation technology specialists and diversified industrial conglomerates with filtration divisions. Three archetypes dominate: membrane chemistry specialists controlling polyethersulfone and ceramic formulations, stainless steel skid fabricators with domestic metalworking capabilities, and full-system integrators bundling elements, housings, and aftermarket services. Competitive moves concentrate on strategic partnerships between chemistry specialists and regional fabricators, plus portfolio diversification into plant-based beverage filtration configurations.
Among European-based separation technology groups, Alfa Laval and GEA Group exemplify the integrated system archetype spanning membrane chemistry through skid fabrication. Pall Corporation represents the membrane chemistry specialist tier with concentrated expertise in polymeric formulations. These three anchors sit within different competitive positions: Alfa Laval leverages ultrafiltration dominance in dairy whey concentration, GEA Group extends refrigeration-adjacent separation expertise into food processing, and Pall Corporation sustains R&D intensity in beverage clarification applications. Canadian procurement patterns increasingly unbundle these relationships as large cooperatives negotiate direct membrane supply while sourcing domestic fabrication separately.
| Leading Market Players |
|---|
| Alfa Laval |
| Parker Hannifin |
| Eaton Corporation |
| Donaldson Company, Inc. |
| GEA Group |
| Pall Corporation |
| 3M |
| Freudenberg Filtration Technologies |
| MANN+HUMMEL |
| Others |
Pricing and Supply Chain Analysis
Ninety-day membrane element lead times from European and US suppliers concentrate pricing power with polyethersulfone chemistry specialists, while Canadian dairy cooperatives absorb cost volatility through long-term service contracts that bundle replacement cycles with technical support. Health Canada's evolving pore-size mandates force buyers to prioritize specification compliance over procurement cost minimization, compressing price elasticity in Ontario and Quebec processing corridors.
Pricing Analysis
Aftermarket service revenue drives lifetime value as membrane regeneration contracts and fouling diagnosis subscriptions extend customer relationships beyond initial skid installation. Three-tier pricing structure across premium CSA-certified configurations, standard NSF International tiers, and economy cartridge alternatives stratifies the market by validation burden. Pricing pressure stems from sodium hydroxide and nitric acid chemical cost volatility in clean-in-place protocols. Prairie and Atlantic facilities exhibit highest price sensitivity due to limited technical staffing and lower throughput scale.
Supply Chain Analysis
Strategic stockpiling of spiral-wound polymeric membranes dominates procurement behavior as Canadian processors buffer against cross-border logistics friction and currency volatility. Manufacturing concentrates in Germany, the United States, and Japan for polyethersulfone formulations and ceramic alumina substrates. Raw material dependencies center on specialty polymers, precision-milled ceramic substrates, and stainless steel housings. Tariff exposure on US-origin membrane elements creates structural vulnerability. Distribution runs through regional equipment distributors with CFIA compliance expertise and direct OEM relationships with large dairy cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity intensifies as service unbundling separates membrane chemistry supply from skid fabrication, creating niche positions for domestic metalworkers and specialized technical service providers alongside integrated OEMs.
For Market Incumbents: Compound ultrafiltration dominance in Quebec dairy whey fractionation by deepening captive supply of polyethersulfone membrane formulations and securing exclusive service contracts with Montreal-Toronto cooperatives. Add ceramic membrane skids to portfolio through partnership with silicon carbide chemistry specialists, addressing Alberta beef processor pilot demand. Defend against emerging regional fabricators by controlling Health Canada validation documentation pathways. For New Entrants and Emerging Players: Differentiate on ceramic membrane durability for high-temperature seafood processing in Nova Scotia and New Brunswick, where technical service scarcity has delayed adoption. Target Atlantic Canada membrane bioreactor applications in fish protein recovery as the most penetrable white space. Pursue direct membrane element supply contracts with large cooperatives that have already unbundled from integrated OEMs, leveraging CSA certification harmonization to accelerate market entry. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because Health Canada's Safe Food for Canadians Regulations mandate validated pathogen reduction steps that embed membrane technology into dairy and juice processing infrastructure. Acquire membrane chemistry specialists with polyethersulfone or ceramic formulation expertise rather than stainless steel fabricators facing margin compression from procurement unbundling. Watch CFIA enforcement priorities on allergen cross-contact prevention as the signal for capital deployment timing in dedicated filtration line configurations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Chemistry | Captures margin pools shifting from skid fabrication to element supply as cooperatives unbundle procurement. |
| Ceramic Membrane Technology Licensing | Addresses Alberta beef processor demand for chemical-resistant fat recovery systems with extended service intervals. |
| CFIA Validation Documentation Investment | Accelerates regulatory approval for novel pore-size configurations facing laboratory challenge study bottlenecks. |
| Atlantic Canada Technical Service Expansion | Captures Nova Scotia seafood processor modernization demand currently underserved by Montreal-Toronto expertise concentration. |
| Plant-Based Beverage Filtration Partnership | Positions ceramic microfiltration systems for oat and pea milk solids loading requirements exceeding dairy membrane capacity. |
Research Methodology
A standing panel of dairy plant engineers, brewing facility maintenance directors, CFIA compliance officers, and membrane system technicians provided ongoing calibration across the study period. Primary interviews with equipment procurement managers at Quebec and Ontario cooperatives, supplemented by secondary validation from Health Canada regulatory guidance documents, Canadian Food Inspection Agency enforcement bulletins, and Canadian Standards Association certification protocols, anchored demand-side assessment. Bottom-up installation base modeling and top-down market size triangulation from trade flow data ensured consistency.
Consistency checks against membrane element import volumes and provincial dairy processing capital expenditure disclosures validated projection outputs across the analysis window. The analytical framework segmented by technology tier, application category, and end-user procurement sophistication, with CAGRs derived from replacement cycle compression rates and regulatory mandate acceleration curves. Forecast inputs incorporated Health Canada pore-size specification evolution and ceramic membrane pilot adoption trajectories in Alberta protein recovery operations.
Material uncertainties — CFIA enforcement intensity shifts, polymeric membrane import tariff adjustments, and ceramic technology cost curve movements — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory timeline adherence and cooperative capital allocation priorities. Revision becomes warranted when Health Canada pathogen reduction guidance crosses implementation thresholds that accelerate equipment refresh beyond modeled replacement cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Micro Winery Equipment Market
Food Processing Equipment
Sandwich Preparation Refrigerators Market
Food Processing Equipment
Hot Food Processing Equipment Market
Food Processing Equipment
Wine Processing Equipment Market
Food Processing Equipment
Countertop Convection Oven Market
Food Processing Equipment
Global Industrial Bakery Processing Equipment Market
Food Processing Equipment
Multiple Unit Pellet Systems Market
Food Processing Equipment
Global Starch Recovery Systems Market
Food Processing Equipment
Aseptic Processing Market
Food Processing Equipment
Global Food and Beverage Processing Equipment Market
Food Processing Equipment
Small Brewery Equipment Market
Food Processing Equipment
Food Recycling Machines Market
Food Processing Equipment
Bread Slicer Market
Food Processing Equipment
Pulp Washing Equipment Market
Food Processing Equipment
Commercial Tunnel Oven Market
Food Processing Equipment
High Speed Oven Market