
 Multiple Unit Pellet Systems Market | 2026-2036
Multiple Unit Pellet Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Multiple Unit Pellet Systems Market Foresight
Subscription-based equipment uptime contracts is recalibrating how pellet system vendors monetize installed base. Lonza Group Ltd. leverages its biologics manufacturing footprint to anchor high-value pellet production partnerships across European and North American sites. Evonik Industries AG sustains technology leadership in functional excipient-pellet combinations that enable modified-release profiles. ACG Worldwide competes on cost-engineered multi-chamber systems for emerging-market pharmaceutical manufacturers.
Multiple Unit Pellet Systems comprise discrete spherical particulates, typically 0.5–2.0 mm in diameter, produced via extrusion-spheronization or fluid-bed layering, designed for controlled-release drug delivery, taste masking, or dose flexibility in oral solid dosage forms. Multi-chamber configurations lead capital equipment bookings due to their throughput advantage in high-volume generic manufacturing, while micro pellet systems represent the fastest-growing product category as biopharma developers pursue pediatric and geriatric dose tailoring. Extrusion technology occupies the largest installed base, though coating capabilities command premium pricing because functional film layers determine release kinetics and bioequivalence outcomes.
The FDA enforces current Good Manufacturing Practice standards for multiparticulate batch uniformity, while the EMA's MDR framework tightens traceability requirements for pellet-based combination products. India's CDSCO aligns with ICH Q8-Q12 guidelines through its revised Schedule M provisions, raising compliance costs for domestic pellet equipment suppliers. Stakeholders must monitor evolving pharmacopeial standards for pellet friability and dissolution variance, as regulatory divergence between USP, EP, and IP methods threatens to fragment qualification protocols and delay market entry timelines.
Market Dynamics
Pharmaceutical contract manufacturers in Germany and India are scaling pellet-based drug delivery capacity to meet oncology and gastrointestinal therapy demand, while FDA's Quality by Design framework and EMA's process analytical technology guidelines tighten validation standards for multiparticulate dosage forms.
Growth Catalysts
- Oncology formulation demand:Controlled-release pellet systems enable precise dosing for chemotherapy regimens, driving adoption across United States and German hospital networks.
- EMA MDR framework:Traceability mandates for pellet-based combination products accelerate investment in validated manufacturing equipment across European pharmaceutical sites.
- Extrusion-spheronization advancement:Continuous processing technologies reduce batch-to-batch variability, improving yield rates for high-volume generic manufacturers.
Market Restraints
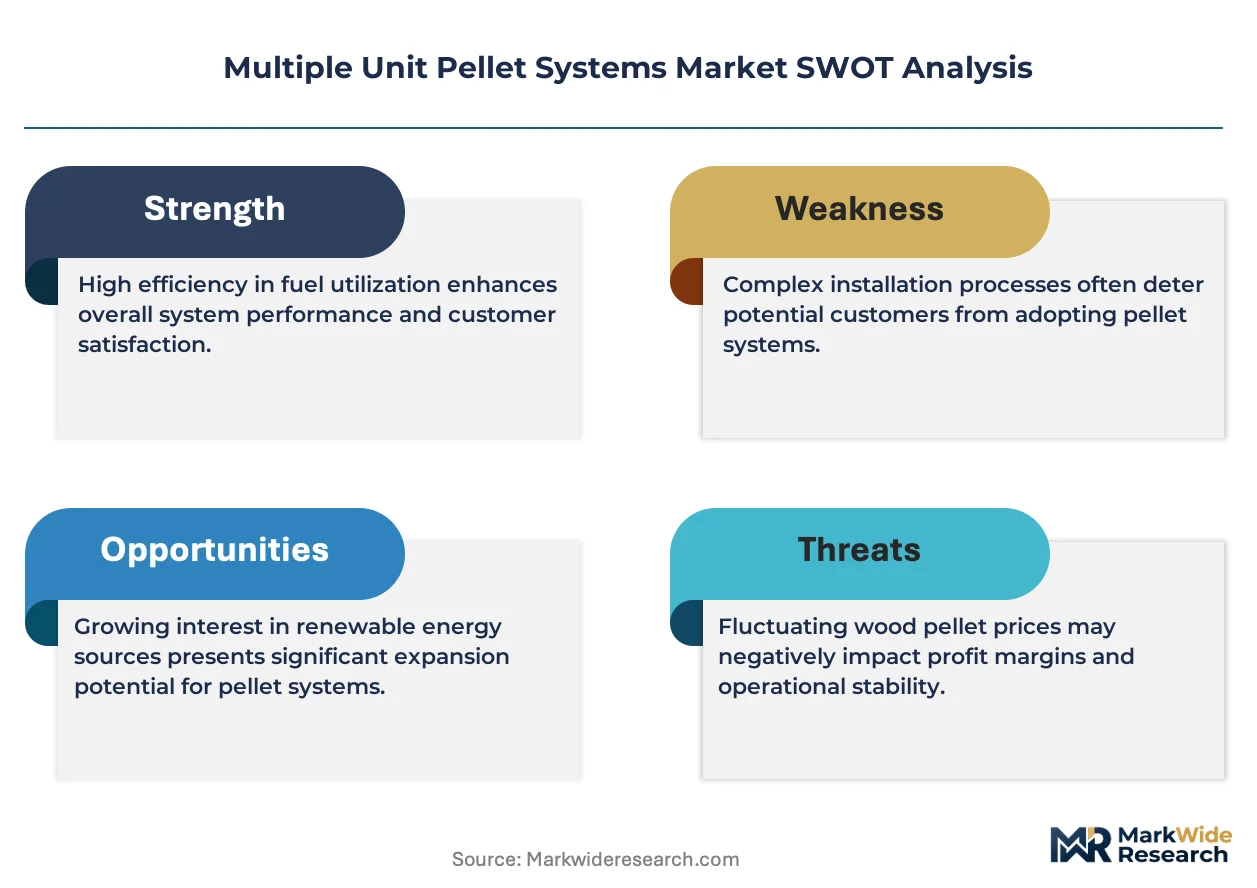
- Functional excipient cost volatility:Specialized polymers and coating materials face price instability from petrochemical feedstock fluctuations, compressing margins for mid-tier equipment suppliers.
- Validation timeline extension:FDA current Good Manufacturing Practice standards for multiparticulate batch uniformity require 18-24 month qualification periods, delaying revenue recognition for new installations.
- Fluid-bed layering substitution:Alternative granulation technologies compete for modified-release applications where coating precision is less critical.
Strategic Opportunities
- Pediatric dose tailoring:Micro pellet systems address unmet needs in weight-based dosing for pediatric oncology, creating white space in United States and German hospital pharmacy compounding.
- India PLI scheme alignment:Domestic pellet equipment suppliers leverage production-linked incentives to capture share from imported systems in emerging-market pharmaceutical manufacturing.
- Continuous manufacturing convergence:Integration of real-time release testing with pellet production lines enables pharma manufacturers to bypass traditional batch testing bottlenecks.
Industry Challenges
- Process analytical technology skill gaps:Shortage of engineers trained in PAT implementation for multiparticulate systems constrains deployment timelines for advanced coating lines.
- Dissolution method harmonization delays:Divergence between USP, EP, and IP pharmacopeial standards for pellet friability testing fragments qualification protocols and extends regulatory submission cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multiple Unit Pellet Systems Market |
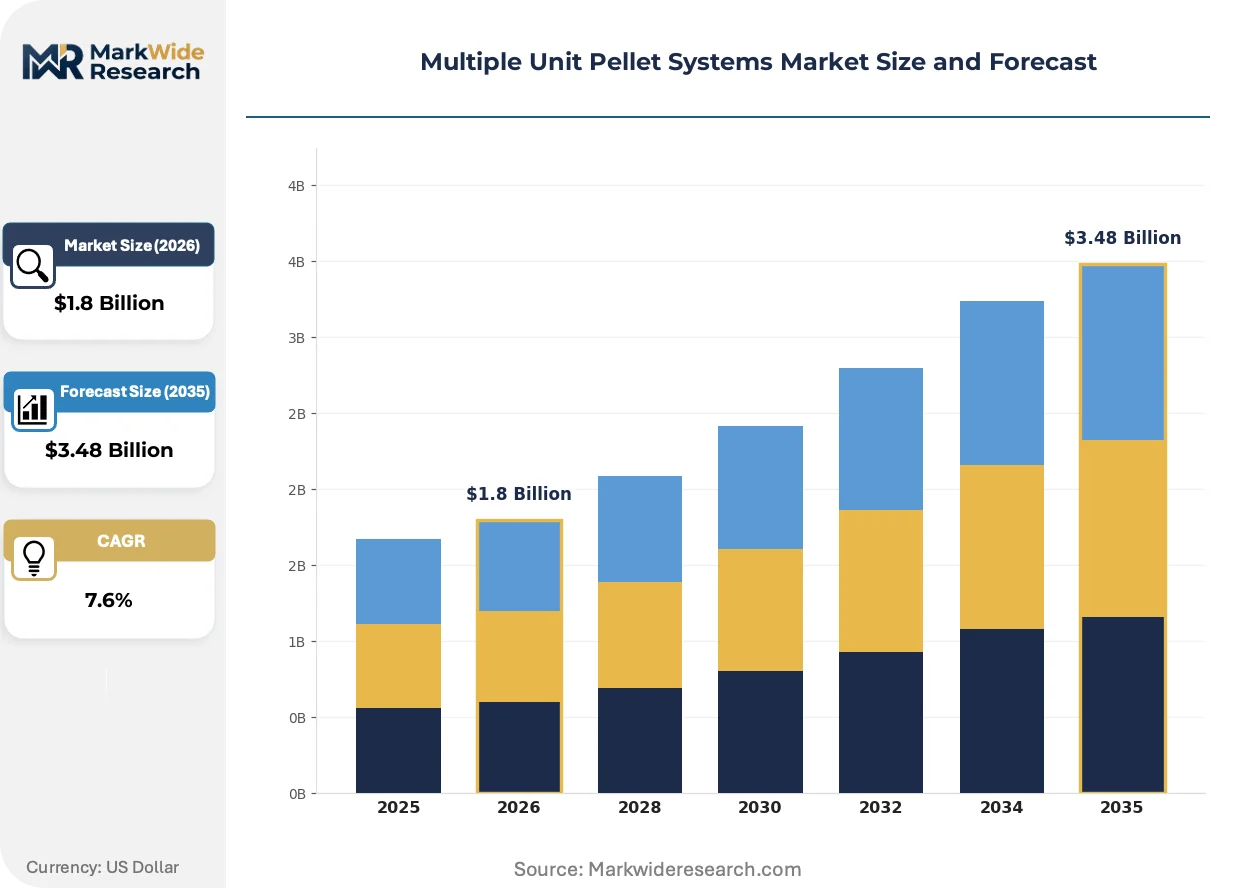
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Chamber, Multi-Chamber, Micro Pellet, Custom Systems End User: Pharmaceuticals, Nutraceuticals, Food Industry, Agriculture Application: Drug Delivery, Food Processing, Biotechnology, Animal Feed Technology: Extrusion, Spheronization, Coating, Blending |
| Companies Covered | Lonza Group Ltd., Bosch Packaging Technology, BASF SE, Johnson & Johnson, Colorcon, Inc., Evonik Industries AG, AstraZeneca, ACG Worldwide, GEA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multiple Unit Pellet Systems Market Shifts & Advancements
Equipment vendors are reconfiguring service models around uptime guarantees rather than capital sales, while coating capabilities command premium positioning as functional film layers determine bioequivalence outcomes.
Micro pellet production systems are decentralizing oncology dose personalization by enabling hospital-site compounding of patient-specific regimens. Regional cancer centers in Germany and the United States are installing compact extrusion-spheronization units to bypass centralized manufacturing delays. This capability is compressing supply chain lead times for critical chemotherapy formulations while reducing waste from expired bulk inventories.
EMA's revised process analytical technology guidelines now mandate real-time coating thickness monitoring for modified-release pellets sold in European markets. Pharmaceutical manufacturers must retrofit existing fluid-bed systems with in-line spectrometry or risk batch rejection during inspections. German equipment vendors are capturing upgrade revenue by embedding PAT sensors into legacy multi-chamber configurations.
Subscription-based equipment uptime contracts are displacing traditional capital purchase arrangements among mid-scale generic manufacturers. Indian pharmaceutical producers now favor performance-linked service agreements that bundle maintenance, consumables, and regulatory documentation support. This shift is most visible in Gujarat and Telangana manufacturing clusters, where contract manufacturers prioritize operational expenditure predictability over ownership.
Multiple Unit Pellet Systems Market Segmentation
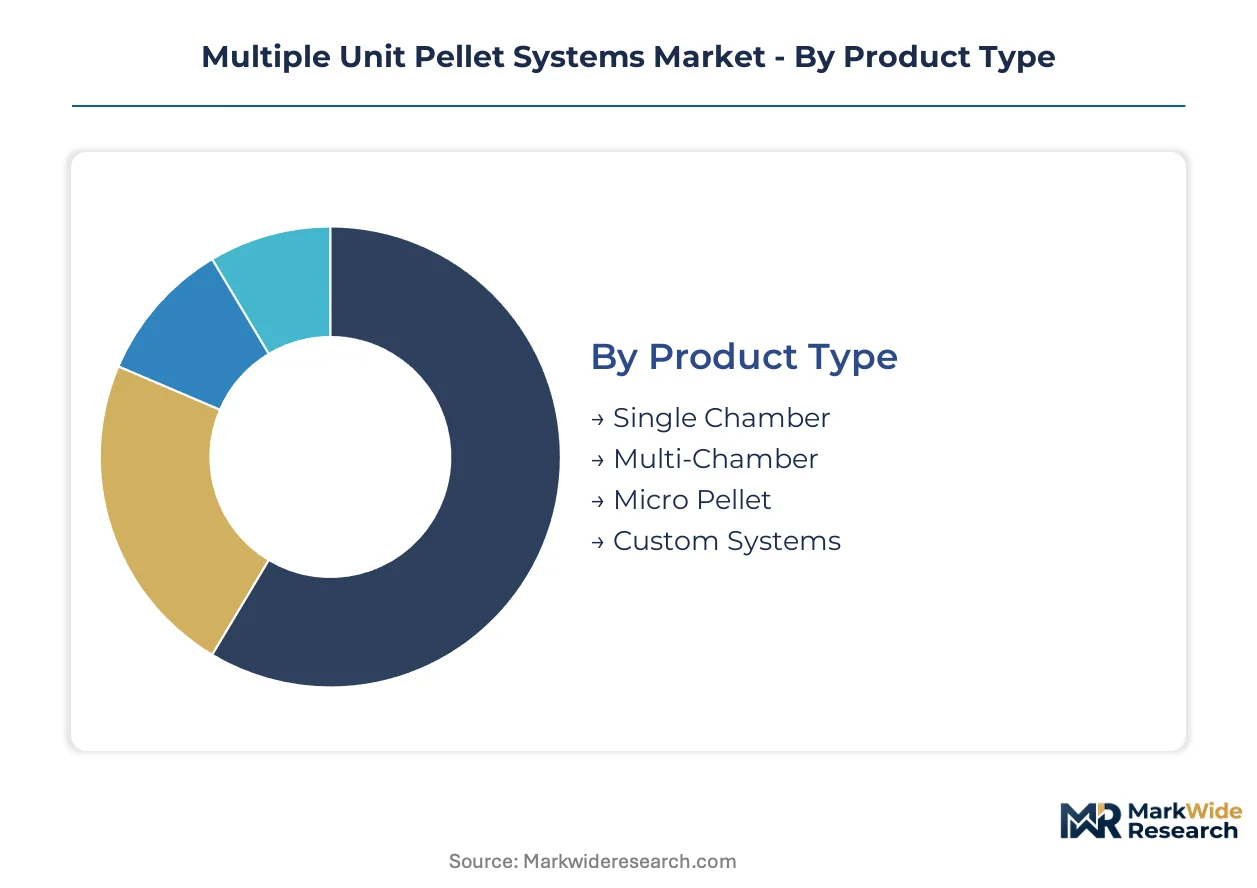
Pellet system segmentation reveals distinct integration patterns across pharmaceutical manufacturing workflows. Standalone units serve contract manufacturers with flexible batch requirements, while embedded configurations dominate continuous production lines where real-time release testing is mandatory.
Product Type:
Standalone pellet production units address batch flexibility needs in contract manufacturing environments, whereas embedded configurations integrate into continuous processing lines with PAT-enabled quality verification.
- Multi-Chamber:High-throughput configurations process multiple formulation streams simultaneously, reducing changeover downtime in generic drug manufacturing facilities across Germany and India. German pharmaceutical contract manufacturers prioritize these systems for oncology batch production where throughput directly determines capacity utilization rates.
- Micro Pellet:Precision units generate sub-millimeter particulates enabling weight-based pediatric dosing and geriatric formulation flexibility. Hospital pharmacy compounding centers in the United States deploy compact micro pellet systems for patient-specific chemotherapy regimens, bypassing centralized manufacturing delays and reducing waste from expired bulk inventories.
- Single Chamber:Entry-level systems serve emerging-market manufacturers with limited capital budgets and lower volume requirements.
- Custom Systems:Engineered configurations address specialized coating or layering requirements for complex modified-release profiles.
Multi-Chamber systems lead volumes today; Micro Pellet is gaining share fastest.
End User:
Customer segmentation tracks value capture across regulated pharmaceutical environments versus less stringent food and agricultural applications where equipment specifications diverge sharply.
- Pharmaceuticals:FDA cGMP and EMA MDR compliance mandates dominate procurement criteria, with validation documentation and PAT integration commanding premium pricing. Oncology formulation demand in United States and German hospital networks drives controlled-release pellet adoption, while India's CDSCO-aligned Schedule M provisions raise domestic manufacturing standards.
- Nutraceuticals:Modified-release profiles for vitamin and mineral delivery require functional coating capabilities similar to pharmaceutical applications, though with reduced validation burden.
- Food Industry:Taste-masking and controlled-release applications for functional ingredients operate under FSSAI and FDA food safety frameworks with lower equipment qualification requirements.
- Agriculture:Slow-release fertilizer and feed additive applications prioritize cost efficiency over precision coating control.
Pharmaceuticals commands the dominant revenue share; Nutraceuticals is expanding most quickly as functional food convergence accelerates.
Application:
Use-case segmentation distinguishes high-value drug delivery applications where bioequivalence outcomes determine equipment selection from industrial processing where throughput efficiency dominates.
- Drug Delivery:Oral solid dosage forms for controlled-release, taste-masking, and dose flexibility represent the core value proposition, with coating precision directly determining pharmacokinetic performance. EMA's revised PAT guidelines now mandate real-time coating thickness monitoring, forcing retrofit investments in European manufacturing sites.
- Biotechnology:Cell culture media and biologic stabilizer applications require aseptic processing capabilities with specialized material compatibility requirements.
- Food Processing:Encapsulation of flavors, probiotics, and functional ingredients leverages pellet technology for shelf-life extension and controlled release.
- Animal Feed:Medicated feed additives and nutrient delivery systems prioritize cost-effective production scale over precision layering control.
Drug Delivery anchors current installed base; Biotechnology shows the steepest expansion trajectory as cell therapy manufacturing scales.
Technology:
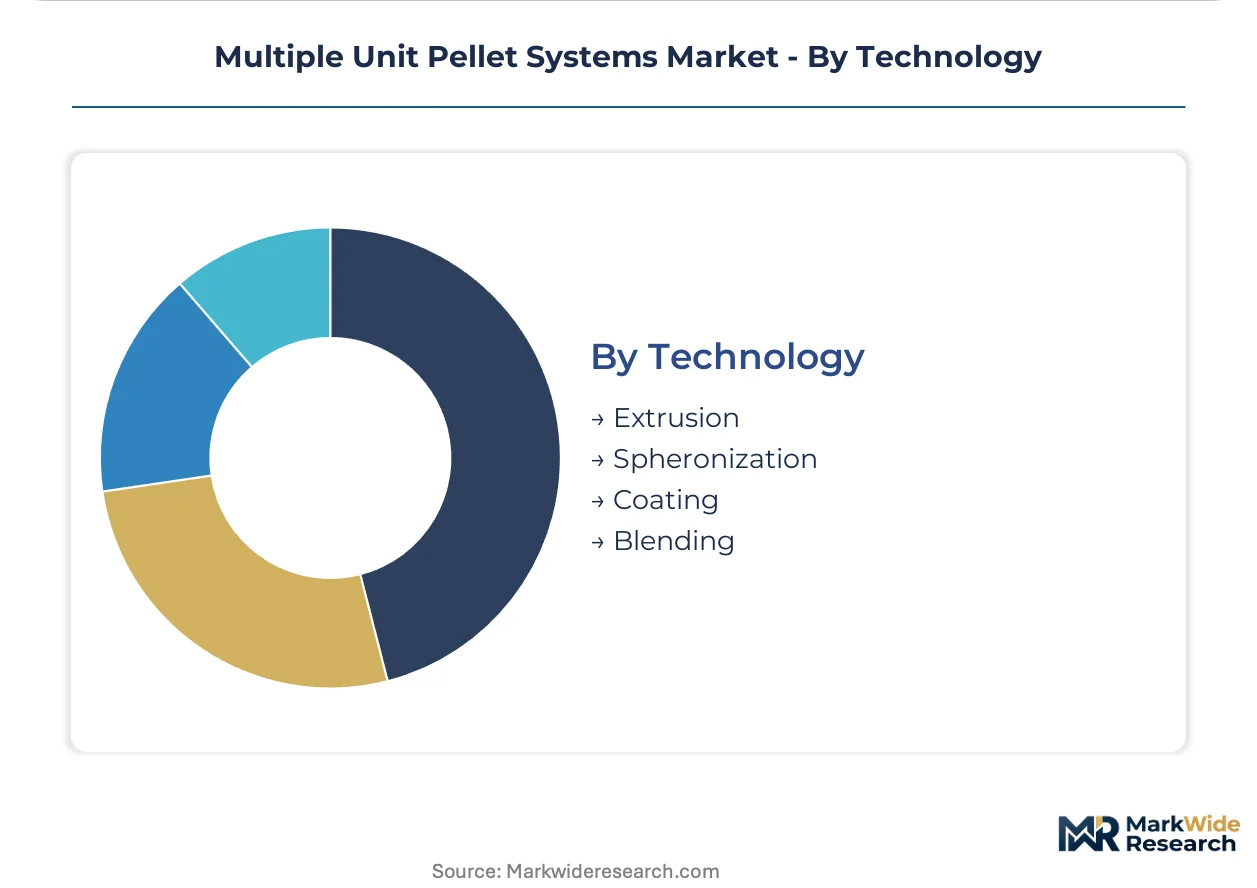
Process technology segmentation reflects the manufacturing workflow from core pellet formation through functional finishing, with coating commanding disproportionate value capture.
- Coating:Functional film application determines release kinetics and bioequivalence outcomes, commanding premium equipment pricing and service contract values. Real-time spectrometry integration for thickness monitoring is becoming mandatory under EMA guidelines, creating upgrade revenue for German equipment vendors.
- Extrusion:Continuous processing advancement reduces batch-to-batch variability, improving yield rates for high-volume generic manufacturers in India and Germany.
- Spheronization:Wet mass conversion to spherical particulates requires precise moisture control and residence time management.
- Blending:Final formulation mixing and homogenization steps integrate pellet systems with downstream tablet or capsule production.
Extrusion occupies the largest installed base; Coating is climbing the fastest as functional release profiles become standard of care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's pharmaceutical contract manufacturers command premium pellet system installations, while India's domestic equipment suppliers leverage production-linked incentives to displace imported systems at lower price points.
United States
Oncology formulation demand from hospital networks drives controlled-release pellet adoption, with Memorial Sloan Kettering and MD Anderson compressing supply chains through on-site compounding capabilities. FDA's current Good Manufacturing Practice standards for multiparticulate batch uniformity extend validation timelines to 18-24 months. The Greater Boston biotech corridor anchors micro pellet system deployments for pediatric dose personalization.
Germany
EMA's Medical Device Regulation framework mandates traceability for pellet-based combination products, accelerating retrofit investments in PAT-enabled coating lines. German pharmaceutical contract manufacturers prioritize multi-chamber configurations for high-throughput oncology batch production. The Rhine-Main manufacturing cluster around Frankfurt concentrates equipment upgrade activity for real-time release testing compliance.
India
CDSCO's revised Schedule M provisions align with ICH Q8-Q12 guidelines, raising compliance costs for domestic pellet equipment suppliers while improving export qualification. The Production-Linked Incentive scheme enables Gujarat and Telangana manufacturing clusters to capture share from European and American imported systems. Contract manufacturers in Ahmedabad and Hyderabad favor subscription-based uptime contracts over capital purchases.
China
NMPA's alignment with ICH quality guidelines drives adoption of extrusion-spheronization systems for generic drug manufacturing, though functional excipient import dependence creates supply vulnerabilities. The Yangtze River Delta pharmaceutical corridor concentrates fluid-bed layering capacity for modified-release formulations. Shanghai and Suzhou manufacturers face pressure to integrate real-time coating thickness monitoring ahead of anticipated regulatory convergence.
Switzerland
Swissmedic's stringent pharmacovigilance requirements for multiparticulate dosage forms position the country as a qualification benchmark for global pharmaceutical manufacturers. Basel's biopharma ecosystem anchors high-value pellet production partnerships for oncology and rare disease therapies. Swiss contract manufacturers command premium pricing for validated manufacturing equipment serving EU and US export markets.
Multiple Unit Pellet Systems Market Competitive Landscape
Top-tier vendors anchor premium coating and PAT-integrated system supply, while mid-tier fabricators compete on cost-engineered multi-chamber configurations for emerging-market generic manufacturers. The vendor base stratifies across three archetypes: European precision equipment specialists, Indian cost-optimized system builders, and diversified chemical conglomerates with excipient-pellet integration capabilities. Capacity expansion and strategic technology licensing represent the dominant competitive vectors as regulatory compliance costs reshape procurement criteria.
Within the diversified chemical conglomerate tier, BASF SE and Evonik Industries AG exemplify functional excipient-pellet combination strategies that command premium positioning. Lonza Group Ltd. occupies a distinctive anchor position leveraging biologics manufacturing footprints to secure high-value production partnerships. Among emerging-market specialists, ACG Worldwide represents the cost-engineered equipment archetype targeting domestic Indian pharmaceutical manufacturers and export markets in Southeast Asia and Africa.
| Leading Market Players |
|---|
| Lonza Group Ltd. |
| Bosch Packaging Technology |
| BASF SE |
| Johnson & Johnson |
| Colorcon, Inc. |
| Evonik Industries AG |
| AstraZeneca |
| ACG Worldwide |
| GEA Group |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up equipment specialists in Germany and Switzerland exercise outsized pricing discipline through captive service networks and proprietary coating technologies, while Indian family-owned mid-caps compete on operational expenditure predictability through subscription-based uptime contracts. This ownership bifurcation concentrates premium pricing power in European precision manufacturers and compresses margins for emerging-market system builders dependent on imported functional excipients.
Pricing Analysis
Capacity additions in India are reshaping price floors for standard multi-chamber configurations as domestic fabricators leverage PLI scheme subsidies. Three-tier pricing structure across premium, standard, and economy levels separates validated PAT-integrated systems from basic extrusion units and refurbished legacy equipment. Pricing pressure stems from petrochemical feedstock volatility affecting specialized polymer coatings. Emerging-market generic manufacturers exhibit highest price sensitivity, while United States hospital pharmacy compounding centers prioritize coating precision over capital cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German pharmaceutical contract manufacturers, while distributor-mediated sales serve mid-tier Indian generic producers. Manufacturing concentrates in Germany, India, and Switzerland, with functional excipient supply anchored in petrochemical feedstocks from Belgium and the Netherlands. Equipment production draws from precision machining components sourced from Japan and specialty steel alloys from Sweden. Single-source vulnerability in high-purity coating polymer supply creates exposure to ECHA REACH regulatory restrictions. Distribution runs through authorized service partners for validation documentation and aftermarket support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between German precision equipment premiums and Indian PLI-subsidized manufacturing costs, with regulatory compliance differentials widening the investable spread.
For Market Incumbents: Anchor premium positioning through backward integration into functional excipient supply and PAT sensor technology. Defend against fluid-bed layering substitution by embedding real-time release testing capabilities as standard configuration. Prioritize capacity additions in Switzerland to capture Swissmedic qualification benchmark premiums for EU and United States export markets. For New Entrants and Emerging Players: Enter via micro pellet system white space in United States pediatric oncology compounding and German hospital pharmacy networks. Target the nutraceuticals segment as the most penetrable vertical given reduced FDA validation burden compared to pharmaceutical applications. Pursue white-label manufacturing partnerships with established coating technology licensors to bypass R&D timeline disadvantages. For Investors and Strategic Acquirers: Valuations sit cheapest among Indian cost-optimized system builders with PLI scheme eligibility and emerging-market export traction. Long-term viability centers on regulatory convergence toward ICH Q8-Q12 guidelines compressing qualification protocol fragmentation. Monitor EMA process analytical technology guideline enforcement intensity as the primary inflection signal for coating equipment upgrade cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| PAT Sensor Integration | EMA mandate for real-time coating thickness monitoring forces retrofit investments across European manufacturing sites. |
| Subscription Service Transition | Performance-linked uptime contracts in Gujarat and Telangana clusters shift revenue from capital sales to recurring service streams. |
| Micro Pellet Capacity Buildout | Hospital-site compounding installations at Memorial Sloan Kettering and German cancer centers decentralize oncology dose personalization. |
| Excipient-Pellet Combination Development | Functional polymer integration by Evonik and BASF creates differentiated modified-release profile capabilities. |
| Continuous Manufacturing Convergence | Real-time release testing integration enables bypass of traditional batch testing bottlenecks in high-volume generic production. |
Research Methodology
Direct dialogue with equipment procurement managers at German pharmaceutical contract manufacturers, regulatory affairs leads navigating FDA cGMP and EMA MDR frameworks, plant engineers at Indian generic manufacturing clusters, and aftermarket service heads at European precision equipment specialists grounded qualitative findings. Secondary validation drew from FDA 483 inspection observations, EMA manufacturing authorization databases, CDSCO Schedule M compliance circulars, and customs trade data for pellet system imports. Bottom-up and top-down triangulation cross-checked equipment shipment volumes against pharmaceutical manufacturing capacity expansion announcements.
Bottom-up modeling aggregated installed base estimates by technology type and coating configuration across the projection horizon, while top-down analysis triangulated against pharmaceutical capital expenditure surveys and contract manufacturing capacity utilization rates. Segmentation dimensions included product type, end-user regulatory stringency tier, application release profile complexity, and geographic regulatory cluster. CAGRs derived from equipment replacement cycle analysis and regulatory-driven upgrade propensity scoring, with inputs from petrochemical feedstock price trajectory assumptions and oncology formulation pipeline expansion rates.
The model holds under stable ICH guideline convergence and functional excipient supply continuity; deviation in REACH regulatory expansion or PLI scheme modification would shift equipment demand geographic distribution. Forecasts reflect assumptions regarding EMA PAT enforcement timeline and FDA multiparticulate batch uniformity inspection intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Electric Brewing System Market
Food Processing Equipment
Coconut Crushers Market
Food Processing Equipment
Food Processing Machinery Market
Food Processing Equipment
Plastic Processing Equipment Market
Food Processing Equipment
Walk-In Coolers and Freezers Market
Food Processing Equipment
Oven Market
Food Processing Equipment
Global High Pressure Processing (HPP) Market
Food Processing Equipment
Filleting Machines Market
Food Processing Equipment
Global Starch Recovery Systems Market
Food Processing Equipment
Spray Drying Equipment Market
Food Processing Equipment
Mooncake Production Line Market
Food Processing Equipment
Mobile Bottling Line Market
Food Processing Equipment
Semi-Auto Egg Tart Forming Machine Market
Food Processing Equipment
Commercial Beverage Blender Market
Food Processing Equipment
Mixing Vessels Market
Food Processing Equipment
Food Disinfection Equipment Market