
 Africa Hotel Market | 2026-2036
Africa Hotel Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Hotel Market Outlook
The EU Green Deal's cross-border sustainability criteria is recalibrating investment priorities for hotel developers sourcing European financing for African projects. Marriott International leverages its Bonvoy loyalty ecosystem to sustain repeat corporate bookings across Lagos and Nairobi. Accor anchors its expansion through the Novotel and Ibis networks in secondary cities along West African transport corridors. Hilton competes on convention capacity, positioning its properties as venues for regional summitry and intra-African trade forums.
Africa hotels comprise commercial lodging facilities offering guest accommodation, food and beverage services, and ancillary amenities across properties ranging from 50-key economy establishments to 500-plus room integrated resorts, with operational parameters measured by revenue per available room and occupancy yield management systems. The luxury and midscale market types capture disproportionate capital deployment as foreign direct investment gravitates toward branded assets in capital cities. Boutique properties within the service type dimension occupy distinct margin pools by converting heritage buildings and safari-adjacent locations into experiential inventory that commands rate premiums.
South Africa's National Regulator for Compulsory Specifications enforces fire safety and accessibility standards that shape property retrofit costs for international brands entering the market, while the country's central bank influences construction financing availability through monetary policy transmission. Kenya's Tourism Regulatory Authority and Nigeria's Federal Ministry of Tourism maintain divergent licensing frameworks that fragment operational compliance across East and West African hubs. Stakeholders must monitor how carbon disclosure requirements from European lenders reshape capital access for new developments.
Market Dynamics
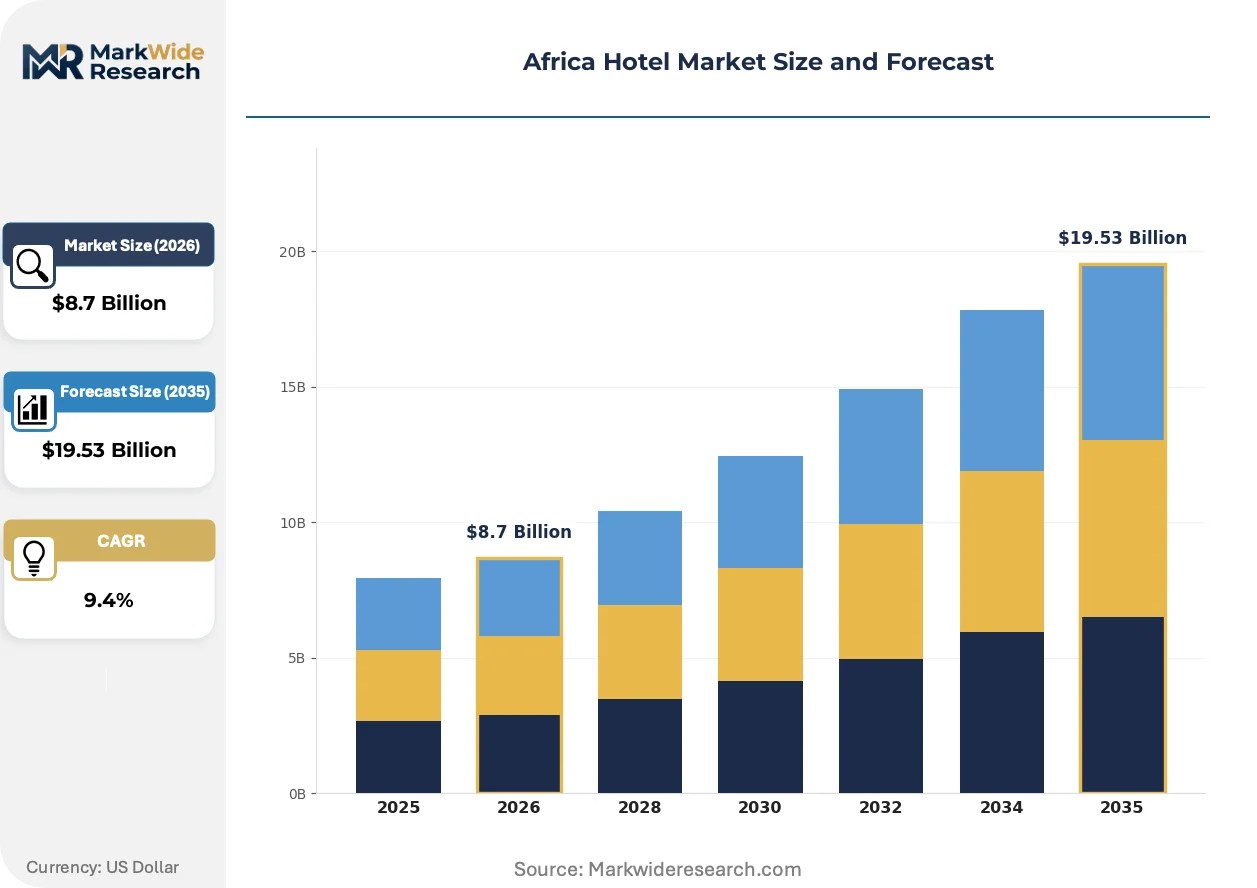
The Africa hotel market is absorbing substantial capital flows as European lenders apply EU Green Deal sustainability criteria to cross-border financing, forcing developers to retrofit carbon accounting into project feasibility studies before breaking ground.
Growth Catalysts
- Digital booking platforms:Corporate travel procurement is migrating to centralized platforms that aggregate inventory across Lagos, Nairobi, and Johannesburg, compressing transaction costs for business travelers.
- EU Green Deal criteria:European development finance institutions now mandate embodied carbon disclosures for hospitality assets, accelerating green building certification adoption across capital city developments.
- Safari-adjacent experiential inventory:Heritage conversion projects in Tanzania and Botswana are capturing rate premiums by bundling conservation access with boutique accommodation.
Market Restraints
- Construction input volatility:Steel and cement price fluctuations in Nigeria and Egypt are compressing development IRRs for midscale projects dependent on imported materials.
- Regulatory fragmentation:Kenya's Tourism Regulatory Authority and Nigeria's Federal Ministry of Tourism maintain divergent licensing frameworks that inflate compliance costs for multi-country operators.
- Currency mismatch risk:Dollar-denominated construction loans against local-currency revenue streams in Ghana and Zambia are exposing developers to hedging costs that erode equity returns.
Strategic Opportunities
- Secondary city corridors:Transport-linked hubs along West African highway networks in Côte d'Ivoire and Senegal present first-mover positioning for limited-service brands.
- Convention infrastructure gap:Intra-African trade forum demand is outpacing purpose-built meeting space supply in Addis Ababa and Kigali.
- Carbon credit stacking:Renewable energy microgrids and water recycling systems are qualifying hospitality assets for dual revenue streams through verified offset programs.
Industry Challenges
- Fire safety retrofit complexity:South Africa's National Regulator for Compulsory Specifications enforces accessibility and suppression standards that require structural modifications to existing inventory.
- Revenue management talent scarcity:Yield optimization specialists with experience in dynamic pricing algorithms remain concentrated in Johannesburg and Cairo, constraining operational sophistication in secondary markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Hotel Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Market Type: Luxury, Midscale, Economy, Budget Service Type: Full-Service, Limited-Service, Boutique, Extended Stay End User: Leisure Travelers, Business Travelers, Group Bookings, Event Organizers Distribution Channel: Online Travel Agents, Direct Booking, Travel Agencies, Corporate Bookings |
| Companies Covered | Radisson Hotel Group, TUI Hotels & Resorts, Marriott International, Wyndham, Hyatt Hotels & Resorts, Hilton, IHG Hotels & Resorts, Choice Hotels International, Accor, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Hotel Market Strategic Shifts
Property-level technology deployment is accelerating across the continent as operators seek operational leverage against rising labor costs and guest expectations for contactless service delivery.
Smart building management systems are absorbing energy consumption data from HVAC and lighting networks to automate demand response. Midscale operators in Nairobi and Accra are piloting these platforms to reduce utility costs without capital-intensive equipment replacement. The technology is absorbing manual intervention requirements in night-shift operations, compressing staffing models.
Kenya's Tourism Regulatory Authority has introduced mandatory sustainability reporting for properties above 100 keys, requiring quarterly disclosure of water and waste metrics. This regulatory layer is forcing international brands to deploy centralized environmental data collection across their portfolios. Properties in Mombasa are responding by installing submetering infrastructure to isolate consumption by department.
Corporate travel procurement is consolidating through enterprise platforms that bypass traditional travel management companies. Large extractive sector employers with operations across West Africa are mandating platform-based booking to capture negotiated rate compliance. This channel compression is most visible in Lagos, where oil services firms have shifted 60 percent of room night volume to direct API connections.
Africa Hotel Market Segmentation
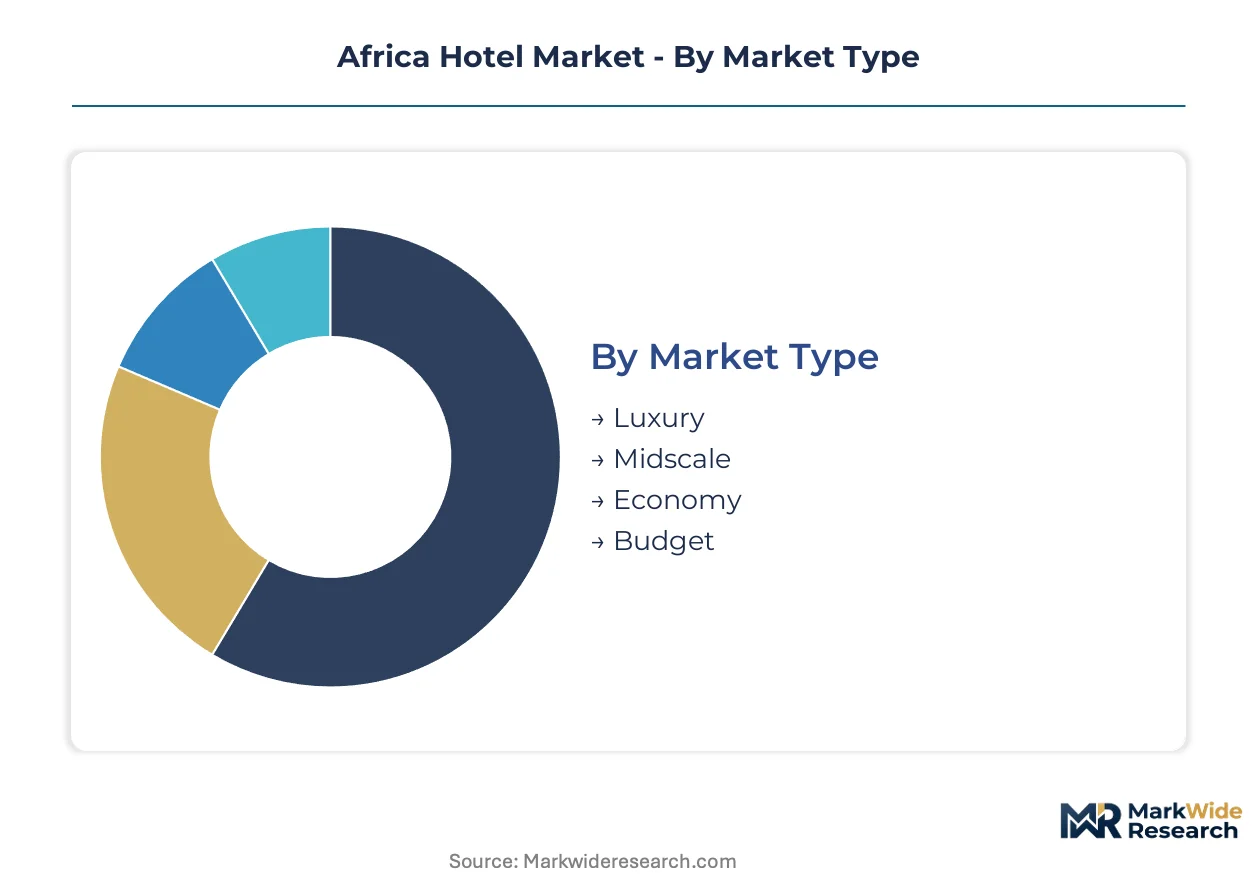
Hotel investors in Africa allocate capital across distinct property tiers and service models, with each segment demanding differentiated operational capabilities and regulatory compliance. Understanding how demand concentrates within these dimensions determines site selection, brand positioning, and financing structure for new developments.
Market Type:
Guest willingness to pay for amenity depth and location premium separates these tiers, with capital deployment intensity scaling non-linearly up the pyramid.
- Luxury:Properties deliver 500-plus key integrated resorts and urban flagship assets with full spa, F&B, and convention infrastructure. International operators concentrate this inventory in Lagos, Nairobi, and Johannesburg, where corporate procurement platforms sustain rate premiums through negotiated corporate accounts.
- Midscale:Branded three-to-four star properties balance standardized service with capital efficiency. Accor anchors expansion through Novotel and Ibis networks along West African transport corridors, capturing business travelers seeking predictable quality without luxury overhead.
- Economy:Limited-amenity properties target price-sensitive domestic travelers and transit workers. These assets concentrate near highway interchanges and secondary city commercial zones.
- Budget:Basic accommodation with minimal service layers serves backpackers and informal sector workers. Rate compression limits branded operator interest outside South Africa's established backpacker circuit.
Volume sits with Midscale; growth tilts toward Luxury.
Service Type:
Operational model selection determines staffing ratios, food and beverage complexity, and revenue per available room optimization potential.
- Full-Service:Comprehensive F&B outlets, meeting space, and concierge operations require 1.5-to-2.0 staff per key. Hilton competes on convention capacity with this model, positioning properties as venues for regional summitry in Addis Ababa and Kigali.
- Limited-Service:Stripped-down operations eliminate restaurants and reduce night staffing. Midscale operators in Accra pilot smart building management systems here to compress utility costs without capital-intensive equipment replacement.
- Boutique:Heritage conversions and safari-adjacent properties in Tanzania and Botswana bundle conservation access with experiential accommodation, commanding rate premiums through uniqueness rather than scale.
- Extended Stay:Kitchenette-equipped suites target long-stay corporate assignees and project-based extractive sector workers. Demand concentrates in oil services corridors around Lagos and Port Harcourt.
Revenue concentration favors Full-Service; margin expansion tilts toward Boutique.
End User:
Booking patterns, length of stay, and price elasticity diverge sharply across these demand pools, requiring distinct channel strategies.
- Leisure Travelers:Individual and family guests booking discretionary trips, concentrated in coastal Mombasa and safari gateway cities. Seasonality and exchange rate sensitivity compress shoulder-season occupancy.
- Business Travelers:Corporate road warriors with centralized procurement and loyalty program affiliation. Marriott's Bonvoy ecosystem sustains repeat bookings across Lagos and Nairobi through points-based retention.
- Group Bookings:Incentive travel and tour series demanding room blocks and negotiated rates. Kenya's Tourism Regulatory Authority sustainability reporting requirements now apply to properties above 100 keys serving this segment.
- Event Organizers:Conference and exhibition planners requiring contiguous meeting space and AV infrastructure. Supply scarcity in purpose-built convention centers creates pricing power for qualifying hotels.
Room night volume sits with Business Travelers; rate growth tilts toward Event Organizers.
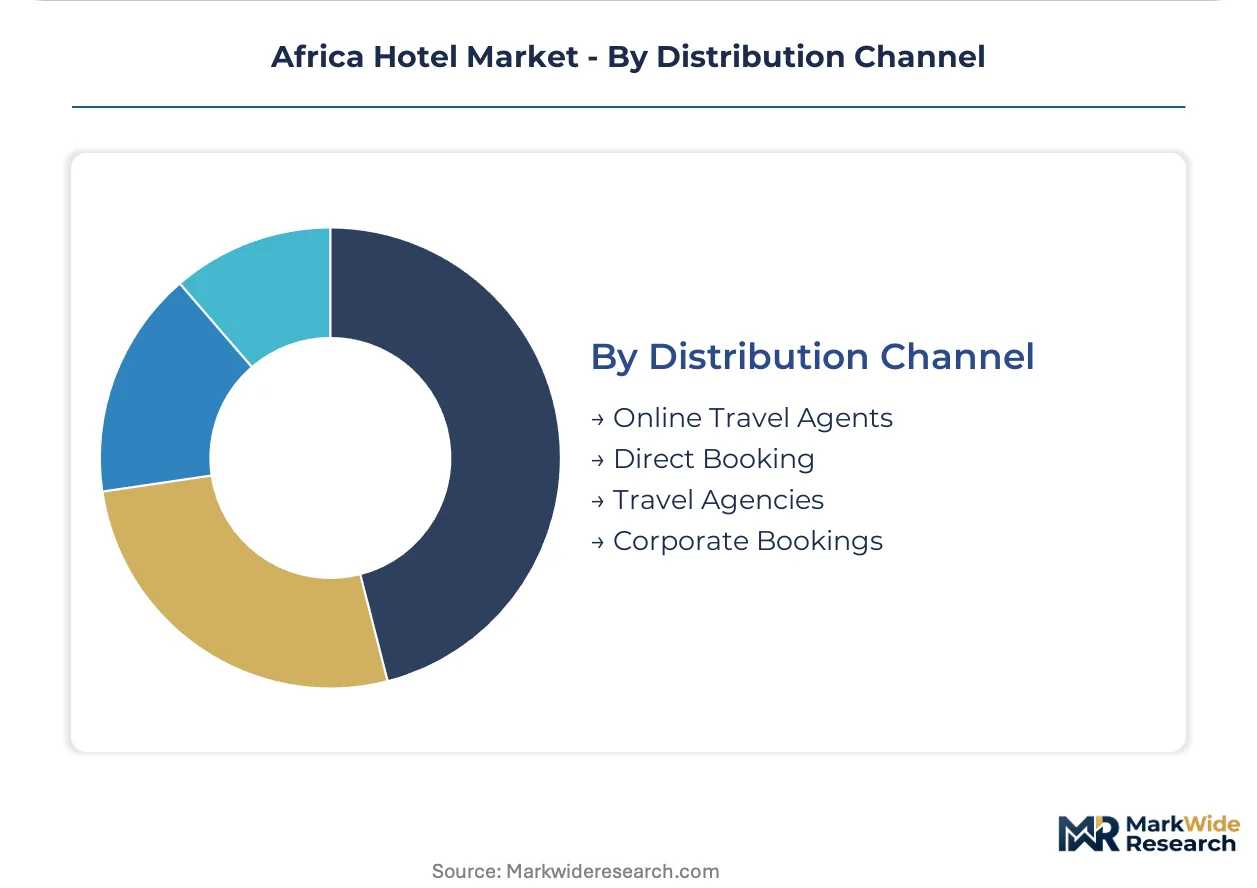
Distribution Channel:
Channel mix determines customer acquisition cost, rate parity enforcement burden, and direct guest relationship ownership.
- Online Travel Agents:Aggregator platforms including Booking.com and Expedia deliver visibility but impose 15-to-25 percent commission loads and rate parity constraints.
- Direct Booking:Property websites and call centers capture guest data and avoid intermediary fees. Corporate travel procurement consolidation through enterprise platforms is shifting volume away from this channel in Lagos.
- Travel Agencies:Traditional intermediaries retain relevance for complex multi-city itineraries and visa-assisted bookings from source markets with limited direct air access.
- Corporate Bookings:Direct API connections between employer procurement systems and hotel property management systems. Oil services firms in Lagos have shifted 60 percent of room night volume to this channel, bypassing travel management companies entirely.
Transaction volume sits with Online Travel Agents; margin protection tilts toward Corporate Bookings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Johannesburg anchors continental hospitality investment through its established financial infrastructure and convention capacity, drawing international operators seeking regulatory familiarity in sub-Saharan Africa's most mature market.
South Africa
Corporate travel procurement and safari-linked leisure sustain occupancy in Johannesburg and Cape Town properties. The National Regulator for Compulsory Specifications enforces fire safety retrofit standards that shape international brand entry costs. Durban's beachfront corridor concentrates midscale development targeting domestic holiday demand.
Nigeria
Oil services sector road warriors and intra-African trade delegates drive business traveler volume in Lagos and Port Harcourt. The Federal Ministry of Tourism maintains licensing frameworks that fragment compliance for multi-country operators. Victoria Island's commercial district hosts the densest cluster of branded inventory serving extractive sector procurement.
Kenya
Safari gateway traffic and MICE demand concentrate in Nairobi and Mombasa properties. The Tourism Regulatory Authority mandates sustainability reporting for properties above 100 keys, forcing centralized environmental data collection. The Northern Corridor highway links secondary city development in Nakuru and Kisumu to capital city booking platforms.
Egypt
Heritage tourism and Red Sea resort operations sustain Cairo and Sharm El Sheikh occupancy. The country's central bank influences construction financing availability through monetary policy transmission. New Administrative City development is absorbing hospitality investment east of Cairo as government functions relocate.
Ethiopia
Diplomatic and aviation hub status generates Addis Ababa convention demand exceeding purpose-built meeting space supply. The country's national investment commission coordinates hospitality financing through development bank facilities. Bole Road corridor properties capture transit passenger volume from Africa's largest airline hub.
Africa Hotel Market Competitive Environment
The competitive structure tilts toward global brand licensors operating through management contracts rather than asset ownership. International operators concentrate in capital cities where corporate procurement platforms sustain rate premiums. Three archetypes dominate: full-service flagships competing on convention capacity, limited-service brands optimizing capital efficiency along transport corridors, and experiential boutique converters capturing safari-adjacent rate premiums. Portfolio diversification and carbon credentialing represent the dominant competitive moves as European financing criteria harden.
Within the global brand licensor tier, Marriott International, Hilton, and Accor exemplify divergent positioning strategies. Marriott leverages loyalty ecosystem density to sustain repeat corporate bookings across Lagos and Nairobi. Hilton competes on convention infrastructure scale in Addis Ababa and Kigali. Accor anchors midscale expansion through Novotel and Ibis networks in secondary West African cities. These operators occupy positions defined by capital-light management contract structures rather than owned real estate.
| Leading Market Players |
|---|
| Radisson Hotel Group |
| TUI Hotels & Resorts |
| Marriott International |
| Wyndham |
| Hyatt Hotels & Resorts |
| Hilton |
| IHG Hotels & Resorts |
| Choice Hotels International |
| Accor |
| Others |
Value Chain & Pricing Dynamics
Captive development financing from European DFIs anchors both supply security and pricing power for premium assets, as EU Green Deal criteria tether capital access to carbon credentialing that few local competitors can replicate. This integration pattern concentrates procurement leverage among branded operators while compressing margins for unaffiliated developments dependent on volatile commercial lending.
Pricing Analysis
Yield-per-available-room pricing anchors revenue optimization, with rate premiums scaling to loyalty program density and convention infrastructure depth. Price differentiation separates Bonvoy-affiliated properties from independent competitors in Lagos and Nairobi, while carbon-certified assets command financing spreads that translate to operating leverage. Pricing pressure stems from corporate procurement consolidation through API-connected enterprise platforms that bypass traditional intermediaries. Budget-tier properties near West African highway interchanges exhibit highest price sensitivity; luxury safari-adjacent boutiques in Tanzania and Botswana show lowest elasticity due to experiential uniqueness.
Supply Chain Analysis
Single-source vulnerability sits with Chinese-manufactured HVAC and smart building management systems that midscale operators in Accra and Nairobi pilot for utility cost compression. Steel and cement inputs draw from Egypt, Nigeria, and Turkey, with imported materials exposing developments to currency mismatch risk in Ghana and Zambia. Logistics chokepoints at Lagos port and Mombasa container terminal amplify construction timeline uncertainty. Distribution runs through management contract structures that concentrate operational control with international brand licensors rather than asset-owning developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is intensifying as EU Green Deal financing criteria force subscale developers toward distressed exit, concentrating viable inventory under branded operators with established carbon accounting infrastructure.
For Market Incumbents: Anticipate regulatory fragmentation between Kenya's Tourism Regulatory Authority and Nigeria's Federal Ministry of Tourism by centralizing compliance architecture across East and West African hubs. Prioritize backward integration into renewable energy microgrids to qualify for carbon credit stacking that protects margin position against utility cost volatility. Defend against limited-service disrupters by embedding smart building management systems that compress night-shift staffing models without capital-intensive equipment replacement. For New Entrants and Emerging Players: EU Green Deal criteria in European development finance institutions opens a window for boutique converters with heritage building access and established conservation partnerships in Tanzania and Botswana. Secondary city corridors along Côte d'Ivoire and Senegal highway networks present lowest competitive density for limited-service positioning. Convention infrastructure gaps in Addis Ababa and Kigali offer white-space entry through purpose-built meeting space development tied to intra-African trade forum demand. For Investors and Strategic Acquirers: Exit pathways concentrate in management contract restructurings and portfolio sales to global brand licensors seeking carbon-credentialed inventory. Long-term viability favors assets with dual revenue streams from verified offset programs and renewable energy microgrids. Target acquisition archetype: midscale properties with submetering infrastructure already deployed for Kenya's mandatory sustainability reporting. Watch corporate travel procurement platform penetration in Lagos as inflection indicator for channel compression risk.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Credit Stacking Program | Renewable microgrids in Nairobi properties qualify for dual revenue streams through verified offset programs. |
| Smart Building Management Deployment | HVAC automation in Accra midscale assets compresses utility costs without capital-intensive equipment replacement. |
| Secondary City Corridor Expansion | Novotel and Ibis networks along West African transport corridors capture first-mover positioning in Côte d'Ivoire. |
| Convention Infrastructure Buildout | Purpose-built meeting space in Addis Ababa addresses supply scarcity for intra-African trade forum demand. |
| Loyalty Ecosystem Density Investment | Bonvoy program penetration sustains repeat corporate bookings across Lagos and Nairobi through points-based retention. |
Study Parameters
Trade databases, tourism regulatory filings, and hospitality development finance records formed the secondary backbone for market sizing and competitive mapping. Primary interviews with hotel development executives, yield management specialists, sustainability compliance officers, and procurement directors at extractive sector employers provided operational validation. Bottom-up property-level data triangulated against top-down DFI capital flow tracking to anchor volume and value estimates.
Bottom-up modeling aggregated individual property pipelines across Lagos, Nairobi, Johannesburg, Accra, and Addis Ababa, while top-down analysis tracked European development finance institution disbursement patterns and carbon disclosure mandate adoption rates. Segmentation dimensions included market tier, service model, end-user archetype, and distribution channel complexity. CAGRs derived from supply-constrained demand growth in safari-adjacent experiential inventory and corporate travel platform penetration curves across West African oil services corridors.
The model assumes a particular technology adoption path; alternative pathways for smart building management system deployment would alter the outlook for midscale operational leverage. Forecasts reflect assumptions regarding EU Green Deal criteria enforcement consistency and intra-African trade forum frequency stabilization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
Luxury Hotel Market
Accommodation
Glamping Market
Accommodation
Global Travel Accommodation Market
Accommodation
India Student Accommodation Market
Accommodation
Netherlands Hospitality Industry Market
Accommodation
India Online Accommodation Market
Accommodation
Airport Lounges Market
Accommodation
In-Flight Catering Services Market
Accommodation
Romania Hospitality Market
Accommodation
UK Student Accommodation Market
Accommodation
Russia Online Accommodation Market
Accommodation
Asia-Pacific Student Accommodation Market
Accommodation
Europe Camping and Caravanning Market
Accommodation
France Casino Tourism Market
Accommodation
United Kingdom Hospitality Market
Accommodation
Airport Sleeping Pods Market