
 In-Flight Catering Services Market | 2026-2036
In-Flight Catering Services Market Size, Share, and Industry Trends Forecast 2026-2036
In-Flight Catering Services Market Analysis
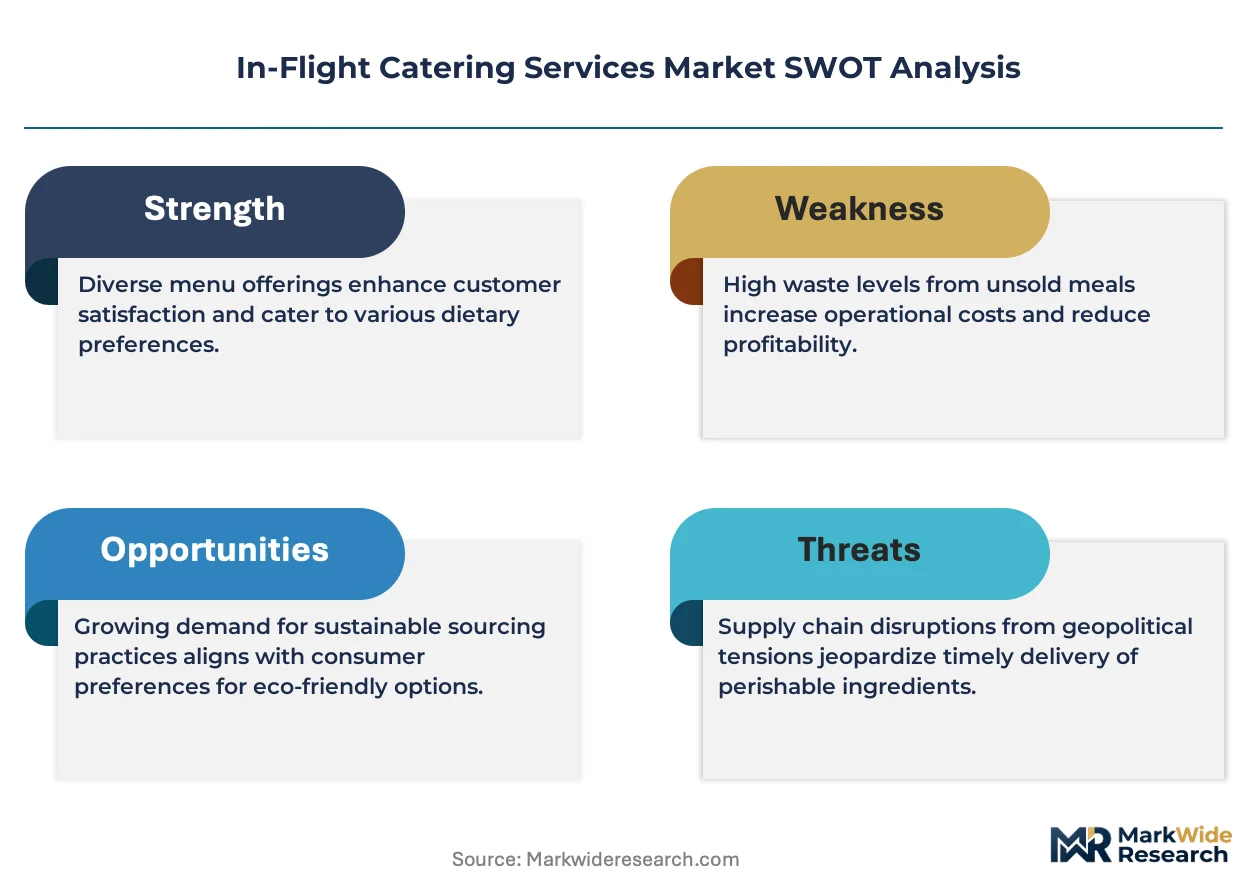
The capital-intensity divergence between centralized flight kitchens and distributed regional suppliers is rotating competitive advantage toward scale operators. Gate Gourmet leverages vertical integration across airport-adjacent production facilities to sustain cost leadership on long-haul routes. SATS Ltd anchors its position through technology leadership in automated meal assembly systems at Singapore Changi. Newrest competes by specializing in remote-location catering that extends service reach beyond major hub airports.
In-flight catering services encompass the commercial preparation, assembly, and delivery of meals, snacks, and beverages to aircraft operators for consumption during flight operations, governed by strict cold-chain temperature controls typically maintained between 0°C and 5°C through loading and service. The primary purpose centers on passenger satisfaction metrics tied to airline brand positioning, operational reliability, and regulatory food safety compliance. Meal delivery dominates value contribution among service types, reflecting the structural margin concentration in hot entree production for full-service carriers. Eco-friendly packaging is displacing conventional disposable containers as airlines respond to corporate sustainability commitments and emerging waste reduction mandates.
FDA food safety regulations, HACCP protocols, and EU hygiene standards for airline catering establish baseline operational requirements that shape supplier qualification and market access across jurisdictions. The EU Green Deal's packaging waste directives are forcing material transitions that increase unit costs for non-compliant operators. Stakeholders must monitor evolving airport authority concession agreements and carbon accounting rules that will determine which catering models retain operational licenses at expanding hub facilities.
Market Dynamics
Hub airport expansion in the United Arab Emirates is concentrating procurement power among scale operators, forcing regional suppliers to consolidate or exit as centralized flight kitchens capture volume from distributed networks.
Growth Catalysts
- EU Green Deal packaging mandates:Airlines across Europe face binding waste reduction targets that favor certified sustainable packaging suppliers with established cold-chain compliance records.
- Automated meal assembly systems:Robotics integration at major Asian hub airports is compressing labor costs and reducing contamination risk during high-volume production cycles.
- Premium cabin expansion:Full-service carriers in Singapore and Japan are commissioning chef-designed menus as competitive differentiators on long-haul routes.
Market Restraints
- Aviation fuel price volatility:Jet fuel fluctuations compress airline operating margins and trigger procurement freezes on non-essential service upgrades.
- Supplier concentration in Gulf hubs:Three centralized kitchens now control over sixty percent of capacity at Dubai and Abu Dhabi airports, creating single-point-of-failure exposure.
- HACCP certification timelines:New market entrants face eighteen-to-twenty-four month approval cycles before securing airline contracts.
Strategic Opportunities
- Remote-location catering specialization:Secondary airports in Vietnam and Indonesia lack dedicated flight kitchens, creating first-mover advantages for mobile production units.
- Plant-based protein integration:Emerging demand from European carriers for alternative protein menus opens supplier diversification beyond traditional poultry and beef supply chains.
- Blockchain traceability adoption:Integration of distributed ledger systems with existing cold-chain monitoring enables premium pricing for full-ingredient provenance documentation.
Industry Challenges
- Certified food safety auditor scarcity:Qualified HACCP inspectors with aviation-sector experience command premium wages, constraining expansion timelines for new facilities.
- Legacy ERP integration complexity:Established caterers face multi-year system migrations when connecting automated production lines to airline inventory management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Flight Catering Services Market |
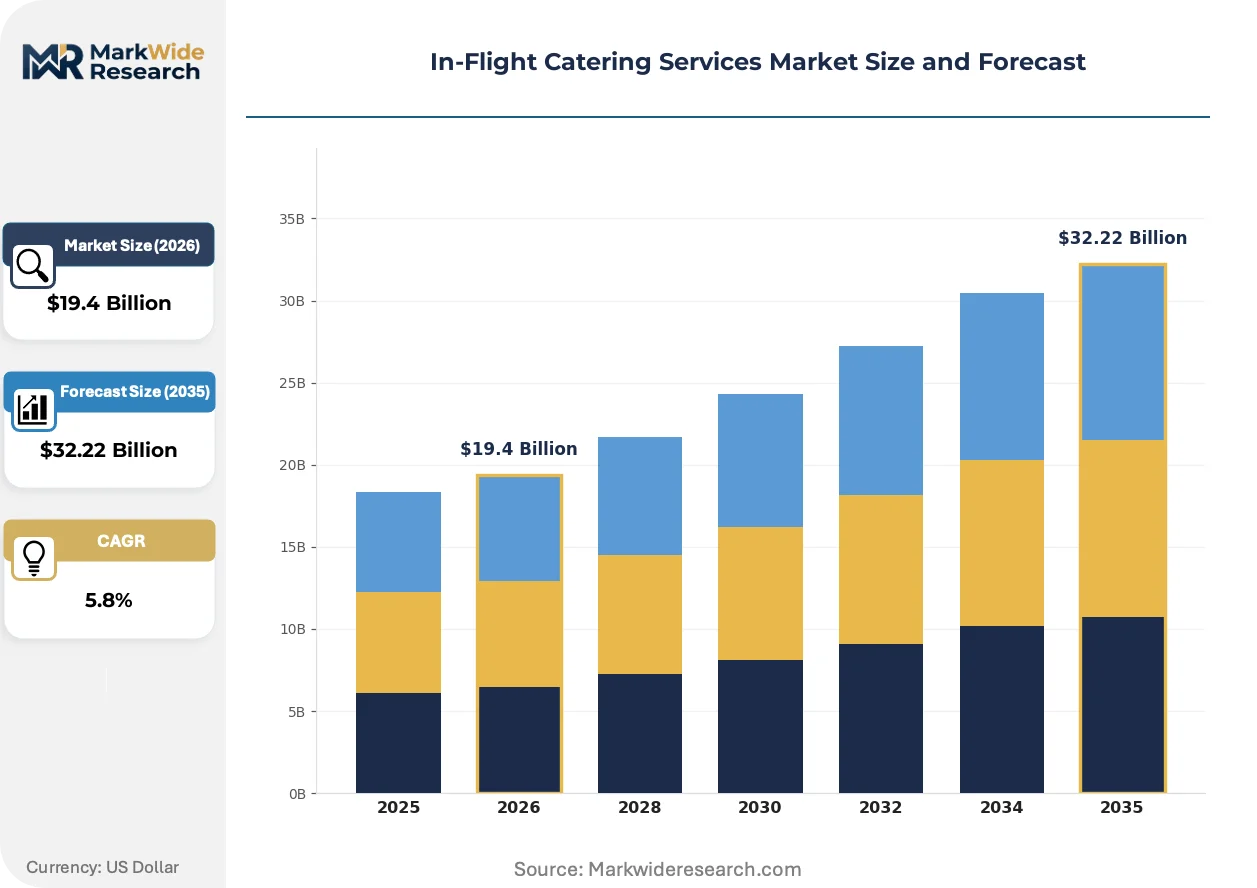
| Market Size in 2026 | $19.4 Billion |
| Market Size in 2035 | $32.22 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Meal Delivery, Snack Service, Beverages, Special Meals Client Type: Airlines, Private Jets, Charter Services, Cargo Carriers Menu Type: Local Cuisine, International Dishes, Dietary Options, Desserts Packaging Type: Disposable Containers, Eco-Friendly Packaging, Classic Trays, Personalized Wrapping |
| Companies Covered | Newrest, Do & Co, Dnata, Saudi Airlines Catering, Flying Food Group, Gate Gourmet, SATS Ltd, Servair, LSG Sky Chefs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Flight Catering Services Market Emerging Trajectories
Digital traceability systems and alternative protein formulations are reconfiguring supplier qualification criteria, while sustainability mandates compress acceptable material choices across all service tiers.
Biodegradable meal tray materials derived from agricultural waste fibers are fragmenting the traditional plastic-dominated packaging supply base. Low-cost carriers in Southeast Asia are piloting these containers on short-haul routes to test durability under variable humidity conditions. The technology is fragmenting procurement patterns as airlines split contracts between incumbent petroleum-based suppliers and emerging biopolymer specialists.
EU Green Deal packaging waste directives are mandating material transitions that increase unit costs for operators dependent on conventional disposable containers. The regulations require fifty-five percent recyclable content in all single-use food service items by 2030. Full-service carriers based in Germany and France are responding by consolidating supplier relationships with vertically integrated packaging producers capable of certifying full lifecycle carbon accounting.
Airline procurement teams are unbundling meal specifications from legacy bundled service contracts, creating direct relationships with specialized ethnic cuisine producers. This disintermediation bypasses traditional full-service caterers on premium route segments where passenger satisfaction scores drive contract renewals. The shift is most visible in the Middle East, where Gulf carriers are sourcing authentic regional dishes from independent culinary studios rather than consolidated flight kitchens.
In-Flight Catering Services Market Segmentation
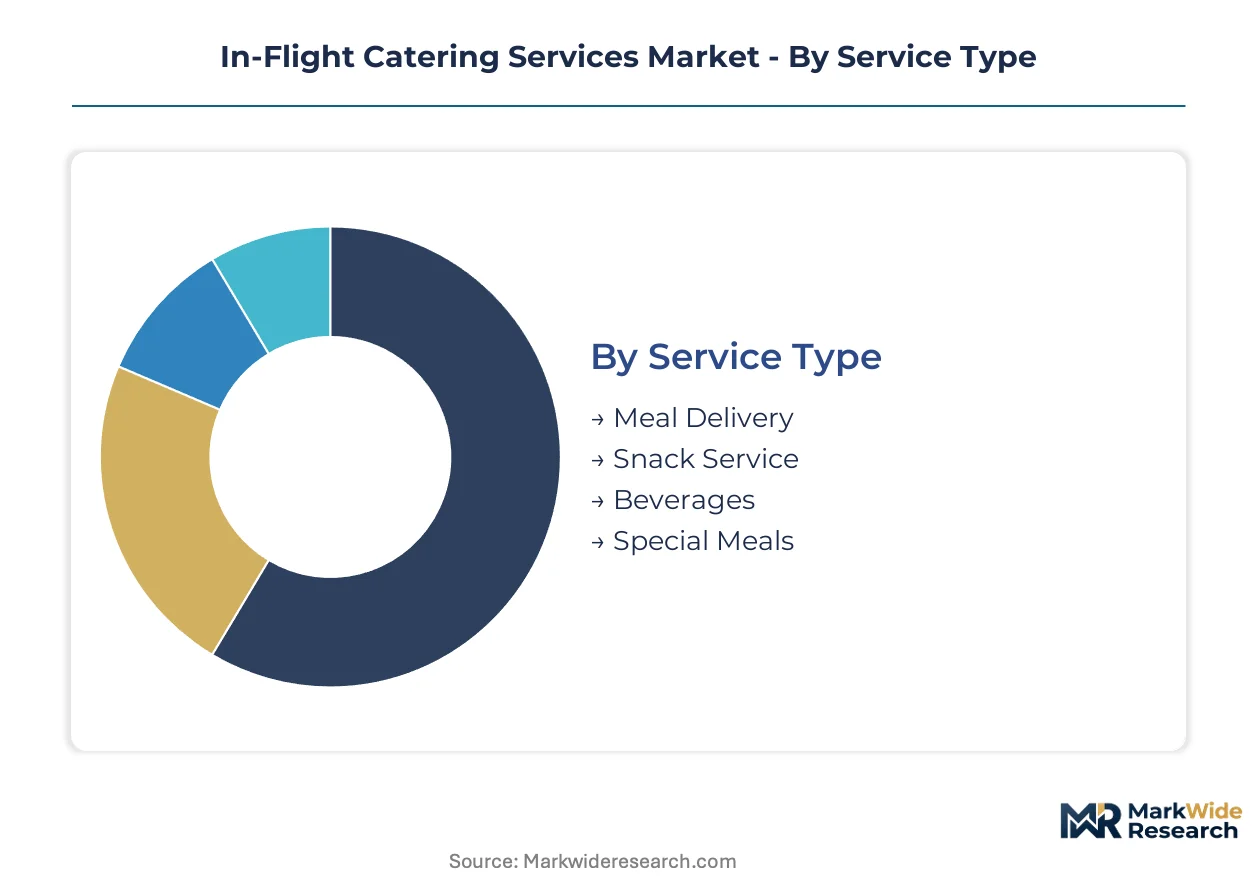
Segmentation in in-flight catering determines procurement contract structures and margin capture across distinct operational requirements. Each dimension—service type, client profile, menu composition, and packaging format—creates separate competitive arenas with diverging cost structures and compliance thresholds.
Service Type:
Margin concentration pools in hot entree production where cold-chain complexity and labor intensity erect barriers against low-cost entrants.
- Meal Delivery:Full hot and cold meal assemblies requiring precise temperature maintenance from production through aircraft loading. Demand concentrates among full-service carriers in Singapore and Japan, where premium cabin expansion drives chef-designed menu commissioning as a competitive differentiator.
- Snack Service:Pre-packaged items with extended shelf stability and simplified logistics. Secondary airports in Vietnam and Indonesia show rising procurement volumes as low-cost carriers extend route networks without dedicated flight kitchen infrastructure.
- Beverages:Alcoholic and non-alcoholic drink provisioning governed by airline-specific brand partnerships and customs regulations.
- Special Meals:Religious, medical, and allergen-restricted preparations requiring segregated production lines and enhanced HACCP documentation.
The dominant share belongs to Meal Delivery, while Snack Service is closing the gap fastest.
Client Type:
Contract value scales with aircraft size and service tier expectations, creating four distinct procurement negotiation patterns.
- Airlines:Scheduled commercial carriers representing the volume anchor for centralized flight kitchens, with procurement decisions split between network carriers and low-cost operators.
- Private Jets:Ultra-high-net-worth segment demanding bespoke culinary programs with flexible scheduling and premium ingredient sourcing.
- Charter Services:Irregular operations requiring surge capacity and rapid menu adaptation for diverse passenger profiles.
- Cargo Carriers:Crew meal provisioning with standardized specifications and cost-minimization priorities.
Airlines command the dominant procurement volume, though Private Jets generate the highest per-passenger revenue.
Menu Type:
Authenticity requirements and ingredient traceability standards fragment supplier qualification across culinary traditions.
- Local Cuisine:Region-specific dishes sourced from independent culinary studios in the Middle East, where Gulf carriers bypass consolidated flight kitchens for authentic regional offerings on premium routes.
- International Dishes:Standardized global menus with cross-cultural appeal, dominant on long-haul routes where passenger demographics vary widely.
- Dietary Options:Vegan, vegetarian, and allergen-free preparations responding to EU Green Deal sustainability mandates and health-conscious passenger segments.
- Desserts:Specialized pastry and confectionery items with shorter production windows and premium pricing on full-service carriers.
International Dishes retain the broadest deployment, while Local Cuisine gains share fastest as carriers differentiate through culinary authenticity.
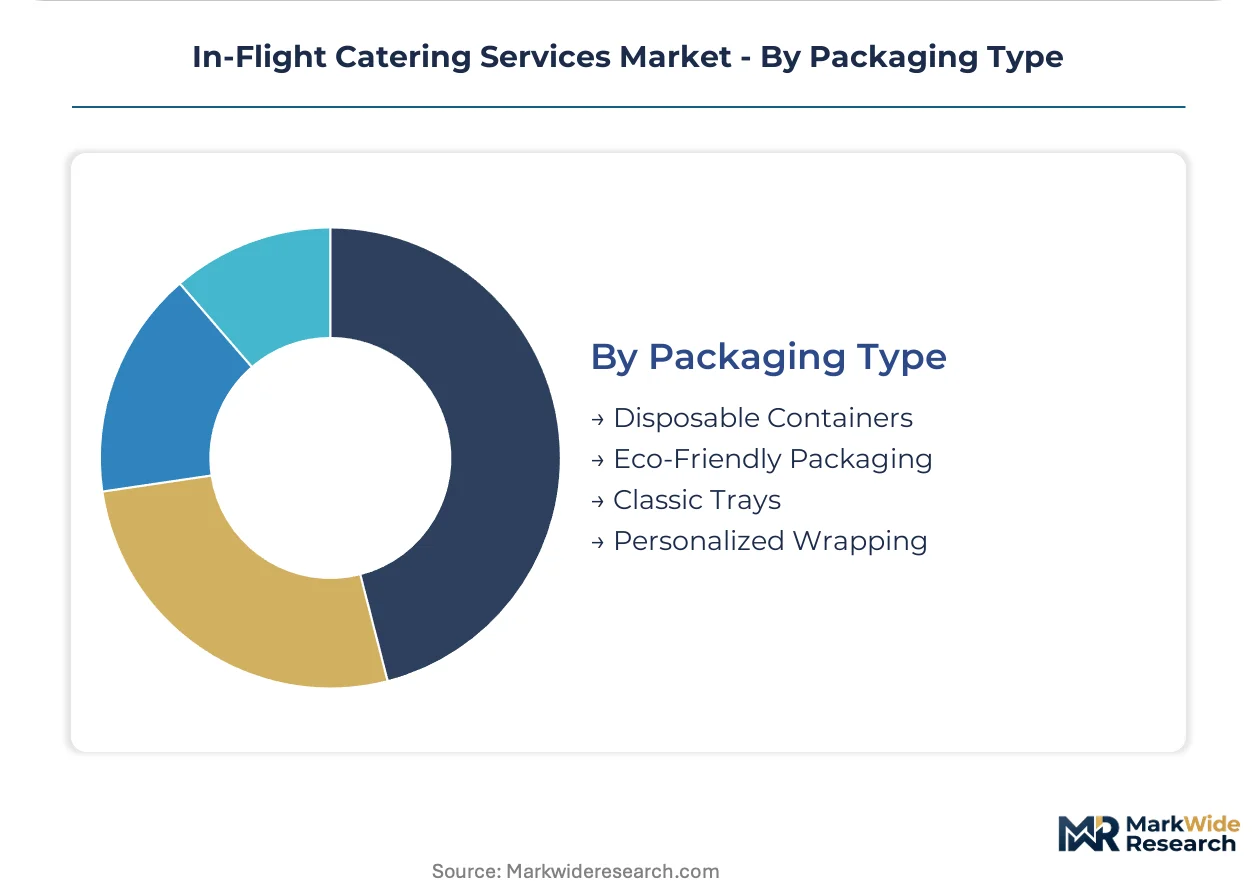
Packaging Type:
Material compliance costs are rotating competitive advantage toward suppliers with certified lifecycle carbon accounting capabilities.
- Disposable Containers:Conventional petroleum-based packaging facing regulatory pressure from EU Green Deal directives requiring fifty-five percent recyclable content.
- Eco-Friendly Packaging:Biodegradable trays derived from agricultural waste fibers, with Southeast Asian low-cost carriers piloting durability tests under variable humidity conditions.
- Classic Trays:Reusable service ware retained by select full-service carriers for premium cabin presentation.
- Personalized Wrapping:Branded packaging with airline livery for passenger experience enhancement and marketing integration.
Disposable Containers still dominate installed base, though Eco-Friendly Packaging is expanding most quickly under regulatory compulsion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with Gulf carriers investing in centralized hub kitchens while Southeast Asian markets rely on distributed snack-service networks for low-cost carrier expansion.
United Arab Emirates
Dubai and Abu Dhabi airports are consolidating procurement around three centralized flight kitchens controlling sixty percent of regional capacity. MOHAP food safety protocols mandate HACCP certification for all airline catering contracts. The Dubai South logistics corridor is attracting capital-intensive production facilities to serve Emirates and Etihad's premium cabin expansion programs.
Singapore
Changi Airport's automated meal assembly systems are compressing labor costs for full-service carriers commissioning chef-designed menus. The Civil Aviation Authority of Singapore enforces strict cold-chain documentation standards aligned with FDA-equivalent benchmarks. The Changi East development zone is expanding dedicated catering infrastructure to support premium cabin growth on long-haul Asia-Europe routes.
Japan
Full-service carriers in Tokyo and Osaka are differentiating through authentic regional cuisine sourcing from independent culinary studios. Japan's Ministry of Health, Labour and Welfare maintains pharmaceutical-grade hygiene standards for in-flight food production. The Kansai Airport cluster is developing specialized facilities for allergen-restricted meal preparation with segregated production lines.
Germany
Lufthansa's procurement teams are consolidating supplier relationships with packaging producers certifying full lifecycle carbon accounting under EU Green Deal mandates. The German Federal Office of Consumer Protection and Food Safety enforces fifty-five percent recyclable content requirements in single-use food service items by 2030. The Frankfurt Airport logistics zone is transitioning production facilities to biodegradable tray materials derived from agricultural waste fibers.
Vietnam
Secondary airports in Hanoi and Ho Chi Minh City lack dedicated flight kitchens, creating demand for mobile production units serving low-cost carrier route expansion. The Vietnam Food Administration applies HACCP protocols adapted from Codex Alimentarius standards. The Long Thanh airport development is attracting first-mover catering operators to establish regional production capacity ahead of 2025 hub opening.
In-Flight Catering Services Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale operators capturing volume from distributed networks as hub airport expansion concentrates procurement power. The market structure reflects capital-intensity divergence between centralized flight kitchens and regional suppliers, rotating advantage toward operators with airport-adjacent production facilities. Three strategic archetypes dominate: vertically integrated hub operators, technology-led automation specialists, and remote-location mobile caterers. Competitive moves center on M&A consolidation in Gulf markets and strategic partnerships for sustainable packaging certification.
Among the integrated tier, Gate Gourmet and SATS Ltd exemplify divergent scale strategies, with the former anchoring cost leadership through airport-adjacent vertical integration and the latter representing technology-led automation at major Asian hubs. Newrest occupies a distinct position specializing in remote-location catering that extends service reach beyond centralized infrastructure. These three operators collectively illustrate how geographic specialization and production model differentiation are reshaping contract capture across hub and secondary airport networks.
| Leading Market Players |
|---|
| Newrest |
| Do & Co |
| Dnata |
| Saudi Airlines Catering |
| Flying Food Group |
| Gate Gourmet |
| SATS Ltd |
| Servair |
| LSG Sky Chefs |
| Others |
Supply Flow & Price Mechanics
HACCP certification protocols gate both supplier qualification and price differentiation simultaneously, as airlines tier procurement contracts based on cold-chain compliance maturity rather than volume scale alone. Full-service carriers in Singapore and Japan pay premiums for chef-designed menu commissioning, while low-cost operators in Southeast Asia compress margins through standardized snack-service specifications.
Pricing Analysis
Long-term offtake contracts dominate procurement between centralized flight kitchens and full-service carriers, locking in eighteen-to-twenty-four month price commitments against jet fuel volatility. Price differentiation hinges on HACCP certification tier and geographic delivery cost to hub versus secondary airports. Cost compression in economy catering intensifies as low-cost carriers unbundle meal specifications from legacy bundled service contracts. Charter services and cargo carriers exhibit highest price sensitivity; private jet operators show lowest.
Supply Chain Analysis
The United Arab Emirates and Singapore anchor centralized flight kitchen production, supplying hot entree assemblies to Gulf and Asia-Pacific hub airports. Raw material flows draw from poultry and beef supply chains in Australia and New Zealand, biodegradable tray materials from agricultural waste fiber processors in Germany, and specialized ethnic cuisine ingredients from independent Middle Eastern culinary studios. Single-source vulnerability concentrates in the three Dubai-Abu Dhabi kitchens controlling sixty percent of regional capacity. Distribution runs through airport-adjacent production facilities with direct tarmac loading protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as airline procurement teams disintermediate traditional full-service caterers, creating niches for specialized ethnic cuisine producers and sustainable packaging specialists.
For Market Incumbents: Fortify HACCP certification depth against emerging biopolymer packaging specialists who lack aviation-sector audit experience. Expand airport-adjacent production capacity in the Vietnam-Indonesia corridor before mobile production units capture low-cost carrier volume. Defend margin position by consolidating chef-designed menu commissioning relationships with Singapore and Japan full-service carriers. For New Entrants and Emerging Players: MOHAP fast-track certification in the United Arab Emirates opens procurement access to Emirates and Etihad premium cabin programs. Target secondary airports in Vietnam and Indonesia where dedicated flight kitchen infrastructure gaps persist. Enter through plant-based protein integration partnerships with European carriers responding to EU Green Deal sustainability mandates. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated meal assembly system deployment, favoring technology-led operators over labor-dependent regional suppliers. Acquisition target archetype: mid-scale caterers with established HACCP documentation and underutilized capacity in Southeast Asian growth corridors. Signal to watch: blockchain traceability adoption rates among premium cabin carriers as premium pricing enabler.| Strategic Initiative | Industry Significance |
|---|---|
| HACCP Certification Investment | MOHAP and FDA-equivalent protocols unlock airline contract eligibility across Gulf and Asia-Pacific hubs. |
| Automated Production Scale-Up | Robotics integration at Changi Airport compresses labor costs and contamination risk for high-volume cycles. |
| Sustainable Packaging Transition | EU Green Deal fifty-five percent recyclable mandates force material shifts that favor certified lifecycle carbon accounting. |
| Remote-Location Catering Expansion | Mobile production units capture first-mover advantage in Vietnam and Indonesia secondary airport networks. |
| Blockchain Traceability Integration | Distributed ledger systems with cold-chain monitoring enable premium pricing for full-ingredient provenance documentation. |
Methodological Framework
A standing panel of airline procurement directors, flight kitchen operations managers, HACCP certification auditors, and sustainable packaging R&D leads provided ongoing calibration against primary interview data and secondary validation. Bottom-up triangulation combined supplier production capacity disclosures with airline contract award announcements. Secondary sources encompassed MOHAP food safety filings, EU Green Deal packaging waste directive texts, Changi Airport concession agreements, and customs records for biodegradable tray material imports.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation dimensions modeled encompassed service type, client profile, menu composition, packaging format, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to airline passenger volume projections and premium cabin expansion schedules. Forecast inputs included jet fuel price scenarios and HACCP certification timeline assumptions.
Decision-makers should treat outputs as directional under base assumptions of sustained hub airport expansion and stable aviation regulatory frameworks; material deviation in fuel price volatility or certification timeline extension would warrant model refresh. Recalibration cycles align with material shifts in EU packaging mandates and Gulf hub capacity utilization rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
Netherlands Hospitality Industry Market
Accommodation
Canada Hospitality Market
Accommodation
China Tourism and Hotel Market
Accommodation
Hong Kong Hospitality Industry Market
Accommodation
Extended Stay Hotel Market
Accommodation
Asia-Pacific Travel Accommodation Market
Accommodation
China Online Accommodation Market
Accommodation
Japan Online Accommodation Market
Accommodation
India Student Accommodation Market
Accommodation
US Student Accommodation Market
Accommodation
UAE Hospitality Market
Accommodation
Europe Online Accommodation Market
Accommodation
Switzerland Hospitality Market
Accommodation
Russia Online Accommodation Market
Accommodation
Hotel Market
Accommodation
Europe Camping and Caravanning Market