
 Europe Student Accommodation Market | 2026-2036
Europe Student Accommodation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Student Accommodation Market Analysis
A persistent shortage of construction tradespeople and project managers is unwinding development timelines across the sector. Greystar leverages its pan-European platform to secure large-scale development sites in supply-constrained university cities. Xior Student Housing anchors its portfolio in the Benelux and Iberian markets through direct development and forward-funding structures. Unite Students dominates the UK operational landscape with extensive in-house property management capabilities.
Europe student accommodation encompasses purpose-built residential assets designed for enrolled learners, typically featuring individual study bedrooms with shared or private bathroom facilities, communal kitchens, and integrated security systems with electronic access control. These assets serve the core commercial purpose of generating rental income from academic-term leases while providing universities with enrollment-attracting housing infrastructure. Studio configurations within the Property Type dimension command premium rents and attract the highest institutional valuations due to their self-contained format and privacy appeal. Private Hall assets under Facility Type are expanding fastest as universities divest direct housing ownership and outsource to specialized operators. The Price Range segment stratifies sharply, with Luxury and Premium tiers concentrating in London, Paris, and Munich where international student density supports elevated rate structures.
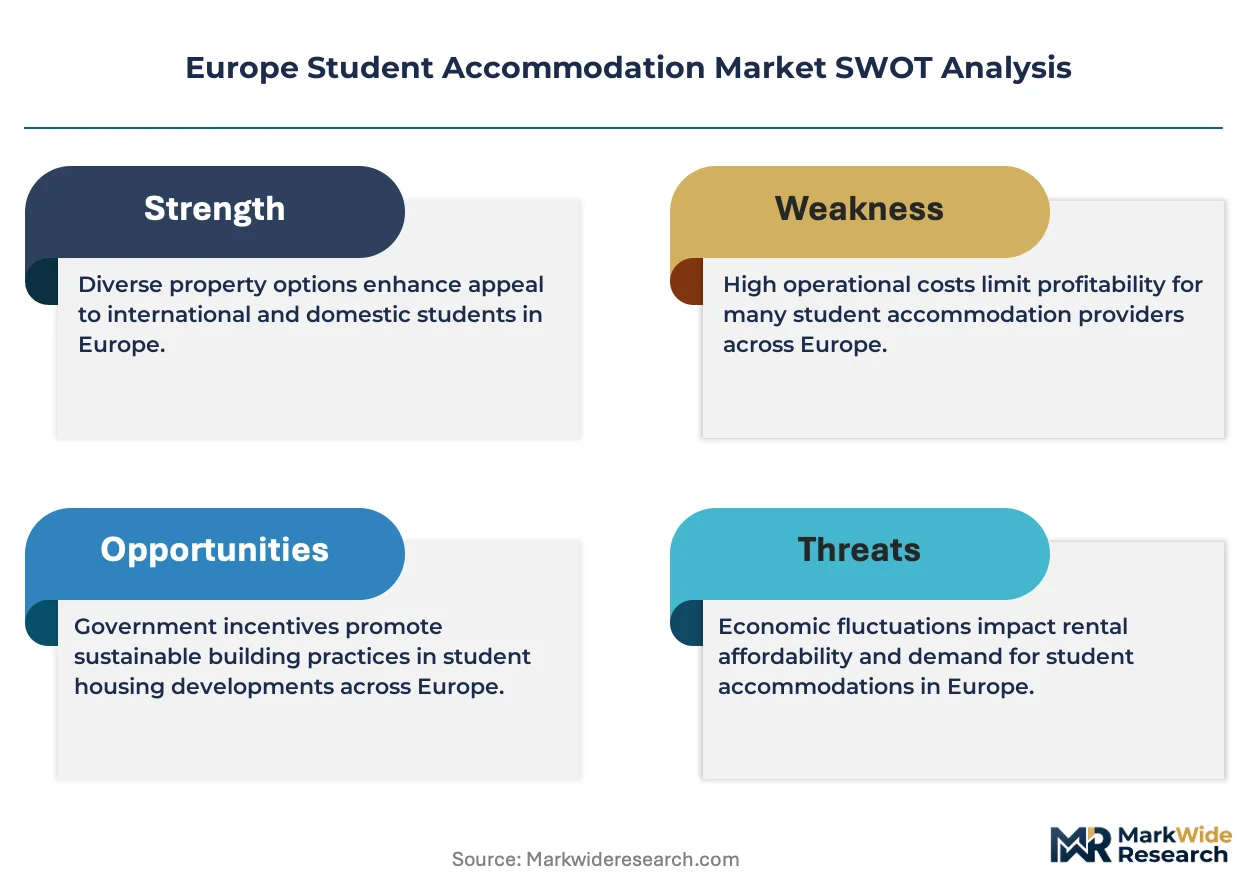
The EU Green Deal and national building codes under EPC frameworks mandate energy efficiency upgrades that retrofitting existing stock must satisfy. REACH regulations govern chemical content in furnishings and construction materials deployed across new-build and refurbished properties. GDPR shapes tenant data handling for digital access systems and online booking platforms operated by housing providers. Stakeholders must track how national rent control variations and student visa policy shifts in key destination countries reshape yield expectations and development feasibility across their European portfolios.
Market Dynamics
The EU Green Deal's building renovation mandates are compressing development timelines across Europe's aging housing stock while institutional capital concentrates in supply-constrained university cities. Operators face simultaneous pressure to decarbonize existing assets and accelerate new-build deliveries.
Growth Catalysts
- Postgraduate Mobility:Non-EU enrollment expansion across the United Kingdom, Germany, and the Netherlands is tightening occupancy rates in Tier-1 cities and supporting rent growth.
- REACH Compliance:Chemical content regulations for furnishings and construction materials are standardizing procurement practices and favoring scaled operators with dedicated compliance functions.
- University Outsourcing:Direct housing divestment by academic institutions is transferring operational risk to specialized private hall operators with pan-European platforms.
Market Restraints
- Construction Labor Scarcity:Persistent shortages of project managers and skilled tradespeople in France, Spain, and Italy are extending development timelines by 18-24 months.
- EPC Retrofit Costs:Energy Performance Certificate upgrades required under national building codes are absorbing capital that would otherwise fund expansion.
- Input Cost Volatility:Steel, timber, and insulation material prices remain sensitive to energy market fluctuations and supply chain disruptions.
Strategic Opportunities
- Benelux Density Gaps:Secondary Belgian and Dutch university cities outside Brussels and Amsterdam offer development sites with limited competing supply.
- Forward-Funding Structures:Institutional investors are pre-committing capital to development pipelines, de-risking construction finance for specialized operators.
- GDPR-Compliant Access Systems:Digital tenant onboarding and biometric entry systems are creating differentiation in security-sensitive parent and international student segments.
Industry Challenges
- Certification Timeline Compression:BREEAM and LEED accreditation processes are extending pre-leasing windows and delaying revenue recognition.
- Integration Complexity:Legacy university housing management systems resist API connectivity with modern revenue management and maintenance platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Student Accommodation Market |
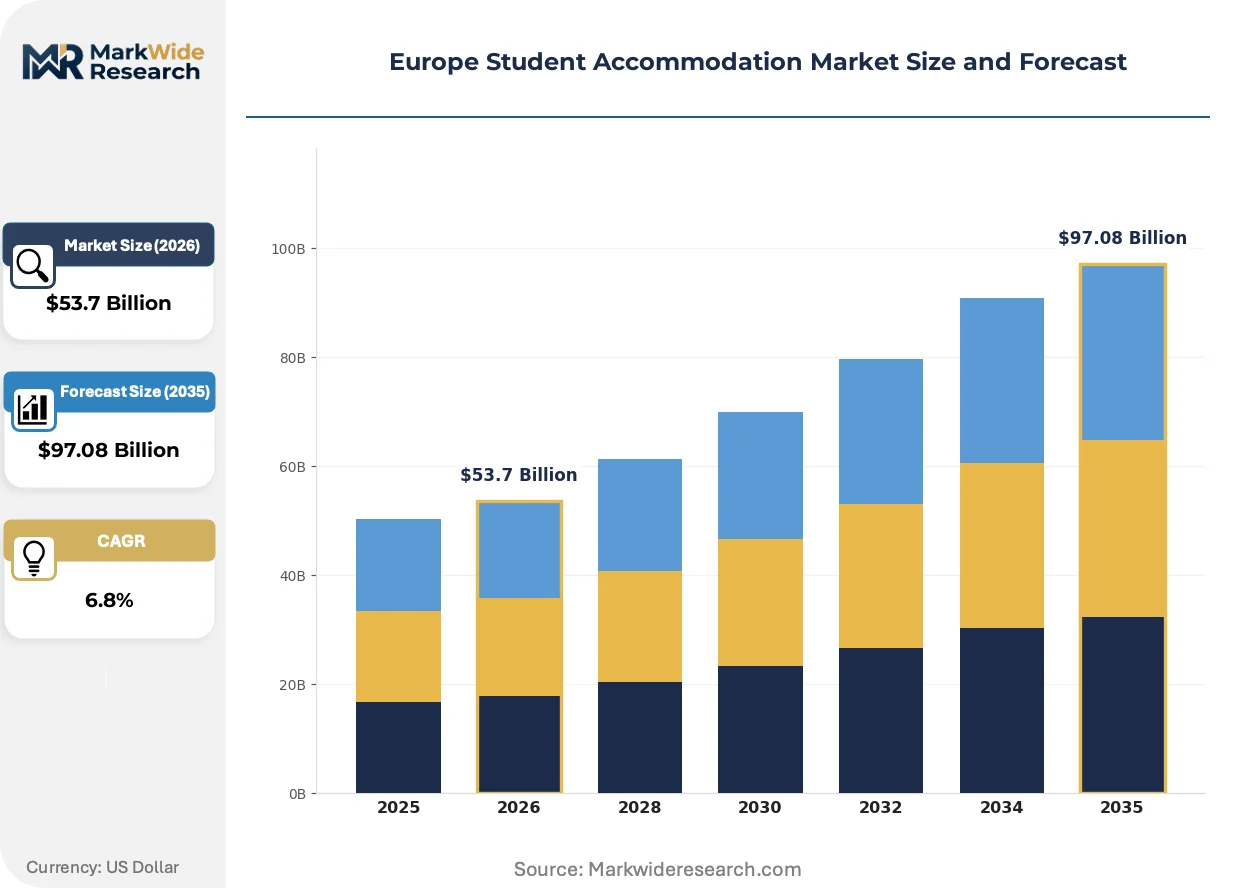
| Market Size in 2026 | $53.7 Billion |
| Market Size in 2035 | $97.08 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Dormitory, Studio, Apartment, Shared Housing Facility Type: Private Hall, University Hall, Homestay, Off-Campus Service Level: Self-Catered, Full Board, Half Board, Flexible Price Range: Budget, Mid-Range, Luxury, Premium |
| Companies Covered | GSA, Xior Student Housing, Unite Students, The Boost Society, Campus Living Villages, iQ Student Accommodation, Scape, Student Roost, Greystar, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Student Accommodation Market Emerging Trajectories
Digital access control and energy management systems are converging with sustainability mandates to reshape asset specifications and operational workflows across European student housing portfolios.
Smart building management platforms integrating HVAC optimization, occupancy sensing, and predictive maintenance are fragmenting the traditional facilities management vendor landscape. Mid-sized operators in Portugal and Poland are adopting cloud-based systems faster than incumbents, compressing the competitive advantage of scale in operational efficiency.
The EU Green Deal's Energy Performance of Buildings Directive is mandating near-zero energy standards for new construction and major renovations by 2030. Developers in London, Berlin, and Munich are pre-emptively specifying heat pumps and photovoltaic arrays to secure planning permissions, accelerating capital deployment into higher-specification assets.
Parent and international student segments are prioritizing self-contained studio configurations with private kitchen and bathroom facilities over traditional shared-flat formats. This preference shift is visible most acutely in London and Paris, where operators are reconfiguring development pipelines toward smaller unit footprints and premium rate structures.
Europe Student Accommodation Market Segmentation
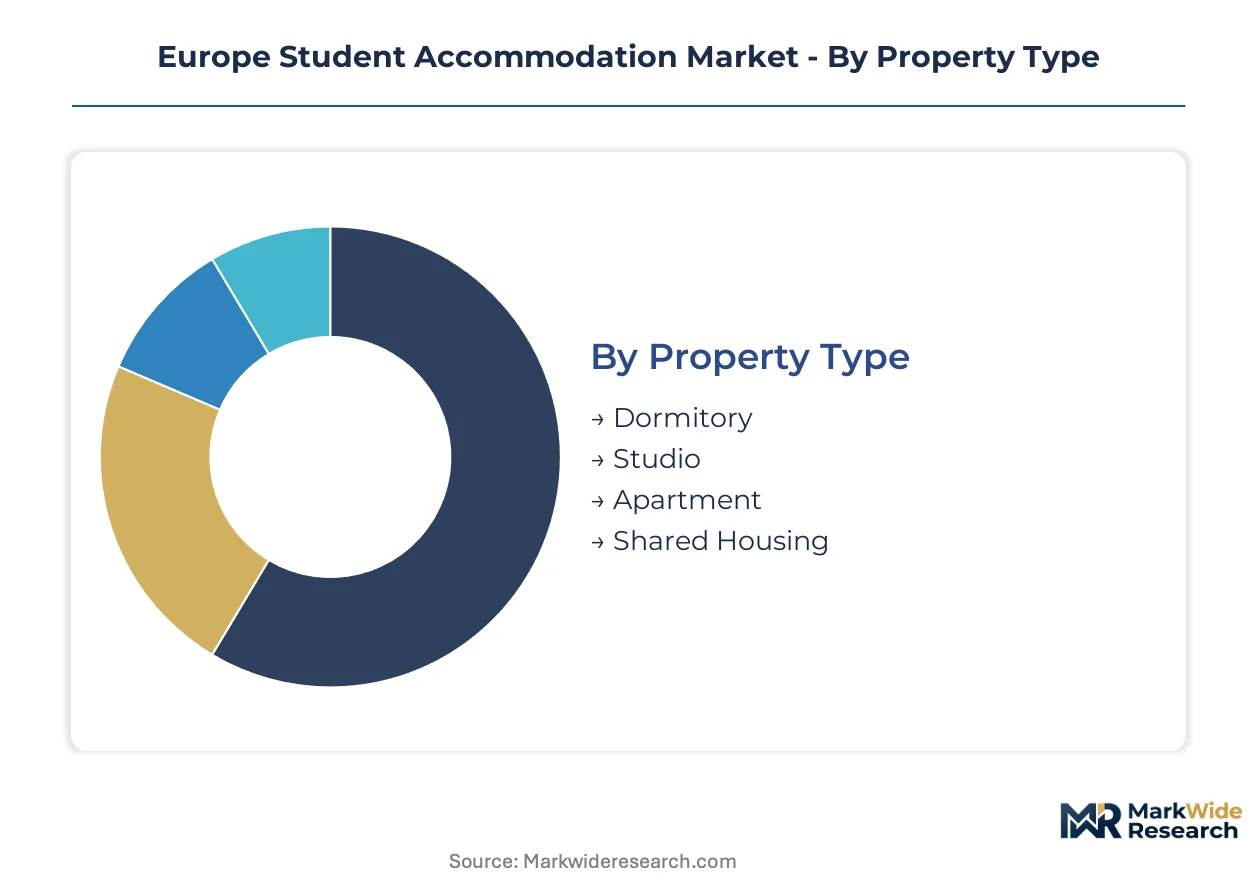
Segmentation in European student housing reveals how capital allocation and rental yield diverge across product configurations. Understanding these divisions exposes where institutional investors concentrate versus where operational complexity escalates.
Property Type:
Margin pools concentrate in configurations that minimize shared infrastructure while maximizing rent per square meter.
- Studio:Self-contained units with private kitchen and bathroom facilities command the highest rent premiums across London, Paris, and Munich. International postgraduate demand in these cities sustains occupancy rates above traditional shared formats.
- Apartment:Multi-bedroom configurations with shared common areas balance density against privacy expectations. German and Dutch university cities favor this format for its blend of social infrastructure and operational efficiency at scale.
- Dormitory:Traditional corridor-style layouts with shared facilities dominate legacy university portfolios across Southern Europe. Capital requirements for refurbishment to modern standards often exceed replacement economics.
- Shared Housing:Converted residential properties in supply-constrained markets like Dublin and Edinburgh fill gaps where purpose-built stock lags enrollment growth. Regulatory compliance with HMO standards varies sharply across national jurisdictions.
Studio holds installed capacity. Apartment is rotating up the share rankings.
Facility Type:
Operational risk transfer from universities to specialized operators is reconfiguring facility ownership structures.
- Private Hall:Purpose-built assets owned and operated by specialized housing providers with pan-European platforms. These facilities integrate professional revenue management and maintenance systems that university legacy operations cannot replicate.
- University Hall:Institution-owned stock faces capital renewal backlogs across the United Kingdom and Italy. Divestment pressures are accelerating as balance sheet constraints collide with Green Deal retrofit mandates.
- Off-Campus:Privately owned residential properties marketed to students through online platforms. Spanish and Portuguese cities see rapid expansion here where planning restrictions limit purpose-built development.
- Homestay:Family-hosted arrangements concentrated in language-study and short-term mobility programs. This segment carries minimal capital intensity but scales poorly for institutional capital deployment.
Private Hall captures the yield compression. Off-Campus is climbing the fastest.
Service Level:
Cost tier differentiation separates operational models requiring fixed labor commitments from variable-cost structures.
- Self-Catered:Kitchen-equipped units without meal provision dominate new-build pipelines across Northern Europe. Students accept lower base rents in exchange for flexible dining budgets.
- Full Board:Comprehensive meal plans integrated into rental contracts persist in traditional collegiate systems. Oxford and Cambridge colleges maintain this model, though capital intensity limits replication.
- Half Board:Breakfast-inclusive arrangements with optional evening meals suit mid-market positioning in Belgian and French markets. Operational complexity sits between fixed and variable cost extremes.
- Flexible:Modular meal credit systems and partnership arrangements with food service operators. This emerging configuration targets international students unfamiliar with local grocery infrastructure.
Self-Catered anchors development pipelines. Flexible is gaining share fastest.
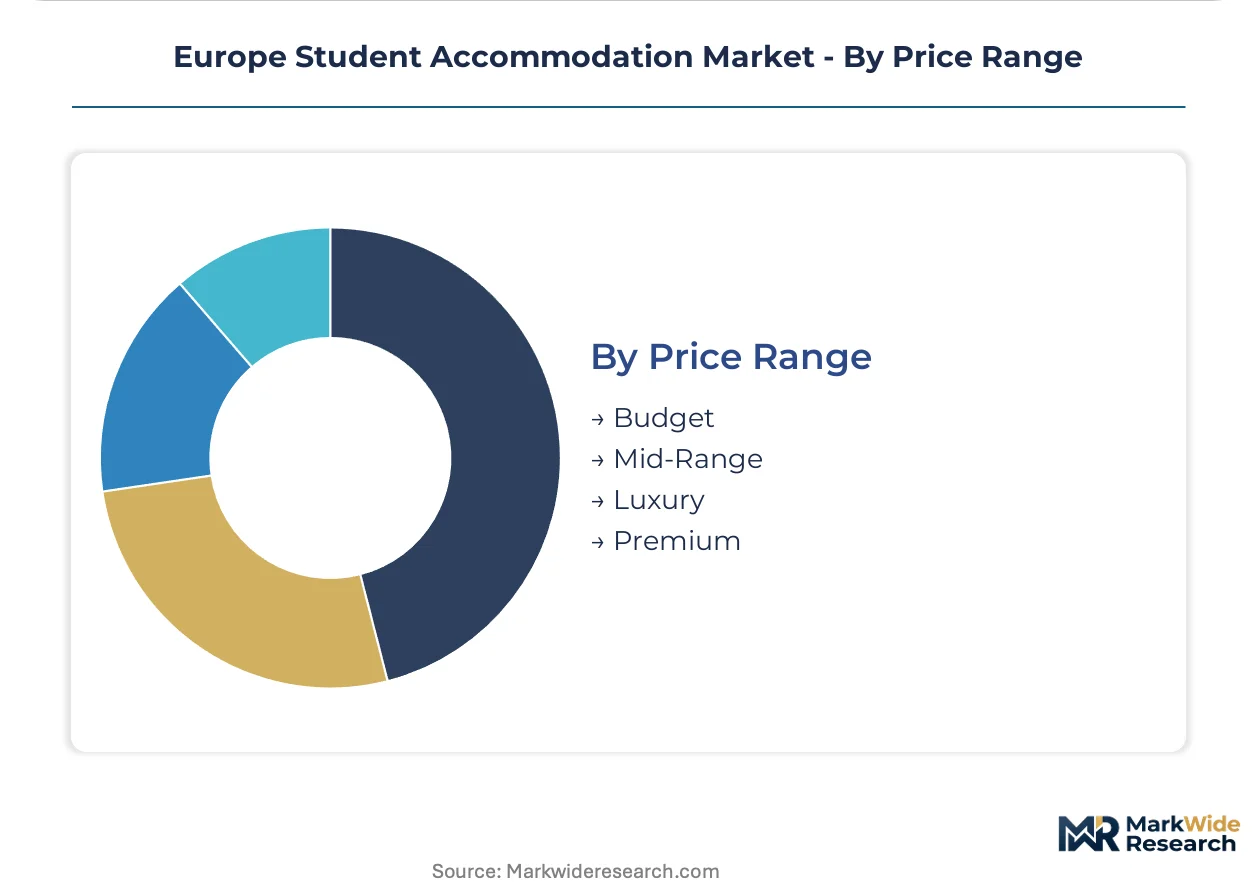
Price Range:
Geographic concentration of international enrollment determines where premium rate structures clear cost thresholds.
- Premium:Top-tier finishes, central locations, and concierge services in London, Amsterdam, and Zurich. Parent-funded international students sustain rate levels that justify development premiums.
- Luxury:High-specification assets with amenities including gyms, cinema rooms, and co-working spaces. Berlin and Vienna see concentrated development here as institutional capital seeks defensive yield.
- Mid-Range:Standardized specifications meeting modern building codes without amenity premiums. This tier fills supply gaps in secondary Dutch and German cities where development costs constrain premium positioning.
- Budget:Basic accommodations with shared facilities and minimal common area investment. Eastern European markets and peripheral Spanish cities concentrate this segment where local purchasing power caps rate structures.
Premium holds pricing power. Mid-Range is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal building renovation mandates anchor the regulatory framework across Europe's dominant student housing geographies. National EPC frameworks and REACH compliance requirements are reshaping capital deployment patterns from London to Berlin.
United Kingdom
Postgraduate enrollment from India and Nigeria is tightening occupancy rates in London, Manchester, and Edinburgh. The UK's Energy Performance Certificate regulations mandate minimum efficiency standards for private rental stock by 2030. Unite Students and iQ Student Accommodation dominate operational scale across these university clusters.
Germany
Rising non-EU enrollment at Technical University of Munich and Humboldt University of Berlin is outpacing purpose-built supply. The German Building Energy Act (GEG) imposes stringent thermal insulation requirements on new construction and major renovations. Greystar secures development sites in Munich and Frankfurt through forward-funding structures with institutional investors.
Netherlands
International student inflows to University of Amsterdam and Delft University of Technology are compressing vacancy rates below historical averages. The Dutch Environmental Management Act integrates EU Green Deal standards into municipal planning permissions. Xior Student Housing anchors portfolio density in Eindhoven and Rotterdam through direct development pipelines.
France
Grandes écoles in Paris and Lyon are expanding English-taught programs to attract Asian and African enrollment. The RE2020 environmental regulation mandates carbon performance thresholds for new residential construction. Scape and Campus Living Villages target Parisian development opportunities where planning restrictions limit competing supply.
Spain
Language-study and Erasmus mobility programs are driving seasonal demand peaks in Barcelona and Madrid. The Spanish Technical Building Code (CTE) aligns with EU energy efficiency directives for thermal envelope standards. Student Roost and The Boost Society evaluate Madrid expansion where off-campus residential conversions fill purpose-built development gaps.
Europe Student Accommodation Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in Europe's student housing structure. Pan-European platforms with in-house development, operations, and capital-raising capabilities command institutional capital flows. Specialist operators concentrate in single-country markets or niche product configurations. Competitive positioning depends on securing supply-constrained university city sites and executing forward-funding partnerships with pension funds and sovereign wealth vehicles.
Within the integrated platform tier, Greystar and Unite Students exemplify scale-driven operational models spanning multiple jurisdictions. Xior Student Housing occupies a position as a Benelux-Iberia specialist with concentrated geographic density. These three entities represent distinct archetypes: the global capital deployer, the national operational incumbent, and the regional development specialist.
| Leading Market Players |
|---|
| GSA |
| Xior Student Housing |
| Unite Students |
| The Boost Society |
| Campus Living Villages |
| iQ Student Accommodation |
| Scape |
| Student Roost |
| Greystar |
| Others |
Supply Flow & Price Mechanics
Forward-funding development contracts with institutional investors lock in construction cost visibility and rental rate floors across supply-constrained university cities. These structures transfer delivery risk to specialized operators while securing capital commitments before steel and timber procurement begins.
Pricing Analysis
London commands rent premiums triple those of secondary Dutch cities, with studio configurations in Amsterdam and Munich occupying intermediate positions. Three-tier pricing structure across premium, standard, and economy levels segments sharply by international student density and proximity to elite institutions. Pricing pressure stems from construction labor scarcity extending delivery timelines and compressing developer margins. Budget-tier students in Eastern European markets exhibit highest price sensitivity, while parent-funded postgraduates in London show least elasticity.
Supply Chain Analysis
Extended lead times for heat pumps and photovoltaic arrays now stretch 14-18 months across Northern European markets. Manufacturing concentrates in Germany, Poland, and China for HVAC components, with timber framing sourced from Scandinavian and Baltic suppliers. Single-source vulnerability runs through Chinese-manufactured smart access control systems. Distribution runs through pan-European procurement platforms serving consolidated operator networks rather than fragmented university purchasing departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's 2030 near-zero energy mandate for new construction disrupts legacy development economics and rewards early compliance investment. This regulatory inflection compresses timelines for asset refurbishment and redirects capital toward higher-specification pipelines.
For Market Incumbents: Shield portfolio yields by accelerating EPC retrofit programs ahead of enforcement deadlines. Backward integration into dedicated construction crews mitigates project manager scarcity threatening delivery schedules. Prioritize BREEAM pre-certification to compress pre-leasing windows and secure institutional capital commitments.
For New Entrants and Emerging Players: BREEAM accreditation fast-tracks access to forward-funding structures from pension funds and sovereign wealth vehicles. Secondary Belgian university cities outside Brussels offer penetrable development sites with limited competing supply. Partner with municipal planning departments early to secure permissions before Green Deal standards tighten.
For Investors and Strategic Acquirers: Capital is best deployed toward regional specialists with concentrated Benelux-Iberia density and proven development execution. Long-term viability hinges on operators who control land pipelines in supply-constrained cities rather than those dependent on third-party site acquisition. Watch for inflection when national student visa policy shifts alter enrollment composition in key destination markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Certification Pre-Commitment | BREEAM accreditation secures planning permissions and institutional capital in Berlin and Munich. |
| Forward-Funding Partnership | Pre-committed development pipelines de-risk construction finance for specialized operators. |
| Smart Access System Integration | GDPR-compliant biometric entry differentiates assets for security-sensitive international segments. |
| Secondary City Expansion | Development in Eindhoven and Rotterdam captures enrollment growth with limited competing supply. |
| University Outsourcing Capture | Operational risk transfer from divesting institutions expands addressable market for private hall operators. |
Methodological Framework
Operator-level perspectives from student housing developers, university estate directors, institutional investment officers, and facilities management vendors anchored the qualitative base. Primary interviews combined with secondary validation from EU building energy directive filings, national EPC registry data, university enrollment statistics, and REACH compliance documentation. Bottom-up unit economics triangulated against top-down capital deployment tracking across pan-European portfolios.
Sensitivity analysis tested enrollment volatility, construction cost inflation, and regulatory timeline acceleration across the projection horizon. Segmentation dimensions modeled include property type, facility ownership structure, service level configuration, and price tier positioning. CAGRs derived from fitted growth curves incorporating pipeline delivery schedules and occupancy rate assumptions. Forecast inputs incorporated EU Green Deal implementation variance and national student visa policy trajectories.
Underlying assumptions cover sustained non-EU postgraduate mobility, construction labor market tightness, and EPC enforcement adherence, with deviation risk concentrated in immigration policy shifts and energy input cost volatility. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
France Online Accommodation Market
Accommodation
Youth Summer Camp Market
Accommodation
Asia-Pacific Travel Accommodation Market
Accommodation
Germany Student Accommodation Market
Accommodation
Italy Online Accommodation Market
Accommodation
United Kingdom Hospitality Market
Accommodation
US Recreational and Vacation Camp Market
Accommodation
Movie Theaters Market
Accommodation
Switzerland Hospitality Market
Accommodation
Japan Online Accommodation Market
Accommodation
France Hospitality Market
Accommodation
Sri Lanka Hospitality Industry Market
Accommodation
China Tourism and Hotel Market
Accommodation
India Student Accommodation Market
Accommodation
In-Flight Catering Services Market
Accommodation
India Online Accommodation Market