
 Sri Lanka Hospitality Industry Market | 2026-2036
Sri Lanka Hospitality Industry Market Size, Share, and Industry Trends Forecast 2026-2036
Sri Lanka Hospitality Industry Market Insights
Ancillary wellness and Ayurveda retreat revenue is tilting margin pools away from pure accommodation toward experiential packages. Jetwing Hotels PLC leverages its vertical integration into sustainable architecture and community-based tourism to sustain premium positioning across multiple coastal properties. Cinnamon Hotels & Resorts anchors its competitive stance through heritage property restoration and culinary programming that differentiates its urban and beachfront portfolios. Aitken Spence Hotels competes via diversified geographic coverage spanning Sri Lanka, the Maldives, and Oman, while Hilton Sri Lanka controls brand standards and loyalty distribution in the Colombo luxury segment.
The Sri Lanka hospitality industry encompasses lodging, food and beverage service, and guest experience management delivered through properties ranging from boutique villas to integrated resorts, typically operating on asset-light or managed-contract models with 15-40% food and beverage contribution to total revenue. The sector's primary commercial purpose centers on capturing foreign exchange inflows through visitor spending while generating direct and indirect employment across rural and urban economies. Hotels and resorts occupy the dominant revenue position within service type segmentation, though homestays are recording faster volume expansion as digital platforms reduce entry barriers for property owners. Luxury pricing tier properties command disproportionate margin contribution relative to room inventory share, while online travel agents now intermediate a majority of international bookings and reshape direct channel economics for branded operators.
The Sri Lanka Tourism Development Authority enforces resort classification and environmental compliance standards that shape capital deployment decisions for new developments. BIS-aligned fire safety and building codes, alongside coastal conservation regulations administered by the Central Environmental Authority, constrain permissible construction zones and elevate project approval timelines. Stakeholders must monitor regulatory clarity on leasehold structures for foreign investors and evolving sustainability disclosure requirements that will influence access to international green financing instruments.
Market Dynamics
The Sri Lanka hospitality sector is experiencing a fundamental recomposition as coastal conservation regulations administered by the Central Environmental Authority compress developable land supply while simultaneously elevating capital requirements for new projects. This regulatory tightening is forcing incumbent operators toward asset-light expansion models and experiential programming to sustain returns without proportional room inventory growth.
Growth Catalysts
- Sri Lanka Tourism Development Authority licensing reforms:Streamlined resort classification procedures are reducing approval timelines for heritage property conversions, unlocking premium inventory in Galle Fort and colonial districts.
- Wellness tourism demand:International visitor spending on Ayurveda retreat packages is expanding revenue per available room beyond traditional accommodation metrics.
- Digital platform penetration:Online travel agents are democratizing market access for boutique villa operators along the southern coastal belt from Galle to Hambantota.
Market Restraints
- Coastal construction moratoria:Central Environmental Authority buffer zone restrictions are eliminating beachfront development sites in high-demand districts, concentrating competition for grandfathered properties.
- Imported equipment dependency:Fire safety and building code compliance under BIS-aligned standards requires foreign-sourced materials, exposing project budgets to currency volatility.
- Leasehold uncertainty:Ambiguity in foreign investor lease structures is constraining capital deployment from institutional hospitality funds.
Strategic Opportunities
- Inland heritage circuits:Underdeveloped cultural tourism infrastructure in Anuradhapura and Polonnaruwa offers first-mover positioning for experiential lodge concepts.
- Green financing access:Evolving sustainability disclosure requirements will qualify compliant operators for international green bond markets at preferential rates.
- Community-based tourism integration:Partnership models with rural cooperatives in the hill country enable authentic programming that commands rate premiums from European source markets.
Industry Challenges
- Skilled culinary and wellness practitioner shortages:Traditional Ayurveda therapy training pipelines cannot satisfy resort expansion plans, forcing operators into expensive expatriate recruitment.
- Legacy property retrofit complexity:Heritage building conversions must reconcile authentic restoration with modern fire safety and accessibility codes, extending project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sri Lanka Hospitality Industry Market |
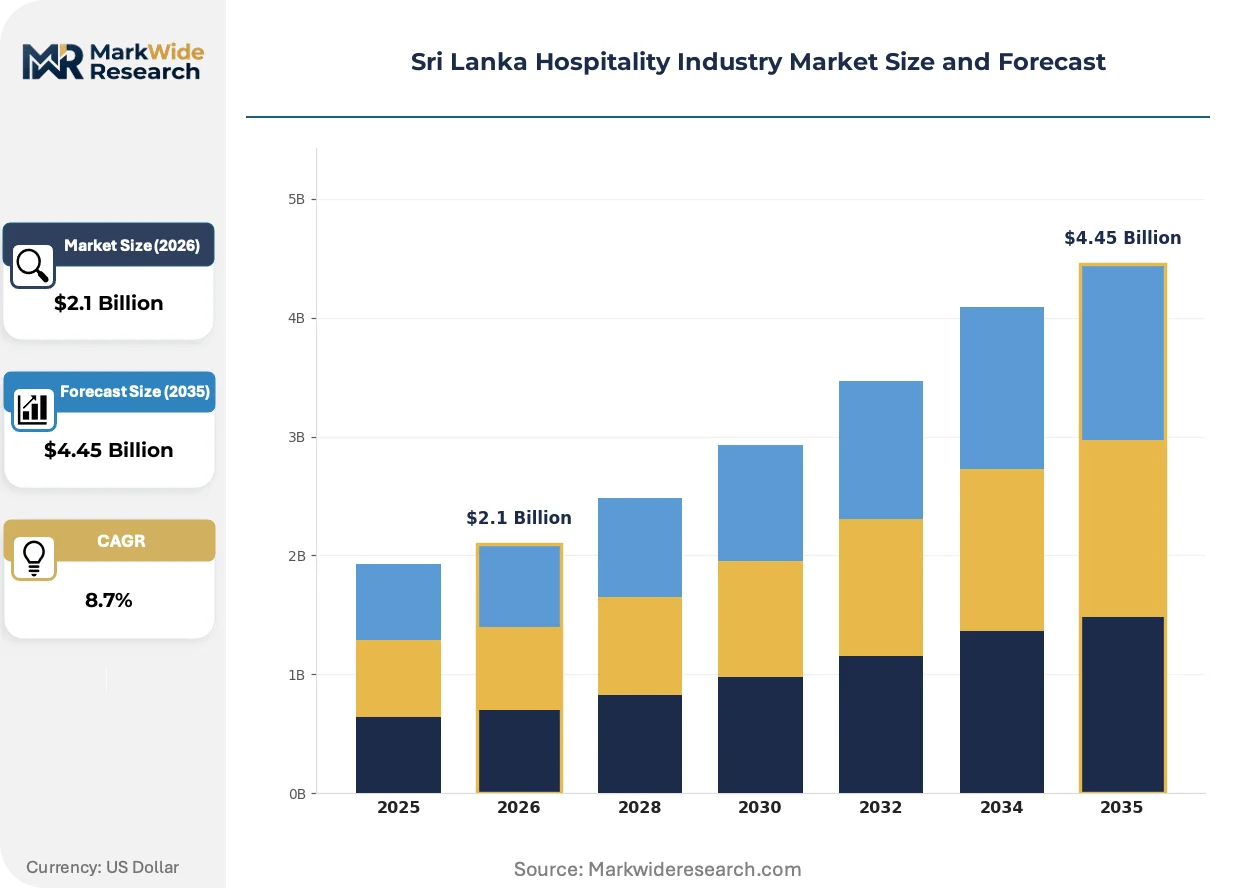
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Hotels, Resorts, Guesthouses, Homestays Customer Type: Business Travelers, Tourists, Local Residents, Event Organizers Pricing Tier: Luxury, Mid-Range, Budget, Economy Distribution Channel: Direct Booking, Online Travel Agents, Travel Agencies, Corporate Partnerships |
| Companies Covered | Jetwing Hotels PLC, Cinnamon Hotels & Resorts, Aitken Spence Hotels, Hilton Sri Lanka, Minor Hotels, Renuka City Hotels, Renuka Hotels, Eden Hotel Lanka, TAL Lanka Hotels, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sri Lanka Hospitality Industry Market Trends and Innovations
Technology is virtualizing guest service delivery while regulatory pressure intensifies around environmental compliance, and procurement behavior is fragmenting as direct booking channels lose share to platform intermediaries. These shifts are compressing margin structures and redefining competitive differentiation beyond physical asset quality.
Property management systems with integrated revenue optimization are virtualizing front-desk operations and concierge functions. Mid-scale operators in Colombo and beachfront districts are adopting cloud-based platforms fastest, displacing legacy on-premise installations. This technology is virtualizing service labor requirements while enabling dynamic pricing granularity that was previously accessible only to international flagged properties.
The Sri Lanka Tourism Development Authority is tightening environmental audit protocols for resort license renewals, mandating wastewater treatment and renewable energy thresholds. Properties in the southern coastal belt face the steepest compliance curves given sensitive marine ecosystems. Operators are responding by retrofitting solar arrays and captive water recycling systems to preempt enforcement action and qualify for green certification tiers.
Corporate and leisure travelers are consolidating booking activity through online travel agents, compressing direct channel economics for branded operators. This concentration is forcing heritage properties and boutique villas into platform dependency, eroding guest relationship data ownership. The shift is most pronounced in European source markets where package tourism intermediaries dominate Sri Lanka destination marketing.
Sri Lanka Hospitality Industry Market Segmentation
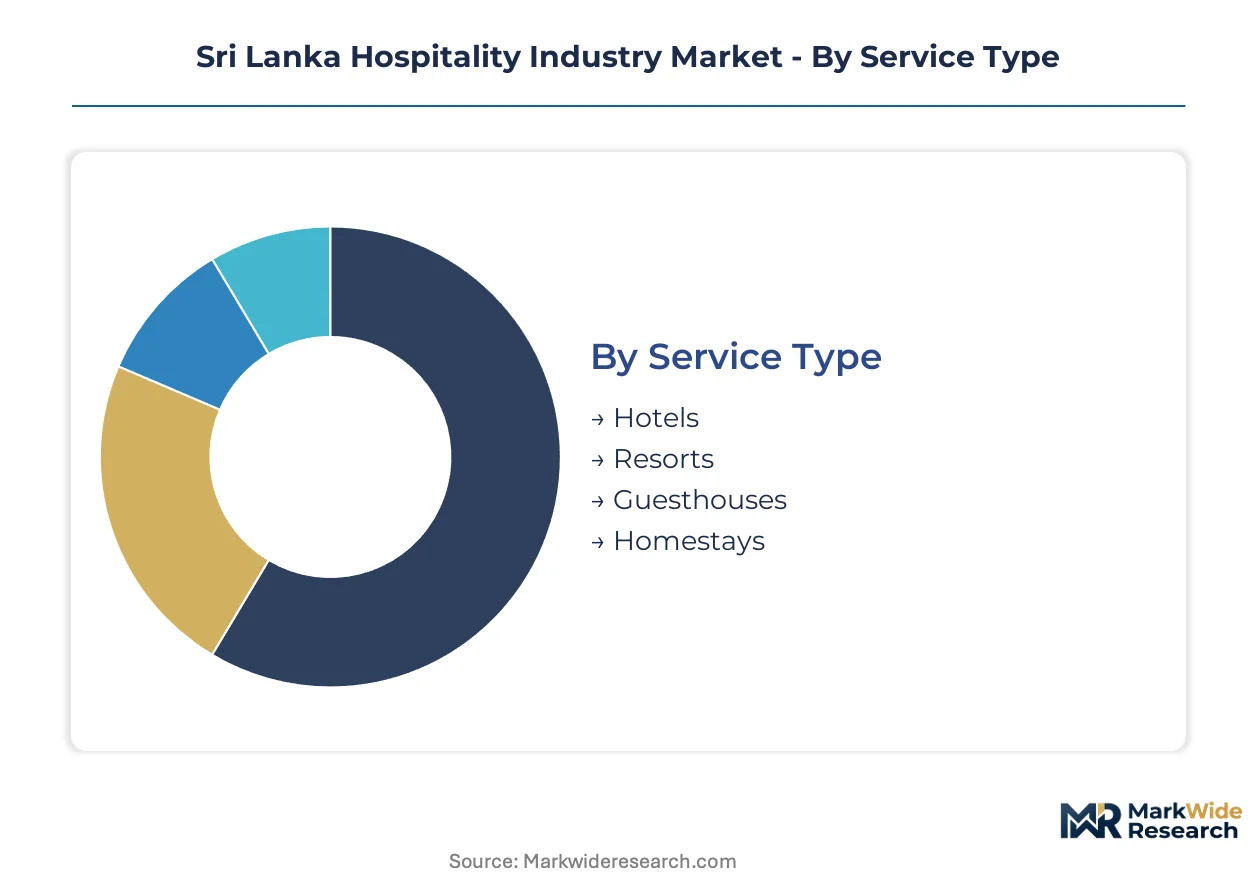
Sri Lanka's hospitality market fragments across service models with starkly divergent capital cycles and margin structures. Understanding these segment boundaries reveals why operators are shifting inventory mix toward experiential formats despite longer payback periods.
Service Type:
Guest turnover velocity varies dramatically across these formats, with beachfront resorts cycling inventory slowest due to extended-stay programming while urban hotels turn rooms fastest.
- Hotels:Full-service properties in Colombo and Kandy deliver standardized accommodation with food and beverage operations. International chains dominate the capital's corporate segment, though local operators capture wedding and pilgrimage traffic in secondary cities. The Sri Lanka Tourism Development Authority classifies these properties through a star-rating system that shapes rate positioning and tax treatment.
- Resorts:Integrated coastal properties along the southern belt from Galle to Hambantota combine accommodation with wellness, dining, and activity programming. Central Environmental Authority buffer zone restrictions have frozen new beachfront supply, concentrating competition for grandfathered sites with captive water access. These assets command the longest average guest stays and highest ancillary spend per night.
- Guesthouses:Small-scale properties typically family-operated with under twenty rooms, concentrated in hill country tea districts and cultural triangle towns. Anuradhapura and Sigiriya host dense clusters serving backpacker and independent traveler segments through direct booking relationships.
- Homestays:Residential properties monetizing spare capacity through digital platform listings. Online travel agents have collapsed entry barriers, enabling rapid supply expansion in Galle Fort and Mirissa without formal licensing compliance. These units turn fastest but suffer highest cancellation volatility.
Hotels anchor the volume base while homestays gain share at the steepest rate.
Customer Type:
Revenue stability correlates inversely with booking lead time, with corporate contracts delivering predictable occupancy against the spot-market volatility of leisure tourism.
- Business Travelers:Colombo-centric demand from banking, apparel export, and IT services sectors. Properties near the World Trade Center and Colombo Port City capture weekday premium rates, though weekend compression requires aggressive discounting to leisure segments.
- Tourists:International leisure visitors from Western Europe, India, and China drive seasonal occupancy peaks. Heritage circuit travelers in Polonnaruwa and Anuradhapura exhibit longer booking horizons than beach holiday bookers, enabling revenue management precision.
- Local Residents:Domestic weekend and holiday demand concentrates in hill country resorts and coastal properties within three hours of Colombo. Sinhala and Tamil New Year periods generate rate premiums exceeding international source market peaks.
- Event Organizers:Wedding and conference planners contract block inventory with extended cancellation terms. Bentota and Negombo have developed specialized MICE infrastructure serving regional corporate events from India and the Maldives.
Tourists generate the revenue concentration while local residents provide the demand floor during international travel disruptions.
Pricing Tier:
Capital intensity scales non-linearly with tier position, as luxury properties absorb disproportionate land and compliance costs without proportional room count expansion.
- Luxury:Properties commanding rates above three hundred dollars nightly, concentrated in Colombo's Cinnamon Lakeside corridor and boutique conversions within Galle Fort's UNESCO buffer. Heritage restoration requirements and imported finishing specifications extend development timelines.
- Mid-Range:Three and four-star properties serving package tourism intermediaries and independent Indian travelers. Properties in Mirissa and Unawatuna compete on location proximity rather than differentiated programming.
- Budget:Functional accommodation targeting backpacker and volunteer tourism segments. Ella and Arugam Bay host dense clusters with minimal food and beverage capture.
- Economy:Transit-oriented properties near Bandaranaike International Airport and Colombo Fort railway terminus. These assets optimize bed turnover over guest experience investment.
Mid-range properties anchor the room inventory base while luxury tier expansion accelerates most quickly despite regulatory friction.
Distribution Channel:
Channel economics diverge sharply on commission burden and guest data ownership, with direct bookings retaining full margin against platform intermediation costs.
- Direct Booking:Brand.com and telephone reservations preserving rate integrity and guest relationship data. Heritage properties in Galle Fort leverage Instagram and travel blogger content to reduce platform dependency.
- Online Travel Agents:Booking.com, Agoda, and Expedia intermediate the majority of international leisure demand. Commission rates between fifteen and twenty-five percent compress net revenue per room night, particularly for independent operators without chain-scale negotiating leverage.
- Travel Agencies:Traditional tour operators in European source markets contract block inventory with extended payment terms. These relationships provide occupancy certainty at discounted rates during shoulder seasons.
- Corporate Partnerships:Direct contracts with multinational employers and diplomatic missions. Colombo properties serving the port and financial districts secure multi-year rate agreements with volume commitments.
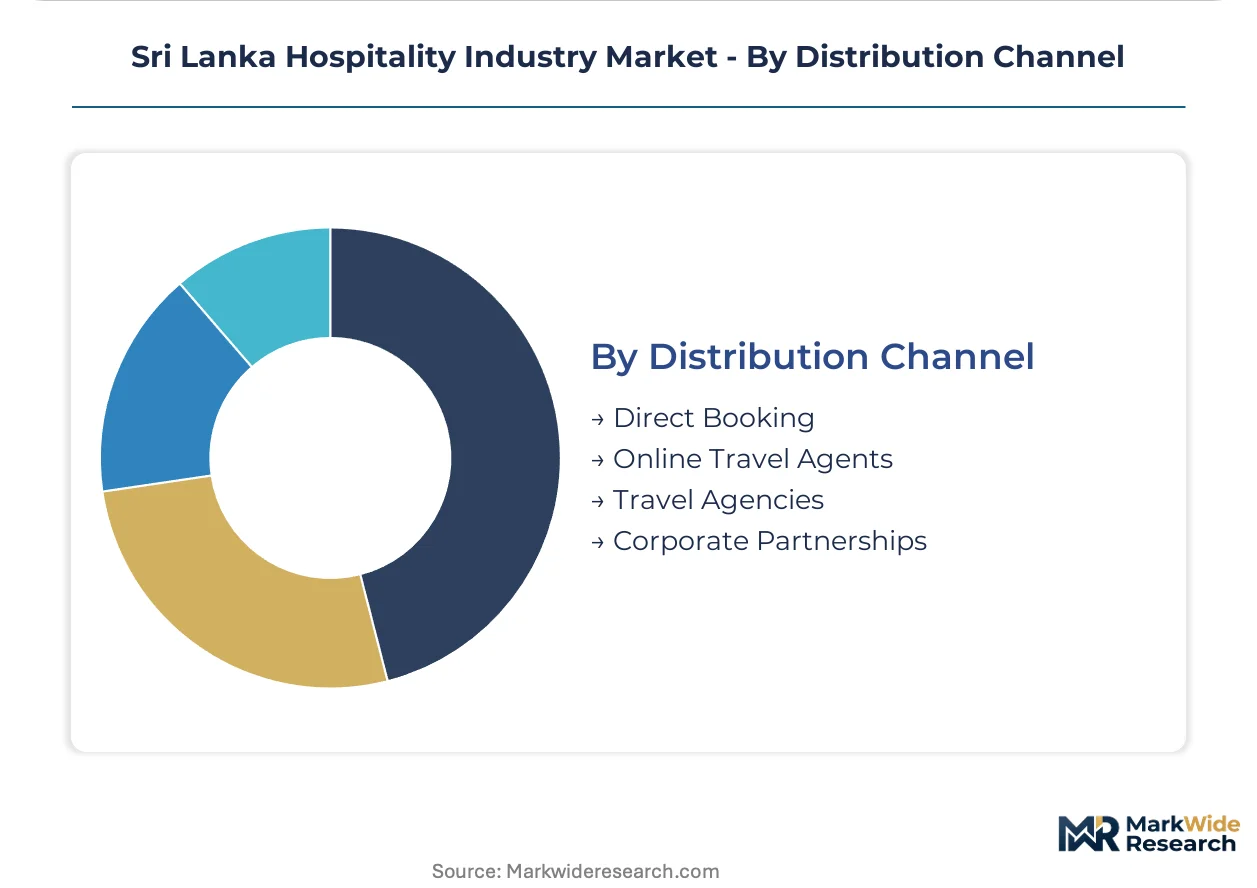
Online travel agents intermediate the transaction volume base while direct booking channels expand most rapidly among heritage and boutique operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Leisure travelers along Sri Lanka's southern coastal belt exhibit the lowest price elasticity, absorbing premium rates for heritage-integrated experiences, while domestic weekend demand in hill country resorts remains highly sensitive to rate fluctuations.
Western Province
Colombo's corporate hospitality segment serves banking, apparel export, and port logistics sectors with weekday premium pricing. The Sri Lanka Tourism Development Authority classifies properties through star-rating protocols that shape tax treatment and rate positioning. Cinnamon Lakeside corridor properties capture diplomatic and multinational contract demand, while Negombo beach clusters specialize in airport-transit and MICE infrastructure.
Southern Province
International leisure demand concentrates along the Galle to Hambantota coastal belt, where heritage property conversions command rate premiums. Central Environmental Authority buffer zone restrictions have frozen new beachfront supply, concentrating competition for grandfathered sites. Jetwing Hotels PLC anchors multiple sustainable properties across this corridor, leveraging vertical integration into community-based tourism programming.
Central Province
Hill country tea district guesthouses serve independent travelers and European wellness tourists with direct booking relationships. Domestic Sinhala and Tamil New Year periods generate rate premiums exceeding international peaks. Kandy's temple corridor properties capture pilgrimage traffic with extended-stay programming, though skilled Ayurveda practitioner shortages constrain retreat expansion plans.
North Central Province
Cultural triangle infrastructure in Anuradhapura and Polonnaruwa remains underdeveloped relative to coastal counterparts, offering first-mover positioning for experiential lodge concepts. Heritage circuit travelers exhibit longer booking horizons than beach holiday bookers. The Sri Lanka Tourism Development Authority is streamlining resort classification procedures to unlock premium inventory in colonial districts.
Eastern Province
Arugam Bay surf tourism and Trincomalee natural harbor traffic drive seasonal occupancy in budget and mid-range segments. Post-conflict infrastructure recovery continues to lag western and southern counterparts. Local resident demand provides floor pricing during international travel disruptions, particularly around domestic holiday periods.
Sri Lanka Hospitality Industry Market Competitive Landscape
Vertically integrated domestic conglomerates and international flagged operators split the market between experiential programming depth and distribution scale. The competitive terrain exhibits moderate concentration, with local heritage specialists commanding premium positioning against global chain standards. Two strategic archetypes dominate: property owners with captive supply chains in sustainable architecture and wellness programming, and asset-light management contractors leveraging international loyalty networks. Portfolio diversification into adjacent geographies and heritage restoration capabilities constitute the dominant competitive moves.
Within the integrated domestic tier, Jetwing Hotels PLC and Cinnamon Hotels & Resorts exemplify contrasting approaches to sustainable positioning. Jetwing anchors its competitive stance through backward integration into community-based tourism and environmental architecture across multiple coastal properties. Cinnamon occupies a position defined by heritage property restoration and differentiated culinary programming spanning urban and beachfront portfolios. Aitken Spence Hotels represents the geographic diversification archetype, with holdings extending beyond Sri Lanka into the Maldives and Oman markets. Hilton Sri Lanka sits within the international flagged tier, controlling brand standards and loyalty distribution in Colombo's luxury segment.
| Leading Market Players |
|---|
| Jetwing Hotels PLC |
| Cinnamon Hotels & Resorts |
| Aitken Spence Hotels |
| Hilton Sri Lanka |
| Minor Hotels |
| Renuka City Hotels |
| Renuka Hotels |
| Eden Hotel Lanka |
| TAL Lanka Hotels |
| Others |
Pricing and Supply Chain Analysis
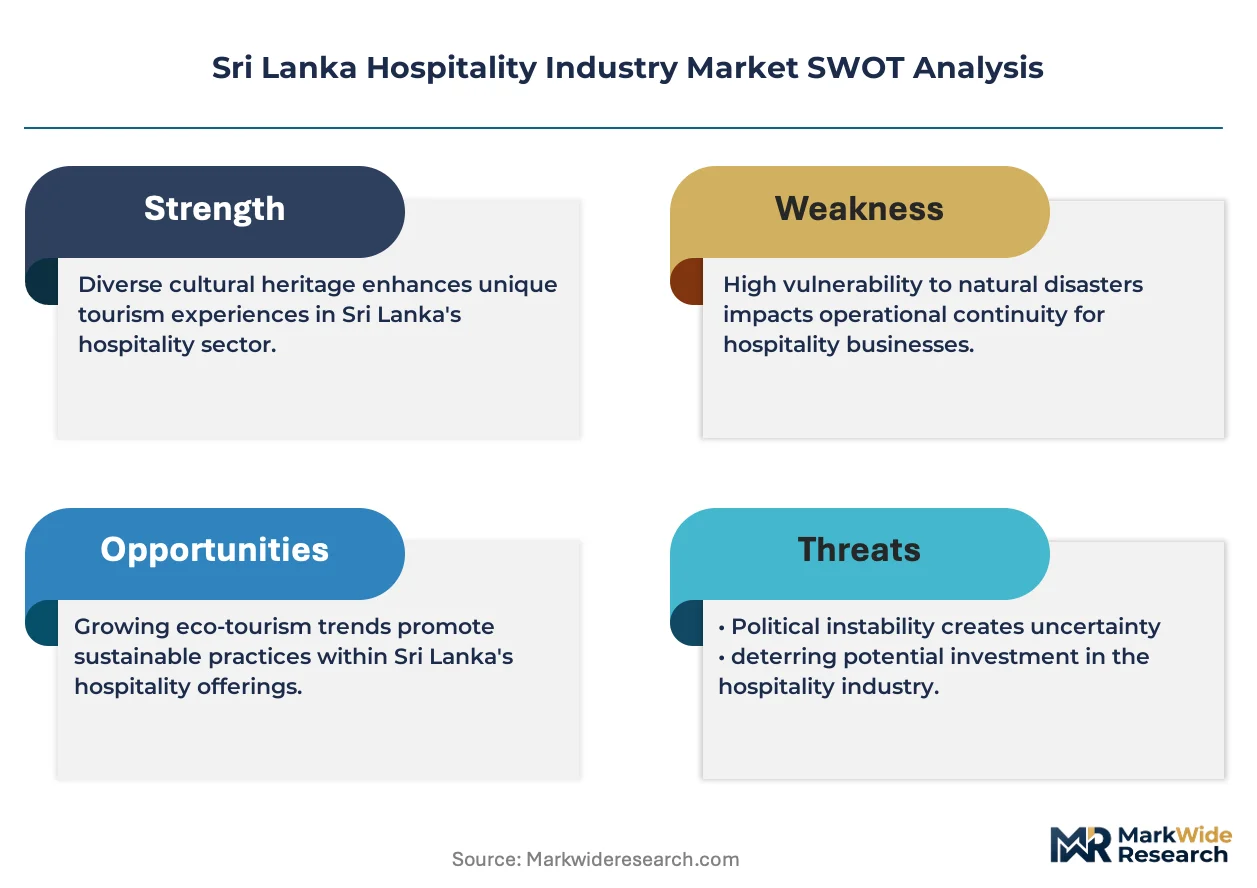
The southern coastal belt from Galle to Hambantota anchors Sri Lanka's hospitality supply base, where grandfathered beachfront inventory scarcity concentrates pricing power among heritage property operators. Central Environmental Authority buffer zone restrictions have eliminated new coastal development sites, forcing competition for limited room stock and sustaining rate premiums across experiential lodge concepts.
Pricing Analysis
Ancillary wellness programming and Ayurveda retreat packages drive lifetime value beyond pure accommodation revenue. Three-tier pricing structure across luxury heritage conversions, mid-range beachfront properties, and economy guesthouses segments the market by experiential depth. Pricing pressure stems from online travel agent commission burdens compressing net margins for independent operators. International leisure travelers from Western Europe exhibit lowest price sensitivity, while domestic weekend demand in hill country resorts remains highly elastic.
Supply Chain Analysis
Imported fire safety equipment and building materials from India, China, and Singapore feed hospitality construction and retrofit projects. BIS-aligned compliance standards require foreign-sourced steel, electrical systems, and wastewater treatment components. Single-source vulnerability concentrates in specialized Ayurveda therapy equipment and heritage restoration materials. Distribution runs through Colombo-based procurement hubs serving property developments across all provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sri Lanka's hospitality sector tracks a cyclical recovery anchored to international visitor volume rebounds following macroeconomic stabilization. Foreign exchange inflow restoration and Tourism Development Authority licensing reforms constitute the primary cyclical driver.
For Market Incumbents: Insulate margin pools by deepening backward integration into sustainable architecture and captive wellness programming. Jetwing Hotels PLC's community-based tourism model demonstrates defensive positioning against platform intermediation. Heritage property operators should prioritize direct booking channel investment to reduce online travel agent dependency. For New Entrants and Emerging Players: Establish a beachhead in underdeveloped inland heritage circuits around Anuradhapura and Polonnaruwa, where experiential lodge concepts face limited competition. The North Central Province offers first-mover positioning with longer booking horizons from cultural triangle travelers. Green financing qualification provides a differentiated capital access angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors asset-light management contract specialists with heritage restoration capabilities. Long-term viability hinges on regulatory clarity around foreign investor lease structures and coastal conservation compliance trajectories. Monitor Sri Lanka Tourism Development Authority sustainability disclosure requirements as an inflection indicator for green bond market access.| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Property Restoration | Unlocks premium inventory in Galle Fort and colonial districts under streamlined licensing reforms. |
| Green Certification Program | Qualifies compliant operators for international green financing instruments at preferential rates. |
| Direct Booking Channel Expansion | Preserves guest relationship data ownership against online travel agent platform concentration. |
| Community-Based Tourism Integration | Enables authentic programming commanding rate premiums from European source markets. |
| Ayurveda Practitioner Training Pipeline | Addresses skilled therapy shortages constraining wellness retreat expansion plans. |
Research Methodology
Cross-validation between executive interviews and regulatory filing analysis anchors the qualitative findings. Primary discussions with resort operations directors, Sri Lanka Tourism Development Authority licensing officers, heritage property architects, and Ayurveda retreat wellness directors combined with secondary review of Central Environmental Authority coastal zone determinations, BIS-aligned building code documentation, and customs import records. Bottom-up property inventory assessment and top-down foreign exchange inflow analysis provided triangulation.
Calibration against historical occupancy patterns and capital deployment timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, pricing tier, customer archetype, and distribution channel, with regional regulatory cluster as an industry-specific overlay. CAGRs derived from supply-constrained growth assumptions and experiential programming penetration curves. Forecast inputs incorporated heritage conversion pipeline data and online travel agent commission trajectory assumptions.
Macroeconomic conditions sit as an overlay; deviation in exchange rate volatility, international airlift capacity, or sovereign debt restructuring outcomes would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory clarity timelines and coastal conservation enforcement intensity. Cross-checking against Sri Lanka Tourism Development Authority official visitor arrival statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
France Casino Tourism Market
Accommodation
Europe Student Accommodation Market
Accommodation
UAE Hospitality Market
Accommodation
Underwater Hotels Market
Accommodation
Asia-Pacific Student Accommodation Market
Accommodation
United States Online Accommodation Market
Accommodation
France Hospitality Market
Accommodation
Peer to Peer Accommodation Market
Accommodation
Italy Online Accommodation Market
Accommodation
Hong Kong Hospitality Industry Market
Accommodation
India Online Accommodation Market
Accommodation
China Online Accommodation Market
Accommodation
Hostel Market
Accommodation
Germany Student Accommodation Market
Accommodation
France Online Accommodation Market
Accommodation
UK Student Accommodation Market