
 Sweden Hospitality Market | 2026-2036
Sweden Hospitality Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Hospitality Market Insights
The EU Green Deal is rebalancing capital allocation across Swedish hospitality assets as property owners retrofit existing stock to meet tightening carbon performance criteria. Scandic Hotels leverages its Nordic network density to consolidate procurement of sustainable building materials. Nordic Choice Hotels anchors its competitive position through backward integration into property development and adaptive reuse projects. Elite Hotels differentiates via design-forward boutique concepts targeting domestic weekend demand.
Sweden hospitality encompasses lodging, food service, event hosting, and travel coordination delivered through fixed and floating commercial premises, typically requiring fire safety certification, accessibility compliance, and food hygiene authorization under national ordinances. Accommodation and food and beverage together absorb the majority of operating revenue, with boutique properties capturing outsized margin per available room against standardized mid-range inventory. Conference attendees and business travelers represent the most resilient customer type, while luxury and boutique price tiers concentrate reinvestment in experiential amenities.
Swedish building codes, the Swedish Environmental Protection Agency's commercial emissions guidelines, and EU CSRD disclosure rules collectively shape renovation timelines and operating cost structures for hospitality operators. The Swedish Work Environment Authority enforces staff density and training protocols that influence service model economics across property categories. Stakeholders must track how tightening energy performance standards redistribute returns between owned real estate and managed-service contracts.
Market Dynamics
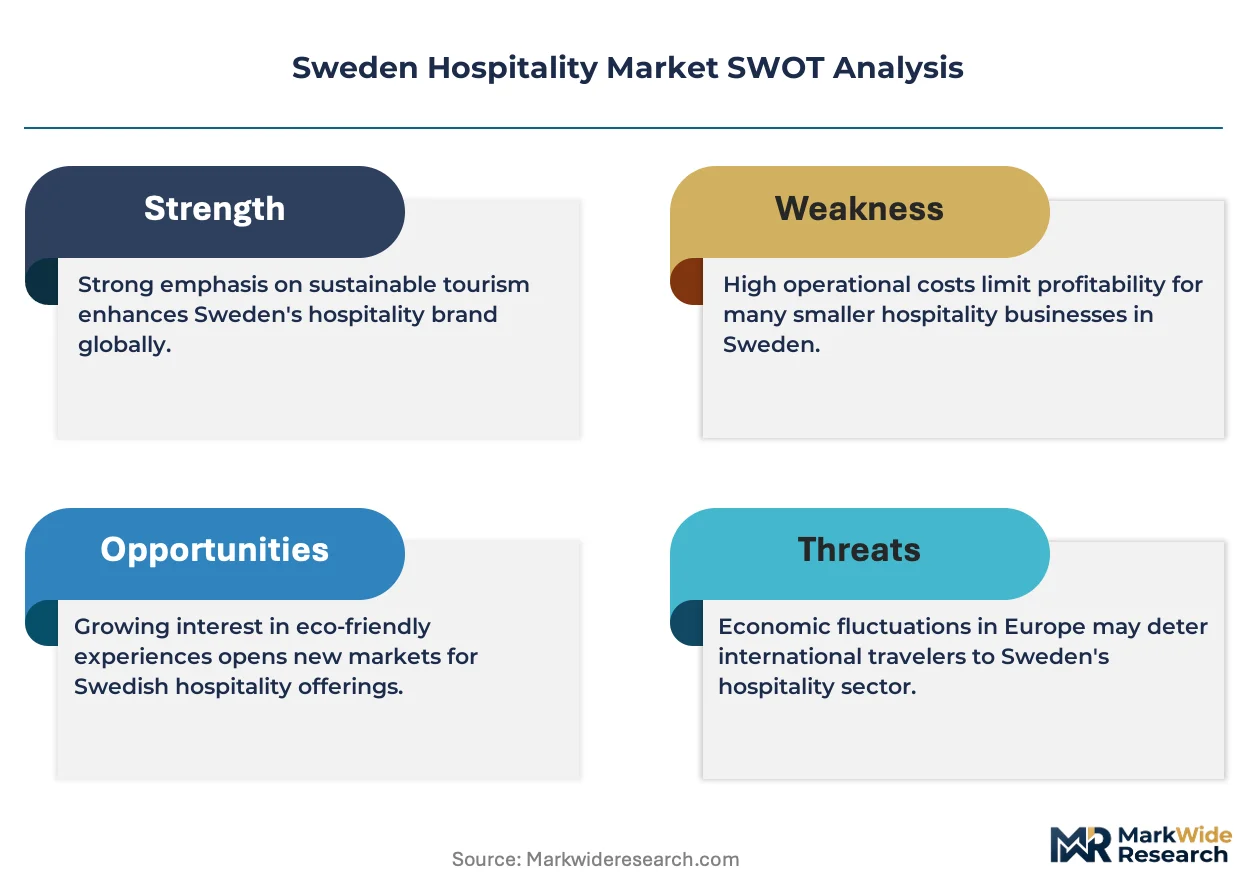
EU CSRD disclosure rules and Sweden's tightening building energy standards are compressing renovation timelines across commercial lodging stock, forcing asset owners to front-load capital expenditure or exit marginal properties entirely.
Growth Catalysts
- EU Green Deal capital reallocation:Property owners retrofit existing assets to meet tightening carbon performance criteria, unlocking financing for sustainable hospitality projects across Swedish urban centers.
- Business travel corridor density:Stockholm's hotel and conference infrastructure concentrates demand from corporate accounts, sustaining premium occupancy rates through weekday cycles.
- Adaptive reuse project pipelines:Nordic Choice Hotels and regional developers convert underutilized commercial buildings into boutique lodging, expanding room supply without greenfield construction.
Market Restraints
- Construction input cost volatility:Sustainable building materials and energy-efficient HVAC systems carry 20-40% premiums over conventional alternatives, compressing developer margins on retrofit projects.
- Skilled trade concentration:Certified green building technicians and fire safety engineers cluster in Stockholm, leaving secondary Swedish cities underserved for complex renovation work.
- Regulatory friction from overlapping mandates:Swedish Environmental Protection Agency emissions guidelines, national building codes, and EU CSRD rules create conflicting compliance timelines for multi-asset portfolios.
Strategic Opportunities
- Domestic weekend leisure expansion:Elite Hotels and boutique operators target underserved regional destinations like Gothenburg and Malmö with design-forward concepts capturing margin premiums from staycation demand.
- Floating commercial premises development:Archipelago and lake-based hospitality assets exploit regulatory exemptions for temporary structures while meeting accessibility and fire safety certification.
- Procurement consortium formation:Mid-scale operators replicate Scandic's network-density advantage by pooling sustainable material purchasing power across Nordic markets.
Industry Challenges
- Certified hospitality workforce scarcity:The Swedish Work Environment Authority's staff density and training protocols exceed supply of qualified food hygiene and fire safety personnel, constraining service model scaling.
- Legacy property system integration:Energy management retrofits in 1970s-1980s hotel stock require phased shutdowns that conflict with continuous operation mandates from business travel contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Hospitality Market |
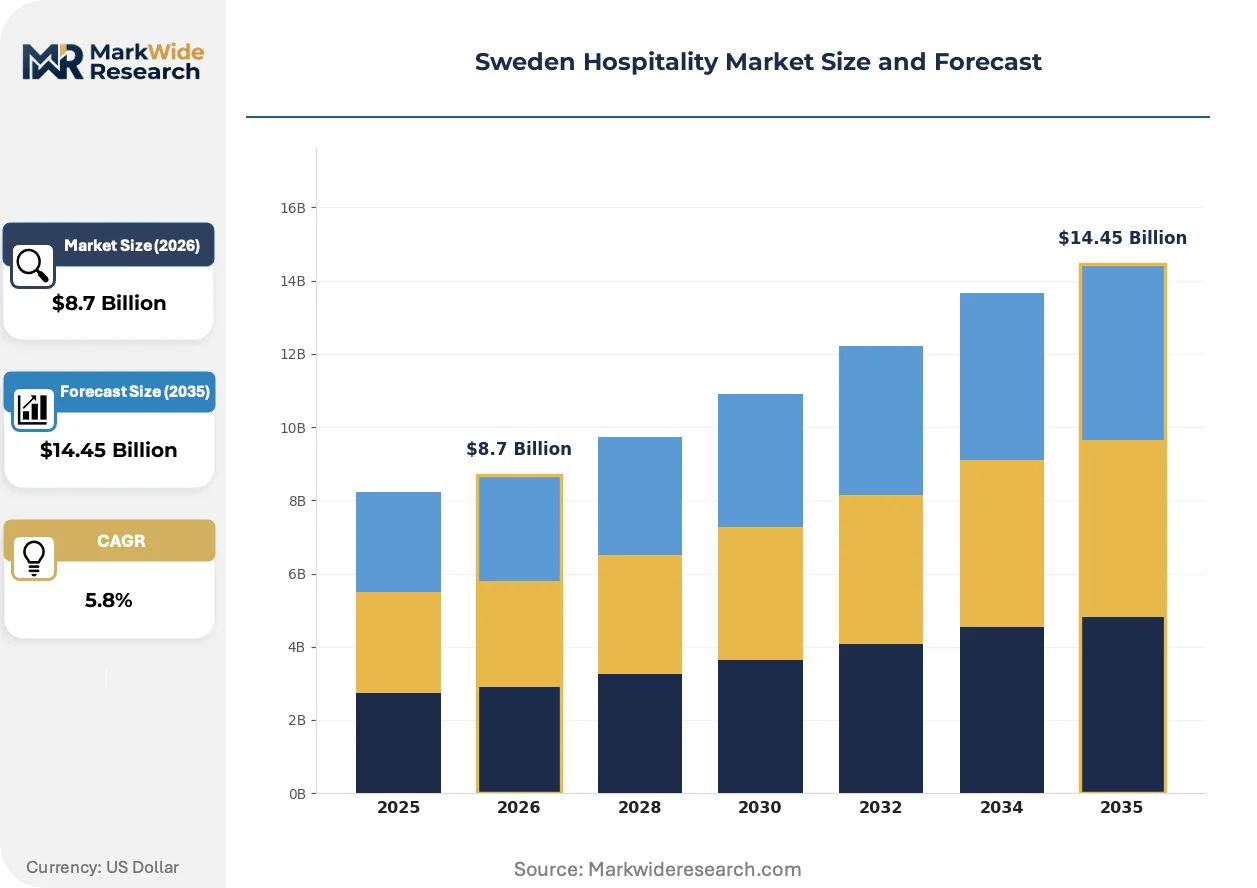
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Food & Beverage, Accommodation, Travel Services, Event Management Customer Type: Business Travelers, Tourists, Locals, Conference Attendees End User: Hotels, Restaurants, Cafes, Cruise Lines Price Tier: Luxury, Mid-range, Budget, Boutique |
| Companies Covered | Scandic Hotels, Nordic Choice Hotels, Best Western Hotels & Resorts, Radisson Hotel Group, First Hotels, Elite Hotels, ESS Group, Marriott International, Accor Hotels, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Hospitality Market Trends and Innovations
Digital building management systems and guest-facing automation are restructuring operational cost profiles across Swedish hospitality assets, compressing labor intensity while raising capital deployment requirements.
Heat pump and district heating integration is electrifying thermal infrastructure in Stockholm's premium hotel stock. Scandic and Nordic Choice Hotels deploy these systems across 2019-2024 renovation waves, cutting Scope 1 emissions while locking in decade-long energy cost predictability against volatile gas markets.
Sweden's national building energy standards now mandate efficiency upgrades for commercial lodging above 1,000 square meters. Property owners face compressed compliance windows through 2030, driving consolidation toward institutional owners with balance sheet capacity for simultaneous multi-asset retrofits.
Corporate travel buyers now unbundle conference hosting from room blocks, forcing Stockholm hotel operators to price meeting space independently and compete with standalone venue operators. Procurement teams at pharmaceutical and technology firms pioneered this shift, extending it to public sector accounts across Swedish administrative regions.
Sweden Hospitality Market Segmentation
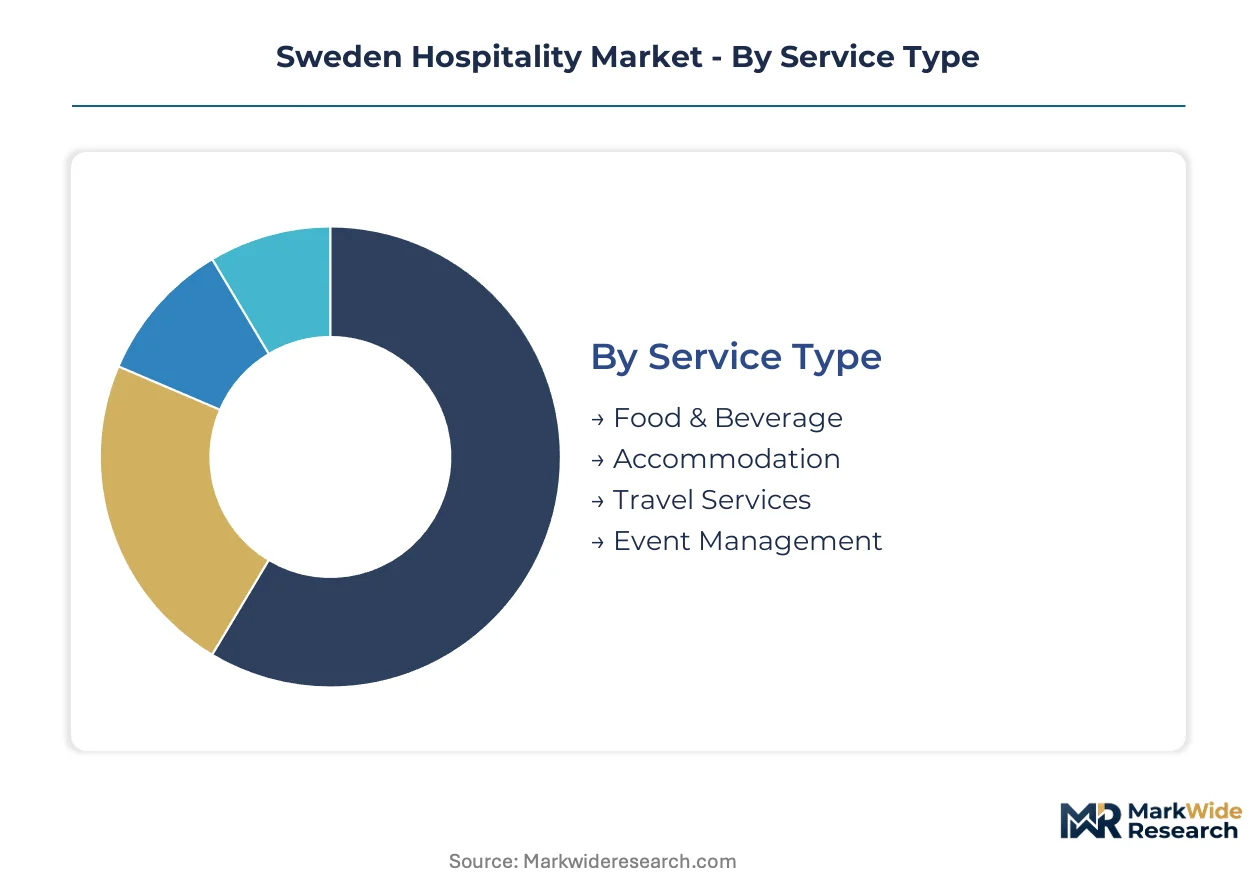
Swedish hospitality operators configure service portfolios around distinct demand clusters, each carrying different margin profiles and capital intensity requirements. Segmentation clarity determines property positioning against Stockholm's corporate corridor density versus regional leisure catchments.
Service Type:
Supply concentration in Stockholm's hotel and conference corridor concentrates revenue in accommodation and food service combinations, while peripheral operators fragment across specialized offerings.
- Accommodation:Room inventory dominates revenue capture across urban properties, with Stockholm's business travel corridor sustaining premium weekday occupancy. Swedish building energy standards mandate efficiency upgrades that compress returns on legacy stock outside capital-rich ownership structures.
- Food & Beverage:On-premise dining and banquet operations absorb the majority of variable labor costs, with fire safety certification and food hygiene authorization requirements constraining rapid service model scaling under Swedish Work Environment Authority protocols.
- Travel Services:Coordination and booking intermediaries concentrate in digital platforms, with traditional agency models retreating toward corporate account management.
- Event Management:Conference hosting and standalone venue operations compete for corporate procurement budgets that increasingly unbundle meeting space from room blocks.
Today's leader: Accommodation. Tomorrow's challenger: Event Management.
Customer Type:
Cost tier differentiation separates corporate accounts commanding premium pricing from price-sensitive leisure segments driving volume in secondary cities.
- Business Travelers:Corporate accounts sustain premium occupancy through weekday cycles, with pharmaceutical and technology firms pioneering procurement shifts that unbundle conference hosting from traditional room block arrangements.
- Conference Attendees:Delegates concentrate demand in Stockholm's hotel infrastructure, with public sector accounts across Swedish administrative regions adopting corporate procurement unbundling practices.
- Tourists:International visitation clusters in summer months, with archipelago and lake-based assets exploiting regulatory exemptions for floating commercial premises.
- Locals:Domestic weekend demand expands in regional destinations like Gothenburg and Malmö, capturing margin premiums through design-forward boutique concepts.
Corporate accounts anchor current revenue. Domestic leisure segments climb the fastest as staycation behavior hardens post-pandemic.
End User:
Application-specific requirements fragment operational standards across fixed versus floating premises, with certification burdens varying by property type.
- Hotels:Full-service properties above 1,000 square meters face compressed compliance windows through 2030 under national building energy standards, driving consolidation toward institutional owners with multi-asset retrofit capacity.
- Restaurants:Standalone food service operations carry lower capital intensity but face identical Swedish Work Environment Authority staff density protocols that constrain scaling.
- Cafes:Limited-service formats target high-frequency local demand with reduced fire safety certification complexity.
- Cruise Lines:Floating commercial premises in archipelago routes exploit regulatory exemptions for temporary structures while maintaining accessibility compliance.
Fixed urban hotels dominate investment flows. Floating premises gain share fastest as coastal and lake-based development accelerates.
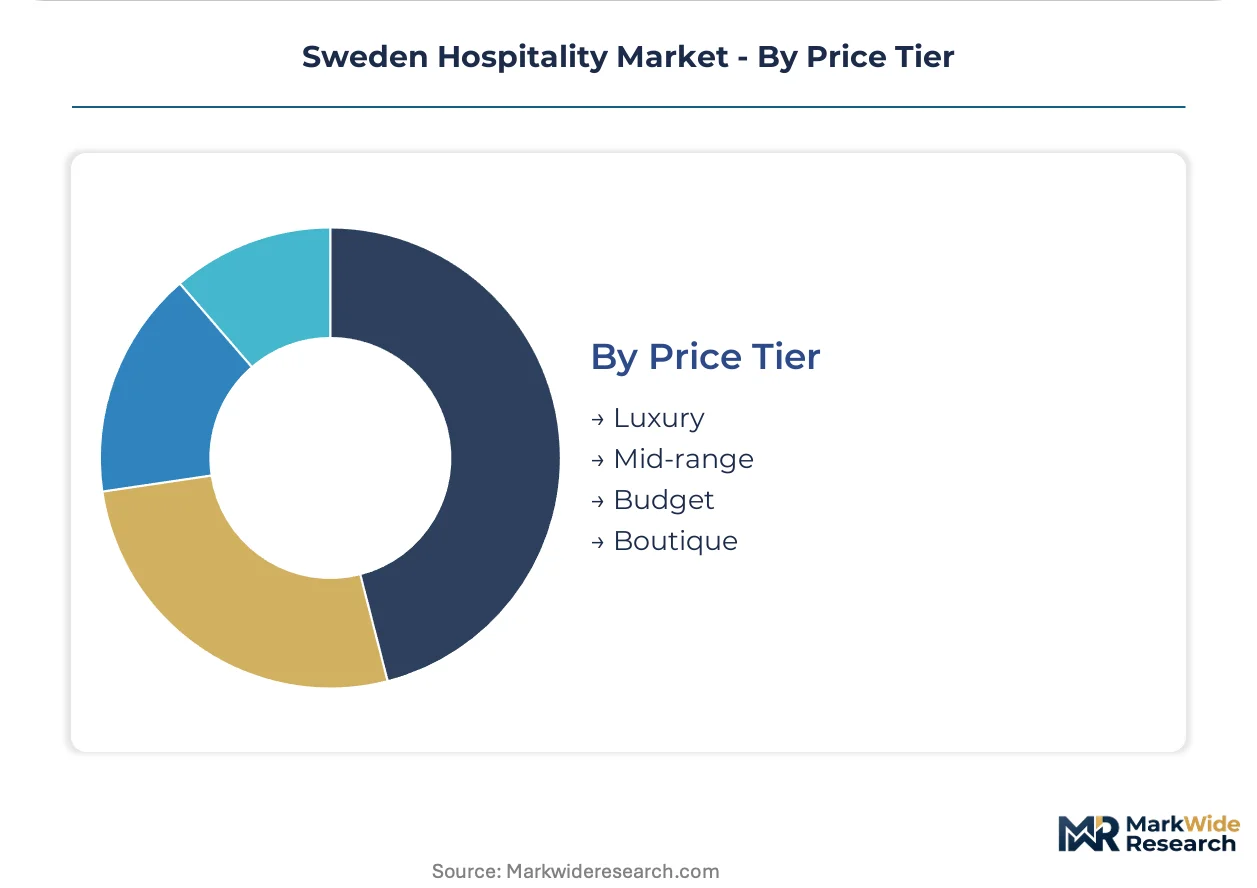
Price Tier:
Margin structure stratifies sharply across experiential amenity intensity, with reinvestment requirements scaling non-linearly above mid-range positioning.
- Boutique:Design-forward concepts capture outsized margin per available room against standardized inventory, with Elite Hotels and regional operators targeting underserved regional destinations through adaptive reuse projects.
- Luxury:Experiential amenity concentration demands continuous capital deployment, with heat pump and district heating integration locking in decade-long energy cost predictability against volatile gas markets.
- Mid-range:Network density advantages enable procurement consortium formation, with Scandic leveraging Nordic scale for sustainable material purchasing power.
- Budget:Price-sensitive positioning limits retrofit investment capacity, exposing marginal properties to exit pressures under tightening carbon performance criteria.
Boutique properties lead margin extraction. Budget tier faces steepest consolidation pressure from regulatory compliance costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sweden's hospitality sector traces its modern scale to post-war tourism infrastructure expansion and the 1990s conference economy buildout in Stockholm. Urban commercial lodging now concentrates in three metropolitan corridors, each shaped by distinct demand drivers and regulatory enforcement patterns.
Stockholm Metro
Corporate accounts from pharmaceutical and technology firms sustain premium weekday occupancy through the capital's hotel and conference corridor. The Swedish Environmental Protection Agency enforces commercial emissions guidelines that compress renovation timelines for properties above 1,000 square meters. Heat pump and district heating integration dominates 2019-2024 renovation waves across Norrmalm and Södermalm clusters.
Gothenburg
Domestic weekend leisure demand expands fastest here as staycation behavior hardens post-pandemic. National building energy standards mandate efficiency upgrades that expose marginal properties to exit pressures. Design-forward boutique concepts from Elite Hotels and regional operators capture margin premiums through adaptive reuse of harbor district commercial buildings.
Malmö
Cross-border business travel from Copenhagen sustains mid-range property occupancy through the Øresund Bridge corridor. EU CSRD disclosure rules overlay Swedish ordinances to create layered compliance timelines for multi-asset portfolios. Floating commercial premises in the archipelago exploit regulatory exemptions for temporary structures while maintaining accessibility compliance.
Uppsala
University and research institution demand anchors year-round occupancy outside seasonal tourism cycles. The Swedish Work Environment Authority enforces staff density protocols that constrain rapid service model scaling in this secondary city. Limited certified green building technician availability delays complex renovation timelines compared to Stockholm.
Sweden Hospitality Market Competitive Landscape
Capital-heavy property owners compete with asset-light management contract operators across Sweden's hospitality sector. Institutional owners with balance sheet capacity for multi-asset retrofits consolidate market share as tightening carbon performance criteria force marginal exits. Three strategic archetypes dominate: Nordic network consolidators leveraging procurement scale, design-forward boutique specialists, and global flag operators licensing premium brands. Competitive moves concentrate on adaptive reuse project pipelines and sustainable material purchasing consortiums.
Among Nordic-origin operators, Scandic Hotels, Nordic Choice Hotels, and Elite Hotels occupy distinct positioning tiers. Scandic exemplifies the network-density archetype through consolidated sustainable building material procurement across regional markets. Nordic Choice anchors the backward integration model through captive property development and adaptive reuse pipelines. Elite Hotels represents the boutique differentiation vector targeting domestic weekend demand with design-forward concepts in underserved regional destinations like Gothenburg and Malmö.
| Leading Market Players |
|---|
| Scandic Hotels |
| Nordic Choice Hotels |
| Best Western Hotels & Resorts |
| Radisson Hotel Group |
| First Hotels |
| Elite Hotels |
| ESS Group |
| Marriott International |
| Accor Hotels |
| Others |
Pricing and Supply Chain Analysis
Steel and timber price indices in Nordic construction markets cascade through Swedish hospitality development costs, compressing margins on sustainable retrofit projects while concentrating pricing power among institutional owners with captive procurement scale.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates Swedish hospitality revenue capture, with certification grade under EU CSRD disclosure rules and brand premium from Nordic network density serving as primary differentiation drivers. Cost compression in budget-tier properties is intensifying because sustainable building material premiums strain retrofit investment capacity. Corporate business travelers exhibit lowest price sensitivity, while domestic leisure segments in secondary cities drive volume at thinner margins.
Supply Chain Analysis
Certified green building technicians and fire safety engineers cluster disproportionately in Stockholm, leaving Gothenburg, Malmö, and Uppsala underserved for complex renovation work and extending project timelines. Sustainable HVAC systems and fire-rated building materials draw from German, Danish, and domestic Swedish manufacturing bases. Single-source vulnerability in certified workforce availability creates bottleneck risk. Distribution runs through consolidated procurement consortiums led by network-dense operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sweden hospitality functions as a stable compounder, with EU Green Deal capital reallocation driving steady reinvestment cycles across commercial lodging stock.
For Market Incumbents: To counter regulatory compliance cost escalation, consolidate multi-asset retrofit programs under institutional balance sheet capacity and deepen backward integration into sustainable material procurement through Nordic purchasing consortiums. For New Entrants and Emerging Players: Capture white-space in floating commercial premises across archipelago routes and adaptive reuse pipelines in Gothenburg harbor district, exploiting regulatory exemptions for temporary structures and design-forward positioning against standardized inventory. For Investors and Strategic Acquirers: Asymmetric upside sits with boutique specialists holding adaptive reuse development capabilities and district heating integration expertise. Five-to-ten-year viability hinges on CSRD compliance positioning. Watch certified green building technician availability as workforce scarcity inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Reuse Pipeline Development | Converts underutilized commercial buildings into boutique lodging without greenfield construction permits. |
| Sustainable Procurement Consortium | Pools purchasing power across Nordic markets to offset 20-40% premiums on energy-efficient building materials. |
| Heat Pump and District Heating Integration | Electrifies thermal infrastructure while locking decade-long energy cost predictability against volatile gas markets. |
| Floating Premises Certification Program | Exploits regulatory exemptions for temporary archipelago structures while maintaining accessibility compliance. |
| Domestic Weekend Leisure Expansion | Targets underserved regional destinations with design-forward concepts capturing staycation margin premiums. |
Research Methodology
Bottom-up property-level modeling reconciled against top-down capital flow tracking forms the analytical core of this study. Primary interviews with hotel development executives, asset managers at institutional owners, procurement directors at Nordic operator networks, and certified green building technicians informed demand-side assumptions. Secondary validation drew from Swedish Environmental Protection Agency emissions filings, EU CSRD disclosure registries, national building code enforcement records, and hospitality asset transaction databases. Triangulation across these sources anchored segmentation-level projections.
Historical trendline analysis of renovation cycle timing, occupancy rate patterns, and capital deployment intensity established baseline growth trajectories across the projection horizon. Segmentation dimensions modeled include service type, customer archetype, end-use property format, and price tier positioning. CAGRs were derived from regression analysis of property-level revenue per available room against regulatory compliance investment requirements. Forecast inputs incorporated EU Green Deal capital allocation flows and district heating infrastructure buildout schedules.
Construction input cost volatility, certified workforce availability shocks, and regulatory timeline acceleration are the dominant revision risks to modeled projections. Forecasts reflect assumptions on sustained EU CSRD enforcement intensity and stable Nordic green building material supply chains. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
Netherlands Hospitality Industry Market
Accommodation
Global Travel Accommodation Market
Accommodation
Croatia Hospitality Market
Accommodation
Capsule Hotels Market
Accommodation
Hong Kong Hospitality Industry Market
Accommodation
Alternative Accommodation Market
Accommodation
US Recreational and Vacation Camp Market
Accommodation
Youth Summer Camp Market
Accommodation
Sri Lanka Hospitality Industry Market
Accommodation
Romania Hospitality Market
Accommodation
In-Flight Catering Services Market
Accommodation
Extended Stay Hotel Market
Accommodation
India Online Accommodation Market
Accommodation
France Casino Tourism Market
Accommodation
Casino Hotel Market
Accommodation
UK Student Accommodation Market