
 Global Filtration and Contamination Control Market | 2026-2036
Global Filtration and Contamination Control Market Size, Share, and Industry Trends Forecast 2026-2036
Global Filtration and Contamination Control Market Intelligence
Aftermarket sales of consumable filter media and service contracts is rewriting the industry's profit structure, shifting value away from initial equipment sales. Donaldson Company, Inc. leverages its extensive portfolio to capture recurring revenue streams in industrial and engine filtration. Parker-Hannifin Corp. competes on the basis of integrated systems, combining its filtration products with its broader fluid power and motion control technologies, creating a comprehensive solution for original equipment manufacturers.
Filtration and contamination control refers to the processes and equipment used to separate and remove particulates, contaminants, and microorganisms from a liquid or gaseous medium. These systems employ media with precisely engineered pore structures, often rated in microns, to achieve specific levels of purity required for industrial processes or life sciences applications. Liquid filters for pharmaceutical manufacturing and water treatment represent a mature, high-volume segment. However, advanced membrane filters designed for semiconductor fabrication and biotechnology applications are experiencing the most significant value growth.
Regulatory mandates from bodies like the US FDA and the European Medicines Agency (EMA) dictate stringent cleanliness standards for pharmaceutical manufacturing. Concurrently, ISO 14644 standards for cleanrooms and controlled environments define the required performance of air filtration systems across multiple industries worldwide. The critical decision for end-users now centers on balancing the upfront capital expenditure for advanced filtration systems against the long-term operational benefits and the significant financial risk of non-compliance.
Market Dynamics
The central structural force shaping the market is the escalating purity requirement from advanced manufacturing sectors. Semiconductor fabrication's push toward sub-5nm nodes and biopharmaceutical demand for sterile production environments are compelling investment in filtration technologies that were previously considered niche or experimental.
Growth Catalysts
- Advanced Semiconductor Nodes:The transition to smaller node architectures in semiconductor fabrication, particularly within clusters in Taiwan and South Korea, requires unprecedented levels of chemical and atmospheric purity, driving investment in state-of-the-art filtration.
- Stringent Cleanroom Standards:Global adoption of ISO 14644 standards for cleanrooms and controlled environments mandates specific air cleanliness levels by particle count, creating a consistent, regulation-driven demand for high-efficiency particulate air (HEPA/ULPA) filters.
- Biopharmaceutical Manufacturing:The expansion of biologics, cell therapies, and vaccine production necessitates sterile processing environments, with regulatory bodies like the US FDA and EMA imposing strict contamination control protocols that fuel demand for validated liquid and air filters.
Market Restraints
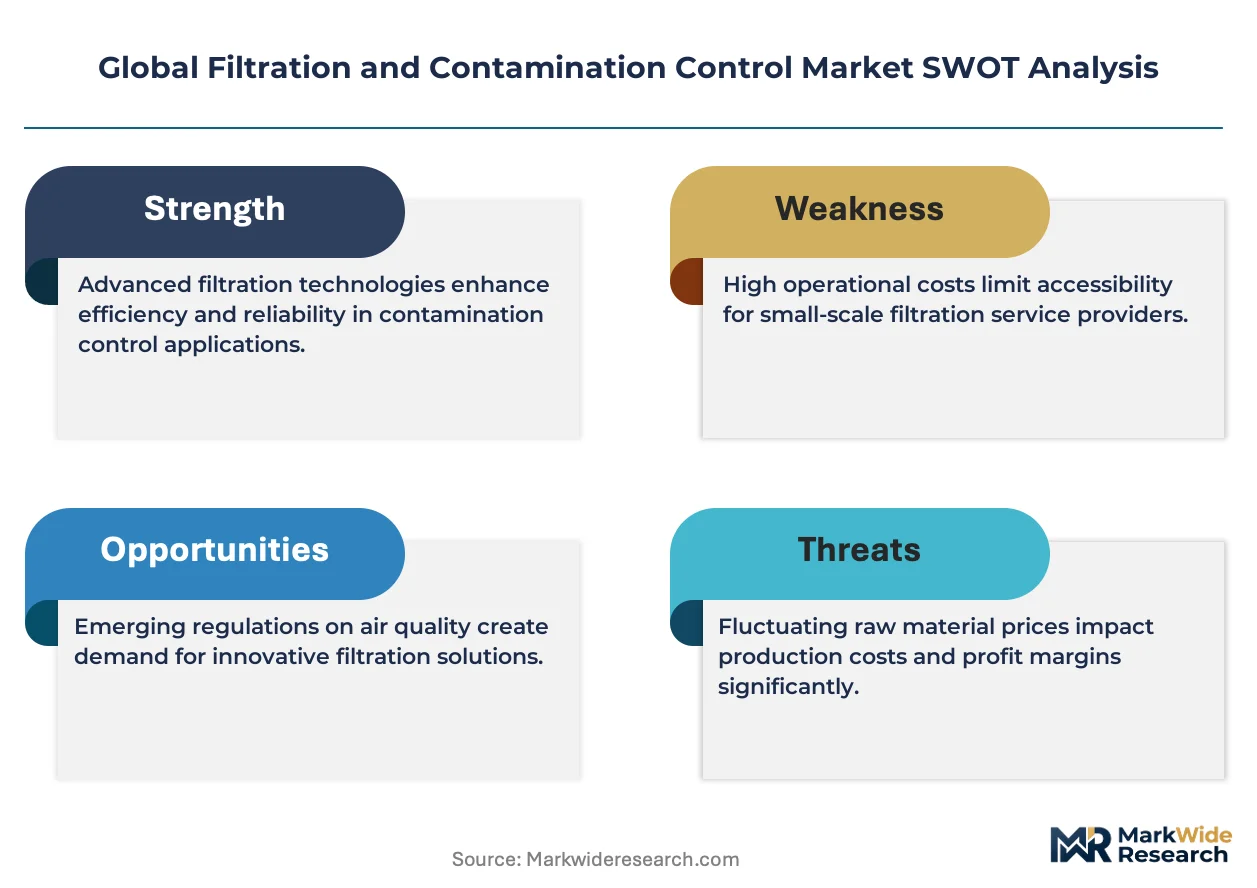
- High Capital Expenditure:The significant upfront cost of advanced filtration systems, particularly for ultra-pure water or cleanroom air handling units, acts as a barrier for small to medium-sized enterprises, slowing adoption outside of high-margin industries.
- Material Science Limitations:Developing filter media that combines extremely fine pore structures with high flow rates and chemical resistance remains a significant technical challenge, creating performance trade-offs for end-users in demanding applications.
- Consumable Cost Volatility:The pricing of specialized polymer and ceramic materials used in advanced membranes and filter media is subject to fluctuations in raw material and energy costs, creating margin pressure for manufacturers and unpredictability for end-users.
Strategic Opportunities
- IoT-Enabled Predictive Maintenance:Integrating sensors into filtration systems to monitor pressure drop, flow rates, and particle counts allows for the development of service-based models offering predictive maintenance and guaranteed uptime, creating new revenue streams.
- Contaminant-Specific Solutions:Growing concerns over emerging contaminants like PFAS in water supplies and volatile organic compounds (VOCs) in industrial settings create opportunities for developing highly selective adsorption and membrane technologies tailored to specific chemical targets.
- Cell and Gene Therapy:The unique and stringent sterility requirements for manufacturing cell and gene therapies present a high-value opportunity for single-use filtration assemblies and closed-system processing solutions that minimize contamination risks.
Industry Challenges
- Validation and Compliance Burden:Validating that filtration systems consistently meet the dynamic requirements of regulators like the EMA and US FDA is a complex and time-consuming process, posing a significant operational challenge, especially in life sciences.
- Specialized Talent Scarcity:A shortage of technicians and engineers with the expertise to design, install, and maintain complex contamination control systems for industries like semiconductor manufacturing hinders efficient deployment and operation.
- Legacy System Integration:Retrofitting older manufacturing facilities with modern, high-efficiency filtration systems often presents significant engineering challenges and downtime, complicating the upgrade cycle for established industrial players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Filtration and Contamination Control Market |
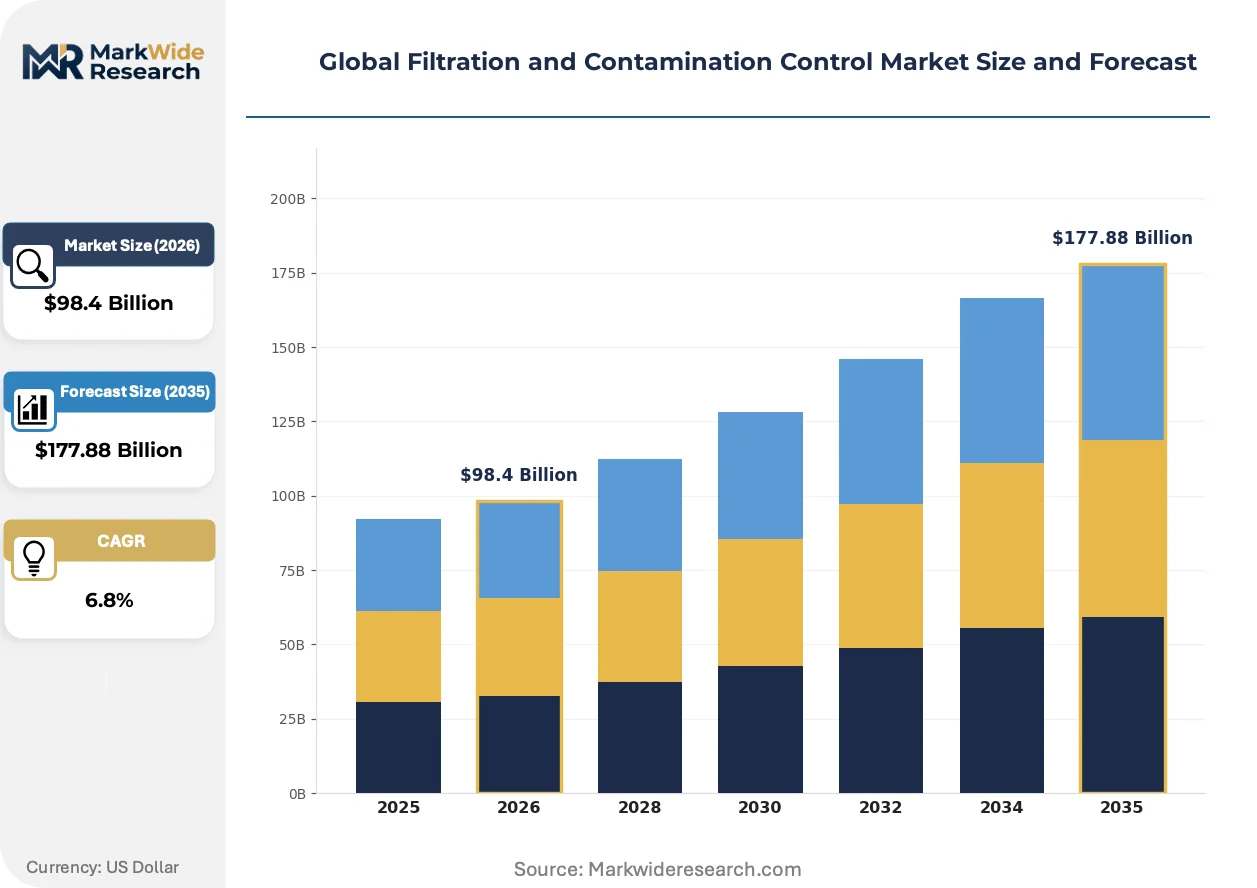
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $177.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Filters, Liquid Filters, Gas Filters, Membrane Filters, Separator Equipment Technology: Depth Filtration, Surface Filtration, Adsorption, Centrifugal Separation, Electrostatic Precipitation Application: Pharmaceutical Manufacturing, Food & Beverage Production, Semiconductor Fabrication, Chemical Processing, Water Treatment End User: Biotechnology Firms, Process Engineering Plants, Cleanroom Facilities, Analytical Laboratories, Environmental Agencies |
| Companies Covered | MANN+HUMMEL Holding GmbH, Donaldson Company, Inc., Parker-Hannifin Corp., Pall Corporation, Filtration Group Corporation, Eaton Corporation plc, Cummins Inc., HYDAC International GmbH, CECO Environmental Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Filtration and Contamination Control Market Strategic Shifts & Innovations
Intelligence and materials science are transforming filtration from passive separation to active, data-driven contamination management. The development of novel media and embedded sensing is creating systems that not only purify but also provide critical process intelligence and performance guarantees.
Advanced Membrane Filters
Nanofiber-based filter media provides superior efficiency in capturing sub-micron particles with a lower pressure drop compared to conventional materials. Advanced manufacturing sectors, including aerospace and microelectronics, are accelerating adoption of these materials for critical air quality control. The improved performance and energy efficiency of nanofiber technology is rendering obsolete traditional melt-blown media in high-specification cleanroom and gas turbine inlet applications.
Regulatory Focus on Emerging Contaminants
European Union directives and US EPA health advisories targeting PFAS "forever chemicals" are establishing new mandates for water purification. This regulatory pressure forces investment in novel filtration capabilities for both municipal drinking water and industrial wastewater treatment. Water utilities and chemical manufacturers are the most affected segments, driving research into advanced ion exchange, reverse osmosis, and specialized adsorbent technologies.
Lifecycle Service Models
A fundamental shift in procurement is occurring as end-users favor long-term service agreements that bundle consumable media, maintenance, and performance verification. This model disrupts the traditional distributor channel focused on one-time equipment sales, benefiting suppliers with direct service capabilities. This trend is most pronounced in critical industries like pharmaceutical production and data center cooling, where system reliability is non-negotiable.
Global Filtration and Contamination Control Market Segmentation
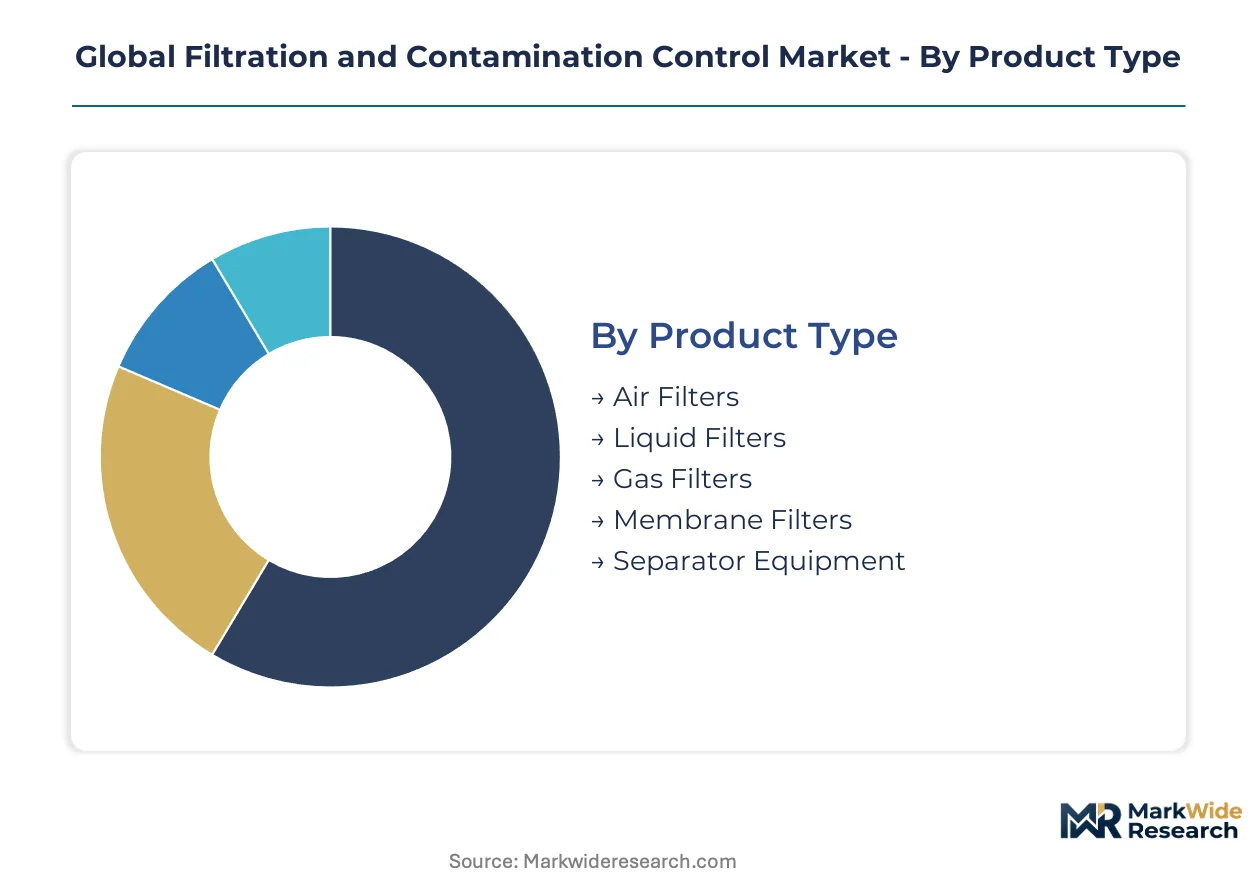
Understanding the market’s segmentation is crucial for identifying where value accumulates and how operational complexities differ across various product types, technologies, applications, and end-users. This granular view reveals specific demand drivers and the distinct purity requirements that shape investment decisions within the filtration and contamination control industry.
Product Type:
The turnover rate for filtration products varies significantly, with some media requiring frequent replacement while others offer extended service life. This influences recurring revenue streams and procurement cycles for end-users.
- Air Filters:Employ fibrous media like HEPA or ULPA to capture airborne particulates down to sub-micron levels, crucial for clean environments. Demand concentrates in cleanroom facilities in Taiwan and South Korea due to stringent ISO 14644 standards for semiconductor manufacturing.
- Membrane Filters:Utilize semi-permeable barriers with precisely engineered pore structures, often made from polymers or ceramics, for highly selective separation. Significant value growth is observed in biopharmaceutical applications due to the need for sterile processing and advanced separation.
- Liquid Filters:Remove suspended solids and contaminants from aqueous or organic liquids using various media, including cartridges and bags. Water treatment plants and pharmaceutical production facilities are major end-users requiring consistent fluid purity.
- Gas Filters:Purify process gases and compressed air, protecting sensitive equipment and ensuring product quality in industrial settings. Industrial chemical processing and electronics manufacturing require specific gas filtration solutions.
- Separator Equipment:Employs physical principles like centrifugal force or gravity to separate solids from liquids or gases, often used for bulk material handling. Oil and gas operations and wastewater treatment utilize these systems for primary separation.
Air Filters dominate the installed base. Membrane Filters are where expansion concentrates.
Technology:
The cost tier of filtration technologies ranges from widely adopted, economical methods to highly specialized, capital-intensive solutions designed for extreme purity. This influences initial investment versus long-term operational expenses.
- Adsorption:Uses porous materials like activated carbon or specialized resins to capture contaminants through surface adhesion, often targeting specific chemical species. Growing concerns over emerging contaminants like PFAS in water supplies drive investment in these selective technologies.
- Depth Filtration:Relies on a thick filter medium to trap particles throughout its matrix, offering high dirt-holding capacity and extended service life. Pharmaceutical manufacturing often uses depth filters for clarification steps before final sterile filtration.
- Surface Filtration:Traps particles on the surface of a thin membrane or filter medium, enabling efficient removal of uniformly sized contaminants. Semiconductor fabrication utilizes surface filtration for critical process fluids.
- Centrifugal Separation:Employs rotational force to separate components of different densities, commonly used for solid-liquid or liquid-liquid separation. This technology is vital in chemical processing and wastewater treatment for bulk separation.
- Electrostatic Precipitation:Uses an electrostatic charge to remove fine particles from gas streams, offering high efficiency for industrial emissions control. Power generation facilities and industrial boilers implement electrostatic precipitators for air pollution control.
Depth Filtration provides foundational capabilities, while Adsorption offers specialized solutions for complex chemical challenges.
Application:
Application segments are differentiated by the volume of material processed, with some sectors handling vast quantities of fluids while others prioritize ultra-high purity for smaller, high-value streams.
- Semiconductor Fabrication:Requires ultra-high purity filtration for process chemicals, gases, and cleanroom air to achieve sub-5nm node architectures. Advanced chip manufacturing clusters in Taiwan and South Korea are critical demand centers for these exacting standards.
- Pharmaceutical Manufacturing:Mandates stringent sterility and particulate control for drug production, driven by US FDA and EMA regulations. Biologics and cell therapy production significantly increase the demand for validated liquid and air filters.
- Food & Beverage Production:Utilizes filtration for product clarity, microbial control, and ingredient purification to meet quality and safety standards. Breweries and dairy processing plants are significant consumers of filtration media for product integrity.
- Chemical Processing:Employs filtration for catalyst recovery, product purification, and effluent treatment in diverse chemical reactions. Petrochemical operations and specialty chemical production require robust filtration systems for process efficiency.
- Water Treatment:Addresses municipal and industrial water purification needs, removing suspended solids, pathogens, and emerging contaminants from source water. Regulatory mandates for drinking water quality drive continuous investment in advanced filtration.
Water Treatment represents the highest volume demand, but Semiconductor Fabrication drives the most significant value creation.
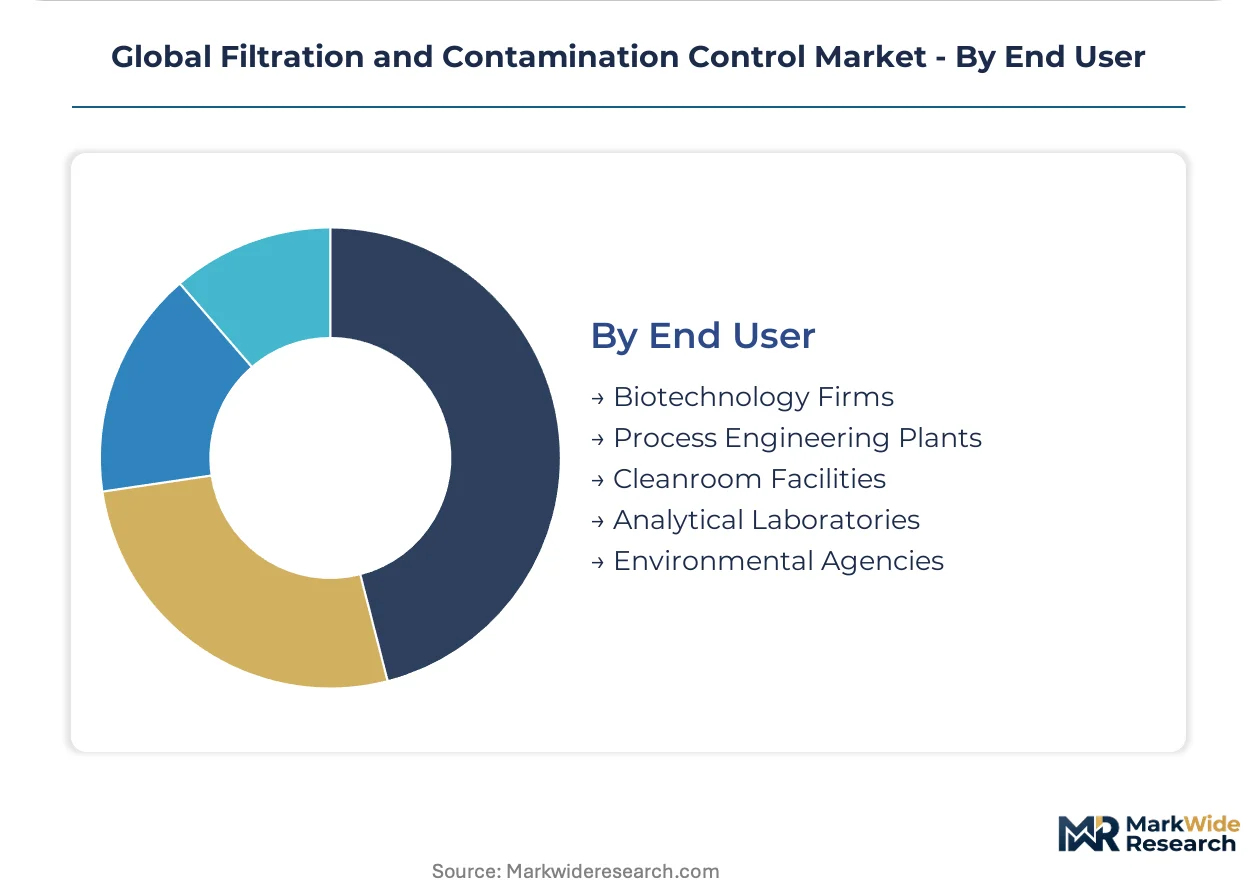
End User:
End-user segments are distinguished by their specific regulatory environments and the nature of their operational processes, impacting their procurement strategies and service requirements.
- Biotechnology Firms:Require highly specialized and validated filtration systems for cell culture, fermentation, and purification of biologics. The expansion of gene and cell therapies creates demand for single-use and sterile processing solutions.
- Cleanroom Facilities:Depend on high-efficiency air filtration systems to maintain ISO 14644 cleanliness standards for sensitive manufacturing processes. Semiconductor plants and pharmaceutical aseptic filling lines are primary users of these controlled environments.
- Process Engineering Plants:Integrate filtration solutions into large-scale industrial operations for fluid purification, waste reduction, and equipment protection. Chemical and petrochemical industries frequently utilize these services for continuous operation.
- Analytical Laboratories:Use precision filtration for sample preparation, instrument protection, and ensuring accurate test results in research and quality control. Research institutions and quality control labs rely on high-purity filtration for data integrity.
- Environmental Agencies:Utilize filtration technologies for air quality monitoring, water sampling, and pollution control efforts across various industries. Regulatory compliance drives demand for effective environmental filtration solutions to meet standards.
Biotechnology Firms drive demand for bespoke systems, while Process Engineering Plants rely on standardized, high-throughput solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global filtration and contamination control market exhibits a distinct consumption-mix differential, with advanced manufacturing hubs prioritizing ultra-high purity for high-value streams, while other regions focus on large-volume water treatment and industrial process efficiency. Investments in specialized filtration technologies are heavily concentrated in areas with robust semiconductor and biopharmaceutical ecosystems.
Taiwan
Demand for advanced filtration in Taiwan stems from its dominant position in semiconductor manufacturing, requiring ultra-pure process chemicals and cleanroom air. The country's environmental protection agency enforces strict wastewater discharge limits for industrial facilities, driving investment in advanced liquid filtration. Hsinchu Science Park remains a critical hub for sub-5nm node fabrication, necessitating continuous upgrades in contamination control systems.
South Korea
South Korea's filtration market is significantly shaped by its advanced semiconductor and display manufacturing sectors, demanding stringent particulate control. The Ministry of Environment sets rigorous air quality standards for industrial emissions, impacting filter media selection. Major technology clusters like those in Gyeonggi Province drive innovation in ULPA filters and advanced membrane technologies for critical applications.
United States
The United States market is characterized by strong demand from its biopharmaceutical and semiconductor industries, requiring validated sterile filtration and ultra-pure environments. The US FDA mandates rigorous contamination control protocols for drug manufacturing, fueling investment in high-efficiency filters. Research Triangle Park in North Carolina and Silicon Valley in California are key centers for bioprocessing and chip fabrication, respectively.
Germany
Germany's market for filtration and contamination control is robust, driven by its advanced manufacturing base, including automotive, chemical, and pharmaceutical sectors. Strict EU environmental regulations, such as those from the European Medicines Agency, necessitate high-performance air and liquid filtration systems. Industrial regions like Bavaria and North Rhine-Westphalia are significant consumers of specialized filters for process optimization and emission control.
China
China's market sees substantial demand from its rapidly expanding pharmaceutical manufacturing and electronics industries, alongside significant water and wastewater treatment needs. The Ministry of Ecology and Environment implements stringent pollution control policies, driving adoption of advanced filtration solutions. Major industrial zones in the Yangtze River Delta and Pearl River Delta are critical areas for both industrial process filtration and environmental protection.
Global Filtration and Contamination Control Market Key Industry Players
Capability concentration sits with one tier of players offering highly specialized, performance-driven solutions, while scale advantage sits with another tier providing broad portfolios for diverse industrial applications. The market structure exhibits a blend of highly specialized technology providers and diversified industrial conglomerates. Strategic archetypes include integrated solution providers, niche technology innovators, and aftermarket service specialists. Companies primarily focus on strategic partnerships and portfolio diversification to enhance their market reach.
Specialists in integrated filtration systems, such as Donaldson Company, Inc., leverage extensive product lines to serve multiple industrial and engine applications. Parker-Hannifin Corp. exemplifies a diversified engineering firm, combining filtration with broader motion and control technologies to offer comprehensive solutions. Pall Corporation represents a key player with a strong focus on life sciences and advanced membrane filtration, catering to high-purity requirements in biopharmaceutical and semiconductor sectors.
| Leading Market Players |
|---|
| MANN+HUMMEL Holding GmbH |
| Donaldson Company, Inc. |
| Parker-Hannifin Corp. |
| Pall Corporation |
| Filtration Group Corporation |
| Eaton Corporation plc |
| Cummins Inc. |
| HYDAC International GmbH |
| CECO Environmental Corp. |
| Others |
Cost & Logistics Intelligence
Trans-Pacific shipping routes, critical for delivering specialized filter media and components, directly influence supply concentration and subsequent price differentiation in advanced filtration markets. The significant cost of transporting high-purity materials and finished advanced filtration systems impacts regional pricing structures. This dynamic leads to higher pricing in regions distant from primary manufacturing hubs.
Pricing Analysis
Long-term service agreements and project-based contracts form the dominant pricing model for advanced filtration systems, ensuring recurring revenue streams for suppliers. Price differentiation stems from the certification level, such as US FDA validation for life sciences, and the customization required for specific process integration. Pricing pressure exists for standard liquid and air filters due to raw material cost volatility. Biopharmaceutical and semiconductor end-users exhibit lower price sensitivity compared to industrial water treatment facilities.
Supply Chain Analysis
Contract manufacturing concentration in regions like Taiwan and South Korea, particularly for advanced membrane and nanofiber media, defines the supply landscape. The supply chain draws from specialized polymer and ceramic material producers, often concentrated in Germany and the United States. Raw material cost volatility represents a significant structural risk for filter media manufacturers. Distribution for complex systems often runs through direct sales channels, while consumable media relies on a network of specialized industrial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The filtration and contamination control market requires a strong substitution defense, as novel purification technologies like advanced membrane separation threaten to displace traditional media in critical applications.
For Market Incumbents:Entrench core market positions by investing heavily in advanced materials science for nanofiber and membrane technologies. Acquire niche technology innovators specializing in contaminant-specific solutions to counter emerging threats like PFAS regulations. Deepen vertical integration into specialized media manufacturing to control input costs and intellectual property. Leverage extensive service networks to offer IoT-enabled predictive maintenance, securing long-term customer relationships and recurring revenue.
For New Entrants and Emerging Players:Establish a beachhead in niche segments like cell and gene therapy manufacturing, which demand highly specialized single-use filtration systems. Target the growing demand for contaminant-specific solutions, particularly in water treatment, where existing technologies are less effective against emerging pollutants. Develop a service-centric go-to-market strategy, offering performance guarantees and bundled maintenance to overcome high capital expenditure barriers for smaller end-users. Focus on modular, scalable solutions that integrate easily with legacy systems.
For Investors and Strategic Acquirers:US FDA and EMA mandates for sterile biopharmaceutical production reshape the acquisition landscape for filtration technology. Long-term viability favors firms with proprietary advanced membrane and nanofiber technologies, particularly those addressing semiconductor and life sciences purity requirements. Acquire specialized firms offering IoT-enabled filtration systems or those with strong intellectual property in emerging contaminant removal. The signal to watch is the acceleration of regulatory mandates for new contaminant classes or stricter cleanroom standards.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Advanced Membrane Technology Firms | Secures proprietary technology and market share in high-growth biopharmaceutical and semiconductor applications. |
| Investment in Nanofiber Media R&D | Develops next-generation filtration solutions with superior efficiency and lower pressure drop for cleanroom environments. |
| Expansion of IoT-Enabled Service Offerings | Transforms revenue models from product sales to recurring service contracts, enhancing customer retention for Donaldson Company. |
| Strategic Partnerships for Contaminant-Specific Solutions | Addresses regulatory mandates for emerging contaminants like PFAS, creating new revenue streams in municipal water treatment. |
| Capacity Expansion in Sterile Single-Use Filtration | Supports the rapid growth of cell and gene therapy manufacturing, meeting stringent regulatory requirements for purity. |
Research Approach
Cross-validation between primary interviews with industry plant managers and secondary analysis of ISO 14644 standards anchors the qualitative findings. This study incorporates insights from R&D directors, procurement leads, and regulatory affairs specialists across semiconductor, pharmaceutical, and water treatment sectors. Secondary data sources include US FDA filings, European Medicines Agency guidelines, trade association reports, and company annual statements for market sizing and trend identification. A bottom-up and top-down triangulation approach ensures data consistency.
Market size and growth projections undergo calibration using a multi-variable analytical framework across the analysis window. The model integrates segmentation dimensions including product type, technology, application, end-user, and specific purity level requirements. Compound annual growth rates are derived from historical data and projected forward based on identified growth catalysts and market restraints. Key industry-specific forecast inputs include semiconductor node roadmaps and biopharmaceutical pipeline developments.
Stress conditions across raw material volatility and geopolitical trade policies were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Quarterly review of semiconductor fab announcements and biopharma regulatory changes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Hydraulic Filters Market
Filters
Global Filter Market
Filters
Residential Filters Market
Filters
Global Baghouse Filters Market
Filters
Global Pleated Filters Market
Filters
Fabric Filters Market
Filters
Activated Carbon Filter Market
Filters
Filtering Centrifuges Market
Filters
Industrial Air Filtration Market
Filters
Global Hollow Fiber Filtration Market
Filters
Aerospace Filter Market
Filters
Industrial Filter Paper Market
Filters
Global Filter Press Market
Filters
Filtration and Separation Market
Filters
Round Plate Filter Press Market
Filters
United States Activated Carbon Market