
 Global Insulin Infusion Pumps Market | 2026-2036
Global Insulin Infusion Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Insulin Infusion Pumps Market Foresight
Premium connectivity specifications are rotating toward the center of competitive strategy in insulin infusion pumps. Medtronic leverages its integrated CGM pipeline to sustain technology leadership across multiple geographies. Insulet Corporation anchors its position through patch pump specialization and direct-to-consumer channel control. Tandem Diabetes Care differentiates via smart algorithm development and touchscreen interface design.
An insulin infusion pump is a programmable electromechanical device that delivers rapid-acting insulin through a subcutaneous catheter at programmed basal rates and patient-initiated bolus doses, typically operating with precision of 0.025 to 0.1 units per hour. Its primary commercial purpose is to replicate physiological pancreatic beta-cell function for glycemic management in diabetic patients. Patch pumps now lead volume growth due to reduced tubing burden and discrete wearability, while integrated CGM technology commands the deepest margin pools through recurring sensor revenue. Tubed pumps retain structural importance in pediatric diabetes and specialized center settings where dosing complexity demands maximum programmability.
FDA premarket notification pathways and EMA Medical Device Regulation conformity assessments shape product launch cadence and software update protocols across major markets. ISO 15197 and IEC 62304 standards govern glucose monitoring accuracy and medical device software lifecycle requirements, directly influencing R&D resource allocation. WHO prequalification initiatives for low-and-middle-income country access are expanding addressable patient populations beyond traditional reimbursement strongholds. Stakeholders must monitor evolving cybersecurity guidance from FDA and post-market surveillance requirements under EU MDR as predicate for sustained market access.
Market Dynamics
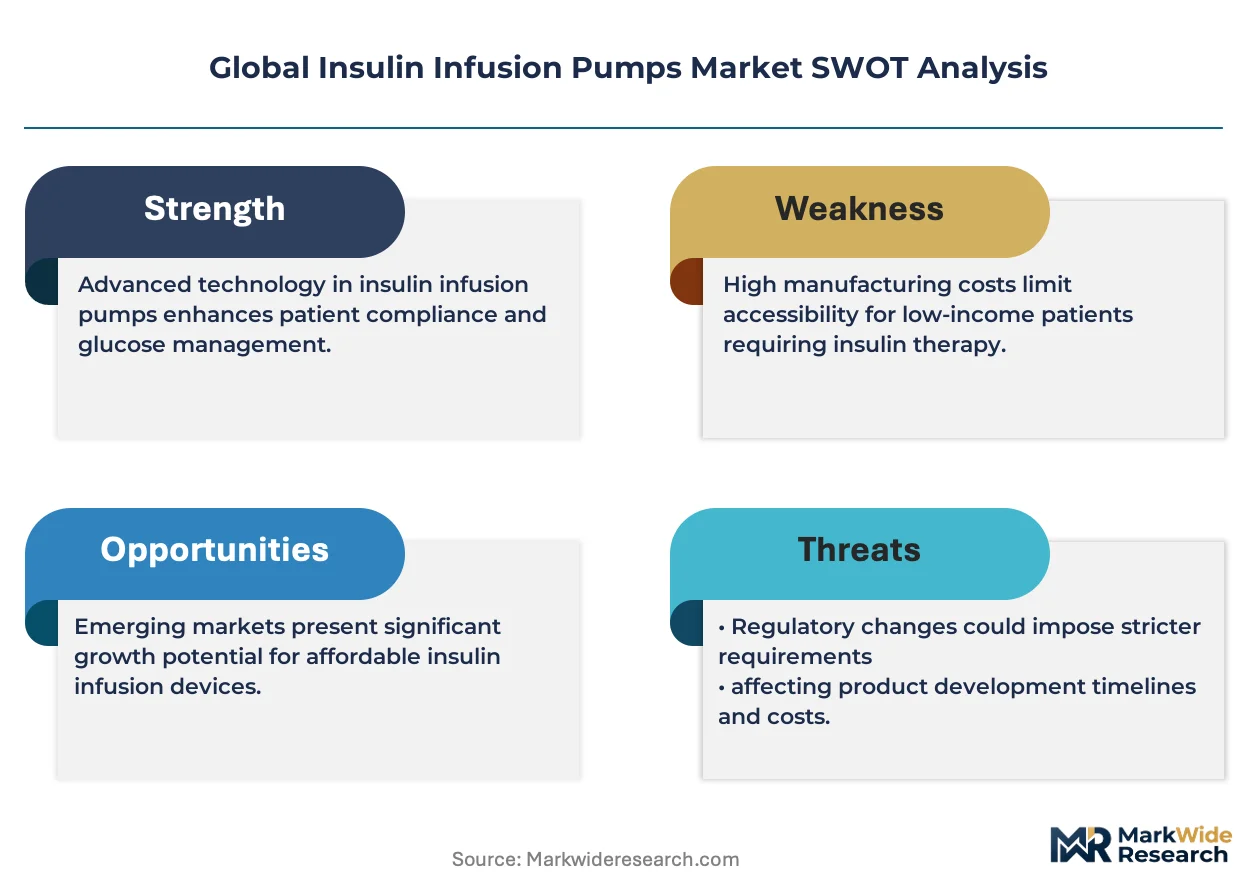
Integration of continuous glucose monitoring with insulin delivery systems is compressing competitive differentiation timelines and forcing R&D budget reallocation toward software algorithm development.
Growth Catalysts
- Reimbursement framework maturation:Germany's statutory health insurance system now covers patch pump systems for Type 1 diabetes patients, expanding addressable patient pools beyond traditional tubed pump candidates.
- WHO prequalification pathways:The organization's medical device prequalification program for low-and-middle-income countries is opening procurement channels previously inaccessible to commercial manufacturers.
- Sensor miniaturization:Advances in microelectromechanical systems are enabling 14-day wear durations for integrated CGM sensors, reducing patient burden and improving adherence metrics.
Market Restraints
- Supply concentration in semiconductor substrates:Precision dosing chips rely on foundry capacity concentrated in Taiwan, creating vulnerability to geopolitical disruption or capacity constraints.
- EMA MDR transition friction:The Medical Device Regulation's enhanced clinical evidence requirements are extending conformity assessment timelines for software-updatable devices.
- Disposable component cost structures:Single-use infusion sets and sensors generate recurring out-of-pocket expenses that limit adoption among underinsured populations in the United States.
Strategic Opportunities
- Direct-to-consumer channel expansion:Brazil's ANVISA has streamlined registration for consumer-facing diabetes management devices, enabling bypass of traditional hospital procurement.
- Pediatric algorithm specialization:Closed-loop systems optimized for glycemic variability patterns in children represent an underserved application with distinct regulatory and clinical requirements.
- AI-enabled predictive dosing:Machine learning integration with insulin delivery is creating differentiation opportunities separate from hardware specification competition.
Industry Challenges
- Cybersecurity validation complexity:FDA's premarket guidance for interconnected devices requires specialized firmware engineering talent that competes with broader medical device and automotive sectors.
- Legacy EHR integration:Hospital information system compatibility requirements vary across Japan's prefectural health networks, complicating enterprise sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Insulin Infusion Pumps Market |
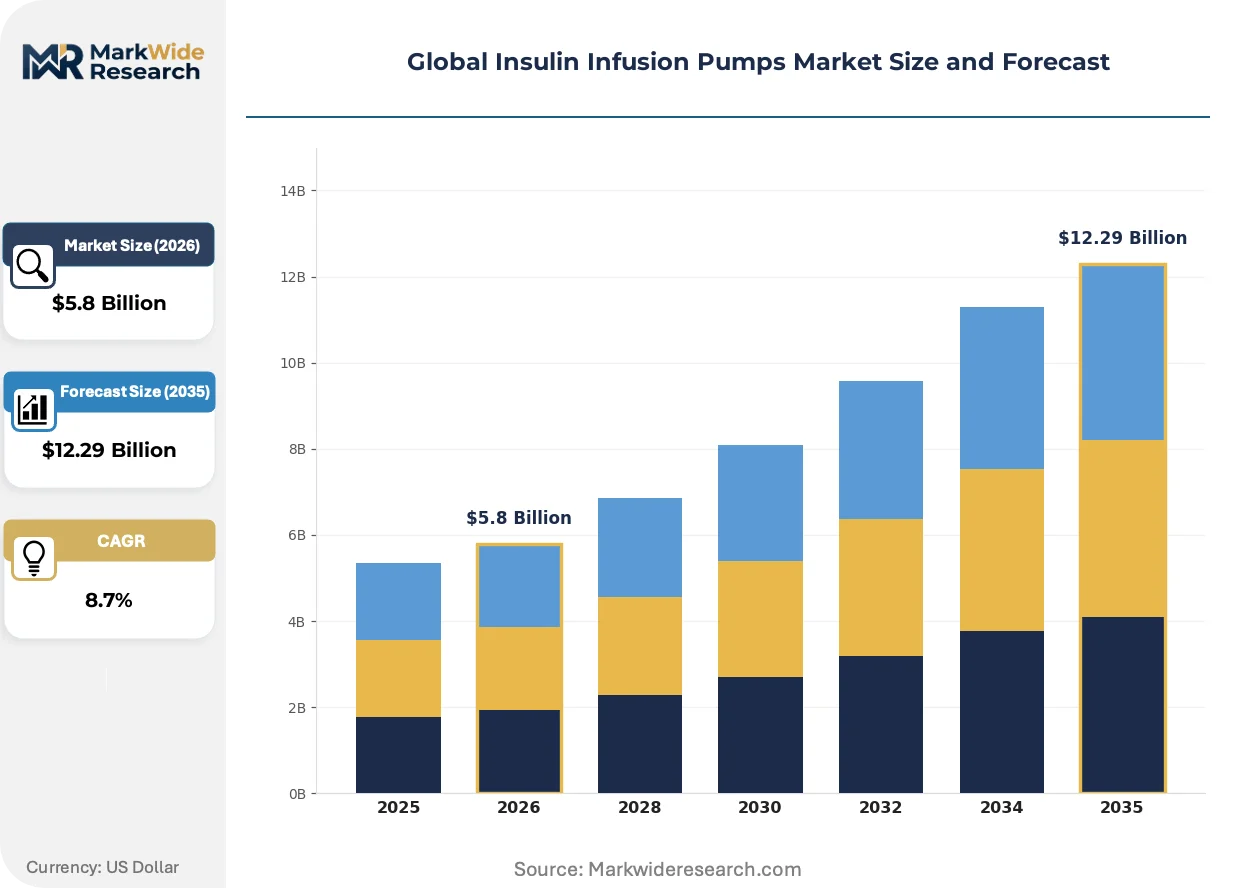
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $12.29 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Patch Pumps, Tubed Pumps, Disposable Pumps, Wearable Pumps Technology: Bluetooth Connectivity, Integrated CGM, Wireless Charging, Smart Algorithms, Remote Monitoring Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Pediatric Diabetes, Renal Diabetes End User: Diabetes Clinics, Specialized Centers, Home Care Providers, Ambulatory Care |
| Companies Covered | Medtronic, Insulet Corporation, Tandem Diabetes Care, F. Hoffmann-La Roche Ltd, Ypsomed AG, SOOIL Development, Medtrum Technologies, EOFlow, Apex Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Insulin Infusion Pumps Market Shifts & Advancements
Algorithm-driven automation is displacing manual patient intervention as the primary value proposition, while regulatory frameworks race to catch up with software-as-medical-device classification.
Closed-loop artificial pancreas systems are displacing conventional hybrid closed-loop configurations in premium market tiers. Pediatric endocrinology centers in the United States and Germany are adopting these systems at accelerating rates. This displacement is compressing margins for manufacturers lacking proprietary algorithm portfolios.
EU MDR's software lifecycle requirements are mandating documented validation protocols for every over-the-air update. Manufacturers must now maintain quality management systems that treat firmware revisions as design changes. Patch pump developers face particular scrutiny given their reliance on smartphone control applications.
Patient data ownership preferences are fragmenting traditional care team relationships. Direct device-to-cloud connectivity enables individuals to share glycemic data selectively with clinicians, family members, or research platforms. This behavioral shift is most pronounced among working-age Type 1 diabetes patients in Japan and the United States.
Global Insulin Infusion Pumps Market Segmentation
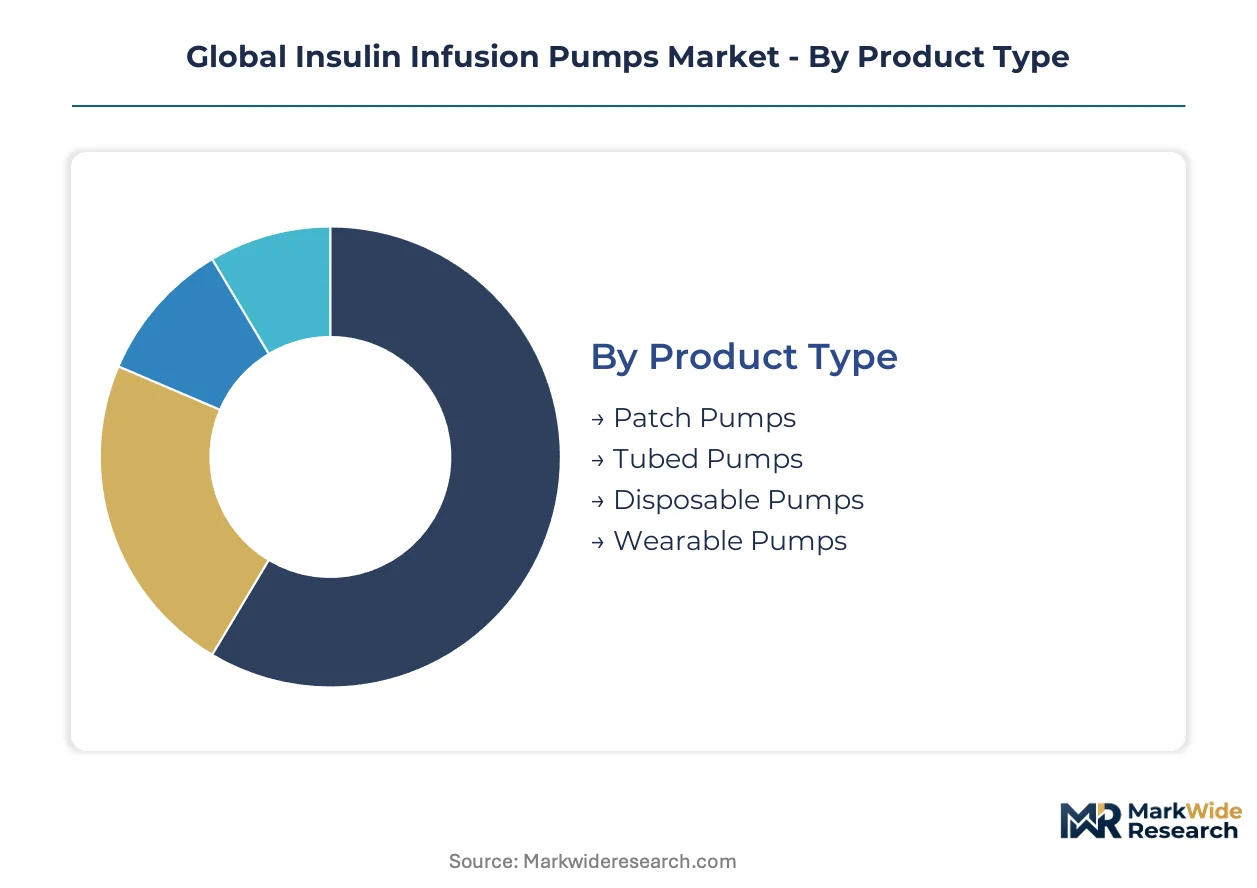
Insulin infusion pump manufacturers allocate R&D budgets across distinct technical and clinical dimensions. Each segmentation axis carries unique regulatory pathways, reimbursement codes, and competitive intensity profiles that determine margin capture.
Product Type:
FDA 510(k) clearance timelines and EMA MDR conformity assessments diverge sharply across pump architectures, creating structural advantages for certain form factors.
- Patch Pumps:Tubeless adhesive devices attach directly to skin with integrated insulin reservoir and cannula. Home care providers in Germany and Japan are expanding procurement of these systems as statutory reimbursement frameworks mature for Type 1 diabetes management.
- Tubed Pumps:Traditional devices connect reservoir to infusion set via flexible tubing, offering maximum basal rate programmability down to 0.025 units per hour. Pediatric diabetes centers in the United States retain preference for this architecture due to dosing precision requirements in small children.
- Disposable Pumps:Single-use devices with pre-filled insulin cartridges eliminate maintenance burden. These systems appeal to underinsured populations seeking lower upfront capital commitment.
- Wearable Pumps:Hybrid designs combine patch convenience with tubed pump reservoir capacity. Japan's PMDA has streamlined review pathways for these intermediate configurations.
Patch pumps handle the majority of new patient onboarding volume; disposable pumps are expanding most quickly in emerging reimbursement markets.
Technology:
Cost tier stratification separates premium integrated systems from connectivity-only configurations, with algorithm development consuming disproportionate engineering resources.
- Bluetooth Connectivity:Standard wireless protocol enabling smartphone control and data transmission. This capability now serves as baseline hygiene factor rather than differentiation lever across United States and European markets.
- Integrated CGM:Continuous glucose monitoring sensors embedded within pump ecosystem, generating recurring sensor revenue streams. Germany's statutory health insurance system now covers these integrated systems, expanding addressable patient pools beyond traditional pump candidates.
- Wireless Charging:Inductive power transfer eliminating battery replacement routines. This specification concentrates demand among working-age Type 1 patients in Japan seeking discrete device management.
- Smart Algorithms:Predictive insulin dosing based on glucose trend analysis and meal detection. FDA premarket notification pathways for algorithm-updatable devices are extending development timelines.
- Remote Monitoring:Cloud-based data sharing with clinicians and caregivers. Pediatric endocrinology centers in the United States are adopting these capabilities at accelerating rates for adolescent patient populations.
Integrated CGM commands the deepest margin pools; smart algorithms are gaining share fastest as competitive differentiation migrates toward software.
Application:
Patient population heterogeneity drives distinct clinical requirements, reimbursement coding, and device specification priorities across diabetes subtypes.
- Type 1 Diabetes:Autoimmune beta-cell destruction requiring exogenous insulin replacement. This population constitutes the core addressable market for closed-loop artificial pancreas systems in Germany, Japan, and the United States.
- Type 2 Diabetes:Insulin resistance with progressive beta-cell dysfunction. Pump adoption remains limited to advanced cases failing multiple daily injection regimens, with reimbursement authorization requiring documented glycemic variability.
- Gestational Diabetes:Glucose intolerance during pregnancy requiring intensive insulin management. Short-duration therapy needs favor rental or hospital-based pump programs over capital equipment purchase.
- Pediatric Diabetes:Glycemic management in patients under 18 years with distinct insulin sensitivity patterns. FDA has established specialized review pathways for devices targeting this indication.
- Renal Diabetes:Diabetes complicated by chronic kidney disease with altered insulin pharmacokinetics. Specialized centers in Japan are developing dosing protocols for this underserved application.
Type 1 diabetes handles the majority of device throughput; pediatric diabetes is climbing the fastest on share as closed-loop systems penetrate specialty centers.
End User:
Procurement authority and reimbursement flow differ materially across care settings, shaping sales cycle complexity and pricing negotiation leverage.
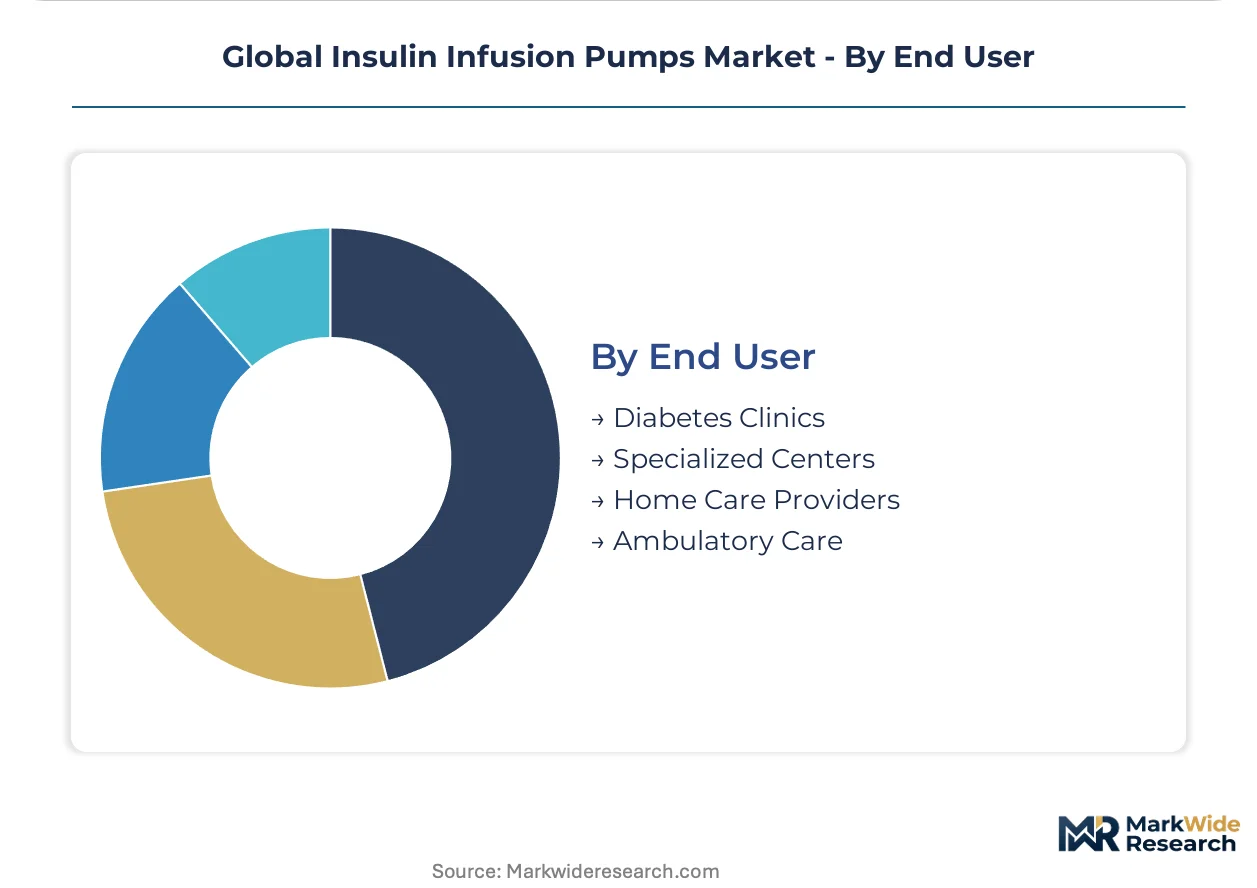
- Diabetes Clinics:Outpatient facilities with dedicated pump initiation programs. These sites concentrate patient training resources and drive initial device selection in United States metropolitan markets.
- Specialized Centers:Academic medical centers with research protocols and complex case referral networks. EMA MDR's enhanced clinical evidence requirements are extending enterprise sales cycles into these institutions.
- Home Care Providers:Distributors and service organizations managing direct-to-patient logistics. Brazil's ANVISA has streamlined registration enabling these channels to bypass traditional hospital procurement.
- Ambulatory Care:General practice and community health settings with limited pump expertise. WHO prequalification initiatives are expanding addressable populations through these access points in low-and-middle-income countries.
Diabetes clinics handle the majority of new patient throughput; home care providers are gaining share fastest as direct-to-consumer channels mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports integrated pump systems to Japan and the United States through specialized medical device distributors, while component suppliers in Taiwan feed precision dosing chips to assembly facilities across North America and Europe.
United States
Pediatric endocrinology centers in Boston and San Francisco drive closed-loop system procurement, with FDA premarket notification pathways accelerating algorithm-updatable device reviews. The Southeast corridor concentrates patch pump distribution infrastructure serving underinsured populations.
Germany
Statutory health insurance coverage for patch pump systems expanded patient pools beyond traditional tubed pump candidates, with EMA MDR conformity assessments shaping software update protocols. The Baden-Württemberg cluster hosts specialized diabetes technology research consortia.
Japan
PMDA streamlined review pathways for wearable pump configurations, while METI standards govern wireless charging specifications preferred by working-age Type 1 patients. The Kanto region concentrates hospital information system integration expertise for enterprise sales.
Brazil
ANVISA registration streamlining enabled direct-to-consumer channels bypassing traditional hospital procurement, expanding home care provider penetration. São Paulo anchors diabetes clinic networks managing pump initiation programs for Type 1 populations.
South Korea
MFDS medical device approval pathways support export-oriented manufacturing for integrated CGM ecosystems, with Seoul Capital Area hosting algorithm development talent pools. Local distributors supply patch pump systems to Japan and Southeast Asian markets.
Global Insulin Infusion Pumps Market Competitive Landscape
Listed leaders compete with private specialists across software algorithm development and direct-to-consumer channel control. The vendor base concentrates around three technology archetypes: integrated CGM pipeline owners, patch pump specialization firms, and touchscreen interface developers. Strategic moves center on M&A for algorithm portfolios and geographic expansion through regulatory pathway optimization.
Within the integrated technology tier, Medtronic and Tandem Diabetes Care occupy positions exemplifying closed-loop system development, while Insulet Corporation anchors the patch pump specialization archetype through tubeless adhesive device focus. These three firms represent distinct competitive vectors—hardware-software integration, form factor innovation, and algorithm-driven automation—each commanding differential margin pools based on recurring sensor revenue versus capital equipment sales.
| Leading Market Players |
|---|
| Medtronic |
| Insulet Corporation |
| Tandem Diabetes Care |
| F. Hoffmann-La Roche Ltd |
| Ypsomed AG |
| SOOIL Development |
| Medtrum Technologies |
| EOFlow |
| Apex Medical |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation agreements with Taiwan-based semiconductor foundries lock in both precision dosing chip supply and cost visibility for insulin pump manufacturers navigating FDA and EMA regulatory pathways. These contractual structures insulate tier-one vendors from spot-market volatility while embedding volume commitments that shape competitive entry barriers.
Pricing Analysis
Current-generation closed-loop artificial pancreas systems command substantial premiums over prior-generation hybrid closed-loop configurations, while next-generation AI-enabled predictive dosing platforms are entering pilot pricing programs. Three-tier pricing structure across premium integrated CGM ecosystems, standard connectivity-enabled pumps, and economy disposable devices stratifies the market. Cost compression in the standard tier intensifies because Bluetooth connectivity has become a baseline hygiene factor rather than differentiation. Uninsured and underinsured populations in the United States exhibit highest price sensitivity, while pediatric diabetes centers demonstrate lowest sensitivity due to reimbursement coverage and clinical outcome priorities.
Supply Chain Analysis
Inbound logistics costs through the Trans-Pacific trade lane fluctuate with container availability at Taiwanese ports, directly affecting landed costs for precision semiconductor components. Manufacturing concentration rests on Taiwan for dosing chips, South Korea for sensor microelectromechanical systems, and Germany for specialized polymer infusion sets. Raw material dependencies include medical-grade silicone tubing, lithium-polymer battery cells, and subcutaneous-grade steel cannulas. Single-source vulnerability in Taiwan semiconductor foundry capacity represents the dominant structural risk. Distribution runs through specialized medical device distributors in Germany and direct-to-consumer channels in Brazil and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The insulin infusion pump market is accelerating through FDA premarket notification streamlining for algorithm-updatable devices, creating a regulatory inflection that rewards software-centric competitive positioning.
For Market Incumbents: Fortify algorithm portfolios through targeted acquisition of machine learning specialists and deepen captive production of CGM sensor substrates to offset Taiwan foundry concentration risk. Closed-loop artificial pancreas systems from emerging South Korean and Chinese developers threaten technology leadership positions held by established vendors. For New Entrants and Emerging Players: Differentiate on pediatric algorithm specialization and direct-to-consumer channel control in Brazil's streamlined ANVISA registration environment. Gestational diabetes rental programs and renal diabetes dosing protocols represent the most penetrable white-space applications. Go-to-market execution should prioritize home care provider partnerships over hospital procurement cycles. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated CGM pipeline owners with demonstrated FDA clearance velocity and recurring sensor revenue streams. Long-term viability hinges on software-as-medical-device regulatory navigation capabilities across the five-to-ten year horizon. Watch for EMA MDR transition completion timelines as the critical inflection signal for European market access scalability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for Algorithm-Updatable Device | Accelerates market entry through streamlined 510(k) pathways for AI-enabled dosing systems. |
| CE Marking Pathway under EU MDR | Unlocks statutory reimbursement coverage in Germany's patch pump expansion framework. |
| Hospital System Partnership | Secures preferred vendor status at pediatric endocrinology centers in Boston and San Francisco. |
| Software Companion Development | Enables smartphone control applications that satisfy PMDA streamlined review for wearable pumps. |
| Reimbursement Strategy | Positions integrated CGM systems for WHO prequalification procurement in low-and-middle-income markets. |
Research Methodology
A standing panel of pediatric endocrinologists, hospital GPO contracts managers, biomedical engineers, and regulatory affairs specialists provided ongoing calibration throughout the research process. Primary interview data combined with secondary validation from FDA 510(k) filings, EMA MDR submission databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up patient population modeling and top-down manufacturer revenue analysis underwent iterative triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including pump architecture, technology integration level, diabetes subtype, and end-user procurement channel. CAGRs derived from patient onboarding rates, reimbursement expansion trajectories, and sensor replacement frequency assumptions. Forecast inputs incorporated ISO 15197 glucose accuracy standards and IEC 62304 software lifecycle requirements.
Material uncertainties — reimbursement authorization delays, semiconductor supply disruptions, cybersecurity guidance revisions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory pathway timelines and sensor miniaturization curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Italy Oral Anti-Diabetic Drug Market
Diabetes Care
Italy Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Oman Diabetes Care Devices Market
Diabetes Care
Self-Monitoring Blood Glucose Devices Market
Diabetes Care
North America Insulin Infusion Pumps Market
Diabetes Care
Vietnam Diabetes Care Devices Market
Diabetes Care
Self-Monitoring Blood Glucose (SMBG) Market
Diabetes Care
India Oral Anti-Diabetic Drug Market
Diabetes Care
Alternatives for Injectable Diabetes Care Market
Diabetes Care
Combination Anti-Diabetes Drugs Market
Diabetes Care
Australia Continuous Glucose Monitoring Devices Market
Diabetes Care
Italy Continuous Glucose Monitoring Devices Market
Diabetes Care
Next Generation Diabetes Therapy and Drug Delivery Market
Diabetes Care
APAC Insulin Infusion Pumps Market
Diabetes Care
Asia Pacific Blood Glucose Monitoring Market
Diabetes Care
Antidiabetics Market