
 Call Center Outsourcing Market | 2026-2036
Call Center Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Call Center Outsourcing Market Analysis
Omnichannel delivery infrastructure is reshaping competitive dynamics across the call center outsourcing landscape. Teleperformance leverages its geographic footprint across 170 countries to sustain operational resilience at scale. Alorica anchors its model through workforce development programs that reduce agent attrition in high-churn environments. SupportNinja specializes in nearshore delivery for technology startups seeking cultural alignment with North American customers.
Call center outsourcing encompasses the delegation of customer interaction management to third-party providers operating voice, digital, and self-service channels, typically governed by service level agreements specifying average handle time, first-call resolution rates, and customer satisfaction thresholds. The primary commercial purpose centers on converting fixed labor costs into variable operational expenditure while accessing specialized expertise unavailable in-house. Inbound services and technical support command premium pricing due to the specialized agent skill sets and longer training curves required, while outbound services face margin compression from regulatory restrictions on telemarketing practices. Cloud-based solutions and AI-driven systems represent the fastest-expanding technology segments as enterprises replace legacy on-premise automatic call distribution hardware with elastic, API-integrated platforms.
The US Federal Communications Commission enforces Telephone Consumer Protection Act restrictions that constrain outbound dialing strategies and shape compliance investments across American-facing operations. India's Telecom Regulatory Authority of India governs telecom infrastructure quality standards that directly affect voice clarity and connectivity uptime for offshore delivery centers. The European Union's General Data Protection Regulation imposes data residency and cross-border transfer requirements that increase operational complexity for multi-national contracts. Stakeholders must evaluate whether nearshore diversification or automation-first architectures offer more durable risk-adjusted returns as labor arbitrage advantages erode.
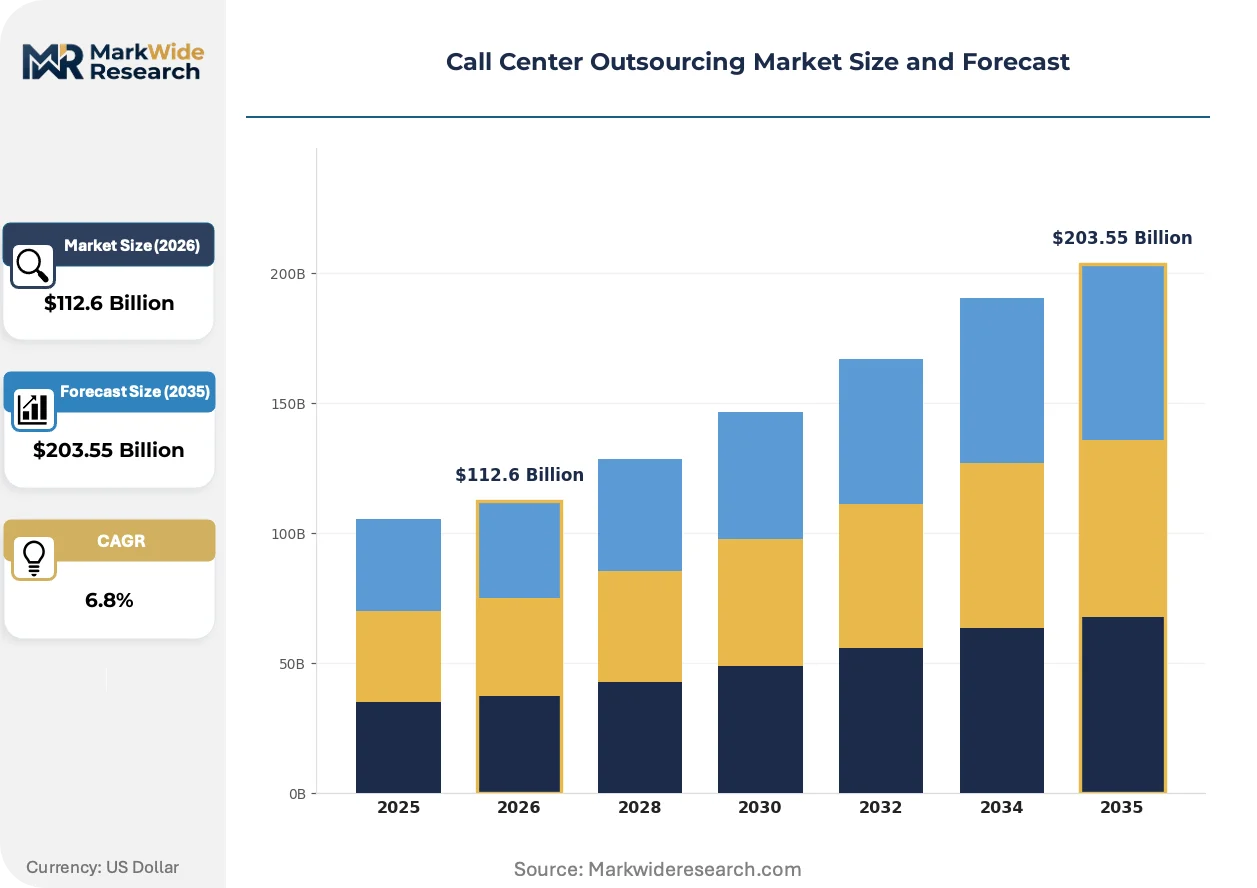
Market Dynamics
Cloud migration and AI integration are compressing infrastructure costs while forcing legacy automatic call distribution systems into obsolescence across outsourced customer service operations.
Growth Catalysts
- Healthcare outsourcing expansion:Patient engagement and billing support operations are migrating to third-party providers as hospitals seek operational expenditure flexibility.
- TRAI infrastructure standards:India's Telecom Regulatory Authority mandates voice clarity and connectivity uptime benchmarks that enhance offshore delivery reliability for voice-centric contracts.
- API-integrated platforms:Elastic cloud architectures are replacing on-premise hardware, enabling rapid scaling without capital-intensive infrastructure deployment.
Market Restraints
- FCC compliance burden:The US Telephone Consumer Protection Act constrains outbound dialing strategies, forcing compliance investments that compress margins on telemarketing services.
- Agent attrition economics:High-turnover environments in India and the Philippines drive recurring recruitment and training costs that offset labor arbitrage gains.
- Data residency complexity:GDPR cross-border transfer requirements impose operational friction on multi-national contracts requiring EU customer data handling.
Strategic Opportunities
- Nearshore technology startup segment:Cultural alignment demands from North American SaaS companies create premium pricing potential for Mexico and Colombia delivery centers.
- AI-human hybrid models:Converging natural language processing with live agent escalation pathways opens new service tiers between full automation and traditional voice support.
- EU AI Act preparation services:Compliance consulting and algorithmic audit capabilities represent emerging revenue streams as European enterprises face automated decision-making transparency mandates.
Industry Challenges
- Multilingual technical talent scarcity:Specialized agent skill sets for healthcare and financial services verticals require extended training curves that delay contract ramp-up.
- Legacy system integration friction:Enterprise clients maintain heterogeneous CRM environments that complicate unified agent desktop deployments and API standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Call Center Outsourcing Market |
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $203.55 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inbound Services, Outbound Services, Technical Support, Customer Service Industry Vertical: Telecommunications, Healthcare, Retail, Financial Services Technology: Cloud-based Solutions, AI-driven Systems, Automated Response, Omnichannel Platforms End User: Small Enterprises, Large Corporations, Non-profits, Government Agencies |
| Companies Covered | TaskUs, Alorica, Concentrix + Webhelp, Atento, SupportNinja, Teleperformance, TTEC, WOW24-7, Foundever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Call Center Outsourcing Market Emerging Trajectories
Agent augmentation technologies are reconfiguring workforce economics while regulatory data frameworks and buyer procurement preferences reshape contract structures across outsourced customer operations.
Conversational AI platforms are digitizing routine inquiry resolution through natural language understanding engines that handle password resets, order status checks, and appointment scheduling. Mid-market enterprises are deploying these systems fastest, often starting with after-hours coverage before expanding to overflow handling. The technology is digitizing tier-one support volumes, compressing headcount requirements for basic transactional interactions while elevating live agents to exception handling and revenue-generating conversations.
GDPR data residency enforcement is fragmenting multi-national contract architectures as European enterprises demand EU-located infrastructure and restricted cross-border data flows. Providers must maintain redundant delivery centers across Dublin, Warsaw, and Lisbon to serve pan-European clients without triggering transfer mechanism complexity. Financial services and healthcare verticals face the strictest interpretation, with some German insurers requiring in-country agent seating for all policyholder interactions.
Outcome-based pricing models are displacing traditional per-agent-hour contracts as enterprise procurement teams demand measurable customer satisfaction and first-call resolution guarantees. Technology and retail verticals are driving this shift fastest, with some agreements tying fifty percent of fees to net promoter score achievement. The transformation is most visible in US-headquartered contracts, where CFO scrutiny of contact center spend has intensified following pandemic-era volume spikes that exposed cost structure rigidity.
Call Center Outsourcing Market Segmentation
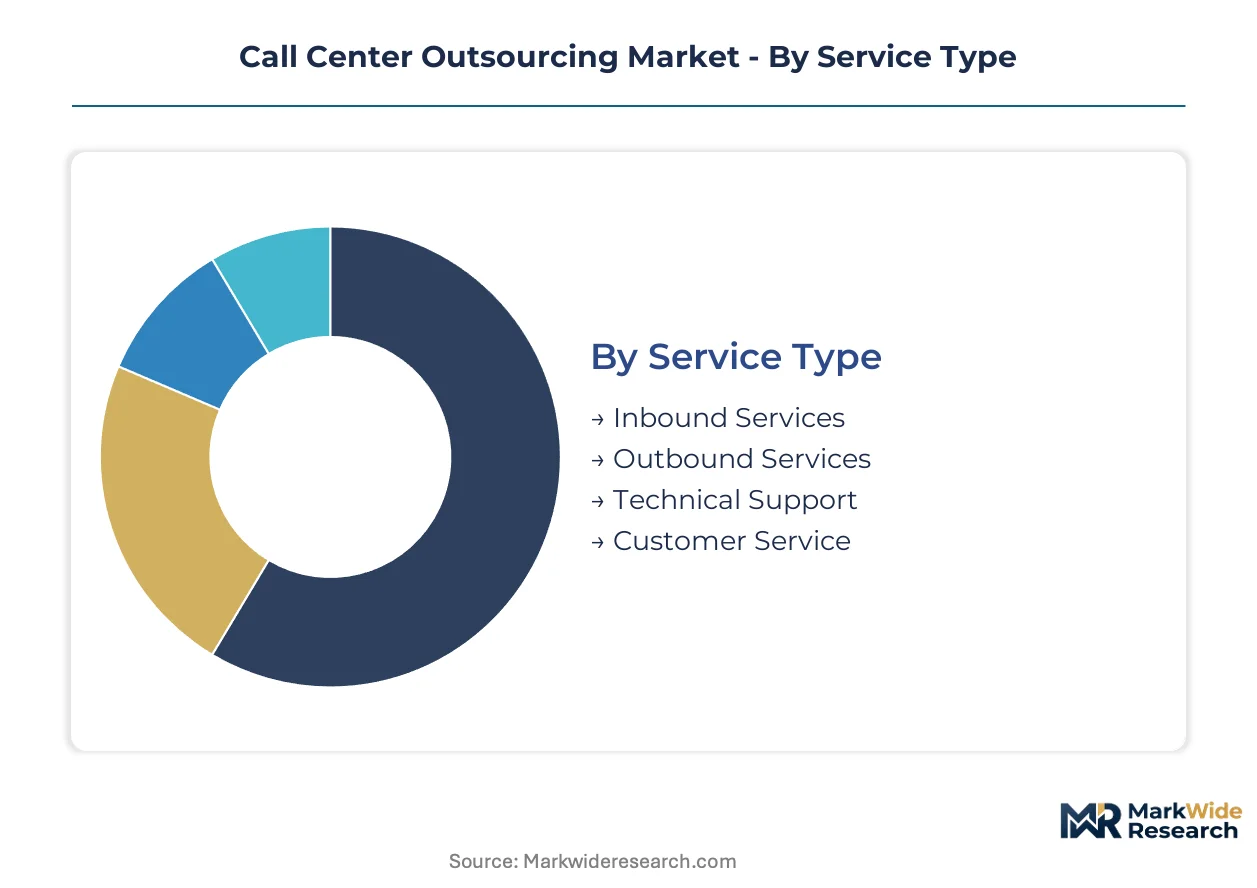
Service differentiation in call center outsourcing determines contract pricing tiers and margin sustainability. Segment boundaries increasingly blur as AI-augmented delivery models reshape traditional category definitions.
Service Type:
After-sales service intensity varies dramatically across service categories, with technical support and inbound operations requiring sustained agent engagement versus transactional outbound campaigns.
- Inbound Services:Voice and digital channels handling customer-initiated contacts including billing inquiries, order tracking, and account management. Healthcare providers in the United States concentrate demand here as patient engagement outsourcing accelerates under operational expenditure pressures.
- Technical Support:Specialized troubleshooting for software, hardware, and telecommunications products requiring certified agent credentials and extended training curricula. SaaS companies in North America drive premium pricing for nearshore delivery with cultural alignment requirements.
- Outbound Services:Telemarketing, collections, and survey administration facing margin compression from FCC Telephone Consumer Protection Act compliance investments.
- Customer Service:General inquiry resolution spanning multiple touchpoints with standardized scripting and quality monitoring protocols.
By volume, Inbound Services leads. By growth pace, Technical Support is ahead.
Industry Vertical:
Cost tier stratification separates regulated verticals with compliance premiums from retail sectors competing on unit economics.
- Healthcare:Patient engagement, appointment scheduling, and revenue cycle management requiring HIPAA-compliant infrastructure and specialized medical terminology training. Hospital systems across India and the Philippines expand offshore contracts to convert fixed labor costs into variable expenditure.
- Financial Services:Banking, insurance, and wealth management support demanding PCI-DSS data security protocols and fraud prevention capabilities. GDPR data residency requirements fragment European contract architectures toward Dublin and Warsaw delivery centers.
- Telecommunications:Subscriber acquisition, retention, and technical troubleshooting with high call volume elasticity and seasonal demand spikes.
- Retail:Order management, returns processing, and loyalty program support with intense price competition and outcome-based pricing pressure.
Healthcare commands the highest contract values. Retail shows the steepest expansion trajectory as e-commerce penetration deepens.
Technology:
Application maturity separates legacy automatic call distribution deployments from API-integrated cloud architectures.
- Cloud-based Solutions:Elastic infrastructure replacing on-premise hardware with rapid scaling capabilities and reduced capital deployment. Mid-market enterprises across the United States adopt these platforms fastest for overflow and after-hours coverage.
- AI-driven Systems:Natural language processing engines handling tier-one inquiry resolution with live agent escalation pathways. European enterprises invest here ahead of EU AI Act transparency mandates.
- Automated Response:Interactive voice response and chatbot deployments for password resets, balance inquiries, and appointment scheduling.
- Omnichannel Platforms:Unified voice, email, chat, and social media routing with persistent customer context across touchpoints.
Cloud-based Solutions dominate current deployment volume. AI-driven Systems are climbing fastest as agent augmentation economics improve.
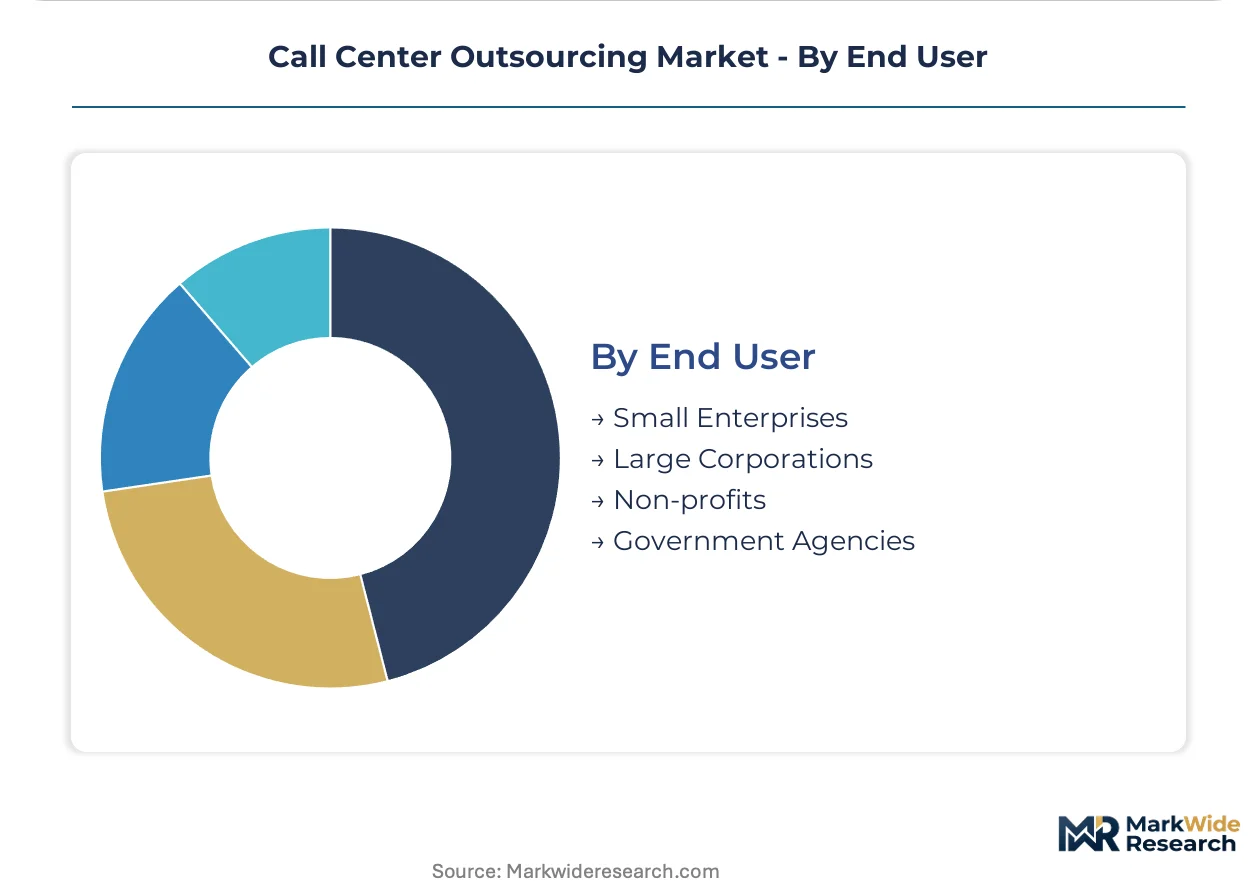
End User:
Customer type dictates procurement sophistication and contract structure complexity.
- Large Corporations:Multi-year agreements with outcome-based pricing tied to net promoter scores and first-call resolution guarantees. Technology and retail verticals in North America drive this shift with CFO scrutiny intensifying following pandemic-era volume spikes.
- Small Enterprises:Flexible, short-term contracts prioritizing rapid deployment over customization with pay-per-use cloud consumption models.
- Government Agencies:RFP-driven procurement with strict security clearance requirements and domestic seating mandates affecting offshore delivery feasibility.
- Non-profits:Cost-constrained donor engagement and volunteer coordination with limited technology integration requirements.
Large Corporations anchor revenue concentration. Small Enterprises are gaining share fastest as self-service platform accessibility improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Submarine cable infrastructure underwrites the Philippines' position as a voice-centric delivery hub, with the SEA-US and Asia-America Gateway cables enabling sub-50ms latency to North American markets. Metro Manila and Cebu City concentrate over 1.3 million seats across outsourced customer operations.
United States
Healthcare systems in Texas and Florida are expanding patient engagement outsourcing to convert fixed labor costs into variable expenditure. The FCC's Telephone Consumer Protection Act constrains outbound dialing strategies, forcing compliance investments that compress telemarketing margins. Dallas-Fort Worth and Phoenix host major onshore delivery centers serving domestic-only contracts with strict data residency requirements.
India
TRAI-mandated voice clarity and connectivity uptime benchmarks enhance offshore delivery reliability for voice-centric contracts. Bangalore and Hyderabad lead cloud migration adoption, with API-integrated platforms replacing legacy automatic call distribution hardware. The country's national IT regulator enforces data localization norms that complicate multi-national contract architectures.
Philippines
Metro Manila anchors voice-centric operations with cultural affinity advantages for North American customer bases. The national telecom regulator maintains infrastructure quality standards that directly affect connectivity uptime for offshore delivery centers. Cebu City and Davao are expanding as secondary hubs to diversify geographic risk beyond the capital region.
Mexico
SaaS companies seeking cultural alignment with North American customers are concentrating demand in Guadalajara and Mexico City. The federal telecommunications regulator oversees voice service quality standards that affect nearshore delivery reliability. Monterrey is emerging as a technical support specialization hub with bilingual engineering talent pools.
Ireland
GDPR data residency requirements are fragmenting European contract architectures toward Dublin delivery centers. The national data protection authority enforces strict cross-border transfer protocols that increase operational complexity for multi-national contracts. Cork and Galway host redundant facilities serving pan-European financial services clients requiring EU-located infrastructure.
Call Center Outsourcing Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in workforce development and compliance consulting. The vendor base clusters around three strategic archetypes: geographic footprint aggregators sustaining operational resilience at scale, workforce development specialists reducing agent attrition in high-churn environments, and nearshore delivery operators capturing cultural alignment premiums. Consolidation pressure is intensifying through strategic partnerships and outcome-based pricing model adoption.
Among the named players, Teleperformance exemplifies the geographic footprint aggregator archetype with operations spanning 170 countries. Alorica anchors the workforce development specialist position through training programs targeting retention in high-churn delivery environments. SupportNinja occupies the nearshore technology startup segment, serving North American SaaS companies from Mexico and Colombia delivery centers.
| Leading Market Players |
|---|
| TaskUs |
| Alorica |
| Concentrix + Webhelp |
| Atento |
| SupportNinja |
| Teleperformance |
| TTEC |
| WOW24-7 |
| Foundever |
| Others |
Supply Flow & Price Mechanics
Metro Manila's 1.3 million seat concentration compresses margins on voice-centric contracts as capacity gluts force rate competition, while cloud migration in Bangalore and Hyderabad enables premium pricing for API-integrated delivery models.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates contract architectures. Premium tiers attach to HIPAA-compliant healthcare engagements and GDPR-constrained European delivery, while economy tiers serve high-volume retail overflow with outcome-based net promoter score guarantees. Cost compression in telemarketing services intensifies because FCC Telephone Consumer Protection Act compliance investments erode margins. Small enterprises exhibit highest price sensitivity, prioritizing pay-per-use cloud consumption over customized deployments.
Supply Chain Analysis
Upstream talent pipelines in India, the Philippines, and Mexico feed agent supply into delivery center networks. Workforce development programs, submarine cable infrastructure, and bilingual engineering curricula constitute critical inputs. Single-source vulnerability concentrates in Metro Manila's voice-centric operations, where geographic risk from natural disasters or political disruption lacks adequate redundancy. Distribution runs through direct enterprise contracts and RFP-driven government procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Call center outsourcing operates as a defensive-moat industry where multi-year contract lock-ins and specialized agent training create switching costs that protect incumbent positions.
For Market Incumbents: Build regulatory compliance moats by embedding HIPAA and GDPR certification into delivery center infrastructure before EU AI Act transparency mandates take effect. Expand redundant facilities in Cebu City and Davao to dilute Metro Manila geographic concentration risk. Alorica's workforce development model offers a template for reducing agent attrition economics that threaten labor arbitrage gains. For New Entrants and Emerging Players: Pursue nearshore technology startup segments in Guadalajara and Monterrey where North American SaaS companies pay premiums for cultural alignment. Target AI-human hybrid service tiers that incumbent legacy architectures cannot deploy rapidly. Lead with API-integrated platform capabilities rather than competing on per-agent-hour rates. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors workforce development specialists with proven retention programs over pure geographic footprint aggregators. Long-term viability hinges on automation-first architectures that compress headcount requirements for tier-one interactions. Monitor cloud migration adoption curves in mid-market enterprises as inflection indicators for platform-switching velocity.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Human Hybrid Model Deployment | Natural language processing engines with live agent escalation capture margin between full automation and traditional voice support. |
| Nearshore Delivery Center Expansion | Guadalajara and Mexico City facilities serve North American SaaS companies seeking cultural alignment premiums. |
| GDPR Compliance Infrastructure Investment | Dublin, Warsaw, and Lisbon redundant facilities enable pan-European contracts without cross-border transfer complexity. |
| Outcome-Based Pricing Transition | Net promoter score guarantees replace per-agent-hour contracts under CFO scrutiny of contact center expenditure rigidity. |
| Workforce Development Program Scaling | Specialized medical terminology and certified agent credentials reduce attrition economics in high-churn delivery environments. |
Methodological Framework
Desk research of regulatory filings, telecom infrastructure disclosures, and enterprise procurement databases preceded structured interviews with contact center operations directors, CIOs at healthcare systems, SaaS customer success executives, and workforce development specialists. Primary fieldwork captured contract structure evolution and cloud migration timelines. Secondary validation drew from TRAI infrastructure reports, FCC enforcement actions, and EU data protection authority guidance. Bottom-up seat-count analysis and top-down market sizing triangulated volume estimates.
Assumptions held fixed include prevailing regulatory frameworks across the analysis window, while AI adoption curves and nearshore demand shifts were modeled as scenario variables. Segmentation dimensions covered service type, industry vertical, technology deployment model, organization size tier, and regional delivery hub. CAGRs derived from historical growth pattern analysis applied to seat expansion and pricing trajectory inputs. Cloud infrastructure capex disclosures and agent wage inflation indices informed cost-side projections.
Sensitivities concentrate around FCC enforcement intensity on outbound dialing, EU AI Act implementation timelines, and submarine cable disruption scenarios. Cross-checking against enterprise IT spending surveys and contact center technology adoption benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Global Software Outsourcing Market
Business Process Outsourcing (BPO)
Europe Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Business Processing Outsourcing Market
Business Process Outsourcing (BPO)
Healthcare Supply Chain BPO Market
Business Process Outsourcing (BPO)
Recruitment Process Outsourcing (RPO) Services Market
Business Process Outsourcing (BPO)
Global Application Outsourcing Market
Business Process Outsourcing (BPO)
Global Supply Chain Management BPO Market
Business Process Outsourcing (BPO)
Payroll Outsourcing Services Market
Business Process Outsourcing (BPO)
Global IT Outsourcing Services Market
Business Process Outsourcing (BPO)
Business Process Management (BPM) Market
Business Process Outsourcing (BPO)
Business Process Automation (BPA) Market
Business Process Outsourcing (BPO)
Cloud Based BPO Market
Business Process Outsourcing (BPO)
Back Office Outsourcing Market
Business Process Outsourcing (BPO)
Automotive Business Process Management Market
Business Process Outsourcing (BPO)
North America Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
BPO Business Analytics Market