
 Healthcare Supply Chain BPO Market | 2026-2036
Healthcare Supply Chain BPO Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Supply Chain BPO Market Intelligence
Modular service bundling is restructuring how healthcare organizations purchase supply chain outsourcing, unbundling traditional end-to-end contracts into discrete procurement, inventory, and distribution modules. IQVIA leverages its clinical data heritage to anchor analytics-driven supply chain engagements for pharmaceutical manufacturers. Accenture Healthcare competes through technology leadership in cloud-based procurement platforms. Genpact Healthcare specializes in process automation for hospital inventory workflows.
Healthcare supply chain business process outsourcing encompasses the delegation of operational functions including procurement, inventory management, order fulfillment, and distribution logistics to third-party specialists, typically governed by service-level agreements specifying turnaround times, accuracy rates, and compliance benchmarks. Cloud-based technology deployments are expanding fastest among segment categories as hospital IT departments prioritize scalable infrastructure over capital-intensive on-premises systems. Managed services within the solution dimension dominate current revenue pools, while analytics offerings capture disproportionate margin expansion as clients demand predictive demand forecasting.
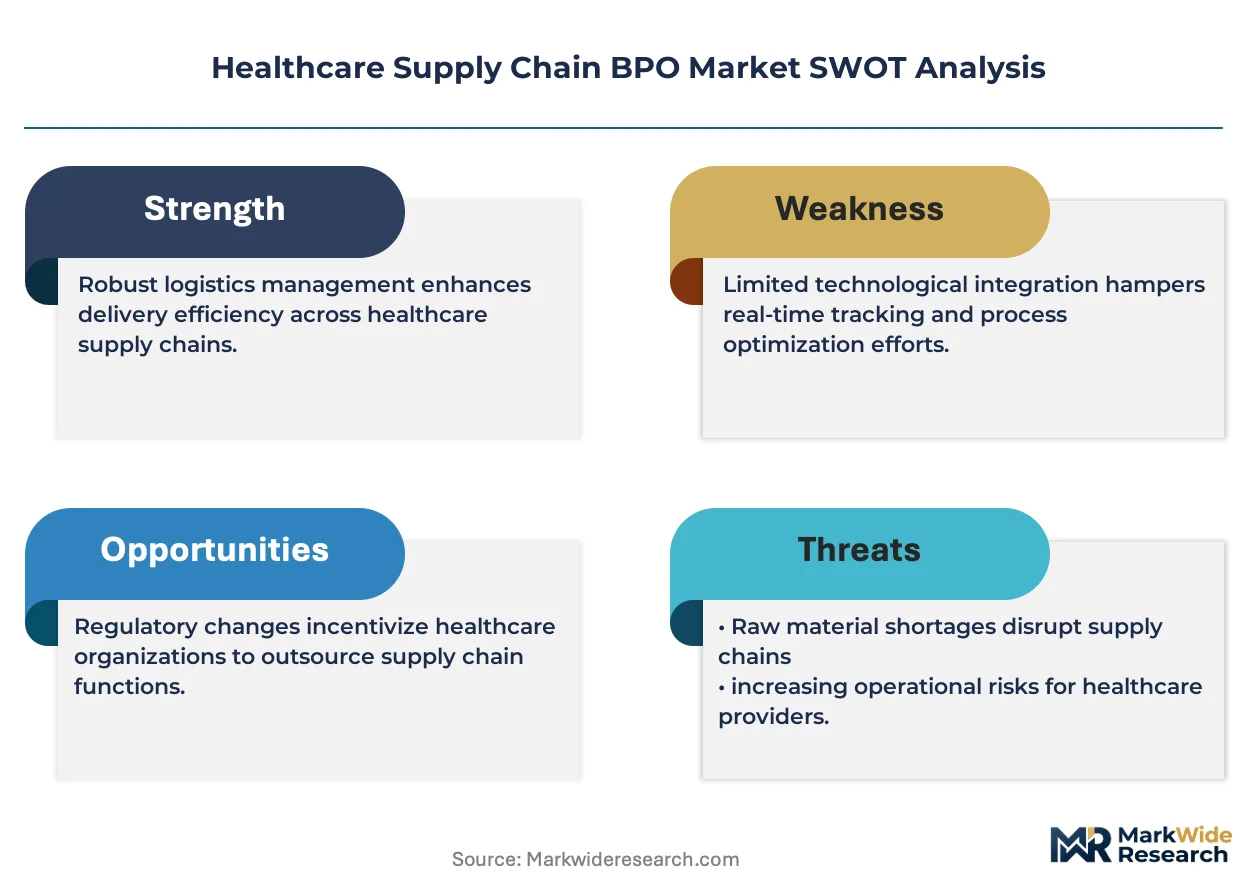
FDA track-and-trace mandates and HIPAA data security requirements shape vendor qualification criteria and contract structures for healthcare supply chain BPO engagements in the United States. The Drug Supply Chain Security Act compels pharmaceutical supply chain participants to maintain serialized product histories, creating compliance-driven demand for specialized outsourcing partners. Stakeholders must evaluate whether their provider networks possess validated infrastructure to accommodate imminent interoperability requirements between hospital ERP systems and national drug verification databases.
Market Dynamics
Serialized pharmaceutical tracking mandates are compressing implementation timelines for hospital systems, forcing rapid infrastructure upgrades and specialized outsourcing partnerships to maintain compliance with verification requirements.
Growth Catalysts
- FDA Drug Supply Chain Security Act:Serialized product history requirements compel pharmaceutical distributors to outsource track-and-trace infrastructure, creating compliance-driven demand for validated BPO partners.
- Cloud-based procurement platforms:Hospital IT departments prioritize scalable infrastructure over capital-intensive on-premises systems, accelerating technology refresh cycles.
- Integrated delivery networks:Consolidated hospital systems in the United States face mounting pressure to reduce operational expenditures, expanding addressable market for specialized supply chain outsourcing.
Market Restraints
- HIPAA data security requirements:Stringent patient data protection standards constrain vendor qualification criteria and contract structures, limiting eligible BPO provider pools.
- Interoperability infrastructure gaps:Hospital ERP systems require costly upgrades to interface with national drug verification databases, delaying implementation timelines.
- Legacy system integration:Proprietary inventory management platforms in established hospital networks resist seamless cloud migration, fragmenting technology adoption.
Strategic Opportunities
- Analytics-driven engagements:Predictive demand forecasting capabilities capture disproportionate margin expansion as pharmaceutical manufacturers seek clinical data heritage integration.
- Process automation specialization:Hospital inventory workflows present white space for robotic process automation deployment in medication dispensing and replenishment.
- Modular service unbundling:Discrete procurement, inventory, and distribution modules replace traditional end-to-end contracts, enabling flexible engagement models.
Industry Challenges
- Serialized infrastructure talent scarcity:Qualified personnel for track-and-trace system validation remain concentrated among specialized consultancies, constraining provider scaling.
- Compliance timeline compression:FDA enforcement deadlines for unit-level serialization outpace hospital system procurement cycles, creating implementation bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Supply Chain BPO Market |
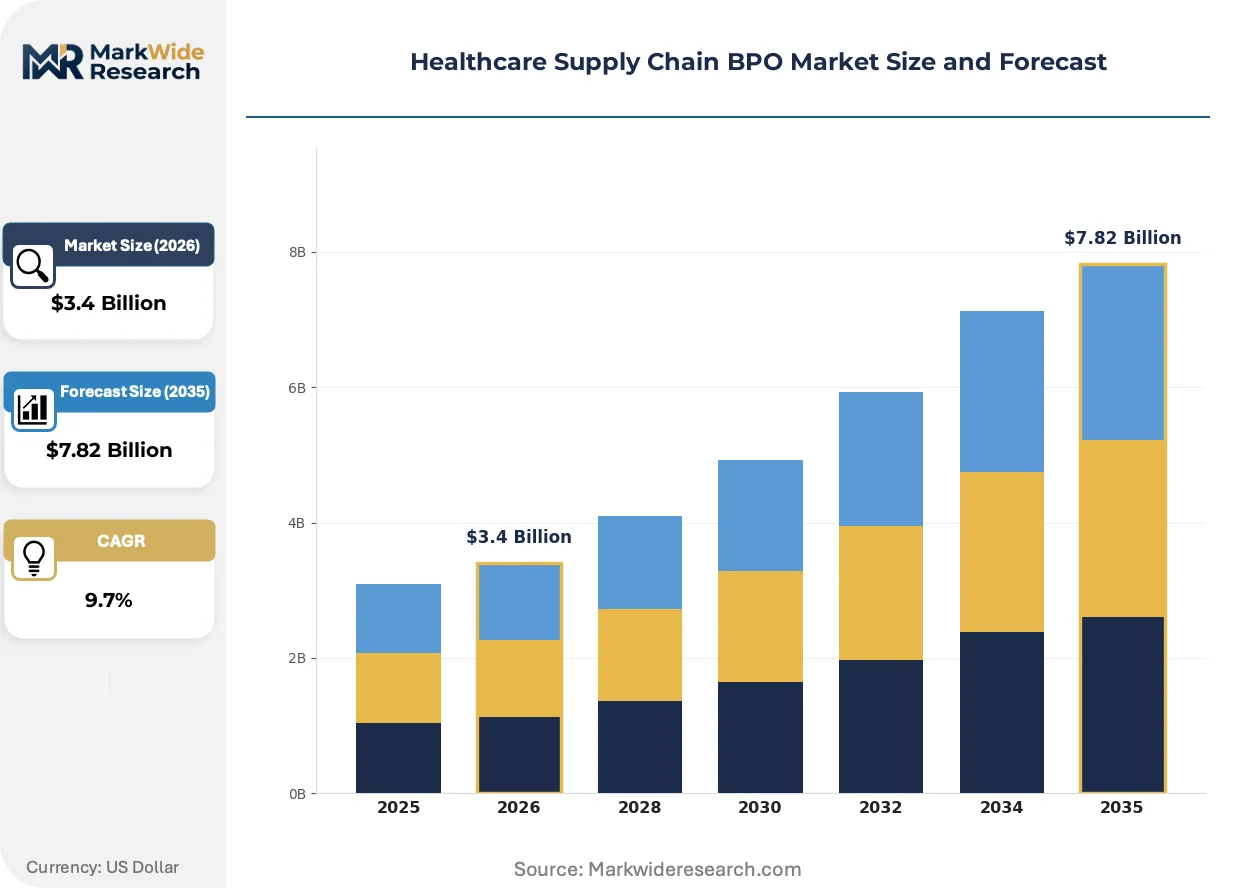
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $7.82 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inventory Management, Order Processing, Procurement, Distribution End User: Hospitals, Pharmacies, Clinics, Laboratories Technology: Cloud-Based, On-Premises, Mobile Applications, IoT Solutions Solution: Managed Services, Consulting Services, Software Solutions, Analytics |
| Companies Covered | IQVIA, Optum, Accenture Healthcare, Insignia Resources, Conifer Health Solutions, Genpact Healthcare, R1 RCM, Hugo, Cognizant Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Supply Chain BPO Market Strategic Shifts & Innovations
Technology convergence between clinical data platforms and supply chain operations is restructuring competitive positioning, while regulatory mandates force serialized infrastructure investments ahead of traditional upgrade cycles.
Blockchain-enabled provenance tracking is converging with pharmaceutical distribution networks to create immutable audit trails for drug authenticity verification. Specialty pharmaceutical manufacturers are piloting these systems at scale, with several large integrated delivery networks mandating supplier participation by 2027. This technology convergence is compressing the window for competitive differentiation among third-party logistics providers.
The FDA's enhanced track-and-trace requirements for pharmaceutical distribution are accelerating serialized supply chain infrastructure investments across the United States. Drug manufacturers must maintain interoperable product histories from production through dispensation, forcing wholesale distributors to upgrade warehouse management systems. Hospital pharmacies face the steepest compliance burden as they integrate with national verification databases.
Service-level agreement structures are evolving from cost-per-transaction models toward outcome-based frameworks tied to inventory availability and compliance accuracy. Large health systems are unbundling procurement from logistics, selecting specialized providers for each function rather than single-source arrangements. This pattern is most visible in the United States, where integrated delivery networks possess sufficient scale to justify multi-vendor management overhead.
Healthcare Supply Chain BPO Market Segmentation
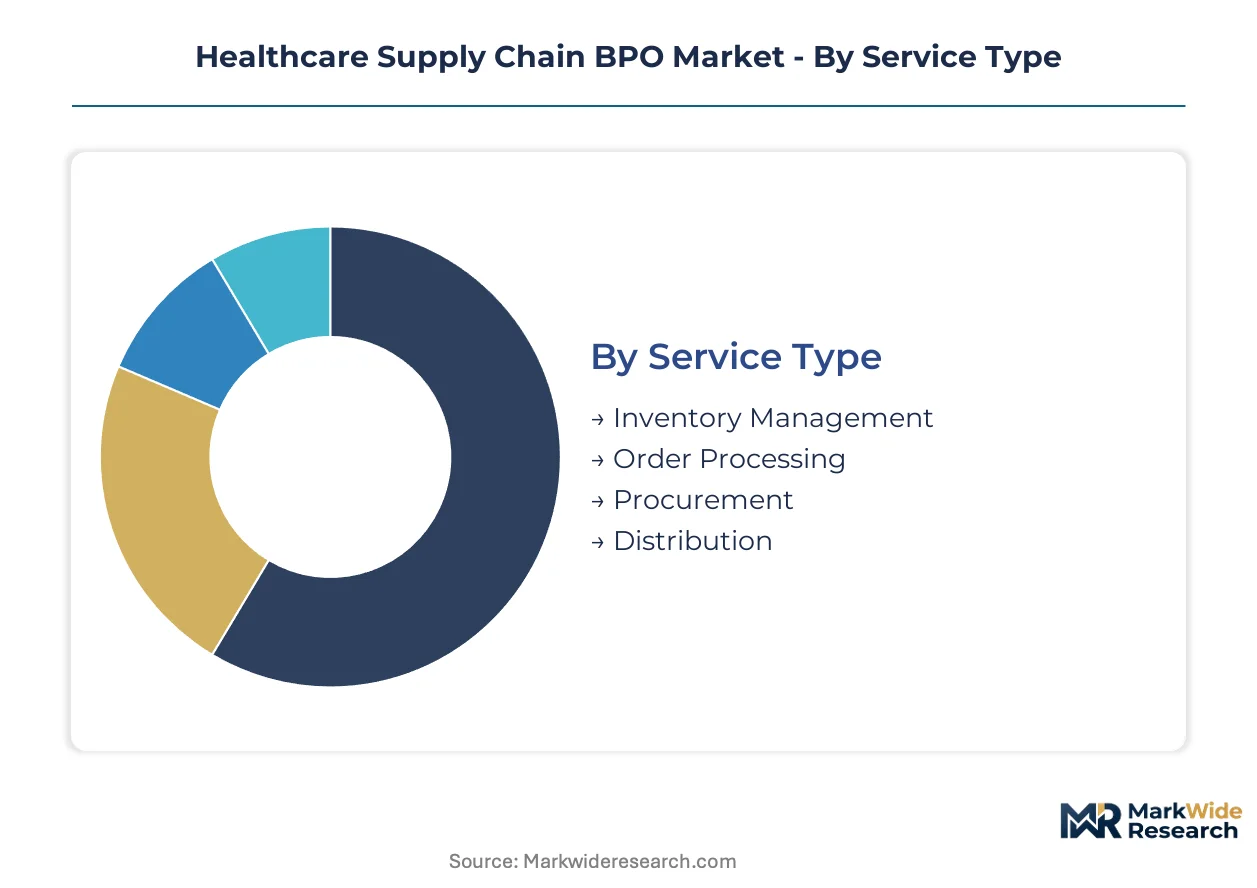
Healthcare supply chain BPO segmentation reveals distinct investment profiles and technology dependencies that shape vendor selection and contract structures. Each dimension carries specific compliance burdens and integration requirements that determine outsourcing economics.
Service Type:
Capital intensity varies sharply across operational functions, with infrastructure-heavy segments demanding serialized track-and-trace systems while knowledge-based services require analytics platforms.
- Inventory Management:Warehouse automation systems and RFID-enabled medication tracking dominate capital deployment. Hospital systems in the United States concentrate demand here as they integrate with FDA-mandated national verification databases.
- Procurement:Cloud-based sourcing platforms and supplier relationship management tools anchor technology stacks. Integrated delivery networks prioritize this segment to consolidate purchasing power across consolidated health systems.
- Order Processing:Electronic data interchange infrastructure and automated order validation workflows reduce manual touchpoints.
- Distribution:Cold chain logistics networks and last-mile delivery optimization require specialized fleet and facility investments.
Most installed capacity flows through Inventory Management. Expansion is steepest in Procurement.
End User:
Customer scale and regulatory exposure create diverging service requirements, with large institutional buyers commanding customized solutions and smaller providers accepting standardized packages.
- Hospitals:Enterprise resource planning integration and multi-facility inventory visibility systems define technical specifications. Academic medical centers and integrated delivery networks drive demand for predictive analytics and automated replenishment.
- Pharmacies:Dispensing workflow automation and medication synchronization platforms shape outsourcing priorities. Hospital outpatient pharmacies and specialty pharmacy operators invest most aggressively in serialized inventory tracking.
- Clinics:Lightweight cloud-based procurement tools and simplified inventory dashboards match limited IT resources.
- Laboratories:Reagent supply continuity and specimen tracking integration with laboratory information systems determine vendor selection.
Contract value concentrates in Hospitals. New account formation runs fastest in Pharmacies.
Technology:
Deployment architecture decisions lock in multi-year cost structures and scalability ceilings, with cloud migrations accelerating among capital-constrained buyers.
- Cloud-Based:Subscription pricing models and API-first architectures enable rapid scaling without data center investments. Hospital IT departments prioritize this model to redirect capital toward clinical technology.
- IoT Solutions:Sensor networks for temperature monitoring and automated inventory counting require edge computing infrastructure and device management platforms.
- On-Premises:Legacy system retention and data sovereignty requirements sustain demand among security-sensitive organizations.
- Mobile Applications:Point-of-care inventory lookup and bedside medication verification drive clinical workflow integration.
Technology spending tilts toward Cloud-Based. IoT Solutions is climbing the fastest.
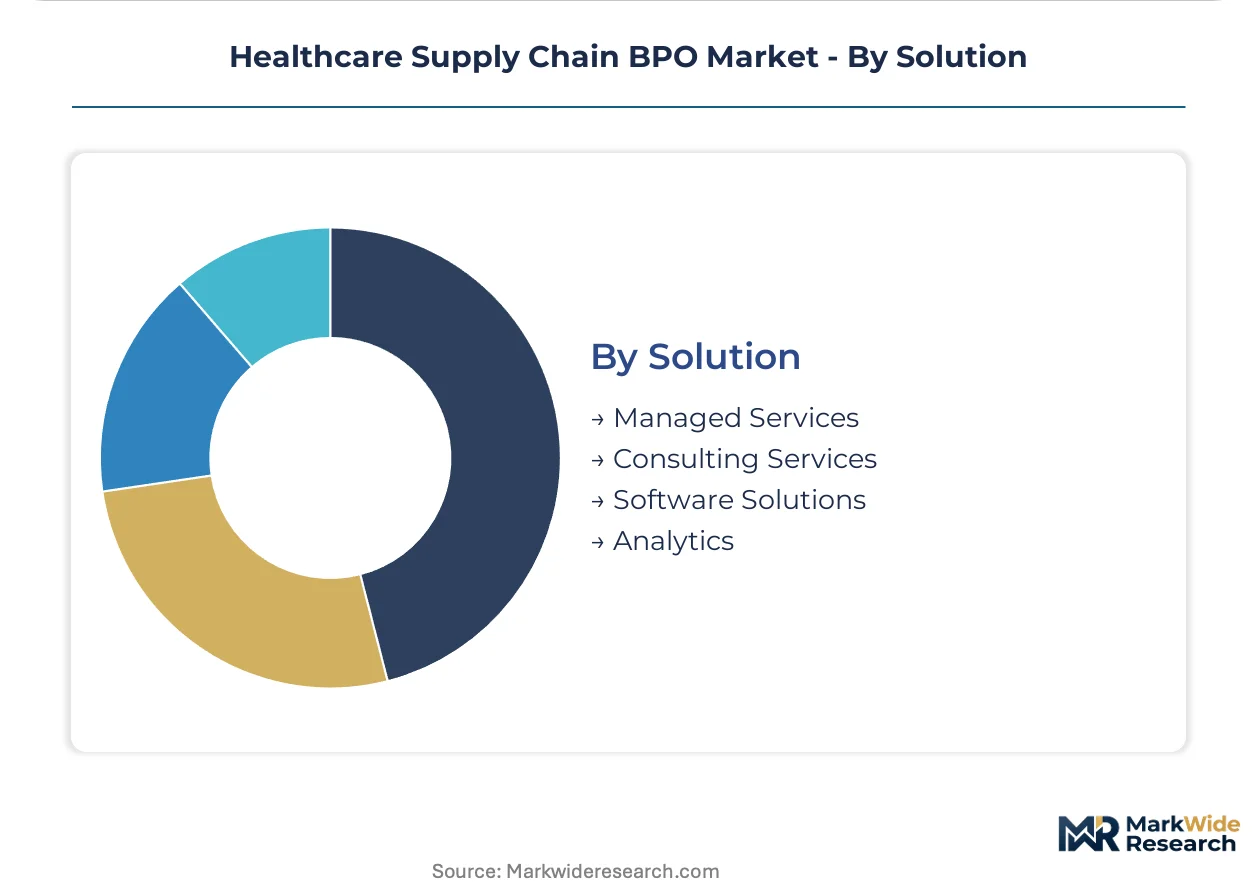
Solution:
Margin structure and contract duration differ materially across solution types, with outcome-based pricing emerging in high-value analytics engagements.
- Managed Services:Multi-year operational contracts with guaranteed service levels and penalty structures for non-compliance. Pharmaceutical distributors rely on these arrangements to satisfy FDA track-and-trace mandates without building internal capabilities.
- Analytics:Predictive demand forecasting and clinical-supply integration command premium pricing. Manufacturers leverage these tools to align production schedules with real-world utilization patterns.
- Consulting Services:Transformation advisory and vendor selection support address one-time optimization needs.
- Software Solutions:Licensed platforms for procurement and inventory management with implementation and maintenance fees.
Revenue pools concentrate in Managed Services. Margin expansion is steepest in Analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The healthcare supply chain BPO industry traces its modern scale to the United States, where integrated delivery networks pioneered procurement consolidation in the 1990s and pharmaceutical distributors first confronted serialized tracking mandates.
United States
Hospital systems and pharmaceutical distributors drive outsourcing demand as FDA Drug Supply Chain Security Act deadlines compress implementation timelines. HIPAA data security requirements constrain vendor pools to qualified specialists with validated infrastructure. The Philadelphia-Camden corridor hosts dense clusters of pharmaceutical logistics providers upgrading warehouse management systems for interoperability with national verification databases.
Germany
Pharmaceutical manufacturers and hospital networks seek supply chain optimization amid EMA serialization requirements and EU MDR compliance burdens. The country's national pharmaceutical regulator enforces stringent track-and-trace standards that mirror FDA timelines. The Rhine-Ruhr metropolitan region concentrates BPO provider development, with Düsseldorf-based firms specializing in cold chain logistics for biologics distribution.
United Kingdom
NHS procurement consolidation and post-Brexit regulatory divergence create specialized outsourcing opportunities for inventory management and supplier qualification. The Medicines and Healthcare products Regulatory Agency maintains distinct serialization protocols requiring dedicated compliance infrastructure. London anchors demand for analytics-driven engagements, while Manchester hosts emerging cloud-based procurement platform development.
India
Domestic pharmaceutical manufacturers and hospital chains expand outsourcing to meet CDSCO track-and-trace mandates and export market compliance requirements. The Production Linked Incentive scheme for pharmaceuticals accelerates capacity expansion and associated supply chain investments. Hyderabad and Mumbai form the core industrial cluster, with Hyderabad's Genome Valley driving specialized cold chain BPO services for biopharma exports.
Japan
Aging demographics and hospital consolidation pressure operational expenditure reduction while PMDA serialization rules align with international standards. METI initiatives promote supply chain digitization through standardized data exchange protocols. The Osaka-Kobe corridor concentrates pharmaceutical distribution infrastructure, with Kobe's port facilities supporting specialized import logistics BPO services for temperature-sensitive therapies.
Healthcare Supply Chain BPO Market Key Industry Players
Premium-margin players sit above commodity-margin players across the analytics and compliance-specialization dimension, with outcome-based pricing separating high-value predictive forecasting from transactional procurement services. The market structures around three tiers: global consultancies with healthcare verticals, specialized healthcare BPO pure-plays, and technology-enabled process automation specialists. Consolidation pressures favor acquisition of niche compliance capabilities and cloud-native platform assets.
Within the specialized healthcare BPO tier, IQVIA and Genpact Healthcare exemplify divergent archetypes—one leveraging clinical data heritage for pharmaceutical manufacturer engagements, the other deploying process automation for hospital inventory workflows. Accenture Healthcare occupies a position at the technology-platform intersection, anchoring cloud-based procurement infrastructure for integrated delivery networks. These three represent the dominant competitive positioning vectors: data-anchored analytics, operational automation, and enterprise technology integration.
| Leading Market Players |
|---|
| IQVIA |
| Optum |
| Accenture Healthcare |
| Insignia Resources |
| Conifer Health Solutions |
| Genpact Healthcare |
| R1 RCM |
| Hugo |
| Cognizant Healthcare |
| Others |
Cost & Logistics Intelligence
Cloud-based procurement platform migration simultaneously compresses cost economics for hospital IT departments and concentrates supply capability among vendors with validated FDA track-and-trace infrastructure. This technology transition rewards scaled providers while squeezing margins for legacy on-premises specialists unable to amortize compliance investments across subscriber bases.
Pricing Analysis
Subscription-based SaaS tiers with outcome-linked escalation clauses dominate contract structures for healthcare supply chain BPO engagements. Price differentiation rests on serialization certification grade and analytics depth rather than base transaction volume. Cost compression in standardized procurement modules is intensifying because cloud-native entrants are undercutting legacy providers. Community hospital systems exhibit highest price sensitivity, while integrated delivery networks prioritize compliance accuracy over unit cost.
Supply Chain Analysis
Direct-to-hospital channels handle hyperscale integrated delivery network demand, while distributor-intermediated routes serve fragmented clinic and pharmacy segments. Capability concentrates in the United States, India, and Germany, with Hyderabad and Philadelphia-Camden corridors anchoring pharmaceutical logistics specialization. The vendor ecosystem draws from cloud infrastructure providers, RFID hardware manufacturers, and serialized database operators. Single-source vulnerability in qualified track-and-trace personnel constrains rapid scaling. Distribution runs through multi-tier pharmaceutical wholesalers with last-mile hospital pharmacy integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare supply chain BPO has entered a late-cycle quality phase where FDA serialization mandates and outcome-based contracting favor providers with validated infrastructure over price competitors. Demand is tilting toward premium analytics-anchored engagements that integrate clinical data heritage with operational execution.
For Market Incumbents: Extend cloud platform capabilities through API-first architectures that embed into hospital ERP systems, defending against specialized automation pure-plays. Deepen vertical integration into serialized inventory hardware to capture margin pools that currently leak to third-party RFID and sensor vendors. Accenture Healthcare and IQVIA demonstrate this platform-control trajectory. For New Entrants and Emerging Players: Specialty pharmacy operators represent the most penetrable buyer archetype, as their explosive growth outpaces established BPO relationship coverage. Community hospital systems in secondary US markets offer white-space expansion with lighter compliance burdens than academic medical centers. A robotics-process-automation-first go-to-market angle bypasses entrenched cloud procurement incumbents. For Investors and Strategic Acquirers: Roll-up economics work for regional healthcare BPO specialists because FDA validation timelines create moats against greenfield competition. Five-to-ten-year viability hinges on cloud-native platform assets rather than legacy managed services contracts. The signal to watch is hospital system unbundling velocity—accelerating modular procurement adoption indicates consolidation opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Platform Integration | API-first architectures enable seamless hospital ERP embedding, reducing implementation friction for IDNs. |
| Serialized Infrastructure Investment | FDA Drug Supply Chain Security Act compliance creates vendor qualification barriers that protect incumbent margins. |
| Analytics Capability Acquisition | Clinical data heritage integration commands premium pricing from pharmaceutical manufacturers seeking demand forecasting. |
| Process Automation Deployment | Robotic process automation in medication dispensing addresses labor scarcity while improving inventory accuracy benchmarks. |
| Regional Compliance Specialization | EMA and PMDA serialization expertise opens export market access for domestic pharmaceutical manufacturers. |
Research Approach
Multiple input streams — executive interviews with supply chain officers at integrated delivery networks, procurement managers at pharmaceutical distributors, and regulatory affairs leads at BPO providers — were reconciled against secondary validation. FDA guidance documents, CMS hospital cost reports, and pharmaceutical track-and-trace implementation databases anchored quantitative sizing. Bottom-up contract value analysis and top-down market aggregation were cross-checked for consistency.
Data-stream reconciliation across service type, technology deployment, and end-user segmentation dimensions shaped the analytical framework. CAGRs were derived from fitted growth curves applied to disclosed contract values and announced platform deployments. Cloud adoption velocity, FDA enforcement timeline compression, and hospital consolidation patterns served as industry-specific forecast inputs throughout the modeling period.
Inputs from hospital procurement databases and BPO provider disclosures were available through the study window; gaps in private contract pricing introduce uncertainty bands around segment-level estimates. Forecasts reflect assumptions regarding regulatory deadline adherence and technology refresh cycle timing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Payroll Outsourcing Services Market
Business Process Outsourcing (BPO)
Procurement Outsourcing Services Market
Business Process Outsourcing (BPO)
Document Outsourcing Services Market
Business Process Outsourcing (BPO)
BFSI BPO Services Market
Business Process Outsourcing (BPO)
Service Bureau Market
Business Process Outsourcing (BPO)
IT Outsourcing Market
Business Process Outsourcing (BPO)
Global Supply Chain Management BPO Market
Business Process Outsourcing (BPO)
Business Processing Outsourcing Market
Business Process Outsourcing (BPO)
Business Process Re-Engineering Market
Business Process Outsourcing (BPO)
Direct to Customer Outsourced Fulfillment Market
Business Process Outsourcing (BPO)
US Managed Print Services Market
Business Process Outsourcing (BPO)
Global Telecom Outsourcing Market
Business Process Outsourcing (BPO)
Front Office BPO Services Market
Business Process Outsourcing (BPO)
Customer Relationship Management (CRM) Outsourcing Market
Business Process Outsourcing (BPO)
Employment Screening Services Market
Business Process Outsourcing (BPO)
Cloud Based BPO Market