
 Business Process Automation (BPA) Market | 2026-2036
Business Process Automation (BPA) Market Size, Share, and Industry Trends Forecast 2026-2036
Business Process Automation (BPA) Market Outlook
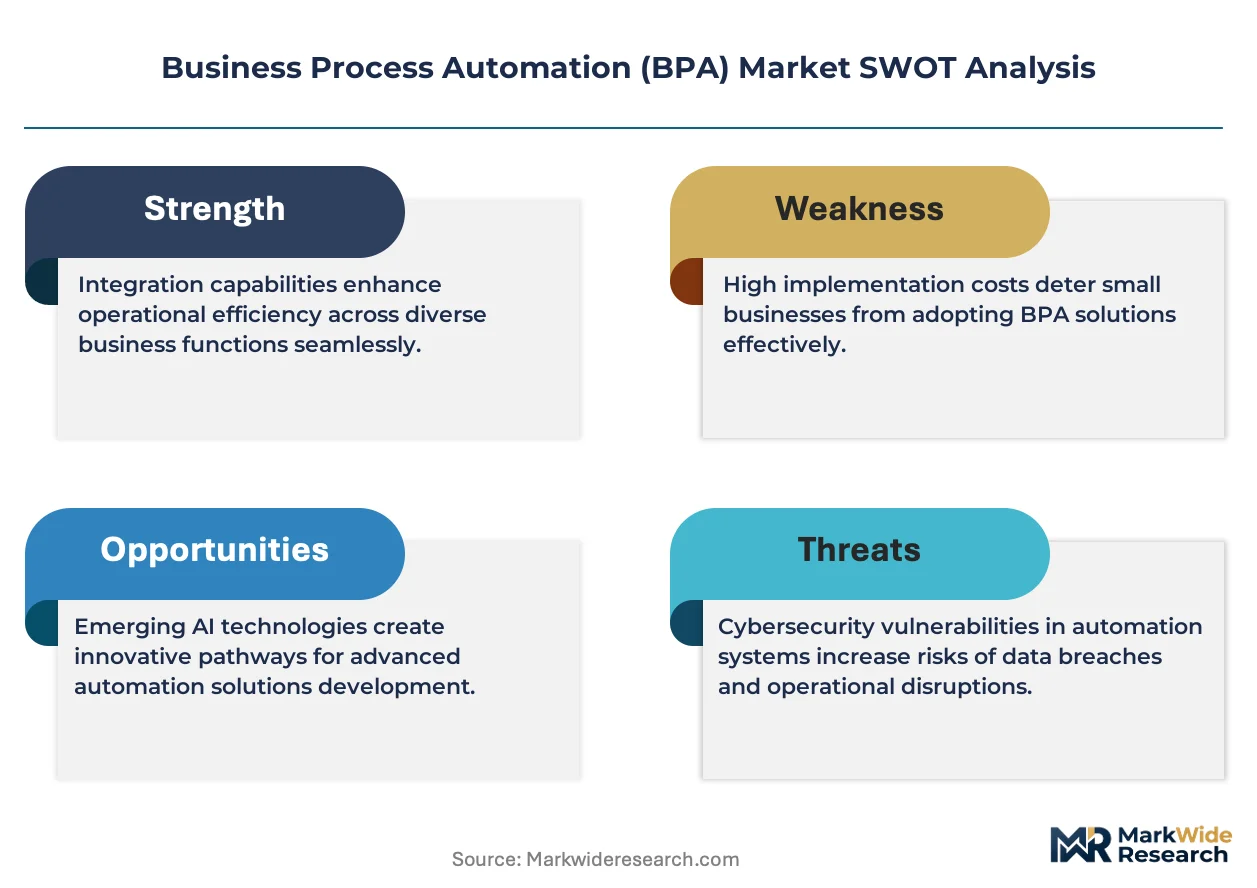
The BPA software landscape is recalibrating around a sharp split between enterprise-grade platforms with native AI orchestration and lightweight task-automation tools sold on per-seat subscriptions. UiPath leverages its robotic process automation heritage to anchor premium pricing for complex multi-system workflows. SAP Signavio sustains dominance in process mining and governance layers inside Fortune 500 accounts. Automation Anywhere competes aggressively on cloud-native deployment speed for mid-market buyers.
Business Process Automation encompasses software platforms that design, execute, monitor, and optimize repetitive workflows through rule engines, API integrations, and increasingly machine-learning inference layers operating at sub-second latency. Its primary commercial purpose is to reduce manual handoffs, enforce compliance checkpoints, and extract structured data from unstructured inputs across enterprise operations. Cloud deployment now leads expansion as organizations retire on-premises orchestration servers, while robotic process automation remains the most mature technology segment with established margin pools. Workflow automation incorporating artificial intelligence represents the fastest-growing category, though implementation services still capture substantial value during enterprise rollout phases.
The EU AI Act imposes risk-classification requirements on automated decision systems, compelling BPA vendors to embed audit trails and human-in-the-loop checkpoints. HIPAA in the United States and Japan's METI guidelines on AI governance similarly shape product architecture and market access conditions for healthcare and financial automation. Stakeholders must monitor how rapidly evolving algorithmic accountability standards will redefine competitive moats between compliant full-stack providers and point-solution vendors lacking certification depth.
Market Dynamics
The BPA market is recalibrating around a decisive technology shift: artificial intelligence inference layers are displacing rule-based orchestration engines, forcing vendors to rebuild core architectures around sub-second machine-learning pipelines rather than legacy workflow scripts.
Growth Catalysts
- EU AI Act compliance mandates:Risk-classification requirements for automated decision systems are compelling enterprises to replace ungoverned automation with auditable platforms embedding human-in-the-loop checkpoints.
- Healthcare claims processing automation:HIPAA-covered entities are accelerating patient intake digitization to reduce manual handoffs and enforce compliance checkpoints across revenue cycle operations.
- Cloud-native deployment models:Organizations retiring on-premises orchestration servers are migrating to API-first platforms, expanding addressable market for subscription-based workflow tools.
Market Restraints
- Implementation service dependency:Complex multi-system workflows require substantial professional services, elongating payback periods and compressing vendor margins during enterprise rollout phases.
- Algorithmic accountability uncertainty:Rapidly evolving audit trail requirements across Japan's METI guidelines and US state-level AI governance create certification friction and product architecture risk.
- Legacy system entrenchment:Fortune 500 accounts with deep SAP and Oracle ERP investments face high switching costs that delay cloud-native automation adoption.
Strategic Opportunities
- Process mining convergence:Vendors integrating governance layers with execution engines can capture premium positioning inside large enterprises seeking unified visibility.
- Mid-market cloud velocity:Buyers with fewer legacy constraints present faster deployment cycles and higher willingness to adopt pure SaaS orchestration tools.
- Healthcare automation white space:HIPAA-compliant platforms addressing unstructured clinical data extraction remain underpenetrated relative to administrative workflow automation.
Industry Challenges
- Machine-learning operations talent scarcity:Enterprises struggle to staff teams capable of maintaining inference pipelines and retraining models at sub-second latency requirements.
- Multi-vendor integration complexity:Heterogeneous technology stacks spanning RPA, API gateways, and AI services demand specialized architecture expertise most buyers lack internally.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Business Process Automation (BPA) Market |
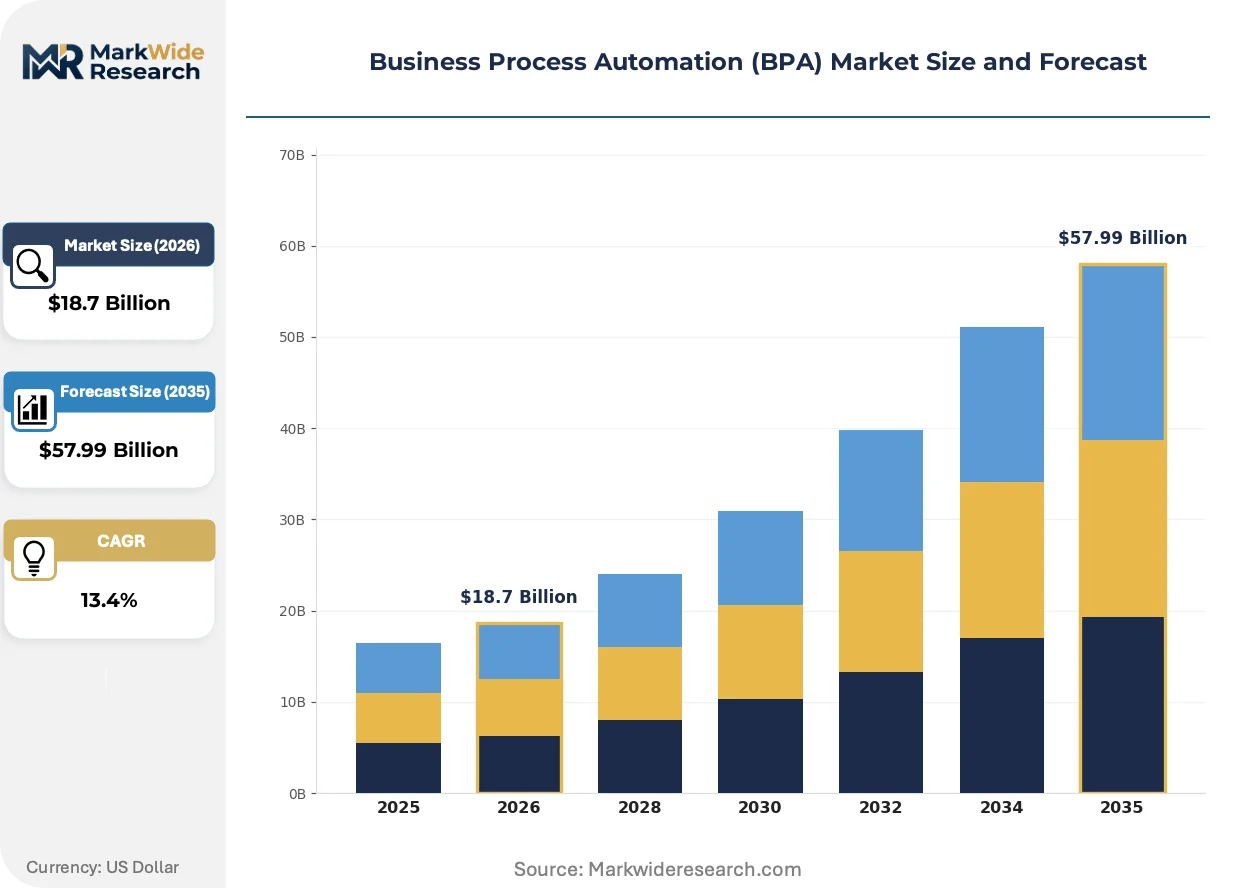
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $57.99 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud, Hybrid, Managed Services End User: Manufacturing, BFSI, Healthcare, Retail Technology: Robotic Process Automation, Machine Learning, Artificial Intelligence, Workflow Automation Service Type: Consulting, Implementation, Integration, Maintenance |
| Companies Covered | Microsoft Power Automate, SAP Signavio, UiPath, WEBCON, Newgen Software Technologies, Automation Anywhere, Appian, BP Logix, Camunda, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Business Process Automation (BPA) Market Strategic Shifts
Workflow automation platforms are converging around three decisive vectors: embedded intelligence replacing scripted logic, compliance architecture becoming a competitive differentiator, and procurement models shifting toward consumption-based pricing.
Intelligent document processing with native large language model inference is consolidating fragmented capture solutions into unified extraction platforms. Healthcare payers and financial services firms are deploying these systems at enterprise scale, collapsing previously separate OCR, NLP, and validation workflows into single-vendor architectures. This consolidation is compressing margin pools for point-solution document vendors while elevating full-stack providers.
The EU AI Act's risk-tier classification system is forcing BPA vendors to embed technical documentation and human oversight mechanisms directly into product roadmaps. Industrial consequence includes mandatory conformity assessments for high-risk automation use cases, particularly credit decisions and patient diagnostics. Healthcare and banking segments in Germany and France are responding by prioritizing certified platforms over faster-to-deploy uncertified alternatives.
Buyers are unbundling implementation services from software subscriptions, demanding fixed-scope professional engagements separate from recurring platform fees. Channel partners and systems integrators are capturing this disintermediated value, particularly in the United States where mid-market buyers prefer outcome-defined project contracts over bundled SaaS pricing. This pattern is most visible among regional healthcare networks seeking rapid deployment without long-term vendor dependency.
Business Process Automation (BPA) Market Segmentation
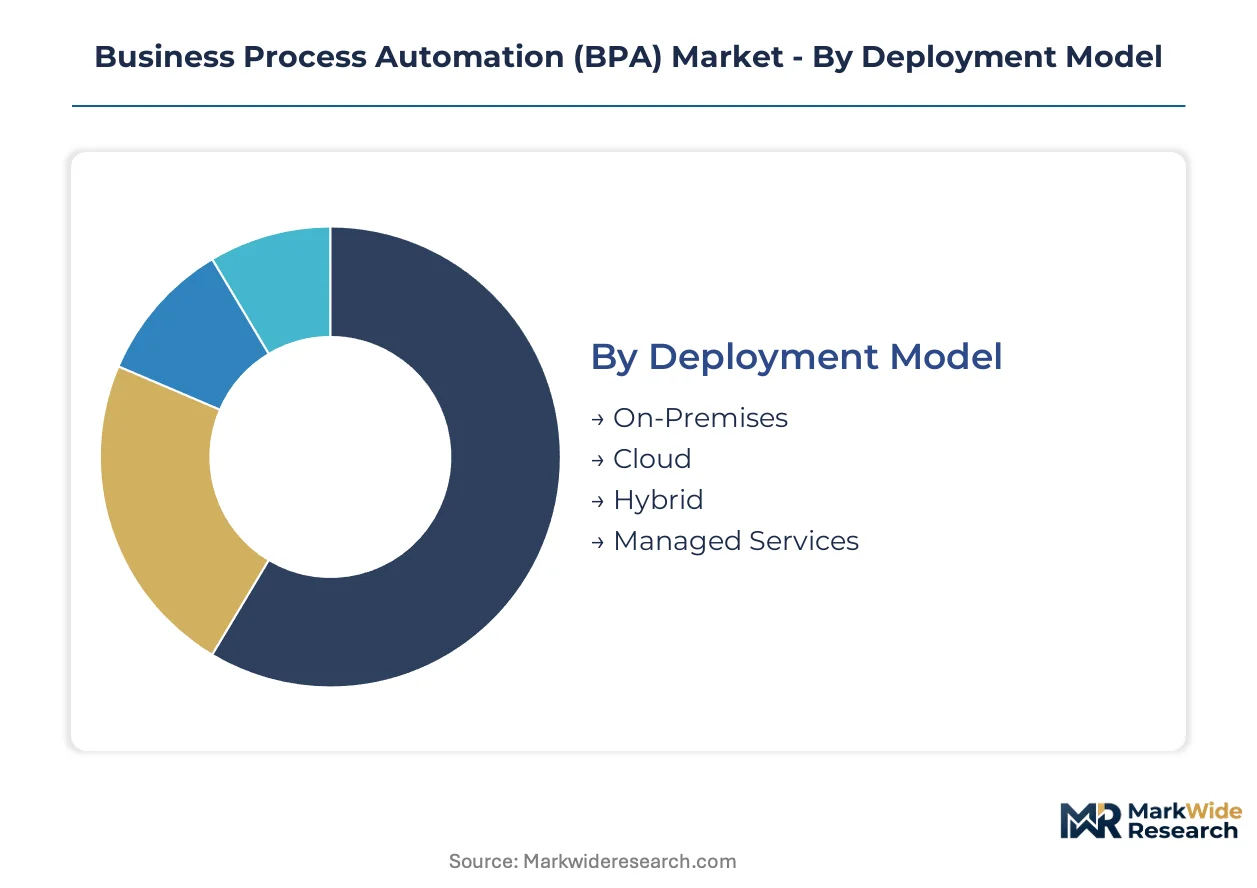
BPA procurement decisions hinge on compliance architecture and infrastructure maturity. Buyers segment investments across deployment models, end-use verticals, technology stacks, and service tiers to match regulatory exposure with operational complexity.
Deployment Model:
HIPAA-covered entities and EU AI Act regulated firms face divergent certification burdens depending on data residency and inference pipeline location.
- Cloud:Multi-tenant architectures with SOC 2 Type II and ISO 27001 certifications dominate new procurement in Germany and the United States. Healthcare payers favor cloud-native platforms for patient intake automation to satisfy HIPAA audit trail requirements without maintaining physical infrastructure.
- Hybrid:Split architectures keep sensitive inference workloads on-premises while pushing orchestration logic to cloud instances. Financial institutions in Japan deploy hybrid models to satisfy METI AI governance guidelines while retaining sub-second latency for trading workflows.
- On-Premises:Air-gapped installations persist in defense and classified government environments requiring CMMC compliance.
- Managed Services:Outsourced operations with vendor-assumed liability appeal to mid-market buyers lacking internal MLOps talent.
Leading the category by volume: Cloud. Growing fastest: Hybrid.
End User:
Vertical-specific compliance mandates reshape automation architecture from intake through archival.
- Healthcare:HIPAA-covered entities automate revenue cycle operations with embedded human-in-the-loop checkpoints for prior authorization and claims adjudication. German hospital networks prioritize EU AI Act conformity assessments for diagnostic automation.
- BFSI:Credit decisioning workflows trigger high-risk classification under EU AI Act, forcing auditable model documentation and bias testing. US banks integrate SEC audit trail requirements into trade surveillance automation.
- Manufacturing:OSHA incident reporting and EPA emissions monitoring drive shop-floor workflow digitization.
- Retail:Inventory orchestration and returns processing automation concentrate in high-volume e-commerce operations.
Dominant by procurement value: Healthcare. Expanding most quickly: BFSI.
Technology:
Architecture choices determine whether platforms satisfy emerging algorithmic accountability standards.
- Artificial Intelligence:Large language model inference layers for unstructured document processing require continuous retraining pipelines and explainability documentation under EU AI Act high-risk provisions. Healthcare payers deploy these systems for clinical note extraction.
- Robotic Process Automation:Rule-based desktop automation remains the most mature segment with established margin pools, though EU AI Act risk tiers are forcing migration toward governed alternatives.
- Machine Learning:Predictive models for demand forecasting and fraud detection demand MLOps infrastructure most mid-market buyers lack internally.
- Workflow Automation:API-first orchestration engines with native compliance checkpoints are displacing legacy BPM suites in cloud migration cycles.
Highest revenue concentration: Robotic Process Automation. Steepest expansion trajectory: Artificial Intelligence.
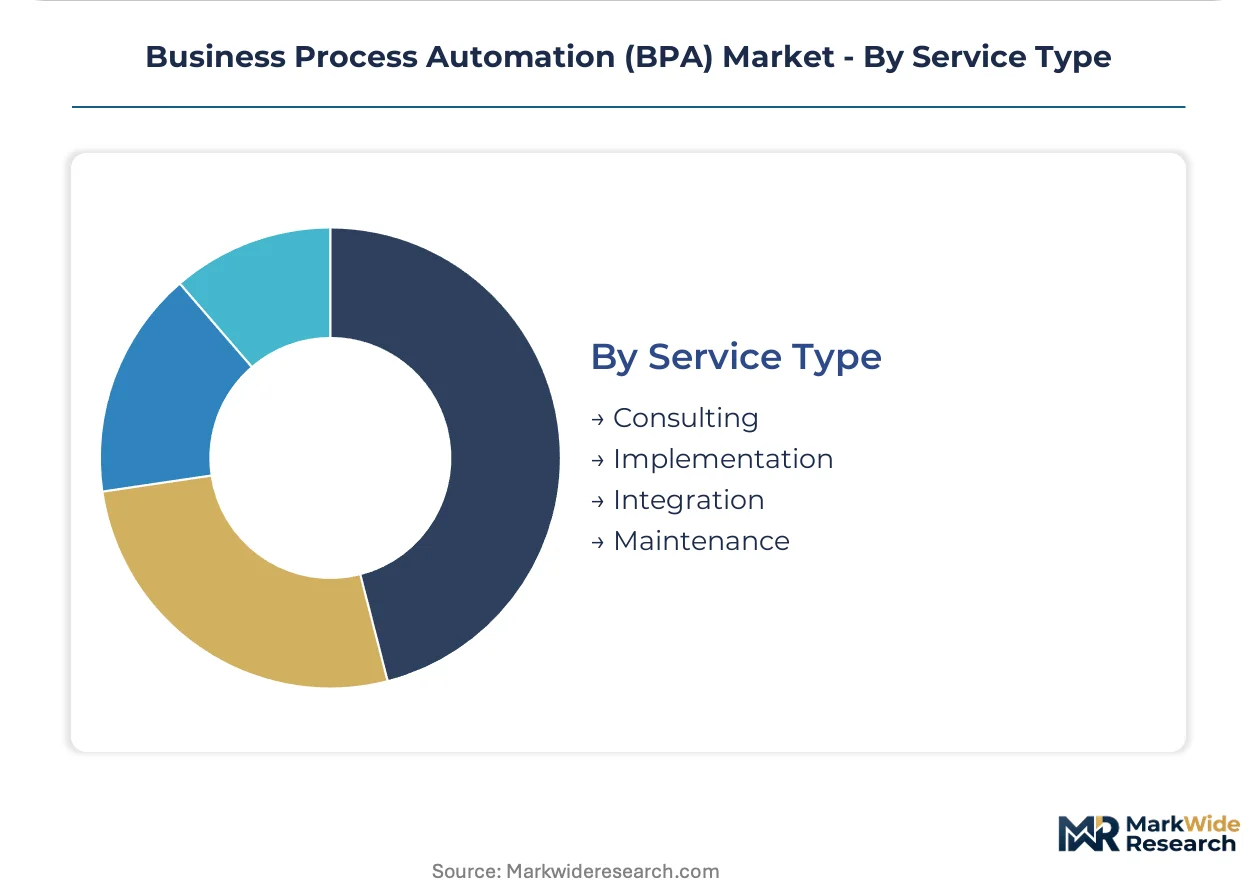
Service Type:
Professional services capture substantial value during enterprise rollout phases, with procurement patterns shifting toward unbundled engagements.
- Implementation:Complex multi-system workflow deployment requires specialized architecture expertise for SAP and Oracle ERP integration. US mid-market buyers increasingly demand fixed-scope project contracts separate from recurring platform fees.
- Consulting:Process mining and governance layer design precede execution engine procurement in Fortune 500 accounts.
- Integration:API gateway configuration and legacy system bridging consume significant professional services hours.
- Maintenance:Ongoing model retraining and compliance documentation updates generate recurring revenue for certified platforms.
Largest service spend: Implementation. Gaining share fastest: Consulting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley and the San Francisco Bay Area anchor enterprise automation demand, hosting headquarters for UiPath, Automation Anywhere, and Appian alongside dense concentrations of Fortune 500 pilot deployments. Healthcare networks in the region drive HIPAA-compliant workflow procurement for revenue cycle operations.
United States
Healthcare payers and financial services firms dominate BPA procurement, with hospital networks automating patient intake and claims adjudication workflows. HIPAA audit trail requirements and SEC disclosure mandates for algorithmic trading surveillance reshape vendor certification standards. The Boston-Cambridge corridor concentrates healthcare automation R&D, while New York Metro leads financial services deployment.
Germany
Industrial manufacturing and automotive supply chains drive process mining adoption, with Mittelstand firms modernizing legacy ERP integrations. EU AI Act risk-classification requirements for automated decision systems compel conformity assessments for diagnostic and credit-scoring automation. The Stuttgart-Karlsruhe manufacturing belt hosts dense clusters of SAP-integrated workflow deployments.
Japan
Financial institutions and precision manufacturers prioritize hybrid deployment models to satisfy METI AI governance guidelines while maintaining sub-second latency for trading workflows. The Tokyo-Osaka corridor concentrates enterprise automation procurement, with regional banks automating compliance documentation and trade surveillance. Yokohama's industrial zone anchors manufacturing workflow digitization for OSHA-equivalent incident reporting.
United Kingdom
Professional services firms and insurance underwriters lead cloud-native automation adoption, with Lloyd's of London market participants automating claims processing and regulatory reporting. GDPR data residency requirements intersect with emerging UK AI governance frameworks to shape vendor selection criteria. The London-Reading technology corridor hosts concentrated deployment of API-first orchestration platforms.
India
IT services exporters and banking sector modernization drive demand for robotic process automation, with HDFC Bank and ICICI Bank scaling attended automation for customer onboarding. RBI guidelines on digital lending and data localization influence platform architecture decisions. Bangalore's technology corridor anchors delivery centers for global enterprise automation implementation services.
Business Process Automation (BPA) Market Competitive Environment
Premium-margin players sit above commodity-margin players across compliance certification depth, with full-stack providers commanding pricing power for EU AI Act-conforming deployments while point-solution vendors compete on per-seat subscription velocity. The market structure stratifies into three tiers: enterprise-grade platforms with native AI orchestration, mid-market cloud-native tools, and legacy on-premises workflow suites. Strategic archetypes include RPA heritage vendors pivoting toward governed automation, process mining specialists extending into execution layers, and API-first challengers displacing legacy BPM suites. Consolidation pressure drives acquisition activity for MLOps talent and healthcare compliance expertise, while geographic expansion targets mid-market buyers in Germany and Japan.
Within the premium-tier vector, UiPath and SAP Signavio exemplify divergent strategic positions—UiPath represents the RPA-to-AI-orchestration pivot with robotic automation heritage, while SAP Signavio anchors process mining and governance layer dominance inside Fortune 500 accounts. Automation Anywhere occupies a position on the cloud-native velocity axis, competing for mid-market buyers with faster deployment cycles. These three companies illustrate how certification depth, deployment speed, and ERP integration heritage define competitive positioning.
| Leading Market Players |
|---|
| Microsoft Power Automate |
| SAP Signavio |
| UiPath |
| WEBCON |
| Newgen Software Technologies |
| Automation Anywhere |
| Appian |
| BP Logix |
| Camunda |
| Others |
Value Chain & Pricing Dynamics
Machine-learning inference layers replacing rule-based orchestration engines simultaneously compress development costs for cloud-native vendors and concentrate supply power among hyperscaler-backed platforms with dedicated silicon access. This architectural shift redraws cost curves across deployment tiers while tightening vendor margins for legacy on-premises orchestration providers.
Pricing Analysis
Outcome-based pricing anchored to workflow throughput and compliance audit trail completeness dominates enterprise procurement, with UiPath and SAP Signavio commanding premium positioning for EU AI Act-conforming deployments. Three-tier pricing structure across premium, standard, and economy levels separates certified full-stack platforms from point-solution vendors and open-source alternatives. Cost compression in the mid-market tier intensifies as Automation Anywhere and cloud-native challengers compete on per-seat velocity. Healthcare payers exhibit lowest price sensitivity due to HIPAA liability exposure, while regional manufacturing networks in Germany drive hardest bargain on implementation scope.
Supply Chain Analysis
India's software services exports and data localization mandates under RBI guidelines reshape sourcing patterns for implementation talent and cloud infrastructure. The BPA supply chain draws from Taiwan for advanced semiconductors powering inference workloads, Ireland and Singapore for data center hosting serving EU and APAC compliance requirements, and Poland and Romania for engineering talent supporting European deployments. Single-source vulnerability concentrates in NVIDIA GPU supply for AI training pipelines. Distribution runs through hyperscaler marketplaces, systems integrator channel partners, and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The BPA market sits in a technology-transition phase where artificial intelligence inference layers are systematically displacing legacy robotic process automation scripts, rewarding vendors who rebuild core architectures around sub-second machine-learning pipelines.
For Market Incumbents: Lock in certification depth for EU AI Act high-risk use cases before conformity assessment backlogs elongate sales cycles. Fortify MLOps talent pipelines through acquisition of specialist firms in Bangalore and Warsaw to counter cloud-native challengers. Prioritize SAP and Oracle ERP integration heritage as a defensive moat against API-first entrants targeting mid-market displacement. For New Entrants and Emerging Players: EU AI Act in Germany and France opens a window for healthcare automation specialists offering pre-certified diagnostic workflow platforms. White space concentrates in HIPAA-compliant clinical data extraction for mid-market hospital networks seeking rapid deployment without long-term vendor dependency. Go-to-market velocity favors outcome-defined project contracts disaggregated from recurring platform fees. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by hyperscaler platforms seeking vertical compliance expertise and process mining capabilities. Long-term viability hinges on sustained differentiation in algorithmic accountability documentation rather than raw automation throughput. Watch for inflection when EU AI Act enforcement actions trigger replacement cycles among uncertified incumbent installations.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Certification | Mandatory conformity assessments for high-risk automation use cases in German healthcare and French banking segments. |
| Healthcare Compliance Acquisition | Specialist firms with HIPAA audit trail expertise command premium positioning in US hospital network procurement. |
| Hyperscaler Marketplace Integration | Microsoft Azure and AWS marketplace listings accelerate mid-market discovery and reduce customer acquisition costs. |
| Process Mining Platform Extension | SAP Signavio demonstrates governance-to-execution layer convergence capturing Fortune 500 unified visibility demand. |
| MLOps Talent Center Establishment | Bangalore and Warsaw delivery centers address machine-learning operations scarcity constraining enterprise rollout velocity. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across platform engineering directors, healthcare CIOs, compliance officers at HIPAA-covered entities, and systems integrator partners. SEC 10-K disclosures, EU AI Act implementation guidance, METI governance frameworks, and hyperscaler capex reports provided demand-side validation. Bottom-up deployment estimates triangulated against top-down market sizing from cloud infrastructure spend patterns.
Segment-level modeling captured deployment mode, end-use vertical, technology stack, and organization size across the projection horizon. CAGRs derived from elasticity-adjusted adoption curves reflecting regulatory enforcement timelines and cloud migration cycles. Inputs included EU AI Act risk-classification implementation schedules, HIPAA audit trail technology refresh patterns, and mid-market SaaS procurement velocity indices.
Caveats apply where EU AI Act enforcement intensity or HIPAA penalty regime shifts could materially shift the outlook for certified platform demand. Model assumptions rest on sustained cloud infrastructure cost curves and continued hyperscaler marketplace expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Direct to Customer Outsourced Fulfillment Market
Business Process Outsourcing (BPO)
Asia-Pacific Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Digitalization in Bpo Market
Business Process Outsourcing (BPO)
Call Center Outsourcing Market
Business Process Outsourcing (BPO)
Indonesia Business Process Outsourcing Services Market
Business Process Outsourcing (BPO)
US Managed Print Services Market
Business Process Outsourcing (BPO)
Public Cloud Business Process Services Market
Business Process Outsourcing (BPO)
Procurement Outsourcing Services Market
Business Process Outsourcing (BPO)
Customer Relationship Management (CRM) Outsourcing Market
Business Process Outsourcing (BPO)
Global Application Outsourcing Market
Business Process Outsourcing (BPO)
Desktop Outsourcing Market
Business Process Outsourcing (BPO)
Legal Process Outsourcing (LPO) Market
Business Process Outsourcing (BPO)
UAE Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Service Bureau Market
Business Process Outsourcing (BPO)
Global Software Outsourcing Market
Business Process Outsourcing (BPO)
Labor Outsourcing Service Market