
 Business Process Management (BPM) Market | 2026-2036
Business Process Management (BPM) Market Size, Share, and Industry Trends Forecast 2026-2036
Business Process Management (BPM) Market Intelligence
North American software vendors is recalibrating platform architectures to embed AI-driven process orchestration. Accenture leverages its consulting depth to anchor complex transformation engagements for Fortune 500 clients. SAP Signavio sustains technology leadership in process mining and visualization tools. TIBCO competes through real-time data fabric integration with BPM engines.
Business Process Management comprises methodologies, software tools, and systematic approaches for designing, executing, monitoring, and optimizing operational workflows across organizations, typically incorporating process modeling notation standards, workflow engines with SLA-based routing rules, and analytics dashboards measuring cycle time and exception rates. Its primary purpose is eliminating operational friction, ensuring regulatory traceability, and accelerating decision velocity in mission-critical functions. Cloud-based deployment now leads solution type adoption as enterprises prioritize elastic scalability and reduced infrastructure overhead, while process automation within the solution type dimension captures the fastest expansion trajectory due to labor cost pressures and accuracy demands. The BFSI industry vertical maintains the deepest margin pools given compliance complexity and transaction volumes.
The EU AI Act and GDPR impose algorithmic transparency and data residency requirements that reshape platform design priorities for vendors serving European enterprises. In the United States, NIST cybersecurity frameworks and sector-specific mandates from the SEC influence audit trail and access control specifications in BPM implementations. Stakeholders must monitor evolving AI governance standards and their interoperability with existing process automation investments.
Market Dynamics
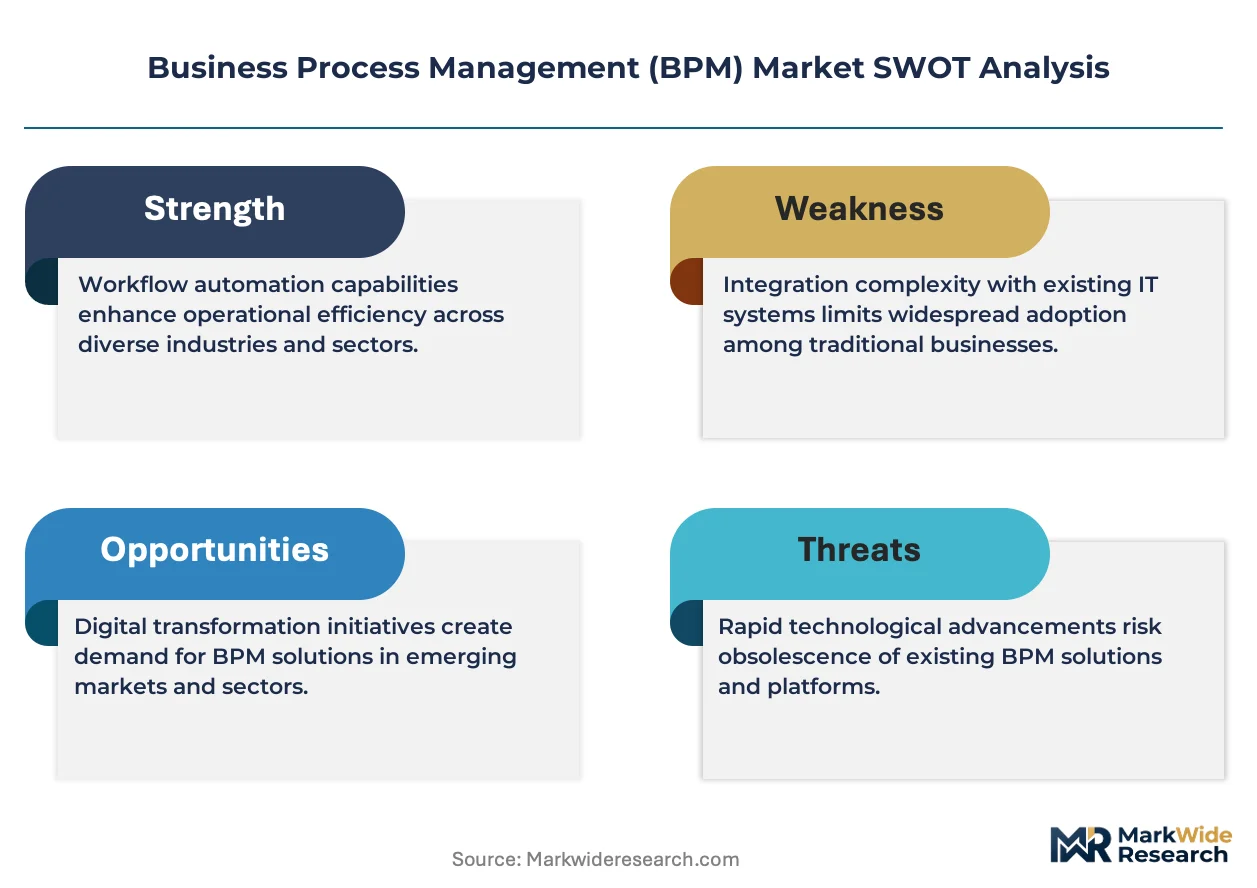
AI-driven process orchestration is compressing implementation cycles and forcing vendors to rearchitect platforms around real-time decision engines rather than static workflow templates.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises must deploy algorithmic transparency tools by 2026, accelerating replacement of legacy BPM suites with auditable, explainable automation platforms.
- BFSI transaction volume pressures:Financial institutions face SLA compression for KYC and AML workflows, driving demand for intelligent process mining and exception-handling automation.
- Cloud elasticity requirements:Seasonal demand spikes in retail and logistics operations favor consumption-based BPM deployment over fixed-capacity on-premise infrastructure.
Market Restraints
- Specialized talent scarcity:Process mining engineers and AI governance specialists command premium compensation, inflating total cost of ownership for enterprise implementations.
- Data residency fragmentation:Divergent national cloud sovereignty laws in Germany, France, and emerging markets force vendors to maintain redundant infrastructure stacks.
- Legacy system entrenchment:Mainframe-based core banking and ERP systems resist API-based integration, prolonging hybrid architecture complexity.
Strategic Opportunities
- Mid-market penetration gap:Sub-$1B revenue manufacturers in the United States lack dedicated process excellence teams, creating whitespace for managed BPM services.
- Healthcare prior authorization automation:HIPAA-compliant workflow engines can capture administrative burden reduction budgets from hospital systems and payers.
- ISO 9001:2015 quality management convergence:Integrated BPM-quality platforms appeal to aerospace and medical device suppliers facing dual certification pressures.
Industry Challenges
- Multi-cloud integration complexity:Enterprises deploying BPM across AWS, Azure, and private clouds encounter inconsistent API governance and identity federation gaps.
- AI model drift in production workflows:Automated decision nodes require continuous retraining pipelines that most IT organizations lack operational maturity to sustain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Business Process Management (BPM) Market |
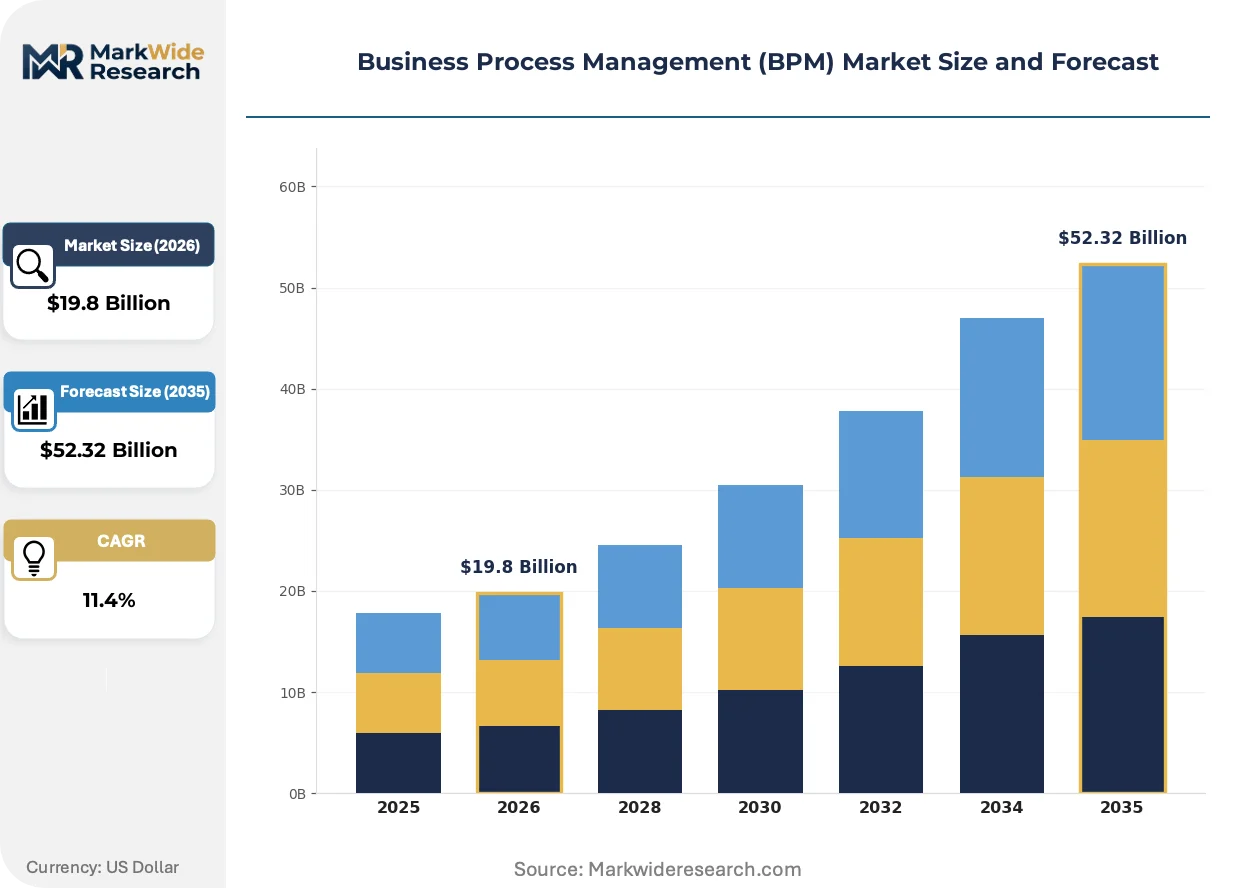
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $52.32 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted Solution Type: Process Modeling, Process Automation, Workflow Management, Process Analytics, Case Management Industry Vertical: BFSI, Telecommunications, Manufacturing, Government Agencies, Education End User: Enterprises, Small & Medium Businesses, IT Companies, Consulting Firms |
| Companies Covered | Genpact, Agiloft, SAP Signavio, Cognizant, Accenture, TIBCO, BP Logix, Wipro, Newgen Software Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Business Process Management (BPM) Market Strategic Shifts & Innovations
Process intelligence platforms are absorbing adjacent capabilities—mining, simulation, and execution—into unified stacks that collapse vendor consolidation cycles and compress buyer evaluation timelines.
Process mining engines with built-in simulation layers are unifying historical analysis and predictive optimization into single-pane environments. Fortune 500 manufacturers in automotive and pharmaceuticals are standardizing on these converged platforms within 18-month procurement cycles. This unification is eliminating the integration tax previously paid to stitch together separate mining and BPM tools.
The EU AI Act's risk-classification framework for automated decision systems is mandating human-in-the-loop audit trails and explainability modules. Platform vendors must embed counterfactual reasoning and decision-provenance logging or face exclusion from European public-sector tenders. Healthcare and financial services procurement teams in Germany and France now require AI Act readiness attestations before pilot approvals.
Subscription-to-outcome contracting is displacing seat-based licensing for process automation. Enterprise buyers in the United States increasingly tie vendor payments to documented cycle-time reduction or FTE redeployment metrics. This shift concentrates negotiation leverage with procurement functions that possess baseline process analytics capabilities, favoring buyers with mature measurement infrastructure.
Business Process Management (BPM) Market Segmentation
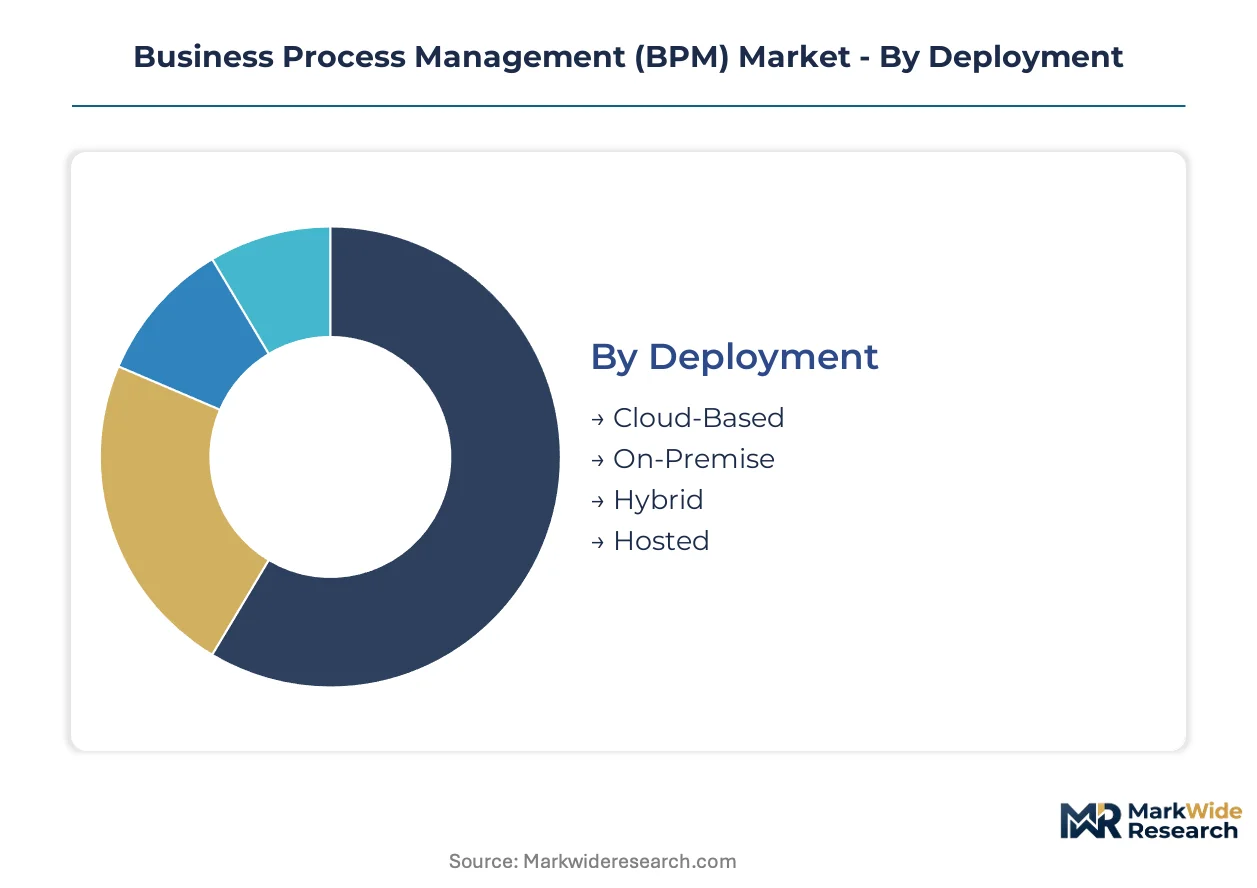
Deployment architecture determines infrastructure spend patterns and vendor selection criteria for BPM implementations. Solution type alignment shapes whether procurement teams prioritize visualization tools or execution engines. Industry vertical focus dictates compliance module requirements and integration complexity.
Deployment:
Supply concentration among hyperscale cloud providers is consolidating infrastructure decisions around three dominant platforms.
- Cloud-Based:Elastic compute resources enable consumption-based scaling for seasonal transaction volumes. Financial services firms in the United States favor multi-tenant SaaS architectures to accelerate GDPR and EU AI Act compliance without capital expenditure cycles.
- On-Premise:Dedicated hardware stacks maintain air-gapped environments for classified government workflows. Defense contractors and national security agencies mandate on-premise BPM for controlled unclassified information processing.
- Hybrid:Split orchestration layers route sensitive operations to private infrastructure while pushing analytics to public cloud endpoints. German automotive manufacturers deploy hybrid configurations to satisfy both commercial agility and works council data sovereignty requirements.
- Hosted:Single-tenant managed services deliver dedicated instance isolation without internal infrastructure ownership. Mid-market manufacturers lacking DevOps capabilities contract hosted BPM for ISO 9001 audit trail maintenance.
Cloud-Based deployments absorb the bulk of installed capacity; Hybrid configurations are expanding most quickly.
Solution Type:
Application depth varies by organizational process maturity and existing technology debt.
- Process Automation:Robotic process automation engines and intelligent document processing compress cycle times for high-volume transactional workflows. Healthcare payers in the United States deploy automation modules to reduce prior authorization turnaround from weeks to hours.
- Process Modeling:BPMN 2.0-compliant design environments enable business-IT collaboration on workflow specification. Aerospace suppliers utilize modeling tools to map AS9100 quality processes before ERP configuration.
- Workflow Management:SLA-driven routing engines enforce escalation rules and exception handling protocols. Telecommunications carriers rely on workflow management for network incident response coordination across distributed operations centers.
- Process Analytics:Real-time dashboards and conformance checking identify bottlenecks through event log analysis. Pharmaceutical manufacturers apply process analytics to batch record review acceleration.
- Case Management:Adaptive frameworks handle unstructured, knowledge-intensive processes without predefined paths. Government agencies implement case management for benefit adjudication requiring discretionary judgment.
Process Automation commands the largest addressable spend; Process Analytics is climbing the fastest as measurement infrastructure matures.
Industry Vertical:
Margin pools and procurement authority concentrate in regulated sectors with complex transaction architectures.
- BFSI:Anti-money laundering and know-your-customer workflows demand auditable decision trails with sub-second response requirements. European banks facing EU AI Act algorithmic transparency mandates are replacing legacy rule engines with explainable automation platforms.
- Manufacturing:Shop-floor integration with MES and quality management systems drives edge-computing BPM deployments. German automotive suppliers converge BPM with ISO 9001:2015 documentation for dual certification efficiency.
- Telecommunications:Service fulfillment and assurance processes span OSS/BSS integration layers requiring real-time orchestration. Tier-1 carriers prioritize low-latency BPM engines for 5G network slice provisioning.
- Government Agencies:Procurement regulations and citizen service delivery mandates favor FedRAMP-authorized or equivalent certified platforms. United States federal agencies constrain vendor selection to cloud environments meeting NIST 800-53 controls.
- Education:Student lifecycle management and research administration workflows compete for limited IT budgets. University systems deploy lightweight BPM for admissions and financial aid coordination.
BFSI captures the deepest margin pools; Manufacturing is gaining share fastest through Industry 4.0 integration requirements.
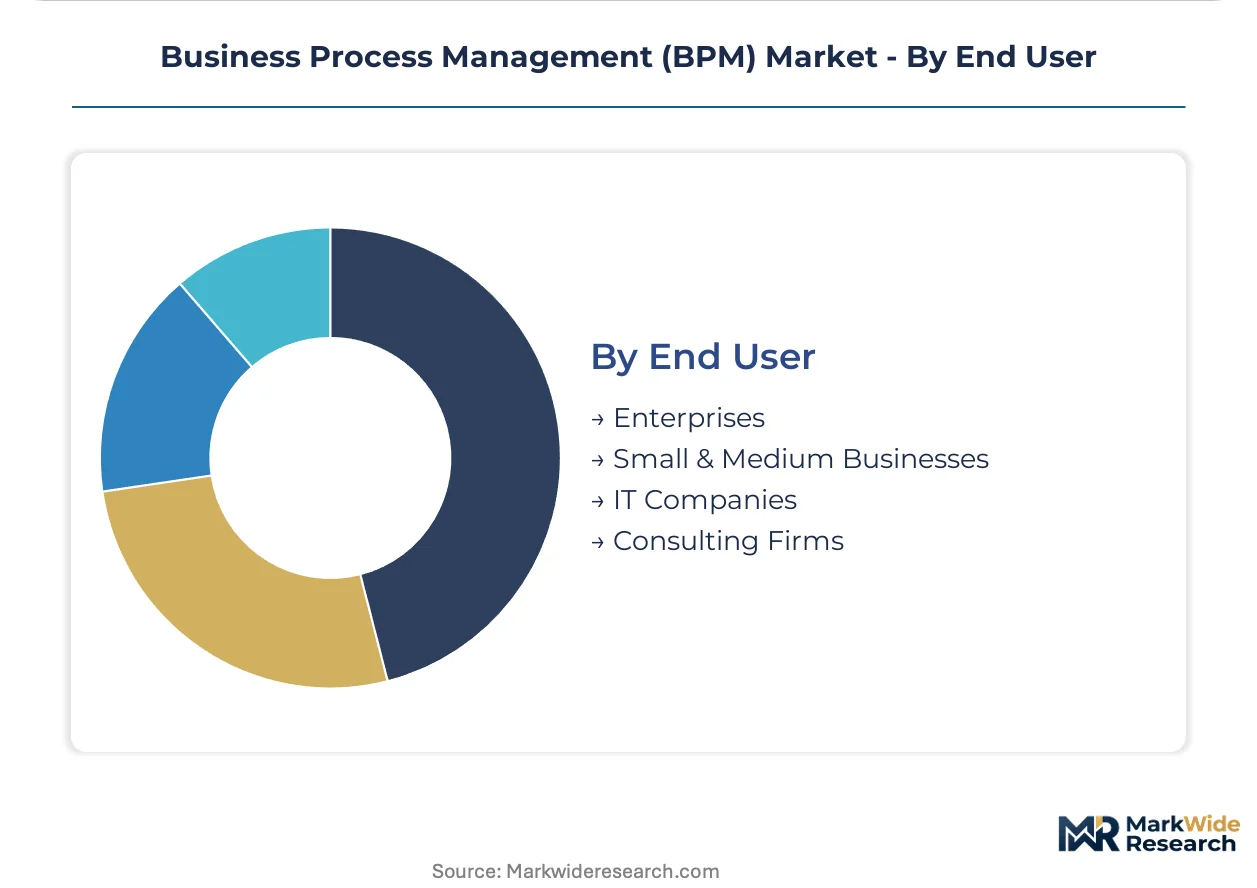
End User:
Customer type determines implementation complexity and support model expectations.
- Enterprises:Global process standardization across business units requires multi-language, multi-currency BPM suites with SAP and Oracle integration. Fortune 500 manufacturers consolidate fragmented workflow tools onto unified platforms.
- Small & Medium Businesses:Pre-configured industry templates and rapid deployment methodologies reduce time-to-value for resource-constrained organizations. United States mid-market manufacturers adopt managed BPM services lacking internal process excellence teams.
- IT Companies:Internal software development and client delivery operations utilize BPM for project portfolio management and service desk automation. Systems integrators embed BPM engines within custom application stacks.
- Consulting Firms:Methodology-driven transformation engagements leverage BPM platforms as change management infrastructure. Strategy consultants deploy process mining and simulation tools for merger integration and cost reduction programs.
Enterprises dominate current procurement volume; Small & Medium Businesses represent the steepest expansion trajectory as cloud delivery lowers entry barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure investments in Virginia and Oregon data centers anchor United States BPM platform delivery, while software development clusters in Bangalore and Hyderabad feed implementation capacity for global deployments.
United States
Financial services institutions in New York and Chicago drive demand for compliance-automation platforms handling SEC audit trails and NIST cybersecurity frameworks. The FDA's digital health guidance shapes workflow requirements for pharmaceutical manufacturers automating batch record reviews. Silicon Valley vendors and Boston consulting clusters compete for Fortune 500 transformation contracts.
Germany
Automotive suppliers in Stuttgart and Munich pursue ISO 9001:2015 convergence with BPM documentation for dual certification efficiency. The KBA and works council agreements enforce strict data sovereignty requirements favoring hybrid deployments. Industrial software clusters in Bavaria develop edge-computing BPM integrations for smart factory deployments.
United Kingdom
London-based financial services firms invest in algorithmic transparency tools ahead of anticipated alignment with EU AI Act principles. The Financial Conduct Authority's operational resilience rules mandate business continuity testing within BPM orchestration layers. Fintech clusters in Manchester and Edinburgh specialize in regulatory workflow automation for mid-tier banks.
India
IT services hubs in Bangalore and Hyderabad deliver BPM implementation capacity for global enterprises seeking cost-optimized transformation. RBI guidelines on digital lending workflows drive domestic demand for auditable process automation. Manufacturing corridors in Gujarat and Tamil Nadu adopt cloud BPM for supplier quality management.
France
Paris-headquartered luxury goods groups deploy BPM for supply chain traceability meeting CSRD disclosure requirements. The CNIL enforces GDPR-compliant data processing logs within automation platforms. Aerospace clusters in Toulouse integrate BPM with AS9100 quality systems for defense and commercial aviation contracts.
Business Process Management (BPM) Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue AI-native orchestration capabilities outside legacy workflow paradigms. The vendor landscape stratifies across three maturity tiers: global systems integrators anchoring complex transformation programs, pure-play software vendors defending technology leadership positions, and regional specialists capturing mid-market managed services contracts. Consolidation pressure intensifies as process intelligence platforms absorb adjacent mining and simulation functions. Dominant competitive moves include strategic partnerships embedding BPM engines within hyperscale cloud marketplaces and vertical integration into industry-specific compliance modules.
Within the consulting-anchored tier, Accenture exemplifies the transformation-program archetype through methodology-driven engagements. SAP Signavio occupies a position representing technology-centric vendors with process mining and visualization depth. TIBCO sits within the integration-specialist segment, anchoring real-time data fabric connectivity with BPM execution layers.
| Leading Market Players |
|---|
| Genpact |
| Agiloft |
| SAP Signavio |
| Cognizant |
| Accenture |
| TIBCO |
| BP Logix |
| Wipro |
| Newgen Software Technologies |
| Others |
Cost & Logistics Intelligence
Captive cloud infrastructure development by hyperscale providers anchors supply positions while compressing margins for independent software vendors unable to match consumption-based economics. This vertical integration dynamic concentrates pricing power with AWS, Microsoft Azure, and Google Cloud, forcing BPM vendors to absorb platform fees or surrender margin to marketplace commissions.
Pricing Analysis
Warranty and service bundling separates enterprise-grade BPM contracts from self-serve SaaS tiers, with implementation support and SLA guarantees commanding premium positioning. Subscription-to-outcome contracting is displacing seat-based licensing as United States procurement teams tie vendor payments to documented cycle-time reduction metrics. Price differentiation hinges on AI governance module inclusion and EU AI Act compliance attestation status. Cost compression in mid-market tiers is intensifying because cloud-native entrants undercut legacy suite pricing by sixty percent or more. Small and medium businesses exhibit highest price sensitivity, while Fortune 500 manufacturers with dedicated process excellence teams prioritize capability depth over license cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based semiconductor fabrication for BPM platform hardware acceleration and Ireland-based data centers for European GDPR-compliant processing. Component sourcing draws from Germany for industrial edge-computing hardware, India for implementation engineering capacity, and the United States for hyperscale cloud infrastructure. Supply chain risk centers on tariff exposure for cross-border data routing equipment and algorithmic transparency tooling. Distribution runs through direct enterprise sales forces for complex transformation engagements, hyperscaler marketplaces for cloud-native deployments, and systems integrator channels for managed service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into process mining engines and AI governance modules defines competitive survival as vendors race to collapse vendor consolidation cycles and capture outcome-based contracting premiums.
For Market Incumbents: Acquire specialized process mining firms to unify historical analysis and predictive optimization within single-pane environments before cloud-native entrants replicate this convergence. Integrate EU AI Act explainability modules directly into core orchestration layers to preempt exclusion from European public-sector tenders. Threat substitution from AI-native orchestration platforms without legacy workflow paradigms demands defensive capability expansion. Leverage consulting depth to anchor complex transformation engagements and resist margin compression from outcome-based contracting. For New Entrants and Emerging Players: The premium-to-economy pricing gap in healthcare prior authorization automation offers immediate white-space capture for HIPAA-compliant workflow engines with rapid deployment methodologies. Target United States mid-market manufacturers lacking dedicated process excellence teams with managed BPM services priced below Accenture-tier transformation programs. Aerospace and medical device suppliers facing dual ISO 9001:2015 and AS9100 certification pressures represent underpenetrated verticals. Go-to-market angle should emphasize pre-configured industry templates with audit trail maintenance guarantees rather than custom implementation services. For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscaler marketplace acquisitions and vertical software consolidation plays as process intelligence platforms absorb adjacent mining and simulation functions. Long-term viability favors vendors with embedded AI governance capabilities and demonstrated EU AI Act compliance attestations. Acquisition target archetype includes regional specialists with mid-market managed services contracts and ISO 9001 convergence expertise. Signal to watch is subscription-to-outcome contract penetration rates as procurement leverage shifts toward buyers with mature measurement infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies process mining, simulation, and execution layers to eliminate vendor consolidation cycles for Fortune 500 manufacturers. |
| Acquisition of Specialist Firm | Captures process mining depth and AI governance expertise to satisfy EU AI Act algorithmic transparency mandates. |
| Strategic Partnership | Embeds BPM engines within hyperscale cloud marketplaces to secure consumption-based distribution economics. |
| Geographic Expansion | Establishes GDPR-compliant data residency infrastructure in Germany and France to capture European public-sector tenders. |
| Product Launch | Introduces healthcare-specific prior authorization modules to capture administrative burden reduction budgets from United States payers. |
Research Approach
Document review covered SEC filings of publicly traded software vendors, EU regulatory guidance on algorithmic transparency, and hyperscaler capex disclosures, complemented by interviews with process excellence directors, IT procurement officers at Fortune 500 manufacturers, cloud platform engineers, and healthcare payer operations executives. Secondary validation drew from BPM vendor pricing documentation, systems integrator case studies, and ISO certification body reports. Bottom-up sizing of deployment volumes and top-down cross-check against aggregate software spending produced converged market estimates.
Cross-referencing historical adoption curves against expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled include deployment architecture, solution type, industry vertical, and organization size tier. CAGRs were derived from slope analysis of cloud migration trajectories and regulatory compliance investment cycles. Forecast inputs incorporated EU AI Act implementation timelines and BFSI transaction volume compression patterns.
Underlying measurement precision varies by segment; cloud-based deployments carry tighter precision than on-premise configurations given disclosed hyperscaler revenue attribution. Forecasts reflect assumptions regarding regulatory enforcement consistency and enterprise cloud migration velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Back Office Outsourcing Market
Business Process Outsourcing (BPO)
Automotive Business Process Management Market
Business Process Outsourcing (BPO)
Cloud Based BPO Market
Business Process Outsourcing (BPO)
Indonesia Business Process Outsourcing Services Market
Business Process Outsourcing (BPO)
Employment Screening Services Market
Business Process Outsourcing (BPO)
UAE Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Call Center Outsourcing Market
Business Process Outsourcing (BPO)
Data Entry Service Market
Business Process Outsourcing (BPO)
Recruitment Process Outsourcing (RPO) Services Market
Business Process Outsourcing (BPO)
Global Outsourced Sales Service Market
Business Process Outsourcing (BPO)
Global Document Outsourcing Market
Business Process Outsourcing (BPO)
South Africa Business Process Outsourcing Market
Business Process Outsourcing (BPO)
Asia-Pacific Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Direct to Customer Outsourced Fulfillment Market
Business Process Outsourcing (BPO)
Global Cloud Bpo Market
Business Process Outsourcing (BPO)
Middle East and Africa Business Process Outsourcing (BPO) Market