
 Global Application Outsourcing Market | 2026-2036
Global Application Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Application Outsourcing Market Foresight
India's technology corridor is reconfiguring global delivery geography for application outsourcing. Tata Consultancy Services anchors extensive offshore development centers across Bangalore and Hyderabad. Accenture Plc leverages hybrid delivery models to sustain premium positioning in cloud migration services. IBM Consulting differentiates through deep vertical expertise in regulated industries.
Application outsourcing encompasses the external management of software development, maintenance, testing, and modernization functions performed under contractual service agreements with defined SLAs, security protocols, and governance frameworks. Its primary purpose is to reduce internal IT operational burden while accessing specialized technical capabilities and scalable talent pools. Cloud migration services within the service type dimension are attracting disproportionate investment as enterprises accelerate mainframe-to-cloud transitions. The BFSI vertical commands the deepest engagement complexity due to stringent data residency requirements and legacy system interdependencies. Managed services under engagement type are consolidating margin pools through multi-year annuity contracts with embedded automation clauses.
FDA guidelines on software validation for healthcare applications shape outsourcing provider qualification requirements in the United States. The EU AI Act and GDPR jointly determine algorithmic transparency and cross-border data handling standards for European engagements. ISO 27001 certification has become a baseline market access requirement rather than a competitive differentiator. Stakeholders must evaluate provider investments in generative AI tooling and sovereign cloud infrastructure as decisive capability thresholds.
Market Dynamics
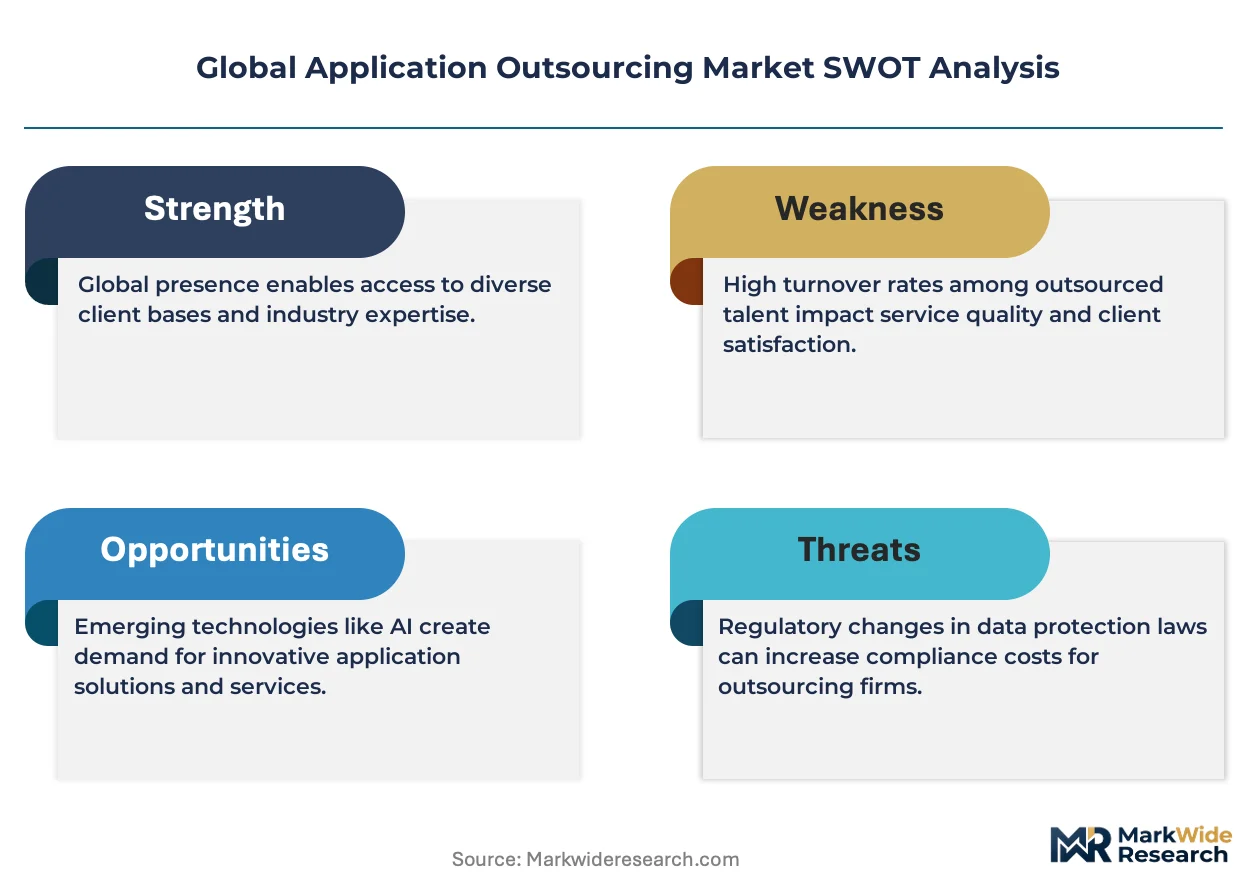
The EU AI Act is forcing European enterprises to restructure outsourcing partnerships around algorithmic transparency mandates, compressing vendor qualification timelines and elevating compliance-ready providers.
Growth Catalysts
- Cloud Migration Acceleration:Mainframe-to-cloud transitions are pulling multi-year modernization contracts across BFSI and healthcare verticals. Enterprises seek providers with sovereign cloud infrastructure certifications.
- India's Delivery Corridor:Deepening specialized capabilities in Bangalore and Hyderabad are concentrating offshore development capacity. Technology services clusters now support complex regulatory workloads.
- GDPR-EU AI Act Convergence:Joint compliance requirements for cross-border data handling and algorithmic accountability are disqualifying non-compliant vendors. This creates preference premiums for certified providers.
Market Restraints
- Legacy System Interdependencies:BFSI institutions face prohibitive switching costs from decades-old core banking architectures. Migration complexity extends project timelines and inflates risk premiums.
- Talent Concentration Risk:Specialized cloud engineering skills cluster in Indian metropolitan centers. Geographic supply concentration creates wage inflation and attrition vulnerability.
- Data Residency Mandates:National regulations in Germany, France, and India require local processing infrastructure. Fragmented compliance architectures inflate provider operational costs.
Strategic Opportunities
- Generative AI Tooling Integration:Code generation and automated testing capabilities are opening new service line expansion. Early movers are embedding AI-assisted delivery into annuity contracts.
- Healthcare Outsourcing White Space:FDA software validation requirements are raising barriers for incumbent providers. Specialized compliance expertise creates entry opportunity in clinical application management.
- ISO 27001-Plus Positioning:Baseline certification saturation enables differentiation through sovereign cloud attestations and sector-specific security frameworks. Premium pricing attaches to stacked credentials.
Industry Challenges
- Embedded Automation Clause Execution:Multi-year managed services contracts now mandate productivity improvements through robotic process automation. Providers face capex intensity for tool deployment without guaranteed outcome realization.
- Cross-Border IP Framework Complexity:Software development across jurisdictions generates patent and trade secret fragmentation. Dispute resolution across US, EU, and Indian legal systems inflates contract structuring costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Application Outsourcing Market |
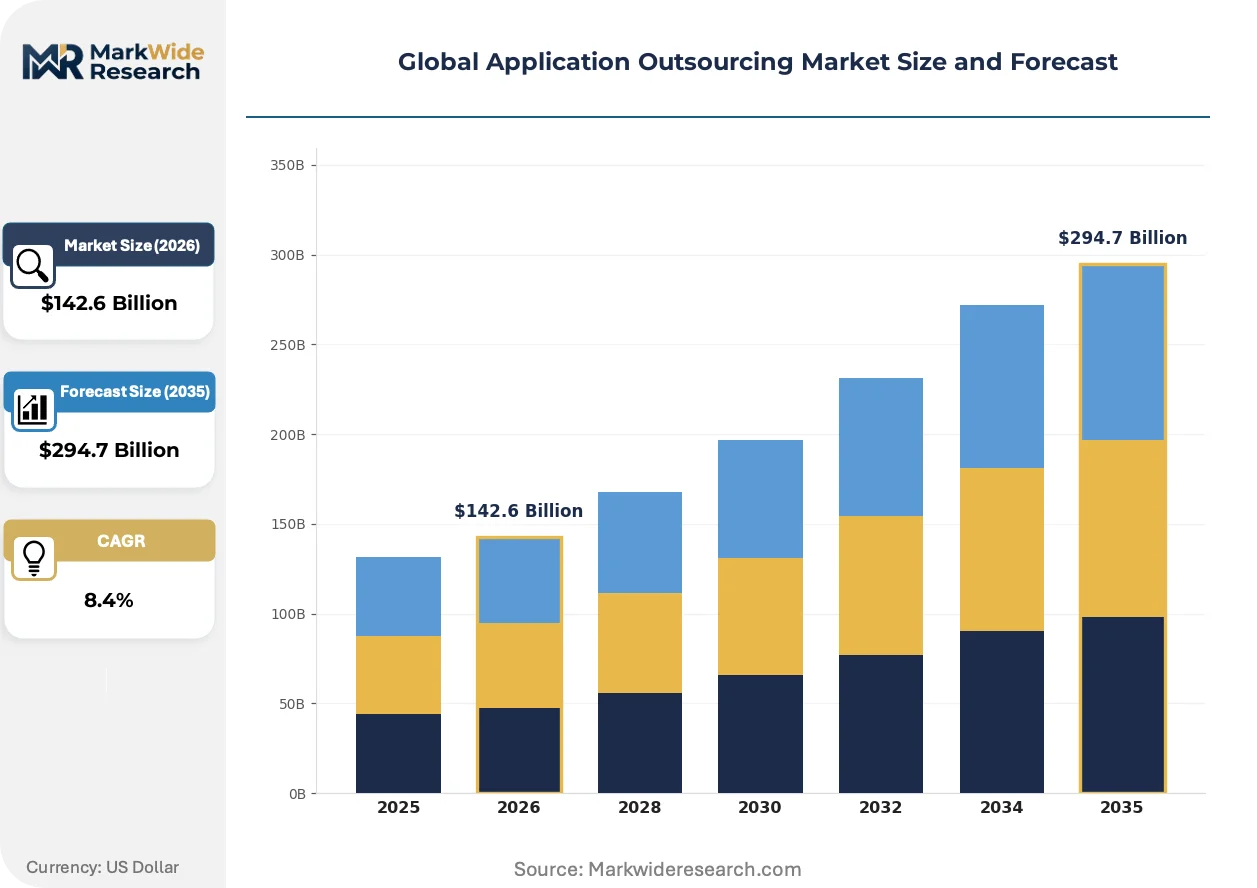
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $294.7 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Application Development, Application Maintenance, Testing Services, Cloud Migration, Consulting Services Industry Vertical: BFSI, Telecommunications, Retail, Manufacturing, Government, Education Engagement Type: Staff Augmentation, Project-Based, Dedicated Teams, Managed Services, Hybrid Models Delivery Model: Onshore, Nearshore, Offshore, Hybrid, Cloud-Based |
| Companies Covered | Accenture Plc, Tata Consultancy Services, IBM Consulting, Cognizant Technology Solutions Corporation, Wipro Limited, NTT Data, HCL Technologies, Infosys Ltd., Capgemini, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Application Outsourcing Market Shifts & Advancements
Generative AI tooling is collapsing traditional service delivery economics while regulatory convergence across the EU and US is rewriting vendor qualification protocols. Demand patterns are rotating toward outcome-governed engagements.
Large language model code generation is collapsing the cost structure for routine application maintenance and testing functions. BFSI procurement teams are piloting AI-assisted delivery models in non-core systems. This compression is enabling price repositioning in commoditized service tiers.
The EU AI Act's algorithmic transparency mandates are reshaping provider disclosure requirements for automated decision systems. Healthcare and financial services outsourcing contracts now embed audit rights for training data provenance. German and French enterprises are demanding pre-certified AI governance frameworks as table stakes.
Enterprise buyers are consolidating vendor portfolios around integrated platform capabilities. Discrete project-based engagements are yielding to multi-tower managed services with embedded automation clauses. This concentration is most visible in US healthcare and UK financial services procurement patterns.
Global Application Outsourcing Market Segmentation
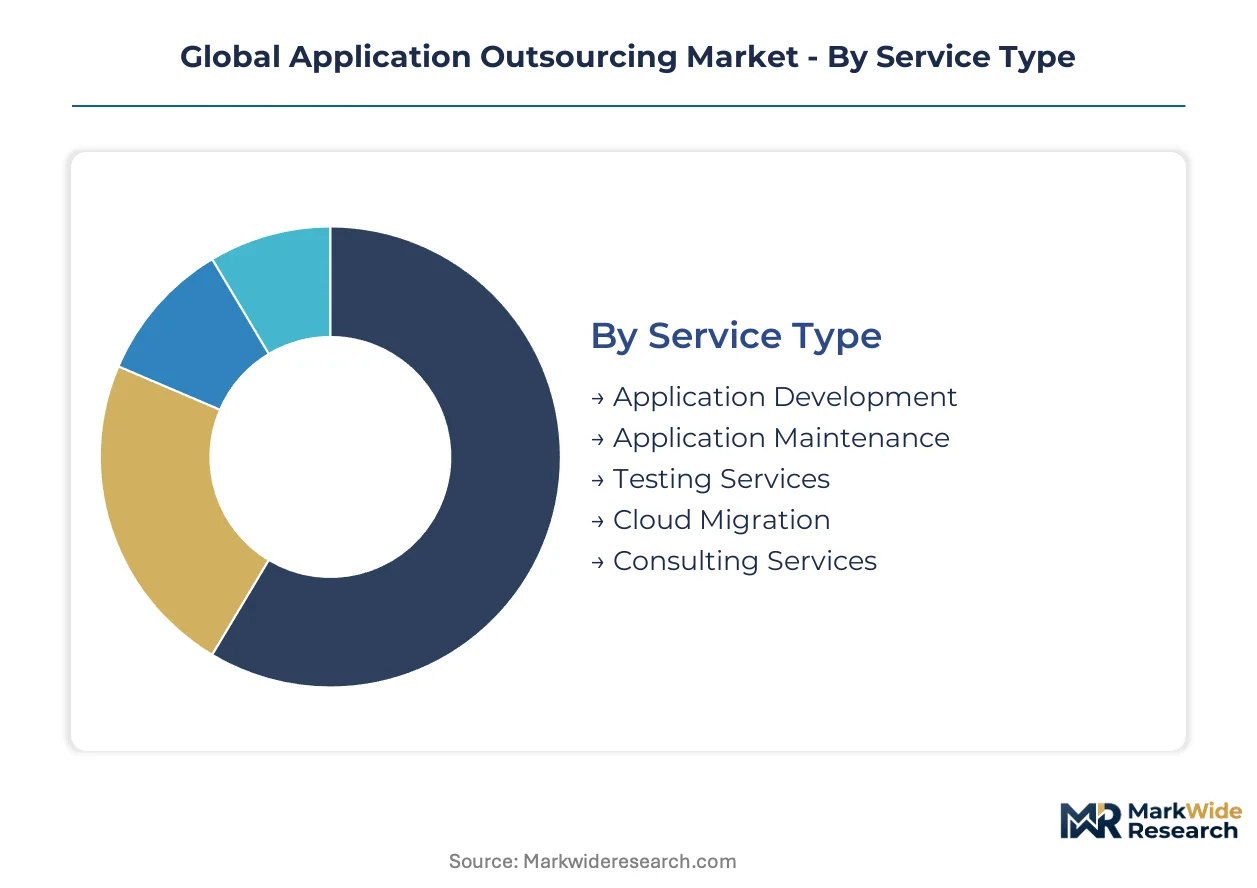
Application outsourcing segmentation reveals distinct service economics and compliance requirements across delivery modes. Procurement teams use these categories to match vendor capabilities against workload complexity and regulatory exposure.
Service Type:
After-sales service intensity varies sharply across service types, with maintenance and support functions demanding sustained engineering presence while development engagements taper post-deployment.
- Cloud Migration:Mainframe-to-cloud transitions require sovereign infrastructure certifications and multi-year modernization roadmaps. BFSI institutions in Germany and France are concentrating procurement here due to data residency mandates under GDPR.
- Application Maintenance:Sustained engineering presence for legacy system upkeep generates recurring revenue pools. Indian delivery corridors in Bangalore and Hyderabad dominate capacity for COBOL and mainframe skill sets.
- Application Development:Custom software builds with defined release milestones.
- Testing Services:Quality assurance and automated validation protocols.
- Consulting Services:Advisory engagements for architecture and transformation planning.
Cloud Migration holds the largest share; momentum sits with Application Maintenance.
Industry Vertical:
Cost tier stratification separates verticals, with BFSI and healthcare commanding premium pricing for compliance-heavy workloads while retail and education operate at standardized rates.
- BFSI:Core banking modernization with stringent data residency requirements and legacy interdependencies. German and French regulatory frameworks under EU AI Act and GDPR elevate vendor qualification barriers.
- Telecommunications:Network operations and customer-facing application management. Indian operators are expanding managed services contracts for billing and CRM platforms.
- Retail:E-commerce platform maintenance and seasonal scaling support.
- Manufacturing:ERP integration and supply chain application management.
- Government:Citizen service portals with sovereignty requirements.
- Education:Learning management systems and administrative platforms.
BFSI commands premium pricing; telecommunications is climbing the fastest.
Engagement Type:
Volume concentration patterns favor multi-year structures, with managed services and hybrid models capturing expanding procurement share against discrete project arrangements.
- Managed Services:Multi-year annuity contracts with embedded automation clauses and defined SLA frameworks. US healthcare providers are consolidating here under FDA software validation requirements.
- Hybrid Models:Blended onshore-offshore delivery with flexible scaling mechanisms. UK financial services procurement teams favor this structure for regulatory proximity combined with cost optimization.
- Staff Augmentation:Temporary personnel placement for skill gap filling.
- Project-Based:Fixed-scope delivery with defined milestones and acceptance criteria.
- Dedicated Teams:Captive offshore units for sustained client alignment.
Managed Services holds the largest share; Hybrid Models are gaining share fastest.
Delivery Model:
Customer type segmentation separates enterprise buyers seeking sovereign control from mid-market purchasers prioritizing cost efficiency over geographic proximity.
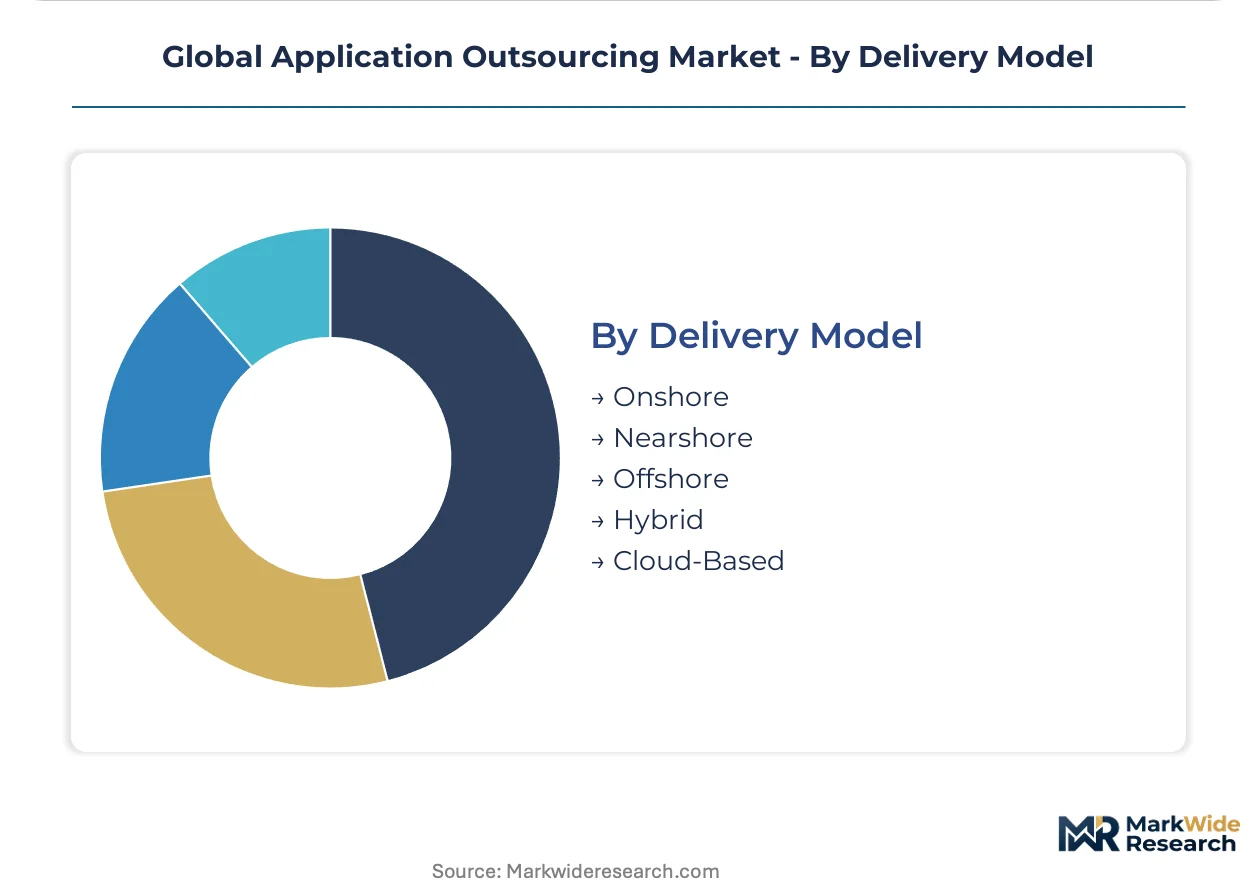
- Offshore:India-based delivery centers with specialized regulatory workload capabilities. Hyderabad and Bangalore clusters now support complex BFSI and healthcare compliance requirements.
- Hybrid:Coordinated onshore-offshore execution with workload tiering by sensitivity. German enterprises are mandating this structure for EU AI Act algorithmic transparency compliance.
- Onshore:Domestic delivery for maximum regulatory proximity.
- Nearshore:Regional proximity sourcing for timezone alignment.
- Cloud-Based:Fully distributed delivery via sovereign cloud infrastructure.
Offshore holds the largest share; Hybrid is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian delivery corridors concentrate specialized capacity for regulatory workloads. The United States, Germany, United Kingdom, and Japan anchor demand through distinct compliance frameworks and vertical requirements.
United States
BFSI institutions and healthcare providers drive complex modernization mandates. FDA software validation requirements shape outsourcing provider qualifications for clinical application management. Delivery clusters concentrate in Dallas-Fort Worth and New York Metro for proximity to financial services headquarters.
Germany
Industrial enterprises and automotive suppliers demand sovereign cloud infrastructure for ERP integration. EU AI Act algorithmic transparency mandates compress vendor qualification timelines. Frankfurt and Munich technology corridors deepen specialized delivery for regulated manufacturing workloads.
United Kingdom
Financial services procurement teams favor hybrid engagement models for regulatory proximity combined with cost optimization. FCA operational resilience requirements elevate vendor scrutiny for critical banking infrastructure. London and Edinburgh clusters support multi-tower managed services consolidation.
India
Bangalore and Hyderabad delivery centers anchor global offshore capacity for complex BFSI and healthcare compliance requirements. RBI data localization directives and SEBI cybersecurity frameworks shape infrastructure investment patterns. Technology services corridors now support mainframe-to-cloud transitions for European and North American enterprises.
Japan
Manufacturing conglomerates and telecommunications operators seek application maintenance for legacy system interdependencies. METI digital transformation incentives accelerate cloud migration procurement. Tokyo and Osaka metropolitan areas concentrate domestic delivery capacity for maximum regulatory proximity.
Global Application Outsourcing Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in discrete service lines. The vendor base stratifies across three tiers: global consultancies with end-to-end capabilities, offshore specialists with scale-driven delivery models, and boutique firms with vertical-specific compliance expertise. Dominant competitive moves include embedded automation clause integration and sovereign cloud infrastructure certification.
Among India-based delivery specialists, Tata Consultancy Services and Wipro Limited exemplify scale-driven offshore positioning with deep regulatory workload capabilities. Accenture Plc anchors the premium-tier consultancy segment through hybrid delivery model execution. These three entities represent distinct competitive archetypes: scale-specialist, integrated platform, and premium advisory respectively.
| Leading Market Players |
|---|
| Accenture Plc |
| Tata Consultancy Services |
| IBM Consulting |
| Cognizant Technology Solutions Corporation |
| Wipro Limited |
| NTT Data |
| HCL Technologies |
| Infosys Ltd. |
| Capgemini |
| Others |
Supply & Pricing Matrix
Undercapacity in sovereign cloud infrastructure across Germany and France is compressing vendor qualification timelines while elevating pricing premiums for compliant providers. Indian delivery corridors at full utilization are transmitting wage inflation into offshore contract rates, reshaping buyer procurement calculus.
Pricing Analysis
GDPR-EU AI Act convergence dictates the pricing tier structure across European engagements, with algorithmic transparency mandates separating certified providers from commodity competitors. Three-tier pricing structure across premium compliance-ready, standard certified, and economy non-regulated tiers reflects certification stacking intensity. Cost compression in standard-tier maintenance services is intensifying because generative AI tooling collapses routine delivery economics. Mid-market enterprises in retail and education verticals exhibit highest price sensitivity, while BFSI institutions accept premium positioning for data residency assurance.
Supply Chain Analysis
Talent concentration risk between Indian metropolitan centers and European regulatory hubs dominates supply chain vulnerability assessment for complex workload delivery. Engineering capacity concentrates in India, Germany, and the United Kingdom, with sovereign cloud infrastructure sourcing from domestic providers in France and Germany. Provider capability development draws from specialized university pipelines, certification body accreditations, and hyperscaler partnership tiers. Single-source vulnerability in Bangalore-Hyderabad talent clusters threatens delivery continuity during attrition spikes. Distribution runs through direct enterprise sales teams with embedded solution architects, supplemented by systems integrator partnerships for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed services annuity contracts represent a service-attach opportunity expanding faster than discrete project delivery, with embedded automation clauses deepening recurring revenue capture per client relationship.
For Market Incumbents: Build switching-cost moats through legacy system interdependency mapping and multi-tower consolidation. Accenture Plc and Tata Consultancy Services should deepen sovereign cloud infrastructure certifications ahead of EU AI Act enforcement waves. Threat from boutique compliance specialists requires preemptive vertical expertise acquisition in FDA-validated healthcare segments. Capacity addition in Frankfurt and Munich technology corridors anchors regulatory proximity for German industrial clients. For New Entrants and Emerging Players: Pursue healthcare outsourcing white space created by FDA software validation barriers for incumbent generalists. Clinical application management for US providers offers most penetrable entry point given specialized compliance requirements. Target mid-tier hospital systems with bundled validation-ready maintenance services as differentiated go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among managed services providers with embedded automation clauses and multi-year contract tenures. Long-term viability across the analysis window favors platform integrators over discrete project shops. Acquisition target archetype: boutique firms with stacked ISO 27001-plus credentials and vertical-specific compliance expertise. Signal to watch: generative AI tooling deployment velocity as margin compression indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | EU AI Act compliance enables premium positioning in German and French procurement cycles. |
| Generative AI Tooling Integration | Code generation capabilities collapse maintenance economics for BFSI legacy systems. |
| Vertical Compliance Acquisition | FDA validation expertise opens healthcare outsourcing white space against generalist incumbents. |
| Multi-Tower Managed Services Consolidation | UK financial services procurement patterns favor integrated platform capabilities over discrete vendors. |
| Hybrid Delivery Model Expansion | Blended onshore-offshore execution satisfies German algorithmic transparency mandates with cost optimization. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews combined with secondary source validation. CTOs at BFSI institutions, IT procurement officers in healthcare systems, platform engineers at Indian delivery centers, channel partners for systems integrators, and regulatory compliance leads were interviewed. Secondary sources included SEC filings for listed providers, EU AI Act implementation guidance documents, RBI data localization directives, and hyperscaler sovereign cloud certification disclosures. Bottom-up contract value aggregation and top-down market sizing triangulation anchored volume estimates.
Calibration against historical contract award patterns and announced modernization roadmaps shaped trajectory assumptions across the projection horizon. Segmentation dimensions modeled include service type, industry vertical, engagement type, delivery model, and geographic regulatory cluster. CAGRs were derived from trend extrapolation of disclosed contract values and announced capacity investments. Cloud migration velocity in BFSI and generative AI tooling deployment rates served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in central bank rate trajectories and cross-border data flow restrictions would shift the trajectory of offshore delivery demand. Forecasts reflect documented assumptions about regulatory enforcement timing and technology adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Payroll Outsourcing Services Market
Business Process Outsourcing (BPO)
Healthcare Supply Chain BPO Market
Business Process Outsourcing (BPO)
Service Bureau Market
Business Process Outsourcing (BPO)
Asia-Pacific Business Process As a Service (Bpaas) Market
Business Process Outsourcing (BPO)
Document Outsourcing Services Market
Business Process Outsourcing (BPO)
United States IT Outsourcing Market
Business Process Outsourcing (BPO)
Global Telecom Outsourcing Market
Business Process Outsourcing (BPO)
Business Process As a Service (Bpaas) Market
Business Process Outsourcing (BPO)
Global Document Outsourcing Market
Business Process Outsourcing (BPO)
Business Process Re-Engineering Market
Business Process Outsourcing (BPO)
Back Office Outsourcing Market
Business Process Outsourcing (BPO)
Global IT Outsourcing Services Market
Business Process Outsourcing (BPO)
Business Process Management (BPM) Market
Business Process Outsourcing (BPO)
Call Center Outsourcing Market
Business Process Outsourcing (BPO)
Global Insurance Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Global Supply Chain Management BPO Market