
 Back Office Outsourcing Market | 2026-2036
Back Office Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Back Office Outsourcing Market Insights
Skilled accounting and IT labor scarcity in developed economies is reorganizing how enterprises approach non-core operations. TaskUs leverages its Philippines-based workforce to sustain high-volume customer support contracts for technology clients. Cloudstaff anchors its competitive stance through dedicated team models that extend client control over remote finance and accounting functions. GigaBPO competes by specializing in procurement and data management services for mid-market manufacturing firms.
Back office outsourcing encompasses the delegation of internal business functions—finance and accounting, human resources, IT support, data management, and procurement—to third-party providers operating through cloud-based platforms, SLA-governed workflows, and offshore or nearshore delivery centers. These arrangements reduce fixed cost structures while granting access to specialized process expertise and scalable technology infrastructure. Finance and accounting outsourcing commands the largest revenue pool due to complex regulatory reporting requirements, while IT support and data management segments exhibit the fastest structural growth as enterprises migrate legacy systems to cloud environments. Customer support remains a mature, high-volume category where margin compression pushes providers toward AI-augmented delivery models.
The US Securities and Exchange Commission mandates financial reporting controls that shape demand for compliant finance and accounting outsourcing arrangements, while India's RBI guidelines on data localization influence IT support and data management contract structuring. The EU's GDPR framework restricts cross-border personal data flows in human resources outsourcing, compelling providers to establish European delivery infrastructure. Buyers must evaluate provider capabilities against evolving multi-jurisdictional compliance requirements rather than cost metrics alone.
Market Dynamics
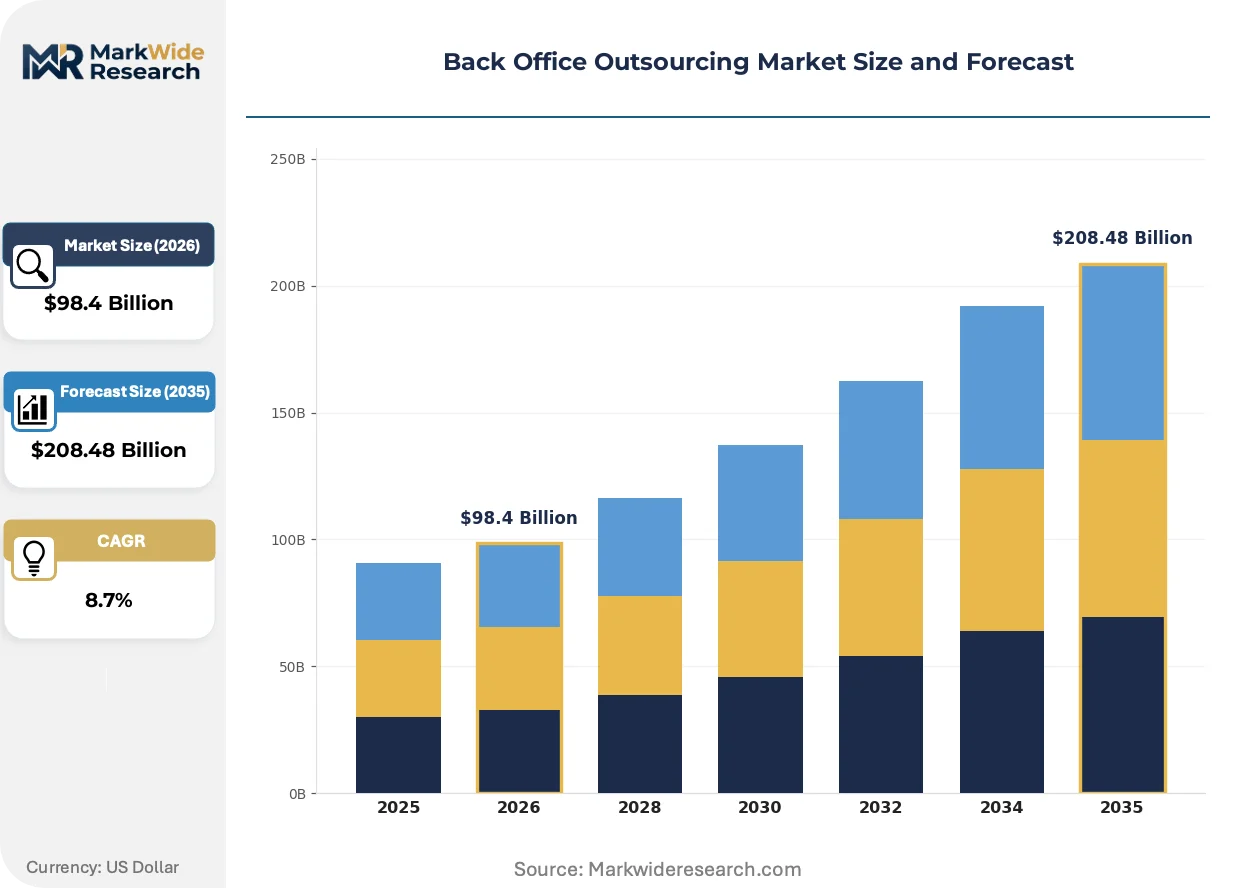
Cloud migration and AI-enabled process automation are compressing delivery timelines while fragmenting provider value pools between commodity transaction processing and high-margin advisory services. The SEC's financial reporting mandates and India's RBI data localization requirements are forcing contract structures that embed compliance costs directly into pricing models.
Growth Catalysts
- GDPR-driven European infrastructure buildout:The EU's cross-border data flow restrictions compel providers to establish captive delivery centers in Germany, Poland, and Ireland, expanding addressable contract value through compliance-embedded pricing.
- Healthcare revenue cycle complexity:US hospital systems facing ICD-10 billing mandates and prior authorization automation requirements are outsourcing end-to-end revenue management to specialized finance and accounting providers.
- Generative AI document processing:Large language models trained on enterprise ERP data are automating invoice matching, reconciliation, and exception handling at throughput rates that reshape staffing ratios in finance operations.
Market Restraints
- Philippines labor cost inflation:Manila-based customer support wages have risen 40% since 2019, eroding the cost arbitrage that sustained high-volume voice contracts for North American buyers.
- Technical debt in legacy ERP integration:SAP and Oracle system migrations to cloud environments require 18-24 month timelines that delay automation ROI realization and extend payback periods.
- RBI data localization friction:India's central bank mandates restrict cross-border data flows in IT support and data management, forcing redundant infrastructure investments that inflate contract minimums.
Strategic Opportunities
- US mid-market manufacturing penetration:Firms with 500-5,000 employees remain underserved by tier-one providers, creating white space for procurement and supply chain finance outsourcing specialists.
- ISO 27001 certification arbitrage:Buyers facing vendor consolidation mandates are prioritizing providers with existing information security certifications, accelerating competitive displacement of uncertified regional players.
- Convergence of RPA and generative AI:The integration of robotic process automation with natural language processing enables end-to-end automation of unstructured document workflows previously requiring human judgment.
Industry Challenges
- Certified accountant scarcity in tier-two Indian cities:US GAAP and IFRS-trained professionals concentrate in Bangalore and Hyderabad, constraining scale-out to lower-cost delivery locations.
- HIPAA Business Associate Agreement complexity:Healthcare outsourcing contracts require legal review cycles of 4-6 months, compressing sales velocity and inflating customer acquisition costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Back Office Outsourcing Market |
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $208.48 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Finance & Accounting, Human Resources, IT Support, Customer Support, Data Management, Procurement Industry Vertical: Banking, Telecommunications, Insurance, Travel & Hospitality, Education, Manufacturing Client Type: Small & Medium Enterprises, Large Enterprises, Startups, Government Agencies Engagement Model: Dedicated Team, Project-based, Fixed Price, Time & Material, Build Operate Transfer |
| Companies Covered | GigaBPO, Virtual Coworker, TaskUs, SupportYourApp, Big Outsource, Unity Communications, Cloudstaff, Fresa Technologies, TECHSPEED INC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Back Office Outsourcing Market Trends and Innovations
Service delivery models are splitting between high-touch advisory functions and fully automated transaction processing, with AI capabilities determining which providers capture margin expansion versus commoditization pressure.
Intelligent document processing is bifurcating competitive positioning in finance and accounting outsourcing. Machine learning systems trained on millions of invoices and purchase orders now extract data fields with 98% accuracy. Large enterprises with complex multi-entity structures are adopting these platforms fastest, while mid-market buyers lag 18-24 months. This technology compression is eliminating data entry roles while expanding demand for exception handling specialists who manage algorithmic edge cases.
REACH chemical substance registration requirements in the European Union are reshaping procurement outsourcing contract scopes. The regulation mandates supply chain traceability documentation that many buyers cannot generate internally. German automotive and industrial chemical buyers are now requiring procurement service providers to embed regulatory compliance verification directly into supplier onboarding workflows, shifting provider selection criteria from cost per transaction to liability coverage depth.
Enterprise buyers are unbundling after-sales support from core outsourcing contracts. Technology and financial services firms now separately procure tier-one troubleshooting, tier-two technical escalation, and knowledge base maintenance from different specialists. This fragmentation is most pronounced in US and UK markets where procurement functions have matured to manage multi-vendor service orchestration, compressing average contract values while expanding total addressable spend.
Back Office Outsourcing Market Segmentation
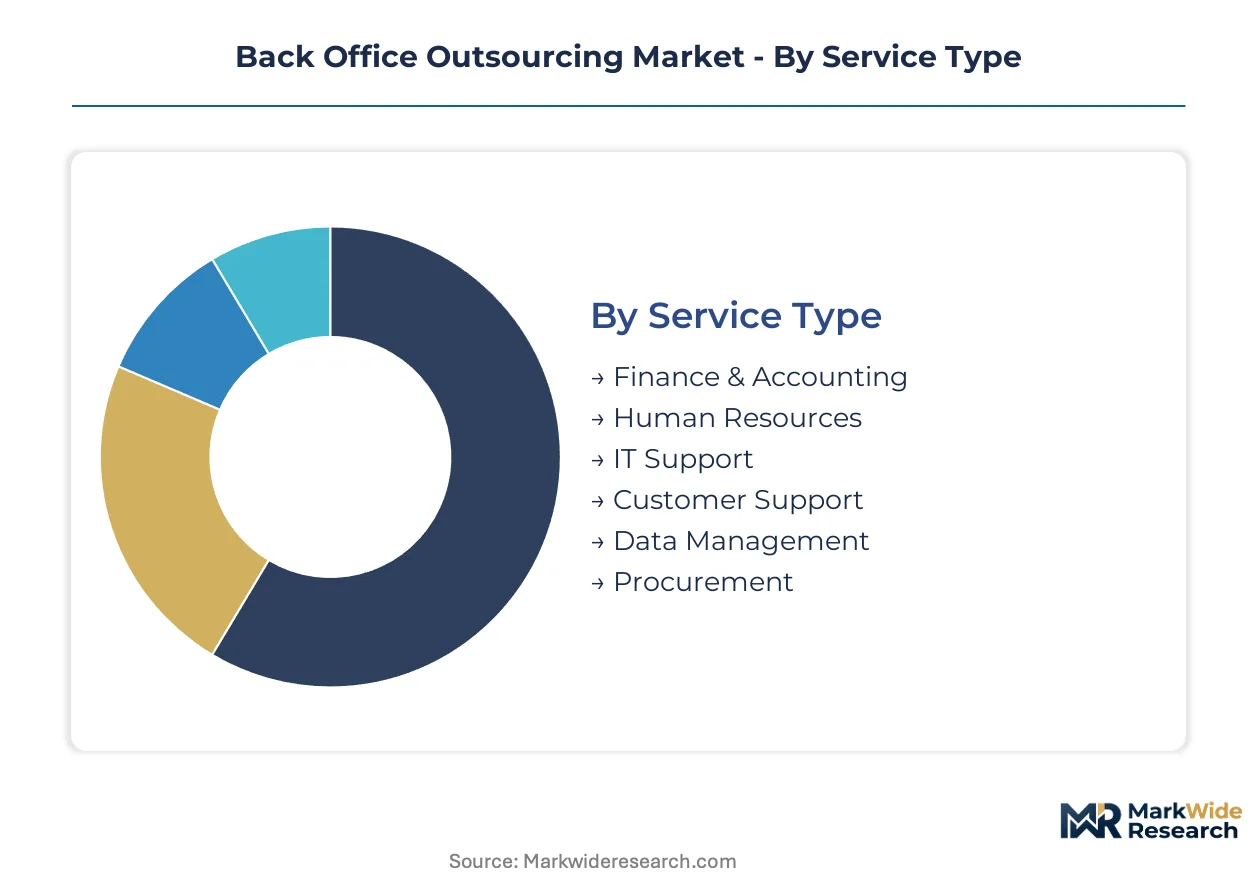
Segmentation in back office outsourcing reveals how compliance requirements and process complexity fragment service demand across buyer profiles. Regulatory mandates from the SEC, RBI, and GDPR reshape contract structures differently for each segment, forcing providers to specialize rather than generalize.
Service Type:
SEC financial reporting controls and India's RBI data localization rules create divergent compliance burdens across service categories, with GDPR adding cross-border friction for EU-facing operations.
- Finance & Accounting:Complex regulatory reporting requirements including US GAAP, IFRS, and SOX compliance drive demand for certified accountants. US hospital systems facing ICD-10 billing mandates outsource end-to-end revenue management to specialized providers in India and the Philippines.
- IT Support:Cloud migration and legacy ERP integration dominate contract scopes. RBI data localization requirements force redundant infrastructure investments in India, inflating contract minimums while compressing delivery timelines through AI-enabled automation.
- Human Resources:GDPR restrictions on cross-border personal data flows compel European delivery infrastructure buildout in Germany, Poland, and Ireland.
- Customer Support:High-volume voice contracts face margin compression from Philippines wage inflation and AI-augmented delivery models.
- Data Management:Machine learning systems trained on enterprise ERP data automate invoice matching and reconciliation at throughput rates that reshape staffing ratios.
- Procurement:REACH chemical substance registration requirements in the EU mandate supply chain traceability documentation, shifting provider selection to liability coverage depth.
Finance & Accounting handles the majority of throughput; IT Support is expanding most quickly on share.
Industry Vertical:
Vertical-specific regulatory density determines outsourcing penetration rates, with financial services and healthcare leading due to mandated control frameworks.
- Banking:Basel III capital adequacy reporting and anti-money laundering compliance create sustained demand for finance and accounting outsourcing. Indian providers capture significant contract flow from US and European banks seeking cost arbitrage.
- Telecommunications:FCC consumer protection mandates and complex billing system migrations drive IT support and customer service outsourcing to Philippines-based operations.
- Insurance:State-level regulatory fragmentation in the US increases compliance costs, favoring specialized providers with multi-jurisdictional expertise.
- Travel & Hospitality:Seasonal demand volatility pushes firms toward flexible engagement models and project-based procurement outsourcing.
- Education:Federal student aid administration and accreditation reporting create niche demand for finance and accounting specialists.
- Manufacturing:REACH compliance and supply chain finance complexity favor procurement outsourcing specialists serving mid-market firms with 500-5,000 employees.
Banking commands the largest contract values; Manufacturing is climbing the fastest as REACH and supply chain finance requirements deepen.
Client Type:
Scale determines access to tier-one provider capabilities and pricing power, with mid-market buyers facing the widest service gaps.
- Large Enterprises:Complex multi-entity structures and SAP/Oracle system migrations require 18-24 month implementation timelines. These buyers unbundle after-sales support into separate tier-one, tier-two, and knowledge base contracts.
- Small & Medium Enterprises:Remain underserved by tier-one providers, creating white space for procurement and supply chain finance specialists. ISO 27001 certification arbitrage accelerates competitive displacement of uncertified regional players.
- Startups:Prioritize flexible time-and-material arrangements and dedicated team models that preserve operational agility.
- Government Agencies:HIPAA Business Associate Agreement complexity extends legal review cycles to 4-6 months, compressing sales velocity and inflating customer acquisition costs.
Large Enterprises anchor provider revenue; Small & Medium Enterprises are gaining attention fastest as tier-one players build down-market capabilities.
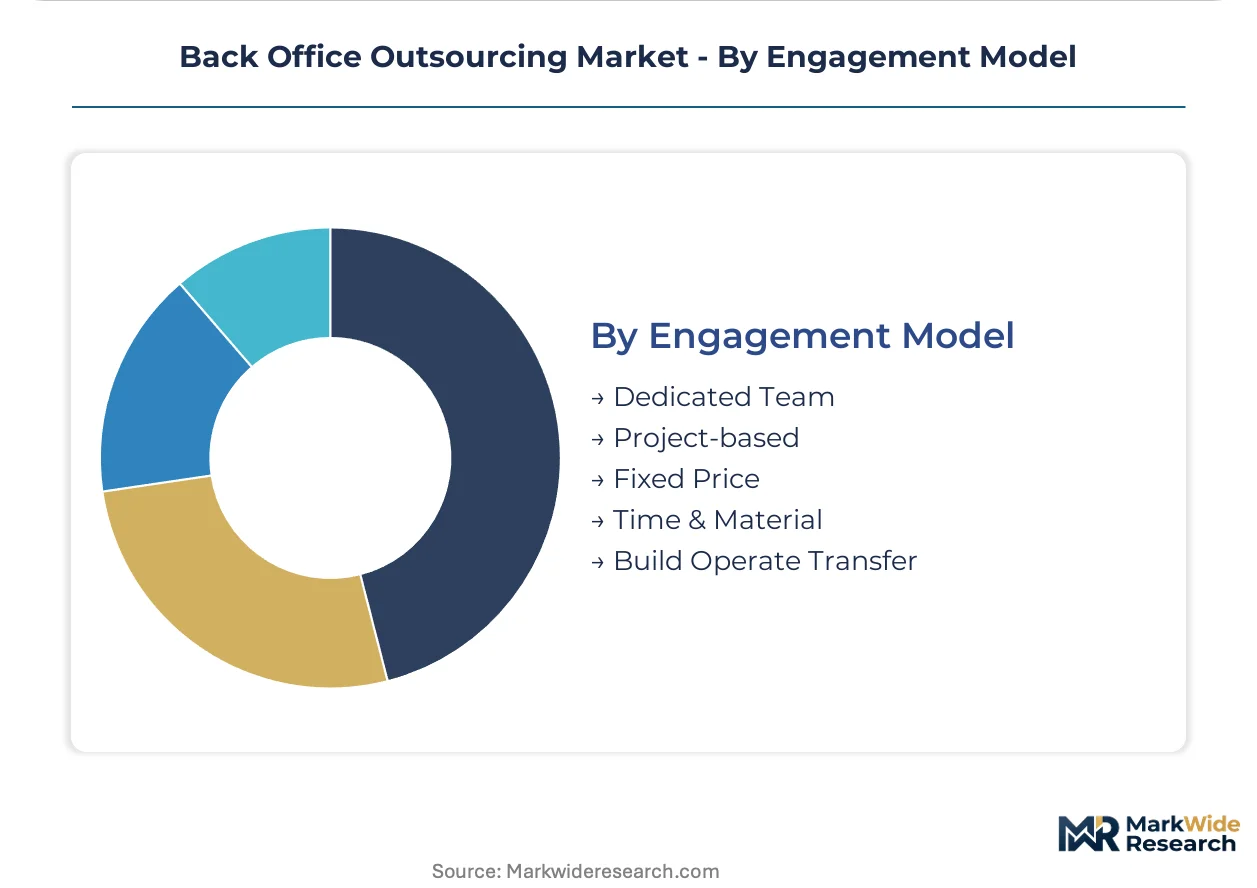
Engagement Model:
Contract structures embed compliance costs directly into pricing models as regulatory mandates fragment risk allocation between buyer and provider.
- Dedicated Team:Cloudstaff and similar providers anchor competitive positioning through extended client control over remote finance and accounting functions. This model captures premium pricing for HIPAA and GDPR-sensitive operations.
- Build Operate Transfer:RBI data localization requirements and captive center mandates in India drive adoption for IT support and data management, despite longer payback periods.
- Project-based:Fits legacy ERP migration and cloud transition initiatives with defined endpoints and automation ROI targets.
- Fixed Price:Compresses margins in mature categories like customer support, pushing providers toward AI-augmented delivery.
- Time & Material:Preferred for generative AI document processing pilots where throughput rates and staffing ratios remain uncertain.
Dedicated Team structures dominate current contract flow; Build Operate Transfer is accelerating fastest as data localization mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States deploy back office outsourcing primarily for healthcare revenue cycle and SEC-compliant finance functions, while European purchasers prioritize GDPR-constrained HR and data operations, and Indian enterprises favor domestic IT support with RBI-mandated localization.
United States
US hospital systems facing ICD-10 billing complexity and prior authorization automation drive demand for healthcare revenue cycle outsourcing. SEC financial reporting controls under SOX mandate specialized finance and accounting arrangements. Delivery concentrates in India and Philippines-based centers serving North American buyers.
Germany
German automotive and industrial chemical buyers require procurement outsourcing with embedded REACH compliance verification. The EU's GDPR framework restricts cross-border personal data flows, compelling providers to establish captive delivery infrastructure. Frankfurt and Berlin host expanding finance and accounting service centers.
India
RBI data localization requirements force redundant infrastructure investments that inflate IT support and data management contract minimums. SEBI compliance mandates shape finance and accounting outsourcing structures for domestic banking clients. Bangalore and Hyderabad concentrate US GAAP and IFRS-trained professionals.
Philippines
Manila-based operations sustain high-volume customer support contracts for North American technology and telecommunications buyers. Labor cost inflation of 40% since 2019 erodes historical cost arbitrage. Cebu and Davao emerge as alternative delivery locations.
United Kingdom
UK financial services firms unbundle after-sales support into separate tier-one, tier-two, and knowledge base contracts. FCA regulatory requirements intersect with GDPR data handling constraints. London procurement functions mature toward multi-vendor service orchestration.
Back Office Outsourcing Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the market fragmenting across service-type verticals rather than consolidating around full-stack providers. Scale advantages concentrate in finance and accounting outsourcing where certified talent scarcity creates barriers, while IT support and customer service segments permit mid-market entry. Three archetypes dominate: Philippines-anchored high-volume customer support operators, India-based compliance-heavy finance and technology providers, and mid-market manufacturing specialists. Competitive moves center on ISO 27001 certification acquisition for vendor consolidation mandates and generative AI capability integration for document processing automation.
Within the Philippines-based high-volume tier, TaskUs exemplifies the customer support archetype serving technology clients, while Cloudstaff occupies a position emphasizing dedicated team models for remote finance functions. Among mid-market manufacturing specialists, GigaBPO represents procurement and data management service concentration.
| Leading Market Players |
|---|
| GigaBPO |
| Virtual Coworker |
| TaskUs |
| SupportYourApp |
| Big Outsource |
| Unity Communications |
| Cloudstaff |
| Fresa Technologies |
| TECHSPEED INC |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization in India-based delivery centers drives cost floors across finance and accounting outsourcing, with Bangalore and Hyderabad talent scarcity compressing margins for uncertified providers while embedding compliance premiums into GDPR-constrained European contracts.
Pricing Analysis
Long-term dedicated team contracts dominate healthcare and banking verticals, embedding HIPAA and SOX compliance costs directly into annual pricing. Three-tier pricing structure across premium certified, standard compliance-ready, and economy transactional tiers differentiates providers, with ISO 27001 certification commanding material premiums. Cost compression in Philippine customer support intensifies because Manila wage inflation erodes historical arbitrage. Small and medium enterprises exhibit highest price sensitivity, while large enterprises with captive center mandates absorb compliance-embedded premiums.
Supply Chain Analysis
Eighteen-month talent onboarding cycles in tier-two Indian cities constrain rapid capacity scaling for US GAAP-trained accountants. Delivery infrastructure draws from India, Philippines, and Poland as primary nodes, with cloud computing licenses, ERP system access, and certified labor pools anchoring cost structures. Single-source vulnerability concentrates in Bangalore-Hyderabad accounting talent corridors. Distribution runs through direct enterprise sales teams and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative AI document processing threatens incumbent finance and accounting providers with automation-driven displacement, forcing substitution defense through advisory service expansion and compliance-embedded pricing power.
For Market Incumbents: Consolidate around ISO 27001-certified delivery footprints to capture vendor consolidation mandates from risk-averse buyers. Acquire generative AI capabilities for invoice matching and exception handling automation before mid-market specialists replicate the technology stack. Defend against Cloudstaff and TaskUs expansion by embedding regulatory compliance verification directly into procurement outsourcing scopes.
For New Entrants and Emerging Players: Anchor in US mid-market manufacturing firms with 500-5,000 employees, where tier-one provider coverage gaps persist. Target REACH compliance-embedded procurement services for German automotive and chemical buyers seeking liability coverage depth. Pursue dedicated team models with flexible time-and-material pilots to bypass lengthy HIPAA Business Associate Agreement negotiations.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among India-based finance and accounting providers with captive healthcare banking relationships and multi-year SOX compliance mandates. Long-term viability hinges on automation-to-advisory ratio improvement and European GDPR-constrained infrastructure ownership. Monitor generative AI throughput rates in invoice processing as the inflection signal for staffing ratio compression and margin expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 27001 Certification Acquisition | Accelerates competitive displacement of uncertified regional players under vendor consolidation mandates. |
| Generative AI Capability Integration | Enables 98% accuracy in invoice data extraction while reshaping finance operations staffing ratios. |
| European Captive Center Buildout | Captures GDPR-constrained HR and data management contracts through compliance-embedded pricing. |
| Mid-Market Manufacturing Penetration | Addresses underserved 500-5,000 employee segment with procurement and supply chain finance specialization. |
| Healthcare Revenue Cycle Expansion | Locks in multi-year contracts with US hospital systems facing ICD-10 billing complexity. |
Research Methodology
A spread of perspectives from CFOs at mid-market manufacturing firms, procurement directors at German automotive OEMs, compliance officers at US hospital systems, and delivery center heads in Bangalore converged on the working assumptions. Primary interviews with these stakeholders combined with secondary validation from SEC filings, RBI regulatory circulars, EU REACH substance databases, and ISO certification registries. Bottom-up contract value aggregation and top-down market sizing triangulation anchored the analytical framework.
Segmentation dimensions modeled span service type, industry vertical, client scale tier, and engagement model structure across the projection horizon. CAGRs derived from historical contract flow analysis and automation adoption curve assumptions. Cloud migration timelines and generative AI throughput benchmarks informed IT support and data management trajectory inputs.
Decision-makers should treat outputs as directional under sustained regulatory enforcement of GDPR, RBI data localization, and SEC financial reporting controls; material deviation in compliance cost absorption or automation adoption velocity would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
IT Outsourcing Market
Business Process Outsourcing (BPO)
Global Service Procurement Market
Business Process Outsourcing (BPO)
Europe Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Global Software Outsourcing Market
Business Process Outsourcing (BPO)
US Managed Print Services Market
Business Process Outsourcing (BPO)
Payroll Outsourcing Services Market
Business Process Outsourcing (BPO)
Front Office BPO Services Market
Business Process Outsourcing (BPO)
Service Bureau Market
Business Process Outsourcing (BPO)
Recruitment Process Outsourcing (RPO) Services Market
Business Process Outsourcing (BPO)
Labor Outsourcing Service Market
Business Process Outsourcing (BPO)
Business Process As a Service (Bpaas) Market
Business Process Outsourcing (BPO)
Global Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Direct to Customer Outsourced Fulfillment Market
Business Process Outsourcing (BPO)
Global Contact and Call Center Outsourcing Market
Business Process Outsourcing (BPO)
Business Process Re-Engineering Market
Business Process Outsourcing (BPO)
Global Telecom Outsourcing Market