
 North America Business Process Outsourcing (BPO) Market | 2026-2036
North America Business Process Outsourcing (BPO) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Business Process Outsourcing (BPO) Market Analytics
Healthcare payer outsourcing is hardening as the dominant growth vertical across the North America BPO landscape. Genpact leverages its domain expertise in healthcare claims management to anchor long-term contracts with major insurers. TTEC sustains competitive positioning through specialized customer experience platforms tailored to regulated industries. Accenture differentiates via AI-infused process automation layered across finance and accounting engagements.
Business Process Outsourcing (BPO) denotes the contractual delegation of specific operational functions—such as customer interaction management, payroll administration, accounts payable processing, or technical helpdesk operations—to external service providers, typically governed by service-level agreements specifying response times, accuracy thresholds, and compliance protocols. Its primary commercial purpose is to reduce fixed cost structures while accessing specialized process expertise and scalable labor pools. Customer Support occupies the largest revenue share within service type segmentation due to perpetual demand for 24/7 multilingual engagement channels. Cloud-Based delivery is expanding fastest as enterprises retire legacy on-premises infrastructure in favor of elastic, API-connected platforms. Onshore engagement models retain premium pricing power in Financial Services, where data sovereignty requirements and regulatory scrutiny limit offshore migration.
HIPAA, the Sarbanes-Oxley Act (SOX), and the Gramm-Leach-Bliley Act (GLBA) collectively shape compliance burdens that filter vendor eligibility and inflate contract values for qualified providers. The US Federal Trade Commission (FTC) and state-level insurance commissioners enforce consumer protection standards that penetrate contract terms and audit frequencies. Stakeholders must monitor evolving state privacy legislation—particularly California's CPRA and emerging frameworks in Virginia and Colorado—as these patchwork requirements will reshape data localization strategies and vendor certification protocols.
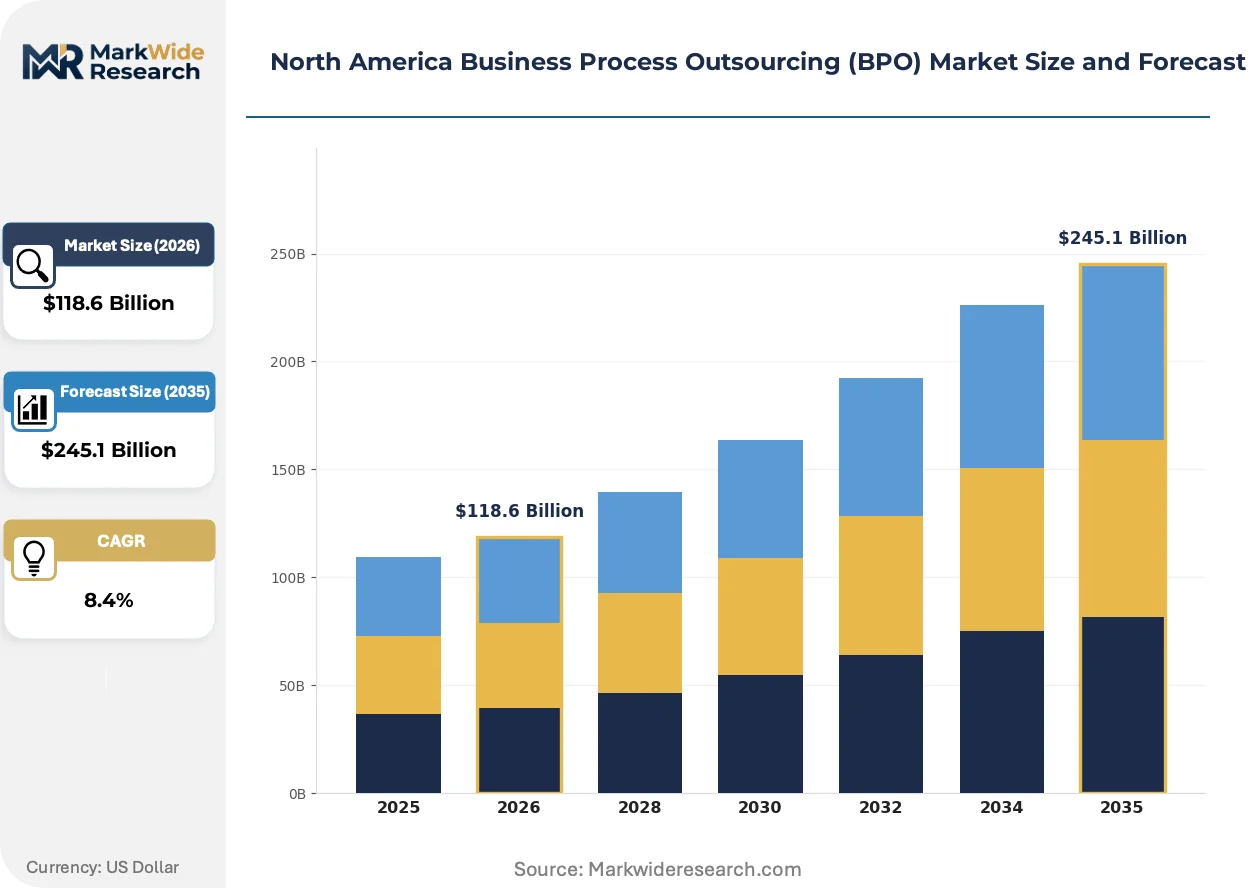
Market Dynamics
HIPAA's tightening data-handling requirements are compressing vendor eligibility pools and inflating certification costs for BPO providers serving US healthcare payers, forcing consolidation around specialized compliance architectures.
Growth Catalysts
- Healthcare Claims Automation:US insurers are expanding third-party processing contracts to reduce administrative overhead and accelerate adjudication cycles. Patient engagement outsourcing follows claims volume growth.
- State Tax Incentives:Southeastern US states including Georgia and North Carolina offer payroll tax credits and infrastructure grants that attract large-scale delivery center investments from BPO operators.
- HIPAA Certification Premium:Certified BPO partners command expanded contract scopes as HIPAA's Security Rule tightens technical safeguard requirements for protected health information handling.
Market Restraints
- Labor Cost Escalation:Wage inflation in US metropolitan delivery hubs compresses margin structures for voice-based customer support operations.
- Data Localization Mandates:State-level privacy legislation in California, Virginia, and Colorado fragments compliance architectures and restricts cross-border data flows.
- Legacy System Integration:Onshore financial services clients maintain proprietary core banking platforms that resist API-based modernization, extending implementation timelines.
Strategic Opportunities
- AI-Infused Process Automation:Machine learning layered across finance and accounting engagements enables outcome-based pricing models and expands addressable contract value.
- Mexican Nearshore Expansion:Bilingual delivery centers in Guadalajara and Monterrey offer US timezone alignment with labor cost arbitrage for voice and back-office functions.
- CPRA Compliance Services:California's privacy framework creates specialized advisory and technical implementation revenue streams for certified BPO providers.
Industry Challenges
- Specialized Talent Scarcity:Healthcare claims adjudication requires certified medical coders and HIPAA-trained analysts, creating recruitment bottlenecks in competitive labor markets.
- Multi-State Certification Burden:BPO operators must maintain separate compliance protocols for California's CPRA, Colorado's CPA, and Virginia's CDPA, fragmenting operational standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Business Process Outsourcing (BPO) Market |
| Market Size in 2026 | $118.6 Billion |
| Market Size in 2035 | $245.1 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Customer Support, Human Resources, Finance & Accounting, IT Services Industry Vertical: Healthcare, Retail, Telecommunications, Financial Services Engagement Model: Onshore, Offshore, Nearshore, Hybrid Delivery Method: Cloud-Based, On-Premises, Managed Services, Dedicated Services |
| Companies Covered | Genpact, TTEC, Insignia Resources, HGS, TCS, Accenture, Concentrix, Foundever, Teleperformance, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Business Process Outsourcing (BPO) Market Evolving Landscape
Cloud-native delivery architectures are overtaking legacy on-premises infrastructure as enterprises prioritize elastic capacity and API-connected ecosystem integration over fixed-cost data center commitments.
Intelligent process automation platforms are overtaking rules-based robotic process automation in US healthcare payer engagements. Machine learning models trained on historical claims patterns now handle complex exception routing and fraud detection. Major insurers are deploying these tools to compress adjudication cycles and reduce manual intervention rates.
The FTC's intensified scrutiny of consumer data practices is reshaping contract audit frequencies and technical safeguard specifications across financial services BPO engagements. Service-level agreements now embed explicit breach notification timelines and third-party penetration testing mandates. Vendors serving banking and insurance clients are restructuring security operations centers to meet these prescriptive requirements.
Outcome-based commercial structures are displacing traditional per-seat or per-transaction pricing in mature BPO relationships. Enterprise buyers in the US Southeast are tying vendor compensation to measurable cost reduction or customer satisfaction metrics. This shift concentrates contract awards with providers demonstrating domain expertise and performance analytics capabilities rather than pure labor arbitrage.
North America Business Process Outsourcing (BPO) Market Segmentation
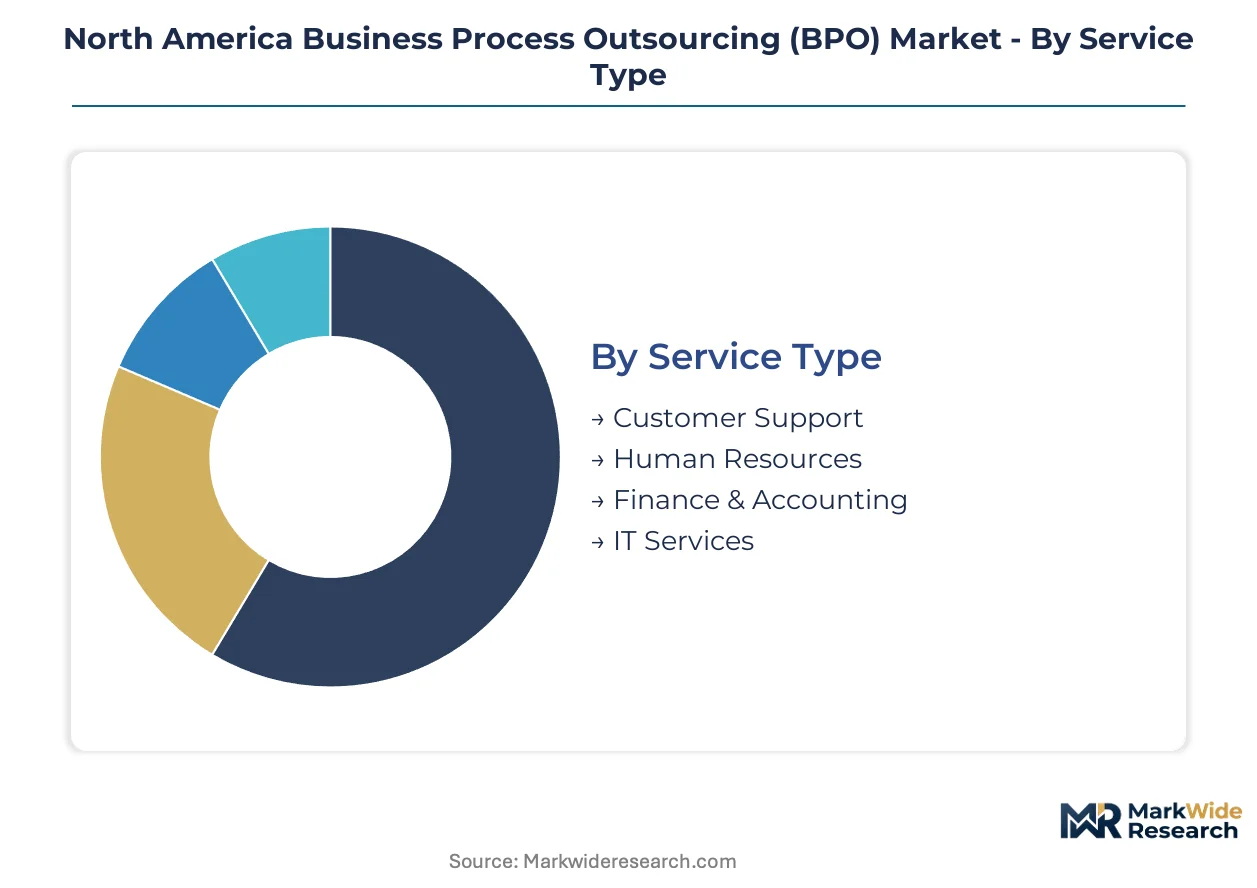
Segmentation in North American BPO reveals how compliance architecture, labor geography, and infrastructure maturity partition contract value. Buyers select service bundles based on regulatory exposure, cost structure, and legacy system constraints rather than functional requirements alone.
Service Type:
Volume concentration sits with voice-based functions while premium pricing attaches to specialized technical and financial processes.
- Customer Support:Multilingual voice, chat, and email channels handling billing inquiries, product troubleshooting, and account management for US and Canadian consumers. Demand clusters in US Southeast delivery centers where state payroll tax credits reduce operational overhead for high-volume operations.
- Finance & Accounting:Accounts payable processing, general ledger management, financial planning and analysis, and regulatory reporting. HIPAA and SOX compliance requirements concentrate contract awards with certified providers serving healthcare payers and publicly traded enterprises.
- Human Resources:Payroll administration, benefits enrollment, and talent acquisition support spanning multi-state employer populations.
- IT Services:Service desk operations, application maintenance, and infrastructure monitoring delivered through ticket-based workflows.
Mature deployment sits with Customer Support. Newer deployment is concentrated in Finance & Accounting.
Industry Vertical:
Healthcare commands compliance premiums while retail competes on cost efficiency and scale velocity.
- Healthcare:Claims processing, patient engagement, revenue cycle management, and prior authorization workflows for US insurers and hospital systems. HIPAA Security Rule enforcement drives consolidation toward BPO partners with certified technical safeguards and audit-ready documentation.
- Financial Services:Mortgage processing, credit card servicing, fraud detection, and regulatory reporting for US banks and insurers. Gramm-Leach-Bliley Act privacy provisions and FTC examination protocols restrict offshore data flows and inflate onshore contract values.
- Telecommunications:Subscriber acquisition, retention campaigns, and technical support for wireless and broadband providers.
- Retail:Order management, returns processing, and loyalty program administration for omnichannel merchants.
Established contract structures dominate Healthcare. Steepest expansion trajectory is visible in Financial Services automation.
Engagement Model:
Geographic labor arbitrage defines cost tiers while regulatory exposure determines model selection.
- Onshore:US and Canadian-based delivery with full regulatory compliance and native language capabilities. Financial services and healthcare payers mandate onshore processing for sensitive data under HIPAA, SOX, and state privacy laws.
- Nearshore:Mexican and Canadian delivery centers offering US timezone alignment with moderate labor cost reduction. Guadalajara and Monterrey clusters serve bilingual voice and back-office functions for US enterprises.
- Offshore:Delivery from outside North America, largely constrained by data localization mandates in California, Virginia, and Colorado.
- Hybrid:Multi-location deployment combining onshore compliance hubs with nearshore scale operations.
Contract maturity concentrates in Onshore engagements. Hybrid architectures are gaining share fastest among mid-market buyers.
Delivery Method:
Cloud migration separates growth investments from legacy maintenance spend.
- Cloud-Based:Elastic, API-connected platforms enabling rapid capacity scaling and ecosystem integration. US enterprises retiring on-premises infrastructure drive fastest expansion in this category.
- Managed Services:Comprehensive outsourcing of function ownership with outcome-based accountability and SLA-driven governance.
- On-Premises:Client-hosted infrastructure maintained for proprietary core banking and legacy claims platforms resisting modernization.
- Dedicated Services:Exclusive team allocation for single-client operations with customized process flows.
Legacy retention persists in On-Premises. Cloud-Based deployment represents the fastest-growing trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southeastern US tax-incentive zones concentrate BPO delivery center investments, with Georgia and North Carolina payroll credits attracting large-scale operations from major operators seeking cost-efficient onshore capacity.
United States
Healthcare payers drive dominant demand through third-party claims processing and patient engagement outsourcing. HIPAA Security Rule enforcement tightens vendor certification requirements and compresses eligible supplier pools. Atlanta and Charlotte anchor major delivery clusters where state infrastructure grants support multi-thousand-seat operations.
Canada
Financial services institutions mandate onshore processing for sensitive data under federal privacy legislation. Health Canada and PMRA oversight extends to pharmaceutical customer service operations requiring compliant handling. Toronto and Vancouver concentrate bilingual delivery capacity serving US and domestic banking clients.
Mexico
Bilingual voice and back-office functions expand in Guadalajara and Monterrey to capture US timezone alignment with labor cost advantages. Nearshore delivery grows for customer support and technical helpdesk operations. Mexican federal economic development programs incentivize delivery center investments in these metropolitan clusters.
North America Business Process Outsourcing (BPO) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with healthcare compliance requirements concentrating awards around certified providers while cost-sensitive retail functions fragment across price-competitive tiers. The vendor landscape organizes around three archetypes: global consultancies with automation platforms, healthcare-specialized operators with HIPAA architectures, and scale-driven customer experience providers. Consolidation pressures intensify as certification costs rise and enterprise buyers reduce supplier counts. Strategic moves center on AI capability acquisitions and Mexican nearshore capacity expansion.
Among the healthcare-specialized tier, Genpact anchors long-term insurer relationships through claims management domain expertise. TTEC occupies a position serving regulated industries with tailored customer experience infrastructure. Accenture exemplifies the automation-integrated consultancy archetype, layering machine learning across finance and accounting engagements.
| Leading Market Players |
|---|
| Genpact |
| TTEC |
| Insignia Resources |
| HGS |
| TCS |
| Accenture |
| Concentrix |
| Foundever |
| Teleperformance |
| Others |
Value Network & Pricing Analysis
HIPAA Security Rule compliance gates both qualified supply and premium-tier pricing access, as certified BPO providers command expanded contract scopes while uncertified operators face exclusion from healthcare payer RFPs. This regulatory filter concentrates pricing power among architecture holders and fragments the vendor base into compliance-tiered segments.
Pricing Analysis
Lead-time-driven pricing angles dominate contract structures, with premium rates attaching to rapid-deployment engagements and spot capacity availability while longer-committed volumes secure discounted rate cards. Three-tier pricing structure across premium, standard, and economy levels stratifies by HIPAA certification grade, domain specialization depth, and geographic delivery cost. Cost compression in voice-based customer support intensifies because wage inflation in US metropolitan hubs erodes margin structures. Retail and telecommunications buyers exhibit highest price sensitivity, while financial services and healthcare payers prioritize compliance assurance over rate minimization.
Supply Chain Analysis
Specialized talent supply rests on US-based medical coder training pipelines and HIPAA-certified analyst development programs concentrated in Georgia, North Carolina, and Texas delivery clusters. Labor inputs draw from community college partnerships, veterans transition programs, and bilingual workforce development initiatives in Guadalajara and Monterrey. Single-source vulnerability attaches to certified compliance architecture providers, as few vendors maintain simultaneous HIPAA, SOX, and state privacy law certifications. Distribution runs through direct enterprise sales teams and channel partners serving mid-market buyers with standardized service bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race, with automation capability acquisition and Mexican nearshore capacity buildout representing the decisive upstream and downstream levers players are pursuing to defend margin structures.
For Market Incumbents: Deploy AI-infused process automation platforms to compress delivery costs and enable outcome-based pricing models that emerging cloud-native competitors cannot match. Consolidate around specialized compliance architectures as HIPAA certification costs rise and enterprise buyers reduce supplier counts. Channel control through exclusive partnerships with major US insurers locks out challengers lacking claims management domain expertise. For New Entrants and Emerging Players: Capture mid-market hybrid engagement demand where buyers seek onshore compliance hubs paired with nearshore scale operations, a segment underserved by pure-play global consultancies. White-space concentration sits with CPRA compliance advisory services and technical implementation for California-headquartered enterprises navigating fragmented state privacy legislation. Go-to-market leverage rests on API-native platform positioning that accelerates legacy system integration timelines. For Investors and Strategic Acquirers: Mexican nearshore capacity announcements from established operators is the leading indicator that labor arbitrage strategies are shifting toward timezone-aligned delivery models with lower wage structures. Long-term viability favors healthcare-specialized operators with embedded insurer relationships and certified technical safeguards over scale-driven customer experience providers facing commoditization pressure. Acquisition target archetype: mid-tier HIPAA-certified BPOs with underutilized delivery center infrastructure in US Southeast tax-incentive zones.| Strategic Initiative | Industry Significance |
|---|---|
| AI Platform Integration | Machine learning deployment across finance and accounting engagements enables outcome-based contract structures. |
| Mexican Nearshore Expansion | Guadalajara and Monterrey delivery centers capture US timezone alignment with labor cost advantages. |
| HIPAA Certification Investment | Security Rule compliance architecture opens healthcare payer contracts with expanded scope and premium pricing. |
| Strategic Partnership | Exclusive relationships with major US insurers lock in long-term claims processing volume commitments. |
| Geographic Expansion | US Southeast delivery center investments leverage Georgia and North Carolina payroll tax credits. |
Research Methodology
Multi-period observation of HIPAA enforcement patterns, state privacy legislation adoption timelines, and delivery center investment flows anchored the trend analysis, supplemented by interviews with BPO operations executives, healthcare payer procurement directors, compliance officers, and Mexican economic development officials. Secondary validation drew from SEC 10-K filings, state tax incentive program disclosures, CMS Medicare administrative data, and industry association workforce reports. Bottom-up contract value estimates triangulated against top-down market sizing from delivery center seat capacity and average revenue per seat metrics.
Input-output matrix framing structured the analytical approach, modeling service type, industry vertical, engagement model, and delivery method dimensions across the projection horizon. CAGRs derived from segment-level growth rate assumptions calibrated to historical contract award velocity and automation adoption curves. Forecast inputs incorporated healthcare claims volume growth, cloud migration spend patterns, and state-level data localization mandate expansion.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to HIPAA rulemaking shifts, multi-state privacy law fragmentation, and AI automation disruption timelines. Assumptions underlying projections reflect current regulatory trajectories and technology adoption curves. A small set of named triggers—FTC enforcement intensity, Mexican labor cost trends, and cloud platform consolidation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Technical Support Outsourcing Market
Business Process Outsourcing (BPO)
Recruitment Process Outsourcing (RPO) Services Market
Business Process Outsourcing (BPO)
Global Supply Chain Management BPO Market
Business Process Outsourcing (BPO)
Global Application Outsourcing Market
Business Process Outsourcing (BPO)
IT Outsourcing Market
Business Process Outsourcing (BPO)
Global Software Outsourcing Market
Business Process Outsourcing (BPO)
Business Processing Outsourcing Market
Business Process Outsourcing (BPO)
UAE Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Payroll Outsourcing Services Market
Business Process Outsourcing (BPO)
Healthcare Supply Chain BPO Market
Business Process Outsourcing (BPO)
Europe Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Asia-Pacific Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Employment Screening Services Market
Business Process Outsourcing (BPO)
Data Entry Service Market
Business Process Outsourcing (BPO)
Automotive Business Process Management Market
Business Process Outsourcing (BPO)
Indonesia Business Process Outsourcing Services Market