
 Global Software Outsourcing Market | 2026-2036
Global Software Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Software Outsourcing Market Outlook
The EU AI Act is rebalancing compliance burdens for vendors serving European clients, forcing investment in algorithmic audit capabilities and localized data infrastructure. Accenture leverages its European regulatory consulting heritage to anchor premium engagements. EPAM Systems specializes in engineering-intensive verticals, sustaining margin pools that generic application maintenance cannot match. Tata Consultancy Services dominates volume-driven enterprise transformation programs across North American and British banking clients.
Global software outsourcing encompasses the contractual delegation of software engineering, quality assurance, and systems integration to external providers, typically delivered through distributed agile teams, dedicated development centers, or staff augmentation models with defined SLAs for code quality, security compliance, and delivery velocity. Its commercial purpose centers on accessing specialized talent pools, compressing development cycles, and converting fixed labor costs into variable operational expenditure. Application development and maintenance commands the largest revenue share within service type segmentation, while cloud deployment models are displacing on-premises delivery as enterprises mandate API-first architecture and containerized infrastructure. Healthcare and BFSI verticals generate the highest contract values due to regulatory complexity and data sensitivity, though retail telecommunications represents the fastest expansion path as omnichannel digital transformation accelerates.
FDA cybersecurity guidance for medical device software, HIPAA data handling protocols, and India's BIS cloud standards collectively shape vendor qualification requirements and contract liability structures across key delivery corridors. The EU AI Act and GDPR enforcement actions are tightening audit obligations for algorithmic systems processed outside member states, redirecting some European demand toward providers with certified EU-based operations. Stakeholders must monitor evolving cross-border data governance frameworks and assess whether their delivery footprint aligns with emerging sovereignty requirements before committing to multi-year engagement structures.
Market Dynamics
Cloud migration mandates from EU regulators and India's data localization rules are forcing vendors to rearchitect delivery footprints, splitting workloads across sovereign infrastructure zones rather than consolidating in traditional offshore hubs.
Growth Catalysts
- EU AI Act compliance:European financial services firms require algorithmic audit capabilities, creating premium service tiers for vendors with certified EU-based operations and localized data infrastructure.
- Containerized microservices:Enterprise API-first architecture mandates are compressing development cycles and expanding contracts for Kubernetes-native engineering teams.
- Poland:Nearshore delivery centers in Warsaw and Kraków capture redirected demand from German automotive and banking clients seeking timezone alignment without Asian latency.
Market Restraints
- Engineering wage inflation:Senior full-stack and DevOps talent costs in Vietnam and Mexico are rising faster than contract rate adjustments can absorb.
- Cross-border data friction:India's BIS cloud standards and EU GDPR enforcement actions impose redundant compliance layers on multi-territory engagements.
- Low-code platforms:Microsoft Power Platform and Salesforce Lightning are capturing internal workflow automation demand previously outsourced to custom development shops.
Strategic Opportunities
- Brazilian fintech:Central Bank of Brazil's open banking mandate and PIX instant payment infrastructure create unmet demand for regulatory-compliant engineering capacity.
- Edge-AI convergence:Medical device manufacturers need firmware-to-cloud pipelines combining embedded systems expertise with MLOps deployment capabilities.
- Japan METI digital transformation subsidies:SME manufacturing modernization programs fund vendor selection for legacy ERP replacement and shop-floor IoT integration.
Industry Challenges
- Embedded systems security certification:FDA cybersecurity guidance for connected medical devices extends qualification timelines by 8-14 months for vendors without prior healthcare compliance track records.
- Fractional CTO talent scarcity:Mid-market enterprises struggle to source technical leadership capable of orchestrating multi-vendor agile teams across three or more timezones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Software Outsourcing Market |
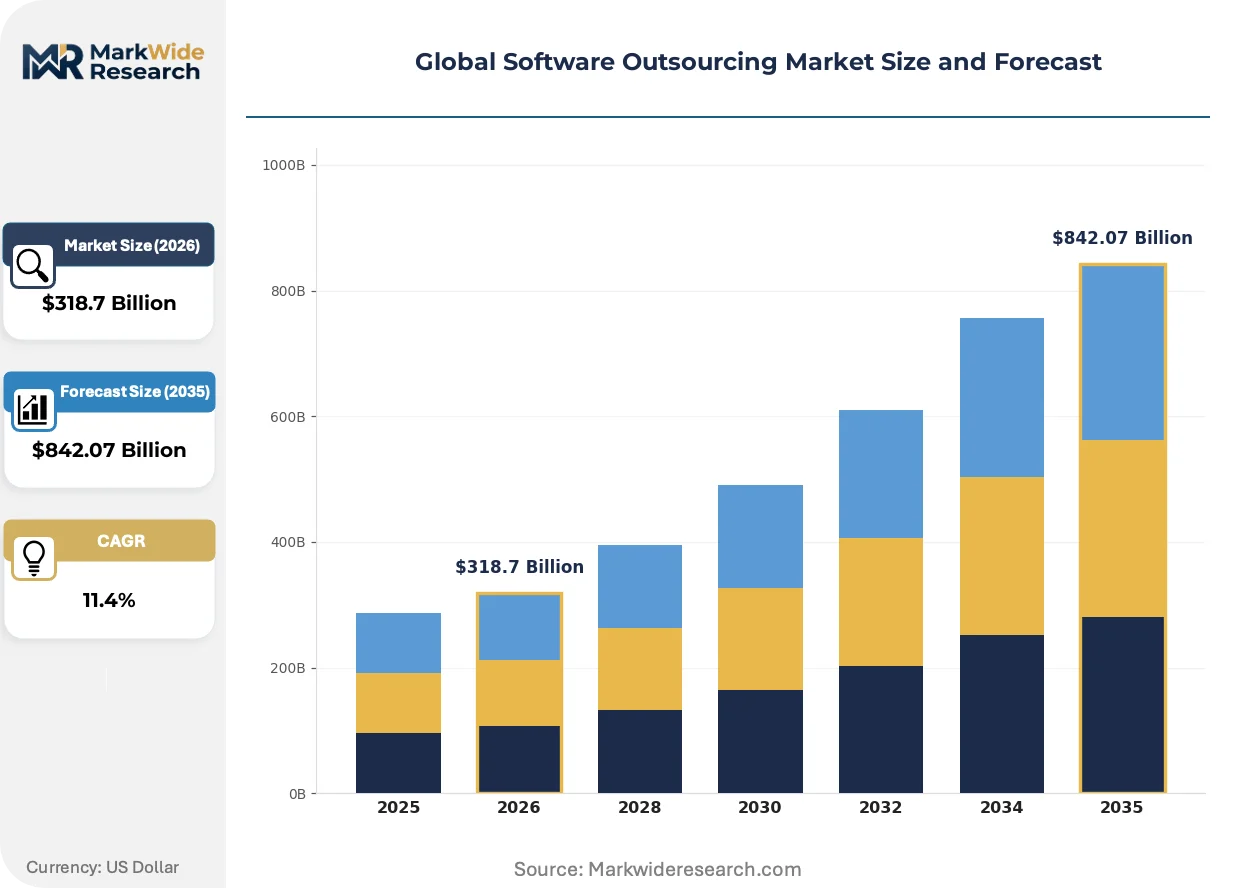
| Market Size in 2026 | $318.7 Billion |
| Market Size in 2035 | $842.07 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Application Development, Maintenance, Testing, Support Deployment Model: On-Premises, Cloud, Hybrid, Remote Industry Vertical: Healthcare, BFSI, Retail, Telecommunications Client Type: SMEs, Large Enterprises, Startups, Government |
| Companies Covered | Wipro, HCLTech, Accenture, Cognizant, Capgemini, Tata Consultancy Services (TCS), EPAM Systems, N-iX, Infosys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Software Outsourcing Market Strategic Shifts
Generative coding assistants and sovereign cloud requirements are fragmenting traditional delivery models, compressing the gap between specification and deployment while mandating geographically distributed infrastructure.
GitHub Copilot and Amazon CodeWhisperer are decentralizing routine coding tasks from dedicated offshore teams toward embedded engineer-augmentation models. Fortune 500 technology departments now deploy these tools across 60-70% of active repositories. This compression is reducing headcount-dependent margin structures and forcing pure-play staff augmentation vendors toward higher-skill advisory positioning.
The EU AI Act's risk-based classification system for algorithmic systems is mandating conformity assessments and technical documentation audits for vendors serving European healthcare and financial clients. Providers without established EU legal entities face procurement exclusion. German automotive OEMs and French insurance groups now require contractual liability clauses covering algorithmic bias and explainability failures.
Enterprise buyers are unbundling monolithic transformation contracts into componentized statement-of-work engagements with 90-day renewal cycles. This fragmentation favors vendors with demonstrated vertical expertise over generalist scale. North American banking and retail clients in particular are rotating spend toward Polish and Mexican delivery centers that combine regulatory familiarity with real-time collaboration windows.
Global Software Outsourcing Market Segmentation
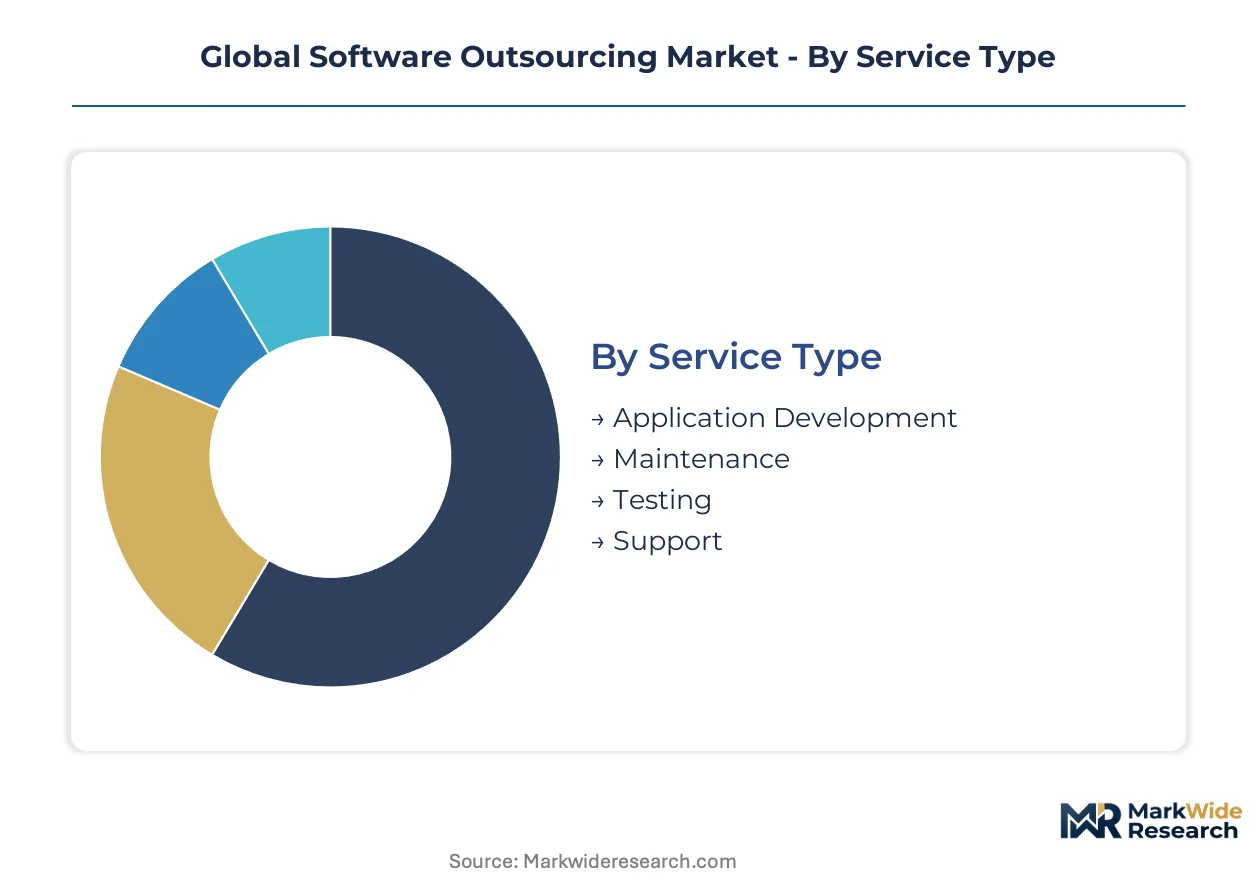
Service delivery models in software outsourcing fragment along technical architecture, regulatory exposure, and client procurement sophistication. Each segmentation axis reveals distinct margin structures and capability requirements that reshape vendor positioning.
Service Type:
Volume concentrates in maintenance contracts while premium margins attach to specialized development competencies.
- Application Development:Custom software engineering spans mobile, web, and enterprise system builds. Healthcare and BFSI clients in Germany and the United States drive demand for FDA and HIPAA-compliant codebases with embedded security protocols.
- Maintenance:Legacy system sustainment and patch management commands the largest contract volume. Indian vendors dominate this tier through scale advantages in Bengaluru and Hyderabad delivery centers.
- Testing:QA automation and security penetration testing. Polish nearshore hubs capture European financial services demand for GDPR-aligned test environments.
- Support:L1-L3 helpdesk and incident resolution. Mexican delivery centers serve United States mid-market clients seeking real-time timezone coverage.
Mature deployment sits with Maintenance. Newer deployment is concentrated in Application Development.
Deployment Model:
Client infrastructure mandates are splitting workloads across sovereignty zones rather than consolidating in single jurisdictions.
- Cloud:Containerized microservices on AWS, Azure, and GCP infrastructure. EU AI Act compliance is redirecting European healthcare workloads toward EU-sovereign cloud regions operated by vendors with local legal entities.
- Hybrid:Split architectures combining on-premises legacy with cloud-native components. Japanese manufacturing SMEs leverage METI subsidies for this transition path.
- On-Premises:Air-gapped or data-center-hosted systems for classified or regulated workloads. Defense and intelligence agencies in the United States and United Kingdom maintain this requirement.
- Remote:Distributed engineer teams accessing client environments through VPN and zero-trust architectures. Brazilian fintech startups adopt this model for PIX payment system integration.
Established spend remains with On-Premises. Steepest expansion trajectory belongs to Cloud.
Industry Vertical:
Regulatory complexity creates tiered pricing power across end-use markets.
- BFSI:Core banking transformation, payment infrastructure, and algorithmic trading systems. German automotive financing and French insurance groups require EU AI Act conformity assessments.
- Healthcare:Electronic health records, medical device software, and telemedicine platforms. FDA cybersecurity guidance extends vendor qualification timelines by 8-14 months.
- Retail:Omnichannel commerce and inventory management systems. United States and United Kingdom retailers rotate spend toward Polish delivery centers.
- Telecommunications:5G network software and customer experience platforms. Vietnamese engineering teams capture this demand through cost-advantaged DevOps capacity.
Contract maturity centers on BFSI. Gaining share fastest is Telecommunications.
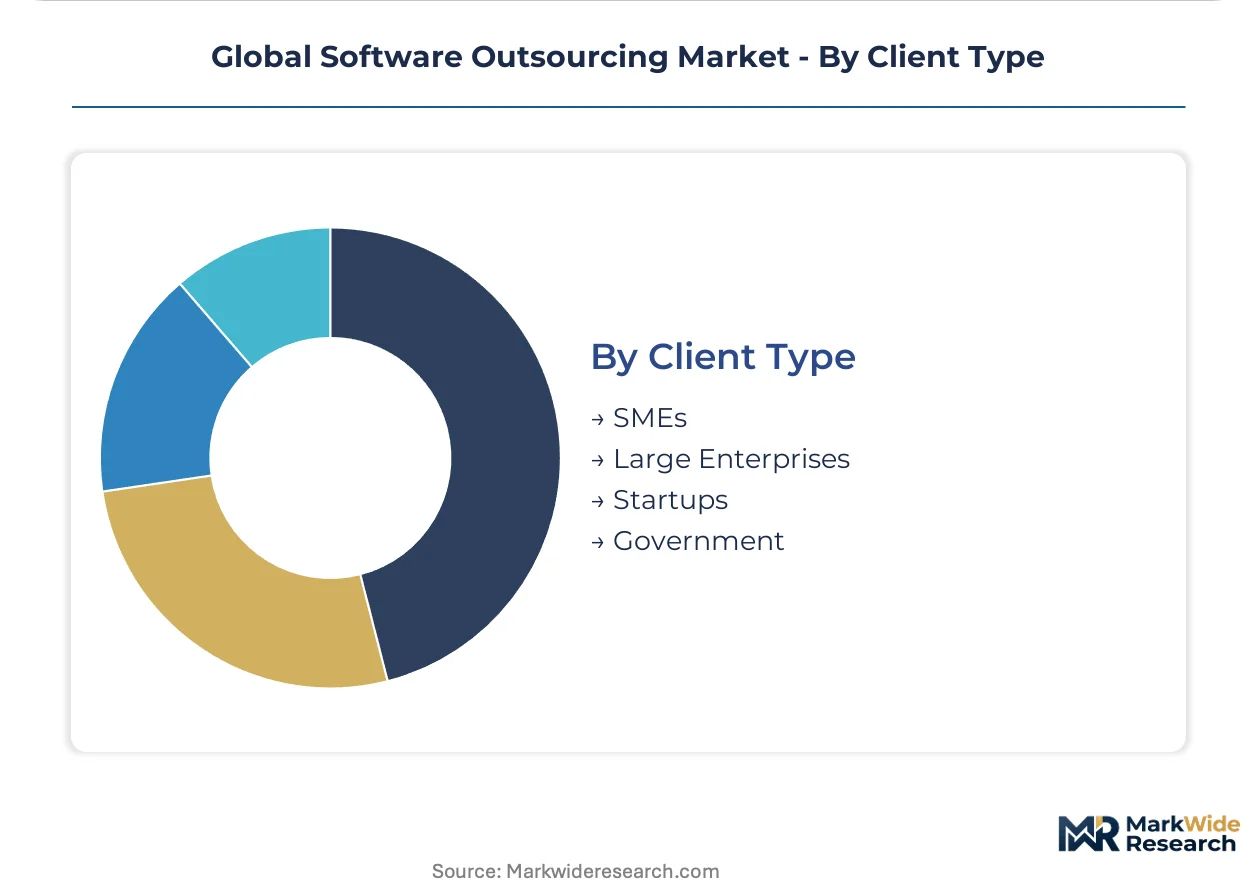
Client Type:
Procurement sophistication and contract scale diverge sharply across buyer categories.
- Large Enterprises:Multi-year transformation programs with dedicated development centers. North American banking clients consolidate spend with vendors offering vertical-specific regulatory expertise.
- SMEs:Componentized statement-of-work engagements with 90-day renewal cycles. Japanese manufacturing SMEs access METI-funded vendor selection for legacy ERP replacement.
- Startups:Staff augmentation and fractional engineering leadership. Brazilian fintech startups drive unmet demand for regulatory-compliant engineering capacity.
- Government:Sovereign infrastructure and classified system development. India's data localization rules and EU GDPR enforcement shape vendor qualification requirements.
Longest-standing relationships exist with Large Enterprises. Emerging demand concentrates in Startups.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Software Technology Parks of India scheme and Poland's Special Economic Zones are concentrating delivery capacity through tax-advantaged infrastructure. These designated zones anchor the geographic redistribution of engineering talent away from traditional hubs.
United States
Financial services firms in New York and Chicago are expanding dedicated development centers for core banking transformation. FDA cybersecurity guidance for medical device software extends vendor qualification timelines. The Dallas-Fort Worth corridor hosts growing delivery centers serving mid-market healthcare clients seeking domestic compliance proximity.
Germany
Automotive OEMs in Stuttgart and Munich require EU AI Act conformity assessments for algorithmic systems. The KBA and German financial regulators mandate localized data infrastructure for connected vehicle software. Warsaw and Kraków delivery centers capture redirected German banking demand through timezone alignment.
India
BFSI transformation programs from North American clients drive volume in Bengaluru and Hyderabad delivery centers. BIS cloud standards and data localization rules force workload splitting across sovereign infrastructure zones. The Software Technology Parks of India scheme continues concentrating engineering talent in designated technology corridors.
Poland
German automotive and French insurance groups redirect demand toward Warsaw and Kraków for GDPR-aligned test environments. EU AI Act compliance requirements favor vendors with certified EU-based operations. Polish nearshore hubs capture European financial services demand previously routed to Asian delivery centers.
Vietnam
Telecommunications 5G network software contracts flow to Ho Chi Minh City and Hanoi engineering teams through cost-advantaged DevOps capacity. Senior full-stack talent costs are rising faster than contract rate adjustments can absorb. Japanese manufacturing SMEs access Vietnamese delivery centers for legacy ERP replacement funded by METI subsidies.
Global Software Outsourcing Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered service categories. The market structures around three distinct layers: global consultancies with regulatory advisory heritage, engineering-intensive specialists with vertical depth, and scale-driven Indian vendors dominating maintenance volume. Strategic moves concentrate on M&A for capability gaps and geographic footprint expansion into nearshore zones.
Among India-based scale operators, Wipro, HCLTech, and Tata Consultancy Services occupy positions exemplifying volume-driven enterprise transformation delivery. These entities represent the archetype of global delivery network consolidation, anchoring multi-year banking and telecommunications contracts through dedicated development center models. Their positioning reflects the competitive imperative to absorb contract fragmentation while defending margin pools in commoditized maintenance tiers.
| Leading Market Players |
|---|
| Wipro |
| HCLTech |
| Accenture |
| Cognizant |
| Capgemini |
| Tata Consultancy Services (TCS) |
| EPAM Systems |
| N-iX |
| Infosys |
| Others |
Value Chain & Pricing Dynamics
Captive development center networks in Bengaluru and Hyderabad anchor volume pricing for Indian vendors while compressing margins for pure staff-augmentation players. Horizontal integration across cloud consulting and regulatory advisory services enables Accenture and Capgemini to command premium positioning against commoditized maintenance tiers.
Pricing Analysis
Short lead-time premiums attach to EU-certified engineering teams serving German automotive and French insurance clients under AI Act compliance deadlines. Three-tier pricing structure across premium, standard, and economy levels stratifies by vertical regulatory exposure and delivery geography. Cost compression in Vietnamese and Mexican DevOps tiers intensifies because senior talent wage inflation outpaces contract rate adjustments. Mid-market United States healthcare buyers exhibit highest price sensitivity; North American banking clients demonstrate lowest sensitivity due to regulatory risk transfer requirements.
Supply Chain Analysis
Freight costs for hardware-dependent edge-AI deployments exert secondary pressure on total project economics, though labor mobility dominates software outsourcing supply chains. Engineering talent concentrates in India, Poland, and Vietnam as primary delivery corridors. Raw material dependencies span semiconductor components for embedded firmware, sovereign cloud infrastructure, and certified test environments. Single-source vulnerability sits with Poland's nearshore capacity serving EU GDPR-aligned workloads. Distribution runs through dedicated development center contracts and statement-of-work engagements with 90-day renewal cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Software Outsourcing Market functions as a cost-of-compliance story where EU AI Act certification requirements erect barrier-to-entry moats favoring vendors with established European legal entities and localized data infrastructure.
For Market Incumbents: Anticipate contract fragmentation by unbundling monolithic transformation programs into componentized engagements with shorter renewal cycles. Accentuate vertical-specific regulatory expertise in healthcare and BFSI to defend margin pools against low-code platform substitution. Prioritize certification investment in FDA cybersecurity and EU AI Act conformity assessments to maintain procurement eligibility. For New Entrants and Emerging Players: Cloud-native fractional CTO marketplaces offer penetration pathways into United States mid-market enterprises struggling to orchestrate multi-vendor agile teams. Brazilian fintech regulatory-compliant engineering capacity represents the most penetrable white-space target given Central Bank open banking mandates. Pursue outcome-based pricing models anchored to PIX payment system integration milestones. For Investors and Strategic Acquirers: Exit pathways concentrate in engineering-intensive specialists with demonstrated vertical depth and EU regulatory consulting heritage. Long-term viability over the coming decade hinges on algorithmic audit capabilities and sovereign cloud infrastructure ownership. Monitor FDA cybersecurity guidance enforcement intensity as inflection indicator for healthcare vendor qualification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | Establishes procurement eligibility for German automotive and French insurance clients. |
| Nearshore Delivery Center Expansion | Warsaw and Kraków facilities capture timezone-aligned demand from European banking. |
| Acquisition of Embedded Systems Specialist | Compresses FDA qualification timelines for medical device software pipelines. |
| Platform Integration with Sovereign Cloud | Aligns delivery footprint with India's BIS standards and EU data localization rules. |
| Geographic Expansion into Brazilian Fintech | Addresses unmet engineering capacity demand from Central Bank PIX infrastructure. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners across North America, Europe, and Asia-Pacific. SEC filings, hyperscaler capex disclosures, and EU regulatory submission databases supplemented demand-side validation. Bottom-up project pipeline analysis and top-down macroeconomic factor weighting enabled triangulation across modeling approaches.
Reconciliation of vendor contract values, talent cost surveys, and regulatory compliance expenditure streams shaped the analytical framework. Segmentation dimensions spanned deployment model, organization size, vertical regulatory exposure, integration complexity, and regional adoption pattern. CAGRs derived from historical contract velocity analysis and forward-looking procurement intention surveys. Edge-AI convergence intensity and METI subsidy disbursement patterns informed scenario weighting across the projection horizon.
Inputs from NASSCOM, Polish Investment and Trade Agency, and Vietnam Ministry of Information and Communications were available through the study window; gaps in private vendor margin disclosure introduce uncertainty bands around profitability estimates. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and cross-border data governance evolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Digitalization in Bpo Market
Business Process Outsourcing (BPO)
Europe Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
North America Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Global Telecom Outsourcing Market
Business Process Outsourcing (BPO)
Contact Center Outsourcing Market
Business Process Outsourcing (BPO)
Global Contact and Call Center Outsourcing Market
Business Process Outsourcing (BPO)
Employment Screening Services Market
Business Process Outsourcing (BPO)
Desktop Outsourcing Market
Business Process Outsourcing (BPO)
BFSI BPO Services Market
Business Process Outsourcing (BPO)
Call Center Outsourcing Market
Business Process Outsourcing (BPO)
Automotive Business Process Management Market
Business Process Outsourcing (BPO)
Global Knowledge Process Outsourcing Market
Business Process Outsourcing (BPO)
Healthcare Supply Chain BPO Market
Business Process Outsourcing (BPO)
Labor Outsourcing Service Market
Business Process Outsourcing (BPO)
United States IT Outsourcing Market
Business Process Outsourcing (BPO)
Asia-Pacific Business Process As a Service (Bpaas) Market