
 Double Stack Oven Market | 2026-2036
Double Stack Oven Market Size, Share, and Industry Trends Forecast 2026-2036
Double Stack Oven Market Foresight
Market Dynamics and Strategic Positioning
Certified commercial kitchen technician availability is bifurcating the competitive landscape between premium service networks and mass-market distribution. Bosch sustains its European manufacturing heritage through rigorous technician certification programs in North America. Miele leverages its direct-service model to control installation quality and aftermarket revenue streams. Thermador competes aggressively on builder-channel relationships, securing specification slots in multi-unit residential developments.
Product Architecture and Segment Structure
A double stack oven comprises two independent cooking chambers vertically integrated into a single frame, typically achieving combined capacities of 6.0 to 10.0 cubic feet with convection airflow systems rated between 1,500 and 3,000 watts per cavity. Electric configurations now dominate new commercial installations where utility rebates favor energy-efficient equipment, while gas units retain share in legacy restaurant infrastructure and regions with lower natural gas tariffs. Built-in installations command premium positioning in renovation-driven demand, whereas modular configurations serve the fastest-growing food truck and ghost kitchen segments where equipment mobility and lease flexibility determine procurement decisions.
Regulatory Environment and Outlook
The US Department of Energy enforces minimum efficiency standards under 10 CFR Part 430, while the EPA's ENERGY STAR certification program shapes buyer specification behavior in institutional procurement. The EU Ecodesign Directive and F-Gas Regulation constrain refrigerant-based cooling integrations in combination oven variants exported to European markets. Stakeholders must monitor evolving electrification mandates in California and New York that threaten gas-powered unit viability in the largest state-level markets.
Market Dynamics
Commercial kitchen electrification mandates and ghost kitchen proliferation are compressing equipment replacement cycles while fragmenting procurement authority between centralized chains and independent operators.
Growth Catalysts
- California electrification mandates:The state's ban on new gas hookups in commercial buildings is forcing bakery and restaurant operators toward electric double stack configurations, accelerating replacement demand in the largest US state market.
- Ghost kitchen clustering:Texas and California operators are deploying modular double stack ovens in leased commissary spaces where equipment mobility and rapid commissioning take priority over permanent installation.
- Convection technology maturation:Third-generation airflow systems with independent cavity controls now deliver consistent results across both chambers, reducing the skill barrier for artisan bread production.
Market Restraints
- Stainless steel input volatility:Cold-rolled steel price swings compress manufacturer margins and delay capital planning for commercial bakery expansions.
- Technician certification scarcity:The limited pool of EPA Section 608 certified commercial kitchen technicians constrains installation capacity and extends project timelines.
- Legacy gas infrastructure lock-in:Existing restaurant buildouts with dedicated gas lines create switching costs that delay electric conversion despite utility rebate availability.
Strategic Opportunities
- Food truck electrification:Battery-powered mobile kitchen platforms in Texas and California create demand for compact electric double stack units with reduced amp draw.
- Utility rebate stacking:The Inflation Reduction Act commercial equipment incentives layered with state-level programs can offset 30-50% of electric oven acquisition costs for qualifying operators.
- Remote diagnostics integration:IoT-enabled cavity monitoring and predictive maintenance alerts are opening recurring revenue streams previously captured by third-party service networks.
Industry Challenges
- Installation coordination complexity:Multi-trade coordination between electricians, HVAC contractors, and health inspectors frequently delays commissioning in renovation-driven projects.
- Certification timeline compression:NSF International food equipment certification and UL safety listing processes create 12-16 week gaps between product readiness and market availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Double Stack Oven Market |
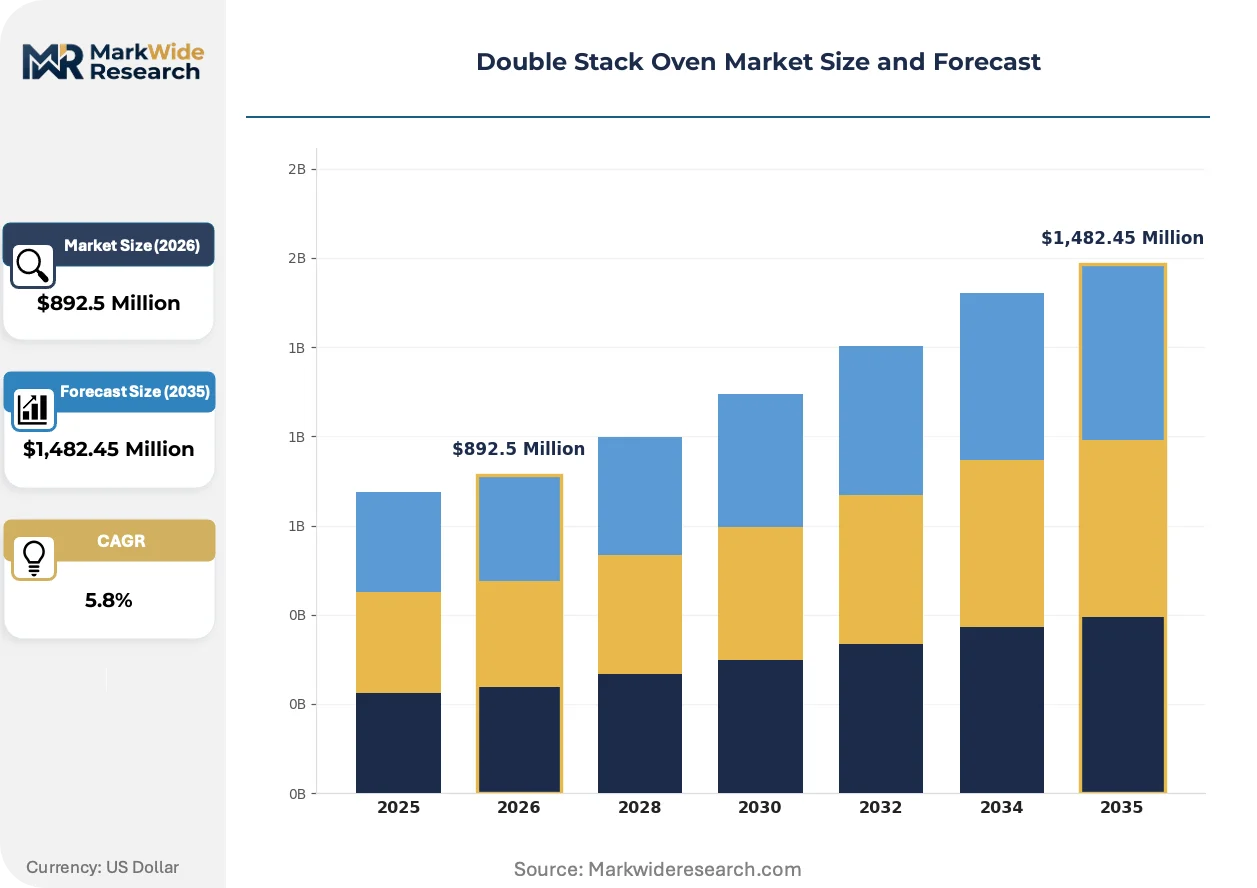
| Market Size in 2026 | $892.5 Million |
| Market Size in 2035 | $1,482.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas, Electric, Convection, Combination End User: Restaurants, Bakeries, Food Trucks, Catering Services Installation Type: Built-in, Modular, Free-standing, Countertop Size: Compact, Standard, Large, Commercial |
| Companies Covered | LG Studio, Bosch, Miele, Cafe Appliances, GE Profile, Monogram, Gaggenau, GE, Thermador, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Double Stack Oven Market Shifts & Advancements
Equipment intelligence and regulatory electrification are converging to redefine how commercial kitchens specify, operate, and service thermal cooking platforms. Three developments dominate current investment patterns.
Smart cavity management systems with independent temperature profiling and automated humidity injection are fragmenting the traditional distinction between convection ovens and specialized deck ovens. Ghost kitchen operators in Houston and Los Angeles are adopting these hybrid configurations to execute both roasted proteins and artisan breads without equipment redundancy. The technology is fragmenting category boundaries and compressing the addressable market for single-purpose thermal equipment.
The EPA's ENERGY STAR Version 3.0 commercial oven specification tightens idle energy limits and mandates visible energy consumption displays. Manufacturers must redesign control interfaces and insulation packages to maintain certification eligibility for institutional procurement channels. California school districts and Texas hospital systems are now excluding non-certified equipment from competitive bidding, reshaping specification behavior across public-sector foodservice.
Equipment-as-a-service contracts with bundled maintenance and technology refresh clauses are displacing traditional capital purchase models among multi-location bakery chains. Leasing structures shift balance sheet treatment and transfer obsolescence risk to manufacturers or third-party fleet operators. This restructuring is most visible in Austin and San Diego where rapidly scaling cookie and bread concepts prioritize cash flow preservation over asset ownership.
Double Stack Oven Market Segmentation
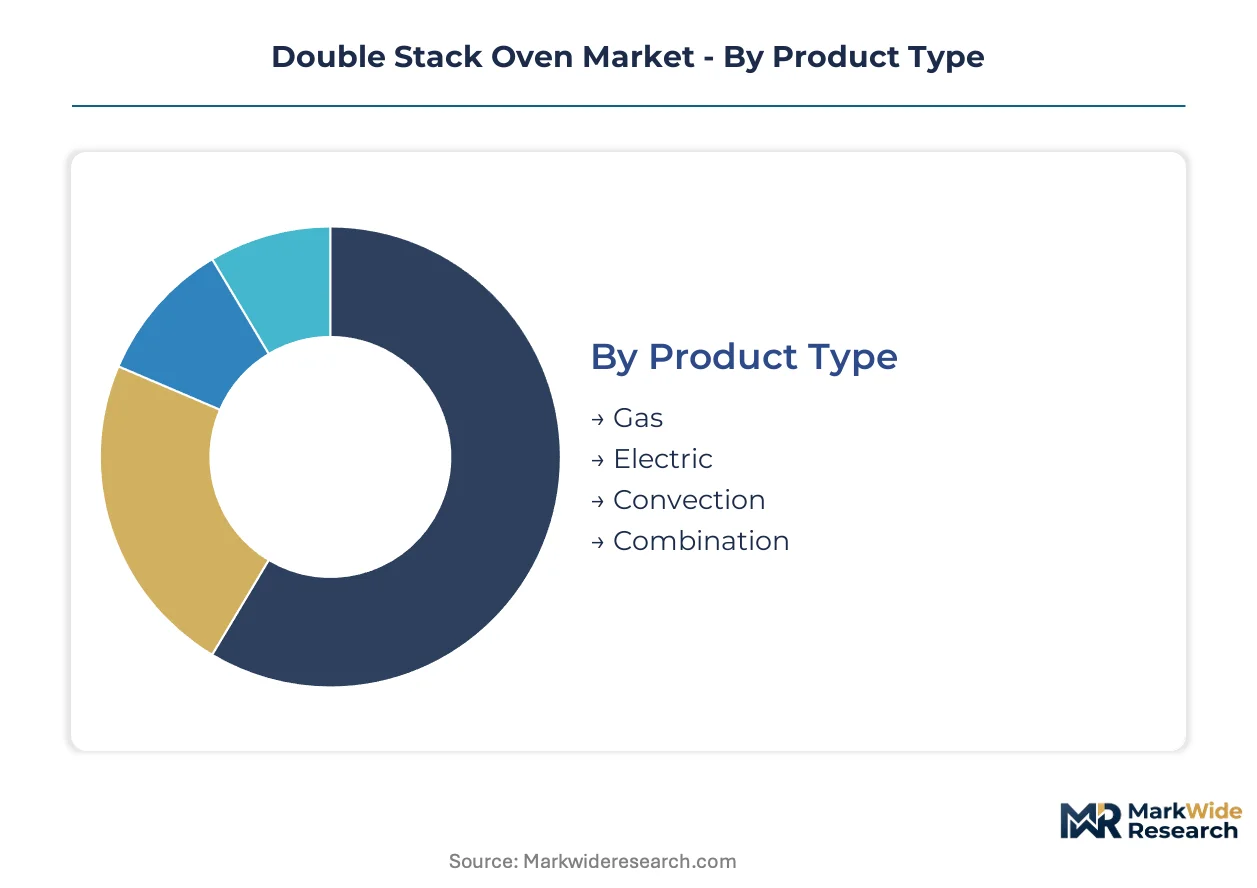
Double stack oven procurement decisions fragment sharply across fuel type, installation constraints, and operational mobility requirements. Understanding these segment boundaries clarifies where electrification mandates, utility rebate structures, and ghost kitchen leasing patterns redirect equipment flows.
Product Type:
EPA ENERGY STAR Version 3.0 idle energy limits and California's commercial building electrification mandates are bifurcating procurement between legacy gas infrastructure and rebate-eligible electric configurations.
- Gas:Retains installed base in Texas restaurant corridors where natural gas tariffs undercut electricity rates and legacy hood ventilation systems reduce conversion costs. Existing gas line infrastructure in Houston and Dallas-Fort Worth food halls delays electric switching despite rebate availability.
- Electric:Captures new commercial bakery capacity in California where Title 24 building standards prohibit new gas hookups. Utility rebate stacking through the Inflation Reduction Act and state programs offsets acquisition premiums for qualifying operators in Los Angeles and San Diego.
- Convection:Third-generation airflow systems with independent cavity controls reduce artisan bread skill barriers. Ghost kitchen clusters in Austin deploy these units for protein roasting and baking without equipment redundancy.
- Combination:Hybrid thermal and steam injection capabilities command specification in institutional foodservice. California school districts and Texas hospital systems require ENERGY STAR certification for competitive bidding eligibility.
Electric configurations handle the majority of new throughput; convection is the fastest mover on share.
End User:
Procurement authority concentrates differently across centralized chains with fleet purchasing power versus independent operators prioritizing lease flexibility and rapid commissioning.
- Restaurants:Full-service and fast-casual operators in Texas urban corridors balance renovation-driven built-in installations against modular equipment for expansion locations. Gas-to-electric conversion timelines stretch project completion in legacy buildouts.
- Bakeries:Artisan bread specialists in California drive capacity investments with convection technology maturation. Independent chains in San Diego prioritize equipment-as-a-service contracts to preserve cash flow during scaling.
- Food Trucks:Battery-powered mobile kitchen platforms in Texas and California create demand for compact electric units with reduced amp draw. Mobility requirements favor modular and countertop configurations over permanent installation.
- Catering Services:Event-based operators require rapid deployment capabilities and multi-voltage compatibility. Leased commissary access in Houston and Los Angeles shapes procurement toward transferable equipment assets.
Restaurants absorb the largest equipment volume; food trucks are expanding most quickly on share.
Installation Type:
Real estate tenure structures—owned versus leased, permanent versus temporary—determine whether operators prioritize capital-integrated built-ins or transferable modular systems.
- Built-in:Renovation-driven demand in California independent bakeries commands premium positioning. Multi-trade coordination between electricians, HVAC contractors, and health inspectors extends commissioning timelines.
- Modular:Ghost kitchen proliferation in Texas and California commissary spaces prioritizes equipment mobility and lease flexibility. Rapid deployment without structural modification reduces operator capital risk.
- Free-standing:Intermediate positioning serves mid-scale catering operations requiring repositioning without full modularity. Castor-mounted units in Austin food halls balance stability with relocation capability.
- Countertop:Compact configurations address food truck spatial constraints and front-of-house baking demonstrations. Reduced cubic footage limits throughput but enables deployment in non-traditional kitchen footprints.
Built-in installations anchor renovation spending; modular configurations are climbing fastest on share.
Size:
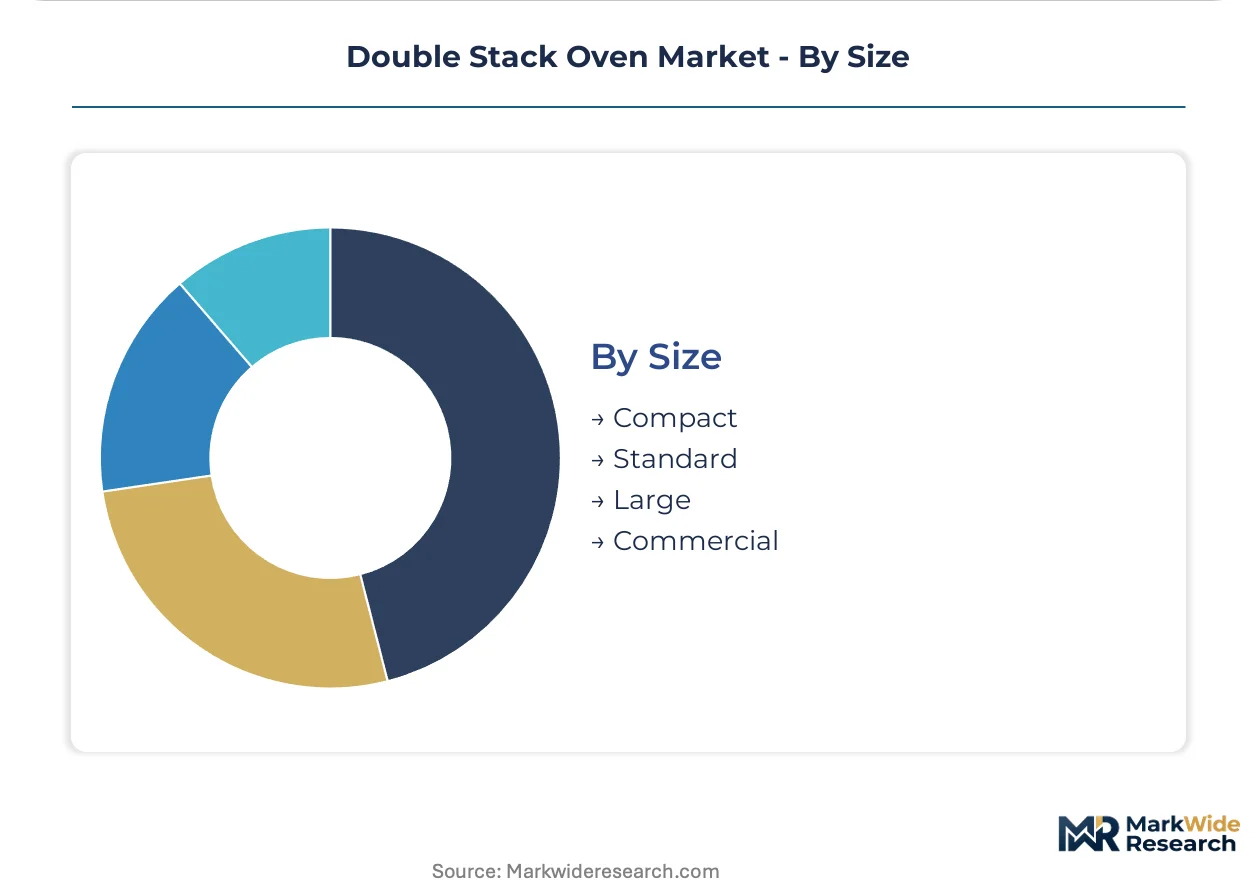
Throughput requirements and physical space constraints segment demand across volume tiers with distinct margin profiles and service network dependencies.
- Compact:Food truck and small-format ghost kitchen deployments in Texas and California prioritize reduced amp draw and spatial efficiency. Limited cavity dimensions constrain batch sizes but enable non-traditional venue access.
- Standard:Mid-scale independent restaurants and bakeries balance throughput with kitchen footprint optimization. This tier captures the broadest cross-section of electrification-driven replacement demand.
- Large:High-volume catering and institutional foodservice requires coordinated electrical infrastructure upgrades. California school districts and Texas hospital systems specify these units for centralized production kitchens.
- Commercial:Industrial bakery chains and commissary operators deploy maximum-capacity configurations with automated loading systems. Equipment-as-a-service contracts concentrate in this tier among multi-location Austin and San Diego operators.
Standard sizes handle the majority of unit volume; compact configurations show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Department of Energy's appliance efficiency standards under 10 CFR Part 430 anchor procurement behavior in the dominant North American market, while electrification mandates in California and New York reshape equipment specifications across state lines.
United States
Commercial bakery capacity investments and ghost kitchen clustering in Texas and California drive equipment demand. The Inflation Reduction Act commercial equipment incentives layer with state rebates to offset electric oven acquisition costs. Houston and Los Angeles commissary spaces deploy modular configurations for lease flexibility.
Germany
Artisan bread production standards and energy transition policies accelerate convection technology adoption. The EU Ecodesign Directive constrains refrigerant-based cooling integrations in combination oven variants. Bavarian industrial bakery chains prioritize equipment-as-a-service contracts to preserve capital during scaling.
China
Foodservice infrastructure expansion and domestic bakery chain growth create throughput demand for large-capacity configurations. GB standards for commercial kitchen equipment establish baseline efficiency requirements. Shanghai and Shenzhen equipment distributors report rising specification of electric double stack units in new commercial developments.
Japan
Compact kitchen footprints in urban restaurants and convenience store bakery integration favor space-optimized configurations. METI energy efficiency guidelines shape institutional procurement specifications. Tokyo and Osaka ghost kitchen operators adopt modular systems for rapid deployment in leased facilities.
United Kingdom
Independent bakery chain expansion and renovation-driven replacement cycles support built-in installation demand. The UK Net Zero Strategy pressures gas-to-electric conversion timelines in commercial foodservice. London and Manchester commissary kitchens specify transferable equipment assets for operational flexibility.
Double Stack Oven Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in a structure defined by service network depth and certification program reach. The upper tier controls specification relationships with multi-unit developers and institutional procurement channels, while mid-tier fabricators compete on utility rebate eligibility and rapid commissioning capabilities. Three archetypes dominate: heritage European manufacturers with technician certification ecosystems, North American brands with builder-channel scale, and Asian fabricators with cost-optimized modular platforms. Competitive moves concentrate on strategic partnerships with ghost kitchen operators and portfolio diversification into equipment-as-a-service contracts.
Among heritage European manufacturers, Bosch and Miele exemplify the premium-tier archetype through controlled service networks and direct-installation models. LG Studio anchors the Asian-origin competitive position with scale-driven manufacturing capabilities. Thermador occupies a position within the North American specification-focused tier, leveraging builder relationships for multi-unit residential penetration.
| Leading Market Players |
|---|
| LG Studio |
| Bosch |
| Miele |
| Cafe Appliances |
| GE Profile |
| Monogram |
| Gaggenau |
| GE |
| Thermador |
| Others |
Supply & Pricing Matrix
Capacity utilization at European convection component plants anchors pricing power for premium-tier manufacturers while compressing margin floors for mass-market fabricators sourcing from Asian assembly networks. This scale asymmetry concentrates supply chain leverage among heritage brands with captive technician certification ecosystems and fragments procurement options for independent operators seeking rapid commissioning.
Pricing Analysis
California-to-Texas price spreads of 15-25 percent reflect divergent rebate stacking availability and installation cost structures across state regulatory regimes. Three-tier pricing structure across premium, standard, and economy levels segments by certification depth, with UL-NSF dual-listed units commanding acquisition premiums over single-certified alternatives. Pricing pressure stems from stainless steel input volatility and compressed bakery expansion timelines. Ghost kitchen operators in Houston and Austin exhibit highest price sensitivity due to lease-term uncertainty, while California school districts demonstrate lowest sensitivity given institutional procurement budgets and electrification mandate compliance deadlines.
Supply Chain Analysis
Port congestion at Long Beach and Rotterdam has elevated inbound logistics costs for European-manufactured convection assemblies and Asian-sourced control modules. Manufacturing concentrates in Germany, China, and Mexico, with German facilities supplying premium-tier heritage brands and Mexican plants serving North American builder-channel volume. Raw material dependencies center on cold-rolled stainless steel, copper wiring, and ceramic insulation substrates. Single-source vulnerability concentrates in EPA Section 608 certified compressor sub-assemblies. Distribution runs through manufacturer-direct service networks for premium tiers and regional equipment distributors for standard-economy segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Remote diagnostics integration and predictive maintenance subscriptions are expanding faster than hardware unit sales, repositioning the market as a service-attach opportunity where recurring revenue streams capture lifetime customer value beyond initial equipment transactions.
For Market Incumbents: Consolidate technician certification ecosystems to defend against emerging equipment-as-a-service fleet operators capturing multi-location bakery chains. Deepen backward integration into convection airflow component manufacturing to offset stainless steel margin compression. Prioritize NSF-UL dual-certification investment to maintain institutional procurement eligibility as California and Texas school districts tighten specification standards.
For New Entrants and Emerging Players: Lead with battery-compatible compact electric units targeting Texas food truck electrification pilots where reduced amp draw specifications remain undersupplied. Focus initial deployment on Austin and San Diego ghost kitchen clusters where lease flexibility requirements favor modular configurations over heritage brand permanence. Pursue utility rebate eligibility as primary go-to-market credential to offset brand recognition deficits in institutional channels.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors service-network-integrated manufacturers over pure-play fabricators as IoT-enabled predictive maintenance reshapes customer retention economics. Long-term viability hinges on electrification mandate exposure diversification across California, Texas, and New York regulatory jurisdictions. Acquisition targets should demonstrate EPA ENERGY STAR Version 3.0 certification readiness and established ghost kitchen operator relationships. Monitor California Title 24 amendment timelines as inflection indicator for gas-to-electric conversion acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Contract Expansion | Transforms balance sheet treatment for Austin and San Diego bakery chains while transferring obsolescence risk to manufacturers. |
| IoT-Enabled Predictive Maintenance Integration | Captures recurring revenue streams previously lost to third-party service networks through cavity monitoring alerts. |
| Utility Rebate Stacking Optimization | Layers Inflation Reduction Act incentives with state programs to offset 30-50 percent of electric oven acquisition premiums. |
| Dual-Certification Fast-Track Investment | Compresses 12-16 week NSF-UL listing gaps to accelerate product readiness and market availability timelines. |
| Ghost Kitchen Commissary Partnership | Secures specification slots in Houston and Los Angeles leased facilities where equipment mobility determines procurement decisions. |
Research Methodology
A spread of perspectives from commercial kitchen equipment distributors, ghost kitchen operators, bakery chain procurement directors, EPA certification consultants, and utility rebate program administrators converged on the working assumptions. Primary fieldwork combined structured interviews with aftermarket service heads and plant engineers at multi-location bakery facilities with secondary validation against DOE appliance efficiency filings, ENERGY STAR certified product databases, and Texas-California utility incentive program disclosures. Bottom-up unit shipment estimates from regional equipment distributors were triangulated against top-down capacity utilization data from heritage manufacturer service networks.
Segmentation dimensions modeled include fuel type, installation configuration, end-user operational scale, and geographic regulatory cluster across the projection horizon. CAGRs were derived from installed base replacement cycle analysis and new capacity investment patterns. Forecast inputs incorporated California Title 24 electrification mandate compliance timelines and Texas natural gas tariff differentials.
Forecasts assume regulatory continuity in DOE 10 CFR Part 430 efficiency standards and California Title 24 building codes; material policy shifts would require re-modeling. Stainless steel price volatility and EPA Section 608 technician certification scarcity represent specific risk factors that could revise equipment availability and installation capacity assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
India Household Flour Milling Machines Market
Food Processing Equipment
Optical Sorter Market
Food Processing Equipment
Reach-In Freezers Market
Food Processing Equipment
Tunnel Oven Market
Food Processing Equipment
Reflow Oven Market
Food Processing Equipment
Europe Household Food Waste Composting Machine Market
Food Processing Equipment
Air Cooled Cube Ice Machines Market
Food Processing Equipment
Micro Winery Equipment Market
Food Processing Equipment
Freshwater Flake Ice Machine Market
Food Processing Equipment
French Fries Cutter Market
Food Processing Equipment
Commercial Mixer Market
Food Processing Equipment
Countertop Food Blenders Market
Food Processing Equipment
Pasty Products Filling Machine Market
Food Processing Equipment
Pulp Washing Equipment Market
Food Processing Equipment
Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Decanter Centrifuge Market