
 Yogurt Makers Market | 2026-2036
Yogurt Makers Market Size, Share, and Industry Trends Forecast 2026-2036
Yogurt Makers Market Outlook
Aftermarket service revenue from replacement parts and warranty extensions is reconfiguring margin capture for yogurt maker manufacturers. Euro Cuisine Inc. leverages its dedicated replacement lid and jar program to sustain recurring consumer touchpoints. Hamilton Beach Brands anchors North American shelf presence through broad retail distribution. Joyoung Co., Ltd dominates the Chinese domestic market with stainless-steel fermentation vessel specialization.
A yogurt maker is an electromechanical or manual appliance designed to maintain controlled temperatures between 40°C and 45°C for bacterial culture incubation, typically employing PTC heating elements or water-bath thermal mass to ensure consistent curd formation. The device serves commercial and residential users seeking batch-controlled probiotic production without industrial dairy infrastructure. Electric yogurt makers with smart features lead unit shipments as Wi-Fi-enabled temperature logging and app-based recipe libraries command premium positioning. Multi-function yogurt makers represent the fastest-growing product type by integrating cheese-making and fermentation modes into single platforms. Manual yogurt makers occupy stable economy-tier segments where price-sensitive households prioritize simplicity over connectivity.
FDA food contact substance regulations govern plastic and silicone components in yogurt makers sold in the United States, while EU REACH and RoHS frameworks restrict hazardous substances in heating element coatings and electronic assemblies across European markets. Ecodesign directives from the European Commission now mandate standby power thresholds for networked kitchen appliances, pushing manufacturers toward lower-wattage smart modules. Stakeholders must monitor evolving right-to-repair legislation in multiple jurisdictions that could mandate spare parts availability periods and reshape aftermarket economics for sealed-unit designs.
Market Dynamics
EU Ecodesign mandates for standby power consumption are forcing yogurt maker manufacturers to redesign heating element architectures and networked control modules across their product portfolios.
Growth Catalysts
- Smart home integration:Wi-Fi-enabled temperature logging and app-based recipe libraries are pulling premium kitchen segment buyers toward connected fermentation appliances in the United States.
- REACH compliance differentiation:EU RoHS and REACH frameworks restricting hazardous substances in heating element coatings are creating competitive separation for compliant manufacturers accessing European retail channels.
- Urban household fermentation routines:Compact countertop appliance demand concentrates in Japanese and South Korean metropolitan kitchens where daily probiotic production anchors domestic food preparation habits.
Market Restraints
- PTC heating element supply concentration:Sourcing of positive temperature coefficient ceramic components clusters among East Asian suppliers, exposing manufacturers to input cost volatility and logistics disruption.
- Silicone and food-contact plastic certification friction:FDA food contact substance regulations for yogurt maker vessels and seals extend product development timelines and testing expenditures for United States market entry.
- Manual appliance substitution:Price-sensitive households in emerging economies continue selecting non-electric fermentation methods, capping electric unit penetration in economy-tier segments.
Strategic Opportunities
- Right-to-repair legislative tailwinds:Evolving spare parts availability mandates in multiple jurisdictions are opening aftermarket revenue streams for replacement lids, jars, and heating elements.
- Multi-function platform convergence:Integration of cheese-making, kefir, and fermentation modes into single appliances is capturing counter space-constrained urban consumers seeking appliance consolidation.
- Specialty retail channel expansion:Direct-to-consumer and specialty kitchenware platforms are bypassing traditional mass retail gatekeepers for premium smart yogurt maker distribution.
Industry Challenges
- Thermal engineering talent scarcity:Precision temperature control firmware development and PTC element calibration require specialized electromechanical expertise that resides concentrated among limited supplier engineering teams.
- Sealed-unit design integration complexity:Waterproofing of smart control modules against fermentation chamber humidity while maintaining repairability creates manufacturing yield and warranty exposure trade-offs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yogurt Makers Market |
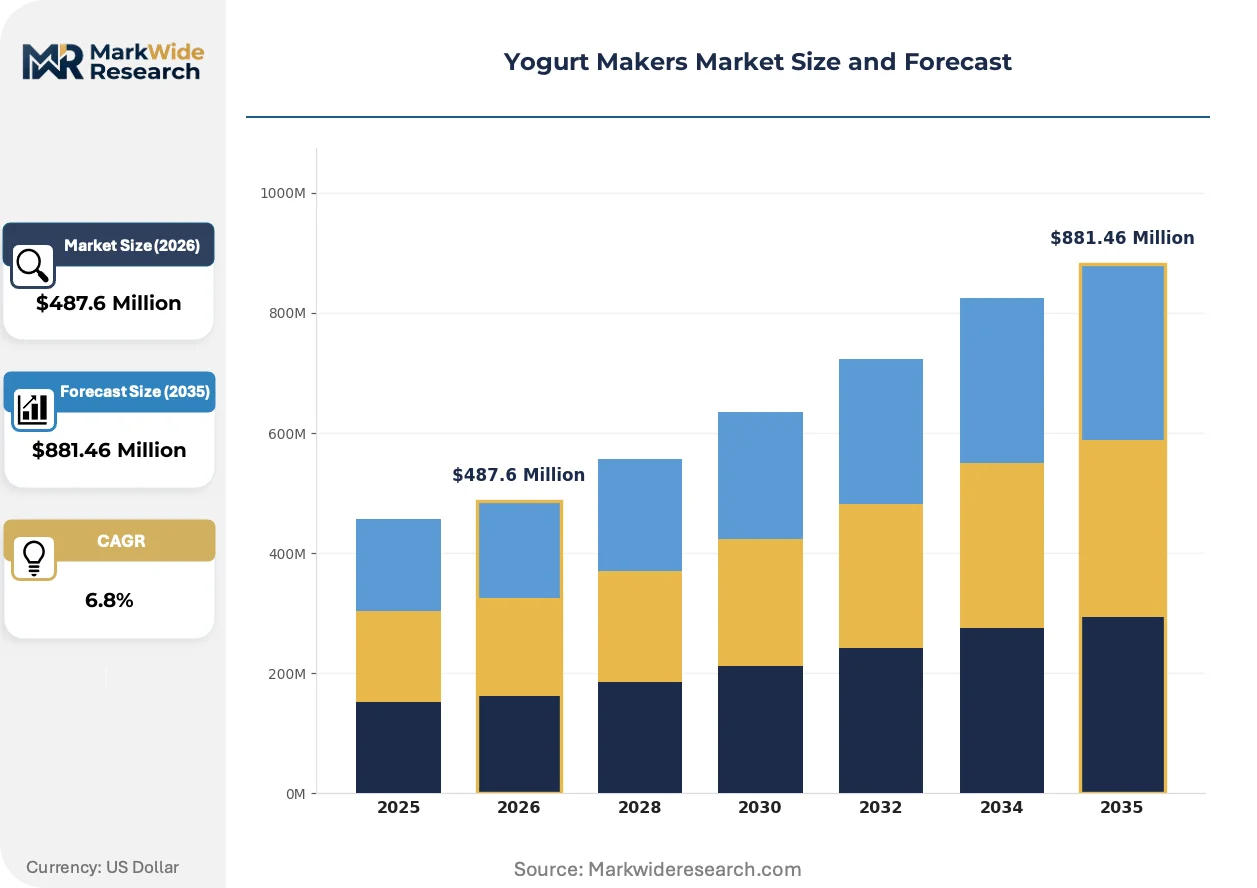
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Yogurt Makers, Manual Yogurt Makers, Multi-Function Yogurt Makers, Professional Yogurt Makers End User: Households, Restaurants, Cafes, Food Services Technology: Thermal Technology, Sous Vide, Smart Features, Induction Heating Capacity: Small Capacity, Medium Capacity, Large Capacity, Industrial Capacity |
| Companies Covered | Euro Cuisine Inc., Gourmia, Ningbo Hippo Electrical Appliance Co., Hamilton Beach Brands, Cuisinart, Philips, Panasonic, TTK Prestige Ltd, Joyoung Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yogurt Makers Market Strategic Shifts
Connected fermentation technology and modular appliance architectures are restructuring how manufacturers capture value beyond initial hardware sales. Regulatory pressure on energy efficiency and material safety is accelerating design iteration cycles.
Precision fermentation monitoring is migrating from standalone temperature probes to integrated multi-sensor arrays measuring pH, viscosity, and bacterial activity in real time. Premium kitchen segment buyers in Germany and France are adopting these systems for batch reproducibility. This sensor convergence is compressing the performance gap between domestic and small-commercial fermentation equipment.
EU Ecodesign directives mandating standby power thresholds for networked kitchen appliances are forcing heating element controller redesigns toward sub-watt idle states. Manufacturers serving European markets must revalidate entire electronic assemblies against revised efficiency benchmarks. Smart yogurt makers with always-on Wi-Fi modules face the steepest compliance engineering burden.
After-sales service unbundling is separating warranty extensions and replacement part subscriptions from original equipment transactions. Urban households in Japan and South Korea are purchasing fermentation vessel and lid replacement programs as standalone recurring purchases. This behavioral shift is visible most acutely in markets with established small appliance refurbishment cultures and dense authorized service networks.
Yogurt Makers Market Segmentation
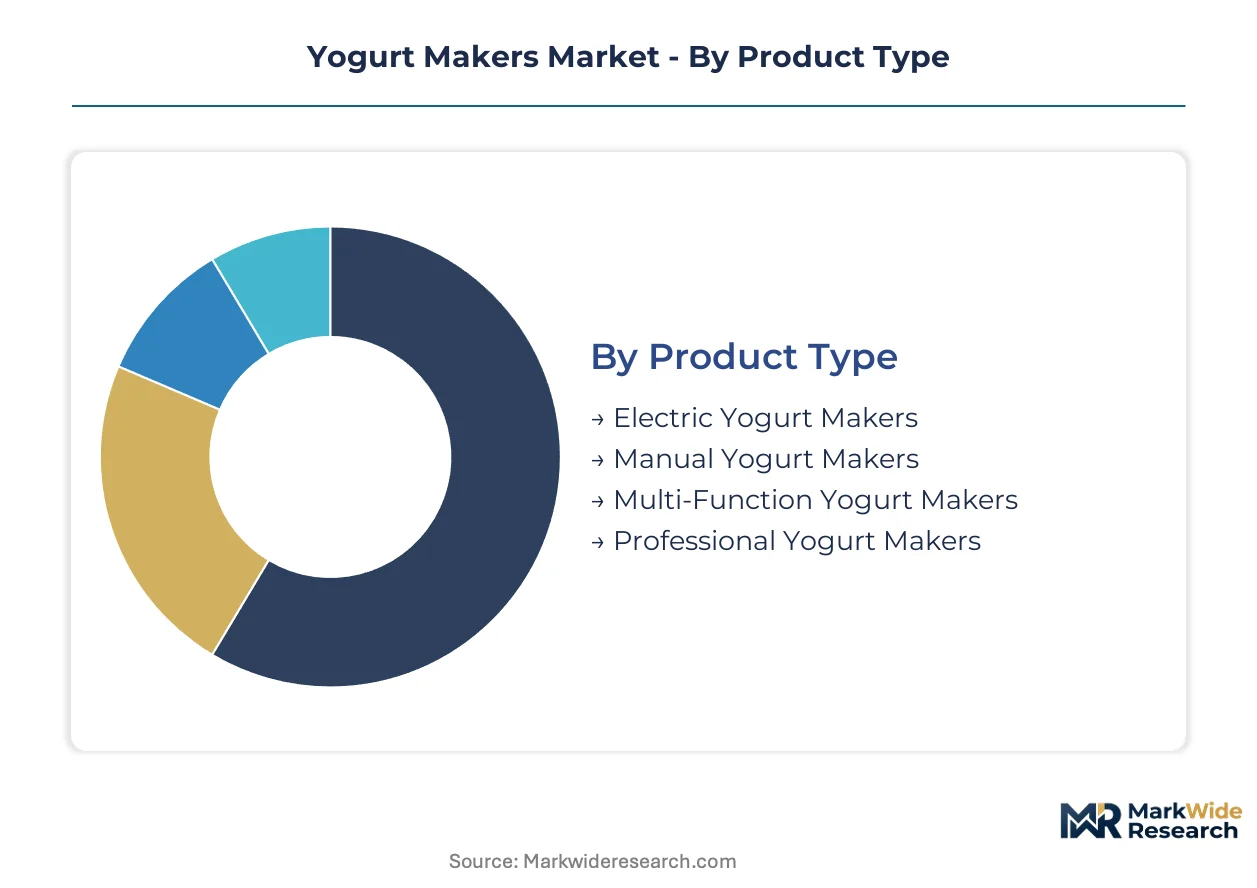
Segmentation in the yogurt makers market reveals distinct service intensity patterns across product tiers. Aftermarket revenue potential varies dramatically by category, with replacement part availability and warranty attachment rates diverging between manual and electric platforms.
Product Type:
After-sales-service intensity peaks with electric and multi-function units where heating element replacement, smart module firmware updates, and vessel lid programs generate recurring revenue streams.
- Electric Yogurt Makers:PTC heating elements and digital temperature controllers define these units. Demand clusters in United States premium kitchen segments where Wi-Fi-enabled models with app-based recipe libraries command sustained replacement part subscriptions.
- Multi-Function Yogurt Makers:Integrated cheese-making, kefir, and fermentation modes expand utility beyond single-purpose appliances. Urban households in Japan and South Korea drive adoption where counter space constraints favor consolidated functionality.
- Manual Yogurt Makers:Non-electric thermal mass designs using insulated chambers or water-bath methods serve price-sensitive markets with minimal aftermarket service requirements.
- Professional Yogurt Makers:Stainless-steel fermentation vessels and precision temperature logging target small commercial kitchens and specialty food producers.
By volume, electric yogurt makers lead. By growth pace, multi-function yogurt makers are ahead.
End User:
Cost tier stratification separates household purchasers seeking countertop convenience from commercial operators demanding batch reproducibility and food safety documentation.
- Households:Residential users prioritize compact footprints and intuitive controls for daily fermentation routines. Japanese and South Korean metropolitan kitchens anchor this segment with established probiotic consumption habits.
- Restaurants:Small-batch artisanal producers require NSF-certified components and precise temperature logging for health inspection compliance.
- Cafes:Specialty beverage operations integrate yogurt makers into house-made ingredient pipelines for smoothies and parfaits.
- Food Services:Institutional kitchens demand industrial-capacity units with HACCP-aligned documentation and rapid vessel interchangeability.
Households dominate absolute unit shipments. Food services deliver the highest per-unit aftermarket revenue attachment.
Technology:
Volume concentration in thermal technology platforms contrasts with margin capture migrating toward sensor-integrated smart systems.
- Thermal Technology:PTC ceramic heating elements and water-bath thermal mass systems remain the baseline architecture across economy and mid-tier electric units.
- Smart Features:Wi-Fi connectivity, multi-sensor arrays measuring pH and viscosity, and cloud-based recipe libraries define premium positioning. EU Ecodesign standby power mandates are forcing controller redesigns toward sub-watt idle states.
- Sous Vide:Precision water circulation adapted from culinary applications enables temperature stability within 0.1°C for specialized fermentation protocols.
- Induction Heating:Electromagnetic vessel warming eliminates direct contact heating elements, improving cleanability and reducing thermal lag in commercial settings.
Thermal technology leads in unit volume. Smart features are climbing the fastest as regulatory pressure and consumer connectivity expectations converge.
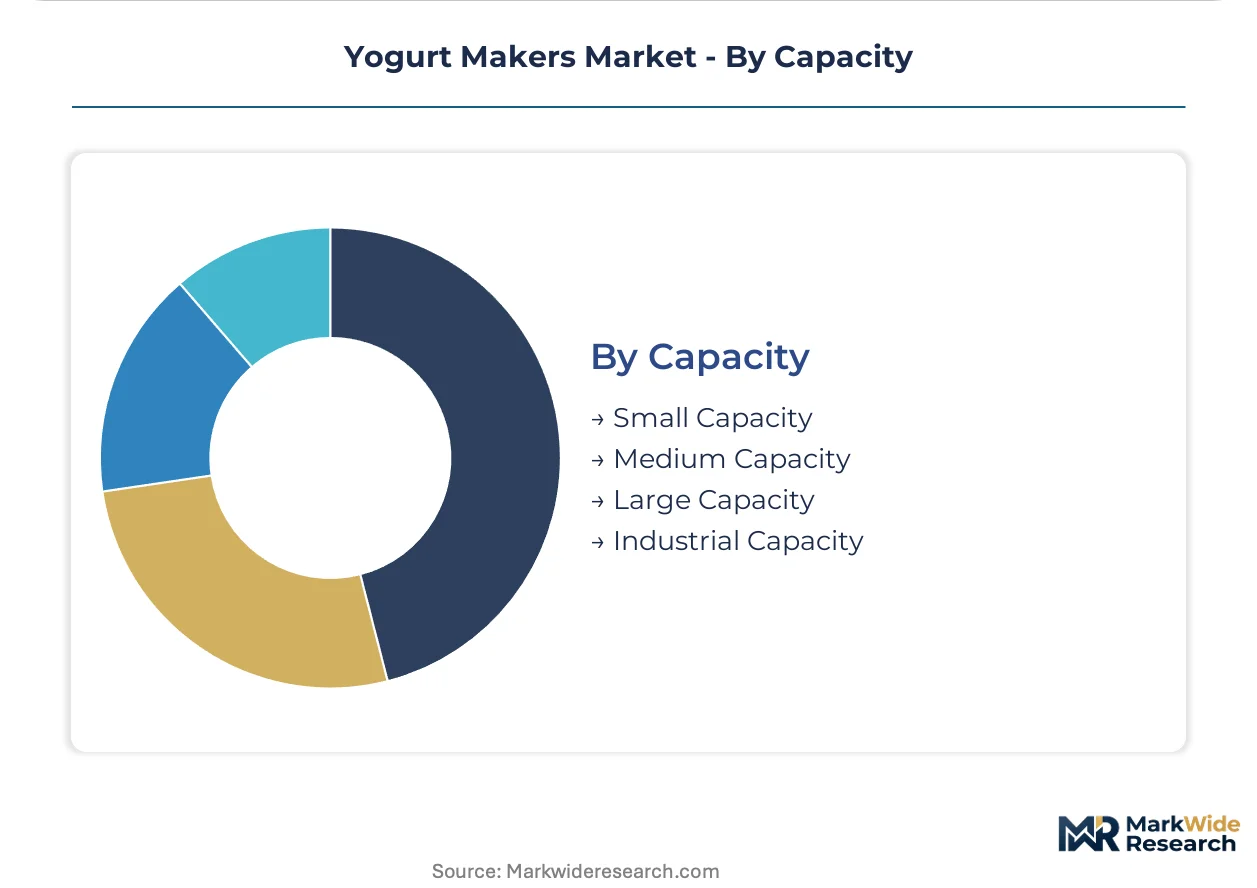
Capacity:
Customer type and application scale dictate capacity selection, with procurement patterns diverging between single-household batch sizes and production-scale fermentation.
- Small Capacity:0.5 to 1.0 liter vessels serve individual users and trial fermentation in compact urban kitchens.
- Medium Capacity:1.0 to 2.0 liter configurations balance family-sized batch production with countertop footprint constraints.
- Large Capacity:2.0 to 5.0 liter units target multi-person households and small commercial operations with moderate throughput needs.
- Industrial Capacity:Exceeding 5.0 liters, these systems employ stainless-steel fermentation chambers and programmable multi-stage temperature profiles for food service and artisanal production.
Medium capacity leads household penetration. Industrial capacity is gaining share fastest as commercial fermentation expands beyond traditional dairy infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese and South Korean households integrate yogurt makers into daily probiotic routines, while US and European consumers prioritize smart connectivity and energy efficiency in premium kitchen segments.
United States
Wi-Fi-enabled temperature logging and app-based recipe libraries drive premium kitchen segment demand. FDA food contact substance regulations govern plastic and silicone vessel components, extending product development timelines for new market entrants. Urban households in California and New York anchor electric unit adoption.
Germany
Energy-conscious consumers favor electric yogurt makers with sub-watt standby power controllers. EU Ecodesign directives mandate networked appliance efficiency thresholds, forcing heating element architecture redesigns. Stuttgart and Munich metropolitan kitchens concentrate demand for precision fermentation monitoring systems.
Japan
Compact countertop appliances anchor daily fermentation routines in Tokyo and Osaka metropolitan households. METI efficiency standards shape domestic appliance certification requirements. Kanto region urban density supports specialty retail channel expansion for premium smart units.
South Korea
Counter space constraints drive multi-function platform adoption integrating cheese-making and kefir modes. MFDS food contact material regulations govern fermentation vessel safety certifications. Seoul Capital Area households dominate compact appliance procurement patterns.
China
Stainless-steel fermentation vessel specialization captures domestic market share in tier-one cities. GB standards and SAMR market supervision frameworks regulate small appliance safety and energy labeling. Yangtze River Delta manufacturing clusters supply PTC heating elements to regional assemblers.
Yogurt Makers Market Competitive Environment
Capability concentration sits with electromechanical specialists possessing precision temperature control firmware expertise; scale advantage sits with broad-line home appliance manufacturers commanding mass retail shelf presence. The market structures around three archetypes: smart-connected platform developers, stainless-steel vessel specialists, and replacement part program operators. Dominant competitive moves include multi-function platform convergence and direct-to-consumer channel expansion bypassing traditional retail gatekeepers.
Among Asia-Pacific-based fabricators, Joyoung Co., Ltd exemplifies stainless-steel fermentation vessel specialization, while Panasonic occupies a position bridging consumer electronics heritage with kitchen appliance diversification. Euro Cuisine Inc. represents the aftermarket service archetype through replacement lid and jar programs. These three anchors illustrate how geographic origin and corporate structure shape competitive positioning without converging on identical capability investments.
| Leading Market Players |
|---|
| Euro Cuisine Inc. |
| Gourmia |
| Ningbo Hippo Electrical Appliance Co. |
| Hamilton Beach Brands |
| Cuisinart |
| Philips |
| Panasonic |
| TTK Prestige Ltd |
| Joyoung Co., Ltd |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta manufacturing clusters anchor global PTC heating element output, concentrating component supply in a corridor that grants incumbent assemblers substantial procurement leverage over mid-tier brands. This geographic density transmits directly into tiered pricing power across electric and multi-function yogurt maker categories.
Pricing Analysis
Long-term offtake contracts dominate procurement relationships for PTC ceramic elements and stainless-steel fermentation vessels, insulating volume purchasers from spot market volatility in raw material inputs. Three-tier pricing structure across premium, standard, and economy levels separates Wi-Fi-enabled smart units with replacement part subscriptions from basic thermal models and manual alternatives. Cost compression in economy-tier electric segments is intensifying because East Asian component suppliers are consolidating heating element fabrication capacity. Household purchasers in emerging markets exhibit the highest price sensitivity, while commercial food service operators prioritize batch reproducibility and NSF certification over unit acquisition cost.
Supply Chain Analysis
Upstream feedstock for PTC ceramics draws from rare earth processing facilities concentrated in China, with secondary sourcing from Japanese and South Korean precision ceramic specialists. Stainless-steel fermentation vessel fabrication rests on cold-rolled steel availability from Yangtze River Delta mills, while silicone food-contact seals hinge on certified polymer compounders in Germany and the United States. Single-source vulnerability concentrates in advanced temperature controller firmware, where specialized electromechanical engineering teams remain geographically clustered. Distribution runs through mass retail chains in North America, specialty kitchenware platforms in Japan, and direct-to-consumer channels for premium smart appliance brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The yogurt makers market sits in a cyclical recovery phase as post-pandemic home fermentation habits institutionalize into daily routines across urban Asian households. Replacement part subscription economics and right-to-repair legislative tailwinds are extending revenue visibility beyond hardware replacement cycles.
For Market Incumbents: Entrench aftermarket service moats by expanding replacement lid and jar program availability periods ahead of mandated right-to-repair compliance deadlines. Secure backward integration into PTC heating element supply through captive relationships with Yangtze River Delta ceramic fabricators, insulating margin structures from input cost volatility. Channel control through specialty retail partnerships in Japan and South Korea defends positioning against direct-to-consumer entrants.
For New Entrants and Emerging Players: Southeast Asian urban households outside established Tokyo-Seoul fermentation corridors present the most penetrable geography for compact multi-function platform introduction. Target commercial food service segments in North American metropolitan markets where HACCP documentation requirements create certification barriers that favor new specialist entrants over broad-line appliance brands. Direct-to-consumer launch with subscription-based vessel replacement programs bypasses mass retail slotting fee structures.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors electromechanical specialists with precision temperature control firmware expertise over broad-line manufacturers lacking fermentation-specific engineering depth. Long-term viability rests on capturing recurring revenue attachment through connected appliance platforms and replacement part ecosystems. Watch smart home interoperability standard adoption as the inflection indicator for platform consolidation versus fragmentation.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Function Platform Convergence | Captures counter space-constrained urban consumers in Seoul and Tokyo seeking appliance consolidation. |
| Direct-to-Consumer Channel Expansion | Bypasses mass retail gatekeepers for premium smart yogurt maker distribution in California and New York. |
| Replacement Part Subscription Programs | Transforms one-time hardware transactions into recurring revenue streams with Japanese household retention. |
| EU Ecodesign Compliance Redesign | Mandates sub-watt standby power controllers for networked appliances accessing German and French retail. |
| Precision Sensor Array Integration | Compresses performance gaps between domestic and small-commercial fermentation equipment for premium buyers. |
Study Parameters
Operator-level perspectives from appliance brand managers, specialty kitchenware retail buyers, PTC heating element procurement leads, fermentation vessel fabricators, and aftermarket service heads anchored the qualitative base. Primary interviews combined with secondary validation against customs records for small appliance trade flows, EU Ecodesign directive implementation databases, FDA food contact substance filings, and METI efficiency standard certifications. Bottom-up unit shipment modeling triangulated against top-down market value reconstruction across product type, end user, technology, and capacity dimensions.
Scenario-bracketing around regulatory implementation timelines and smart home adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, customer scale, thermal versus sensor-integrated technology platforms, and vessel capacity tiers. CAGRs derived from installed base replacement dynamics and first-time purchase penetration curves, with cross-validation against small appliance category spending patterns and urban household kitchen equipment upgrade cycles.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending indices and cross-border component logistics costs would shift the trajectory. Forecasts reflect documented assumptions regarding right-to-repair legislative rollout pace and smart home interoperability standard adoption. Cross-checking against specialty kitchenware retail audit data and small appliance customs clearance volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Sheet Metal Processing Equipment Market
Food Processing Equipment
Contact and Convective Dryers Market
Food Processing Equipment
Fish Cutting Machine Market
Food Processing Equipment
Walk-In Refrigerators & Freezers Market
Food Processing Equipment
Dry Ice Market
Food Processing Equipment
Oven Market
Food Processing Equipment
Vacuum Cooling Equipment Market
Food Processing Equipment
Global Automatic Mask Production Equipment Market
Food Processing Equipment
Mill Mixer Market
Food Processing Equipment
Freeze-Drying Equipment Market
Food Processing Equipment
Magnetic Grill Market
Food Processing Equipment
Craft Brewery Equipment Market
Food Processing Equipment
Food Sterilization Equipment Market
Food Processing Equipment
Food Ingredients Sterilization Market
Food Processing Equipment
Tangyuan Machine Market
Food Processing Equipment
Pea Protein Processing Equipment Market