
 Kebab Machine Market | 2026-2036
Kebab Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Kebab Machine Market Foresight
Buyer concentration across European quick-service chains is pivoting toward centralized procurement of automated kebab equipment for multi-site deployment. Kebab King leverages its manufacturing scale to supply high-volume rotating machines across Germany's dense döner shop network. Arican Industrial Kitchen anchors its position in Turkey through vertical integration into stainless steel fabrication for manual and electric grills. ROLLER GRILL competes on channel control, sustaining distribution partnerships with commercial kitchen dealers across France and Southern Europe.
A kebab machine is a purpose-built cooking apparatus designed to roast stacked, seasoned meat on a vertical rotisserie, typically employing electric heating elements or gas burners capable of sustaining temperatures between 150°C and 200°C for uniform exterior caramelization and controlled interior doneness. Electric rotating machines dominate commercial installations where energy efficiency and labor reduction carry premium value, while manual grills retain structural importance in traditional establishments and emerging markets where capital constraints shape procurement. Stainless steel construction commands the material segment due to hygiene mandates and durability requirements, though aluminum variants occupy niche positions in mobile food truck applications where weight reduction determines equipment selection.
Europe's Ecodesign Directive and REACH chemical compliance frameworks shape product standards for commercial cooking equipment, compelling manufacturers to eliminate hazardous surface coatings and document energy performance across operating cycles. The US FDA and NSF International standards govern food-contact surfaces and sanitation protocols, creating divergent certification requirements that fragment market access strategies between regulatory zones. Stakeholders must monitor evolving energy-efficiency thresholds and material compliance deadlines to align R&D roadmaps with procurement cycles.
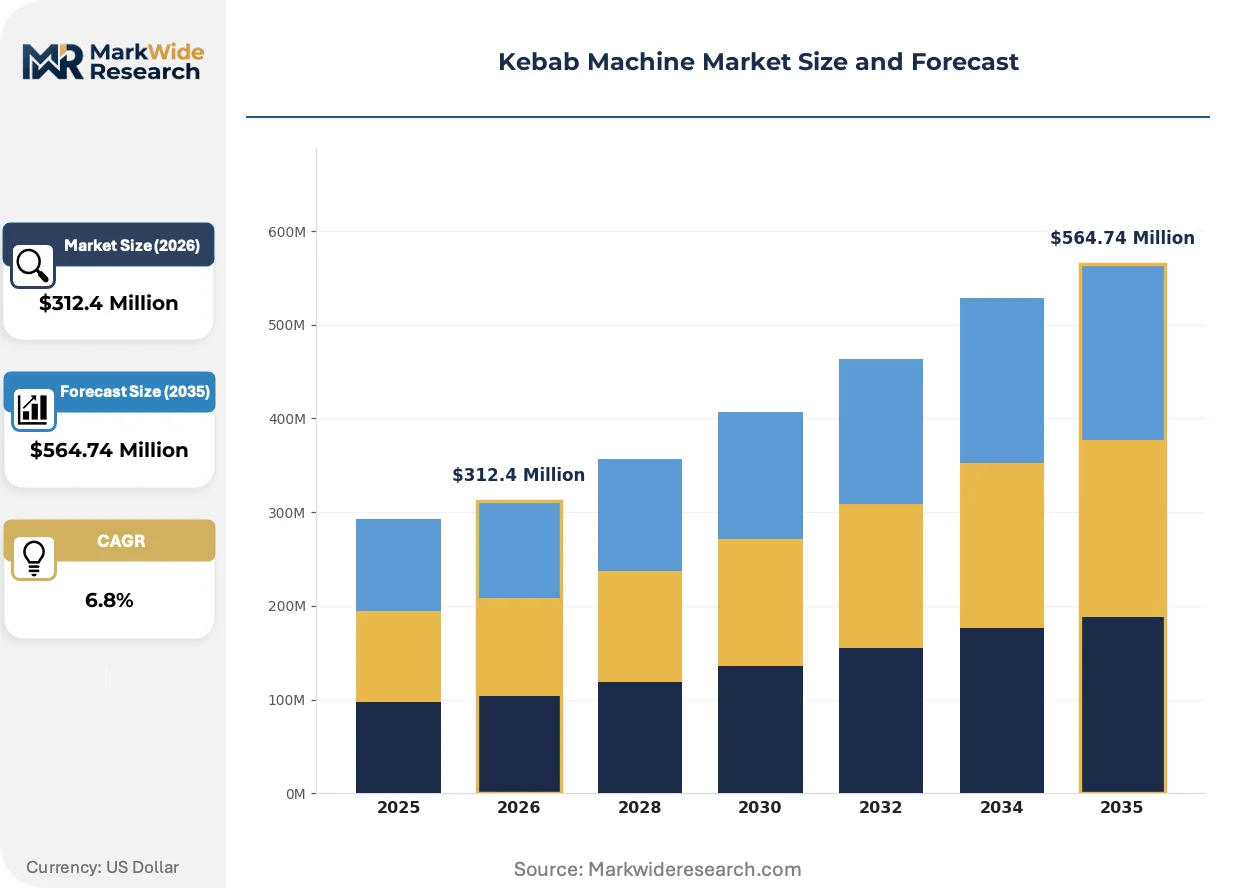
Market Dynamics
Europe's Ecodesign Directive is compressing replacement cycles for gas-fired kebab equipment, forcing commercial kitchens toward electric rotating machines with documented energy performance across operating cycles. This regulatory pressure is restructuring procurement patterns across quick-service restaurant chains.
Growth Catalysts
- REACH chemical compliance:Mandates for eliminating hazardous surface coatings in commercial cooking equipment are accelerating stainless steel adoption across European commercial kitchens.
- Quick-service restaurant chains:Centralized procurement of automated kebab equipment for multi-site deployment is standardizing equipment specifications across franchise networks.
- Berlin-Hamburg supplier density:Germany's dense döner shop network sustains demand for high-volume rotating machines with rapid service turnaround requirements.
Market Restraints
- Stainless steel input volatility:Raw material price swings for food-grade stainless steel compress margins for equipment fabricators serving price-sensitive buyers.
- Electric infrastructure gaps:Emerging markets with unreliable grid capacity limit deployment of electric rotating machines despite efficiency advantages.
- Manual grill substitution:Traditional establishments in Turkey and Eastern Europe retain capital-light manual equipment, slowing premium product penetration.
Strategic Opportunities
- Mobile food truck segment:Aluminum-variant kebab machines addressing weight reduction requirements remain underdeveloped relative to stationary commercial installations.
- NSF International certification:US food-contact surface standards create a compliance pathway for European manufacturers seeking North American market access.
- IoT-enabled temperature monitoring:Convergence of rotisserie automation with connected kitchen platforms opens service revenue streams beyond equipment sales.
Industry Challenges
- Multi-jurisdiction certification timelines:Divergent FDA, NSF International, and Ecodesign documentation requirements extend product launch cycles by 8-14 months.
- Gas-to-electric retrofit complexity:Legacy kitchen ventilation and electrical infrastructure in established döner shops complicates equipment replacement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kebab Machine Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Grills, Manual Grills, Rotating Machines, Skewers End User: Restaurants, Food Trucks, Catering Services, Home Users Material: Stainless Steel, Aluminum, Cast Iron, Non-stick Coating Size: Small, Medium, Large, Extra Large |
| Companies Covered | Kebab King, Arican Industrial Kitchen, Kebapchef, Hakka Brothers, ROLLER GRILL, CKE Holdings Sdn Bhd, Spinning Grillers, Kebap Makinesi, ELANGRILL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kebab Machine Market Shifts & Advancements
Automation in commercial kebab production is advancing through three distinct vectors: equipment electrification, connected kitchen integration, and procurement centralization. These shifts are compressing the traditional equipment replacement cycle while elevating performance documentation requirements.
Infrared heating elements paired with precision temperature sensors are consolidating control over the caramelization process in high-throughput installations. Quick-service chains with standardized menu specifications are adopting these systems fastest. The technology is consolidating vendor relationships around suppliers capable of delivering calibrated performance guarantees rather than standalone hardware.
Europe's Ecodesign Directive and F-Gas Regulation are mandating energy-performance documentation and refrigerant containment standards for commercial cooking equipment with integrated cooling functions. Manufacturers must now submit lifecycle energy consumption data to maintain market access. Electric rotating machines with certified efficiency ratings command preferential placement in chain procurement frameworks.
Buyer concentration among multi-site operators is fragmenting the traditional dealer-distributor channel. Direct manufacturer relationships with centralized procurement teams are displacing regional equipment distributors for volume accounts. Germany's döner franchise networks exhibit this pattern most visibly, with technical specification authority shifting from shop owners to chain-level facilities managers.
Kebab Machine Market Segmentation
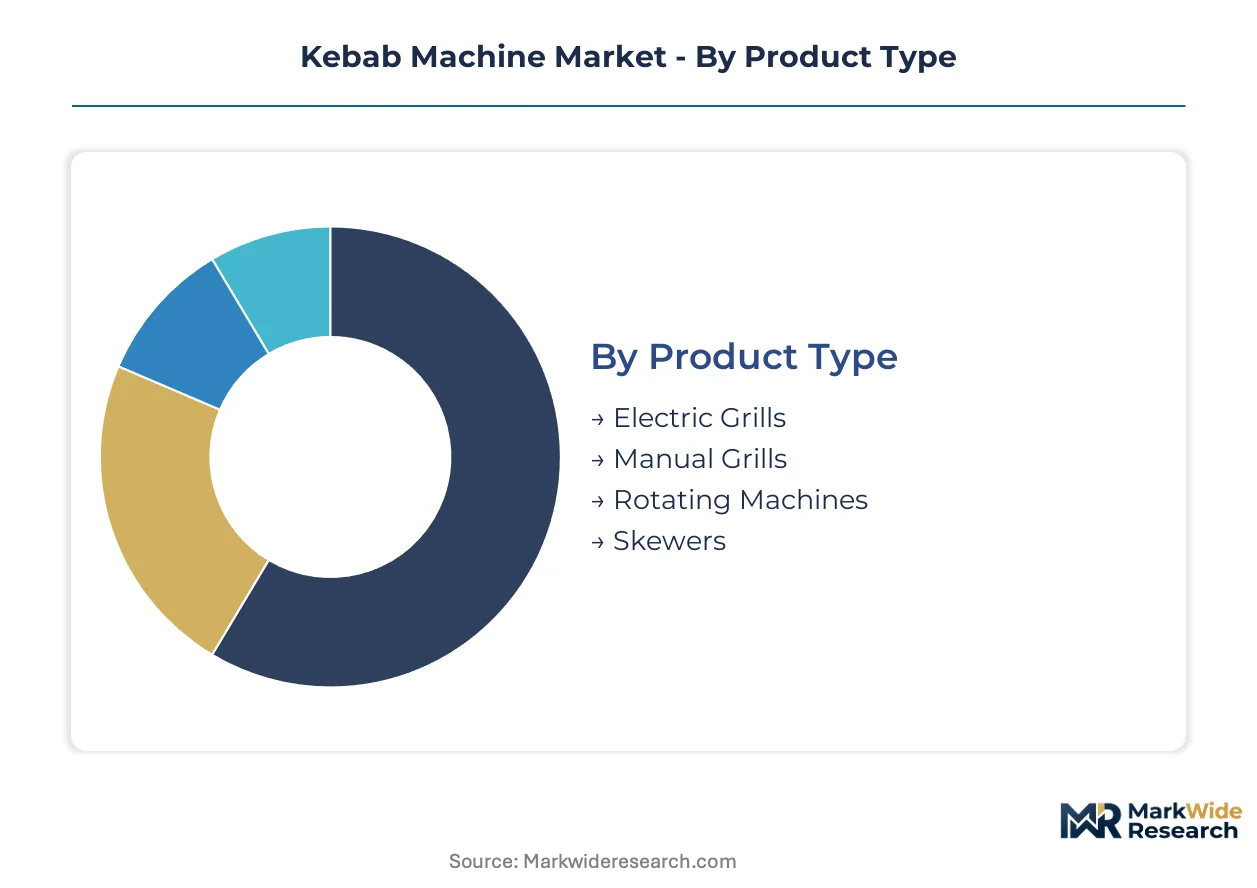
Equipment segmentation in the kebab machine market tracks divergent upgrade cycles across commercial and consumer tiers. Replacement decisions vary sharply by power source, mobility requirements, and kitchen infrastructure constraints.
Product Type:
Regulatory pressure on energy efficiency is compressing replacement timelines for gas-fired equipment and accelerating procurement of electric alternatives.
- Rotating Machines:Vertical rotisserie systems with automated rotation mechanisms sustain temperatures between 150°C and 200°C for uniform caramelization. Quick-service chains in Germany's Berlin-Hamburg corridor specify these for rapid throughput in high-volume döner operations, though gas-to-electric retrofit complexity slows adoption in legacy kitchens.
- Electric Grills:Stationary heating elements with precision temperature control deliver documented energy performance required by Europe's Ecodesign Directive. Centralized procurement teams at multi-site restaurant chains favor these for standardized franchise deployments where efficiency certification carries compliance weight.
- Manual Grills:Capital-light equipment retains dominance in Turkey and Eastern European traditional establishments where labor costs remain below automation thresholds.
- Skewers:Hand-operated vertical spits serve small-scale vendors and home users with minimal infrastructure requirements.
Rotating machines sit at the top of the volume ranking, with electric grills climbing the fastest as regulatory deadlines approach.
End User:
Customer concentration patterns split between stationary commercial installations and mobile food service operations with divergent power and weight priorities.
- Restaurants:Fixed commercial kitchens with established ventilation infrastructure represent the core revenue base for high-capacity equipment. Germany's dense döner shop network sustains demand for machines with rapid service turnaround and NSF International certification for potential North American expansion.
- Food Trucks:Mobile operators prioritize aluminum-variant machines addressing weight reduction requirements and electrical load constraints. This segment remains underdeveloped relative to stationary installations, creating white space for purpose-built lightweight equipment.
- Catering Services:Event-based operators require portable equipment with rapid setup capabilities and dual fuel flexibility for venues with unreliable grid access.
- Home Users:Small-capacity electric units serve enthusiast consumers with countertop footprint limitations and occasional-use duty cycles.
Restaurants command the installed base by revenue, while food trucks are expanding most quickly as mobile food service regulations liberalize across European cities.
Material:
Surface composition decisions trade off hygiene mandates, thermal performance, and procurement cost sensitivity across end-use tiers.
- Stainless Steel:Food-grade 304 and 316 alloys dominate commercial installations due to REACH chemical compliance requirements and durability under continuous operation. European Ecodesign Directive enforcement has eliminated hazardous coating alternatives, consolidating specification authority around bare metal fabrication.
- Aluminum:Weight advantages position this material for mobile food truck applications where payload restrictions determine equipment selection, though thermal mass limitations reduce heat retention versus steel alternatives.
- Cast Iron:Traditional establishments in Turkey favor this material for heat retention and searing performance, despite higher maintenance requirements and corrosion susceptibility.
- Non-stick Coating:Consumer-grade applications use ceramic or PTFE surfaces for ease of cleaning, though REACH restrictions on perfluorinated compounds constrain European market access for coated variants.
Stainless steel leads procurement volumes by a substantial margin, with aluminum gaining share fastest in mobile application development.
Size:
Capacity scaling follows kitchen footprint constraints and peak demand throughput requirements across establishment types.
- Large:High-output machines with extended vertical spits serve quick-service chains and high-traffic urban locations where queue management demands continuous production capacity.
- Medium:Mid-scale equipment balances throughput and space efficiency for independent restaurants with moderate daily volume requirements.
- Small:Compact units fit constrained urban kitchen layouts and cater to specialty operators with limited menu breadth.
- Extra Large:Industrial-scale systems address centralized production facilities supplying multiple retail locations or large-scale catering operations.
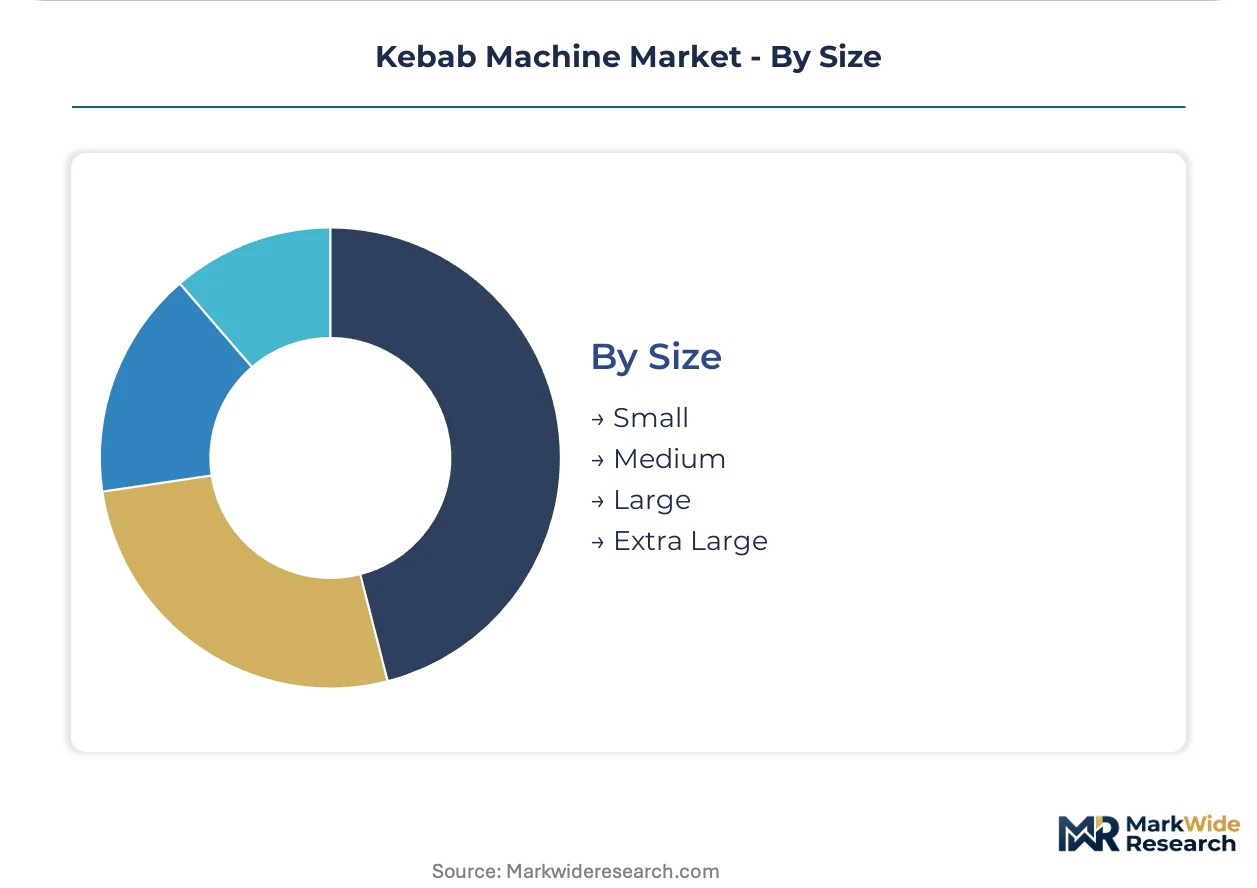
Large-format equipment dominates commercial revenue, with medium-sized machines showing the steepest expansion trajectory among independent restaurant openings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's döner kebab infrastructure outpaces Turkey's domestic equipment density, while France and the United Kingdom build comparable quick-service networks with divergent regulatory compliance timelines.
Germany
Berlin and Hamburg harbor Europe's densest döner shop concentrations, driving demand for high-throughput rotating machines with rapid service turnaround. The Ecodesign Directive mandates documented energy performance across operating cycles, compressing replacement timelines for legacy gas-fired equipment. Equipment procurement authority concentrates with chain-level facilities managers across North Rhine-Westphalia and Bavaria franchise networks.
Turkey
Traditional establishments in Istanbul and Ankara retain manual grills where labor costs remain below automation thresholds, constraining electric machine penetration. The country's national standards body enforces food-contact surface regulations aligned with EU REACH frameworks. Arican Industrial Kitchen anchors domestic supply through captive stainless steel fabrication serving Anatolia's independent restaurant base.
France
Quick-service chains in Paris and Lyon specify electric rotating machines with certified efficiency ratings for centralized franchise procurement. The F-Gas Regulation imposes refrigerant containment standards on equipment with integrated cooling functions. ROLLER GRILL sustains distribution partnerships with commercial kitchen dealers across the Île-de-France and Provence-Alpes-Côte d'Azur corridors.
United Kingdom
London's dense urban kebab shop network sustains demand for medium-format equipment balancing throughput and constrained kitchen footprints. The Food Standards Agency enforces hygiene mandates comparable to NSF International protocols, creating compliance pathways for European manufacturers. Manchester and Birmingham clusters exhibit fastest expansion among independent restaurant openings.
United States
Quick-service chains in New York and Los Angeles pursue NSF International certification for food-contact surfaces to unlock commercial kitchen procurement. FDA standards govern sanitation protocols divergent from European frameworks, fragmenting market access strategies. Chicago and Houston represent emerging demand centers as Mediterranean fast-casual formats expand beyond coastal metros.
Kebab Machine Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across equipment fabrication tiers. The vendor base clusters around three strategic archetypes: scale-driven manufacturers serving high-volume chain accounts, vertically integrated fabricators controlling stainless steel supply, and channel-specialized distributors sustaining dealer relationships. Competitive moves concentrate on geographic expansion into underserved regulatory zones and portfolio diversification toward IoT-enabled temperature monitoring systems.
Among Germany-based suppliers, Kebab King exemplifies the scale-driven archetype serving dense döner networks, while ROLLER GRILL occupies the channel-specialized tier with sustained dealer partnerships across Southern Europe. Turkey's Arican Industrial Kitchen represents vertical integration through captive stainless steel fabrication, anchoring domestic supply against import competition.
| Leading Market Players |
|---|
| Kebab King |
| Arican Industrial Kitchen |
| Kebapchef |
| Hakka Brothers |
| ROLLER GRILL |
| CKE Holdings Sdn Bhd |
| Spinning Grillers |
| Kebap Makinesi |
| ELANGRILL |
| Others |
Supply & Pricing Matrix
Skilled stainless steel fabricators concentrated in Turkey's Anatolia region anchor labor-cost differentials that widen pricing-tier spreads between European-manufactured electric rotating machines and import alternatives from lower-wage fabrication centers. This workforce geography compresses margins for Germany-based suppliers serving price-sensitive independent döner shops while sustaining premium positioning for Ecodesign-certified equipment in chain procurement frameworks.
Pricing Analysis
Capacity additions in China's commercial cooking equipment sector are reshaping price floors for economy-tier manual grills across Eastern European markets. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling. Pricing pressure stems from raw material volatility in food-grade stainless steel, compressing fabricator margins most acutely in the economy tier where Turkish imports compete aggressively. Quick-service chain procurement teams exhibit lowest price sensitivity due to centralized specification authority, while independent restaurant owners in Berlin and Hamburg remain highly cost-responsive.
Supply Chain Analysis
Dual-sourcing requirements mandated by European quick-service chains are fragmenting supplier relationships across Germany, Turkey, and China. Food-grade stainless steel draws from Turkish mills and Chinese export fabricators, with electric heating elements and precision temperature sensors sourced from German and Italian component specialists. Single-source vulnerability in specialized motor drives for automated rotation mechanisms creates procurement risk during supplier qualification transitions. Distribution runs through commercial kitchen equipment dealers in France and direct manufacturer relationships in Germany's dense franchise networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Turkey's lower fabrication costs and Germany's regulatory premium for Ecodesign-certified equipment. The spread between these cost bases creates margin capture opportunities for manufacturers with multi-country production footprints.
For Market Incumbents: Lock in chain-level procurement relationships through certified efficiency documentation and IoT-enabled service bundling. Defend against Turkish import competition by deepening captive supply of stainless steel components and accelerating NSF International certification for North American market access. Channel control through dealer partnerships in Southern Europe remains a critical retention lever.
For New Entrants and Emerging Players: E-commerce direct-to-restaurant platforms offer the lowest-friction entry path for lightweight aluminum-variant machines targeting mobile food truck operators. White space concentrates in underdeveloped North American markets where Mediterranean fast-casual formats expand beyond coastal metros. Pursue NSF International certification as the primary qualification threshold for commercial kitchen procurement.
For Investors and Strategic Acquirers: Commercial kitchen equipment conglomerates are the most active acquirer in this space, seeking bolt-on automation capabilities. Five-to-ten year viability hinges on electrification transition completion and connected kitchen platform integration. Monitor Ecodesign Directive enforcement intensity as the signal for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| IoT-Enabled Temperature Monitoring Integration | Opens recurring service revenue streams beyond equipment sales for ROLLER GRILL and Kebab King. |
| NSF International Certification Investment | Unlocks commercial kitchen procurement access across New York and Los Angeles quick-service chains. |
| Aluminum-Variant Product Line Expansion | Captures mobile food truck demand in European cities liberalizing street vending regulations. |
| Backward Integration into Stainless Steel Fabrication | Mirrors Arican Industrial Kitchen's Turkish model to insulate margins from raw material volatility. |
| Direct Manufacturer-Chain Procurement Relationships | Displaces regional dealers in Germany's Berlin-Hamburg döner franchise networks. |
Research Methodology
Coverage spans Germany, Turkey, France, the United Kingdom, and the United States, with primary inputs from each market gathered through structured interviews with quick-service chain facilities managers, commercial kitchen equipment dealers, stainless steel fabricators, and regulatory compliance officers. Secondary validation drew from Ecodesign Directive implementation reports, NSF International certification databases, FDA food-contact surface standards, and customs trade data on commercial cooking equipment imports. Bottom-up equipment shipment estimates triangulated against top-down restaurant opening and replacement cycle data.
Rate-of-change decomposition anchored the analytical framework across the projection horizon, with CAGRs derived from segment-level growth trajectories. Modeling dimensions included power source type, end-user category, material composition, equipment size tier, and regional regulatory cluster. Industry-specific forecast inputs incorporated Ecodesign Directive compliance deadlines and quick-service chain expansion pipelines.
Raw material price swings, regulatory enforcement delays, and electric infrastructure buildout pace are the dominant revision risks to the outlook. Deviation in stainless steel input costs would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Tunnel Oven Market
Food Processing Equipment
Griddle Market
Food Processing Equipment
Oceania Commercial Ice Machine Market
Food Processing Equipment
Commercial Mixer Market
Food Processing Equipment
Crossflow Wine Filters Market
Food Processing Equipment
Brewery Heat Exchanger Market
Food Processing Equipment
Mixing Vessels Market
Food Processing Equipment
Fish Filleting Machine Market
Food Processing Equipment
Brewing Equipment Market
Food Processing Equipment
Cookers and Ovens Market
Food Processing Equipment
Semi-Auto Egg Tart Forming Machine Market
Food Processing Equipment
Edible Oil Extracting Machine Market
Food Processing Equipment
Loss-In-Weight Feeder Market
Food Processing Equipment
Food Automation Market
Food Processing Equipment
Food Processor Market
Food Processing Equipment
Commercial Beverage Blender Market