
 China Industrial Food and Beverages Filtration System Market | 2026-2036
China Industrial Food and Beverages Filtration System Market Size, Share, and Industry Trends Forecast 2026-2036
China Industrial Food and Beverages Filtration System Market Insights
A shift from imported membrane assemblies toward domestic multi-source supply is hardening across China's filtration procurement landscape. Alfa Laval sustains technology leadership in dairy crossflow systems through its Shanghai engineering center. Jiangsu Grandfort Purification Equipment Co., Ltd. anchors mid-market membrane module production with localized hollow-fiber manufacturing in Taizhou. Eaton competes on hydraulic filtration integration for beverage bottling lines, leveraging its Suzhou distribution hub.
China Industrial Food and Beverages Filtration Systems comprise engineered membrane, depth, and surface filtration assemblies designed to remove particulates, microorganisms, and dissolved solids from process streams, typically operating at pressures from 0.1 to 40 bar depending on technology. Reverse osmosis systems achieve salt rejection rates exceeding 99% for ingredient water preparation in soft drink and brewing applications. Membrane filtration dominates capital expenditure among product types, with ultrafiltration gaining share in dairy protein fractionation where 10-100 kDa molecular weight cutoffs enable selective permeation. Crossflow filtration leads technology adoption in continuous beverage processing, while batch filtration retains installed base in smaller juice clarification operations where operational simplicity outweighs throughput optimization.
China's National Health Commission and SAMR enforce GB 5749 drinking water standards and food contact material regulations that mandate log-reduction performance for pathogen removal in beverage production. MIIT's industrial equipment upgrade directives incentivize filtration energy efficiency improvements through its green manufacturing program. NMPA oversight of food-grade polymer membranes adds compliance layers for imported components. Stakeholders must monitor evolving GB standard revisions and provincial environmental discharge rules to align capital planning with compliance timelines.
Market Dynamics
Membrane technology substitution is compressing installed base economics across China's dairy and beverage processing corridors, forcing incumbent equipment suppliers to reconfigure service revenue models around consumables and technical support rather than capital sales alone.
Growth Catalysts
- GB 5749 Drinking Water Standards:China's National Health Commission mandates stricter microbial log-reduction thresholds, compelling beverage bottlers to upgrade membrane and UV filtration trains in Shanghai and Jiangsu facilities.
- Whey Protein Fractionation:Dairy cooperatives in Shandong deploy ultrafiltration with 10-100 kDa molecular weight cutoffs to capture premium protein isolates for sports nutrition exports.
- Yangtze River Delta Cluster Density:Proximity of beverage conglomerates to membrane engineering centers in Taizhou reduces commissioning cycles and spare parts lead times.
Market Restraints
- Polymer Membrane Import Dependency:Food-grade PVDF and PES hollow-fiber substrates remain concentrated among Japanese and German specialty chemical suppliers, exposing processors to currency volatility and shipping disruptions.
- Energy Cost Escalation:Reverse osmosis systems operating at 15-40 bar for ingredient water preparation face margin pressure from industrial electricity tariffs in coastal provinces.
- Crossflow System Footprint Requirements:Continuous processing configurations demand floor space that retrofit plants in legacy dairy infrastructure cannot accommodate without structural modification.
Strategic Opportunities
- Hebei Province Dairy Expansion:Greenfield processing complexes outside Beijing offer membrane filtration integrators access to uncaptured whey concentration and milk standardization demand.
- MIIT Green Manufacturing Incentives:Energy efficiency improvement subsidies for filtration equipment upgrades create procurement acceleration windows for compliant system vendors.
- Membrane-Ceramic Hybrid Configurations:Convergence of polymeric ultrafiltration with alumina microfiltration pre-treatment extends module lifespan in high-solids juice clarification applications.
Industry Challenges
- Membrane Fouling Expertise Gap:Plant operators lack training in transmembrane pressure optimization and chemical cleaning protocol selection, reducing realized throughput below design specifications.
- NMPA Food-Contact Polymer Certification Timelines:Imported membrane module approvals stretch 18-24 months, delaying technology refresh cycles for multinational beverage brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Industrial Food and Beverages Filtration System Market |
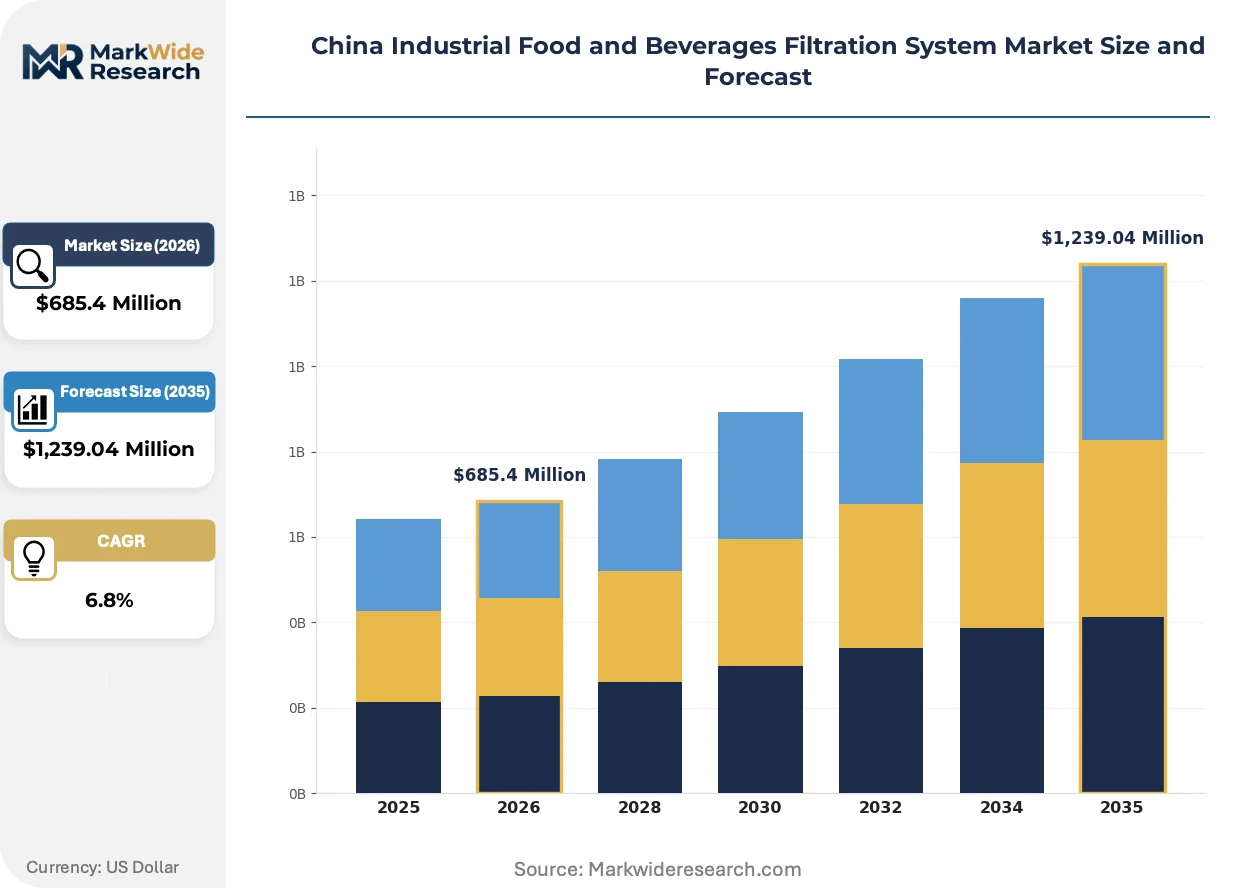
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane Filtration, Microfiltration, Ultrafiltration, Reverse Osmosis End User: Food Processing, Beverage Production, Dairy Industry, Juice Manufacturing Technology: Crossflow Filtration, Batch Filtration, Depth Filtration, Carbon Filtration Application: Water Purification, Oil Recovery, Product Clarification, Flavor Extraction |
| Companies Covered | Alfa Laval, GEA Group, Parker Hannifin, Eaton, 3M, Pall Corporation, Donaldson, Sartorius, Jiangsu Grandfort Purification Equipment Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Industrial Food and Beverages Filtration System Market Trends and Innovations
Filtration technology trajectories in China's food and beverage sector center on energy intensity reduction, regulatory compliance automation, and procurement model restructuring that separates equipment ownership from performance outcomes.
Ceramic membrane modules with alumina and titania substrates are absorbing fouling-intensive duties in high-solids fruit juice and plant protein clarification where polymeric membranes degrade rapidly. Large beverage conglomerates in Jiangsu pilot these systems for 8,000+ hour cleaning intervals. This durability premium is absorbing maintenance labor costs and compressed CIP chemical consumption that previously eroded operating margins in seasonal processing campaigns.
MIIT's industrial equipment upgrade directives now embed energy efficiency benchmarking as a procurement gate for green manufacturing program eligibility. Filtration system vendors must document specific kilowatt-hour per cubic meter metrics to qualify for provincial subsidy pools. Dairy processors in Shandong respond by specifying variable-frequency drive retrofits and permeate recirculation loops in new crossflow installations.
Equipment-as-performance contracts are displacing capital purchase models among mid-scale beverage bottlers in the Yangtze River Delta. Third-party filtration service providers retain membrane asset ownership and charge per-liter permeate fees, transferring fouling risk and module replacement timing away from plant balance sheets. This arrangement concentrates most visibly in seasonal juice operations where utilization volatility punishes fixed-cost depreciation schedules.
China Industrial Food and Beverages Filtration System Market Segmentation
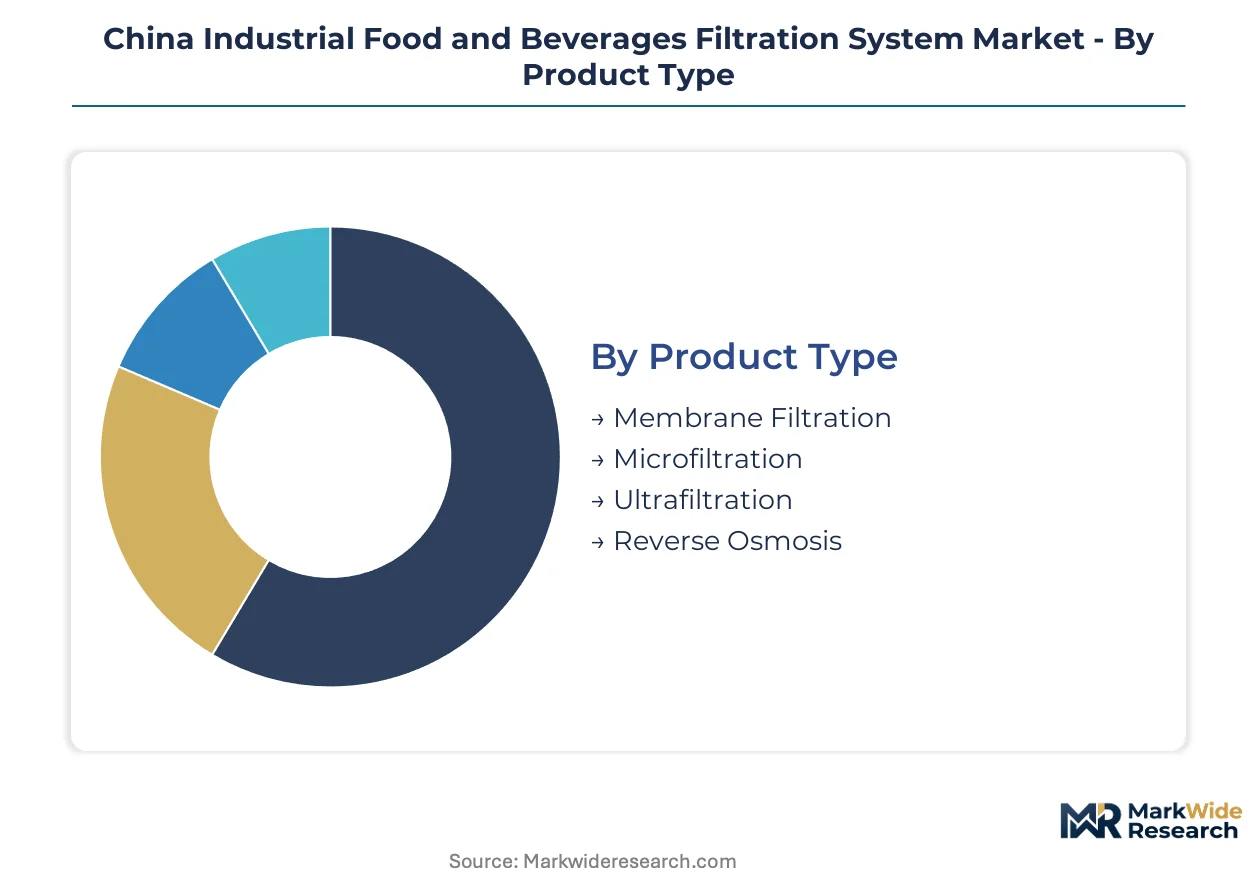
Filtration procurement in China's food and beverage sector fragments across multiple technical dimensions, each carrying distinct regulatory burdens and performance specifications. Procurement committees evaluate membrane pore ratings, flow configurations, and end-use contamination risks when aligning capital expenditure with GB standard compliance and operational throughput targets.
Product Type:
Membrane Filtration commands the most stringent NMPA food-contact polymer certification pathways, with hollow-fiber substrates requiring 18-24 month approval timelines that shape vendor selection criteria.
- Membrane Filtration:Polymeric and ceramic barrier systems operating at 0.1-40 bar pressure ranges achieve pathogen log-reduction for dairy standardization and beverage ingredient water. Dairy cooperatives in Shandong prioritize ultrafiltration modules with 10-100 kDa molecular weight cutoffs for whey protein fractionation, where NMPA polymer approvals and MIIT green manufacturing eligibility determine supplier shortlists.
- Reverse Osmosis:High-pressure configurations at 15-40 bar deliver salt rejection exceeding 99% for soft drink and brewing applications. Beverage bottlers in the Yangtze River Delta specify these systems for GB 5749 drinking water compliance, though industrial electricity tariffs in coastal provinces compress operating margins.
- Microfiltration:0.1-10 micron pore ratings remove suspended solids and bacteria in juice clarification pre-treatment.
- Ultrafiltration:1-100 nanometer separation range enables selective protein and colloid retention in dairy processing.
Membrane Filtration sits at the top of the volume ranking, with Reverse Osmosis climbing the fastest.
End User:
Customer scale and processing intensity separate capital expenditure tiers, with large conglomerates absorbing crossflow system footprints while smaller operators retain batch configurations.
- Dairy Industry:Whey concentration and milk standardization operations in Hebei and Shandong deploy ultrafiltration trains for protein isolate recovery. Greenfield complexes outside Beijing attract membrane integrators seeking uncaptured demand, while legacy plants face structural constraints on continuous processing retrofits.
- Beverage Production:Conglomerates clustered around Shanghai and Jiangsu processing hubs prioritize membrane filtration for ingredient water preparation and final product clarity. GB 5749 microbial thresholds compel UV and membrane train upgrades, with proximity to Taizhou engineering centers reducing commissioning cycles.
- Food Processing:Edible oil and sauce clarification applications favor depth and carbon filtration for color and odor removal.
- Juice Manufacturing:Seasonal operations with utilization volatility increasingly adopt equipment-as-performance contracts to transfer fouling risk.
Dairy Industry leads capital deployment, with Beverage Production expanding most quickly.
Technology:
Flow configuration determines labor intensity and cleaning chemical consumption, with continuous modes favored where throughput optimization outweighs operational simplicity.
- Crossflow Filtration:Tangential flow patterns minimize membrane fouling through shear velocity at the surface, enabling extended operation between chemical cleaning intervals. Large beverage processors in Jiangsu pilot ceramic alumina configurations achieving 8,000+ hour cleaning cycles, absorbing maintenance labor costs that previously eroded margins in seasonal campaigns.
- Batch Filtration:Dead-end configurations retain installed base in smaller juice clarification operations where floor space constraints and operational simplicity outweigh throughput optimization. Legacy dairy infrastructure across Shandong maintains these systems where structural modification for crossflow retrofit proves cost-prohibitive.
- Depth Filtration:Graduated density media capture particulates through tortuous path mechanisms in high-solids applications.
- Carbon Filtration:Activated carbon beds adsorb organic compounds and chlorine for flavor protection in bottled water and brewing.
Crossflow Filtration dominates new installations, with ceramic hybrid configurations gaining share fastest.
Application:
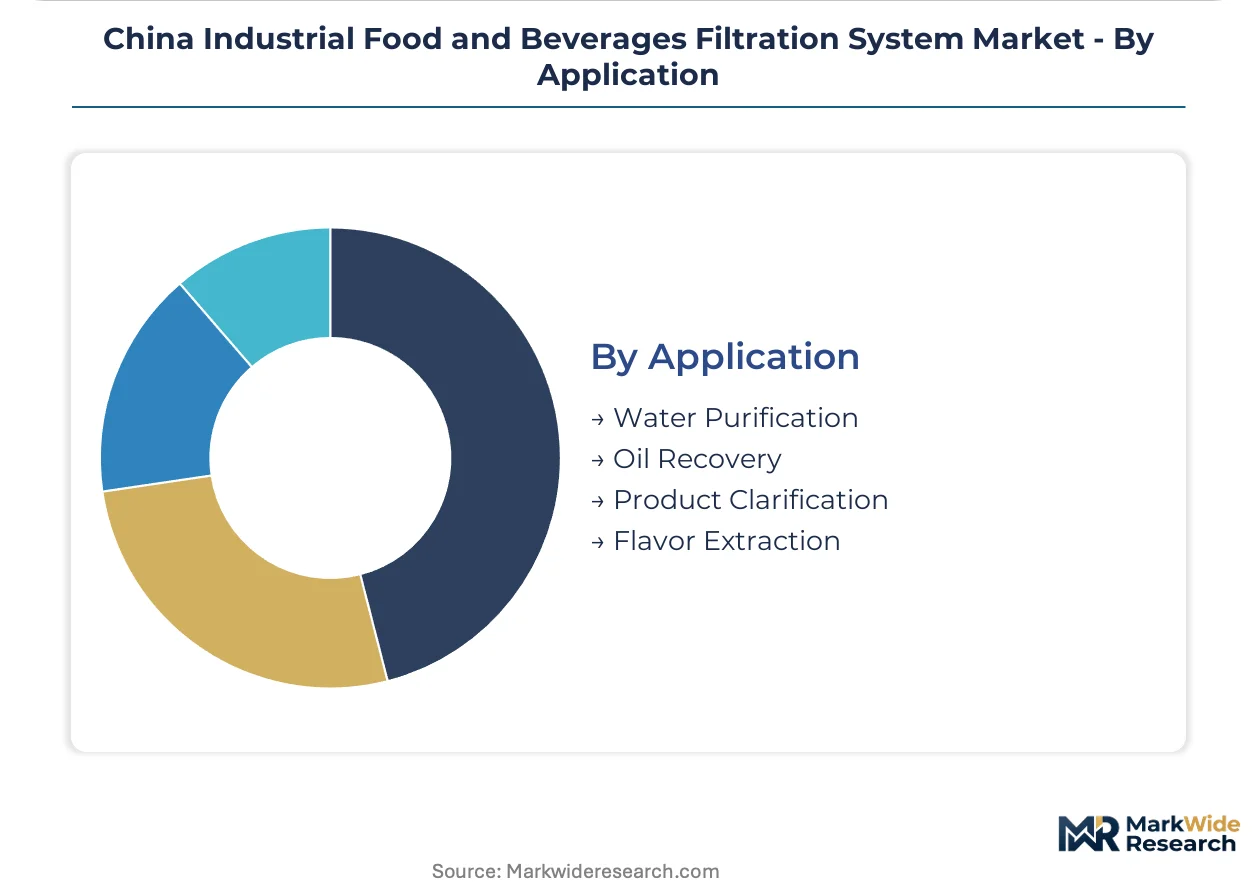
Contaminant type and removal specification separate procurement specifications, with microbial safety applications commanding premium membrane grades over clarity or recovery objectives.
- Water Purification:Ingredient water preparation for soft drinks, brewing, and dairy reconstitution requires multi-stage membrane trains combining microfiltration, ultrafiltration, and reverse osmosis. GB 5749 compliance mandates documented log-reduction performance, with SAMR enforcement intensifying upgrade cycles at Shanghai-area bottling facilities.
- Product Clarification:Juice and plant protein streams with high suspended solids content accelerate membrane fouling, driving adoption of ceramic-microfiltration pre-treatment before polymeric ultrafiltration. Jiangsu processors evaluate alumina-titania hybrid configurations to extend module lifespan and reduce CIP chemical consumption.
- Oil Recovery:Edible oil processing employs pressure-driven membrane systems for degumming and refining efficiency.
- Flavor Extraction:Selective permeation concentrates aromatic compounds in beverage and ingredient applications.
Water Purification anchors procurement volume, with Product Clarification showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping filtration system deployment as processors migrate toward provinces offering faster NMPA certification timelines and MIIT green manufacturing subsidies, compressing commissioning cycles for membrane-intensive dairy and beverage operations.
Shandong Province
Dairy cooperatives deploy ultrafiltration trains for whey protein fractionation targeting sports nutrition exports. GB standards for food contact materials mandate 18-24 month polymer membrane approval windows, pushing processors toward domestic hollow-fiber sourcing. The Jinan-Qingdao corridor concentrates membrane engineering talent and spare parts distribution for Shandong's expanding whey concentration capacity.
Jiangsu Province
Beverage conglomerates cluster around Taizhou membrane manufacturing centers to reduce lead times on polymeric module replacement. MIIT green manufacturing incentives reward documented kilowatt-hour efficiency metrics in new crossflow installations. The Suzhou-Nantong processing belt hosts pilot ceramic alumina configurations achieving extended cleaning intervals for high-solids juice clarification.
Hebei Province
Greenfield dairy complexes outside Beijing attract membrane integrators seeking uncaptured milk standardization demand. SAMR enforcement of GB 5749 drinking water thresholds compels multi-stage filtration train upgrades. The Shijiazhuang-Baoding corridor offers floor space advantages for continuous processing configurations that legacy coastal plants cannot accommodate.
Shanghai Municipality
Beverage bottlers face compressed margins from industrial electricity tariffs affecting reverse osmosis operations at 15-40 bar pressures. Proximity to Yangtze River Delta engineering centers enables rapid commissioning of membrane-UV hybrid systems for microbial log-reduction compliance. The Pudong-Minhang industrial zone concentrates equipment-as-performance contract providers transferring fouling risk from plant balance sheets.
China Industrial Food and Beverages Filtration System Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue ceramic-polymer hybrid configurations and outcome-based service models. The supplier base stratifies across three maturity tiers: multinational engineering centers with localized R&D, domestic hollow-fiber manufacturers with NMPA certification advantages, and third-party filtration service providers retaining membrane asset ownership. Dominant competitive moves include geographic co-location with Yangtze River Delta processing clusters and vertical integration into food-grade polymer substrate production.
Within the multinational tier, Alfa Laval and GEA Group exemplify engineering-center localization strategies, anchoring technology leadership through Shanghai-based application development. Jiangsu Grandfort Purification Equipment Co., Ltd. occupies a position among domestic membrane module fabricators leveraging Taizhou manufacturing proximity to reduce commissioning cycles. Eaton represents the hydraulic filtration integration archetype, with Suzhou distribution infrastructure supporting beverage bottling line deployments. These three players illustrate the competitive spectrum from premium-tier technology licensing to mid-market localized production and distribution-centric service models.
| Leading Market Players |
|---|
| Alfa Laval |
| GEA Group |
| Parker Hannifin |
| Eaton |
| 3M |
| Pall Corporation |
| Donaldson |
| Sartorius |
| Jiangsu Grandfort Purification Equipment Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
PVDF resin price indices from Japanese specialty chemical suppliers cascade through membrane module fabrication into three-tier pricing structures across premium, standard, and economy levels, with coastal beverage processors absorbing currency volatility while inland dairy cooperatives exploit domestic hollow-fiber substitution to compress procurement costs.
Pricing Analysis
Input-cost pass-through from food-grade polymer substrates drives pricing stratification across premium, standard, and economy tiers, with NMPA certification timelines and MIIT green manufacturing eligibility serving as the primary price differentiation drivers. Pricing pressure stems from industrial electricity tariffs compressing reverse osmosis operating margins in Jiangsu and Shanghai facilities. Large beverage conglomerates exhibit lowest price sensitivity due to performance-contract bundling, while seasonal juice operators demonstrate acute sensitivity to per-liter permeate fees.
Supply Chain Analysis
Refurbishment flows for ceramic membrane modules create reverse-logistics value recovery in Jiangsu pilot facilities, extending asset lifecycles beyond 8,000-hour cleaning intervals. Manufacturing concentration centers on China, Japan, and Germany for hollow-fiber substrates and precision engineering components. The supply chain rests on PVDF and PES polymer feedstocks alongside alumina ceramic precursors. Single-source vulnerability from Japanese specialty chemical suppliers exposes processors to shipping disruption. Distribution runs through Taizhou engineering centers and Suzhou distribution hubs serving Yangtze River Delta processing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
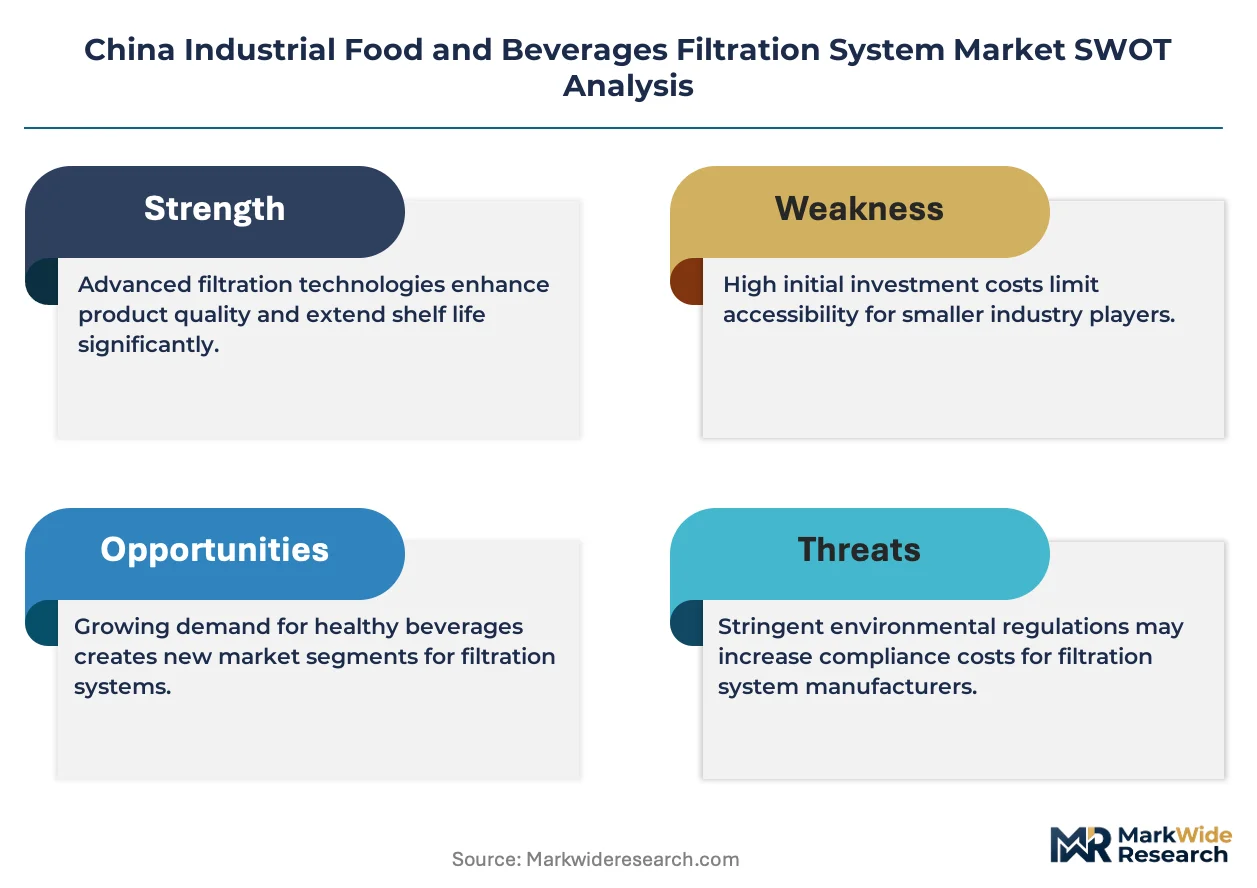
This market functions as a geographic-arbitrage play where Hebei Province's greenfield dairy complexes offer uncaptured demand at lower land and labor costs than saturated coastal corridors, while NMPA certification timelines compress technology refresh cycles for multinational brands.
For Market Incumbents: Deploy ceramic-polymer hybrid R&D to defend against fouling-intensive substitution threats from alumina-titania configurations. Incumbent membrane integrators should anchor capacity addition in Taizhou to exploit proximity advantages against emerging domestic competitors. Certification investment in accelerated NMPA pathways protects margin position from 18-24 month approval delays.
For New Entrants and Emerging Players: Direct-to-processor digital platforms enable equipment-as-performance contract penetration in seasonal juice operations where utilization volatility punishes fixed-cost ownership. White-space targets concentrate in Hebei Province greenfield dairy complexes and membrane refurbishment services for ceramic module lifecycle extension. The most penetrable segment comprises mid-scale beverage bottlers seeking fouling risk transfer.
For Investors and Strategic Acquirers: Asymmetric upside sits with domestic hollow-fiber manufacturers possessing NMPA certification advantages and Taizhou manufacturing proximity. Long-term viability over a multi-year window favors suppliers integrating upstream into food-grade polymer substrate production. The signal to watch is MIIT green manufacturing subsidy expansion accelerating procurement windows for compliant system vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Substrates | Captive PVDF supply insulates margins from Japanese currency volatility and shipping disruption. |
| Ceramic Membrane Manufacturing Scale-Up | Alumina-titania production in Jiangsu addresses fouling-intensive juice clarification demand. |
| Equipment-as-Performance Contract Expansion | Per-liter permeate fee models transfer fouling risk from seasonal juice processor balance sheets. |
| Hebei Province Greenfield Integration | Proximity to Beijing dairy demand captures uncaptured milk standardization and whey concentration volume. |
| NMPA Fast-Track Certification Investment | Accelerated food-contact polymer approvals compress technology refresh cycles for multinational beverage brands. |
Research Methodology
Direct dialogue with membrane system engineers, dairy processing plant managers, beverage procurement directors, and NMPA regulatory consultants grounded qualitative findings, cross-referenced with MIIT equipment upgrade directives, SAMR enforcement bulletins, customs import data for polymer substrates, and SEC filings from multinational filtration suppliers. Bottom-up triangulation against top-down macroeconomic indicators validated market sizing across the analysis window.
Segment-level outputs reflect modeled trajectories for membrane filtration, reverse osmosis, and ceramic hybrid technologies across dairy, beverage, and juice manufacturing end uses, with technology configuration and provincial regulatory cluster as additional segmentation dimensions. CAGRs were derived from installation base turnover rates and greenfield capacity absorption patterns, incorporating energy efficiency benchmarking thresholds and NMPA certification timeline assumptions.
The model assumes a particular technology adoption path; alternative pathways for ceramic membrane substitution would alter the outlook if alumina-titania cost curves compress faster than projected. Practitioners should monitor MIIT subsidy pool exhaustion rates and NMPA staffing capacity for certification backlog signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Micro Winery Equipment Market
Food Processing Equipment
Small Brewery Equipment Market
Food Processing Equipment
Europe Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Cookie Dropper Machine Market
Food Processing Equipment
Industrial Steam Peeler Market
Food Processing Equipment
Countertop Convection Oven Market
Food Processing Equipment
Non-Thermal Food Processing Market
Food Processing Equipment
US Cold Storage Market
Food Processing Equipment
Semi-Auto Egg Tart Forming Machine Market
Food Processing Equipment
Global Food Processing Market
Food Processing Equipment
Electric Chicken Scalder Market
Food Processing Equipment
Brewing Chiller Market
Food Processing Equipment
Steam Blanching Equipment Market
Food Processing Equipment
Bread Processing Equipment Market
Food Processing Equipment
Tangyuan Machine Market
Food Processing Equipment
Food Disinfection Equipment Market